
 Chronic Kidney Disease Market | 2026-2036
Chronic Kidney Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Kidney Disease Market Analysis
Synthetic polymer membranes are pivoting away from traditional cellulose-based dialyzers in chronic kidney disease treatment, cutting production costs while improving biocompatibility profiles. AstraZeneca leverages its SGLT2 inhibitor portfolio to anchor presence in cardio-renal protection. Boehringer Ingelheim competes through integrated diabetes-kidney care pathways. Amgen Inc. specializes in anemia management therapies that complement dialysis regimens.
Chronic kidney disease denotes progressive, irreversible loss of renal function measured by declining glomerular filtration rate below 60 mL/min/1.73m² persisting beyond three months, with end-stage requiring renal replacement therapy or transplantation. Nephrology drugs command concentrated margin pools as oral SGLT2 inhibitors and novel non-steroidal mineralocorticoid antagonists expand addressable patient populations beyond dialysis. Dialysis equipment remains structurally mature with replacement-driven demand, while home care delivery is accelerating fastest as payors push ambulatory cost containment.
FDA oversees pre-market approval of dialysis devices and novel renal therapeutics, while EMA's MDR framework governs CE marking for artificial kidneys and infusion systems in Europe. CMS reimbursement rules in the United States directly shape provider equipment procurement cycles and site-of-care decisions. Stakeholders must monitor evolving HTA evidence requirements and value-based contracting structures as payors tighten access to premium therapies without demonstrated outcomes differentiation.
Market Dynamics
Home-based dialysis is decentralizing treatment delivery away from hospital-based centers, forcing infrastructure reinvestment across provider networks and accelerating peritoneal dialysis adoption as payors prioritize site-of-care cost containment.
Growth Catalysts
- CMS Reimbursement Reform:The United States Medicare payment restructuring incentivizes home dialysis modalities through bundled payment adjustments, expanding addressable patient populations beyond traditional in-center hemodialysis.
- Synthetic Polymer Membranes:Advanced biocompatible dialyzer materials reduce complement activation and beta-2 microglobulin clearance issues, improving patient tolerance and extending session intervals.
- Aging Demographics in China:The country's diabetes prevalence exceeding 11% in urban corridors generates sustained incident CKD cases requiring renal replacement therapy infrastructure expansion.
Market Restraints
- Concentrated Dialyzer Manufacturing:Three Asian suppliers control over 70% of hollow-fiber membrane production, creating input vulnerability for European and North American device assemblers.
- Transplant Organ Scarcity:Limited deceased donor availability and living donor matching constraints perpetuate dialysis dependency, capping therapy substitution potential.
- EMA MDR Compliance Burden:The European Union's Medical Device Regulation imposes extended clinical evidence requirements for artificial kidney systems, delaying market entry for iterative device improvements.
Strategic Opportunities
- Rural United States Penetration:Underserved Appalachian and Great Plains regions present white space for telemedicine-integrated home dialysis programs with remote monitoring capabilities.
- Wearable Artificial Kidney Development:Convergence of miniaturized sorbent technology and biocompatible blood circuits enables continuous ambulatory renal replacement outside clinical settings.
- Value-Based Procurement Mandates:Germany's health technology assessment bodies are expanding outcomes-linked purchasing for renal devices, rewarding providers demonstrating mortality and hospitalization reductions.
Industry Challenges
- Nephrology Workforce Constraints:The United States faces projected shortages of board-certified nephrologists relative to incident ESRD patient growth, straining care coordination capacity.
- Home Dialysis Training Infrastructure:Peritoneal dialysis catheter placement and patient self-care education require specialized nursing resources that provider networks struggle to scale rapidly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Kidney Disease Market |
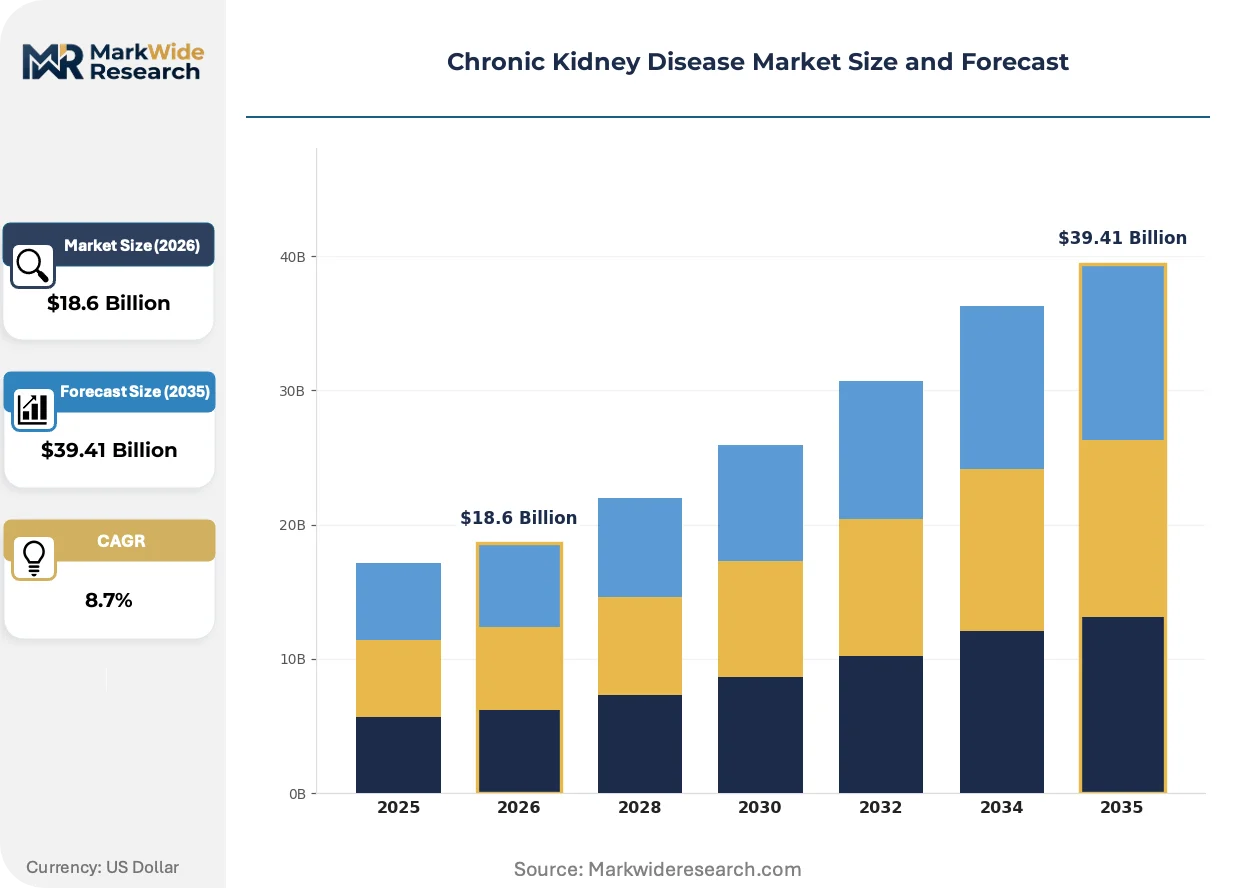
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialysis Equipment, Artificial Kidneys, Renal Replacement Therapy, Nephrology Drugs Therapy Area: Diabetes, Hypertension, Glomerulonephritis, Polycystic Kidney Disease End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Delivery Mode: Intravenous, Oral, Subcutaneous, Intra-arterial |
| Companies Covered | AstraZeneca, Boehringer Ingelheim, Bayer AG, Amgen Inc., Sanofi, Novartis AG, GlaxoSmithKline plc, Pfizer Inc., Reata Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Kidney Disease Market Emerging Trajectories
Digital biomarker integration and portable dialysis hardware are converging to enable continuous renal monitoring outside institutional settings, compressing the gap between acute intervention and chronic management.
Portable hemodialysis systems utilizing sorbent-based regeneration technology are decentralizing treatment delivery from fixed dialysis centers to patient residences and travel settings. Medicare Advantage plans and integrated delivery networks in the United States are accelerating patient qualification for home modalities. This shift is compressing traditional facility-based revenue models while expanding consumables and remote monitoring service markets.
EMA's Medical Device Regulation and FDA's Breakthrough Devices Program are creating divergent approval pathways for artificial kidney innovations, with European requirements demanding longer post-market surveillance. Manufacturers are prioritizing predicate device strategies in the United States while accumulating clinical evidence for CE marking. Dialysis machine and disposable categories face the steepest compliance cost escalation, favoring incumbents with established quality management systems.
Patient self-management platforms integrating mobile applications with connected dialysis equipment are displacing nurse-led treatment monitoring in home settings. Peritoneal dialysis patients in Japan and Germany are adopting Bluetooth-enabled cycler machines that transmit treatment data to centralized care teams. This behavioral shift concentrates data infrastructure investment while reducing per-patient nursing touchpoints.
Chronic Kidney Disease Market Segmentation
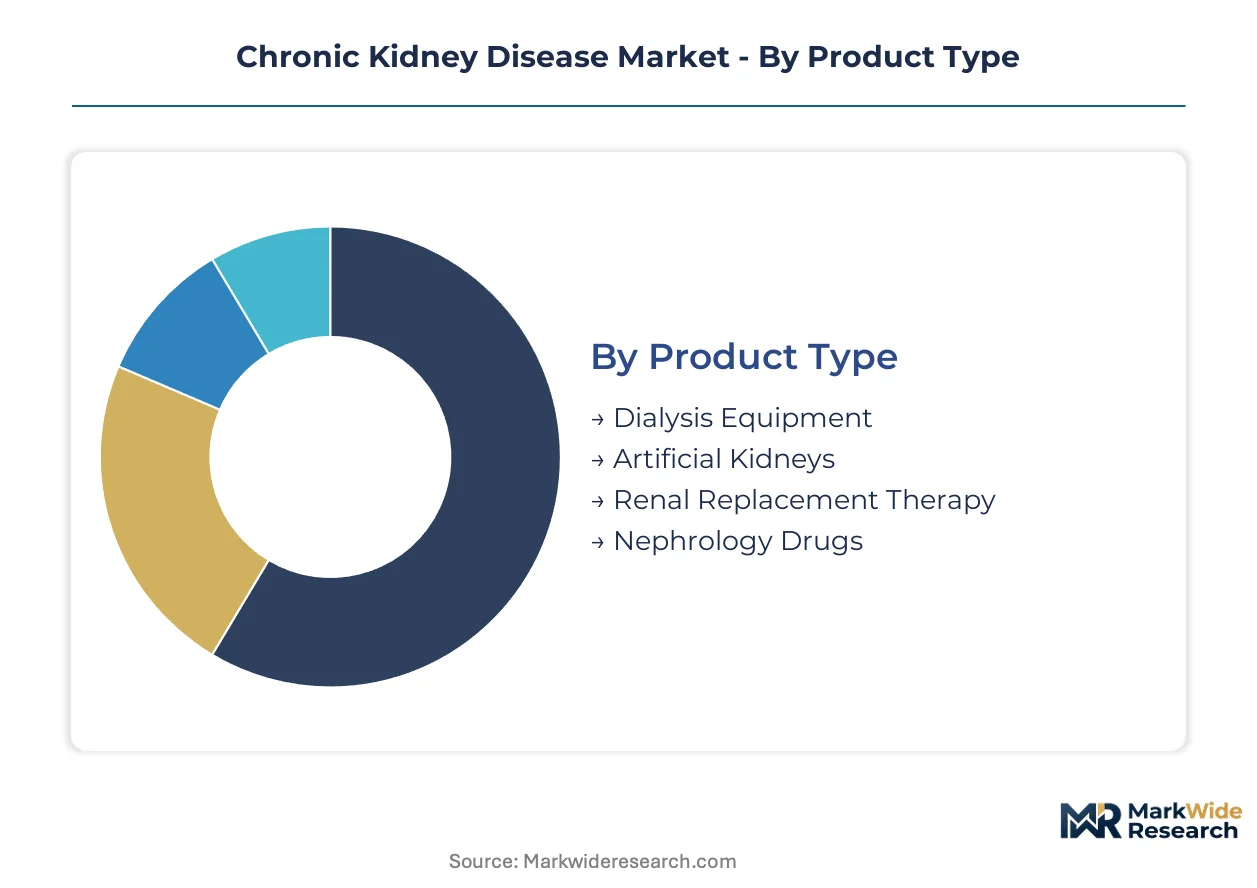
Chronic kidney disease treatment spans device-dependent replacement therapies and pharmaceutical interventions, each demanding distinct regulatory pathways, reimbursement frameworks, and care delivery infrastructure. Segmentation reveals how capital-intensive dialysis hardware, disposable consumables, and oral therapeutics compete for margin pools across institutional and ambulatory settings.
Product Type:
Dialysis equipment and artificial kidneys anchor the high-investment end of the customization spectrum, requiring specialized manufacturing and clinical training, while nephrology drugs scale through standardized oral formulations.
- Dialysis Equipment:Hemodialysis and peritoneal dialysis machines incorporate volumetric ultrafiltration control, conductivity monitoring, and disinfectant circuits. Demand clusters in hospital networks across the United States, Germany, and Japan as facilities expand home dialysis programs under CMS and statutory health insurance reimbursement incentives.
- Artificial Kidneys:Hollow-fiber dialyzers with synthetic polymer membranes—polysulfone, polyethersulfone, or polymethyl methacrylate—govern solute clearance efficiency and biocompatibility profiles. Japanese and German providers drive premium adoption for high-flux variants that enhance beta-2 microglobulin removal and reduce long-term complication burdens.
- Renal Replacement Therapy:Integrated service bundles combining equipment, consumables, and nursing labor.
- Nephrology Drugs:Oral SGLT2 inhibitors and non-steroidal mineralocorticoid antagonists for cardio-renal protection.
Leading the category by volume: Dialysis Equipment. Growing fastest: Nephrology Drugs.
Therapy Area:
Diabetes and hypertension dominate patient volume, while glomerulonephritis and polycystic kidney disease command specialized nephrology referral pathways with distinct reimbursement intensities.
- Diabetes:Diabetic nephropathy represents the single largest indication for renal replacement therapy initiation, driven by prolonged hyperglycemia-induced glomerular basement membrane thickening and mesangial expansion. China's urban diabetes prevalence above 11% sustains incident CKD case generation requiring dialysis infrastructure expansion.
- Hypertension:Hypertensive nephrosclerosis produces progressive renal function decline through arteriolar narrowing and ischemic glomerular injury. United States Medicare data shows hypertensive CKD as the second most common ESRD etiology, with concentrated treatment volumes in southeastern states.
- Glomerulonephritis:Immune-mediated inflammatory conditions including IgA nephropathy and membranous nephropathy.
- Polycystic Kidney Disease:Autosomal dominant genetic disorder with cystic kidney enlargement.
Diabetes generates the highest absolute patient volume. Polycystic Kidney Disease exhibits the steepest expansion trajectory as genetic screening expands addressable populations for tolvaptan and emerging therapies.
End User:
Site-of-care economics differentiate capital-intensive hospital installations from distributed home care models, with reimbursement differentials driving migration toward lower-acuity settings.
- Hospitals:Acute dialysis units and chronic outpatient centers within integrated delivery networks manage complex comorbidities and vascular access complications. German hospital federations and United States health systems anchor equipment procurement volumes through centralized capital budgeting.
- Home Care:Peritoneal dialysis and home hemodialysis programs reduce facility overhead while requiring patient self-management training and remote monitoring infrastructure. CMS bundled payment adjustments and Japanese long-term care insurance accelerate qualification and supply placement.
- Clinics:Freestanding dialysis centers operated by specialized providers.
- Long-term Care Facilities:Skilled nursing facilities with on-site dialysis capability for elderly ESRD patients.
Hospitals retain the largest installed equipment base. Home Care is climbing the fastest as payor cost-containment intensifies.
Delivery Mode:
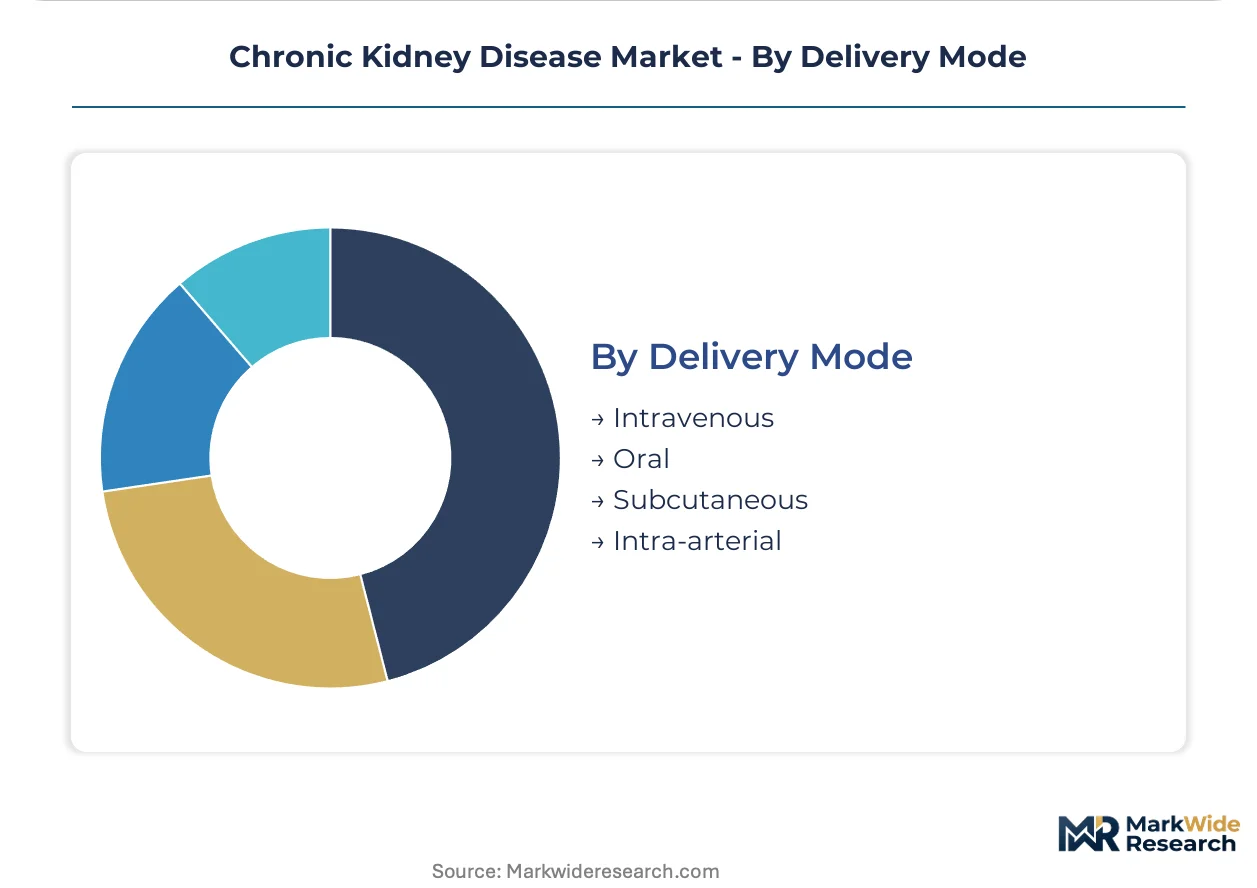
Route of administration determines manufacturing complexity, cold chain requirements, and patient compliance profiles across the therapeutic spectrum.
- Intravenous:Erythropoiesis-stimulating agents, iron supplementation, and dialysis circuit anticoagulation delivered during hemodialysis sessions. United States dialysis providers administer intravenous darbepoetin alfa and ferric carboxymaltose as standard-of-care anemia management.
- Oral:SGLT2 inhibitors, statins, and phosphate binders enable patient self-administration outside clinical supervision. German statutory health insurance and United States Medicare Part D cover oral finerenone and empagliflozin for cardio-renal risk reduction.
- Subcutaneous:Epoetin alfa and continuous glucose monitoring sensors.
- Intra-arterial:Regional chemotherapy and investigational cellular therapies.
Oral formulations dominate prescription volume. Intravenous delivery maintains the highest per-treatment value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and Boao Lecheng International Medical Tourism Pilot Zone concentrate foreign dialysis equipment registrations, accelerating market access for multinational device manufacturers seeking preferential tariff treatment and expedited clinical trial pathways.
United States
Medicare's ESRD bundled payment system drives site-of-care migration toward home dialysis modalities, with CMS reimbursement adjustments favoring peritoneal dialysis training and remote patient monitoring infrastructure. FDA's Breakthrough Devices Program accelerates pre-market approval for wearable artificial kidney prototypes. Texas Medical Center in Houston anchors the largest concentration of dialysis provider headquarters and clinical trial sites.
Germany
Statutory health insurance funds implement outcomes-linked procurement for renal replacement devices through the Federal Joint Committee's health technology assessment framework. EMA's MDR compliance requirements extend post-market surveillance obligations for artificial kidney systems. Baden-Württemberg's medical technology cluster around Tübingen and Stuttgart hosts hollow-fiber membrane manufacturing and dialysis machine assembly operations.
Japan
Long-term care insurance expansion covers home hemodialysis consumables and peritoneal dialysis cyclers for elderly ESRD patients. PMDA's Sakigake designation fast-tracks regenerative medicine products for renal indications. The Kansai region surrounding Osaka maintains the highest per-capita dialysis facility density globally, with concentrated device maintenance and biomedical engineering service providers.
China
Urban diabetes prevalence exceeding 11% sustains incident CKD case generation requiring dialysis infrastructure expansion under the Healthy China 2030 initiative. NMPA's priority review pathway accelerates registration for innovative dialysis membranes and sorbent-based portable systems. The Yangtze River Delta around Shanghai concentrates domestic dialyzer manufacturing joint ventures and tertiary hospital nephrology departments.
Chronic Kidney Disease Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical innovators commanding margin concentration in oral cardio-renal therapies while device assemblers compete on manufacturing scale and regulatory compliance infrastructure. The market structures around three archetypes: integrated diabetes-kidney care platform builders, dialysis equipment and consumable specialists, and anemia management therapy developers. Capacity expansion in synthetic polymer membrane production and strategic partnerships for wearable artificial kidney commercialization represent the dominant competitive moves reshaping positioning.
Among the therapy-focused tier, AstraZeneca and Boehringer Ingelheim occupy positions exemplifying the integrated cardio-renal protection platform model, while Amgen Inc. anchors the anemia management specialization archetype within dialysis complement regimens.
| Leading Market Players |
|---|
| AstraZeneca |
| Boehringer Ingelheim |
| Bayer AG |
| Amgen Inc. |
| Sanofi |
| Novartis AG |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Reata Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
CMS bundled payment administrators and statutory health insurance funds in Germany concentrate procurement authority for dialysis equipment, anchoring contract-based pricing with volume-tiered discounts that penalize non-compliant suppliers. This buyer concentration forces manufacturers to absorb certification and logistics costs within fixed reimbursement ceilings, compressing margins on standard dialyzers while preserving premium pricing for high-flux synthetic membranes.
Pricing Analysis
Short lead-time premiums for emergency dialyzer replacements command 15-25% markups over scheduled contract volumes, while spot-market spot inventory of hollow-fiber membranes trades at discounts to long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels stratifies by biocompatibility certification and beta-2 microglobulin clearance ratings. Pricing pressure stems from CMS reimbursement compression and Japanese long-term care insurance fee schedule revisions. Dialysis service chains exhibit highest price sensitivity due to fixed reimbursement rates, while tertiary hospital networks in Germany tolerate premium tiers for outcome-linked procurement.
Supply Chain Analysis
FDA 510(k) and EMA MDR certification gates constrain dialyzer membrane supply to qualified polymer extrusion facilities, with polysulfone and polyethersulfone resin processing concentrated in Japan, Germany, and the United States. Hollow-fiber spinning equipment and sorbent cartridge assembly draw from precision tooling suppliers in Switzerland and South Korea. Single-source vulnerability permeates high-flux membrane chemistry, where three Asian suppliers control substrate production. Distribution runs through regional device assemblers with hospital system and dialysis clinic direct contracts, bypassing traditional medical distributor markups for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into synthetic polymer resin production and captive hollow-fiber membrane extrusion defines the vertical-integration race in renal replacement therapy, as manufacturers seek insulation from Asian substrate concentration and EMA MDR compliance cost escalation.
For Market Incumbents: Acquire hollow-fiber membrane extrusion capacity in Baden-Württemberg or the Yangtze River Delta to secure supply continuity against concentrated Asian substrate suppliers. Consolidate remote patient monitoring platforms through specialized nursing workforce training contracts, defending against home dialysis entrants lacking care coordination infrastructure. Lock in multi-year polysulfone resin offtake agreements before further CMS reimbursement compression. For New Entrants and Emerging Players: The premium-economy price gap in peritoneal dialysis cyclers creates entry space for Bluetooth-enabled, software-integrated devices at mid-tier positioning. Target Appalachian and Great Plains geographies with telemedicine-integrated home dialysis programs, exploiting nephrologist shortage and CMS bundled payment incentives. Pursue hospital-at-home partnerships with Medicare Advantage plans as the primary go-to-market channel. For Investors and Strategic Acquirers: The window for entry favors wearable artificial kidney developers with FDA Breakthrough Device designation and sorbent regeneration patents. Long-term viability hinges on demonstrating mortality reduction in ambulatory settings sufficient for German outcomes-linked procurement. Watch for PMDA Sakigake fast-track approvals in regenerative renal indications as the signal for platform valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Polymer Backward Integration | Captive polysulfone resin production insulates margins from Asian substrate concentration and tariff exposure. |
| CE Marking Pathway Investment | EMA MDR clinical evidence accumulation accelerates market access for iterative dialyzer improvements in Europe. |
| Hospital System Partnership | Integrated delivery network contracts in Texas Medical Center anchor volume commitments for home dialysis expansion. |
| Software Companion Development | Bluetooth-enabled cycler integration with patient self-management platforms reduces per-patient nursing touchpoints. |
| Reimbursement Strategy | CMS bundled payment qualification and Medicare Advantage network placement determine site-of-care migration capture. |
Methodological Framework
Multi-period observation of dialysis service expansion, SGLT2 inhibitor prescription volumes, and home modality qualification rates anchored the trend analysis, supplemented by interviews with dialysis clinic medical directors, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and nephrology drug formulary directors. Secondary validation drew from CMS Medicare cost reports, FDA 510(k) and PMA filings, EMA MDR technical documentation, Japanese long-term care insurance statistics, and NMPA priority review announcements. Bottom-up equipment installation data and top-down pharmaceutical revenue estimates underwent triangulation against statutory health insurance reimbursement schedules.
Segment-weighting across product type, therapy area, end user, and delivery mode dimensions informed the analytical framework, with therapy-area splits calibrated to diabetes and hypertension prevalence data. CAGRs derived from logistic diffusion modeling of home dialysis adoption curves and pharmaceutical patient-share expansion. Forecast inputs incorporated CMS reimbursement rulemaking timelines, EMA MDR transition deadlines, and NMPA regulatory pathway accelerations without year-specific anchoring.
Inputs from dialysis provider capital expenditure disclosures and pharmaceutical pipeline databases were available through the study window; gaps in real-time home dialysis patient compliance rates introduce uncertainty bands around ambulatory care migration projections. Forecasts reflect assumptions regarding reimbursement stability and regulatory pathway durations. A model refresh is warranted upon material change in CMS bundled payment methodology or EMA MDR post-market surveillance requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Blood Dialyzer Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Renal Denervation Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Renal Stent Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Hemodialyzer Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Global Dialyzer Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
End Stage Renal Disease Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Kidney Transplant Market
Nephrology
Radiation Nephropathy Treatment and Management Market