
 Waste Sorting Equipment Market | 2026-2036
Waste Sorting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Sorting Equipment Market Intelligence
The European Union's Green Deal and its stringent circular economy targets are restructuring demand for high-purity recycled materials. Tomra Systems ASA leverages its leadership in sensor-based sorting to meet these requirements. Steinert GmbH specializes in advanced magnetic and sensor separation for complex waste streams like electronic waste. Machinex Industries Inc. competes by offering integrated material recovery facility designs, particularly for the North American market.
Waste sorting equipment refers to automated systems that segregate materials within mixed waste streams. These machines often use near-infrared (NIR) spectroscopy to identify materials by composition, enabling the production of clean, marketable commodities for recycling. Optical sorters represent the fastest-growing equipment type, driven by the need for high-purity plastics. While municipal solid waste remains the largest application, sorting of construction debris is gaining traction due to landfill diversion mandates.
Regulations such as the EU's RoHS directive and China's dual carbon goals directly shape equipment demand by setting recycling targets and material purity standards. These frameworks define market access criteria and compel investment in advanced sorting technology. Decisions on integrating AI-driven robotics versus upgrading existing sensor-based systems will define the competitive positioning of recycling facility operators.
Market Dynamics
The imperative to create circular economies, codified in regulations like the EU Green Deal and China's dual carbon goals, is the central force shaping the waste sorting equipment market. This policy pressure mandates higher recycling rates and material purity, compelling investment in advanced sorting technologies.
Growth Catalysts
- Stringent Recycling Mandates:The EU's Circular Economy Action Plan, with its specific targets for plastic packaging recycling, directly stimulates demand for optical sorters capable of producing high-purity polymer fractions.
- Landfill Diversion Policies:In developed economies like Germany and Japan, regulations limiting the landfilling of untreated construction and demolition (C&D) waste are creating a dedicated market for equipment that separates wood, aggregates, and metals.
- Commodity Value of Recyclates:The production of clean, marketable commodities, such as food-grade rPET, depends on sophisticated sorting. This economic driver justifies investment in systems that can achieve over 99% purity for specific materials.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for advanced sorting systems, including AI-powered robotics and integrated material recovery facility (MRF) designs, presents a substantial barrier for smaller operators and municipalities.
- Technical Sorting Limitations:Current near-infrared (NIR) technology struggles to accurately identify and separate dark or black plastics, multi-layered packaging, and certain flexible films, leading to material loss and contamination.
- Inconsistent Feedstock Quality:The high variability and contamination levels in municipal solid waste (MSW) streams negatively impact equipment efficiency, increase maintenance requirements, and can degrade the quality of sorted output materials.
Strategic Opportunities
- Emerging Market Infrastructure:Countries in Southeast Asia and Latin America are beginning to formalize national waste management strategies, creating greenfield opportunities for suppliers of foundational sorting and separation equipment.
- E-Waste and Battery Recycling:The growing volume of electronic waste offers a significant opportunity for specialized sorting systems that can recover valuable metals and critical raw materials in compliance with directives like the EU's WEEE.
- Software and AI Integration:Developing AI-driven software that integrates with existing sensor-based systems to improve recognition, provide real-time data analytics, and optimize sorting performance represents a key value-add opportunity.
Industry Challenges
- Skilled Technician Scarcity:A shortage of technicians with the expertise to install, operate, and maintain complex sensor-based and robotic sorting systems creates operational bottlenecks and increases reliance on OEM service contracts.
- Retrofitting Legacy Facilities:Integrating new, high-speed sorting equipment into the physical footprint and workflow of older MRFs is a complex engineering challenge that often leads to costly downtime and operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Sorting Equipment Market |
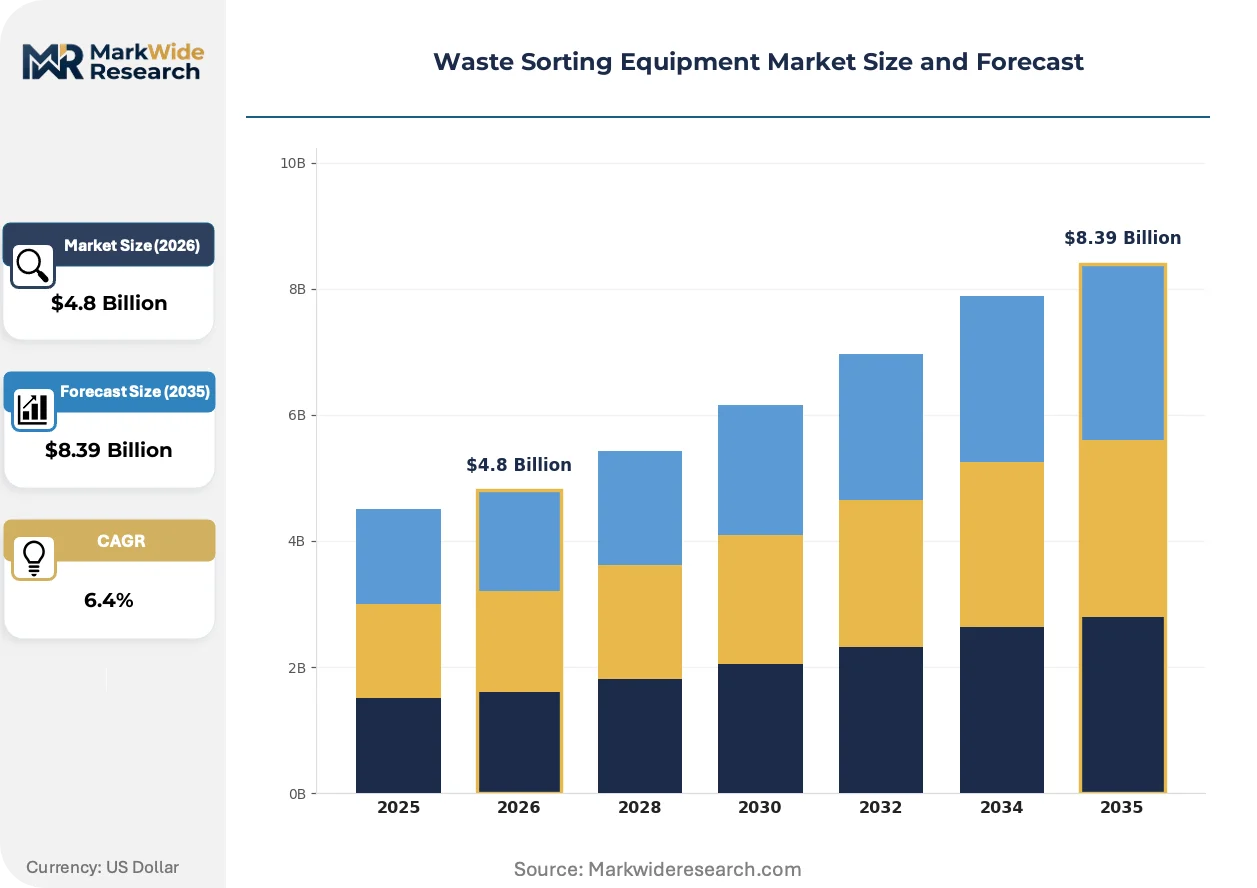
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Magnetic Separator, Eddy Current Separator, Optical Sorter, Trommel Screen, Air Classifier, Shredder Technology: Near Infrared, X-ray Transmission, Color Recognition, Sensor-based Sorting, Laser Sorting, Mechanical Sorting Application: Municipal Solid Waste, Electronic Waste, Construction Debris, Industrial Scraps, Organic Waste, Packaging Waste End User: Recycling Facilities, Waste-to-Energy Plants, Composting Sites, Material Recovery Facilities, Landfill Operators, Sorting Contractors |
| Companies Covered | MSS, Inc., Machinex Industries Inc., Tomra Systems ASA, Sesotec GmbH, Pellenc ST, ZenRobotics Ltd., REDWAVE, Steinert GmbH, CP Manufacturing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Sorting Equipment Market Strategic Shifts & Innovations
The market is defined by a technological pivot from simple mechanical separation toward intelligent, data-driven sorting. This shift is driven by the need to maximize the value of recovered materials in response to stringent quality demands from both regulators and end markets.
AI-powered robotics utilize advanced computer vision and machine learning algorithms to identify and pick specific items from a fast-moving conveyor belt. Material recovery facilities (MRFs) are adopting these systems to target high-value materials or remove problematic contaminants that traditional sorting equipment misses. This robotic capability is converging with established near-infrared (NIR) spectroscopy to create hybrid systems that sort by both object shape and material composition.
China's National Sword policy and its subsequent "dual carbon" goals have fundamentally restructured global recyclable commodity flows. These regulations establish an extremely high-quality standard for imported materials, effectively closing the door to low-grade or mixed waste bales. This directly impacts exporters in North America and Europe, who are now forced to invest in advanced optical and robotic sorting to produce purer outputs that meet new global import criteria.
A transition toward "Recycling-as-a-Service" (RaaS) models is altering procurement patterns for municipalities and private waste handlers. This approach moves away from large, one-time capital equipment purchases to long-term service contracts where facility operators are compensated based on performance metrics like system uptime, throughput, and the purity of recovered commodities. This trend is most prominent in the United States and Australia, where it helps de-risk technology adoption for public entities.
Waste Sorting Equipment Market Segmentation
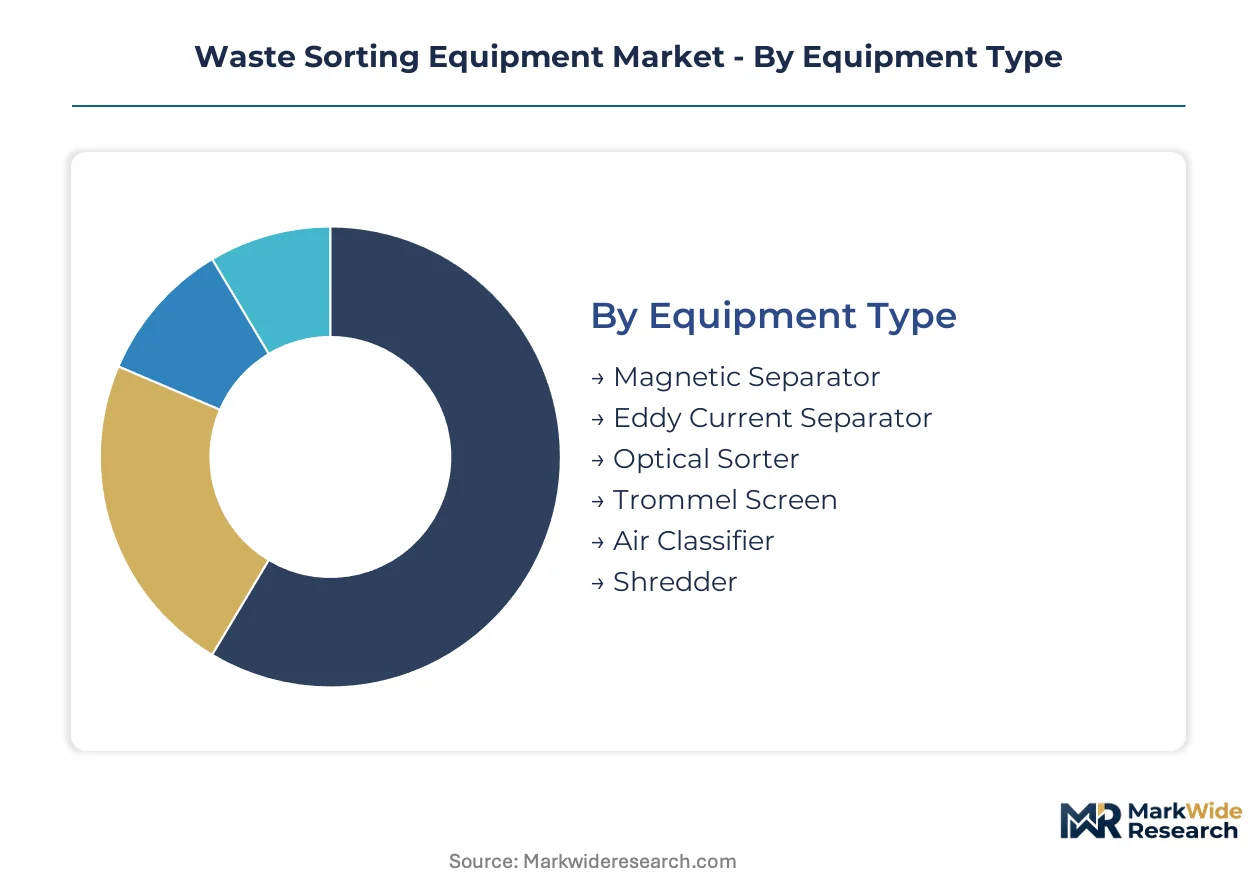
The waste sorting equipment market is segmented to reflect the diverse operational needs and technological advancements driving material recovery. Understanding these distinct segments helps stakeholders identify specific investment opportunities and tailor solutions to address varied waste streams and purity mandates across different regions.
Equipment Type:
Buyers of waste sorting equipment prioritize different functionalities based on the waste stream's complexity and desired output purity.
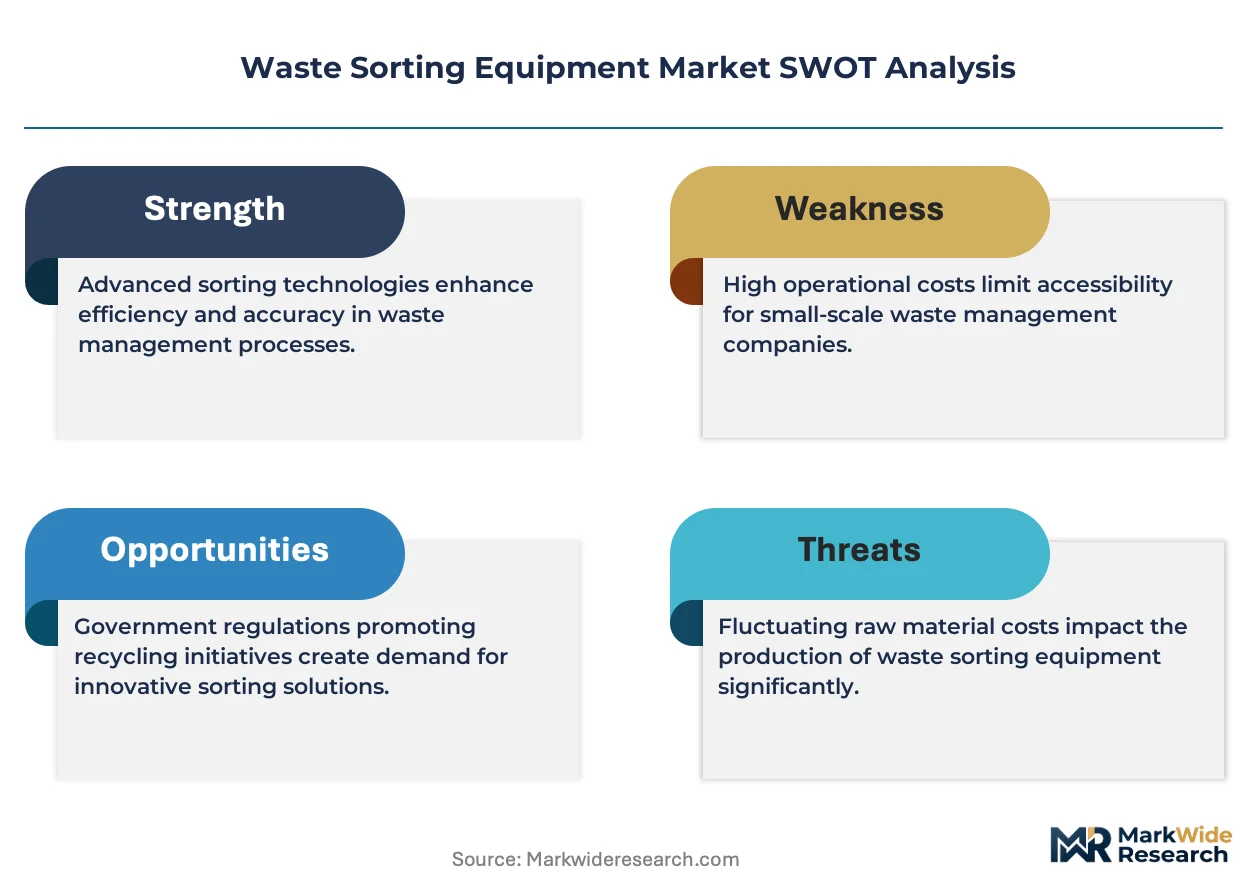
- Optical Sorter:These advanced machines utilize near-infrared (NIR) spectroscopy and visible light cameras to identify materials by composition and color. Demand is concentrating in Europe for high-purity plastic fractions, driven by stringent recycling mandates for packaging waste.
- Eddy Current Separator:This equipment separates non-ferrous metals like aluminum and copper from mixed material streams using rapidly alternating magnetic fields. Developed economies such as Germany increasingly deploy these systems to recover high-value metals from municipal solid waste.
- Magnetic Separator:These devices efficiently remove ferrous metals from waste streams, crucial for protecting downstream equipment and improving material quality.
- Trommel Screen:Rotary drum screens physically separate waste by size, acting as a primary sorting stage in many material recovery facilities.
- Air Classifier:Air classifiers use air currents to separate lighter materials from heavier ones, effective for mixed waste streams containing plastics and organic matter.
- Shredder:Shredders reduce the size of bulky waste materials, facilitating easier handling and subsequent sorting processes.
Magnetic Separators handle the largest volume of ferrous materials today; Optical Sorters are gaining share fastest due to high-purity requirements.
Technology:
The choice of sorting technology is often dictated by the specific material characteristics and target recovery goals for different waste types.
- Near Infrared:NIR technology identifies materials based on their unique spectral absorption characteristics, particularly effective for different plastic polymers. This technology is critical for producing clean, marketable commodities like food-grade rPET in North America.
- Sensor-based Sorting:These systems integrate multiple sensor types, including NIR, X-ray, and color cameras, to achieve highly accurate and versatile material separation. Investment in these technologies is accelerating in countries like Japan to meet strict recycling targets for complex waste.
- X-ray Transmission:XRT technology differentiates materials by density, enabling the separation of heavy metals or glass from mixed waste streams.
- Color Recognition:This technology identifies and separates materials based on their visible color, commonly used for sorting plastics and glass fragments.
- Laser Sorting:Laser-based systems detect and sort materials with specific reflective properties, often employed for specialized applications like glass recycling.
- Mechanical Sorting:This foundational technology uses physical processes such as screens, conveyors, and balers for basic material separation and handling.
Near Infrared technology is critical for high-purity plastic streams; Mechanical Sorting offers foundational cost efficiency for bulk separation.
Application:
Different waste applications contribute varying volumes to the overall demand for sorting equipment, each requiring tailored solutions.
- Municipal Solid Waste:This segment involves sorting mixed household and commercial waste to recover recyclables and reduce landfill volumes. Regulations like the EU Green Deal are compelling significant investment in advanced sorting for MSW across European nations.
- Construction Debris:Sorting equipment for C&D waste separates materials like concrete, wood, and metals for reuse or recycling. Landfill diversion mandates in regions like California are driving demand for robust C&D sorting solutions.
- Electronic Waste:Specialized sorting systems extract valuable metals and components from discarded electronics, addressing directives such as the EU's WEEE.
- Industrial Scraps:Equipment for industrial waste streams processes manufacturing byproducts to recover reusable materials and minimize disposal costs.
- Organic Waste:Sorting technologies help separate organic fractions for composting or anaerobic digestion, supporting circular economy initiatives.
- Packaging Waste:Dedicated sorting lines process various packaging materials, including plastics, paper, and glass, to meet specific recycling targets.
Municipal Solid Waste represents the largest application volume; Electronic Waste applications demonstrate significant potential for future growth.
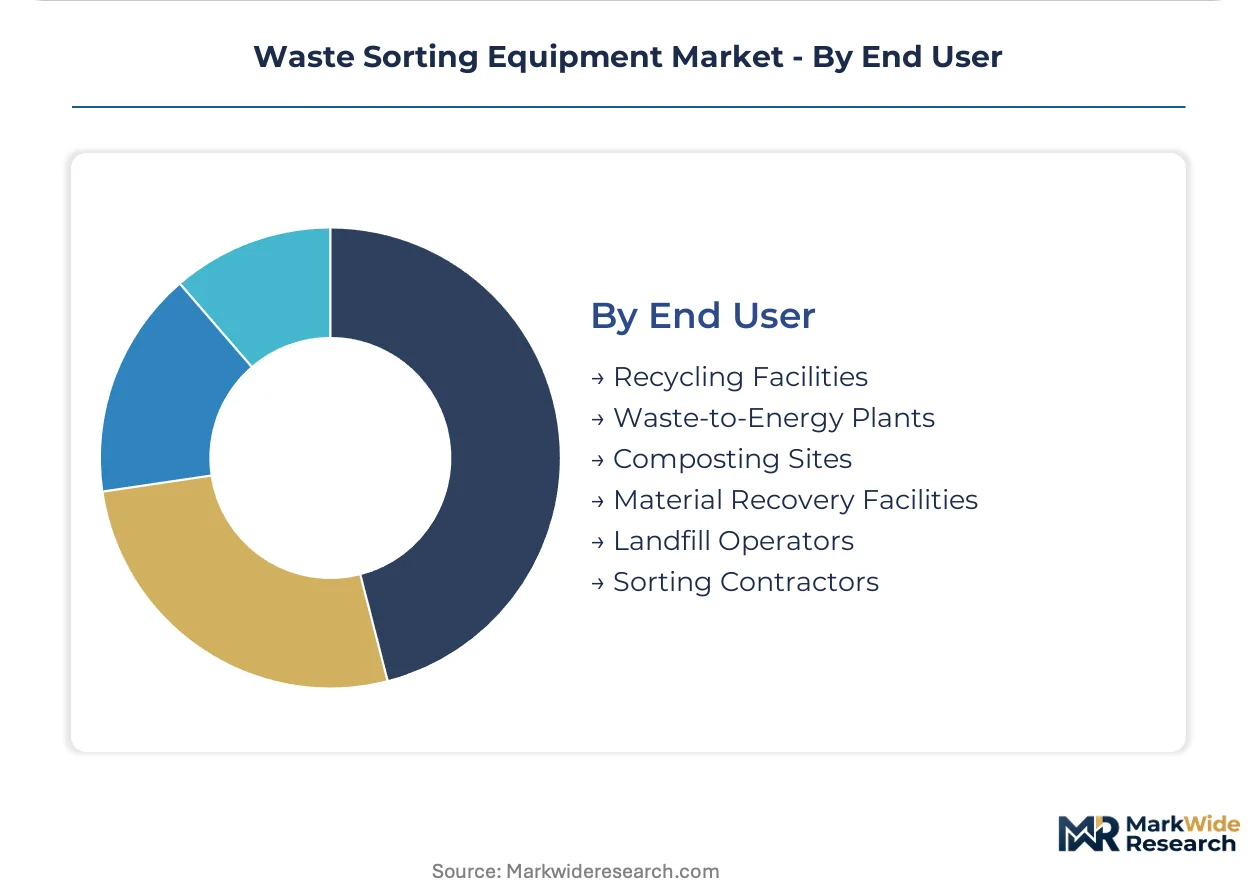
End User:
The operational scale and business model of waste management entities significantly influence their investment in sorting equipment.
- Recycling Facilities:These facilities process collected recyclables into secondary raw materials for industrial use. They require versatile sorting equipment to handle diverse material inputs and achieve high purity outputs.
- Material Recovery Facilities:MRFs are centralized plants designed to receive, separate, and prepare commingled waste for recycling markets. Integrated MRF designs are crucial for efficient operations in North America.
- Waste-to-Energy Plants:These facilities often use sorting equipment to remove non-combustible materials, enhancing efficiency and reducing ash residue.
- Composting Sites:Sorting equipment at composting sites removes contaminants like plastics and metals from organic waste streams.
- Landfill Operators:Some landfill operations utilize sorting equipment for material recovery before final disposal, extending landfill lifespan.
- Sorting Contractors:These specialized service providers offer sorting solutions, often employing mobile or modular equipment for various clients.
Material Recovery Facilities are a mature segment for advanced sorting; Sorting Contractors are demonstrating rapid adoption of flexible solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The waste sorting equipment market has seen significant scaling in developed economies due to early environmental mandates. These regions pioneered advanced recycling technologies and infrastructure. This historical foundation now drives demand for next-generation sorting solutions globally.
Germany
Germany's robust circular economy framework drives significant demand for advanced sorting equipment. National regulations limit landfilling of untreated waste, pushing investment in C&D and MSW sorting. Companies in Bavaria are deploying highly automated systems to achieve high-purity material streams.
Japan
Japan's stringent recycling targets and limited landfill space necessitate sophisticated waste sorting technologies. The country's METI promotes resource efficiency through various recycling initiatives. Osaka's industrial zones are focusing on specialized e-waste sorting to recover critical raw materials.
United States
State-level recycling mandates and the economic value of clean recyclates propel demand for sorting equipment in the United States. Regulations in California, such as landfill diversion policies, accelerate investment in advanced material recovery. The Pacific Northwest region is adopting "Recycling-as-a-Service" models for municipal waste processing.
China
China's ambitious dual carbon goals and strict import quality standards are reshaping its domestic sorting equipment market. New GB standards for recycled materials compel investment in high-purity separation technologies. Industrial parks in Guangdong are deploying optical sorters and robotics to process packaging waste effectively.
France
France actively pursues EU circular economy targets, driving significant demand for modern waste sorting solutions. National legislation, aligned with the EU Green Deal, mandates higher recycling rates for plastic packaging. The Rhône-Alpes region is investing in advanced sensor-based systems for mixed municipal solid waste.
Waste Sorting Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and service integration. The market exhibits a tiered structure, with specialized technology providers at the high end and volume-focused mechanical equipment suppliers at the lower end. Three strategic archetypes define this landscape: sensor-based technology innovators, integrated MRF solution providers, and regional mechanical equipment manufacturers. Competitive moves include strategic partnerships for technology co-development and targeted geographic expansion into emerging markets.
Within the sensor-based technology innovator tier, Norway-based Tomra Systems ASA exemplifies leadership in optical sorting solutions. Germany-based Steinert GmbH occupies a position specializing in advanced magnetic and sensor separation for challenging waste streams. Canada-based Machinex Industries Inc. anchors the integrated material recovery facility design segment, particularly serving the North American market. These entities represent distinct approaches to addressing the evolving demands for high-purity recyclates. Their offerings reflect global market needs for both specialized material recovery and comprehensive facility integration.
| Leading Market Players |
|---|
| MSS, Inc. |
| Machinex Industries Inc. |
| Tomra Systems ASA |
| Sesotec GmbH |
| Pellenc ST |
| ZenRobotics Ltd. |
| REDWAVE |
| Steinert GmbH |
| CP Manufacturing Inc. |
| Others |
Cost & Logistics Intelligence
Logistics costs for transporting mixed waste streams influence the pricing of advanced sorting equipment, as operators seek systems that reduce processing steps and material handling across the value chain.
Pricing Analysis
Project-based pricing models dominate the waste sorting equipment market, reflecting the bespoke nature of material recovery facility (MRF) designs. Price differentiation stems from equipment customization and after-sales service bundles. Pricing pressure stems from the high capital expenditure required for advanced systems, particularly for smaller municipal operators. Recycling facilities exhibit lower price sensitivity due to the long-term value of high-purity outputs.
Supply Chain Analysis
Compliance with international standards like CE marking and ISO certifications gates access for waste sorting equipment suppliers into developed markets like the EU and Japan. Geographic supply concentration centers on Germany, Japan, and Canada for specialized components and high-precision manufacturing. Key raw material dependencies include rare earth elements for magnets and specialized optical sensors. Logistics chokepoints present a structural risk. Distribution runs through direct sales channels and regional integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities exist for waste sorting equipment, driven by the cost disparity between retrofitting legacy facilities in North America and establishing new systems in Southeast Asia.
For Market Incumbents:Extend sensor-based system capabilities with AI-driven software to improve recognition and sorting performance for complex waste streams. Consolidate market share by acquiring specialized robotics firms to counter the threat of new entrants focusing on niche sorting challenges. Invest in regional service hubs in Europe to reduce reliance on OEM service contracts and deepen client relationships.
For New Entrants and Emerging Players:Begin with modular, scalable sorting solutions targeting construction and demolition (C&D) waste in regions like California, where landfill diversion mandates are strong. The C&D waste segment is penetrable due to its consistent material streams compared to mixed municipal solid waste. A go-to-market angle involves offering "Recycling-as-a-Service" models to de-risk technology adoption for public entities.
For Investors and Strategic Acquirers:Consolidation pressure builds where high capital expenditure and technological complexity limit the number of viable long-term players. Long-term viability for the sector hinges on the global push for circular economies, offering a 5-10 year growth horizon. Target acquisition archetypes include specialized AI robotics developers or firms with strong intellectual property in sensor fusion. Watch for increased government incentives for advanced recycling infrastructure as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch AI-Integrated Optical Sorters | This initiative enhances sorting accuracy for complex plastics, meeting stringent EU Green Deal purity mandates. |
| Form Partnerships for RaaS Models | Collaborations with municipalities in the United States de-risk technology adoption and ensure consistent revenue streams. |
| Expand into Southeast Asian Markets | This move captures greenfield opportunities in countries formalizing national waste management strategies. |
| Acquire Robotics & Sensor Technology Firms | This strategy integrates advanced automation and material identification capabilities into existing product portfolios. |
| Scale Production of High-Purity Plastic Sorting Lines | Increased capacity supports the growing demand for food-grade rPET production, particularly in North America. |
Research Approach
Coverage spans Europe, North America, and Asia-Pacific, with primary inputs from each region's waste management and recycling sectors. This study combined in-depth interviews with facility managers, equipment engineers, and regulatory compliance officers. Secondary validation drew from government environmental reports, industry association publications, and company financial filings. A bottom-up and top-down triangulation approach ensured data robustness.
Rate-of-change decomposition informed the market projection across the analysis window, modeling shifts in equipment type, technology, and application. The framework segmented demand by end-user and regional regulatory impact. CAGRs were derived through a regression analysis of historical trends and projected adoption rates. Key forecast inputs included future recycling targets and C&D waste generation volumes.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in global commodity prices for recyclates. Forecasts reflect assumptions regarding regulatory stability and technological evolution. A model refresh is warranted upon material change in global recycling policy or major economic downturns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market