
 North America Trash Bags Market | 2026-2036
North America Trash Bags Market Size, Share, and Industry Trends Forecast 2026-2036
North America Trash Bags Market Analytics
Post-consumer recycled polyethylene is hardening cost structures across the North America trash bags market as virgin resin substitution intensifies. Novolex Holdings leverages captive recycling infrastructure to control feedstock costs across its film operations. Poly-America L.P. sustains margin advantages through backward integration into resin compounding at its Texas facilities. Berry Global anchors regional supply through multi-site blown film capacity serving private-label and branded channels.
Trash bags are flexible polymer containers engineered to specified mil thickness, tensile strength, and puncture resistance for the containment, transport, and disposal of solid waste streams. Standard bags dominate unit volume in residential channels, while heavy-duty formulations command premium positioning in commercial and industrial applications where load-bearing specifications exceed forty pounds. Biodegradable bags represent the fastest-expanding material segment, though compostable certification requirements from BPI and ASTM D6400 compliance create qualification barriers that concentrate margin pools with certified suppliers.
The EPA's sustainable materials management framework and state-level plastic bag preemption battles in Texas and Florida create divergent compliance terrain for manufacturers selling across jurisdictions. California's SB 270 and New York's bag waste reduction act mandate reusable or recycled-content alternatives, while Health Canada and the Canadian Council of Ministers of the Environment advance harmonized extended producer responsibility consultations. Stakeholders must monitor pending federal procurement standards for recycled content and the fragmentation of state composting infrastructure investment cycles.
Market Dynamics
Post-consumer recycled polyethylene feedstock constraints are compressing margin structures across the North America trash bags market, forcing manufacturers to reconfigure resin sourcing strategies and compounding operations.
Growth Catalysts
- California SB 270 implementation:Mandates for recycled-content and reusable alternatives in retail channels are redirecting procurement budgets toward certified compostable and post-consumer recycled film suppliers.
- Municipal organics diversion mandates:Cities across the Northeast corridor require compostable liners for curbside food waste collection, expanding addressable demand for ASTM D6400-certified products.
- Biopolymer formulation advances:PLA and PBAT blends achieving comparable tensile strength to conventional polyethylene are penetrating commercial heavy-duty applications previously resistant to bio-based substitution.
Market Restraints
- Post-consumer resin price volatility:Collection infrastructure gaps and export market competition for baled film are inflating rPE pellet costs relative to virgin polyethylene benchmarks.
- Texas and Florida preemption statutes:State-level prohibitions on local bag bans fragment compliance requirements for manufacturers selling across jurisdictions with divergent regulatory frameworks.
- Composting infrastructure asymmetry:Industrial composting facility concentration in coastal states leaves interior markets without end-of-life processing capacity for certified compostable products.
Strategic Opportunities
- Mexico manufacturing expansion:Proximity to US Southwest distribution hubs and favorable resin feedstock access position Mexican blown film capacity for North American supply chain integration.
- Healthcare waste stream specialization:Biohazard and pharmaceutical waste containment requirements create premium positioning for puncture-resistant, multi-layer coextruded formulations with traceability documentation.
- Extended producer responsibility consultations:Health Canada and CCME harmonization efforts signal forthcoming packaging stewardship obligations that will favor vertically integrated suppliers with lifecycle accountability systems.
Industry Challenges
- BPI and ASTM D6400 certification timelines:Third-party testing and facility audit requirements extend product qualification cycles, delaying revenue recognition for new compostable formulations.
- Blown film equipment reconfiguration:Transitioning extrusion lines between conventional polyethylene and bio-based resins requires screw and die modifications that idle production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Trash Bags Market |
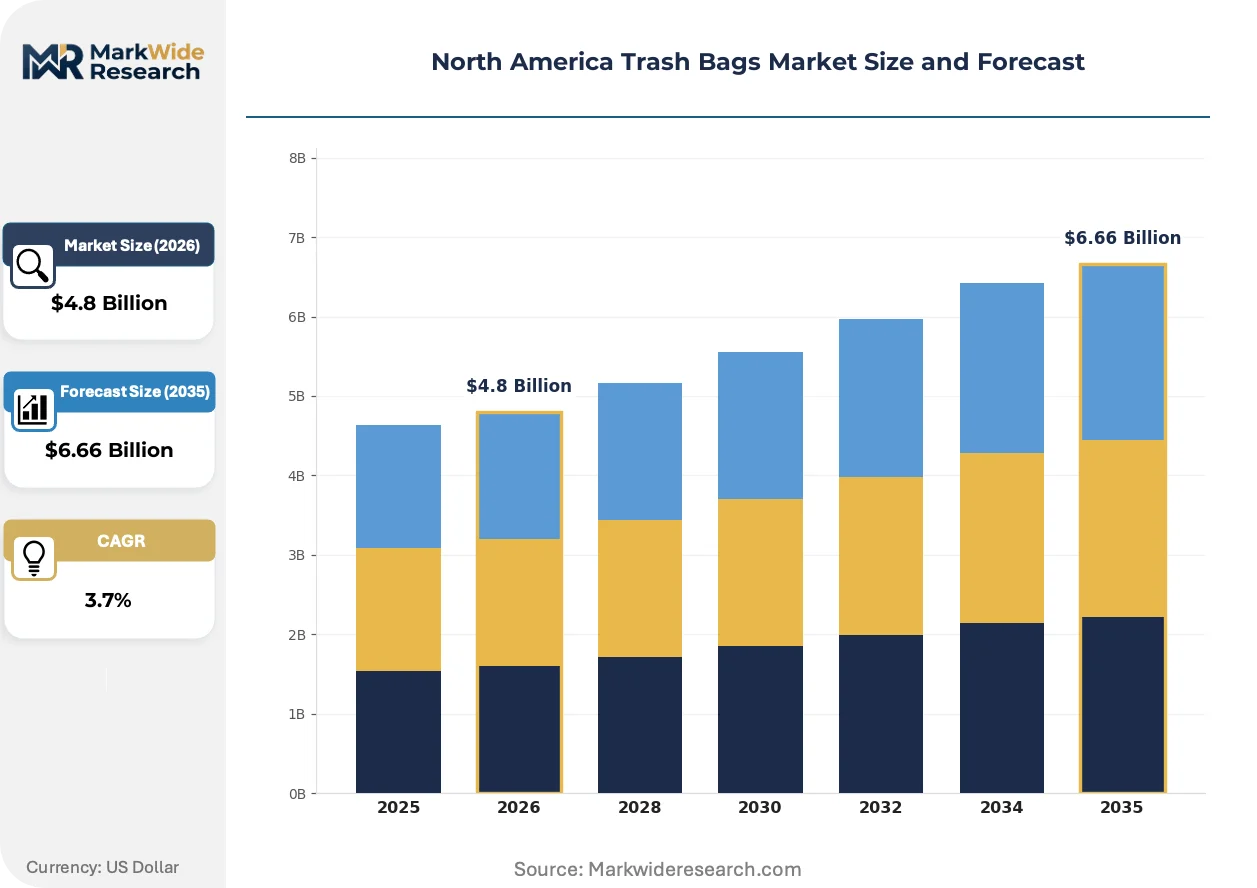
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Heavy-Duty Bags, Biodegradable Bags, Specialty Bags Size: Small, Medium, Large, Extra Large Material: Plastic, Paper, Compostable, Recycled Material Application: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Novolex Holdings LLC, Poly-America L.P., The Glad Products Company, International Plastics Inc., AEP Industries Inc., Berry Global Inc., Inteplast Group, Hefty, Reynolds Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Trash Bags Market Evolving Landscape
Material science breakthroughs and procurement specification tightening are compressing the viable technology set for North American trash bag manufacturers, privileging suppliers with integrated formulation and certification capabilities.
Multi-layer coextrusion technology is consolidating competitive positioning in premium commercial segments. Food service and healthcare waste generators specify mil thickness, dart impact resistance, and seal strength metrics that monolayer films cannot achieve. Novolex Holdings and Berry Global deploy seven-layer lines to engineer proprietary barrier structures, compressing R&D differentiation timelines for mid-tier competitors lacking comparable capital equipment.
EPA sustainable materials management priorities are redirecting federal procurement specifications toward post-consumer recycled content thresholds. The agency's purchasing guidelines influence state and municipal tender requirements, cascading compliance obligations through private-label supply chains. California and New York procurement offices now embed recycled-content verification in contract awards, pressuring manufacturers to document resin provenance through mass-balance certification.
Direct sourcing relationships between waste haulers and film converters are displacing traditional distribution intermediaries in commercial channels. Republic Services and Waste Management negotiate volume commitments with compounders for color-coded, density-specified liners tailored to automated collection equipment. This channel compression concentrates pricing leverage with national accounts and erodes regional distributor margins in metropolitan markets with consolidated waste service provision.
North America Trash Bags Market Segmentation
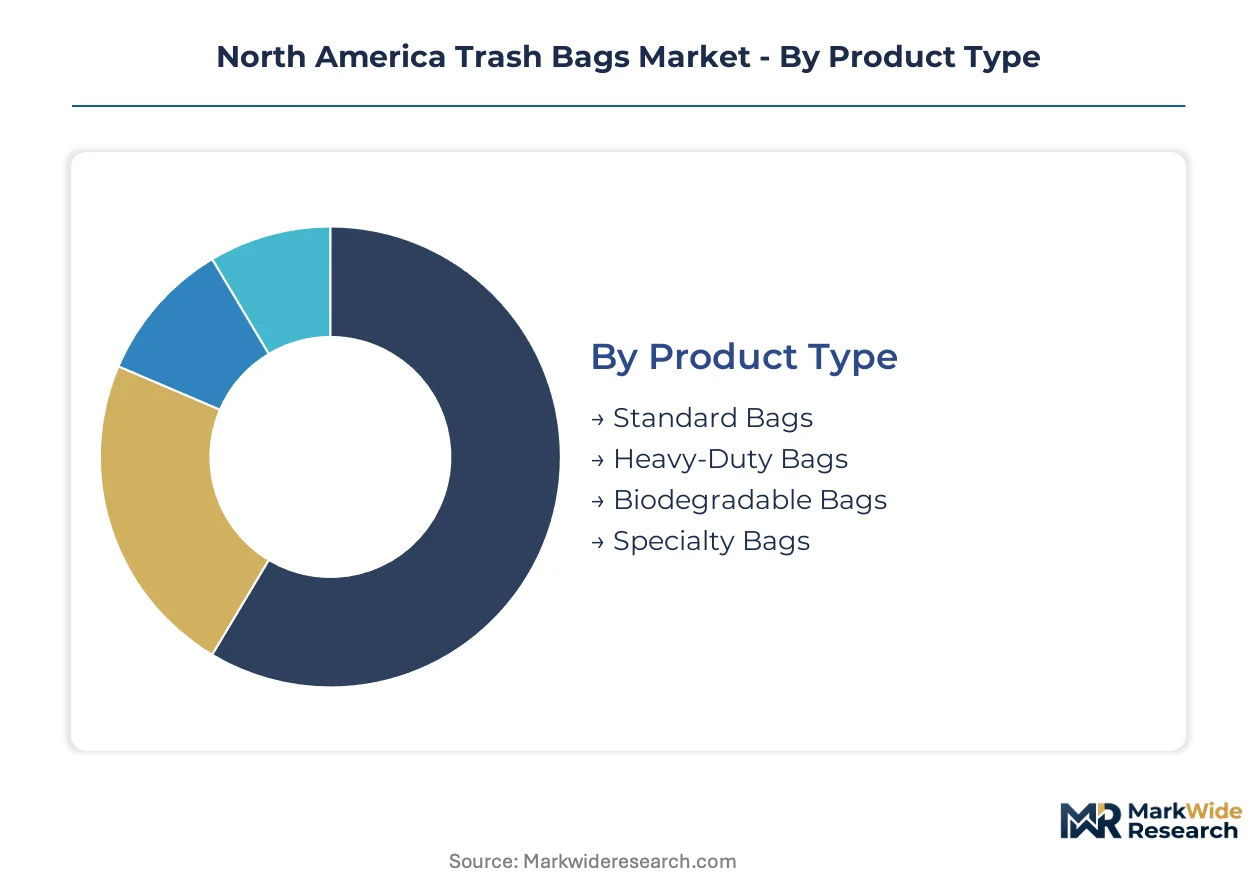
Trash bag manufacturers configure production lines around load-bearing specifications and end-of-life pathways. Segmentation choices determine resin sourcing strategies, certification requirements, and channel access across municipal procurement and retail distribution.
Product Type:
Volume concentrates in commodity-grade formulations while premium pools accrue to certified specialty products with compliance documentation.
- Standard Bags:Monolayer polyethylene films engineered to 0.5-1.0 mil thickness for residential kitchen and bathroom containment. Demand clusters in California and New York retail channels where SB 270 and bag waste reduction acts mandate recycled-content thresholds. Margin compression intensifies as virgin resin substitution costs rise.
- Heavy-Duty Bags:Multi-layer coextruded constructions achieving 40+ pound load capacity through reinforced star-seal bottoms and puncture-resistant sidewalls. Commercial waste haulers in the Northeast corridor specify these for restaurant and retail back-of-house collection where automated compaction equipment applies mechanical stress.
- Biodegradable Bags:PLA and PBAT blends requiring ASTM D6400 certification for industrial composting acceptance. Adoption accelerates in cities with organics diversion mandates.
- Specialty Bags:Healthcare biohazard and odor-control formulations with traceability documentation for regulated waste streams.
Today's leader: Standard Bags. Tomorrow's challenger: Biodegradable Bags.
Size:
Capacity specifications align with collection equipment dimensions and handling ergonomics across residential and commercial settings.
- Small:4-8 gallon capacity for bathroom and office wastebaskets. Hotels and commercial real estate procure these in bulk for uniform placement across property portfolios.
- Medium:13-gallon kitchen canister standard dominates unit volume in US retail. Costco and Walmart private-label programs concentrate procurement here.
- Large:30-33 gallon roll-out cart liners for municipal curbside collection. Specifications vary by automated lift mechanism design across hauler fleets.
- Extra Large:55+ gallon drum liners for industrial and construction debris. Thickness and seam strength requirements exceed residential grades significantly.
Medium sizes generate the highest unit velocity. Extra Large commands the strongest per-unit margin.
Material:
Feedstock selection determines regulatory compliance posture and end-of-life processing options available to waste generators.
- Plastic:Virgin and recycled polyethylene formulations comprising the majority of tonnage. Post-consumer resin integration rates climb under EPA sustainable materials management procurement guidelines.
- Paper:Kraft and wet-strength grades for food service and yard waste applications where composting is the designated disposal pathway. Performance limitations restrict penetration in wet waste streams.
- Compostable:BPI-certified films meeting ASTM D6400 for municipal organics diversion programs. Qualification barriers concentrate supply with certified compounders.
- Recycled Material:Post-consumer and post-industrial content blends qualifying for California and New York recycled-content mandates. Mass-balance certification requirements complicate supply chain documentation.
Plastic maintains volume dominance. Compostable exhibits the steepest expansion trajectory.
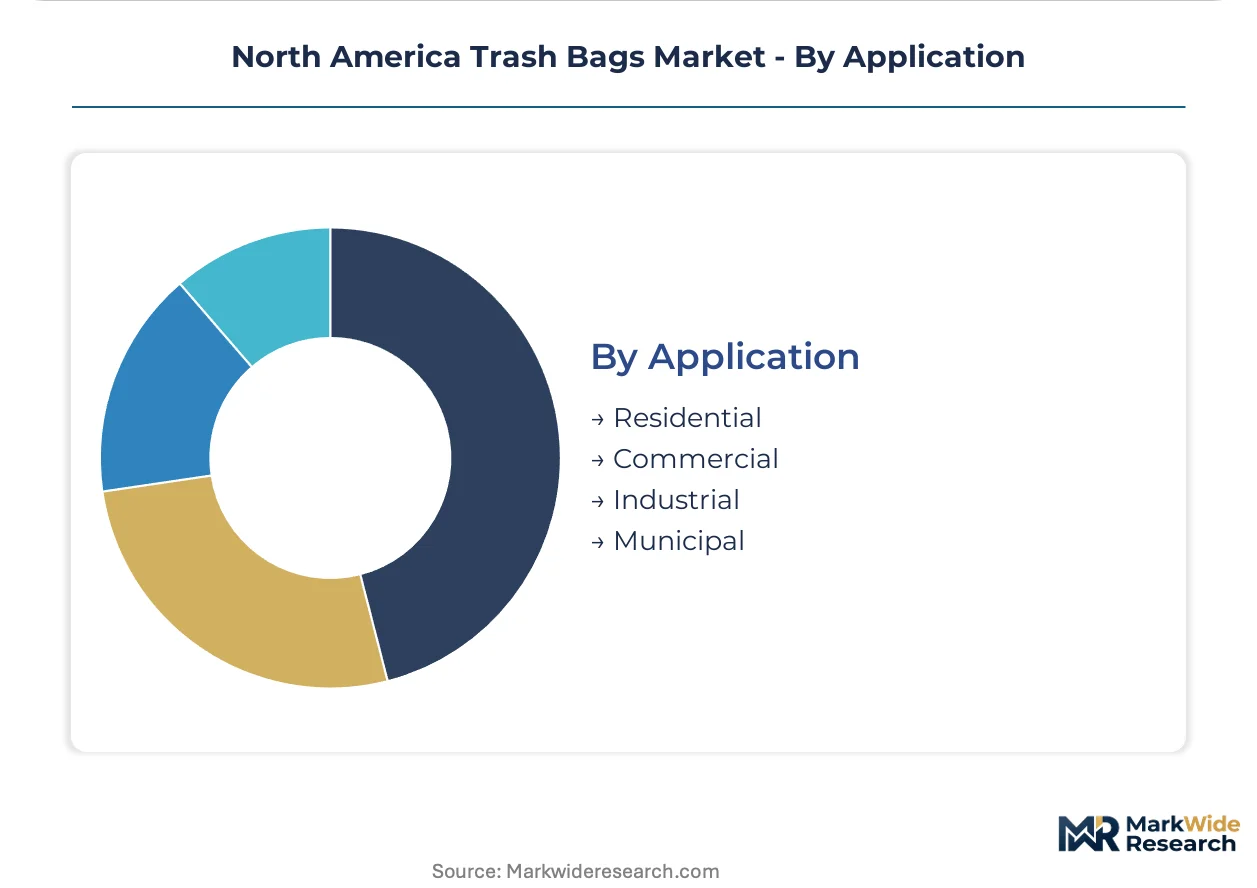
Application:
End-use segmentation separates price-sensitive household procurement from specification-driven commercial and municipal tender processes.
- Residential:Retail and subscription channels serving single-family and multi-unit dwellings. California and New York consumers face the most restrictive bag-ban compliance requirements.
- Commercial:Food service, retail, and office generators purchasing through distribution or direct hauler relationships. Color-coding and density specifications align with automated sorting equipment.
- Industrial:Manufacturing and construction debris containment requiring puncture and tear resistance beyond standard grades. Volume concentrates in Texas and Gulf Coast petrochemical corridors.
- Municipal:City and county procurement for public facilities and curbside collection programs. Extended producer responsibility consultations in Canada signal forthcoming stewardship obligations.
Municipal tenders offer the longest contract duration. Commercial direct sourcing is displacing traditional distribution fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas petrochemical corridor anchors North American resin supply for trash bag manufacturing, with integrated polyethylene production feeding blown film operations across the Gulf Coast. State-level regulatory fragmentation and municipal procurement shifts are redirecting distribution patterns toward California and Northeast markets with stringent sustainability mandates.
United States
California SB 270 and New York's bag waste reduction act mandate recycled-content thresholds in retail channels. EPA sustainable materials management priorities cascade through federal procurement guidelines. Cities across the Northeast corridor specify ASTM D6400-certified compostable liners for curbside organics collection.
Canada
Health Canada and the Canadian Council of Ministers of the Environment advance harmonized extended producer responsibility consultations for packaging stewardship. Municipal procurement in Ontario and British Columbia embeds recycled-content verification requirements. Toronto and Vancouver organics diversion programs drive demand for BPI-certified compostable films.
Mexico
Proximity to US Southwest distribution hubs positions Mexican blown film capacity for North American supply chain integration. Favorable resin feedstock access from Pemex petrochemical complexes supports cost-competitive production. Mexico City and Nuevo León industrial clusters serve cross-border private-label and branded channel demand.
North America Trash Bags Market Competitive Landscape
Global majors compete with regional champions across resin sourcing and certification capabilities in the North America trash bags market. The vendor base spans integrated resin compounders, multi-site film converters, and specialized compostable formulators. Three archetypes dominate: captive recycling operators controlling post-consumer feedstock costs, backward-integrated resin producers with compounding assets, and certified compostable specialists with BPI qualification. Competitive moves concentrate on extrusion line reconfiguration for bio-based resins and direct hauler relationships bypassing traditional distribution.
Among North American film converters, Novolex Holdings LLC, Poly-America L.P., and Berry Global Inc. represent distinct strategic positions within the competitive structure. Novolex exemplifies the captive recycling archetype with infrastructure controlling post-consumer polyethylene feedstock costs. Poly-America L.P. occupies a backward-integrated position through resin compounding operations. Berry Global anchors multi-site blown film capacity serving heterogeneous channel requirements across private-label and branded segments.
| Leading Market Players |
|---|
| Novolex Holdings LLC |
| Poly-America L.P. |
| The Glad Products Company |
| International Plastics Inc. |
| AEP Industries Inc. |
| Berry Global Inc. |
| Inteplast Group |
| Hefty |
| Reynolds Consumer Products |
| Others |
Value Network & Pricing Analysis
Municipal procurement offices in California and New York concentrate demand for certified compostable and recycled-content liners, anchoring a contract-based pricing structure where ASTM D6400 certification and mass-balance documentation command measurable premiums over commodity polyethylene grades.
Pricing Analysis
Post-consumer recycled polyethylene pellet costs pass through directly to finished bag pricing, with rPE feedstock trading at persistent premiums to virgin resin benchmarks due to collection infrastructure gaps. Pricing stratifies across premium certified compostable, standard virgin polyethylene, and economy recycled-content tiers, with differentiation driven by certification level and volume scale. Cost compression in standard residential grades is intensifying as virgin substitution rates climb under state mandates. Small commercial generators exhibit highest price sensitivity, while municipal tenders with multi-year durations show lowest elasticity due to specification lock-in.
Supply Chain Analysis
Rail and trucking freight costs from Texas petrochemical corridors to California and Northeast distribution hubs represent a structural cost layer that Mexican manufacturing alternatives are exploiting through proximity to Southwest markets. Resin supply draws from integrated polyethylene production along the Texas Gulf Coast, with Pemex complexes in Mexico offering secondary feedstock access. Raw material dependencies center on ethylene feedstock, calcium carbonate fillers, and colorant masterbatches. Single-source vulnerability concentrates in post-consumer resin collection networks where export market competition for baled film disrupts domestic supply. Distribution runs through direct hauler relationships and traditional industrial distribution, with channel compression accelerating in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where California SB 270 and analogous state mandates create tiered demand expansion for certified products that conventional polyethylene cannot satisfy.
For Market Incumbents: Anticipate accelerated margin compression in virgin polyethylene standard bags as recycled-content mandates proliferate across additional states. Defensive positioning requires captive recycling infrastructure investment to control rPE feedstock costs and lock in municipal tender compliance. BPI certification capacity expansion represents the critical lever for accessing organics diversion program demand in the Northeast corridor. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels offer the most penetrable route for compostable specialty brands seeking to bypass consolidated retail shelf access controlled by incumbent private-label suppliers. White-space targets include healthcare biohazard formulations with traceability documentation and odor-control premium tiers for multi-unit residential subscriptions. A sustainability-native positioning with transparent supply chain storytelling provides the strongest go-to-market angle against commodity incumbents. For Investors and Strategic Acquirers: Waste management majors are the most active acquirer in this space, seeking backward integration into film supply to secure liner specifications for automated collection equipment. The five-to-ten year viability window favors vertically integrated compounders with certification capabilities over pure-play converters exposed to resin price volatility. Acquisition targets should display BPI qualification and municipal contract backlog. The signal to watch is federal procurement standard finalization for recycled-content thresholds, which would inflect demand composition decisively toward certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM D6400 Certification Investment | Unlocks municipal organics diversion contracts in California and New York markets. |
| Captive Recycling Infrastructure | Insulates margin structures from rPE feedstock price volatility driven by export competition. |
| Direct Hauler Relationship Development | Bypasses distributor intermediaries in commercial channels where Waste Management and Republic Services consolidate purchasing. |
| Mexico Manufacturing Footprint | Captures freight cost advantages serving Southwest distribution hubs from Pemex feedstock access. |
| Healthcare Waste Specialization | Commands premium positioning through multi-layer coextrusion and traceability documentation for biohazard applications. |
Research Methodology
Multiple input streams — executive interviews with blown film operations managers and municipal procurement officers, customs and trade flow data, and EPA sustainable materials management documentation — were reconciled through bottom-up facility capacity mapping and top-down demand segmentation validation. Primary fieldwork engaged resin compounders, waste hauler fleet managers, and retail category buyers across California, Texas, and New York markets. Secondary sources included SEC 10-K filings from integrated packaging suppliers, state environmental agency procurement databases, and BPI certification registry records.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct segment-level projections across the analysis window. The analytical framework modeled demand by product type, material composition, application channel, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted penetration curves for compostable alternatives and recycled-content mandate compliance schedules. Key forecast inputs included municipal organics diversion program rollout timelines and post-consumer resin collection capacity expansion announcements.
Regulatory preemption battles, industrial composting facility buildout delays, and rPE collection infrastructure investment shortfalls are the dominant revision risks that could compress or extend modeled adoption curves. Stakeholders should weight assumptions against their own operating context and regional exposure to state-level policy fragmentation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
US Medical Waste Management Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Medical Waste Management System Market