
 Compostable Straws Market | 2026-2036
Compostable Straws Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Straws Market Outlook
Plant-based polymer extrusion is reconfiguring how straw manufacturers balance performance with biodegradation timelines. Huhtamaki leverages its European production footprint to supply major food service chains with certified compostable lines. Footprint LLC differentiates through fiber-based molded technology that eliminates plastic entirely. Vegware anchors its competitive position with closed-loop composting partnerships across the United Kingdom and Ireland.
Compostable straws are single-use drinking implements engineered from biopolymers or plant fibers to degrade under industrial composting conditions within 90 to 180 days, with diameter tolerances typically ranging from 4 mm to 8 mm and wall thickness optimized for liquid immersion stability up to 4 hours. Their primary commercial purpose is to replace petroleum-based plastic straws in food service and retail channels without compromising consumer functionality. PLA straws currently dominate volume due to mature resin supply chains and favorable unit economics, though PHA straws represent the fastest-expanding category as marine biodegradability certifications open coastal market access. Paper straws sustain significant share in quick-service applications where cost sensitivity outweighs extended-use performance requirements.
The EU Single-Use Plastics Directive, FDA food contact substance notifications, and BPI certification requirements collectively determine which materials gain food service procurement approval and which formulations face market exclusion. State-level plastic straw bans in California, New York, and Washington create patchwork compliance obligations that favor suppliers with multi-certification portfolios. Stakeholders must monitor evolving industrial composting infrastructure availability, as compostable straw claims remain contingent on regional processing capacity rather than material properties alone.
Market Dynamics
Industrial composting infrastructure gaps are fragmenting market access, forcing suppliers to validate regional processing capacity before certifying products for food service procurement. Material science advances in marine-biodegradable resins are compressing certification timelines while expanding addressable coastal markets.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory phase-outs of petroleum-based straws across member states are redirecting quick-service restaurant procurement toward certified compostable alternatives with BPI or OK Compost INDUSTRIAL labels.
- PHA resin production scale-up:Fermentation-based polyhydroxyalkanoate manufacturing is achieving cost parity with PLA in coastal markets where marine biodegradability certifications command procurement premiums.
- Quick-service restaurant chains:System-wide plastic elimination commitments by major food service operators are consolidating demand into multi-year supply contracts with certified compostable straw manufacturers.
Market Restraints
- Industrial composting facility scarcity:Limited regional processing capacity in the United States Midwest and Southern states invalidates compostability claims regardless of material certification.
- PLA resin price volatility:Corn feedstock cost fluctuations and lactic acid supply concentration in Chinese manufacturing create input cost instability for biopolymer straw producers.
- Performance limitations in hot beverages:PLA glass transition temperatures below 60°C restrict application in coffee service, ceding share to fiber-based alternatives with higher thermal tolerance.
Strategic Opportunities
- Closed-loop composting partnerships:Direct arrangements between straw suppliers and regional composting operators in the United Kingdom and Ireland are securing guaranteed end-of-life processing capacity.
- Home-compostable certification pathways:Emerging TÜV Austria OK Compost HOME standards are opening residential disposal routes in markets lacking industrial infrastructure.
- Marine biodegradability positioning:ASTM D6691 and D6692 certifications for PHA formulations are capturing coastal food service and cruise line procurement specifications.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous BPI, CMA, and OK Compost compliance requirements demand specialized regulatory affairs capacity and extended product validation timelines.
- Food contact substance notification delays:FDA FCN processing backlogs for novel biopolymer formulations are extending time-to-market for next-generation straw materials by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Straws Market |
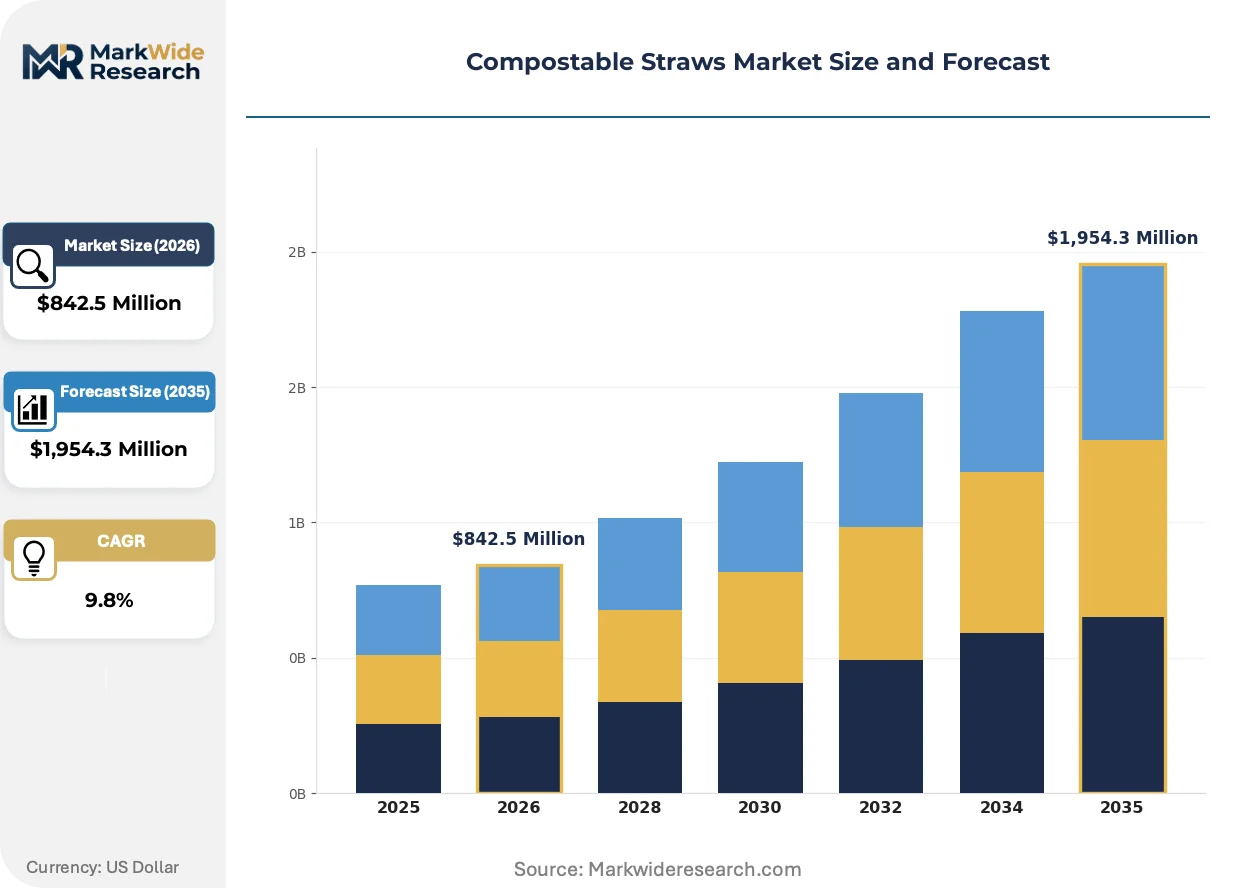
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,954.3 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA Straws, PHA Straws, Paper Straws, Sugarcane Straws Material: Corn Starch, Bamboo, Wheat Straw, Recycled Paper End User: Food Service, Retail, Home Use, Events Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Vegware, Biopac, Huhtamaki, Canada Brown Eco Products, Transcend Packaging, Footprint LLC, Tetra Pak, Sulapac Ltd, Hoffmaster Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Straws Market Strategic Shifts
Material virtualization is compressing the boundary between biopolymer and fiber-based straw architectures, enabling hybrid formulations that optimize for both performance and end-of-life processing. Regulatory fragmentation across jurisdictions is accelerating certification specialization among suppliers.
PHA fermentation technology is virtualizing the traditional PLA-dominated supply structure by enabling marine-biodegradable straw production without industrial composting dependency. Coastal quick-service operators in California and Washington are adopting PHA formulations at accelerated rates to preempt state-level marine plastic pollution mandates. This virtualization is collapsing the historical trade-off between performance stability and environmental credential breadth.
REACH registration requirements for novel biopolymer additives are tightening substance authorization pathways for straw manufacturers supplying European food service chains. The European Chemicals Agency's expanded scrutiny of polymer processing aids is forcing reformulation of PLA compounds used in high-throughput extrusion lines. German and French procurement specifications now explicitly require REACH-compliant supply chain documentation.
Chain-level sustainability scorecards are consolidating buyer power around vendors offering verified lifecycle assessments and carbon footprint disclosures. Quick-service restaurant sustainability teams are unbundling straw purchasing from broader food service packaging contracts to apply specialized compostability criteria. This concentration is most visible in United Kingdom and United States coastal metropolitan markets where consumer-facing environmental claims face heightened scrutiny.
Compostable Straws Market Segmentation
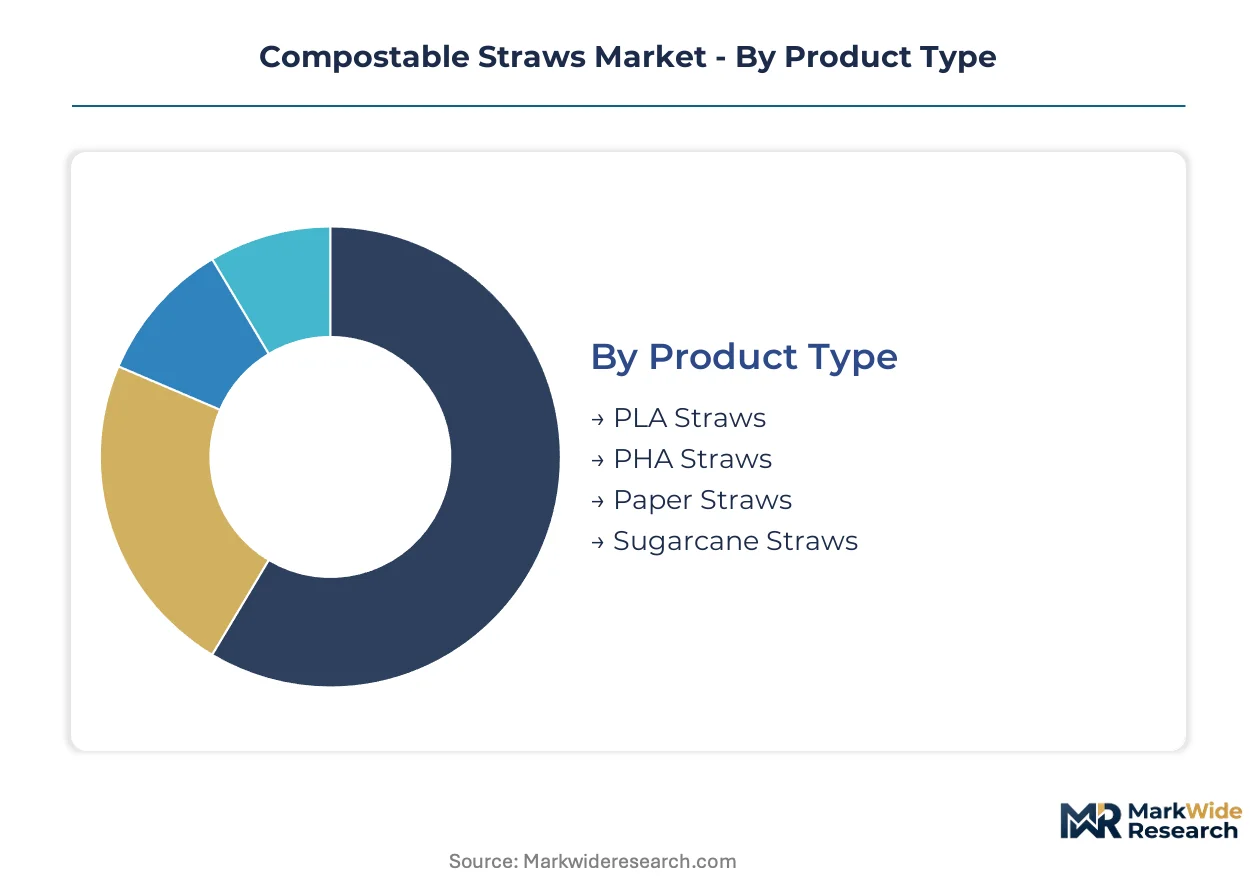
Segmentation in the compostable straws market reflects divergent technical capabilities across material platforms and the uneven distribution of composting infrastructure that validates end-of-life claims. Procurement patterns vary sharply between food service operators seeking certified supply contracts and retail channels prioritizing shelf stability and unit cost.
Product Type:
Mature extrusion technologies dominate volume production, while emerging resin categories are capturing specialized coastal applications through differentiated biodegradation credentials.
- PLA Straws:Polylactic acid formulations leverage established corn-derived resin supply chains and FDA food contact notifications to serve high-volume quick-service restaurant contracts. United States procurement concentrates in California and New York state-level mandate compliance, though PLA glass transition limitations below 60°C restrict hot beverage applications and cede share in coffee service channels.
- PHA Straws:Marine-biodegradable polyhydroxyalkanoate resins produced through fermentation processes achieve ASTM D6691 certification for coastal disposal environments. Washington and California food service operators are adopting PHA formulations preemptively ahead of anticipated state marine plastic pollution mandates, with procurement premiums attached to ocean-end-of-life credentials.
- Paper Straws:Fiber-based rolled constructions using FDA-compliant adhesives serve cost-sensitive quick-service applications where extended immersion stability is secondary to unit economics.
- Sugarcane Straws:Bagasse-derived molded fiber products eliminate plastic content entirely and target European markets with aggressive single-use plastics phase-out timelines under EU Directive enforcement.
PLA straws handle the majority of throughput; PHA straws are expanding most quickly on share through marine certification differentiation.
Material:
Feedstock provenance determines certification eligibility and regional supply security, with agricultural residue streams gaining traction as corn price volatility disrupts traditional biopolymer economics.
- Corn Starch:Dominant feedstock for PLA resin production with mature lactic acid fermentation infrastructure concentrated in Chinese and United States manufacturing bases. Price volatility from agricultural commodity markets creates input cost instability for straw extruders dependent on this supply chain.
- Bamboo:Rapid-renewal grass species with high cellulose content enables fiber-based straw production without agricultural land competition. Asian manufacturing clusters leverage domestic bamboo supply for export-oriented production serving European and North American private-label retail contracts.
- Wheat Straw:Agricultural residue stream from grain processing provides low-cost lignocellulosic fiber for molded pulp straw applications, particularly in European markets where circular economy procurement criteria favor waste-derived inputs.
- Recycled Paper:Post-consumer fiber streams processed to food-grade standards support closed-loop sustainability claims for retail-branded straw products targeting environmentally conscious household purchasers.
Corn starch underpins current volume scale; bamboo is climbing the fastest as manufacturers seek supply chain resilience against agricultural commodity shocks.
End User:
Procurement sophistication varies dramatically across buyer categories, with institutional food service applying multi-certification compliance filters absent in consumer-directed channels.
- Food Service:Quick-service restaurant chains and contract catering operators mandate BPI or OK Compost INDUSTRIAL certification as a condition of supply contract eligibility. United Kingdom and Ireland operators are pioneering closed-loop composting partnerships that guarantee end-of-life processing capacity for certified straw volumes.
- Retail:Supermarket and convenience store channels prioritize unit cost and shelf stability over composting infrastructure verification, with private-label products dominating volume.
- Home Use:Direct-to-consumer sales through e-commerce platforms emphasize home-compostable claims where TÜV Austria OK Compost HOME certification provides differentiation in markets lacking industrial composting access.
- Events:Temporary food service installations at festivals and sporting venues generate concentrated demand spikes with limited control over post-use disposal routing.
Food service channels command the steepest certification requirements; home use is gaining share fastest through residential disposal route expansion.
Distribution Channel:
Channel selection determines buyer access to certification documentation and volume pricing tiers, with institutional procurement consolidating through specialized supply arrangements.
- Online Retail:Direct-to-consumer platforms enable niche product discovery and subscription-based replenishment models for household compostable straw purchasers. Amazon and specialized eco-product marketplaces provide access to TÜV Austria and BPI certification documentation that retail packaging often omits.
- Supermarkets:Mass-market retail placement requires competitive unit pricing and shelf-stable packaging formats that may compromise compostability timelines through moisture barrier requirements.
- Specialty Stores:Zero-waste and natural product retailers curate certified compostable assortments with staff training on proper disposal routing, commanding premium positioning.
- Wholesalers:Food service distribution intermediaries consolidate multi-product orders for restaurant operators, with certification documentation bundled for procurement compliance verification.
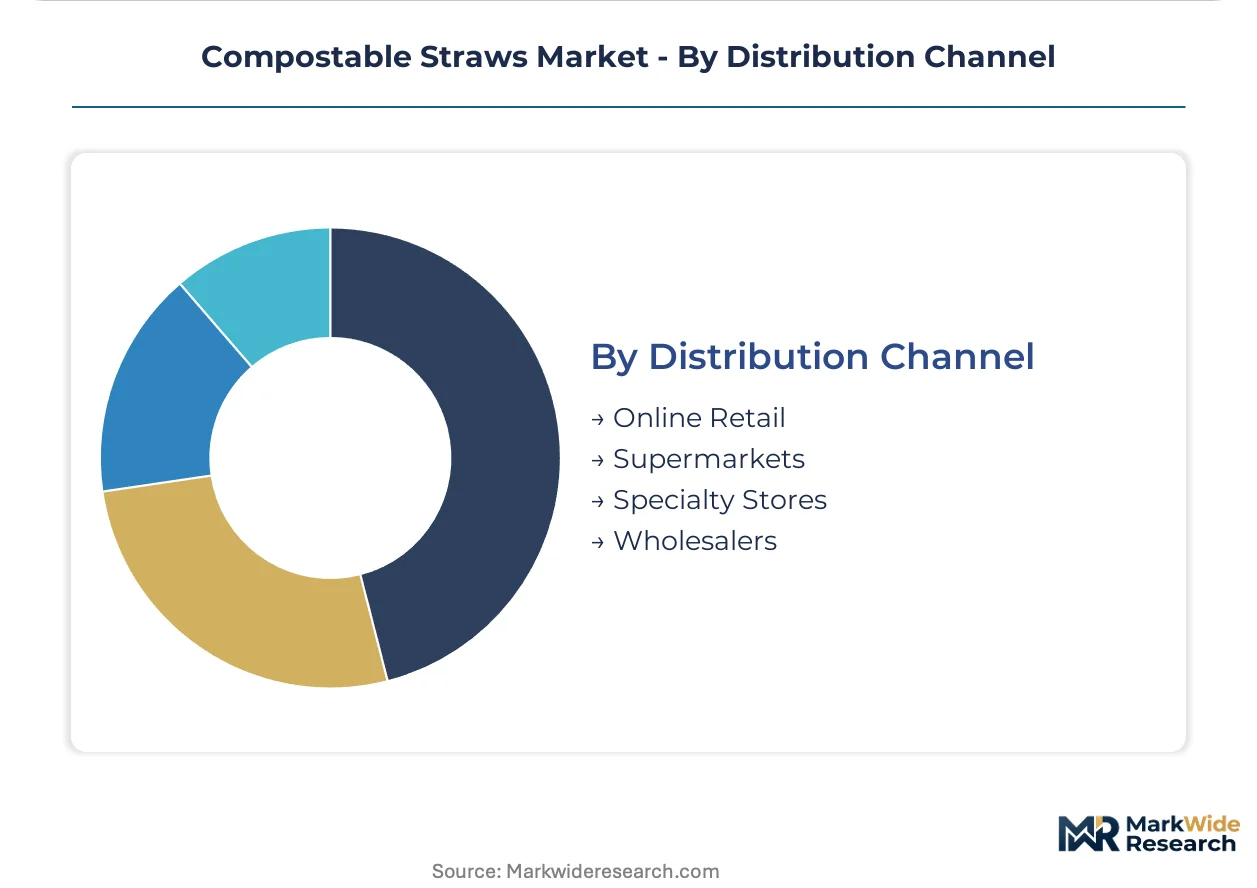
Wholesalers move the largest institutional volumes; online retail is expanding most quickly through direct certification transparency and subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese biopolymer resin manufacturers export PLA compounds to European and North American straw extruders, establishing a trade corridor that feeds California, New York, and German industrial clusters with certified compostable feedstock.
United States
Quick-service restaurant chains in California and Washington drive procurement volume for marine-biodegradable PHA formulations. FDA food contact substance notifications govern material approval timelines for novel biopolymer straws. Los Angeles and San Francisco Bay Area food service operators pilot closed-loop composting partnerships with regional waste processors.
Germany
Industrial composting infrastructure density supports high-volume PLA straw adoption across quick-service and contract catering channels. REACH registration requirements for polymer additives tighten supply chain documentation obligations for food service distributors. Bavaria and North Rhine-Westphalia host extrusion facilities supplying certified compostable lines to EU-wide food service contracts.
United Kingdom
Closed-loop composting partnerships between straw suppliers and regional operators guarantee end-of-life processing capacity for certified volumes. The UK Environment Agency enforces packaging waste regulations that favor industrial compostable claims with verified disposal routing. London and Greater Manchester concentrate food service procurement teams mandating BPI or OK Compost INDUSTRIAL certification.
France
Coastal food service operators in Provence-Alpes-Côte d'Azur adopt marine-biodegradable straws to address Mediterranean plastic pollution visibility. ECHA scrutiny of polymer processing aids forces reformulation of high-throughput PLA compounds. Paris Île-de-France anchors national procurement consolidation for major quick-service restaurant sustainability scorecards.
Canada
Provincial single-use plastics phase-outs in British Columbia and Quebec redirect food service procurement toward certified compostable alternatives. Health Canada food contact material notifications parallel FDA timelines for biopolymer approval. Toronto and Vancouver metropolitan areas concentrate quick-service chain procurement decisions with multi-certification compliance requirements.
Compostable Straws Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered certification and material technology vectors. The vendor base organizes around three strategic archetypes: integrated packaging conglomerates with European production footprints, fiber-based molded technology specialists eliminating plastic content entirely, and fermentation-based resin innovators capturing marine-biodegradable premiums. Consolidation pressures concentrate around multi-year supply contracts from quick-service restaurant chains. Competitive moves center on backward integration into resin supply and geographic expansion of certification portfolios across BPI, CMA, and OK Compost standards.
Within the integrated packaging tier, Huhtamaki Oyj and Tetra Pak Group exemplify scale-driven positions leveraging established European extrusion infrastructure. Among fiber-based specialists, Footprint LLC occupies a position representing molded pulp technology architectures that bypass polymer dependencies entirely. Fermentation-based material innovators include Sulapac Ltd, anchoring the marine-biodegradable vector through PHA resin applications. These three archetypes—integrated conglomerate, fiber specialist, and biopolymer innovator—capture distinct procurement preference clusters across food service, retail, and coastal market segments.
| Leading Market Players |
|---|
| Vegware |
| Biopac |
| Huhtamaki |
| Canada Brown Eco Products |
| Transcend Packaging |
| Footprint LLC |
| Tetra Pak |
| Sulapac Ltd |
| Hoffmaster Group |
| Others |
Value Chain & Pricing Dynamics
Chinese lactic acid fermentation clusters concentrate PLA resin supply for North American and European straw extruders, anchoring margin pools with food service distributors and quick-service procurement teams rather than manufacturers. Corn feedstock volatility transmits directly into biopolymer input costs, compressing extruder margins while certification premiums accrue downstream.
Pricing Analysis
Next-generation PHA formulations command procurement premiums against incumbent PLA and legacy paper constructions across coastal markets. Three-tier pricing structure across marine-certified premium, industrial-compostable standard, and fiber-based economy levels segments buyer access. Cost compression in PLA tiers is intensifying because Chinese resin supply concentration exposes extruders to agricultural commodity swings. Quick-service restaurant chains exhibit lowest price sensitivity due to mandate-driven procurement, while retail private-label channels absorb maximum cost pressure.
Supply Chain Analysis
Tariff exposure between Chinese resin manufacturers and United States extruders dominates supply chain risk calculations for biopolymer straw producers. Feedstock sourcing concentrates in Chinese and Thai lactic acid fermentation facilities, with secondary bamboo pulp processing anchored in Vietnamese and Indonesian fiber mills. Corn starch and bagasse dependencies create agricultural commodity tethering that amplifies margin volatility. Distribution runs through food service wholesalers consolidating multi-product orders for institutional buyers, with certification documentation bundled for compliance verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compostable straws market exhibits cyclical recovery characteristics as regulatory mandate waves refresh procurement cycles across successive jurisdiction adoptions. EU Directive enforcement and state-level plastic phase-outs generate recurring demand spikes that favor positioned suppliers.
For Market Incumbents: Pre-empt marine-biodegradable certification gaps by accelerating PHA resin partnerships before coastal mandates harden procurement specifications. Defend against fiber-based molded pulp substitution by extending thermal performance in next-generation PLA compounds. Backward integration into lactic acid supply secures margin control against Chinese feedstock volatility.
For New Entrants and Emerging Players: Pursue home-compostable certification white space in United States Midwest and Southern states where industrial composting infrastructure remains underdeveloped. Target residential disposal channels through TÜV Austria OK Compost HOME differentiation. Direct-to-consumer subscription models bypass wholesaler consolidation and capture premium positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fiber-based packaging specialists holding molded pulp technology patents and European food service contracts. Five-to-ten year viability hinges on multi-certification portfolio breadth rather than single-technology concentration. Watch FDA food contact notification backlogs as inflection signal for next-generation material time-to-market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| PHA Resin Supply Agreement | Fermentation-based marine-biodegradable capacity secures coastal procurement premiums ahead of mandate expansion. |
| Closed-Loop Composting Partnership | Direct arrangements with regional waste processors guarantee end-of-life processing capacity for certified straw volumes. |
| Multi-Certification Portfolio Expansion | Simultaneous BPI, CMA, and OK Compost compliance unlocks cross-jurisdiction food service contract eligibility. |
| Backward Integration into Lactic Acid | In-house production of PLA feedstock insulates margin structure from Chinese corn starch price volatility. |
| Home-Compostable Product Line Launch | TÜV Austria OK Compost HOME certification opens residential disposal routes in infrastructure-constrained markets. |
Study Parameters
Operator-level perspectives from food service procurement directors, composting facility operators, biopolymer resin technical leads, and quick-service sustainability officers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA food contact substance notifications, BPI certification databases, EU Single-Use Plastics Directive implementation reports, and SEC filings from listed packaging conglomerates. Bottom-up volume modeling and top-down market sizing triangulated across extrusion capacity estimates and food service contract disclosure patterns.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, upside, and downside pathways reflecting regulatory enforcement variance and composting infrastructure buildout rates. Segmentation dimensions modeled include material platform, certification tier, end-use channel, and regional mandate status. CAGRs derived from fitted growth curves applied to disclosed contract volumes and procurement commitment timelines. Industry-specific forecast inputs incorporated PLA resin price indices and industrial composting facility commissioning announcements.
Sensitivities concentrate around FDA notification processing delays, EU Directive enforcement intensity, and regional composting capacity expansion schedules. Forecasts reflect assumptions regarding mandate adoption timelines and certification standard harmonization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market