
 Global Smart Trash Bin Market | 2026-2036
Global Smart Trash Bin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Trash Bin Market Foresight
The capital-intensity divergence between sensor-embedded hardware developers and basic receptacle manufacturers is unwinding competitive boundaries across the waste technology landscape. Bigbelly leverages its solar-powered compacting infrastructure to dominate municipal street deployments in dense urban cores. CleanRobotics sustains R&D intensity around AI-driven sorting algorithms that distinguish recyclables from landfill streams. Ecube Labs anchors its position through IoT-enabled fill-level monitoring that integrates with fleet logistics software.
A smart trash bin is an electronically augmented waste receptacle incorporating infrared or ultrasonic sensors, Bluetooth or IoT connectivity, and automated mechanisms for lid actuation, compaction, or content identification, designed to optimize collection scheduling and reduce operational labor in high-traffic environments. Sensor-based bins lead commercial installations where hygiene automation reduces touchpoints, while compacting variants capture expanding share in transportation hubs where volume reduction directly lowers haulage frequency. IoT integration represents the fastest-growing technology dimension as waste management firms demand real-time data streams for predictive routing.
The EU Green Deal and F-Gas Regulation shape product standards for embedded cooling components in organic waste bins, while Japan's METI enforces JIS interoperability standards for connected city infrastructure. The US EPA and municipal procurement codes in cities like San Francisco and New York mandate diversion-rate compliance that smart sorting capabilities address. Stakeholders must monitor evolving e-waste directives governing the disposal of sensor-laden bin components at end-of-life.
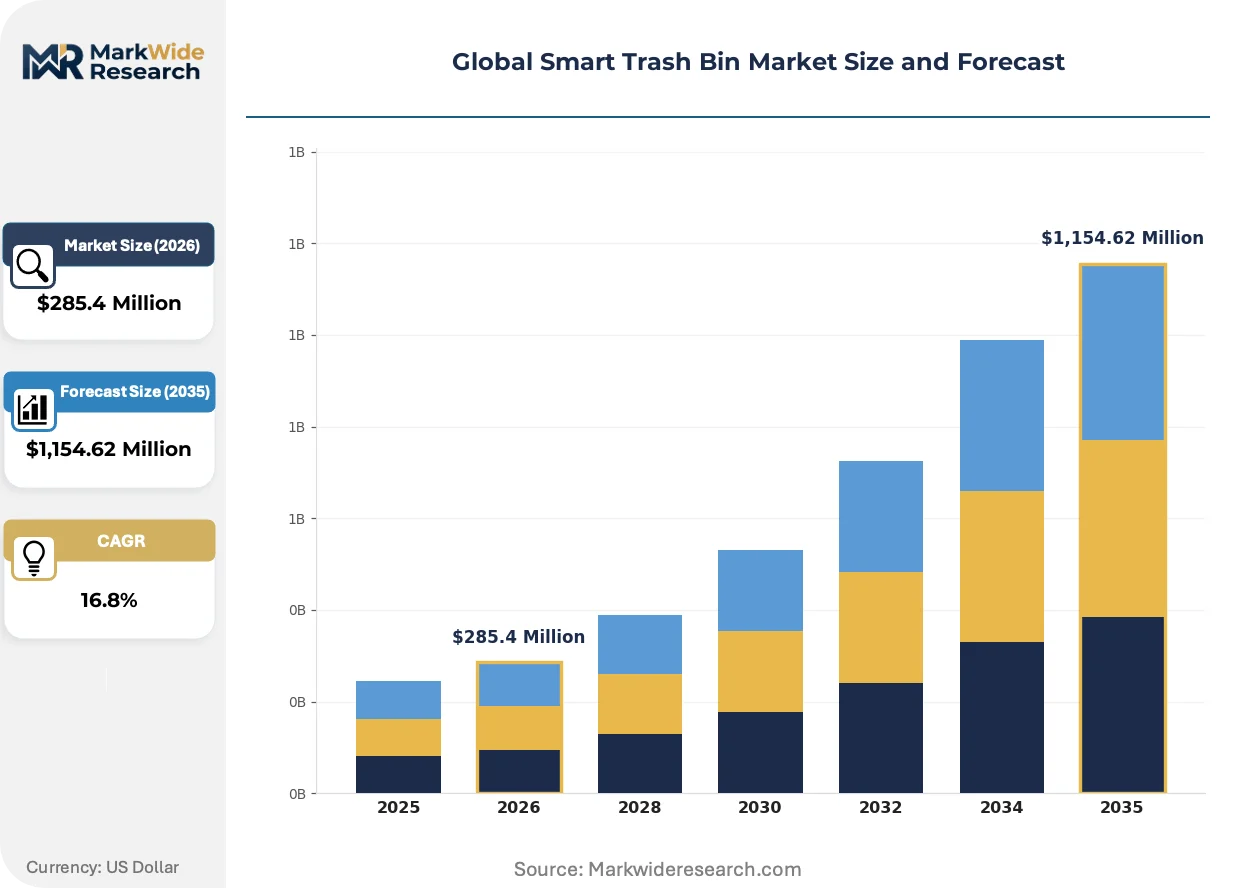
Market Dynamics
Sensor-to-cloud integration is compressing collection cycles across municipal fleets, forcing incumbents to restructure hardware margins around recurring software revenues rather than unit sales.
Growth Catalysts
- EU Green Deal circular economy mandates:Binding diversion-rate targets for municipal waste streams in France, Germany, and Italy are accelerating procurement of sorting-capable bins.
- Japan's metropolitan density:Tokyo and Osaka transit authorities are deploying compacting units in subway corridors where haulage access is restricted.
- Computer vision integration:AI-driven content identification is reducing contamination rates in commercial food courts and airport terminals.
Market Restraints
- Li-ion battery supply concentration:South Korean and Chinese cell manufacturers dominate power modules for solar-compacting units, exposing buyers to input volatility.
- RoHS compliance friction:Embedded electronics in sensor housings face restricted substance thresholds that extend certification timelines for European deployments.
- Mechanical compaction durability limits:Hydraulic systems in high-cycle environments require component replacement at 18-24 month intervals, elevating total cost of ownership.
Strategic Opportunities
- India's smart cities mission:Municipal corporations in Bangalore, Hyderabad, and Pune are piloting fill-level monitoring for informal sector integration.
- LEED certification pathways:Waste diversion point systems in green building standards are creating specification pull from facility managers in Singapore and Australia.
- 5G-enabled edge computing:Low-latency connectivity is enabling real-time compaction triggers and predictive maintenance alerts in South Korean testbeds.
Industry Challenges
- Embedded systems firmware expertise:Shortage of engineers with IoT security and over-the-air update capabilities is delaying product roadmaps.
- Interoperability certification backlog:JIS standards compliance for Japanese connected infrastructure requires 8-14 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Trash Bin Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor-based Bins, Solar-powered Bins, Voice-controlled Bins, Compacting Bins, Manual-operated Bins Technology: Infrared Sensors, Ultrasonic Sensors, Bluetooth Connectivity, IoT Integration, RFID Tagging Application: Commercial Complexes, Educational Institutions, Public Parks, Transportation Hubs, Residential Estates End User: Municipal Authorities, Waste Management Firms, Facility Management Companies, Property Developers, Event Organizers |
| Companies Covered | Enevo, Bigbelly, CleanRobotics, Sensoneo, Ecube Labs, Ausko Pte Ltd, iTouchless Housewares and Products, Simplehuman, Evreka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Trash Bin Market Shifts & Advancements
Hardware commoditization is pushing value capture toward data analytics layers, with vendors restructuring around subscription-based fleet management rather than equipment sales.
Ultrasonic fill-level sensing is bifurcating the installed base between premium precision units and cost-optimized binary indicators. Airport operators and hospital networks are adopting the higher-grade variants for predictive routing, while retail chains deploy simpler threshold alerts. This technology divergence is compressing mid-tier positioning and forcing vendors to choose between sensor performance and unit economics.
The EU F-Gas Regulation is restricting refrigerant options in organic waste cooling compartments, compelling redesigns of temperature-controlled smart bins deployed in Southern European climates. Manufacturers are pivoting toward thermoelectric alternatives that eliminate compressor-dependent cooling loops. Spanish and Italian procurement tenders now embed these specifications as mandatory technical clauses.
Facility management outsourcing is consolidating purchasing authority into integrated service providers across North American commercial real estate. CBRE and JLL are specifying smart bin fleets as bundled elements of waste management contracts rather than standalone capital expenditures. This channel shift is visible most acutely in Class A office towers across Manhattan and downtown Chicago.
Global Smart Trash Bin Market Segmentation
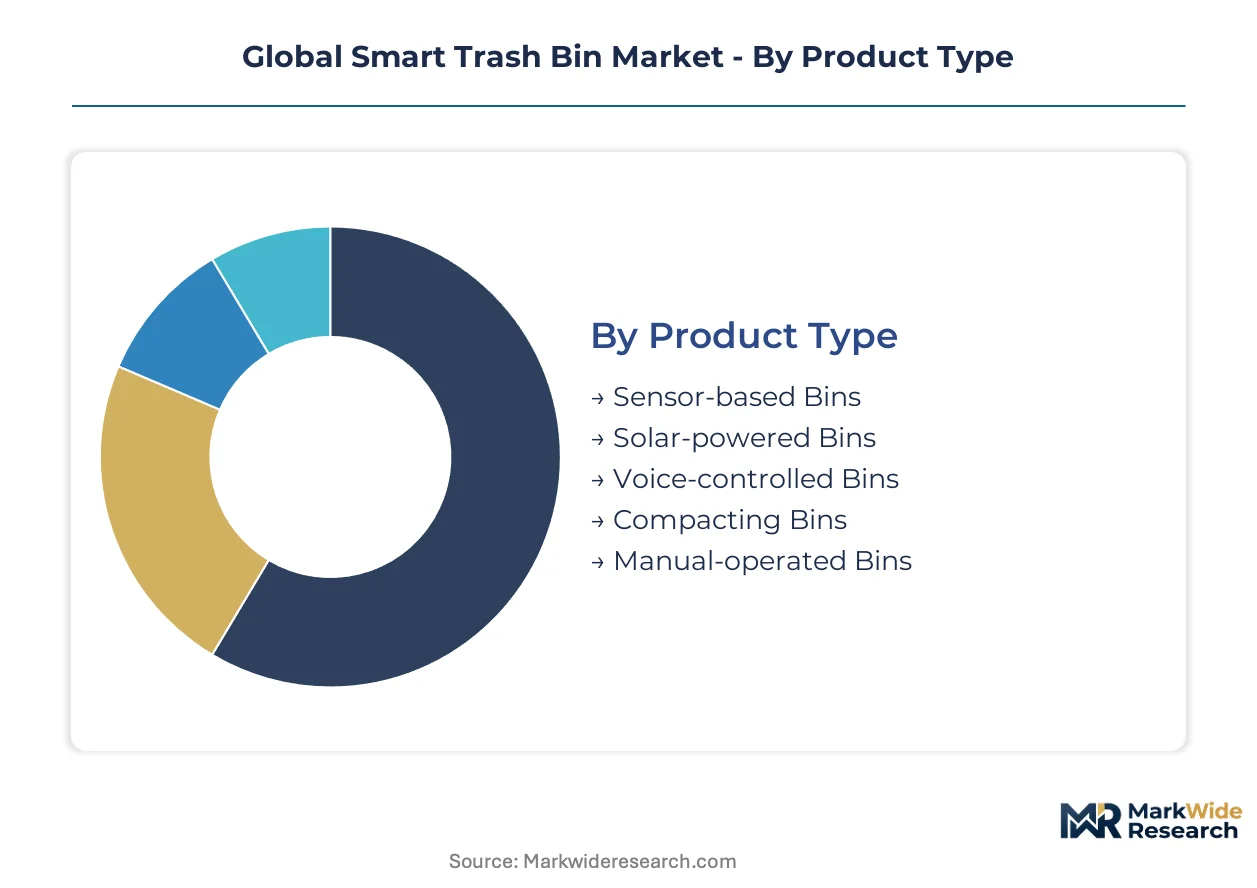
Segmentation in the smart trash bin market determines procurement specifications and margin capture across divergent technology tiers. Municipal buyers prioritize durability and fleet integration, while commercial purchasers emphasize hygiene automation and aesthetic integration.
Product Type:
Margin pools concentrate in compacting and solar-powered units where mechanical complexity and energy harvesting systems justify premium positioning.
- Sensor-based Bins:Infrared or ultrasonic modules trigger automated lid actuation, reducing touchpoint exposure in hospital lobbies and airport terminals. Demand clusters in Singapore's healthcare precincts where infection control protocols mandate contactless waste disposal.
- Solar-powered Bins:Photovoltaic panels power compaction motors and IoT transmitters, enabling off-grid deployment in pedestrian zones without electrical infrastructure. Paris and Barcelona street furniture tenders specify solar units for plaza and promenade installations.
- Voice-controlled Bins:Speech recognition modules enable hands-free operation in food preparation environments. Limited deployment in commercial kitchens.
- Compacting Bins:Hydraulic or screw-drive mechanisms reduce waste volume by 5:1 to 8:1 ratios. Critical for Tokyo subway stations where haulage access windows are restricted to overnight hours.
- Manual-operated Bins:Basic receptacles with minimal electronic augmentation. Lowest margin segment serving cost-constrained municipal fleets.
Compacting bins hold installed capacity. Sensor-based bins are rotating up the share rankings.
Technology:
Technology selection tracks the trade-off between sensing precision and unit economics in high-volume deployments.
- Infrared Sensors:Proximity detection using reflected light beams for lid actuation. Standard specification in German municipal procurement frameworks.
- Ultrasonic Sensors:Time-of-flight measurement enables millimeter-precise fill-level monitoring. Demand concentrates in Netherlands waste-to-energy facilities optimizing collection routing.
- Bluetooth Connectivity:Short-range wireless for localized status alerts and maintenance diagnostics. Deployed in UK retail park pilot programs.
- IoT Integration:Cellular or LPWAN connectivity streaming real-time data to cloud-based fleet management platforms. Fastest-expanding technology dimension as Australian and South Korean operators demand predictive analytics.
- RFID Tagging:Radio-frequency identification for asset tracking and user accountability in corporate campus deployments. Gaining traction in US tech headquarters waste diversion programs.
IoT integration commands development resources. Ultrasonic sensing is climbing the fastest in specification frequency.
Application:
Application context dictates hygiene requirements, aesthetic constraints, and haulage logistics that shape product configuration.
- Commercial Complexes:Shopping malls and office towers demand slim-profile units with finish-grade exteriors. LEED point systems in Singapore and Australia drive specification of diversion-capable sorting bins.
- Educational Institutions:Campuses require vandal-resistant construction and simplified user interfaces. Deployment concentrated in US university sustainability initiatives.
- Public Parks:Weatherproofing and wildlife resistance prioritize sealed compaction mechanisms over sorting sophistication. French and Italian municipal tenders emphasize solar autonomy for remote installations.
- Transportation Hubs:Airports and rail stations combine high foot traffic with restricted service access. Tokyo and Osaka transit authorities specify maximum compaction ratios to minimize collection frequency.
- Residential Estates:Gated communities and high-rise apartments balance aesthetic discretion with odor control. India's smart cities mission pilots fill-level monitoring in Bangalore and Hyderabad residential zones.
Transportation hubs anchor premium pricing. Commercial complexes are gaining share fastest in unit volume.
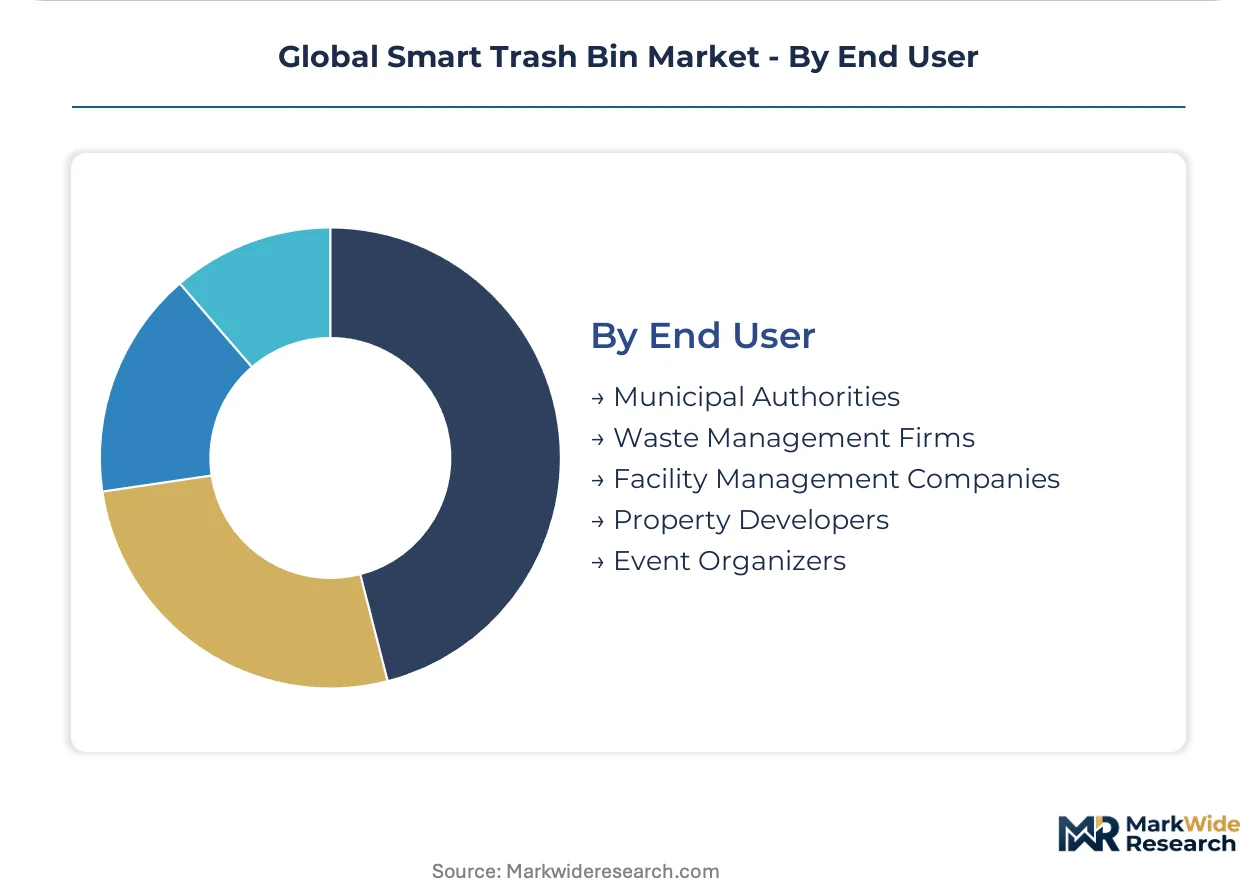
End User:
End-user type determines procurement authority structure and contract duration, with outsourcers consolidating purchasing power.
- Municipal Authorities:City governments specify multi-year fleet contracts with total-cost-of-ownership evaluation criteria. San Francisco and New York procurement codes mandate diversion-rate compliance.
- Waste Management Firms:Haulage operators demand IoT-enabled bins feeding route optimization software. SUEZ and Veolia specifications influence European product roadmaps.
- Facility Management Companies:Integrated service providers bundle smart bins into comprehensive building operations contracts. CBRE and JLL specifications dominate Manhattan and Chicago Class A office deployments.
- Property Developers:Pre-installation in new construction projects targets green building certification points. Pre-sales specifications in Dubai and Sydney premium residential towers.
- Event Organizers:Temporary deployments for festivals and exhibitions prioritize rapid deployment and compact logistics. Seasonal demand concentration in European summer event circuits.
Waste management firms hold contract value concentration. Facility management companies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japanese metropolitan transit systems demonstrate the lowest price elasticity, accepting premium compacting units with restricted haulage access. Municipal procurement in Southern Europe shows highest sensitivity, prioritizing solar autonomy over sensor sophistication. North American facility managers occupy the middle ground, balancing LEED point values against total cost of ownership.
United States
San Francisco and New York municipal codes mandate diversion-rate compliance that pulls smart sorting capabilities into street furniture tenders. EPA procurement guidelines influence specification standards for sensor-embedded bins in federal installations. Manhattan Class A office towers concentrate demand where CBRE and JLL bundle smart bins into integrated facility contracts.
Germany
Binding EU Green Deal diversion targets accelerate municipal procurement of sorting-capable bins across Bavaria and North Rhine-Westphalia. RoHS compliance thresholds for embedded electronics extend certification timelines for European deployments. Stuttgart and Munich waste-to-energy facilities drive demand for ultrasonic fill-level precision in collection routing optimization.
Japan
Tokyo and Osaka transit authorities deploy compacting units in subway corridors where overnight haulage windows are restricted to four hours. METI enforces JIS interoperability standards requiring 8-14 month validation cycles for connected city infrastructure. The Kanto metropolitan corridor anchors premium pricing for maximum compaction ratio specifications.
France
Paris street furniture tenders specify solar-powered units for plaza and promenade installations without electrical infrastructure. EU F-Gas Regulation restricts refrigerant options in organic waste cooling compartments across Southern European climates. Marseille and Nice procurement embed thermoelectric alternatives as mandatory technical clauses in temperature-controlled bin tenders.
Australia
LEED point systems in green building standards create specification pull from facility managers in Sydney and Melbourne commercial complexes. Waste management operators demand IoT-enabled bins feeding predictive analytics platforms for fleet optimization. Brisbane and Perth pilot programs test 5G-enabled edge computing for real-time compaction triggers.
Global Smart Trash Bin Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Sensor-embedded hardware developers command premium positioning through firmware sophistication and fleet software integration. Basic receptacle manufacturers compete on unit economics and rapid deployment logistics. The market structure favors strategic partnerships between technology licensors and municipal contractors, alongside vertical integration into solar panel and battery module supply.
Within the IoT-enabled tier, Enevo and Sensoneo represent the sensor-to-cloud integration archetype, while Ecube Labs anchors the fill-level monitoring specialization. Bigbelly occupies a position exemplifying solar-powered compacting infrastructure for dense urban cores. CleanRobotics sits within the AI-driven sorting segment, distinguishing recyclable streams through computer vision algorithms. These three archetypes—connectivity platforms, solar compaction systems, and intelligent sorting engines—collectively define the competitive vectors reshaping procurement specifications.
| Leading Market Players |
|---|
| Enevo |
| Bigbelly |
| CleanRobotics |
| Sensoneo |
| Ecube Labs |
| Ausko Pte Ltd |
| iTouchless Housewares and Products |
| Simplehuman |
| Evreka |
| Others |
Supply & Pricing Matrix
Long-term municipal fleet contracts lock in both Li-ion battery supply access and predictable unit pricing for solar-compacting manufacturers. These agreements insulate procurement officers from spot-market volatility in South Korean and Chinese cell markets while embedding software subscription tiers into total cost calculations.
Pricing Analysis
After-sales service contracts and firmware subscription tiers now drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates IoT-enabled fleet management bundles from basic sensor-actuation units. Cost compression in the mid-tier is intensifying because ultrasonic sensing modules face commoditization from Asian component suppliers. Municipal authorities in Southern Europe exhibit highest price sensitivity, prioritizing solar autonomy over predictive analytics capabilities.
Supply Chain Analysis
Inventory lead times for hydraulic compaction systems have extended due to precision-machined component shortages from German and Japanese suppliers. Manufacturing concentrates in China, South Korea, and Taiwan for sensor modules, photovoltaic cells, and embedded processors. The chain rests on concentrated Li-ion cell supply and rare-earth magnet availability for motor assemblies. Single-source vulnerability in semiconductor fabrication creates exposure for IoT connectivity chipsets. Distribution runs through municipal procurement frameworks and facility management integrators rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart trash bin penetration remains below saturation across commercial real estate portfolios, creating runway as LEED certification mandates tighten waste diversion requirements in green building standards.
For Market Incumbents: Secure captive supply agreements for Li-ion battery modules through backward integration or long-term offtake with South Korean cell manufacturers. Deepen firmware development capabilities in over-the-air security updates to defend against AI-driven sorting entrants threatening sensor-based hardware margins. For New Entrants and Emerging Players: Fast-track CE marking and RoHS pre-certification enables rapid European municipal tender participation without 18-month validation delays. Target India's smart cities mission pilots in Bangalore and Hyderabad where informal sector integration creates specification whitespace. Lead with fill-level monitoring-as-a-service rather than capital equipment sales to bypass incumbent fleet lock-in. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IoT-enabled fleet management platforms with municipal multi-year contracts. Five-to-ten year viability favors sensor-to-cloud integrators over basic receptacle manufacturers facing hardware commoditization. Monitor JIS interoperability certification backlogs as signal for Japanese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Tier Launch | Converts municipal capex budgets into recurring SaaS revenue streams with 90%+ gross margins. |
| Li-ion Battery Supply Agreement | Locks in cell allocation from Samsung SDI or LG Chem against EV sector demand competition. |
| AI Sorting Algorithm Licensing | Enables CleanRobotics-type computer vision deployment without in-house R&D facility investment. |
| 5G Edge Computing Partnership | Leverages South Korean testbed infrastructure for real-time compaction trigger validation. |
| LEED Certification Pathway Bundle | Positions sensor bins as bundled green building compliance tools for CBRE and JLL specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement officers, waste management fleet operators, and facility management executives at CBRE and JLL; and secondary validation through EPA procurement guidelines, EU Green Deal implementation documents, and METI JIS standard filings. Bottom-up triangulation cross-checked unit deployment data against top-down municipal budget allocations.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, connectivity technology, application context, and end-user procurement authority. CAGRs were derived from installation base expansion curves and software attach-rate assumptions. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and India's smart cities mission pilot scaling patterns.
Decision-makers should treat outputs as directional under stable Li-ion supply and sustained municipal sustainability budget commitments; material deviation in battery input costs or procurement code revisions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Global Oil Spill Management Market