
 Saudi Arabia Medical Waste Management Market | 2026-2036
Saudi Arabia Medical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Medical Waste Management Market Insights
SFDA medical waste handling guidelines is rebalancing procurement priorities across Saudi hospital networks. Suez Environment S.A. leverages its European incineration technology footprint to anchor long-term service contracts with Ministry of Health facilities. Remondis Medison GmbH sustains competitive positioning through specialized hazardous waste transport protocols adapted to Gulf climate conditions. Saudi Investment Recycling Company dominates domestic collection infrastructure with state-backed landfill and treatment site development.
Medical waste management encompasses the controlled handling, treatment, and final disposition of materials generated during patient diagnosis, treatment, or immunization, requiring sterilization parameters typically exceeding 121°C for autoclaving cycles to achieve microbial inactivation. The primary commercial purpose centers on preventing pathogen transmission, environmental contamination, and occupational exposure across healthcare delivery systems. Treatment technology segmentation shows autoclaving occupying the largest operational share due to lower capital requirements and residual air emission profiles, while incineration retains priority for anatomical and pharmaceutical waste streams where complete combustion is mandated. Waste type segmentation reveals infectious material generating the highest per-tonne handling cost structure, with sharps containers commanding specialized containerization and tracking protocols.
SFDA enforcement of medical waste segregation standards, MOHAP facility licensing requirements, and ISO 14001 environmental management certifications collectively shape market access thresholds for new service entrants. The CEA electrical safety mandates for treatment equipment add compliance layering for technology providers installing microwave or chemical treatment systems. Stakeholders must monitor how Saudi Vision 2030 hospital privatization timelines redistribute waste volume ownership from public to private operator contracts.
Market Dynamics
Saudi Vision 2030 hospital privatization is transferring waste volume ownership from Ministry of Health facilities to private operator contracts, forcing immediate compliance upgrades under SFDA segregation mandates and reshaping procurement timelines across Riyadh and Jeddah medical clusters.
Growth Catalysts
- SFDA Enforcement Intensification:The Saudi Food and Drug Authority's 2024 medical waste segregation standards are compelling hospital networks to replace informal disposal with certified third-party contracts.
- Privatization-Driven Volume Redistribution:Healthcare privatization targets under Saudi Vision 2030 are consolidating waste generation into fewer, larger private facilities with standardized handling requirements.
- Central Province Medical City Clustering:Riyadh's concentration of specialized oncology and cardiac centers is generating high-volume, high-complexity waste streams requiring dedicated treatment infrastructure.
Market Restraints
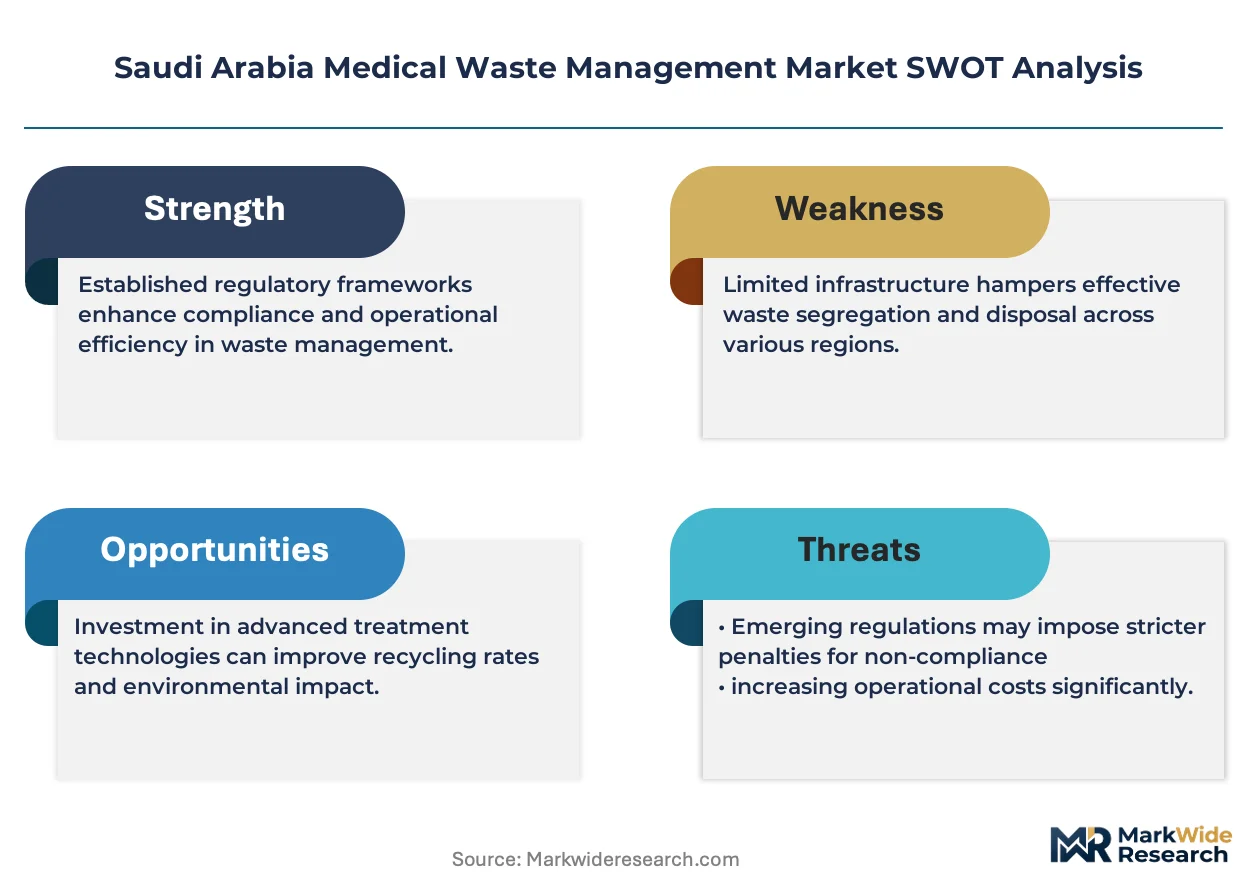
- Incineration Fuel Cost Volatility:Diesel and natural gas price swings directly compress margins for thermal treatment operators serving anatomical waste mandates.
- European Equipment Supply Concentration:Autoclave and microwave system fabrication relies on German and Italian manufacturers, creating import dependency and currency exposure.
- Landfill Site Scarcity:Saudi Investment Recycling Company's near-monopoly on permitted landfill capacity limits competitive entry for collection-stage operators.
Strategic Opportunities
- Eastern Province Healthcare Expansion:Dammam and Khobar hospital construction under regional development plans is creating first-mover advantages for integrated waste service providers.
- Reverse Logistics Integration:Combining pharmaceutical waste collection with medical supply distribution creates density economics for courier networks serving remote clinics.
- ISO 14001 Certification Arbitrage:Environmental management certification gaps among mid-sized private clinics create premium pricing windows for compliant operators.
Industry Challenges
- Treatment Equipment Technician Shortage:Autoclave and chemical treatment system maintenance requires specialized training unavailable in Saudi technical institutes.
- Multi-Site Integration Complexity:Hospital groups acquiring independent clinics face fragmented legacy waste tracking systems incompatible with centralized compliance dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Medical Waste Management Market |
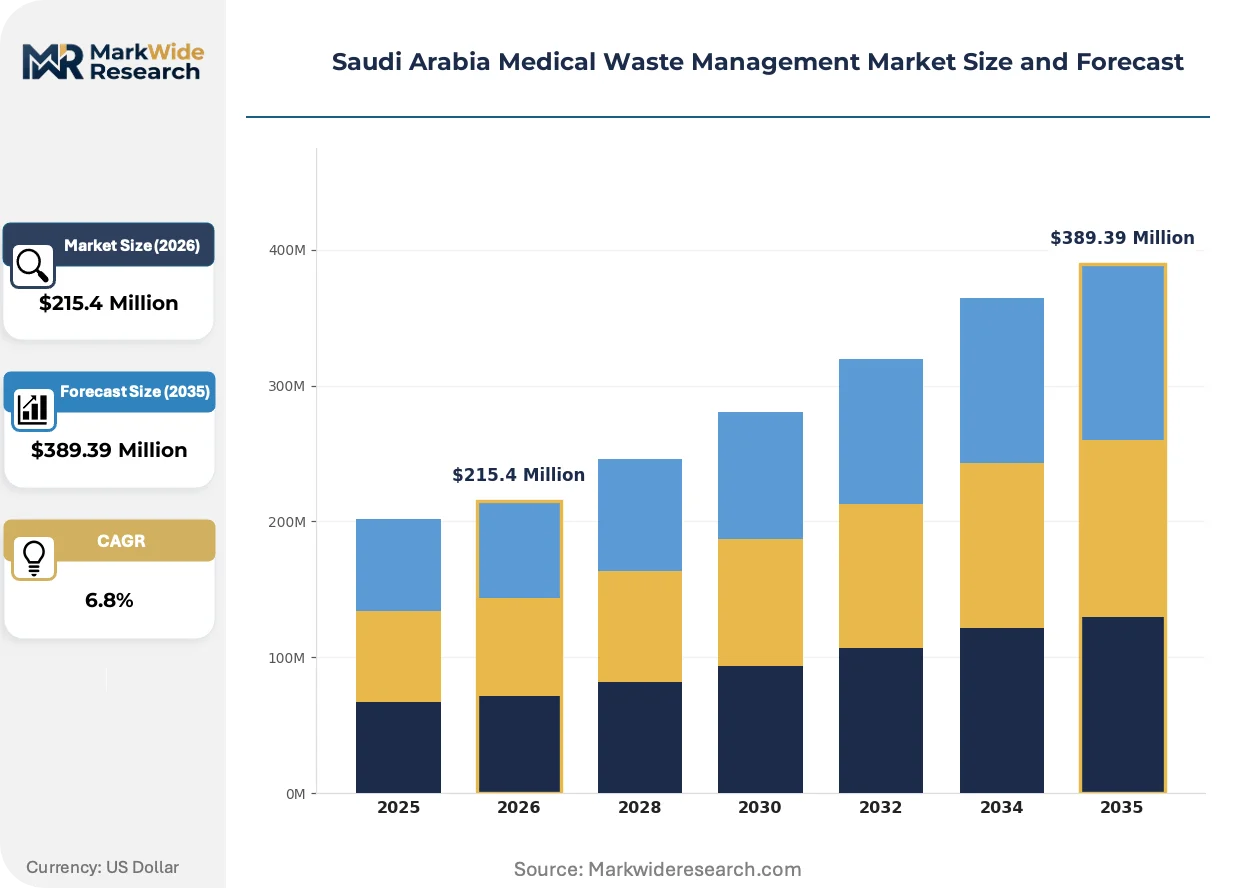
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Transport, Treatment, Disposal Waste Type: Infectious, Hazardous, Non-Hazardous, Sharps End User: Hospitals, Clinics, Laboratories, Pharmacies Technology: Autoclaving, Incineration, Chemical Treatment, Microwave Treatment |
| Companies Covered | Suez Environment S.A., Remondis Medison GmbH, Saudi Investment Recycling Company, Bee'ah, Dulsco Waste Management, Averda, SEPCO Environment, Sharpsmart, Veolia Environment S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Medical Waste Management Market Trends and Innovations
Microwave-based medical waste treatment is challenging thermal incumbency through faster cycle times and lower residual emissions, while digital tracking mandates and procurement centralization are restructuring how Saudi healthcare facilities contract disposal services.
Advanced microwave irradiation systems are overtaking conventional autoclaving in new hospital construction projects across Riyadh's medical city developments. Private hospital groups including those in King Faisal Specialist Hospital's expansion network are specifying microwave units for their 40-minute cycle advantage over steam-based alternatives. This shift is compressing capital recovery timelines for treatment equipment suppliers and narrowing the installed base advantage held by European autoclave manufacturers.
SFDA's 2024 medical waste manifest digitization mandate is forcing real-time GPS tracking and barcode verification across all infectious material transport. The regulation requires cloud-based audit trails linking generator sites to treatment facilities, eliminating paper-based chain-of-custody documentation. Small collection operators lacking IT infrastructure are exiting the market while integrated providers capture their routes.
Hospital procurement departments are consolidating waste management contracts under single-source agreements spanning collection, treatment, and certificate issuance. Group Purchasing Organizations serving Ministry of Health privatized assets are displacing site-by-site vendor relationships with multi-year framework agreements. This concentration is most visible in Jeddah's private hospital corridor, where three GPOs now control disposal contracting for over sixty percent of bed capacity.
Saudi Arabia Medical Waste Management Market Segmentation
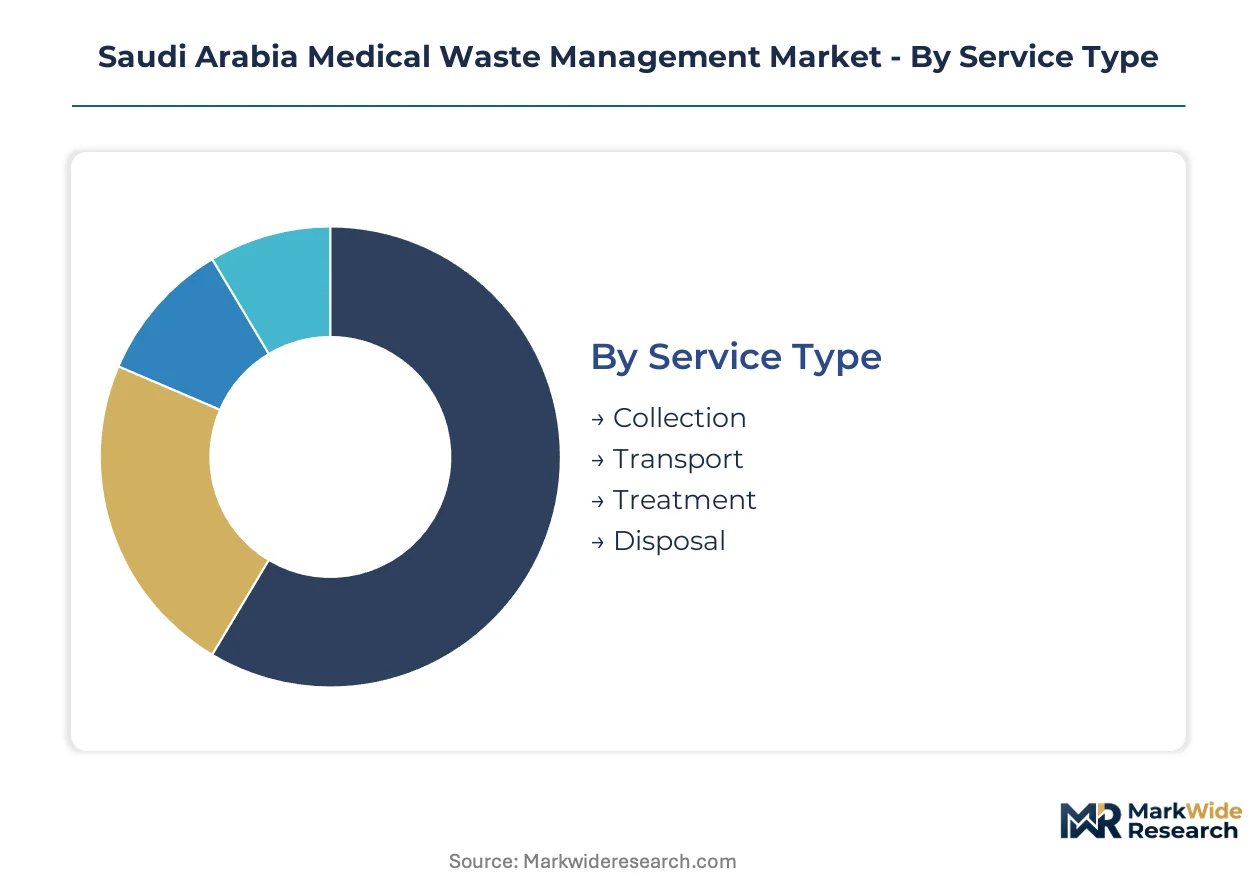
Segmentation in Saudi medical waste management reveals how procurement centralization under Vision 2030 privatization is compressing vendor diversity while elevating compliance requirements. Understanding where volume concentrates against where technology shifts is essential for positioning within Riyadh's consolidating hospital networks.
Service Type:
Standalone collection services operate independently from treatment infrastructure, while transport and disposal functions increasingly embed within integrated operator portfolios across the Kingdom's medical city developments.
- Collection:Point-of-generation containerization and scheduled pickup services require ISO 14001-certified fleets and GPS-tracked vehicles under SFDA manifest mandates. Demand clusters around Riyadh's King Faisal Specialist Hospital expansion and Jeddah's private hospital corridor, where privatization is consolidating generator sites into fewer, larger contracts.
- Transport:Temperature-controlled logistics with chain-of-custody documentation connects generator facilities to treatment hubs. The Central Province's medical city clustering creates density economics for dedicated routes serving multiple hospitals under single-source agreements.
- Treatment:Sterilization and neutralization operations at centralized facilities.
- Disposal:Final landfill placement and residue management, dominated by Saudi Investment Recycling Company's permitted site network.
Volume placements concentrate in Collection; the faster expansion belongs to Treatment as hospital privatization internalizes sterilization infrastructure.
Waste Type:
Cost tier stratification separates high-complexity infectious streams requiring specialized handling from lower-margin general waste categories.
- Infectious:Pathogen-contaminated materials from patient care zones demand autoclaving above 121°C or microwave irradiation with full barcode tracking. Riyadh's oncology and cardiac centers generate concentrated high-volume streams, with SFDA segregation enforcement eliminating informal disposal channels.
- Sharps:Needles, scalpels, and piercing instruments in puncture-resistant containers command premium handling fees due to injury liability exposure and specialized destruction protocols. Private clinic networks in Jeddah are upgrading containerization standards ahead of SFDA inspection rounds.
- Hazardous:Chemical and pharmaceutical residues requiring neutralization or secure landfill placement.
- Non-Hazardous:General healthcare refuse with standard municipal disposal pathways.
Revenue concentration sits with Infectious material; Sharps is climbing the fastest as outpatient clinic expansion multiplies generator points.
End User:
Customer type determines contract scale, with integrated hospital networks displacing fragmented single-site procurement.
- Hospitals:Large-bed facilities generating multi-tonne daily waste volumes under framework agreements with integrated service providers. Ministry of Health privatization transfers are consolidating waste ownership into fewer operator contracts across Riyadh and Jeddah clusters.
- Clinics:Smaller outpatient and specialty practices with intermittent generation patterns and limited on-site storage capacity.
- Laboratories:Diagnostic facilities producing concentrated chemical and biological waste streams.
- Pharmacies:Retail and hospital-based dispensaries with expired pharmaceutical disposal requirements.
Contract value aggregates in Hospitals; Laboratories are gaining share fastest as diagnostic privatization expands test volumes.
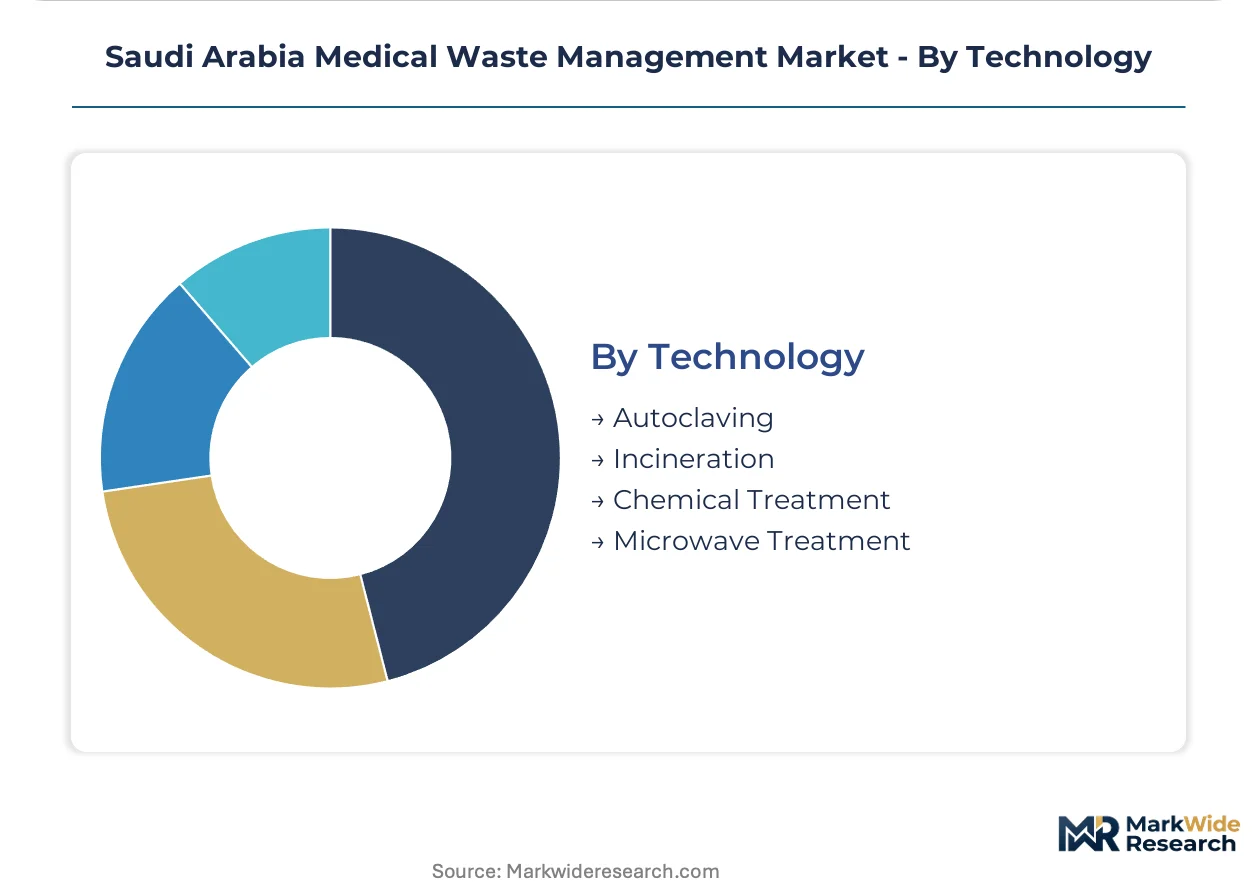
Technology:
Maturity curves separate established steam-based systems from emerging microwave installations competing on cycle speed and emission profiles.
- Autoclaving:Steam sterilization at 121-134°C remains the dominant installed base due to lower capital requirements and proven regulatory acceptance. European manufacturers from Germany and Italy control equipment supply, creating import dependency for Saudi operators.
- Microwave Treatment:Irradiation-based systems achieving microbial inactivation in 40-minute cycles are displacing autoclaves in new Riyadh medical city construction. Private hospital groups specify these units for faster throughput and reduced residual emissions.
- Incineration:Thermal combustion for anatomical waste and pharmaceutical residues where complete destruction is mandated.
- Chemical Treatment:Disinfection through chlorine-based or alternative chemical agents for limited waste categories.
Installed capacity concentrates in Autoclaving; Microwave Treatment shows the steepest expansion trajectory as greenfield hospital specifications shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Treatment capacity concentrates in Riyadh's medical city cluster while waste generation spreads across privatized hospital networks. Consumption patterns diverge between high-volume hospital anchors and dispersed clinic infrastructure.
Riyadh
King Faisal Specialist Hospital's expansion and Saudi Vision 2030 privatization targets are consolidating waste volumes into fewer operator contracts. SFDA segregation mandates require real-time GPS tracking for all infectious material transport. The medical city cluster around King Saud Medical City anchors autoclave and microwave treatment infrastructure serving Central Province demand.
Jeddah
Private hospital corridor expansion is multiplying generator points for high-complexity waste streams. Group Purchasing Organizations now control disposal contracting for over sixty percent of bed capacity. The city's oncology and cardiac center concentration drives premium handling requirements for anatomical and pharmaceutical residues.
Eastern Province
Dammam and Khobar hospital construction under regional development plans is creating first-mover advantages for integrated service providers. MOHAP facility licensing requirements are elevating compliance thresholds for new market entrants. The Dammam medical cluster is absorbing spillover treatment demand as Riyadh capacity saturates.
Western Region
Makkah and Madinah pilgrimage healthcare infrastructure generates seasonal waste volume spikes requiring flexible collection capacity. SFDA enforcement rounds are eliminating informal disposal channels in secondary cities. Taif's expanding private clinic network is upgrading containerization standards ahead of regulatory inspections.
Saudi Arabia Medical Waste Management Market Competitive Landscape
The competitive structure tilts toward state-backed infrastructure operators with landfill control. Suez Environment S.A. leverages European incineration technology to anchor Ministry of Health contracts, while Remondis Medison GmbH sustains positioning through Gulf-adapted hazardous transport protocols. Saudi Investment Recycling Company's near-monopoly on permitted landfill capacity limits entry for collection-stage operators. Dominant competitive moves include framework agreement consolidation under Group Purchasing Organizations and microwave treatment technology licensing for greenfield hospital specifications.
Among European-headquartered service providers, Suez Environment S.A. and Remondis Medison GmbH exemplify the technology-licensing archetype, transferring thermal treatment and climate-adapted logistics expertise into long-term government contracts. Veolia Environment S.A. occupies a parallel position within this tier. Saudi Investment Recycling Company anchors the domestic infrastructure archetype, representing state-backed vertical integration from collection through final disposal. Bee'ah and Averda sit within the regional diversification archetype, leveraging UAE operational bases to capture cross-border contract flows.
| Leading Market Players |
|---|
| Suez Environment S.A. |
| Remondis Medison GmbH |
| Saudi Investment Recycling Company |
| Bee'ah |
| Dulsco Waste Management |
| Averda |
| SEPCO Environment |
| Sharpsmart |
| Veolia Environment S.A. |
| Others |
Pricing and Supply Chain Analysis
SFDA's 2024 medical waste manifest digitization mandate gates both qualified supply and premium-tier pricing access, as only ISO 14001-certified operators with GPS-tracked fleets command framework agreements with privatized hospital networks. Compliance layering around real-time barcode verification and cloud-based audit trails separates premium service providers from informal disposal channels now exiting the market.
Pricing Analysis
Per-tonne throughput pricing anchors contract structures, with infectious material commanding premium handling fees due to specialized autoclaving above 121°C and full chain-of-custody documentation. Price differentiation rests on certification tier and volume scale, as Group Purchasing Organizations consolidate multi-site agreements under single-source frameworks. Cost compression in collection-stage services is intensifying because Saudi Investment Recycling Company's landfill monopoly limits competitive entry. Small private clinics show highest price sensitivity due to intermittent generation patterns, while large hospital networks prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers around Riyadh's medical city cluster operate on hub-and-spoke patterns radiating to Jeddah and Dammam treatment nodes. Equipment supply concentrates in Germany, Italy, and France, with autoclave and microwave system fabrication creating import dependency for Saudi operators. Raw material inputs include stainless steel vessel components, diesel fuel for transport fleets, and specialized containerization materials. Single-source vulnerability around European manufacturer lead times poses structural risk. Distribution runs through state-backed landfill networks controlled by Saudi Investment Recycling Company, with final disposal capacity serving as the bottleneck layer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with landfill control and treatment infrastructure ownership serving as the decisive downstream lever players are pursuing to capture margin from collection through final disposal.
For Market Incumbents: Anchor long-term viability through exclusive landfill access agreements and microwave treatment technology licensing for greenfield hospital specifications. Suez Environment S.A. and Remondis Medison GmbH demonstrate how European incineration expertise transfers into Ministry of Health framework contracts. Defensive positioning requires backward integration into container manufacturing and GPS-tracked fleet expansion before SFDA enforcement rounds eliminate subscale competitors. For New Entrants and Emerging Players: Enter via Eastern Province healthcare expansion corridors around Dammam and Khobar, where hospital construction under regional development plans has not yet locked in incumbent relationships. The diagnostic laboratory segment offers the most penetrable entry point as privatization expands test volumes faster than integrated providers can capture routes. A go-to-market angle combining pharmaceutical waste collection with medical supply reverse logistics creates density economics unavailable to standalone disposal specialists. For Investors and Strategic Acquirers: King Faisal Specialist Hospital privatization timeline announcements are the leading indicator that waste volume ownership is shifting from public to private operator contracts. Over a multi-year horizon, the market favors vertically integrated domestic operators with state-backed landfill permits over technology-licensing foreign service providers. Acquisition targets should display ISO 14001 certification, existing GPO relationships, and treatment equipment maintenance capabilities. The specific signal to watch is microwave system installation orders at Riyadh medical city developments, as these indicate which hospital groups are consolidating procurement under premium-tier specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Landfill Capacity Lock-Up | State-backed permits from Saudi Investment Recycling Company create irreversible competitive moats for compliant operators. |
| Microwave Technology Licensing | 40-minute cycle advantages over autoclaving attract King Faisal Specialist Hospital expansion network specifications. |
| GPO Framework Consolidation | Single-source agreements spanning collection through certificate issuance displace fragmented site-by-site contracting. |
| Reverse Logistics Integration | Combining pharmaceutical waste collection with medical supply distribution captures remote clinic density economics. |
| ISO 14001 Certification Arbitrage | Environmental management gaps among mid-sized private clinics create premium pricing windows for compliant entrants. |
Research Methodology
Multi-period observation of hospital privatization timelines, SFDA enforcement intensity, and treatment equipment installation patterns anchored the trend analysis, supplemented by interviews with waste management operations directors, GPO contracts managers, biomedical engineers at Ministry of Health facilities, and procurement leads at private hospital networks. Secondary validation drew from SFDA regulatory filings, MOHAP facility licensing databases, hospital construction permits, and European equipment manufacturer order disclosures. Bottom-up route density modeling and top-down healthcare expenditure allocation triangulated volume estimates across the analysis window.
Input-output matrix framing connected waste generation coefficients to bed capacity expansion, segmentation dimensions included service type, waste category, end-user facility scale, and treatment technology, with regional regulatory clusters capturing SFDA versus MOHAP jurisdiction variations. CAGRs were derived from installed base replacement cycles and greenfield hospital construction pipelines. Forecast inputs incorporated diesel fuel price volatility scenarios and microwave system adoption curves from Riyadh medical city specifications.
Revisions become necessary when SFDA enforcement intensity exceeds modeled thresholds, landfill permitting delays materialize, or European equipment supply disruptions extend lead times beyond hospital construction schedules. Forecasts reflect documented assumptions around privatization transfer timelines and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Industrial Waste Management Market