
 Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market | 2026-2036
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market Insights
Aftermarket service revenue from biogas plant operations and maintenance is narrowing as facility operators bring predictive monitoring and spare parts logistics in-house. Veolia leverages its integrated waste-to-energy platform across France and Benelux to control collection-to-grid value chains. SUEZ sustains competitive positioning through specialized wet digestion technology leadership at scale. SARIA ReFood anchors German market presence with backward integration into retail collection contracts.
Retail food waste-to-biogas logistics and treatment networks comprise the coordinated infrastructure for collecting, transporting, and converting supermarket and grocery surplus into biomethane through anaerobic digestion, typically operating at mesophilic temperatures of 35-40°C with hydraulic retention times of 20-30 days to produce biogas with 50-70% methane content for grid injection or combined heat and power generation. Wet digestion systems dominate existing European capacity due to mature engineering and compatibility with high-moisture retail food streams, while thermal hydrolysis pre-treatment represents the fastest-growing technology segment as operators seek to accelerate hydrolysis rates and increase biogas yield per ton of feedstock. Energy producers represent the most concentrated end-user margin pool, since offtake agreements for upgraded biomethane command premium pricing under renewable gas certificates.
The EU Green Deal and F-Gas Regulation shape biogas upgrading equipment standards and biomethane grid injection specifications across member states, while national implementations through Germany's EEG tariff framework and France's energy regulatory commission create divergent incentive landscapes for project developers. ECHA's bio-waste characterization protocols under REACH-aligned standards determine pre-treatment requirements and digestate classification for agricultural reuse. Stakeholders must monitor the EU AI Act's emerging compliance obligations for automated sorting and contamination detection systems deployed at retail collection points.
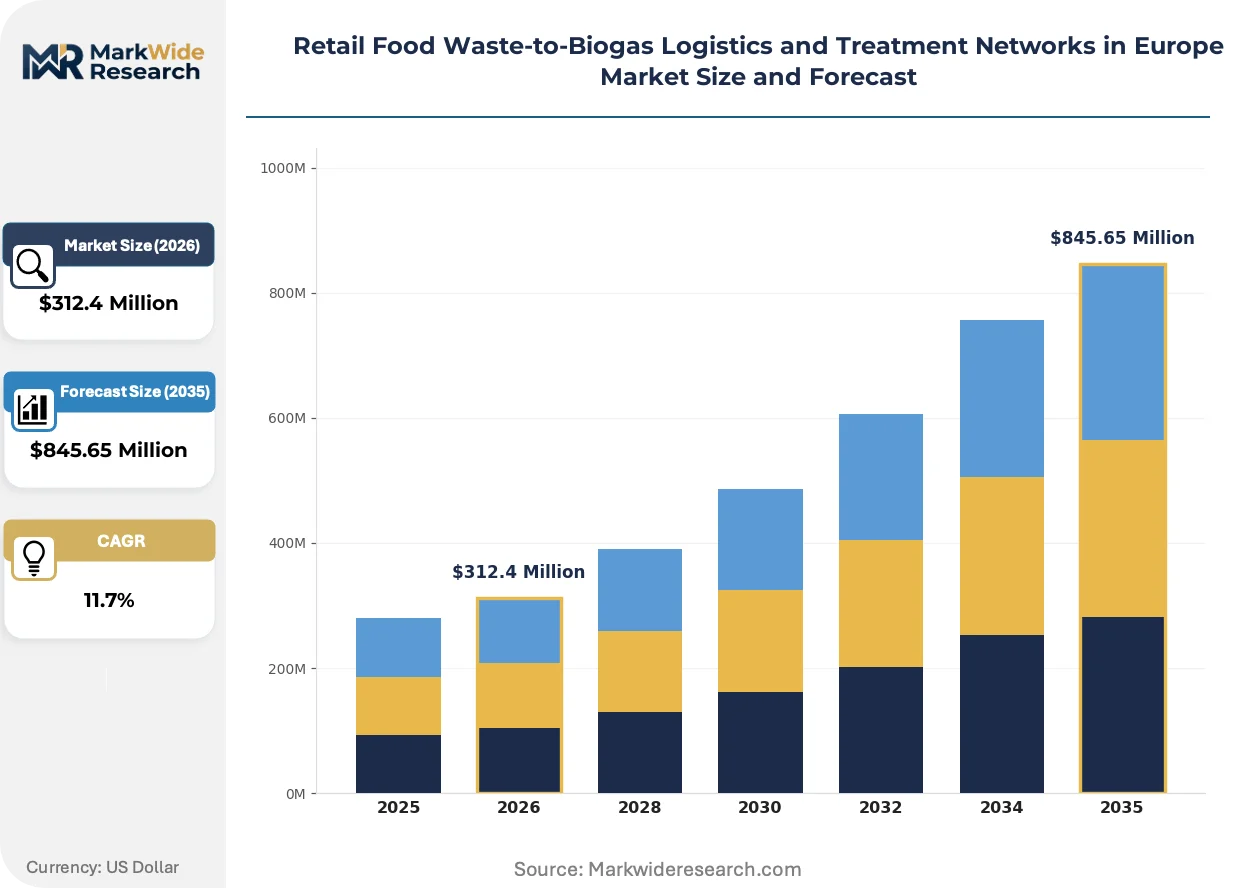
Market Dynamics
The EU Green Deal's mandatory food waste reduction targets are compressing project timelines across member states, forcing grocery retailers and municipal authorities into co-investment frameworks for anaerobic digestion infrastructure before 2030 deadlines.
Growth Catalysts
- EEG tariff framework:Germany's renewable energy remuneration guarantees stabilize investor returns for biomethane upgrading facilities, attracting capital from energy producers into retail waste collection partnerships.
- Rhine-Ruhr corridor concentration:Dense supermarket distribution and existing gas grid infrastructure create feedstock-to-grid economics that outperform peripheral European regions.
- Thermal hydrolysis pre-treatment:Operators deploying this technology achieve 20-30% faster hydrolysis rates, unlocking higher biogas yields per ton of retail food waste processed.
Market Restraints
- Digestate contamination protocols:ECHA's REACH-aligned bio-waste characterization imposes costly pre-treatment requirements for plastic and packaging separation, eroding plant-level margins.
- Grid injection specification divergence:France's energy regulatory commission maintains distinct biomethane quality thresholds from Germany's DVGW standards, fragmenting equipment procurement and compliance costs.
- Natural gas price volatility:Unhedged exposure to TTF benchmark movements compresses offtake contract premiums, undermining project finance assumptions for biomethane producers.
Strategic Opportunities
- Benelux logistics integration:Netherlands' centralized retail distribution hubs and port-connected gas infrastructure offer consolidation points for cross-border feedstock aggregation.
- EU AI Act compliance services:Automated sorting and contamination detection systems at retail collection points create vendor opportunities for computer vision and sensor integration specialists.
- Agricultural digestate valorization:Nitrogen recovery technologies are converging with biogas upgrading to produce ammonium sulfate fertilizers, opening circular economy revenue streams.
Industry Challenges
- Process engineering talent scarcity:Specialized expertise in wet digestion optimization and biogas upgrading membrane selection concentrates among aging technical workforces in Germany and France.
- Legacy ERP integration:Retail waste tracking systems require real-time data pipelines into anaerobic digestion plant control systems, creating interoperability friction with supermarket inventory management platforms.
- CSRD reporting alignment:Scope 3 emissions verification for food waste diversion demands standardized measurement protocols that remain under development across national bio-waste registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Supply Chain Stage: Collection, Transportation, Pre-Treatment, Anaerobic Digestion, Post-Treatment Facility Type: Biogas Plant, Composting Site, Recycling Terminal, Transfer Station End User: Agricultural Operators, Energy Producers, Municipal Authorities, Waste Management Firms Technology Employed: Wet Digestion, Dry Digestion, Thermal Hydrolysis, Gas Upgrading, Combined Heat and Power |
| Companies Covered | Veolia, SUEZ, SARIA ReFood, Renewi, Biffa, Biogen, Anaergia, Entsorga, EnviTec Biogas, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market Trends and Innovations
Technology convergence between pre-treatment systems and grid injection infrastructure is compressing capital deployment cycles, while regulatory pressure on scope 3 emissions disclosure is elevating biomethane certificate premiums above conventional renewable energy attributes.
Thermal hydrolysis pre-treatment systems are hybridizing with conventional mesophilic wet digestion to accelerate hydrolysis rates and boost methane yields from high-moisture retail food streams. Energy producers in Germany's Rhine-Ruhr corridor are deploying these integrated configurations at scale. The technology is hybridizing project economics by reducing hydraulic retention times from 30 days toward 15-20 days, enabling smaller reactor volumes per ton of annual throughput.
The EU AI Act's emerging compliance obligations for automated contamination detection are mandating sensor deployment at retail collection points before waste enters logistics networks. Industrial consequence includes capital reallocation from transport fleet expansion toward sorting infrastructure at supermarket distribution centers. France and Benelux retailers are responding fastest, integrating computer vision systems with existing waste compactor installations to preempt regulatory enforcement timelines.
Energy producers are consolidating offtake negotiations directly with grocery retail chains, bypassing traditional waste management intermediaries to secure long-term feedstock supply. This channel compression displaces third-party logistics providers from margin capture in biomethane value chains. The shift is most visible in Germany, where REWE Group and EDEKA have established direct contracting relationships with biogas upgrading facility operators for source-separated organic waste streams.
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market Segmentation
Segmentation reveals how value pools concentrate across the retail food waste-to-biogas value chain in Europe. Facility operators and energy producers target distinct technology and service configurations based on feedstock characteristics and grid access economics.
Supply Chain Stage:
Use-case spectrum spans decentralized retail collection through centralized grid injection infrastructure.
- Collection:Source-separated organic waste programs at supermarket distribution centers require dedicated bin infrastructure and contamination monitoring. Germany's Rhine-Ruhr corridor concentrates demand as grocery retailers expand direct contracting with biogas operators under EEG tariff frameworks.
- Pre-Treatment:Thermal hydrolysis systems accelerate hydrolysis rates for high-moisture retail food streams, achieving 20-30% faster processing than conventional methods. Netherlands and Benelux retailers deploy these systems at centralized distribution hubs to aggregate cross-border feedstock.
- Transportation:Refrigerated logistics networks move source-separated waste from retail points to anaerobic digestion facilities.
- Anaerobic Digestion:Mesophilic wet digestion at 35-40°C dominates European capacity with 20-30 day hydraulic retention times.
- Post-Treatment:Biogas upgrading to biomethane specifications enables grid injection under national regulatory frameworks.
Established volume favors Anaerobic Digestion; emerging adoption favors Pre-Treatment.
Facility Type:
Capital intensity and regulatory licensing requirements shape facility deployment patterns across member states.
- Biogas Plant:Anaerobic digestion facilities with biogas upgrading capacity command premium returns through renewable gas certificates. France and Germany concentrate capacity as energy producers co-invest with municipal authorities under divergent national incentive structures.
- Composting Site:Aerobic processing facilities handle lower-value organic streams unsuitable for energy recovery.
- Recycling Terminal:Material recovery facilities separate contaminants from retail food waste before biological treatment.
- Transfer Station:Intermediate consolidation points aggregate retail waste volumes for efficient long-haul transport to centralized digestion facilities.
Revenue concentration sits with Biogas Plant configurations; regulatory flexibility favors Transfer Station networks.
End User:
Stakeholder procurement patterns reflect divergent priorities for feedstock security, energy returns, and waste diversion compliance.
- Energy Producers:Biomethane offtake agreements generate concentrated margin pools through renewable gas certificate premiums. Germany's EEG tariff framework stabilizes investor returns, attracting capital into retail waste collection partnerships across the Rhine-Ruhr corridor.
- Municipal Authorities:Public entities co-finance anaerobic digestion infrastructure to meet EU Green Deal mandatory food waste reduction targets.
- Agricultural Operators:Farms utilize digestate as fertilizer and biogas for on-farm energy generation.
- Waste Management Firms:Integrated operators control collection-to-treatment value chains through logistics networks and processing assets.
Margin capture concentrates with Energy Producers; procurement volume expansion favors Municipal Authorities.
Technology Employed:
Technology selection determines biogas yield, capital efficiency, and compliance with evolving grid injection specifications.
- Wet Digestion:Mesophilic systems at 35-40°C with 50-70% methane content represent mature European capacity compatible with high-moisture retail food streams. Existing infrastructure dominates Germany and France where engineering expertise concentrates among aging technical workforces.
- Thermal Hydrolysis:Pre-treatment technology reduces hydraulic retention times toward 15-20 days, enabling smaller reactor volumes per ton of throughput. Rhine-Ruhr corridor operators deploy integrated configurations to boost methane yields from supermarket surplus.
- Dry Digestion:Solid-state systems process lower-moisture organic waste streams with reduced water requirements.
- Gas Upgrading:Membrane and pressure swing adsorption systems purify biogas to biomethane for grid injection.
- Combined Heat and Power:On-site electricity and thermal generation serves facilities without grid access or upgrading infrastructure.
Deployment scale favors Wet Digestion; yield optimization favors Thermal Hydrolysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's Rhine-Ruhr corridor show lowest price elasticity due to EEG tariff certainty, while French project developers face higher sensitivity to natural gas benchmark volatility under divergent regulatory frameworks.
Germany
EEG tariff guarantees stabilize investor returns for biomethane upgrading facilities, attracting capital from energy producers into retail waste collection partnerships. The EU Green Deal's mandatory food waste reduction targets compress project timelines before 2030 deadlines. Rhine-Ruhr corridor operators deploy thermal hydrolysis-integrated configurations to boost methane yields from supermarket surplus.
France
Veolia leverages its integrated waste-to-energy platform across France and Benelux to control collection-to-grid value chains. The energy regulatory commission maintains distinct biomethane quality thresholds from Germany's DVGW standards, fragmenting equipment procurement costs. Île-de-France retailers respond fastest to EU AI Act compliance obligations, integrating computer vision systems with existing waste compactor installations.
Netherlands
Centralized retail distribution hubs and port-connected gas infrastructure offer consolidation points for cross-border feedstock aggregation. REACH-aligned bio-waste characterization protocols impose costly pre-treatment requirements for plastic separation. Randstad logistics networks aggregate volumes for efficient long-haul transport to centralized digestion facilities.
United Kingdom
Biffa and Renewi compete for supermarket distribution center contracts as grocery retailers expand source-separated organic waste programs. CSRD reporting alignment demands standardized measurement protocols for Scope 3 emissions verification that remain under development across national bio-waste registries. Greater London municipal authorities co-finance anaerobic digestion infrastructure to meet diversion targets.
Italy
Agricultural digestate valorization opportunities converge with biogas upgrading to produce ammonium sulfate fertilizers, opening circular economy revenue streams. ECHA's bio-waste characterization determines pre-treatment requirements for agricultural reuse classification. Lombardy and Emilia-Romagna concentrate wet digestion capacity where engineering expertise concentrates among aging technical workforces.
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market Competitive Landscape
Integrated waste-to-energy platforms and specialized digestion technology providers split the market along vertical control versus technical specialization lines. The vendor base concentrates among European multinationals with established logistics networks and regional engineering firms with proprietary pre-treatment capabilities. Two archetypes dominate: full-service environmental conglomerates controlling collection-to-grid value chains, and technology-focused operators deploying thermal hydrolysis for yield optimization. Competitive dynamics center on direct contracting relationships with grocery retail chains and co-investment frameworks with municipal authorities under national incentive structures.
Among France-based environmental service conglomerates, Veolia and SUEZ exemplify divergent strategic positioning within integrated waste-to-energy platforms. Veolia occupies a position emphasizing cross-border logistics control across France and Benelux, while SUEZ represents technology-led differentiation through wet digestion specialization. SARIA ReFood anchors German market presence with backward integration into retail collection contracts, demonstrating how feedstock security arrangements determine competitive positioning under EEG tariff frameworks.
| Leading Market Players |
|---|
| Veolia |
| SUEZ |
| SARIA ReFood |
| Renewi |
| Biffa |
| Biogen |
| Anaergia |
| Entsorga |
| EnviTec Biogas |
| Others |
Pricing and Supply Chain Analysis
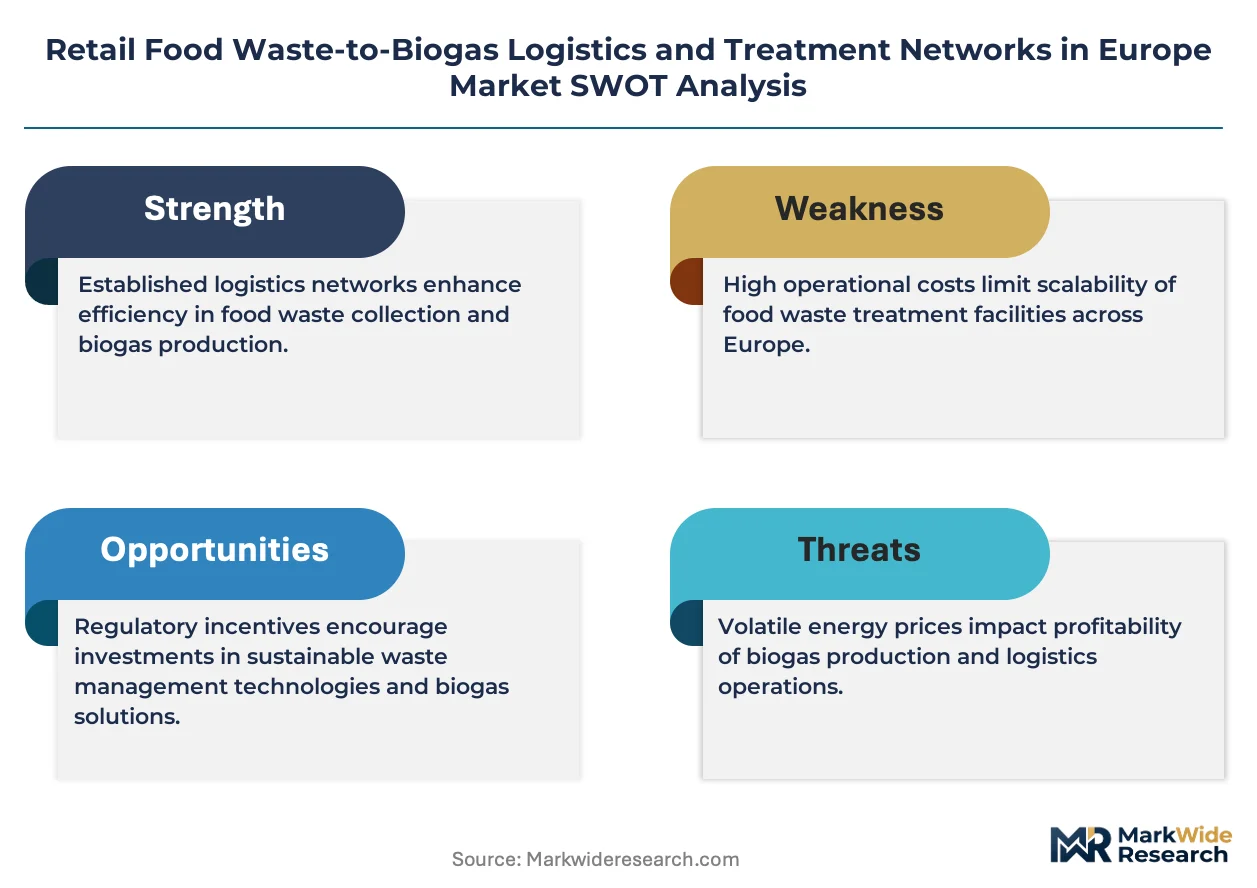
Germany's thermal hydrolysis equipment suppliers anchor upstream concentration, directing margin capture toward biogas upgrading operators who control renewable gas certificate monetization across the Rhine-Ruhr corridor.
Pricing Analysis
Aftermarket service contracts from predictive maintenance and spare parts logistics drive lifetime value for anaerobic digestion facility operators. Three-tier pricing structure across premium, standard, and economy levels segments by biomethane certification grade and grid injection proximity. Cost compression in standard-tier upgrading equipment intensifies as membrane suppliers compete for Rhine-Ruhr deployment contracts. Energy producers show lowest price sensitivity due to EEG tariff certainty, while municipal authorities face highest sensitivity under constrained public procurement budgets.
Supply Chain Analysis
Dual-use technology controls on automated sorting systems limit cross-border equipment flows from Netherlands sensor manufacturers to French retail distribution centers. Wet digestion reactor fabrication concentrates in Germany, Italy, and Denmark, drawing from specialized stainless steel alloys and precision membrane components. Single-source vulnerability in thermal hydrolysis pressure vessel supply creates bottlenecks for capacity expansion timelines. Distribution runs through centralized biogas upgrading facilities co-located with existing natural gas grid injection points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's 2030 food waste reduction mandate creates a regulatory inflection compressing project development cycles and accelerating capital deployment into anaerobic digestion infrastructure.
For Market Incumbents: Build feedstock security moats through direct contracting relationships with REWE Group and EDEKA supermarket chains. Secure thermal hydrolysis technology leadership to defend against emerging pre-treatment specialists. Add upgrading capacity in Netherlands port-connected zones to anchor cross-border aggregation economics. For New Entrants and Emerging Players: Southern European municipal markets offer underpenetrated procurement opportunities as Italy and Spain lag Rhine-Ru corridor deployment rates. Target agricultural digestate valorization partnerships with Lombardy farming cooperatives. Enter through EU AI Act compliance service provision for automated contamination detection at retail collection points. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed waste management platforms seeking exit liquidity before EEG tariff framework revisions. Five-to-ten year viability hinges on biomethane certificate premium sustainability under evolving renewable gas standards. Watch for thermal hydrolysis technology consolidation signals as yield optimization becomes table stakes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Retail Collection | SARIA ReFood's supermarket contract control secures feedstock supply against logistics intermediaries. |
| Thermal Hydrolysis Technology Licensing | EnviTec Biogas membrane partnerships accelerate hydrolysis rates for Rhine-Ruhr operators. |
| Cross-Border Feedstock Aggregation | Netherlands port infrastructure enables Benelux-France waste stream consolidation at scale. |
| EU AI Act Compliance Services | Computer vision deployment at French retail points preempts regulatory enforcement timelines. |
| Agricultural Digestate Valorization | Nitrogen recovery integration with Italian biogas upgrading opens circular economy revenue streams. |
Research Methodology
Cross-validation between regulatory filing analysis and equipment vendor disclosures anchors the qualitative findings in this study. Primary interviews with biogas plant operators, municipal waste procurement officers, energy utility planning teams, and thermal hydrolysis engineering specialists combined with secondary validation from EEG tariff framework documents, ECHA bio-waste characterization protocols, EU Green Deal implementation reports, and national grid injection standards. Bottom-up capacity modeling and top-down renewable gas certificate market sizing provided triangulation across data sources.
Calibration against historical deployment rates in Germany's Rhine-Ruhr corridor and France's Île-de-France region grounded the analytical framework across the projection horizon. Segmentation dimensions modeled include supply chain stage, facility type, end-user archetype, and technology employed, with regulatory framework cluster as an industry-specific overlay. CAGRs derived from feedstock availability projections and biomethane offtake contract formation rates, incorporating natural gas benchmark volatility assumptions and EEG tariff stability scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by energy producer consortiums would shift outcomes from baseline projections. Material shifts in EU Green Deal enforcement timelines or EEG tariff reduction schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Vacuum Waste Systems Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market