
 Solar Waste Recycling Market | 2026-2036
Solar Waste Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Waste Recycling Market Intelligence
A focus on high-purity material recovery is rotating the market away from simple mechanical processing towards advanced hydrometallurgical techniques. Veolia Environnement SA leverages its global waste management infrastructure to offer integrated collection and processing services. First Solar Inc. specializes in recycling its own cadmium telluride thin-film panels, creating a closed-loop system. ROSI Solar focuses on recovering high-purity silicon and silver from photovoltaic waste, targeting higher-value material streams.
Solar waste recycling involves the disassembly and material recovery from end-of-life photovoltaic modules, inverters, and batteries. The process aims to extract valuable materials like silicon, silver, copper, and aluminum, diverting hazardous components from landfills. Within processing technologies, hydrometallurgical processing is gaining share over pyrometallurgical methods due to higher recovery rates for precious metals. Photovoltaic panels constitute the largest end-of-life category by volume, driven by the first wave of large-scale solar installations reaching their operational lifespan.
Regulatory frameworks are the primary market shapers. The European Union's WEEE Directive mandates producer responsibility, while in the United States, EPA rules under RCRA govern the handling of potentially hazardous materials from panels. In China, national dual carbon goals implicitly support the development of a circular economy for solar components. Stakeholders must now decide whether to invest in advanced recovery technologies or secure long-term partnerships with specialized recyclers.
Market Dynamics
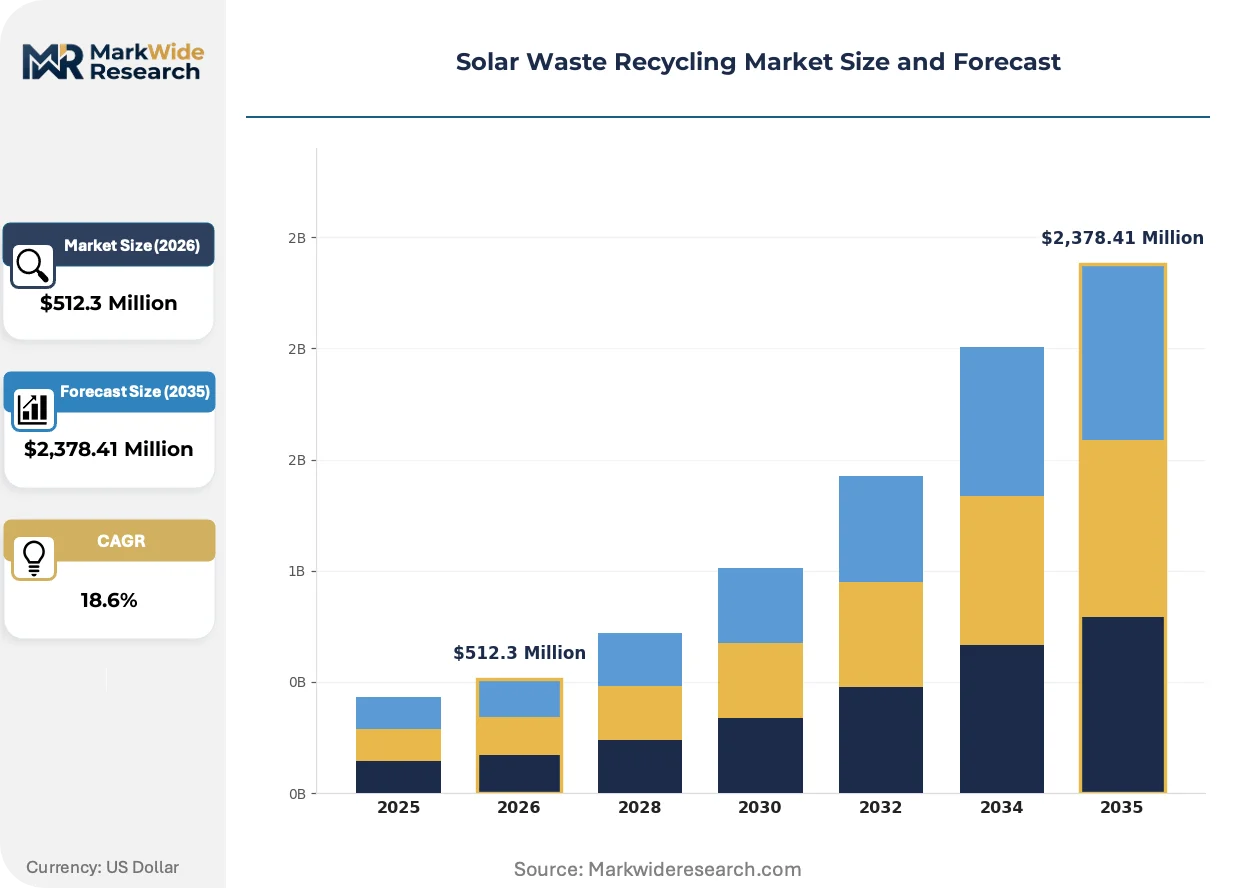
Regulatory frameworks, particularly producer responsibility mandates, are the primary force shaping the solar waste recycling market. The decommissioning of first-generation utility-scale solar farms provides the raw material stream, creating a compliance-driven and supply-led industry structure.
Growth Catalysts
- EU WEEE Directive:The European Union's Waste Electrical and Electronic Equipment Directive imposes legally binding collection, recovery, and recycling targets on photovoltaic panel producers, creating a non-negotiable demand for recycling services.
- High-Value Material Recovery:The economic incentive to reclaim valuable and strategic materials, such as high-purity silicon, silver, and copper, from panel waste drives investment in advanced processing technologies beyond simple shredding.
- Aging Infrastructure:Mature solar markets, including Germany, Japan, and the United States, possess large installed bases of early-generation solar panels now approaching their end-of-life, creating concentrated volumes of feedstock for recyclers.
Market Restraints
- Unfavorable Logistics Costs:The high cost of collecting and transporting bulky, heavy panels from geographically dispersed sites often outweighs the intrinsic value of the recoverable materials, particularly for residential installations.
- Complex Material Separation:The laminated structure of photovoltaic panels, with polymers like EVA strongly bonded to glass and cells, presents a significant technical challenge for efficient, low-energy, and cost-effective material separation.
- Inconsistent Regulation:Outside of the European Union, a patchwork of inconsistent or non-existent regulations, such as the state-by-state approach under RCRA in the United States, creates market uncertainty and deters long-term investment in recycling capacity.
Strategic Opportunities
- Second-Life Panel Markets:Developing certified channels for testing, repairing, and reselling used panels for less demanding applications creates an intermediate value stream, extending asset life before incurring final recycling costs.
- On-Site Processing Solutions:The development of mobile or modular recycling units that can be deployed directly at large-scale solar farm decommissioning sites offers a path to reduce transportation costs and integrate logistics.
- Circular Economy Policies:National industrial strategies, such as China's dual carbon goals, create future demand for a domestic circular economy for solar components, opening opportunities for technology licensing and service partnerships.
Industry Challenges
- Reverse Logistics Complexity:Establishing an efficient reverse supply chain to collect end-of-life panels from millions of individual residential and small commercial rooftops presents a significant operational hurdle compared to centralized utility-scale sites.
- Lack of Design-for-Recycling:The absence of standardized panel designs and the use of difficult-to-separate materials in legacy products inhibit the use of automated disassembly, requiring costly and slow manual labor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Waste Recycling Market |
| Market Size in 2026 | $512.3 Million |
| Market Size in 2035 | $2,378.41 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Curbside Collection, Drop-off Centers, Retail Partnerships, Mobile Units Processing Technology: Mechanical Recycling, Pyrometallurgical Processing, Hydrometallurgical Processing, Biotechnology End-of-Life Category: Photovoltaic Panels, Inverters, Batteries, Miscellaneous Components Service Type: Collection Services, Processing Services, Consulting Services, Compliance Services |
| Companies Covered | First Solar Inc., Reiling GmbH & Co. KG, Solarcycle, Inc, Veolia Environnement SA, ROSI Solar, Echo Environmental, LLC, SILCONTEL LTD, Silrec Corporation, We Recycle Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Waste Recycling Market Strategic Shifts & Innovations
Technological advancements and policy pressures are transforming solar waste processing from a disposal-centric activity into a sophisticated material recovery industry. The focus is now on maximizing the recapture of high-purity, strategic materials to support a circular economy for photovoltaics.
Hydrometallurgical processing uses chemical solutions to selectively leach and recover high-purity metals like silver and silicon from shredded photovoltaic material. Specialized recyclers are pioneering these techniques to move beyond the recovery of simple bulk materials like glass and aluminum. This trend is bifurcating the market between low-margin mechanical shredding operations and high-value, chemistry-based refiners targeting strategic materials.
The US Environmental Protection Agency (EPA) is clarifying rules under the Resource Conservation and Recovery Act (RCRA) regarding the classification of photovoltaic panels as universal or hazardous waste. This action pressures solar asset owners and operators to adopt formal end-of-life management plans rather than relying on landfilling. Consequently, utility-scale operators in states with stricter environmental regulations are proactively establishing partnerships with certified electronics recyclers.
A shift is occurring from ad-hoc, end-of-life disposal contracts to integrated, long-term asset management agreements that include decommissioning and recycling services. This model displaces transactional relationships with waste haulers in favor of strategic partnerships with specialized recyclers who can provide documentation for ESG reporting. This trend is most prominent among large-scale solar farm operators in Europe, driven by producer responsibility obligations under the WEEE Directive.
Solar Waste Recycling Market Segmentation
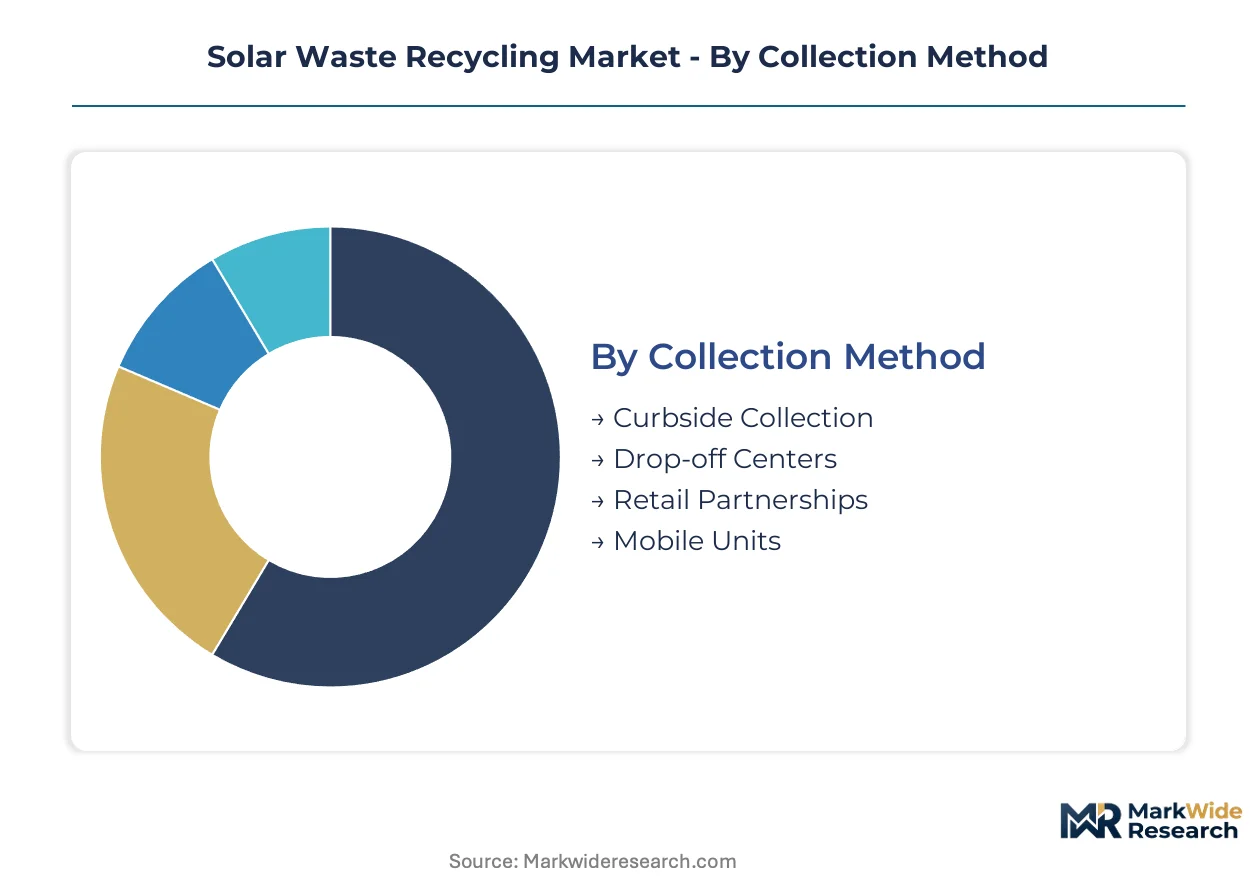
The solar waste recycling market's segmentation reflects the diverse challenges and opportunities inherent in recovering materials from end-of-life solar infrastructure. Understanding these distinct segments allows stakeholders to tailor collection strategies, optimize processing technologies, and develop specialized services that meet evolving regulatory and material recovery demands across global markets.
Collection Method:
Substitution pressure is highest for traditional collection methods as mobile units and retail partnerships offer more convenient and efficient alternatives for certain panel types and volumes. The logistics of reverse supply chains are evolving to reduce overall costs.
- Curbside Collection:This method involves scheduled pickups directly from residential or small commercial sites, often integrated with existing municipal waste management systems. Its scalability is limited by panel volume and weight, making it less viable for large-scale decommissioning projects.
- Drop-off Centers:Dedicated facilities or designated areas at existing recycling centers accept end-of-life solar panels from various sources. These centers concentrate material streams, which reduces individual transportation costs and supports initial sorting efforts before specialized processing.
- Retail Partnerships:Collaborations with electronics retailers or solar installers enable consumers to return end-of-life panels at convenient locations. This approach improves accessibility for residential panel owners, particularly in regions with strong consumer protection laws.
- Mobile Units:Specialized vehicles or modular setups are deployed directly to large utility-scale solar farms for on-site dismantling and initial material separation. This reduces the high cost of transporting bulky panels over long distances and integrates with decommissioning schedules.
Drop-off Centers retain volume leadership; Mobile Units hold the steepest expansion curve.
Processing Technology:
The cost tier of processing technologies varies significantly, with mechanical methods offering lower initial investment but lower material purity compared to advanced chemical processes. Investment decisions hinge on desired recovery rates and material value.
- Mechanical Recycling:This involves physical processes like shredding, grinding, and separation to recover bulk materials such as glass, aluminum, and some plastics. It serves as a foundational step for many recycling operations, particularly for high-volume, lower-value components.
- Pyrometallurgical Processing:This method uses high temperatures to smelt materials, separating metals from non-metallic components. It can degrade materials and consume significant energy.
- Hydrometallurgical Processing:Chemical solutions selectively leach and recover high-purity metals like silver, copper, and silicon from shredded photovoltaic material. This advanced technique yields higher-value material streams, driving demand for specialized refining capabilities in Europe and Japan.
- Biotechnology:Emerging technologies explore the use of biological agents or processes to separate and recover materials from solar waste. This innovative approach aims for more environmentally benign and energy-efficient recovery methods.
Mechanical Recycling still handles the largest volume; Hydrometallurgical Processing is gaining share fastest.
End-of-Life Category:
The volume of material dictates processing strategies for each end-of-life category, with photovoltaic panels representing the largest and most complex stream. Each category presents unique material compositions and recovery challenges.
- Photovoltaic Panels:These modules constitute the largest volume of solar waste, driven by the decommissioning of first-generation utility-scale installations. Recovery focuses on glass, aluminum, silicon, and precious metals like silver, often requiring multi-stage processes.
- Inverters:Inverters convert DC power from panels to AC power, containing valuable copper, aluminum, and circuit board materials. Recycling focuses on efficient metal recovery.
- Batteries:Energy storage units, increasingly integrated with solar systems, contain critical materials such as lithium, cobalt, and nickel. Their recycling is crucial due to both material value and potential environmental hazards, with significant focus in the United States and Germany.
- Miscellaneous Components:This category includes mounting structures, cabling, and other electrical balance-of-system parts. These components are primarily metal-based, making their recovery relatively straightforward through conventional metal recycling channels.
Photovoltaic Panels dominate the material stream; Batteries show the most rapid increase in end-of-life volume.
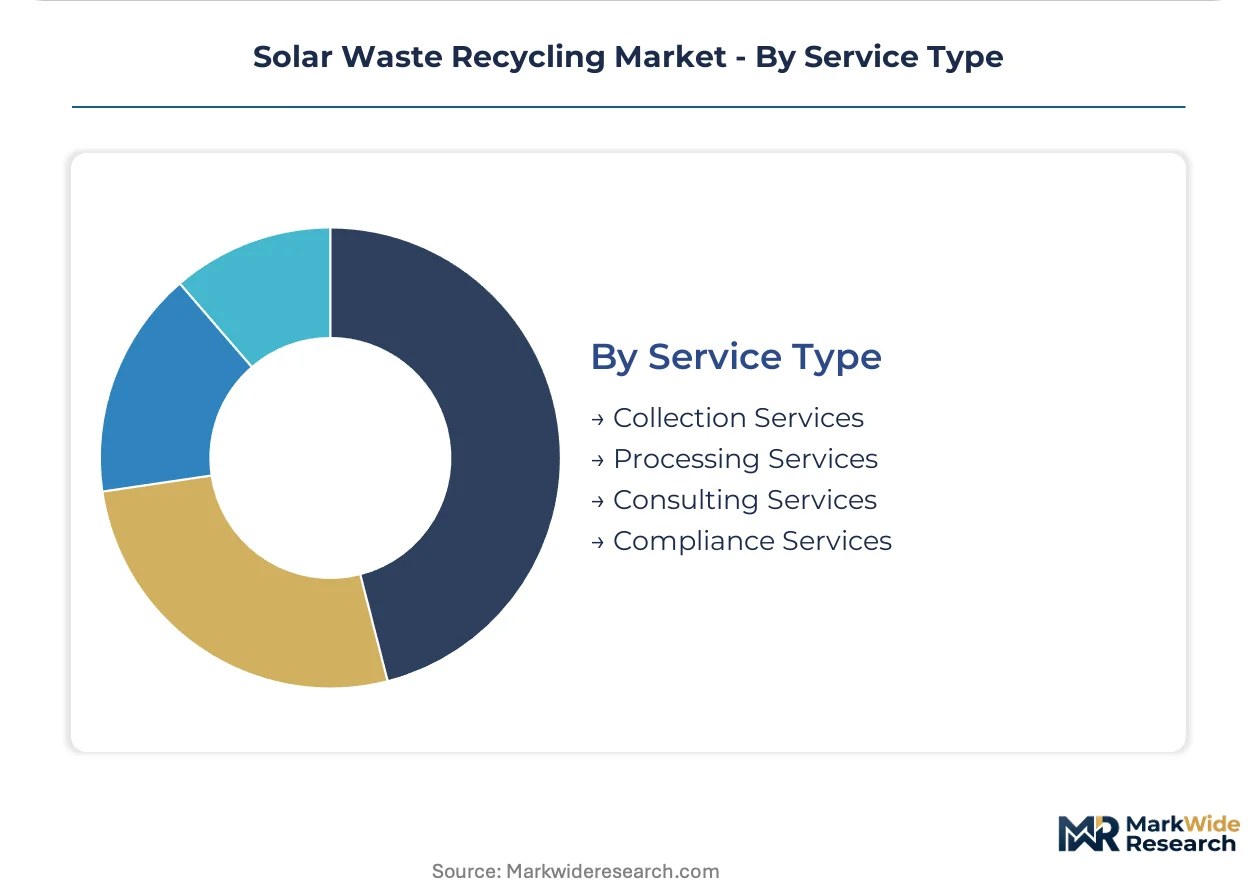
Service Type:
Customer type significantly influences the demand for different service types, with utility-scale operators requiring comprehensive, integrated solutions, and residential customers needing more accessible, simplified options. Regulatory compliance drives specific service needs.
- Collection Services:Collection services encompass logistics for picking up, transporting, and consolidating end-of-life solar components. Efficient networks reduce costs and improve material availability.
- Processing Services:This involves the actual dismantling, separation, and material recovery operations using mechanical, thermal, or chemical techniques. Specialized processing facilities extract valuable resources from complex solar waste streams.
- Consulting Services:Providers offer expertise in navigating regulatory frameworks, developing end-of-life management plans, and optimizing recycling strategies for solar asset owners. These services are particularly vital for large enterprises.
- Compliance Services:These services ensure that solar panel producers and operators meet mandated recycling targets and reporting requirements under directives like the EU WEEE Directive. Compliance solutions provide necessary documentation and adherence to environmental regulations.
Processing Services command the largest market share; Compliance Services are experiencing the fastest growth in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of end-of-life solar panels and recycling infrastructure is evident in mature solar markets, driven by early installations reaching decommissioning age. These regions also possess robust regulatory frameworks and technological capabilities to support advanced material recovery. The logistical challenges of solar panel collection often necessitate localized processing solutions within these key geographies.
Germany
Germany's significant installed base of first-generation photovoltaic panels creates substantial feedstock for recycling operations. The EU WEEE Directive mandates high recycling targets, ensuring a consistent demand for processing services. Facilities in states like Bavaria and North Rhine-Westphalia actively develop advanced hydrometallurgical techniques for silicon and silver recovery.
United States
The United States sees growing volumes of end-of-life panels, particularly from utility-scale solar farms. EPA rules under RCRA influence waste classification, prompting asset owners to seek certified recycling solutions. California and Arizona, with large solar installations, are developing regional hubs for panel collection and material processing.
Japan
Japan's early adoption of solar power now translates into a rising wave of decommissioned panels. METI guidelines encourage responsible end-of-life management for photovoltaic modules. Recycling initiatives in regions like Fukushima and Kansai focus on recovering high-purity materials to support domestic manufacturing.
China
China's rapid expansion of solar capacity means future recycling volumes will be immense, particularly from large-scale projects. National dual carbon goals implicitly support the development of a circular economy for solar components. The Yangtze River Delta and Pearl River Delta regions are investing in new recycling technologies and infrastructure.
France
France, a prominent EU member, contributes significantly to the European solar waste stream. The country adheres strictly to the EU WEEE Directive, which drives producer responsibility schemes. Specialized recycling centers in regions such as Occitanie and Auvergne-Rhône-Alpes are expanding capacity for advanced material separation.
Solar Waste Recycling Market Key Industry Players
Concentration sits with large waste management conglomerates and specialized material recovery firms within the solar waste recycling market. The market structure exhibits a tiered approach, with foundational mechanical processors at one end and high-value chemical refiners at the other. Dominant competitive moves include strategic partnerships for collection logistics and continuous investment in advanced processing technologies to improve material purity.
Specialists in high-purity material recovery include First Solar Inc., which focuses on closed-loop recycling of its own cadmium telluride thin-film panels. Veolia Environnement SA, a global waste management giant, exemplifies integrated collection and processing services, leveraging its extensive infrastructure. ROSI Solar occupies a position within the advanced recycling segment, targeting the recovery of high-value silicon and silver from photovoltaic waste streams.
| Leading Market Players |
|---|
| First Solar Inc. |
| Reiling GmbH & Co. KG |
| Solarcycle, Inc |
| Veolia Environnement SA |
| ROSI Solar |
| Echo Environmental, LLC |
| SILCONTEL LTD |
| Silrec Corporation |
| We Recycle Solar |
| Others |
Cost & Logistics Intelligence
High-purity material recovery, a key substitution dynamic, is simultaneously reshaping supply geography towards specialized processing hubs and elevating pricing economics for advanced material streams.
Pricing Analysis
The EU WEEE Directive dictates the pricing tier structure for recycling services, emphasizing compliance and material recovery targets. The dominant pricing model involves contract-based long-term asset management agreements for utility-scale operators. Price differentiation stems from the purity of recovered materials and the provision of comprehensive ESG reporting documentation. Pricing pressure stems from the high cost of collecting and transporting residential panels, making this segment highly price-sensitive. Utility-scale operators, driven by regulatory obligations, exhibit lower price sensitivity for compliant and integrated solutions.
Supply Chain Analysis
Strategic aggregation of end-of-life panels precedes advanced processing in this industry, moving away from just-in-time disposal. Geographic supply concentration for feedstock occurs in Germany, the United States, and Japan, reflecting early solar adoption and large installed bases. Raw material dependencies center on high-purity silicon, silver, and copper recovered from photovoltaic panels. Inconsistent regulation outside the European Union creates a structural risk by deterring long-term investment, with distribution running through direct service partnerships between asset owners and specialized recyclers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
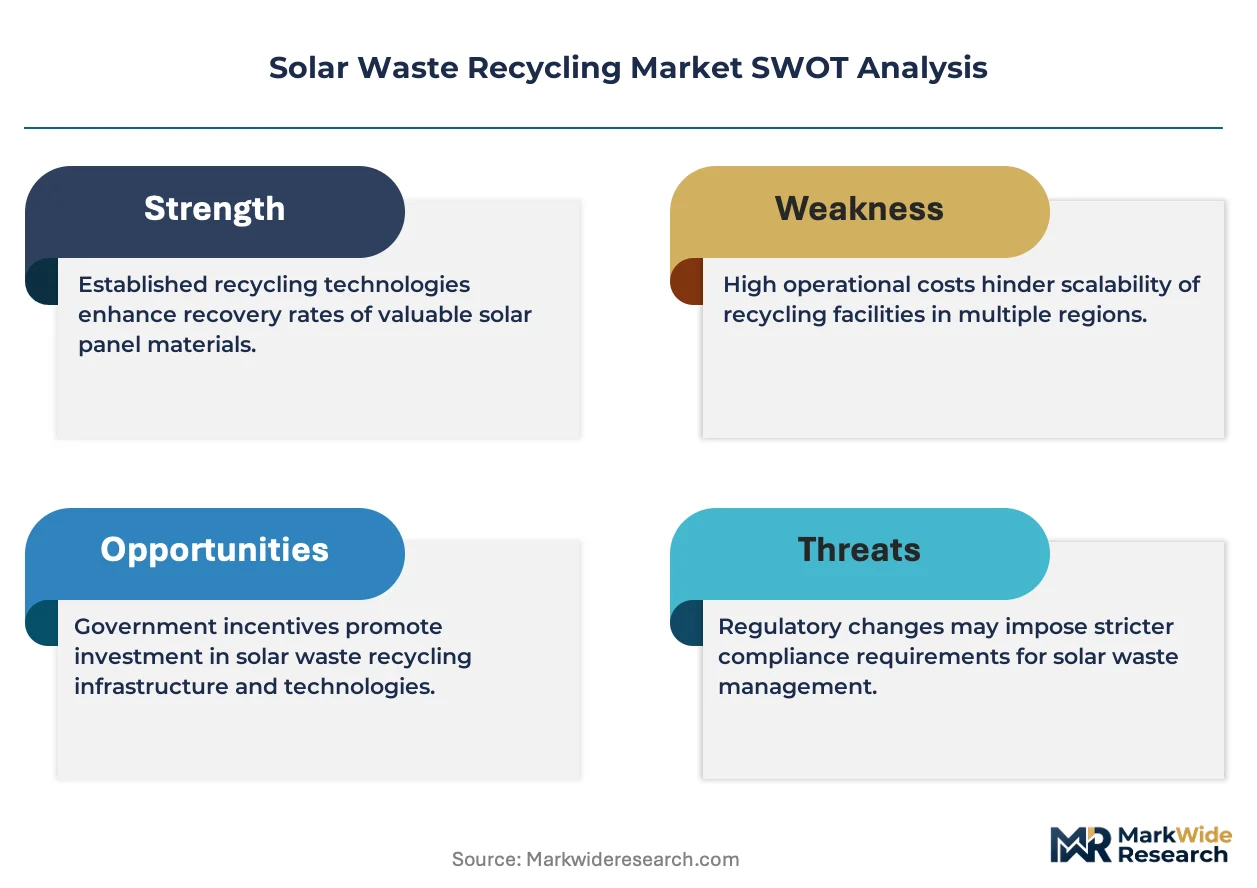
The solar waste recycling market is entering a cyclical recovery, driven by the increasing wave of first-generation utility-scale solar panels reaching their end-of-life.
For Market Incumbents: Consolidate advanced processing capabilities through strategic acquisitions to counter the threat of fragmented regulation. Secure long-term asset management agreements with utility-scale operators, leveraging investment in hydrometallurgical technology. This approach reinforces market position against emerging specialized recyclers and ensures compliance with EU WEEE Directive obligations.
For New Entrants and Emerging Players: Lead with modular, on-site processing solutions to address the high cost of reverse logistics. Target regions with nascent recycling infrastructure but growing solar capacity, such as developing areas in China, for technology licensing. Focus on high-purity material recovery from photovoltaic panels as a penetrable segment, offering a compelling value proposition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized material recovery firms and reverse logistics providers. Long-term viability is strong, anchored by expanding producer responsibility laws and the strategic value of recovered critical materials. Acquisition targets include firms demonstrating high recovery rates for silver and silicon or those with established mobile processing unit deployments. A signal to watch is the expansion of robust circular economy policies beyond current EU mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout in Hydrometallurgical Processing | Increases recovery rates for high-value materials like silver and silicon, meeting circular economy goals. |
| Develop Mobile On-Site Recycling Units | Reduces unfavorable logistics costs for large-scale solar farm decommissioning projects. |
| Secure Long-Term Utility Partnerships | Guarantees stable feedstock supply and ensures compliance for major solar asset owners. |
| Invest in Design-for-Recycling R&D | Simplifies future material separation from photovoltaic panels, lowering processing costs. |
| Geographic Expansion into Emerging Solar Markets | Captures future end-of-life volumes from China and other rapidly growing solar regions. |
Research Approach
A spread of perspectives from utility-scale solar farm operators, specialized recyclers, regulatory body representatives, and material science engineers converged on the working assumptions. Primary interviews were conducted with these industry stakeholders, validated through extensive secondary research. Secondary sources included EU WEEE Directive documentation, EPA RCRA guidelines, METI guidelines, and industry association reports. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Segmentation dimensions modeled include collection method, processing technology, end-of-life category, service type, and regional regulatory compliance maturity. The analytical framework projects market trajectories across the analysis window, with compound annual growth rates derived from historical trends and anticipated market shifts. Key forecast inputs include installed solar capacity decommissioning schedules and evolving material recovery rates for advanced technologies.
The analysis sits within stated boundaries; outcomes outside significant regulatory shifts or unforeseen technological advancements would require recalibration. Forecasts reflect assumptions regarding economic stability and continued policy support. Revision becomes warranted when commodity prices for recovered materials experience sustained volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
E-Waste Management Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
E-Scrap Recycling Market