
 Asia-Pacific Municipal Solid Waste Management Market | 2026-2036
Asia-Pacific Municipal Solid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Municipal Solid Waste Management Market Insights
China's dual carbon goals is broadening the addressable market for advanced waste processing across East Asia. Veolia Environment S.A. leverages its European incineration expertise to compete for municipal contracts in secondary Chinese cities. Beijing Enterprises Environment Group anchors domestic market share through integrated collection-to-disposal operations in northern provinces. Zhejiang Weiming Environment Protection Co. Ltd. differentiates via specialized hazardous waste treatment capabilities along the Yangtze River Delta.
Asia-Pacific municipal solid waste management encompasses the systematic collection, transport, processing, and final disposition of refuse generated by urban populations, with modern facilities achieving combustion temperatures exceeding 850 degrees Celsius in mass-burn incinerators to ensure complete dioxin decomposition. The primary purpose is to minimize environmental contamination while recovering energy and recyclable materials from heterogeneous waste streams. Collection services currently occupy the largest revenue share due to labor-intensive door-to-door logistics in dense informal settlements, though anaerobic digestion is registering the fastest capacity additions as food waste diversion mandates spread. Incineration technology leads capital deployment in Japan and South Korea where land scarcity elevates tipping fees, while composting retains structural importance across India's agrarian states seeking soil amendment outputs.
China's MEE enforces increasingly stringent landfill leachate standards that force facility upgrades, while India's CPCB mandates extended producer responsibility frameworks for plastic waste that reshape collection economics. Japan's METI subsidizes next-generation gasification plants under revised feed-in tariff schedules. Stakeholders must monitor how Indonesia's national waste bank program and Vietnam's pending circular economy decree alter competitive access rules before committing to long-term asset positions.
Market Dynamics
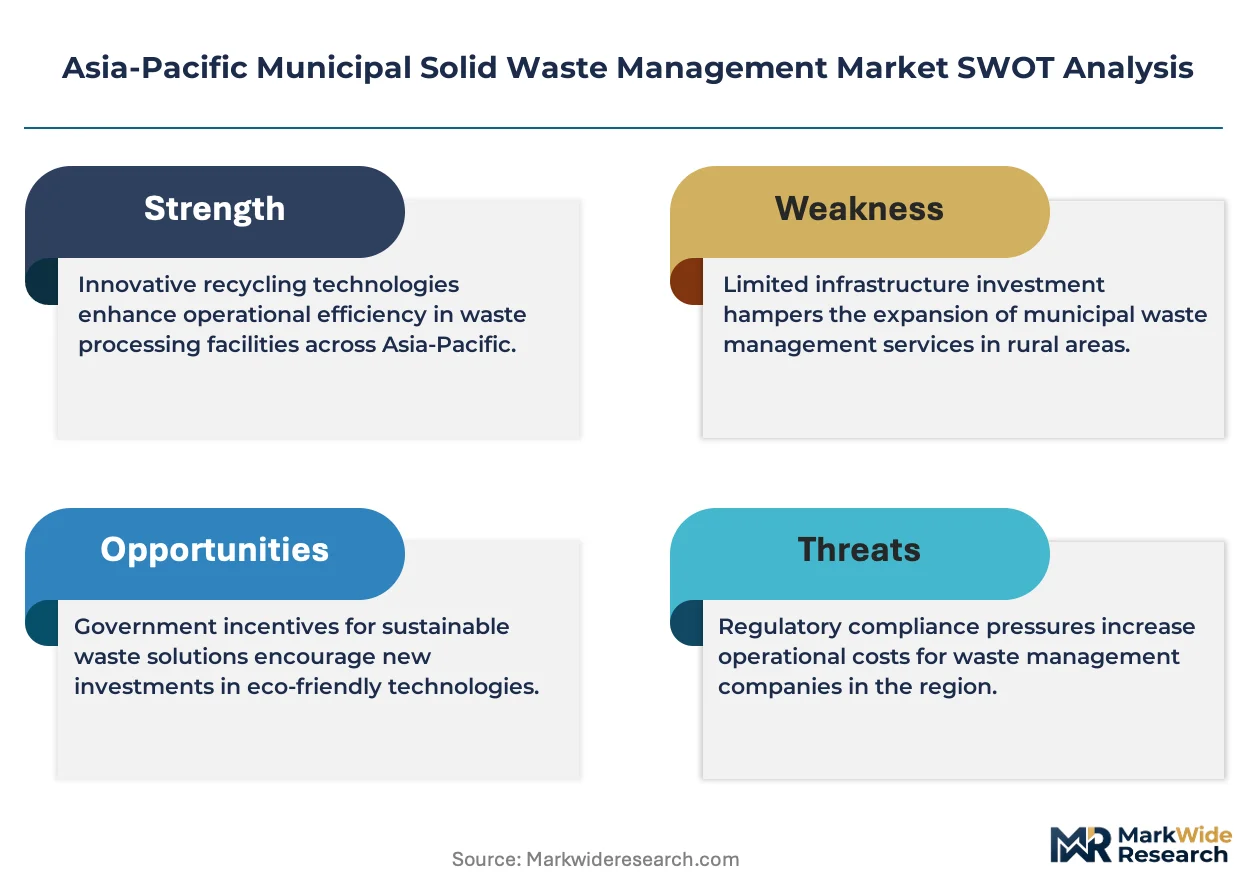
Landfill capacity exhaustion across Southeast Asian megacities is forcing municipal governments toward capital-intensive thermal treatment and anaerobic digestion infrastructure, compressing project timelines and elevating equipment procurement urgency.
Growth Catalysts
- China's dual carbon goals:Beijing's net-zero commitments mandate methane capture from municipal waste, redirecting provincial budgets toward anaerobic digestion and biogas upgrading facilities.
- Extended Producer Responsibility:India's CPCB plastic waste rules obligate brand owners to fund collection infrastructure, creating guaranteed revenue streams for integrated waste management operators.
- Feed-in tariff revisions:Japan's METI has elevated power purchase rates for advanced gasification outputs, improving project IRRs for next-generation waste-to-energy plants.
Market Restraints
- Capital intensity barriers:Mass-burn incinerators require USD 150-400 million per 1,000-tonne daily capacity, freezing out municipal governments without multilateral development bank co-financing.
- Technical limitation:Heterogeneous waste streams in Indonesian informal settlements exceed 50% moisture content, degrading combustion efficiency and requiring costly pre-treatment drying.
- Regulatory friction:Vietnam's pending circular economy decree lacks implementing sub-decrees, leaving foreign investors exposed to licensing ambiguity and tariff renegotiation risk.
Strategic Opportunities
- Underpenetrated secondary cities:Surabaya, Bandung, and Medan in Indonesia lack engineered landfills, creating first-mover advantages for integrated collection-to-energy operators.
- Technology convergence:AI-powered sorting robotics combined with near-infrared spectroscopy is enabling high-purity plastic recovery from commingled municipal streams at throughput rates exceeding manual labor.
- Regulatory tailwind:South Korea's food waste diversion mandates, enforced through RFID-tracked disposal bags, guarantee feedstock supply for anaerobic digestion facility operators.
Industry Challenges
- Capex intensity:Leachate treatment upgrades to meet China's MEE discharge standards require 15-25% of original landfill construction costs, straining operator balance sheets.
- Integration complexity:Legacy open dumping sites across the Philippines resist retrofitting for sanitary landfill standards due to informal settlement encroachment and title disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Municipal Solid Waste Management Market |
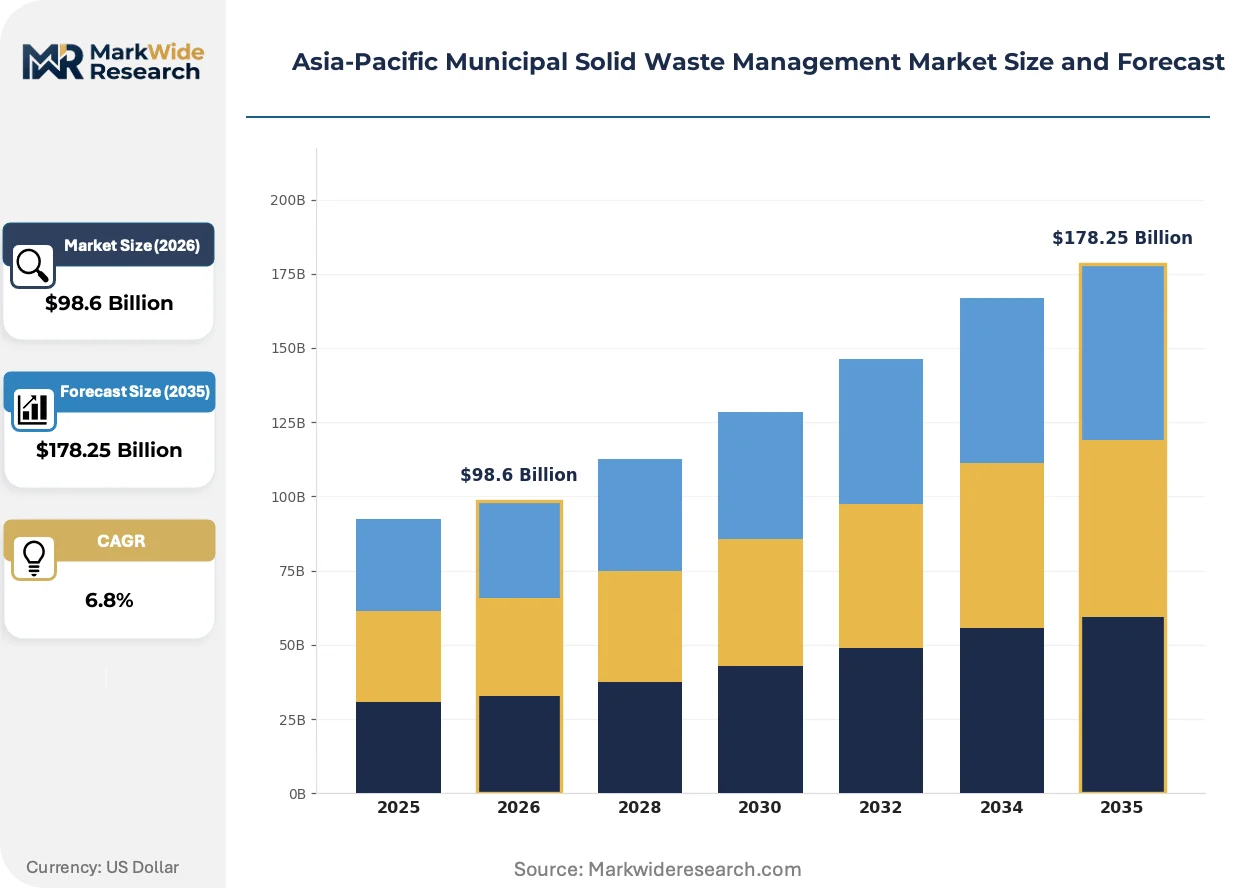
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Disposal, Treatment Technology: Incineration, Landfilling, Composting, Anaerobic Digestion End User: Municipalities, Private Companies, NGOs, Community Organizations Waste Type: Organic Waste, Plastic Waste, E-Waste, Hazardous Waste |
| Companies Covered | Veolia Environment S.A., Suez Group, Waste Management Inc., Covanta Holding Corporation, China Everbright Environment Group, Beijing Enterprises Environment Group, China Tianying Inc., Chongqing Sanfeng Environmental Protection, Zhejiang Weiming Environment Protection Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Municipal Solid Waste Management Market Trends and Innovations
Digitalization of waste logistics and thermal treatment efficiency gains are compressing operating costs while regulatory mandates on organic diversion reshape facility design specifications across the region.
Optical sorting systems employing artificial intelligence and hyperspectral imaging are automating the separation of recyclables from mixed municipal streams. Japanese and South Korean materials recovery facilities deploy these systems at 30-50 tonne per hour throughput rates. The technology is automating quality control roles previously requiring manual picker stations, reducing labor costs by half in high-wage environments.
China's MEE landfill leachate discharge standards now enforce total nitrogen limits below 15 mg/L, forcing facility upgrades nationwide. Operators must install membrane bioreactor and reverse osmosis trains to achieve compliance. Northern province facilities face the steepest retrofit burden due to older single-liner designs and limited leachate storage capacity.
Municipal procurement patterns are fragmenting as Indonesian cities experiment with performance-based service contracts. Surabaya's waste bank program and Jakarta's regional operator splits displace single-city monopolies. Vietnam's pending public-private partnership framework accelerates this shift, with Ho Chi Minh City soliciting bids on 20-year build-operate-transfer terms for integrated treatment complexes.
Asia-Pacific Municipal Solid Waste Management Market Segmentation
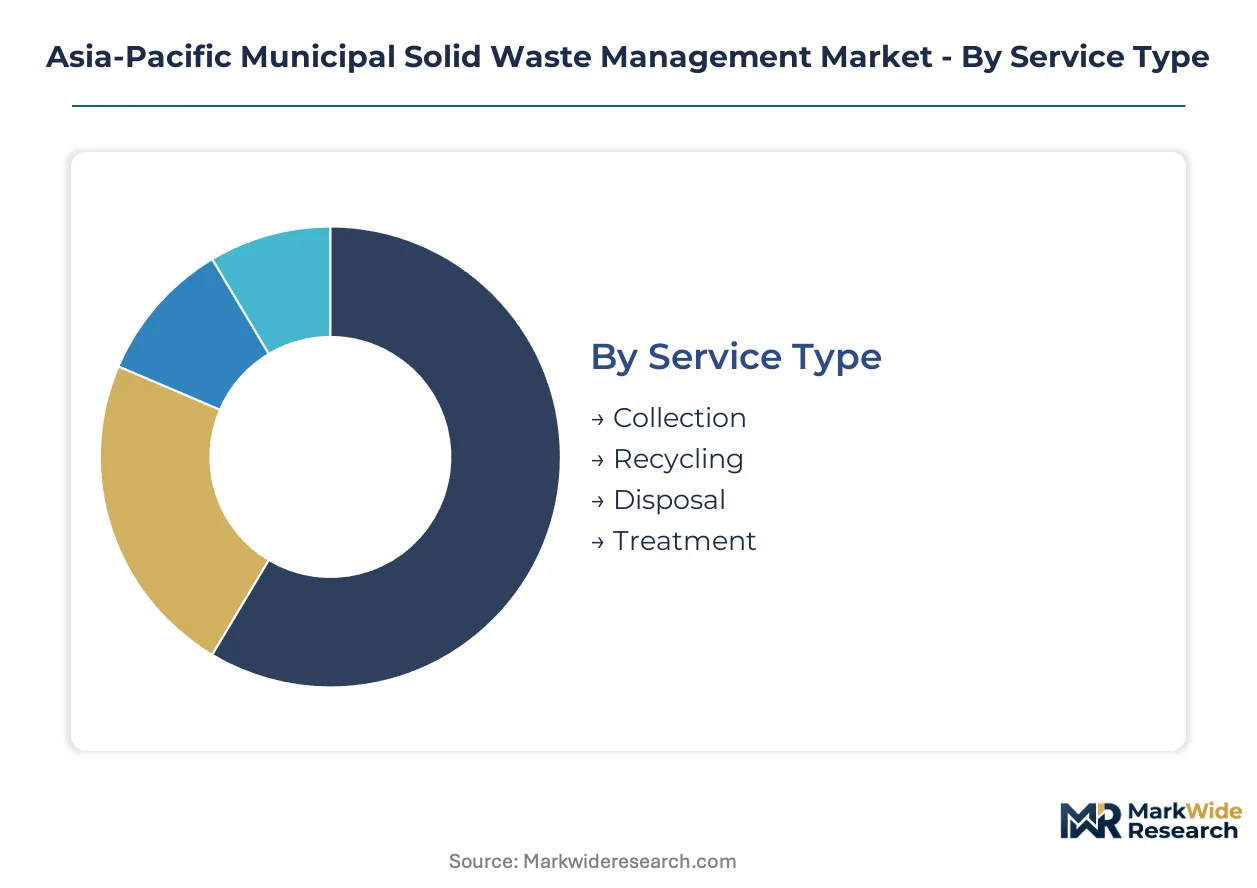
Segmentation in Asia-Pacific municipal solid waste management reveals divergent capital deployment patterns across service tiers and technology maturity levels. Collection and disposal services currently absorb the majority of municipal budgets, while advanced treatment technologies command premium equipment margins and longer contract tenures.
Service Type:
Standalone collection operations function as labor-intensive entry points for municipal contractors, whereas integrated disposal and treatment services embed within multi-decade concession frameworks that lock in revenue visibility.
- Collection:Door-to-door logistics in dense informal settlements across Jakarta, Surabaya, and Manila rely on informal waste picker networks integrated into formal municipal contracts. India's CPCB extended producer responsibility rules now obligate brand owners to fund separate collection streams for plastic packaging, redirecting capital toward dedicated fleet expansion in tier-2 cities.
- Recycling:Materials recovery facilities employing AI-powered optical sorting achieve 30-50 tonne per hour throughput in Japanese and South Korean operations. China's MEE enforcement of stricter contamination standards for imported recyclables has compressed margins for manual sorting operations, accelerating automation procurement across coastal provinces.
- Disposal:Engineered landfills with composite liner systems and leachate collection represent the baseline compliance standard for Indonesian and Vietnamese municipalities. Northern China facilities face 15-25% retrofit costs to meet MEE total nitrogen discharge limits below 15 mg/L.
- Treatment:Thermal and biological processing infrastructure commands the highest capital intensity per tonne of installed capacity, with mass-burn incinerators requiring USD 150-400 million per 1,000-tonne daily throughput.
Volume placements concentrate in Collection; the faster expansion belongs to Treatment.
Technology:
Technology selection tracks land scarcity gradients and feedstock moisture profiles, with mature thermal systems dominating capital deployment in Japan and South Korea while biological alternatives gain traction in high-organic waste corridors.
- Incineration:Mass-burn facilities achieving combustion temperatures exceeding 850 degrees Celsius ensure complete dioxin decomposition. Japan's METI feed-in tariff revisions for advanced gasification outputs have improved project IRRs for next-generation plants in secondary cities.
- Landfilling:Sanitary landfill construction dominates Indonesian and Vietnamese procurement where engineered capacity remains underdeveloped. Surabaya, Bandung, and Medan lack compliant disposal facilities, creating first-mover advantages for integrated operators.
- Composting:Windrow and in-vessel systems retain structural importance across India's agrarian states seeking soil amendment outputs. Punjab and Haryana procurement prioritizes compost quality standards for agricultural resale.
- Anaerobic Digestion:Biogas upgrading facilities capture methane from organic waste streams to meet China's dual carbon goals. South Korea's RFID-tracked food waste disposal bags guarantee feedstock supply for facility operators under national diversion mandates.
Capital deployment clusters in Incineration; the steepest capacity additions are occurring in Anaerobic Digestion.
End User:
Contracting authority determines risk allocation structures, with municipal concessions spanning 20-30 years and private sector procurement favoring shorter performance-based terms.
- Municipalities:City governments across Southeast Asia are fragmenting procurement into performance-based service contracts. Jakarta's regional operator splits and Surabaya's waste bank program displace single-city monopolies.
- Private Companies:Industrial waste generators in China's Yangtze River Delta and Pearl River Delta clusters contract directly for hazardous waste treatment capacity. Zhejiang Weiming Environment Protection anchors market share through specialized capabilities in this segment.
- NGOs:Community-based organizations manage decentralized collection points in Philippine informal settlements where formal infrastructure encroachment remains limited.
- Community Organizations:Waste bank cooperatives in Indonesian cities intermediate between households and formal recyclers, capturing price arbitrage on sorted materials.
Contract volume aggregates in Municipalities; the most rapid procurement evolution is occurring among Private Companies.
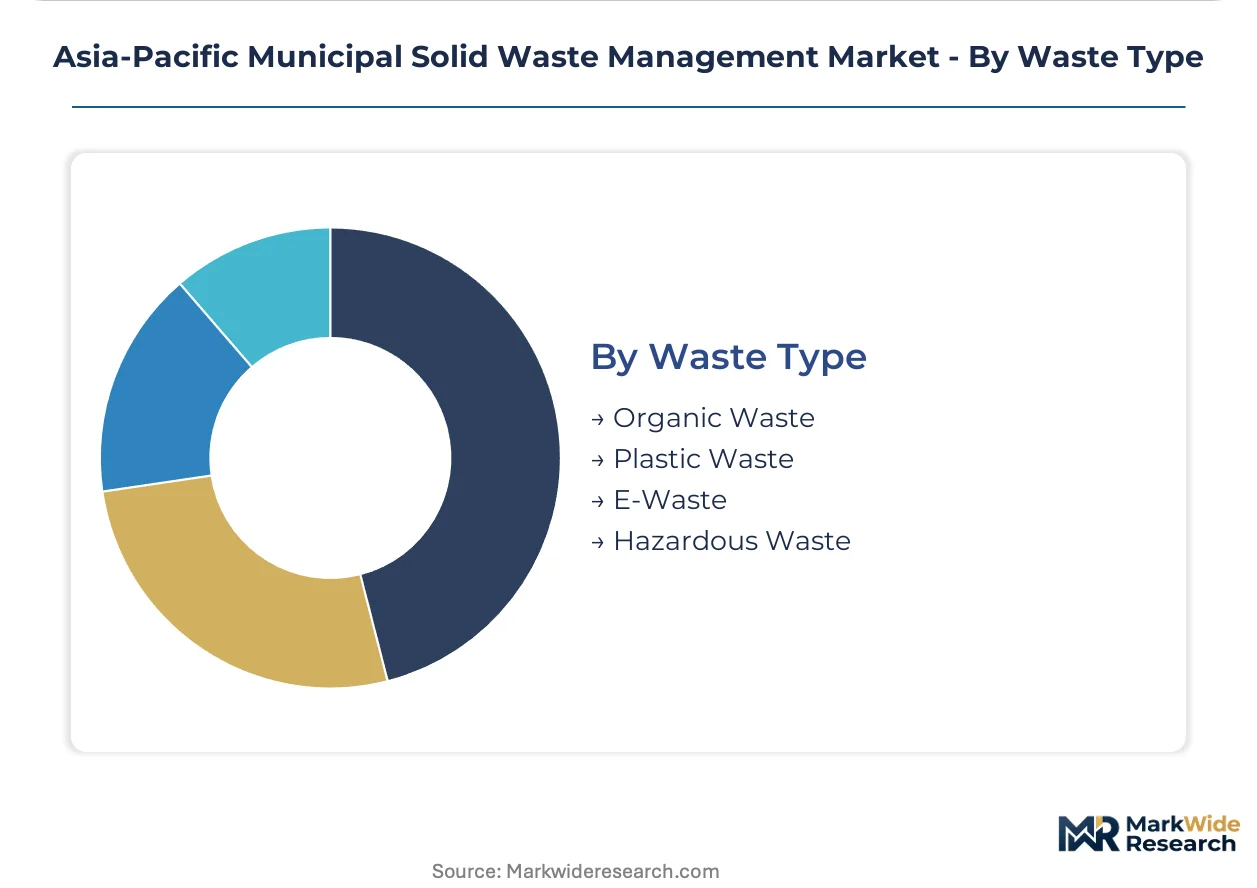
Waste Type:
Feedstock heterogeneity dictates preprocessing requirements and technology compatibility, with high-moisture organic streams degrading combustion efficiency and requiring costly drying infrastructure.
- Organic Waste:Food waste and agricultural residues exceeding 50% moisture content in Indonesian informal settlements require pre-treatment drying before thermal processing. South Korea's national diversion mandates guarantee feedstock supply for anaerobic digestion operators.
- Plastic Waste:India's CPCB extended producer responsibility frameworks obligate brand owners to fund collection infrastructure, creating guaranteed revenue streams for integrated operators. Near-infrared spectroscopy enables high-purity recovery from commingled streams.
- E-Waste:Informal dismantling clusters in Guiyu, China and Moradabad, India face progressive formalization pressure under MEE and CPCB enforcement actions.
- Hazardous Waste:Specialized treatment capabilities concentrate along China's Yangtze River Delta where chemical and pharmaceutical manufacturing generates concentrated demand.
Tonnage volumes dominate in Organic Waste; regulatory tailwinds are accelerating infrastructure deployment for Plastic Waste.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors the region's procurement urgency as landfill capacity exhaustion forces Indonesian municipalities toward thermal treatment infrastructure, with Surabaya and Bandung following similar capital deployment trajectories across Southeast Asian megacities.
China
Beijing-Tianjin-Hebei and the Yangtze River Delta drive mechanized sorting and anaerobic digestion deployment under MEE landfill leachate standards. The dual carbon goals mandate methane capture from municipal waste, redirecting provincial budgets toward biogas upgrading facilities. Northern province landfills face 15-25% retrofit costs to meet total nitrogen discharge limits below 15 mg/L.
Japan
Land scarcity across the Kanto and Kansai regions elevates tipping fees and sustains mass-burn incinerator deployment. METI feed-in tariff revisions for advanced gasification outputs improve project IRRs for next-generation waste-to-energy plants in secondary cities. Combustion temperatures exceeding 850 degrees Celsius ensure complete dioxin decomposition in metropolitan facilities.
South Korea
Seoul Capital Area operators benefit from guaranteed feedstock supply under national food waste diversion mandates enforced through RFID-tracked disposal bags. Anaerobic digestion capacity additions outpace other technology categories as biogas upgrading facilities capture methane from organic streams. Materials recovery facilities deploy AI-powered optical sorting at 30-50 tonne per hour throughput rates.
India
Punjab and Haryana prioritize compost quality standards for agricultural resale, sustaining windrow and in-vessel system procurement across agrarian states. CPCB extended producer responsibility frameworks for plastic waste obligate brand owners to fund collection infrastructure, creating guaranteed revenue streams for integrated operators. Tier-2 cities redirect capital toward dedicated fleet expansion under EPR-funded collection streams.
Indonesia
Surabaya, Bandung, and Medan lack engineered landfills, creating first-mover advantages for integrated collection-to-energy operators. Municipal procurement fragments as cities experiment with performance-based service contracts and waste bank programs displace single-city monopolies. High-moisture waste streams exceeding 50% content degrade combustion efficiency and require costly pre-treatment drying infrastructure.
Asia-Pacific Municipal Solid Waste Management Market Competitive Landscape
The competitive structure tilts toward integrated collection-to-disposal operators with multi-decade concession frameworks. State-affiliated environment groups anchor domestic market share through vertically controlled provincial networks, while European incineration specialists compete for municipal contracts in secondary Chinese cities. Three archetypes dominate: integrated domestic champions, foreign technology licensors, and specialized hazardous waste treatment operators. Capacity expansion and strategic partnerships constitute the primary competitive moves as operators secure feedstock supply agreements and technology licensing arrangements.
Among China-based integrated operators, Beijing Enterprises Environment Group and Zhejiang Weiming Environment Protection Co. Ltd. occupy positions within the domestic champion tier, with the latter representing specialized hazardous waste treatment capabilities along industrial corridors. Veolia Environment S.A. exemplifies the foreign technology licensor archetype competing for municipal contracts. These three anchors illustrate the competitive tension between provincial incumbents and international specialists vying for procurement fragmentation in Indonesian and Vietnamese markets.
| Leading Market Players |
|---|
| Veolia Environment S.A. |
| Suez Group |
| Waste Management Inc. |
| Covanta Holding Corporation |
| China Everbright Environment Group |
| Beijing Enterprises Environment Group |
| China Tianying Inc. |
| Chongqing Sanfeng Environmental Protection |
| Zhejiang Weiming Environment Protection Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between MEE-compliant engineered landfills and legacy open dumping sites manifests in procurement premiums of 40-60% for composite liner systems, while that same bifurcation concentrates equipment sourcing among Jiangsu and Zhejiang manufacturers with MEE certification track records. Municipal buyers in Jakarta and Surabaya face extended tender cycles as they navigate this tiered supply base, with thermal treatment vendors commanding advance payment structures unavailable to conventional collection operators.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for anaerobic digestion and waste-to-energy facilities, with operators securing tipping fees indexed to power output rather than tonnage received. Price differentiation rests on technology maturity tier—mass-burn incinerators with 850-degree Celsius combustion specifications command 25-35% premiums over basic grate systems—while cost compression in manual collection services intensifies due to EPR-funded fleet expansion in Indian tier-2 cities. Municipal governments exhibit highest price sensitivity for standalone collection contracts, whereas industrial hazardous waste generators in China's Yangtze River Delta demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Skilled technician availability constraints in Shandong and Guangdong provinces limit deployment velocity for AI-powered optical sorting systems, forcing vendors to anchor training programs at installation sites. Equipment manufacturing concentrates in China, Germany, and Japan, with membrane bioreactor components for leachate treatment drawing from specialty chemical suppliers in South Korea and the Netherlands. Single-source vulnerability pervades near-infrared spectroscopy sensor procurement, where two Japanese suppliers dominate global output. Distribution runs through municipal tender processes with 18-24 month procurement cycles, supplemented by direct industrial contracts for hazardous waste capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase as AI-powered sorting robotics displace manual picker stations across Japanese and South Korean materials recovery facilities, compressing labor costs while elevating capital intensity. Incumbents must reposition around this automation inflection to defend concession renewals.
For Market Incumbents: Anticipate procurement fragmentation in Indonesian and Vietnamese municipalities by securing performance-based contract templates before Surabaya's waste bank program and Ho Chi Minh City's PPP framework mature. Anchor defensive positioning through backward integration into sorting equipment supply chains, particularly near-infrared spectroscopy maintenance capabilities that lock in municipal dependency. Prioritize MEE certification investment for northern China landfill retrofits ahead of total nitrogen discharge enforcement deadlines.
For New Entrants and Emerging Players: Begin with Surabaya, Bandung, and Medan in Indonesia, where engineered landfill absence creates first-mover advantages without incumbent concession encumbrance. Target anaerobic digestion deployment in South Korea's Seoul Capital Area, where RFID-tracked food waste disposal bags guarantee feedstock supply under national diversion mandates. Pursue technology licensing partnerships with European gasification specialists to bypass capital barriers in mass-burn incineration.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated collection-to-energy operators possessing MEE-certified thermal treatment assets, given China's dual carbon goals mandating methane capture infrastructure expansion. Long-term viability across the analysis window favors concession holders with 20-30 year municipal contracts in secondary Chinese cities and Indonesian urban corridors. Monitor Vietnam's pending circular economy decree implementing sub-decrees as the inflection signal for licensing clarity and tariff renegotiation risk resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | European gasification specialists enable Japanese METI feed-in tariff capture without full capex burden. |
| Backward Integration | In-house membrane bioreactor production reduces MEE compliance upgrade costs for northern China landfills. |
| Performance-Based Contracting | Surabaya's waste bank program template locks in 15-20 year revenue visibility against procurement fragmentation. |
| Feedstock Supply Agreement | RFID-tracked food waste diversion mandates in South Korea guarantee anaerobic digestion facility utilization. |
| Regulatory Certification Investment | MEE leachate discharge compliance opens northern China retrofit market worth 15-25% of original construction costs. |
Research Methodology
Multi-period observation of anaerobic digestion capacity additions, MEE enforcement actions, and METI feed-in tariff revisions anchored the trend analysis, supplemented by interviews with municipal procurement officers in Jakarta and Surabaya, waste-to-energy project developers across China's Yangtze River Delta, equipment procurement leads at Beijing Enterprises Environment Group, and leachate treatment specialists in northern provinces. Secondary validation drew from MEE discharge standard filings, Indonesian national waste bank program documentation, Japanese METI tariff schedules, Indian CPCB extended producer responsibility circulars, and Vietnam's pending circular economy decree drafts. Bottom-up project pipeline tracking triangulated against top-down municipal budget allocation analysis.
Input-output matrices modeled waste tonnage flows across collection, recycling, disposal, and treatment service tiers, segmented by technology maturity, end-user contracting authority, and organic versus plastic versus hazardous waste streams. CAGRs derived from facility commissioning timelines, equipment procurement cycles, and concession renewal patterns across the projection horizon. Industry-specific forecast inputs incorporated moisture content profiles for Indonesian informal settlements and RFID-tracked food waste diversion compliance rates in South Korea.
Underlying measurement precision varies by segment; incineration and anaerobic digestion capacity data carry tighter precision than informal collection network estimates. Forecasts embed assumptions regarding MEE enforcement continuity, METI tariff stability, and Vietnamese decree implementation timelines. Material deviation in China's dual carbon goal provincial budget allocations, Indonesia's waste bank program scaling velocity, or Vietnam's licensing clarity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
Animal Waste Incinerator Market