
 India Municipal Solid Waste Management Market | 2026-2036
India Municipal Solid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
India Municipal Solid Waste Management Market Insights
Project finance through municipal bonds and hybrid annuity models is fragmenting competitive access across India's waste management landscape. Ramky Enviro Engineers Ltd leverages its integrated landfill and biomedical waste infrastructure to dominate long-term contracts in southern states. Antony Waste Handling Cell Ltd anchors its position through specialized transportation and processing operations across western India. A2Z Green Waste Management Ltd competes via technology partnerships in composting and waste-to-energy installations.
India municipal solid waste management encompasses the systematic collection, transportation, processing, and disposal of solid refuse generated by urban and semi-urban populations, with typical waste composition ranging from forty to sixty percent organic matter, fifteen to twenty-five percent recyclables, and ten to fifteen percent inert materials. The primary purpose is environmental protection through controlled decomposition, energy recovery, and material recycling to reduce landfill burden and public health hazards. Collection and transportation services capture the largest revenue share due to pervasive municipal outsourcing, while anaerobic digestion represents the fastest-expanding technology segment driven by biogas valorization and compressed biogas mandates. Processing services concentrate margin pools where waste-to-energy tariffs and carbon credit mechanisms apply.
The Central Pollution Control Board enforces emission standards for incineration and landfill leachate under Environment Protection Act provisions, while the Ministry of Housing and Urban Affairs channels Swachh Bharat Mission funding toward city-level infrastructure. BIS certification requirements for compost quality and plastic recycling outputs shape product marketability and processor compliance obligations. Stakeholders must monitor state-level solid waste management rule implementation and emerging extended producer responsibility enforcement to align capacity investments with regulatory trajectories.
Market Dynamics
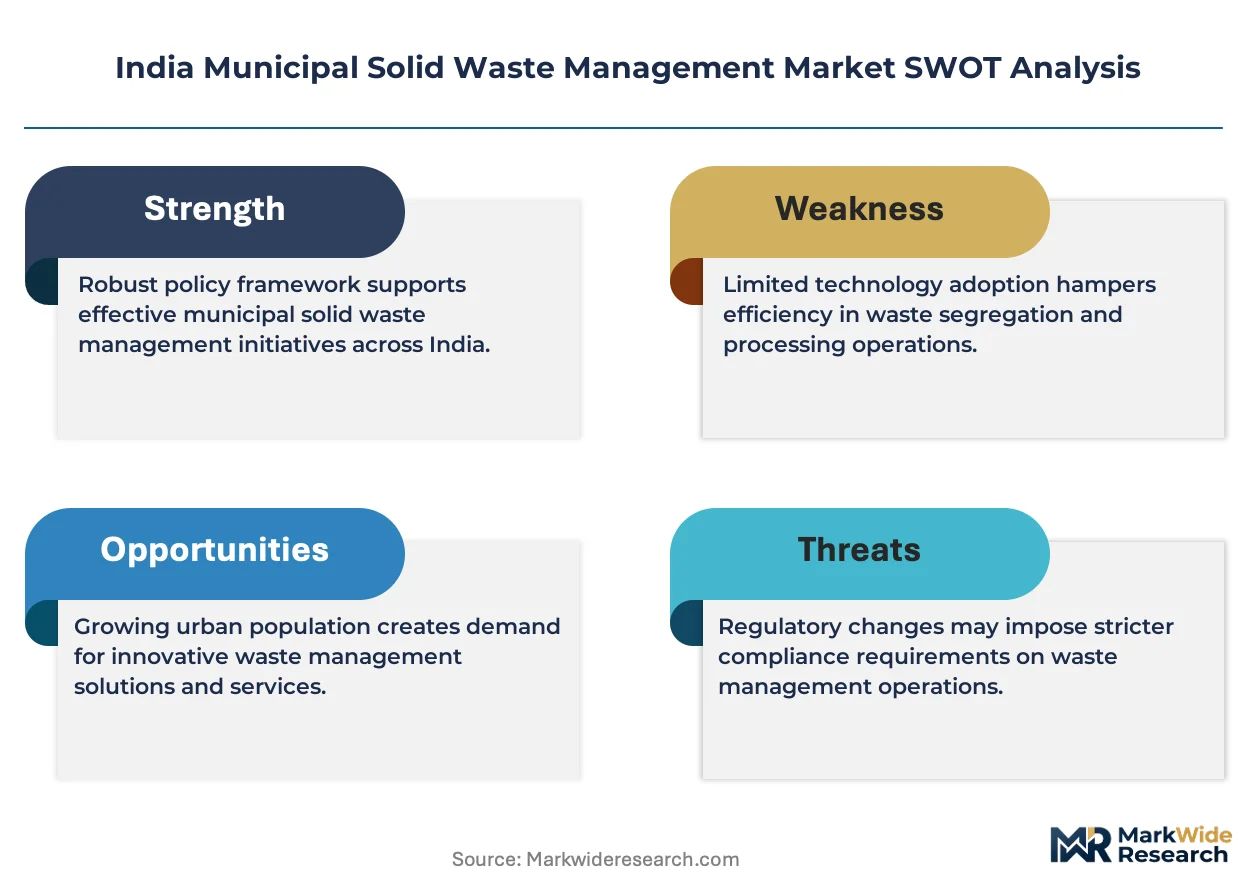
India's waste management sector is pivoting toward integrated processing infrastructure as the Central Pollution Control Board tightens landfill leachate and emission standards under Environment Protection Act provisions. Municipal corporations now prioritize anaerobic digestion and waste-to-energy installations over legacy dumping sites.
Growth Catalysts
- Swachh Bharat Mission Phase II:The Ministry of Housing and Urban Affairs channels capital toward 100% source segregation and scientific landfill remediation in Tier-1 and Tier-2 cities.
- Compressed Biogas Mandates:The Petroleum and Natural Gas Regulatory Board's blending requirements for CBG in city gas distribution networks pull organic waste toward anaerobic digestion facilities.
- Maharashtra Infrastructure Expansion:Urban local bodies in Mumbai, Pune, and Nagpur accelerate integrated waste processing complex tenders under state solid waste management rule compliance deadlines.
Market Restraints
- Land Acquisition Bottlenecks:Greenfield waste processing sites face 18-36 month clearance timelines as state pollution control boards enforce buffer zone requirements under siting guidelines.
- Feedstock Quality Volatility:Unsegregated municipal waste streams containing 40-60% moisture and high inert fractions degrade biogas yields and increase preprocessing capex.
- Interstate Transport Restrictions:Hazardous and plastic waste movement rules under the Plastic Waste Management Rules create compliance friction for multi-city operators.
Strategic Opportunities
- Extended Producer Responsibility Enforcement:The Central Pollution Control Board's tightening plastic waste EPR targets create contracted feedstock security for pyrolysis and co-processing facilities.
- Gujarat Industrial Corridor:Chemical and textile clusters in Vadodara, Surat, and Ahmedabad generate concentrated industrial waste streams suitable for captive waste-to-energy installations.
- Blockchain-Enabled Tracking:Integration of IoT weighbridge systems with distributed ledger verification is streamlining municipal payment reconciliation and tipping fee transparency.
Industry Challenges
- Waste Characterization Expertise Gap:Municipal engineers lack training in calorific value assessment and biomethane potential testing, delaying project commissioning.
- Legacy Dump Site Remediation:Bioremediation of 3,000+ legacy dumpsites requires specialized geotechnical and leachate treatment capabilities that few domestic contractors possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Municipal Solid Waste Management Market |
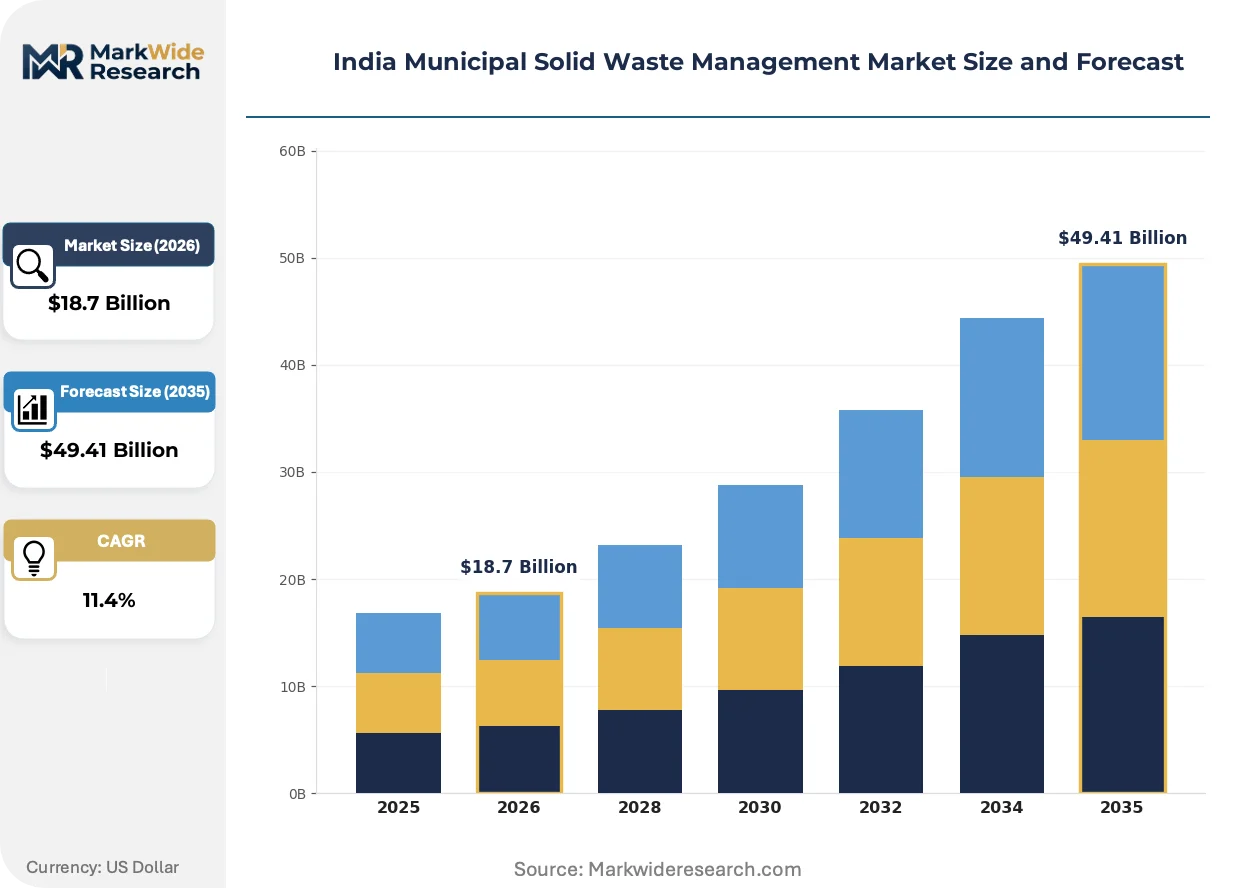
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Landfill, Composting, Incineration, Anaerobic Digestion Service Type: Collection, Transportation, Processing, Disposal Waste Type: Organic, Plastic, Metal, E-Waste End User: Municipalities, Private Sector, NGOs, Households |
| Companies Covered | Ramky Enviro Engineers Ltd, Antony Waste Handling Cell Ltd, A2Z Green Waste Management Ltd, Veolia Group, Eco Wise Waste Management Pvt Ltd, Jindal ITF Urban Infrastructure Ltd, BVG India Ltd, Attero Recycling Pvt Ltd, SUEZ India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Municipal Solid Waste Management Market Trends and Innovations
Technology convergence and regulatory stringency are compressing project development cycles across India's waste processing value chain. Operators now compete on feedstock security and offtake contracting rather than equipment supply alone.
Anaerobic digestion technology is migrating from simple biogas capture to integrated compressed biogas upgrading with grid injection capabilities. Municipal corporations in Tamil Nadu and Karnataka are mandating CBG output specifications in new tenders. This migration is compressing equipment supplier margins while elevating process engineering and O&M contract values.
The Plastic Waste Management Rules amendment tightening EPR targets and banning single-use plastics is forcing brand owners to establish dedicated recycling partnerships. FMCG and packaging companies now contract directly with pyrolysis and mechanical recycling operators. Western India states with established petrochemical infrastructure are capturing disproportionate recycling capacity investments.
Municipal procurement patterns are fragmenting as urban local bodies shift from single-vendor DBO contracts to segregated collection, transportation, and processing tenders. Smaller specialized operators are winning transportation and MRF management segments. This unbundling is most visible in Maharashtra and Gujarat where municipal corporations have operationalized independent tipping fee structures for each service tier.
India Municipal Solid Waste Management Market Segmentation
Segmentation reveals how capital allocation and contract structures vary across India's waste management value chain. Technology choices determine tariff structures and carbon credit eligibility. Service unbundling is fragmenting vendor relationships across collection, transportation, and processing tiers.
Technology:
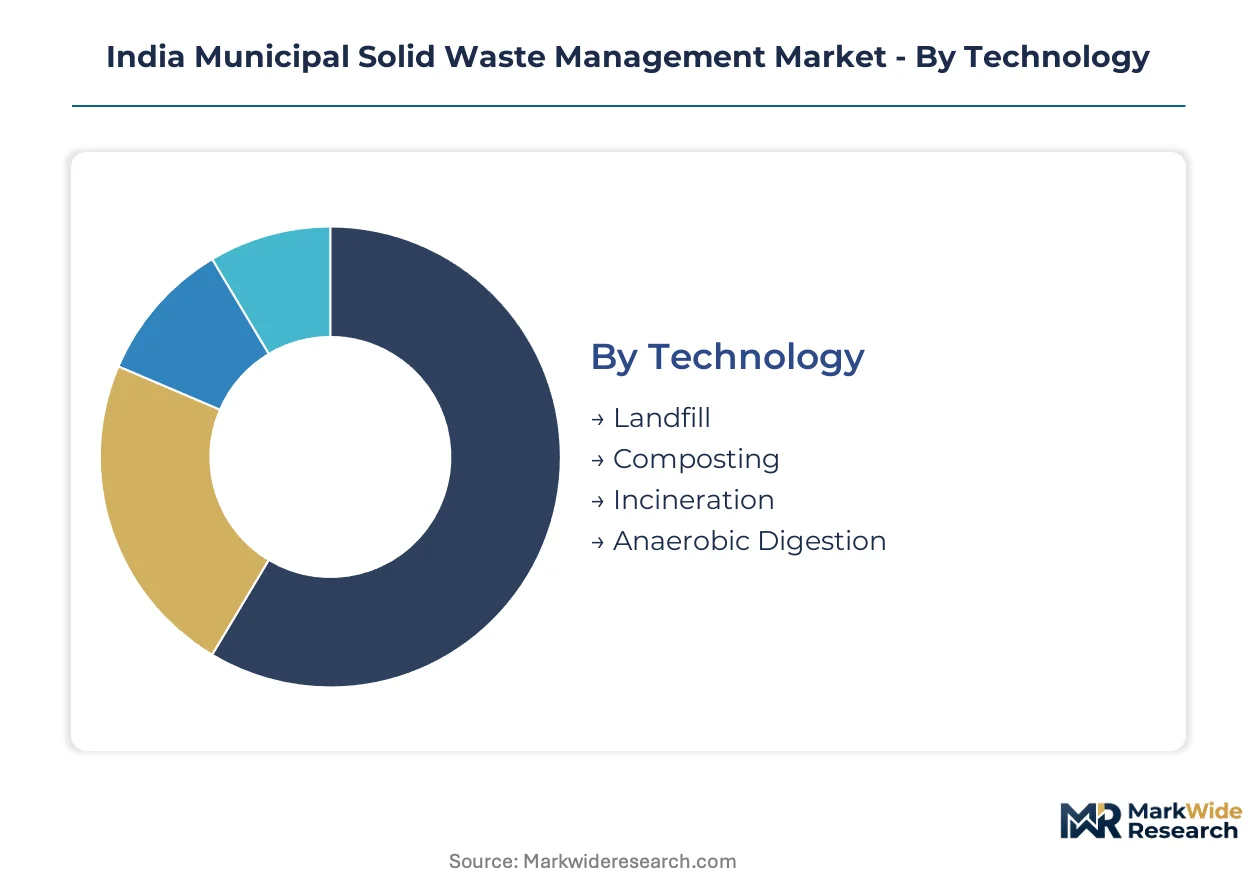
Technology segmentation tracks capital intensity, emission profiles, and energy recovery potential across processing alternatives.
- Anaerobic Digestion:Biological decomposition of organic fraction in oxygen-free environments yielding biogas upgradable to compressed biogas. Maharashtra and Gujarat municipalities mandate CBG output specifications in new tenders, pulling investment toward integrated upgrading infrastructure.
- Landfill:Engineered containment with leachate collection and gas recovery systems for residual waste streams. Tamil Nadu and Karnataka impose stricter siting buffer zones under state pollution control board guidelines, extending clearance timelines for greenfield sites.
- Composting:Aerobic decomposition producing soil amendments requiring BIS certification for agricultural marketability.
- Incineration:Thermal oxidation with energy recovery, subject to Central Pollution Control Board emission standards under Environment Protection Act provisions.
Landfill holds installed capacity. Anaerobic Digestion is rotating up the share rankings.
Service Type:
Service segmentation reflects municipal procurement unbundling and specialized operator entry across the value chain.
- Collection:Door-to-door segregated waste gathering using compacting vehicles and IoT-enabled weighbridge systems. Urban local bodies in Maharashtra and Gujarat now operate independent tipping fee structures for collection tiers, fragmenting single-vendor contracts.
- Processing:Material recovery, biological treatment, and thermal conversion operations capturing margin pools through waste-to-energy tariffs and carbon credit mechanisms. Tier-1 cities concentrate investment in integrated processing complexes under Swachh Bharat Mission Phase II directives.
- Transportation:Secondary transfer and long-haul logistics from collection points to processing or disposal facilities.
- Disposal:Final placement of residuals in sanitary landfills or engineered containment facilities.
Collection commands contract volume. Processing is climbing the fastest toward value concentration.
Waste Type:
Waste composition segmentation shapes preprocessing requirements, technology matching, and offtake contracting structures.
- Organic:Biodegradable fraction comprising 40-60% of typical municipal streams with high moisture content. Compressed biogas blending mandates from the Petroleum and Natural Gas Regulatory Board secure feedstock offtake for anaerobic digestion operators in city gas distribution networks.
- Plastic:Polymer waste streams governed by Extended Producer Responsibility targets under Plastic Waste Management Rules amendments. Brand owners in FMCG and packaging sectors now contract directly with pyrolysis and mechanical recycling operators.
- Metal:Ferrous and non-ferrous recyclables recovered through material recovery facilities.
- E-Waste:Discarded electrical and electronic equipment subject to separate handling regulations and specialized dismantling infrastructure.
Organic waste dominates feedstock tonnage. Plastic is gaining share fastest through EPR enforcement.
End User:
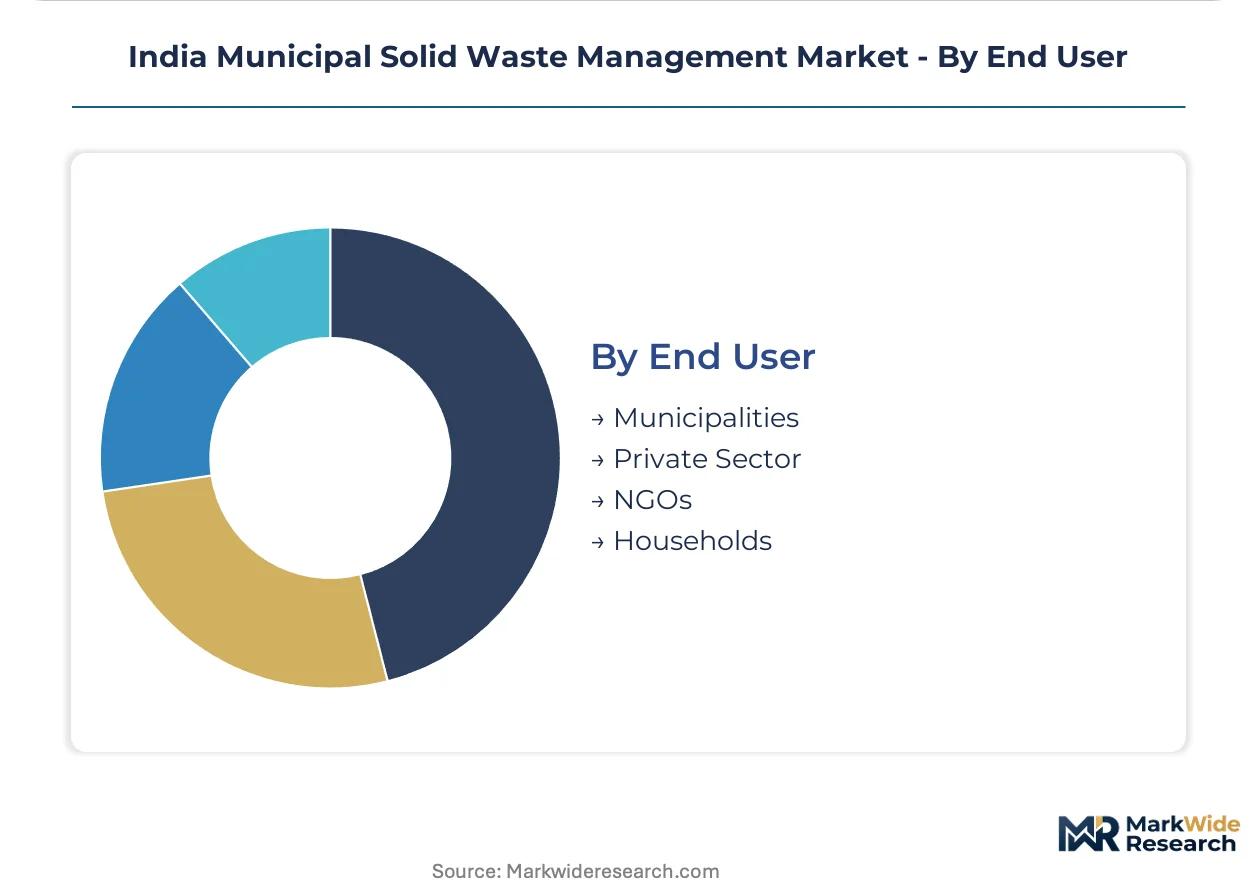
End user segmentation captures demand concentration across institutional purchasers and decentralized generators.
- Municipalities:Urban local bodies responsible for 100% scientific waste management under Swachh Bharat Mission compliance deadlines. Municipal corporations in Mumbai, Pune, Nagpur, Chennai, and Bangalore accelerate integrated complex tenders.
- Private Sector:Industrial clusters and commercial establishments generating captive waste streams. Chemical and textile clusters in Gujarat's Vadodara-Surat-Ahmedabad corridor deploy waste-to-energy installations for process heat and power.
- NGOs:Civil society organizations facilitating source segregation awareness and decentralized composting in residential colonies.
- Households:Individual generators subject to source segregation mandates and user fee structures.
Municipalities anchor contract value. Private Sector is expanding most quickly through industrial corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swachh Bharat Mission Phase II funding is accelerating municipal infrastructure tenders across India's urban centers. State pollution control boards are enforcing buffer zone requirements that reshape site selection timelines. Tier-1 and Tier-2 cities now dominate procurement volumes for integrated waste processing complexes.
Maharashtra
Mumbai, Pune, and Nagpur municipal corporations are floating integrated waste processing complex tenders under state solid waste management rule compliance deadlines. The Maharashtra Pollution Control Board mandates 500-meter buffer zones for greenfield landfill sites. The Mumbai Metropolitan Region concentrates anaerobic digestion capacity investments tied to compressed biogas offtake agreements with city gas distribution networks.
Gujarat
Chemical and textile clusters in Vadodara, Surat, and Ahmedabad generate concentrated industrial waste streams suitable for captive waste-to-energy installations. The Gujarat Pollution Control Board enforces emission standards for incineration facilities under Environment Protection Act provisions. The Vadodara-Surat-Ahmedabad corridor attracts disproportionate recycling capacity investments due to established petrochemical infrastructure.
Tamil Nadu
Chennai and Coimbatore urban local bodies are mandating CBG output specifications in new anaerobic digestion tenders. The Tamil Nadu Pollution Control Board imposes stricter siting buffer zones than national minimums, extending clearance timelines. The Chennai metropolitan area anchors southern India's largest landfill remediation contracts under Swachh Bharat Mission directives.
Karnataka
Bangalore municipal corporations are unbundling collection, transportation, and processing contracts into segregated tenders with independent tipping fee structures. The Karnataka State Pollution Control Board requires BIS certification for compost outputs entering agricultural supply chains. The Bangalore-Tumkur industrial belt hosts emerging pyrolysis facilities targeting plastic waste EPR compliance from FMCG brand owners.
Delhi-NCR
Legacy dump site remediation contracts for Bhalswa, Ghazipur, and Okhla landfills are attracting specialized geotechnical contractors with leachate treatment capabilities. The Delhi Pollution Control Committee enforces stricter emission norms for waste-to-energy plants than neighboring states. The National Capital Region's industrial corridors in Faridabad and Ghaziabad are deploying captive biogas upgrading facilities for grid injection.
India Municipal Solid Waste Management Market Competitive Landscape
On the supply side, the industry is consolidating around integrated operators with landfill remediation and biomedical waste capabilities. Municipal outsourcing patterns favor vendors offering design-build-operate contracts spanning collection through final disposal. Three strategic archetypes dominate: integrated infrastructure conglomerates, specialized transportation and logistics providers, and technology-focused processing specialists. Competitive positioning hinges on securing long-term municipal concessions and securing feedstock offtake agreements under extended producer responsibility frameworks.
Among India-based integrated operators, Ramky Enviro Engineers Ltd and Antony Waste Handling Cell Ltd exemplify contrasting geographic anchoring strategies, with the former concentrating long-term concessions in southern states and the latter dominating western India through specialized transportation networks. A2Z Green Waste Management Ltd occupies a position within the technology-focused tier, competing via partnerships in composting and waste-to-energy installations. These three operators represent the dominant competitive archetypes shaping contract award patterns across state-level municipal procurement.
| Leading Market Players |
|---|
| Ramky Enviro Engineers Ltd |
| Antony Waste Handling Cell Ltd |
| A2Z Green Waste Management Ltd |
| Veolia Group |
| Eco Wise Waste Management Pvt Ltd |
| Jindal ITF Urban Infrastructure Ltd |
| BVG India Ltd |
| Attero Recycling Pvt Ltd |
| SUEZ India |
| Others |
Pricing and Supply Chain Analysis
The Delhi-Mumbai Industrial Corridor freight lanes concentrate equipment logistics costs for anaerobic digestion reactors and leachate treatment systems, compressing margins for distant bidders while amplifying price premiums for operators with Gujarat-Maharashtra captive fabrication. This corridor cost dynamic feeds into municipal tender pricing, where proximity to fabrication clusters determines competitive positioning on design-build-operate contracts.
Pricing Analysis
Collection service tiers create the primary spread between metro municipalities and Tier-2 urban local bodies, with tipping fees diverging based on route density and vehicle utilization rates. Project-based DBO contracts dominate processing infrastructure, while per-ton transportation fees apply to collection and haulage segments. Price compression runs through collection services as municipal corporations unbundle contracts and fragment vendor relationships. Small urban local bodies in Karnataka and Tamil Nadu exhibit highest price sensitivity due to constrained Swachh Bharat Mission allocations, whereas Mumbai and Delhi municipal corporations prioritize technology compliance over unit cost.
Supply Chain Analysis
Domestic fabrication capacity concentrates in Gujarat, Maharashtra, and Tamil Nadu engineering clusters, with Vadodara-Surat-Ahmedabad corridor housing specialized biogas upgrading equipment manufacturers. Stainless steel reactor vessels, membrane gas upgrading modules, and IoT weighbridge systems constitute critical input dependencies. Single-source vulnerability persists for advanced membrane technology imports feeding compressed biogas purification trains. Distribution runs through municipal corporation tender portals and state urban development authority frameworks, with limited direct procurement by private industrial generators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's municipal solid waste management market structures around long-term service-attach economics, where operations and maintenance contracts extending 15-25 years generate recurring revenue streams that outpace upfront EPC margins. This service-attach dynamic favors operators with demonstrated landfill remediation and leachate treatment capabilities.
For Market Incumbents: Harden feedstock security through exclusive collection concessions in Tier-2 cities before municipal unbundling accelerates. Deepen anaerobic digestion upgrading capabilities to capture compressed biogas offtake premiums under Petroleum and Natural Gas Regulatory Board blending mandates. Vertical integration into leachate treatment chemicals and spare parts inventory buffers margin compression from equipment commoditization.
For New Entrants and Emerging Players: Northeastern state municipalities present underpenetrated procurement landscapes with limited incumbent presence and relaxed buffer zone requirements compared to southern and western states. Target Assam and Tripura urban local bodies with bundled collection-processing proposals before Swachh Bharat Mission Phase II compliance deadlines tighten. Pursue technology licensing partnerships with established European anaerobic digestion engineering firms to differentiate on process guarantees.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified infrastructure conglomerates with non-core waste management subsidiaries lacking integrated processing capabilities. The 5-10 year viability window favors operators with demonstrated landfill remediation expertise and existing municipal relationships over pure-play technology licensors. Monitor state pollution control board enforcement actions on legacy dump site closures as inflection indicator for remediation contract acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Waste Processing Complex Development | Maharashtra and Gujarat municipalities prioritize single-vendor DBO contracts spanning collection through energy recovery. |
| Compressed Biogas Upgrading Infrastructure | Petroleum and Natural Gas Regulatory Board blending mandates secure long-term offtake for anaerobic digestion operators. |
| Legacy Landfill Remediation Capability Buildout | Central Pollution Control Board enforcement on 3,000-plus dump sites creates specialized contractor demand in Delhi-NCR. |
| Extended Producer Responsibility Partnership Structuring | Plastic Waste Management Rules amendments force FMCG brand owners into direct pyrolysis and mechanical recycling contracts. |
| Blockchain-Enabled Tipping Fee Transparency Systems | IoT weighbridge integration with distributed ledger verification streamlines municipal payment reconciliation and audit compliance. |
Research Methodology
A spread of perspectives from municipal corporation engineers, state pollution control board enforcement officers, anaerobic digestion technology suppliers, and Swachh Bharat Mission program administrators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against Central Pollution Control Board compliance filings, Ministry of Housing and Urban Affairs tender databases, and state urban development authority procurement records. Bottom-up project pipeline aggregation triangulated against top-down municipal budget allocation analysis.
Demand-supply balance modeling anchored the projection framework, with waste generation coefficients applied across urban population clusters and processing capacity buildout tracked through announced tender awards. Segmentation dimensions modeled include technology type, service tier unbundling, waste composition fraction, and end-user procurement authority. CAGRs derived from capacity commissioning timelines and municipal expenditure growth trajectories. Industry-specific inputs incorporated compressed biogas offtake agreement structures and extended producer responsibility enforcement phase-ins.
Practitioners should monitor state-level solid waste management rule amendments and pollution control board buffer zone enforcement for early signals of project timeline compression or extension. Forecasts reflect assumptions on municipal bond market liquidity and Swachh Bharat Mission central allocation continuity. Quarterly review of tender award patterns and legacy dump site remediation contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Europe Medical Waste Management Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Vacuum Waste Systems Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market