
 North America Green Cement Market | 2026-2036
North America Green Cement Market Size, Share, and Industry Trends Forecast 2026-2036
North America Green Cement Market Insights
Modular specification packages is decoupling green cement procurement from traditional bulk supply agreements, letting buyers configure blends by project carbon target rather than accepting standardized formulations. Holcim leverages its North American plant network to pre-certify low-carbon mixes for LEED-heavy bids. CEMEX anchors its position through integrated quarry-to-distribution control across the Sun Belt. CarbonCure Technologies Inc. differentiates by licensing CO2 injection systems that retrofit existing kilns without full plant replacement.
North America green cement denotes hydraulic binders manufactured with clinker substitution rates exceeding 35 percent through supplementary cementitious materials such as fly ash, slag, or calcined clay, achieving compressive strength ratings comparable to Portland Type I while reducing process emissions by 30 to 70 percent depending on feedstock blend. Its primary commercial purpose is enabling structural concrete placement in jurisdictions with embodied carbon limits or green building mandates. Slag cement currently occupies the largest production share due to established blast furnace supply chains around the Great Lakes, though geopolymer cement represents the fastest-growing category as alkali-activation chemistry matures for precast applications. Infrastructure procurement by state departments of transportation sustains premium pricing for fly ash blends in bridge deck and pavement specifications where freeze-thaw durability governs material selection.
EPA emissions reporting requirements under the Greenhouse Gas Reporting Program force producers above 25,000 metric tons CO2e annually to disclose kiln-level data, tightening competitive pressure on high-clinker operations. California's Buy Clean California Act and the Inflation Reduction Act's domestic content bonuses for federal construction jointly reshape demand toward EPD-verified low-carbon products. The Federal Highway Administration's ongoing specification reviews for performance-based binders will determine whether green cement variants gain automatic equivalency in federally funded road contracts. Stakeholders must monitor whether emerging state-level embodied carbon thresholds for commercial buildings trigger specification cascades that outpace current production capacity for certified low-carbon blends.
Market Dynamics
Federal infrastructure spending under the Infrastructure Investment and Jobs Act is compressing procurement cycles for state transportation departments, forcing rapid qualification of low-carbon binders for highway and bridge specifications across the Texas-California corridor.
Growth Catalysts
- Buy Clean California Act:California's embodied carbon disclosure mandate for public projects is pulling fly ash and slag blends into state-funded construction, creating template specifications that Oregon and Washington are adopting.
- Carbon capture retrofits:CO2 mineralization systems for existing kilns are dropping capital barriers for mid-size producers seeking EPA emissions compliance without full plant replacement.
- Great Lakes slag supply:Established blast furnace infrastructure around Lake Michigan and Lake Erie anchors domestic SCM production, insulating regional supply from import volatility.
Market Restraints
- Fly ash availability constraints:Coal plant retirements across the Ohio River Valley are tightening feedstock supply for high-volume SCM blends, forcing reliance on imported slag.
- Clinker substitution ceilings:ASTM C1157 performance specifications cap replacement rates at 50% for structural load-bearing applications, limiting emission reductions in high-rise construction.
- EPA reporting thresholds:Facilities above 25,000 metric tons CO2e annually face disclosure burdens that favor large integrated producers over independent blenders.
Strategic Opportunities
- Geopolymer precast:Alkali-activated binders for manufactured wall panels and structural elements open specification pathways outside ASTM Portland-centric frameworks.
- Inland Empire distribution hubs:Rail-served terminals in Southern California's warehouse corridor can bypass congested Los Angeles-Long Beach port access for Mexican and Asian SCM imports.
- Federal domestic content bonuses:Inflation Reduction Act provisions for domestic construction materials are pulling EPD-verified low-carbon products into General Services Administration and Department of Defense procurement.
Industry Challenges
- EPD certification bottlenecks:Third-party verification timelines for environmental product declarations stretch 8-14 months, misaligning with compressed federal bid schedules.
- Batch consistency at scale:Variable SCM chemistry from disparate blast furnace and coal ash sources requires real-time quality control systems that smaller blenders lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Green Cement Market |
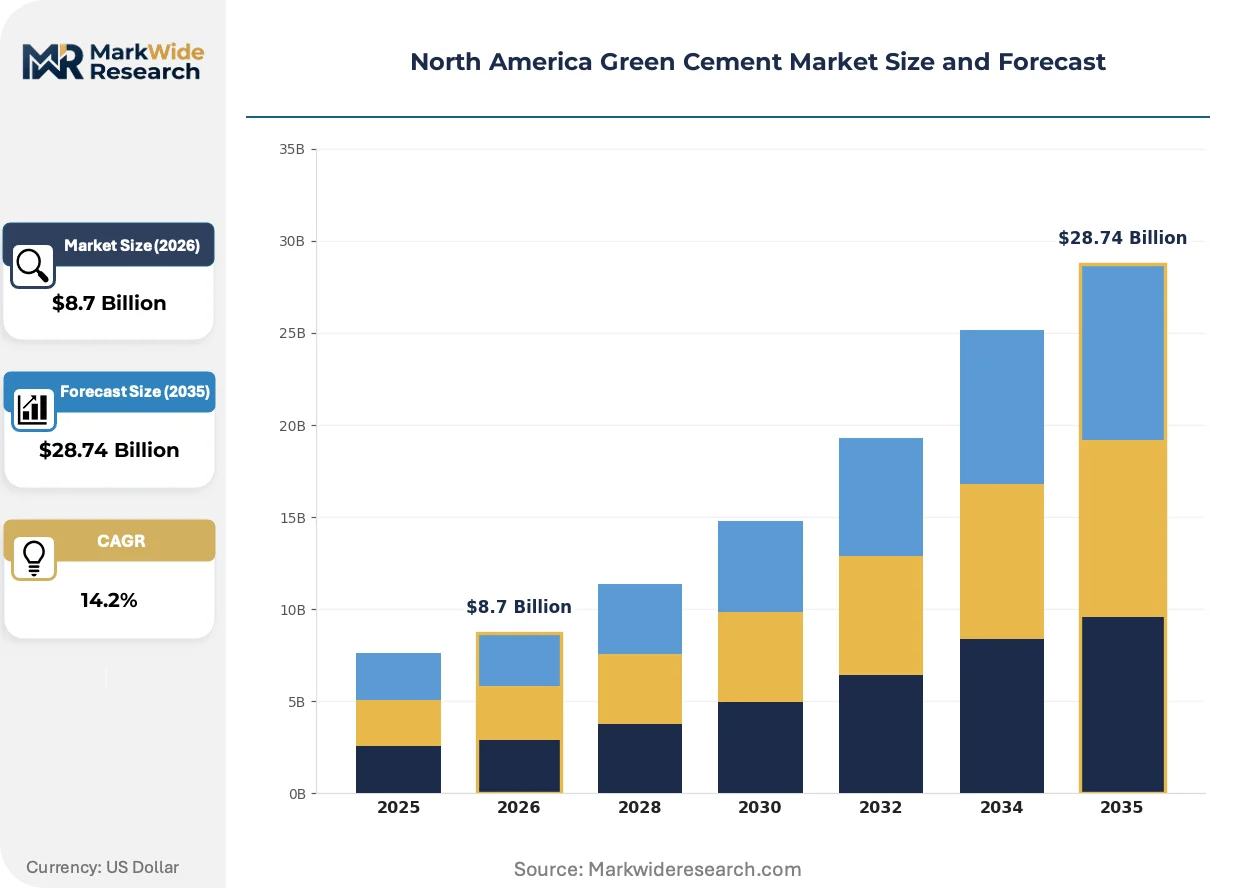
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash Cement, Geopolymer Cement, Slag Cement, Calcium Sulfoaluminate Cement Application: Residential Construction, Commercial Construction, Infrastructure, Roadways End User: Contractors, Builders, Government Agencies, Architects Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Stores |
| Companies Covered | Holcim, CEMEX, Eco Material Technologies, Hoffmann Green Cement Technologies, Fortera Corporation, CarbonCure Technologies Inc., Calera Corporation, CRH plc, LafargeHolcim, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Green Cement Market Trends and Innovations
Modular blending technology and performance-based specifications are fragmenting the traditional bulk supply model, letting project engineers configure cement chemistry by embodied carbon target rather than accepting standardized formulations.
Calcined clay activation is decentralizing clinker production economics by enabling mid-size kiln operators to achieve 40-50% CO2 reduction without carbon capture infrastructure. Texas and California precast manufacturers are piloting LC3 blends for non-structural elements, compressing the premium gap between conventional and green cement to under 15% in high-volume applications.
The Federal Highway Administration's pending performance-based binder equivalency review is forcing state DOTs to rewrite rigid prescriptive specifications that have locked out SCM blends since the 1990s. Illinois and Michigan transportation departments are advancing pilot programs allowing alkali-silica reaction-resistant slag mixes in bridge decks, creating regulatory templates for neighboring states.
Project-level carbon accounting is unbundling cement procurement from ready-mix concrete contracts, letting general contractors source binders directly and back-charge EPD premiums to owners seeking LEED or Living Building Challenge certification. This disintermediation concentrates in California commercial high-rise and Pacific Northwest institutional construction, where municipal green building mandates override traditional subcontractor relationships.
North America Green Cement Market Segmentation
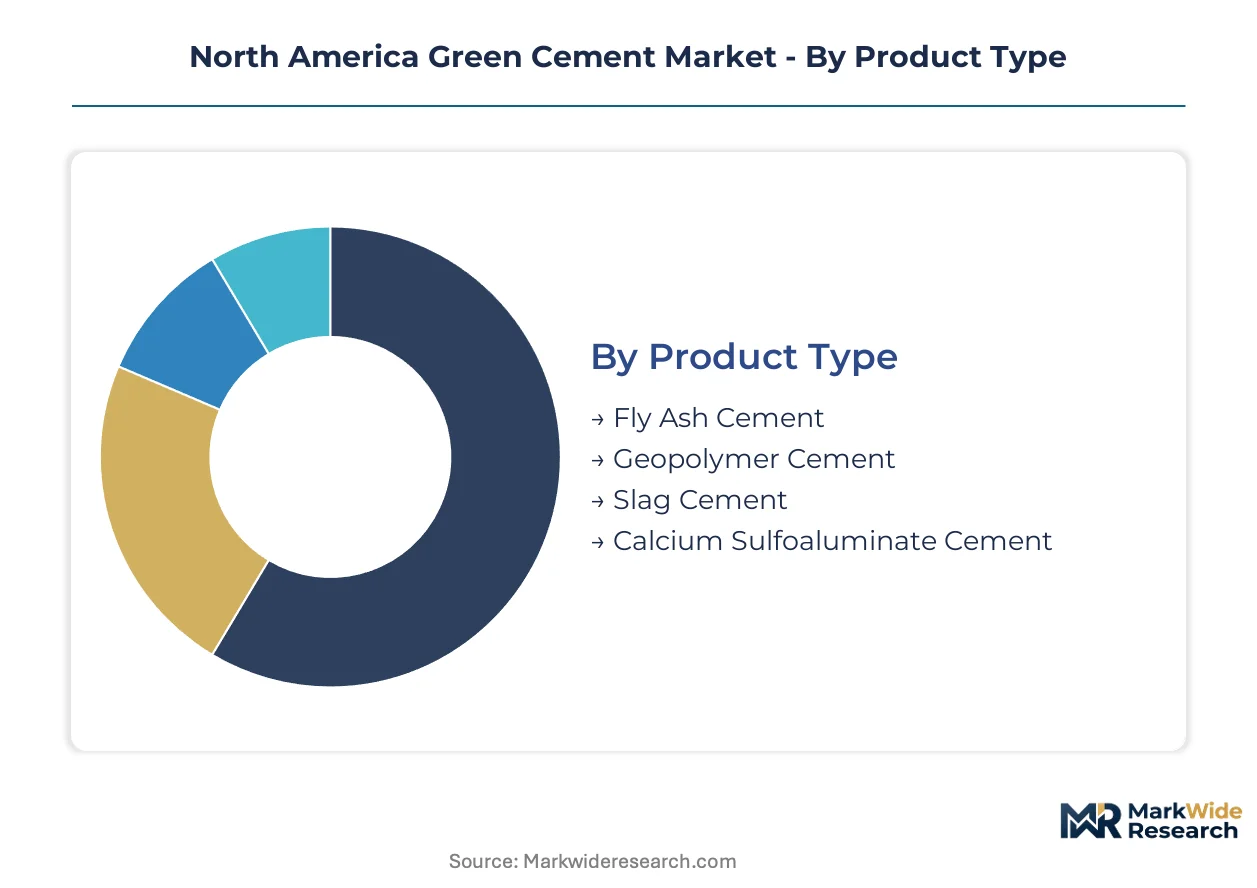
Green cement procurement fragments across four structural dimensions. Product chemistry determines emission reduction potential while application type governs specification rigor and end-user sophistication shapes channel selection.
Product Type:
Integration depth varies sharply — some variants drop into existing ready-mix workflows while others demand dedicated batching infrastructure and contractor retraining.
- Slag Cement:Granulated blast furnace slag blended at 25-70% replacement rates delivers sulfate resistance and lower heat of hydration. Demand concentrates in Great Lakes bridge decks and marine piles where freeze-thaw durability governs. Established Lake Michigan and Lake Erie supply chains insulate pricing from import volatility.
- Fly Ash Cement:Coal combustion residual processed to ASTM C618 standards enables 15-40% clinker substitution with improved workability. Texas-California highway specifications sustain volume, though Ohio River Valley coal plant retirements tighten feedstock availability.
- Geopolymer Cement:Alkali-activated aluminosilicate binders bypass Portland chemistry entirely for 70-80% emission reductions. Precast wall panel manufacturers pilot formulations outside ASTM C1157 constraints.
- Calcium Sulfoaluminate Cement:Low-temperature clinkering achieves rapid strength gain with 25-30% lower kiln emissions. Niche applications in airport runway repairs and cold-weather construction.
Volume placements concentrate in Slag Cement; the faster expansion belongs to Geopolymer Cement.
Application:
Specification stringency escalates from private residential to federally funded infrastructure, with embodied carbon thresholds most aggressive in commercial high-rise and institutional segments.
- Infrastructure:Federal Highway Administration performance-based binder reviews are unlocking slag and fly ash blends in bridge decks and pavement. State DOT procurement cycles compress under Infrastructure Investment and Jobs Act spending deadlines.
- Commercial Construction:LEED and Living Building Challenge mandates drive EPD-verified low-carbon procurement. California Buy Clean Act thresholds force general contractors to unbundle binder sourcing from ready-mix contracts.
- Roadways:Prescriptive state specifications historically excluded SCM blends; Illinois and Michigan pilot programs now permit alkali-silica reaction-resistant slag mixes.
- Residential Construction:Cost sensitivity and builder familiarity with Portland Type I limit penetration; modular home manufacturers represent the exception where factory-controlled batching enables consistent SCM dosing.
Specification reform is accelerating fastest in Infrastructure; Commercial Construction carries the premium pricing power.
End User:
Technical sophistication and procurement scale separate direct specification authority from delegated purchasing through intermediaries.
- Government Agencies:Federal GSA and state DOT procurement wield EPD requirements and domestic content bonuses under Inflation Reduction Act provisions. Disclosure mandates above 25,000 metric tons CO2e reshape supplier qualification.
- Architects:Early design-phase material selection increasingly governs embodied carbon outcomes; California firms specify LC3 blends for municipal clients facing Buy Clean thresholds.
- Contractors:Large infrastructure and commercial general contractors bypass ready-mix intermediaries to source certified binders directly, back-charging EPD premiums to project owners.
- Builders:Production homebuilders lag in specification authority, typically accepting ready-mix supplier recommendations unless municipal green building codes intervene.
Procurement authority clusters with Government Agencies; Architects are gaining influence fastest through early-stage carbon modeling.
Distribution Channel:
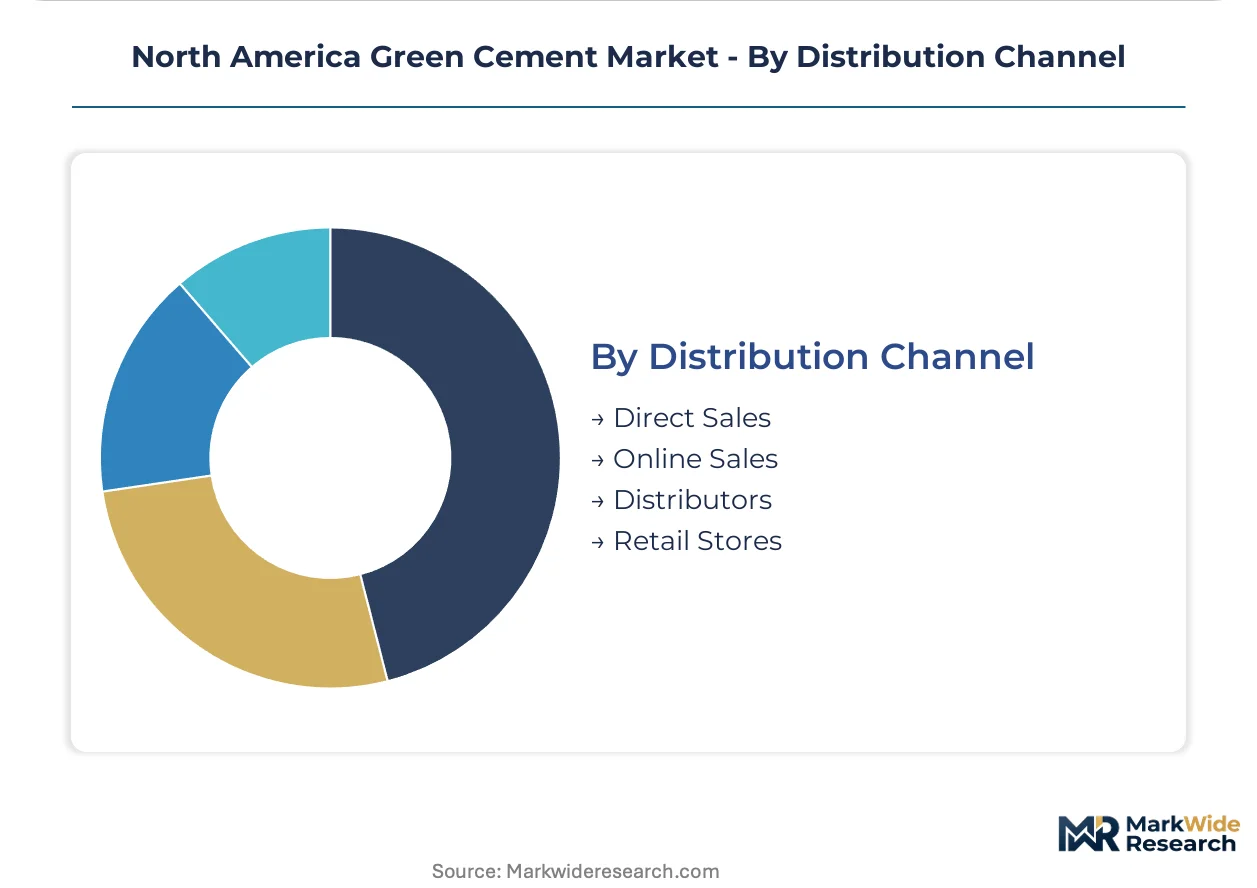
Channel selection tracks shipment scale, specification complexity, and geographic proximity to production or import terminals.
- Direct Sales:Large infrastructure and commercial projects source multi-thousand-ton volumes straight from Holcim and CEMEX grinding facilities, securing lot-consistent EPD documentation.
- Distributors:Regional terminals in Southern California's Inland Empire rail corridor aggregate Mexican and Asian SCM imports for mid-size contractors.
- Online Sales:Emerging platforms connect precast manufacturers with specialty geopolymer suppliers for pilot-scale trials outside traditional bulk agreements.
- Retail Stores:Limited to bagged repair mortars and small-volume specialty blends; negligible share in structural concrete procurement.
Shipment scale favors Direct Sales; Distributors are capturing the import-dependent growth corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the Great Lakes blast furnace corridor while consumption pulls toward the Texas-California infrastructure belt. This geographic split shapes supply chain economics and regulatory arbitrage across the continent.
United States
Federal infrastructure spending under the Infrastructure Investment and Jobs Act compresses state DOT procurement cycles for low-carbon binders. EPA Greenhouse Gas Reporting Program thresholds above 25,000 metric tons CO2e force kiln-level disclosure from major producers. The Texas-California corridor dominates demand, with precast manufacturers in the Inland Empire piloting calcined clay blends for commercial high-rise projects.
Canada
Provincial green building mandates in British Columbia and Ontario drive EPD-verified procurement for institutional construction. The country's national environmental regulator enforces emissions disclosure from cement facilities above threshold scales. Quebec and Ontario slag grinding operations leverage Great Lakes waterway access to serve cross-border infrastructure contracts.
Mexico
Rail-served terminals in Nuevo León and the Bajío Region aggregate calcined clay imports for Central Mexican precast production. The federal infrastructure ministry advances performance-based concrete specifications for highway rehabilitation. Monterrey-based distributors bypass congested Los Angeles-Long Beach port access to supply Southwestern U.S. contractors.
California
The Buy Clean California Act mandates embodied carbon disclosure for state-funded construction, pulling fly ash and slag blends into public procurement. Caltrans specification reform permits alkali-silica reaction-resistant SCM mixes in bridge decks. Los Angeles commercial developers unbundle binder sourcing from ready-mix contracts to secure LEED certification credits.
Texas
State transportation department pilot programs unlock slag and fly ash blends in pavement specifications previously restricted to Portland cement. Federal domestic content bonuses under Inflation Reduction Act provisions pull EPD-verified products into General Services Administration construction. Houston-Galveston petrochemical corridor infrastructure sustains demand for sulfate-resistant blends in marine applications.
North America Green Cement Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists for specification authority in green cement procurement. The market structure shows moderate consolidation around integrated producers with captive clinker capacity and grinding assets. Three archetypes dominate: multinational building materials conglomerates with North American plant networks, technology licensors offering CO2 mineralization systems for retrofit deployment, and independent blenders sourcing supplementary cementitious materials from third-party feedstock suppliers. Competitive moves center on EPD certification pre-qualification for federal bidding and rail terminal access for import-dependent SCM distribution.
Within the multinational conglomerate tier, Holcim and CEMEX anchor competitive positioning through integrated quarry-to-distribution control. Among technology specialists, CarbonCure Technologies Inc. exemplifies the licensing model for CO2 injection systems. These three companies represent distinct strategic postures: scale-driven vertical integration, performance-based specification capture, and capital-light technology deployment.
| Leading Market Players |
|---|
| Holcim |
| CEMEX |
| Eco Material Technologies |
| Hoffmann Green Cement Technologies |
| Fortera Corporation |
| CarbonCure Technologies Inc. |
| Calera Corporation |
| CRH plc |
| LafargeHolcim |
| Others |
Pricing and Supply Chain Analysis
Federal infrastructure procurement timelines under the Infrastructure Investment and Jobs Act are compressing qualification windows for low-carbon binders, forcing supply chains to absorb expedited EPD certification costs and pass through premiums to contractors facing liquidated damages clauses.
Pricing Analysis
Margin tightening in high-volume infrastructure blends reflects coal plant retirements across the Ohio River Valley and escalating imported slag substitution costs. Three-tier pricing structure across EPD-verified premium, state-specification standard, and uncertified economy levels tracks certification grade and volume scale. Pricing pressure stems from fly ash feedstock scarcity as utilities accelerate coal generation phaseouts. Residential builders exhibit highest price sensitivity; federal contractors absorbing domestic content bonuses show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Great Lakes blast furnace slag supply concentrated around Lake Michigan and Lake Erie. Raw material dependencies center on granulated blast furnace slag, Class F fly ash, and calcined clay imports from Mexico and Southeast Asia. Tariff exposure on Asian SCM shipments through Los Angeles-Long Beach port congestion poses structural risk. Distribution runs through rail-served Inland Empire terminals aggregating Mexican imports for Southwestern contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcined clay activation technology is displacing carbon capture as the dominant pathway for mid-size producers seeking 40-50% emission reductions without full plant reconstruction.
For Market Incumbents: To counter independent blenders capturing federal EPD-verified procurement, Holcim and CEMEX should deepen backward integration into captive calcined clay supply through quarry-to-distribution control across the Sun Belt. Priority investment targets real-time quality control systems ensuring batch consistency at multi-thousand-ton infrastructure scale. For New Entrants and Emerging Players: Technology-first licensing of CO2 mineralization systems offers capital-light retrofit pathways for mid-size kiln operators lacking carbon capture infrastructure. White-space concentrates in geopolymer precast for manufactured wall panels outside ASTM C1157 constraints, with go-to-market through direct online platforms connecting specialty suppliers with pilot-scale manufacturers. For Investors and Strategic Acquirers: The window for entry favors technology licensors with proven CO2 injection retrofit deployments over capital-intensive integrated producers. Long-term viability hinges on regulatory persistence of embodied carbon thresholds in commercial building codes. Acquisition targets should demonstrate rail terminal access for import-dependent SCM distribution and pre-qualified EPD documentation for federal bidding. The signal to watch is Federal Highway Administration performance-based binder equivalency determinations unlocking automatic SCM substitution in federally funded road contracts.| Strategic Initiative | Industry Significance |
|---|---|
| EPD Certification Pre-Qualification | Accelerates federal procurement eligibility under Inflation Reduction Act domestic content bonuses. |
| Calcined Clay Supply Integration | Secures feedstock independence from volatile Great Lakes slag and declining fly ash availability. |
| Rail Terminal Network Expansion | Bypasses Los Angeles-Long Beach congestion for Mexican and Asian SCM import aggregation. |
| Geopolymer Pilot Manufacturing | Opens specification pathways outside ASTM Portland-centric frameworks for precast applications. |
| Real-Time Quality Control Deployment | Resolves batch consistency challenges from variable SCM chemistry at commercial scale. |
Research Methodology
Trade databases, EPA Greenhouse Gas Reporting Program filings, and state transportation department procurement records formed the secondary backbone, cross-referenced with primary interviews spanning cement plant operations directors, ready-mix procurement managers, Caltrans specification engineers, and federal GSA construction contracting officers. Bottom-up volume estimates triangulated against top-down infrastructure spending allocations.
Historical trendline analysis tracked clinker substitution rates, EPD certification velocity, and SCM import volumes across the projection horizon. Segmentation modeling captured product chemistry tiers, application specification stringency, end-user procurement authority, and distribution channel shipment scale. CAGRs derived from regression against federal infrastructure appropriations trajectories and state-level embodied carbon threshold adoption curves.
Several conditions sit outside the modeled scope, including potential ASTM C1157 revision expanding structural load-bearing substitution ceilings, unannounced coal plant retirement accelerations, and trade policy shifts affecting Mexican calcined clay tariff treatment. Forecasts reflect documented assumptions about regulatory persistence and technology cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Green Coatings Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
United States Green Cement Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Cement Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Global Green Walls Market