
 APAC Bio-Medical Waste Management Market | 2026-2036
APAC Bio-Medical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Bio-Medical Waste Management Market Insights
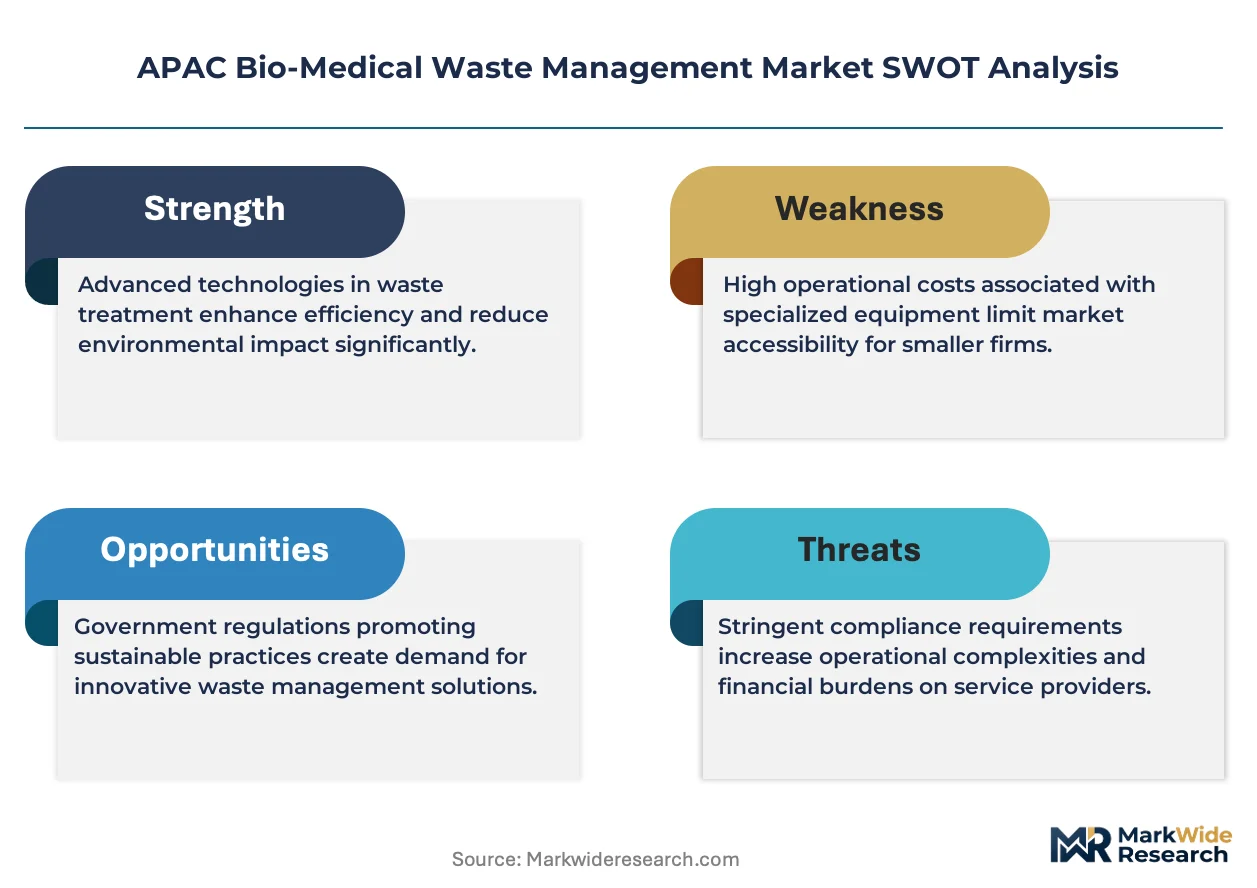
Buyer concentration among hospital networks is expanding across Southeast Asia as multi-facility operators consolidate procurement under single-vendor contracts. Veolia Environnement SA leverages its regional incineration footprint to anchor long-term service agreements with these expanding chains. Suez competes through integrated collection-to-disposal platforms that reduce logistics friction for clustered medical facilities.
Bio-medical waste management encompasses the controlled handling, treatment, and final disposition of waste generated during diagnosis, treatment, or immunization of humans and animals, including materials contaminated with blood, pathogens, or cytotoxic agents that require thermal or chemical neutralization before landfill release. Autoclaving dominates volume processing for infectious waste across the region due to lower capital requirements and regulatory acceptance, while plasma gasification attracts investment for its ability to eliminate residual toxicity and recover energy from hazardous fractions. The waste type dimension shows sharps and infectious categories commanding premium pricing because of specialized handling protocols and liability exposure.
India's Central Pollution Control Board enforces Bio-Medical Waste Management Rules that mandate color-coded segregation and licensed treatment facility registration, while China's Ministry of Ecology and Environment applies GB standards that restrict landfill acceptance of untreated medical residues. These frameworks elevate compliance costs for smaller clinics and accelerate outsourcing to certified operators. Stakeholders must monitor enforcement intensity and treatment capacity gaps as urban healthcare density outpaces permitted disposal infrastructure.
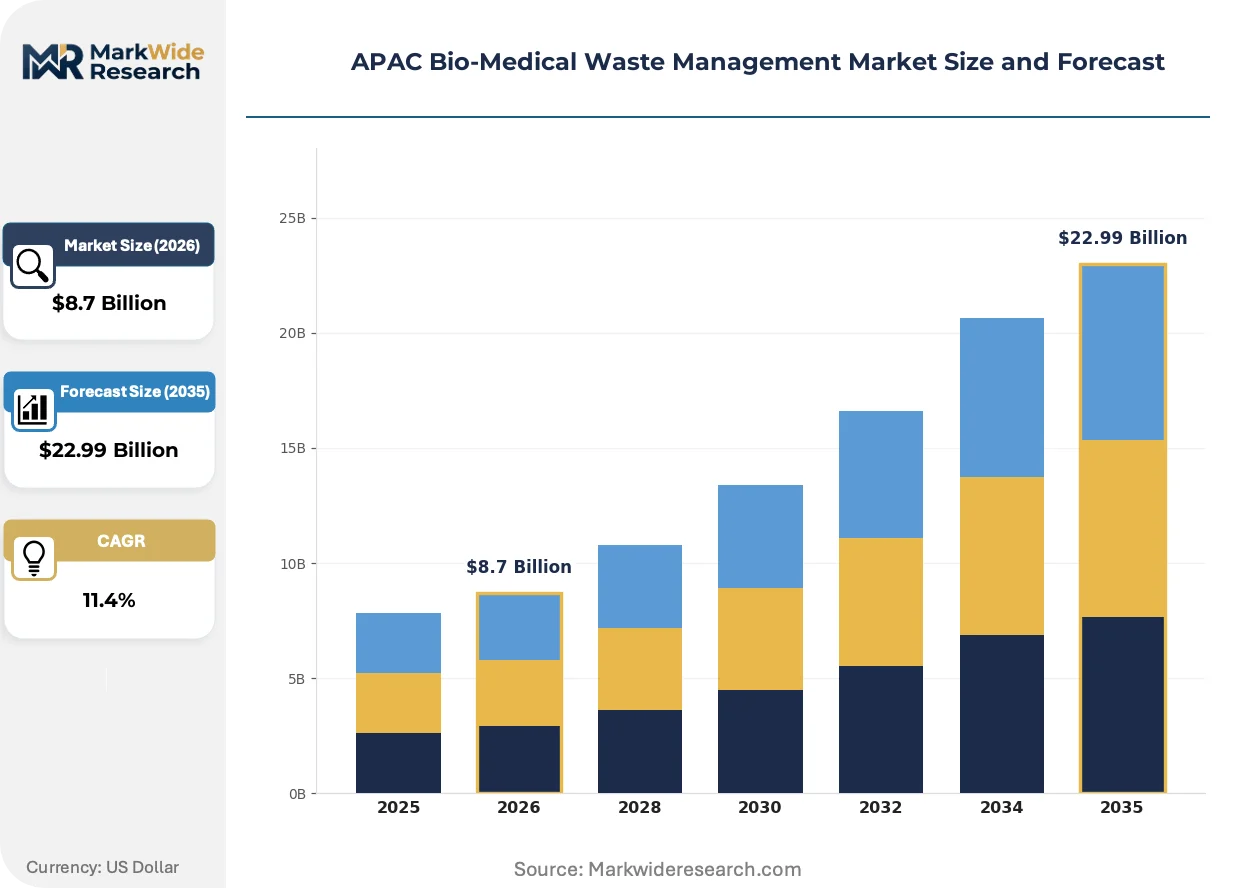
Market Dynamics
Hospital network consolidation across Southeast Asia is compressing vendor relationships into multi-year, multi-facility contracts that favor operators with integrated collection-to-treatment capabilities over fragmented local providers.
Growth Catalysts
- India's Bio-Medical Waste Management Rules:Mandatory color-coded segregation and licensed facility registration are pushing small clinics toward outsourced certified operators.
- Plasma gasification technology:Energy recovery from hazardous fractions is attracting capital investment as landfill restrictions tighten across urban China.
- China's GB standards:Prohibitions on untreated medical residue disposal are accelerating demand for on-site pre-treatment systems in tertiary hospitals.
Market Restraints
- Autoclave energy costs:Steam sterilization's dependence on natural gas and electricity creates margin pressure when utility tariffs spike.
- Permitted incineration capacity:Treatment facility licensing bottlenecks in Indian metropolitan clusters create disposal backlogs during enforcement surges.
- Chemical treatment substitution:Sodium hypochlorite neutralization for liquid infectious waste faces displacement where effluent discharge standards tighten.
Strategic Opportunities
- Vietnam's hospital privatization wave:Greenfield private medical complexes lack legacy waste infrastructure and specify turnkey service contracts.
- Sharps waste container leasing:Reusable containment systems with RFID tracking are penetrating Japanese dialysis center networks.
- Indonesia's healthcare decentralization:Provincial hospital autonomy is creating procurement fragmentation that rewards localized collection logistics.
Industry Challenges
- Autoclave technician certification:Pressure vessel operation licenses require recurrent training that smaller operators struggle to maintain.
- Legacy incinerator retrofitting:Older facilities face multi-year compliance timelines to meet dioxin emission thresholds under tightening MEE enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Bio-Medical Waste Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Transportation, Treatment, Disposal Waste Type: Infectious Waste, Hazardous Waste, Non-Hazardous Waste, Sharps End User: Hospitals, Clinics, Laboratories, Research Institutions Technology: Incineration, Autoclaving, Chemical Treatment, Plasma Gasification |
| Companies Covered | Suez, Veolia Environnement SA, Stericycle, Inc., Waste Management, Inc., REMONDIS SE & Co. KG, Daniels Sharpsmart Inc., Clean Harbors, Inc., BioMedical Waste Solutions, LLC, Sattva Enviro, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Bio-Medical Waste Management Market Trends and Innovations
Digital tracking systems are penetrating waste chain custody documentation while thermal treatment technologies compete on residual toxicity elimination rather than volume throughput alone.
Plasma gasification is converging with pyrolysis systems in Chinese hazardous waste complexes. Municipal medical waste generators in Jiangsu and Zhejiang provinces are piloting hybrid thermal platforms. This convergence is compressing the capital cost gap between conventional incineration and advanced oxidation methods.
China's Ministry of Ecology and Environment is tightening dioxin emission limits for medical waste incinerators under revised GB standards. Existing facilities must install continuous emission monitoring systems or face operational suspension. Tertiary hospitals in Beijing and Shanghai are responding by accelerating outsourced treatment contracts with certified regional hubs.
Service bundling is replacing equipment ownership in procurement decisions across Philippine hospital groups. Large private chains are consolidating waste handling, linen services, and facility disinfection under single-vendor agreements. Metro Manila's expanding dialysis clinic networks exhibit the most pronounced shift toward comprehensive facility management contracts.
APAC Bio-Medical Waste Management Market Segmentation
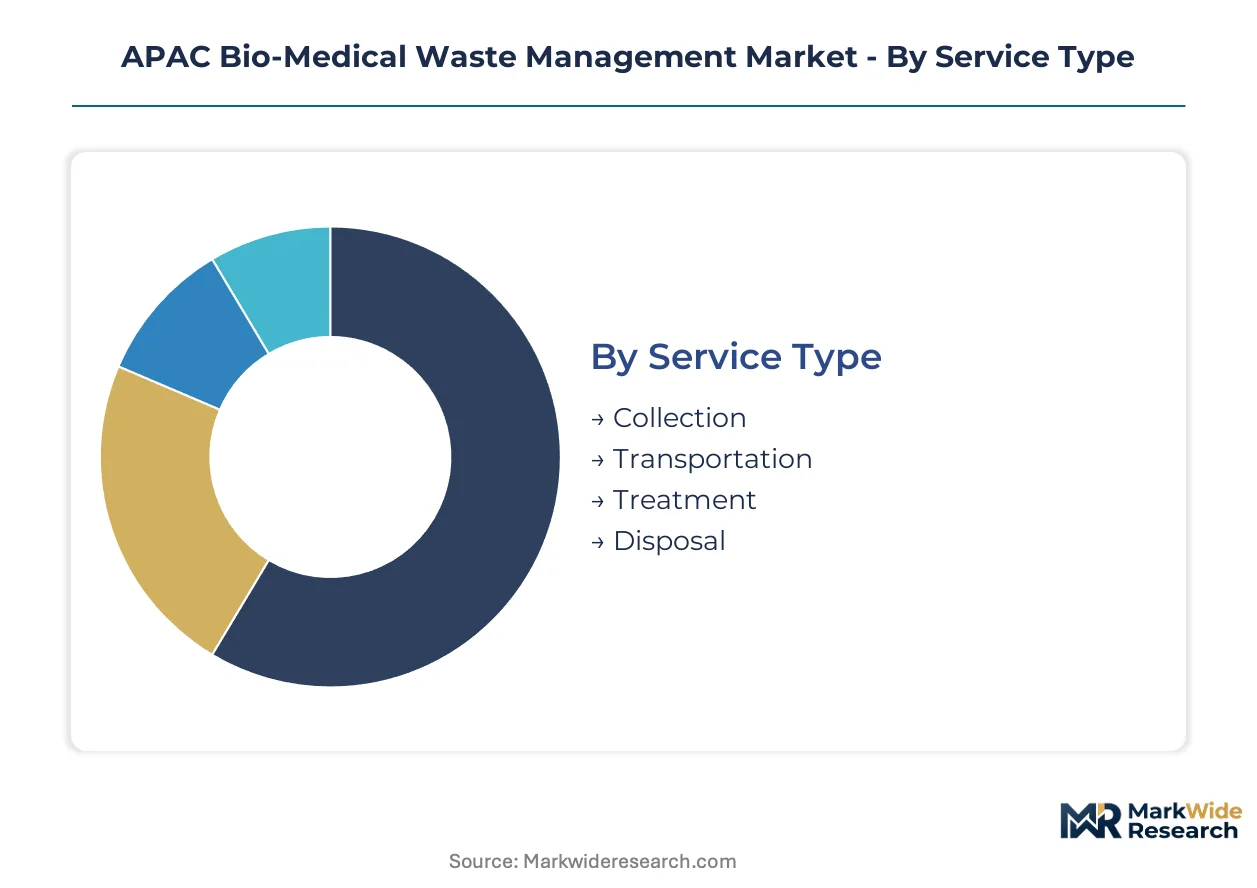
Segmentation in bio-medical waste management reveals how treatment protocols, liability exposure, and infrastructure maturity create divergent margin structures across service tiers. Procurement patterns in APAC increasingly favor integrated operators capable of spanning multiple segment boundaries under unified contracts.
Service Type:
Thermal treatment specifications and logistics density determine which service layers capture value in fragmented versus consolidated markets.
- Collection:Segregated waste pickup at source requires color-coded containment systems compliant with India's Bio-Medical Waste Management Rules. Demand clusters around tertiary hospital networks in Mumbai and Delhi where enforcement surges create urgency for certified handlers.
- Transportation:Refrigerated vehicle fleets with GPS tracking move infectious loads across provincial boundaries in Indonesia and Vietnam. Cold chain integrity failures trigger regulatory penalties that favor operators with dedicated medical waste fleets over general logistics contractors.
- Treatment:Licensed facilities apply thermal or chemical neutralization before landfill release. China's MEE restricts untreated residue acceptance, concentrating demand at regional hubs with continuous emission monitoring systems.
- Disposal:Final landfill placement or ash interment follows toxicity verification. Indian metropolitan clusters face permitted capacity bottlenecks that create disposal backlogs during compliance enforcement waves.
Collection leads on scale; treatment leads on margin expansion.
Waste Type:
Liability exposure and handling complexity stratify pricing power across contamination risk categories.
- Infectious Waste:Materials contaminated with blood, pathogens, or bodily fluids require steam sterilization or incineration before release. Autoclaving dominates volume processing across Southeast Asia due to lower capital barriers and regulatory acceptance.
- Sharps:Needles, scalpels, and broken glass demand puncture-resistant containment and specialized handling protocols. Japanese dialysis center networks are adopting RFID-tracked reusable container leasing to reduce single-use plastic liability.
- Hazardous Waste:Cytotoxic and pharmaceutical residues require advanced oxidation or plasma gasification for toxicity elimination. Plasma systems in Jiangsu and Zhejiang provinces recover energy while meeting tightening dioxin thresholds.
- Non-Hazardous Waste:General medical refuse without contamination risk follows municipal solid waste streams. This category faces pricing compression where hospital procurement bundles waste handling under comprehensive facility management contracts.
Sharps commands premium pricing; infectious waste dominates tonnage throughput.
End User:
Facility scale and regulatory sophistication determine whether generators internalize treatment or outsource to certified operators.
- Hospitals:Multi-facility networks across Southeast Asia consolidate procurement under single-vendor contracts favoring integrated collection-to-disposal platforms. China's tertiary hospitals are accelerating outsourced treatment as MEE tightens on-site emission requirements.
- Clinics:Small-scale generators lack capital for licensed treatment infrastructure and face elevated compliance costs under India's mandatory registration rules. Outsourced certified handling is becoming the default procurement mode.
- Laboratories:Research and diagnostic facilities generate concentrated chemical and biological hazards requiring specialized neutralization protocols.
- Research Institutions:Academic medical centers produce mixed waste streams with variable contamination profiles and episodic volume spikes.
Hospitals anchor revenue concentration; clinics represent the steepest expansion trajectory as regulatory enforcement broadens.
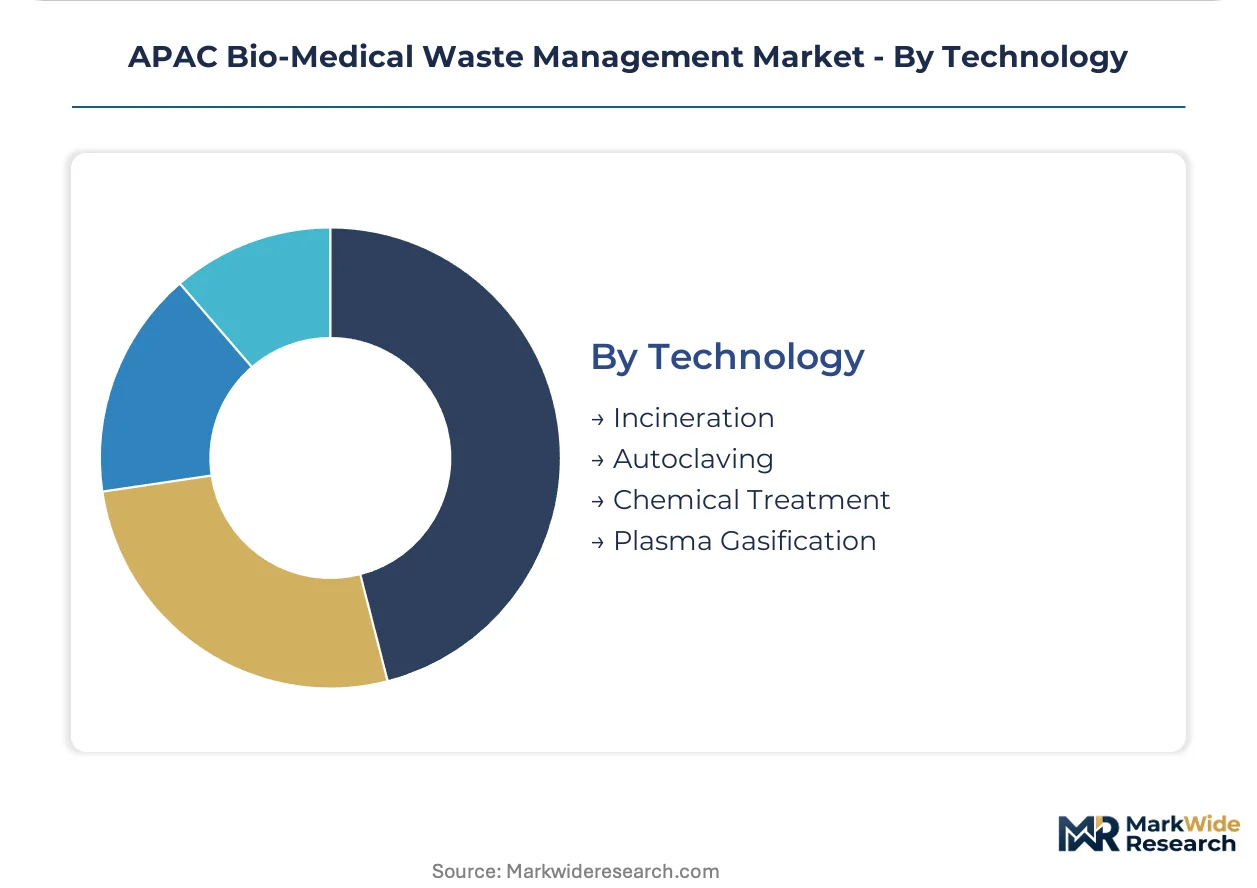
Technology:
Capital intensity and residual toxicity outcomes determine technology selection across urban density gradients.
- Autoclaving:Steam sterilization at 121°C neutralizes infectious agents for landfill disposal. Natural gas and electricity dependence creates margin vulnerability when utility tariffs spike in energy-importing markets.
- Incineration:Thermal oxidation reduces waste volume while requiring continuous emission monitoring under revised GB standards. Legacy facilities face multi-year retrofit timelines to meet dioxin thresholds.
- Plasma Gasification:Arc-driven dissociation eliminates residual toxicity and recovers synthesis gas from hazardous fractions. Capital costs are compressing as hybrid pyrolysis platforms emerge in Chinese hazardous waste complexes.
- Chemical Treatment:Sodium hypochlorite neutralization for liquid infectious waste faces displacement where effluent discharge standards tighten.
Autoclaving dominates installed base; plasma gasification is climbing fastest on energy recovery economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized waste handling technicians and certified treatment facility operators concentrate in India's pharmaceutical corridors and China's industrial zones, anchoring regional capacity expansion.
India
Hospital network consolidation in Mumbai and Delhi-NCR drives outsourced contract volumes. The Central Pollution Control Board enforces Bio-Medical Waste Management Rules mandating color-coded segregation and licensed facility registration. Small clinics in Bengaluru face elevated compliance costs and default to certified operators.
China
Tertiary hospitals in Beijing and Shanghai accelerate outsourced treatment as on-site emission requirements tighten. The Ministry of Ecology and Environment applies GB standards restricting landfill acceptance of untreated medical residues. Jiangsu and Zhejiang provinces pilot hybrid thermal platforms combining plasma gasification with pyrolysis.
Japan
Dialysis center networks adopt RFID-tracked reusable sharps container leasing to reduce single-use plastic liability. METI standards govern medical waste handling protocols. Osaka and Tokyo medical clusters specify comprehensive facility management contracts bundling waste handling with linen services.
Vietnam
Greenfield private medical complexes lack legacy waste infrastructure and specify turnkey service contracts. Hospital privatization creates demand for integrated collection-to-disposal platforms. Ho Chi Minh City and Hanoi hospital networks consolidate procurement under single-vendor agreements.
Indonesia
Provincial hospital autonomy fragments procurement and rewards localized collection logistics. Java's dense healthcare corridors face refrigerated vehicle fleet constraints. Surabaya and Bandung medical facilities prioritize operators with dedicated medical waste cold chains over general logistics contractors.
APAC Bio-Medical Waste Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service tiers, producing a bifurcated structure where scale operators anchor multi-facility contracts and regional players capture localized logistics. The market exhibits moderate consolidation with three to four integrated operators commanding metropolitan hospital networks while fragmented local providers serve peripheral clinics. Strategic archetypes include incineration-heavy conglomerates, collection-focused logistics specialists, and technology-agnostic platform integrators. Dominant competitive moves encompass multi-year contract consolidation with expanding hospital chains and selective facility acquisitions to close geographic coverage gaps.
Among diversified environmental service conglomerates, Suez and Veolia Environnement SA exemplify operators leveraging integrated collection-to-disposal platforms. Suez occupies a position emphasizing logistics density for clustered medical facilities, while Veolia anchors long-term service agreements through regional incineration footprint. Stericycle, Inc. represents the specialist archetype with concentrated exposure to healthcare waste streams. These three entities collectively illustrate the competitive tension between breadth-driven conglomerate strategies and depth-focused healthcare specialization.
| Leading Market Players |
|---|
| Suez |
| Veolia Environnement SA |
| Stericycle, Inc. |
| Waste Management, Inc. |
| REMONDIS SE & Co. KG |
| Daniels Sharpsmart Inc. |
| Clean Harbors, Inc. |
| BioMedical Waste Solutions, LLC |
| Sattva Enviro |
| Others |
Pricing and Supply Chain Analysis
China's GB standards on dioxin emissions and India's Bio-Medical Waste Management Rules gate both qualified supply and premium-tier pricing access. Only operators with certified treatment infrastructure and continuous emission monitoring systems command multi-year contracts with tertiary hospital networks across Mumbai, Delhi-NCR, Beijing, and Shanghai.
Pricing Analysis
The bundled-vs-unbundled service split stratifies pricing power across the APAC bio-medical waste management landscape. Comprehensive facility management contracts bundling waste handling, linen services, and disinfection command premium positioning against transactional per-kilogram disposal arrangements. Price differentiation hinges on certification tier under MEE and Central Pollution Control Board licensing and volume scale across multi-facility networks. Cost compression in the unbundled tier intensifies as small clinics in Bengaluru and Surabaya default to lowest-cost certified handlers. Dialysis center networks in Japan exhibit the least price sensitivity due to liability exposure around sharps containment, while provincial hospitals in Indonesia remain highly price-sensitive under decentralized procurement autonomy.
Supply Chain Analysis
Single-source vulnerability sits with specialized autoclave pressure vessel manufacturers concentrated in China, Japan, and South Korea. Equipment fleets draw from stainless steel fabrication hubs in Jiangsu and Zhejiang provinces, while RFID tracking systems for sharps containers rest on semiconductor sourcing from Taiwanese and South Korean suppliers. Tariff exposure on imported emission monitoring equipment creates procurement bottlenecks for Indian treatment facility operators. Distribution runs through dedicated refrigerated vehicle networks with GPS tracking rather than general logistics contractors, concentrating operational control with integrated collection-to-disposal platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC bio-medical waste management market functions as a regulatory compounder. India's Bio-Medical Waste Management Rules and China's revised GB standards on dioxin emissions are accelerating demand for certified outsourced treatment as enforcement intensity outpaces permitted infrastructure capacity.
For Market Incumbents: Deepen vertical control over refrigerated collection fleets and regional treatment hub capacity to defend against emerging logistics specialists. Plasma gasification technology threatens autoclave-dominated volume processing; incumbents should prioritize certification investment under tightening MEE emission thresholds and anchor multi-year contracts with consolidating hospital networks across Southeast Asia before localized competitors capture provincial procurement fragmentation in Indonesia. For New Entrants and Emerging Players: China's GB standards on untreated medical residue disposal opens a window for on-site pre-treatment system deployment in Beijing and Shanghai tertiary hospitals facing retrofit timelines. Vietnam's hospital privatization wave offers the most penetrable white-space target, as greenfield private medical complexes lack legacy waste infrastructure and specify turnkey service contracts. A go-to-market angle emphasizing integrated collection-to-disposal platforms with RFID-tracked custody documentation differentiates against fragmented local providers. For Investors and Strategic Acquirers: Roll-up economics work for regional collection specialists because metropolitan treatment capacity licensing bottlenecks in India and China create captive demand for certified downstream disposal. Platform consolidation across Java's dense healthcare corridors and the Philippines' dialysis clinic networks offers five-to-ten year viability under tightening regulatory enforcement. The signal to watch is MEE suspension orders against legacy incinerators missing continuous emission monitoring deadlines, which will accelerate outsourced contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Treatment Hub Expansion | Licensed facility additions in Mumbai and Delhi-NCR capture outsourced contract surges from India's Central Pollution Control Board enforcement waves. |
| Hybrid Thermal Platform Deployment | Plasma gasification-pyrolysis convergence in Jiangsu and Zhejiang provinces meets tightening GB standards while recovering synthesis gas. |
| Refrigerated Fleet Densification | Dedicated cold chain vehicle networks with GPS tracking secure multi-facility contracts across Ho Chi Minh City and Hanoi hospital networks. |
| RFID-Tracked Container Leasing | Reusable sharps containment systems penetrate Japanese dialysis center networks, reducing single-use plastic liability under METI protocols. |
| Comprehensive Facility Management Bundling | Integrated waste handling, linen services, and disinfection contracts consolidate procurement across Metro Manila's expanding private hospital chains. |
Research Methodology
Direct dialogue with treatment facility operators, hospital procurement managers, biomedical engineers, and Central Pollution Control Board enforcement officers grounded the qualitative foundation. Secondary validation drew from MEE emission disclosure databases, India's Bio-Medical Waste Management Rules compliance filings, hospital GPO contract repositories, and customs records on autoclave and incinerator equipment imports. Bottom-up service provider capacity estimates and top-down healthcare waste generation coefficients were triangulated to anchor market sizing.
Bottom-up modeling segmented the market across service type, waste category, end-user facility scale, and thermal treatment technology selection. The projection horizon spans from base year valuation through the analysis window, with CAGRs derived from treatment capacity expansion pipelines, regulatory enforcement timelines, and hospital infrastructure investment cycles. Modeled inputs include urban healthcare density gradients, licensed facility permitting rates, and technology substitution curves between autoclaving and plasma gasification.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE suspension campaigns or accelerated hospital privatization waves in Vietnam. Forecasts reflect assumptions around enforcement consistency, equipment import tariff stability, and natural gas pricing volatility affecting autoclave operating economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
United States Trash Bags Market