
 Green Concrete Market | 2026-2036
Green Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Green Concrete Market Intelligence
A shift from single-source supply contracts to multi-source procurement of supplementary cementitious materials is decoupling project timelines from individual supplier availability. Holcim leverages its global footprint to secure diverse waste streams for cement replacement. Cemex specializes in developing proprietary low-emission mix designs for large commercial projects. CarbonCure Technologies operates as a technology licensor, embedding its CO2 mineralization process within existing concrete plants.
Green concrete refers to a class of concrete that utilizes waste materials as a partial or full replacement for Portland cement, reducing energy consumption and CO2 emissions. These formulations often incorporate industrial byproducts like fly ash, slag cement, or silica fume. The product type segment shows fly ash and slag cement concrete dominating due to established supply chains. Within applications, infrastructure development and commercial buildings represent the largest consumers, driven by public and private sustainability mandates.
Regulatory frameworks are central to market formation. The EU Green Deal and China's dual carbon goals create direct incentives for low-carbon building materials. In the United States, EPA regulations on industrial emissions indirectly support the use of captured byproducts in concrete. Navigating the variable performance characteristics of recycled inputs to meet stringent building codes remains a critical challenge for producers.
Market Dynamics
The market is defined by the tension between stringent government decarbonization mandates and the operational complexities of integrating variable waste streams into standardized construction materials. This dynamic forces producers to innovate in material science and supply chain management simultaneously to meet both regulatory and performance requirements.
Growth Catalysts
- Government Mandates:The EU Green Deal and similar frameworks create direct incentives and demand for low-carbon building materials, compelling adoption in public infrastructure and commercial construction projects.
- Infrastructure Development:Large-scale urban construction programs, particularly in China and India, require sustainable materials to meet national environmental goals, creating a massive volume-based demand pull for green concrete.
- Waste Stream Valorization:The increasing availability of industrial byproducts like fly ash and slag cement, driven by environmental regulations on other industries, provides a consistent and cost-effective source of raw materials.
Market Restraints
- Performance Variability:The inconsistent chemical and physical properties of recycled inputs like fly ash from different sources present a significant challenge to producing concrete with predictable strength and durability.
- Supply Chain Logistics:A geographic mismatch often exists between the sources of supplementary cementitious materials, such as coal power plants, and high-demand construction markets, leading to increased transportation costs and logistical hurdles.
- Building Code Barriers:Conservative building codes and slow certification processes for new material formulations can significantly delay the market entry and adoption of innovative green concrete mixes, especially for structural applications.
Strategic Opportunities
- Novel SCM Development:Exploring and commercializing alternative supplementary cementitious materials, such as calcined clays and agricultural waste ash, can reduce reliance on fly ash and open new supply sources.
- Technology Licensing:Carbon capture and mineralization technology providers can expand by licensing their processes to small and mid-sized ready-mix concrete plants, creating a scalable, asset-light business model.
- Emerging Market Penetration:Targeting infrastructure projects in developing nations across Southeast Asia and Africa that are beginning to implement green building standards offers significant long-term growth potential.
Industry Challenges
- Standardization Hurdles:Achieving compliance with established international standards, such as ASTM and EN standards, for novel green concrete formulations is a time-consuming and expensive process that hinders rapid innovation.
- Quality Control Demands:Maintaining consistent quality requires advanced testing protocols and process controls to manage the inherent variability of recycled inputs, adding operational complexity and cost for producers.
- Technical Skill Gaps:A shortage of material scientists and concrete technologists with expertise in the chemistry of low-carbon binders limits the ability of firms to develop and scale new product formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Concrete Market |
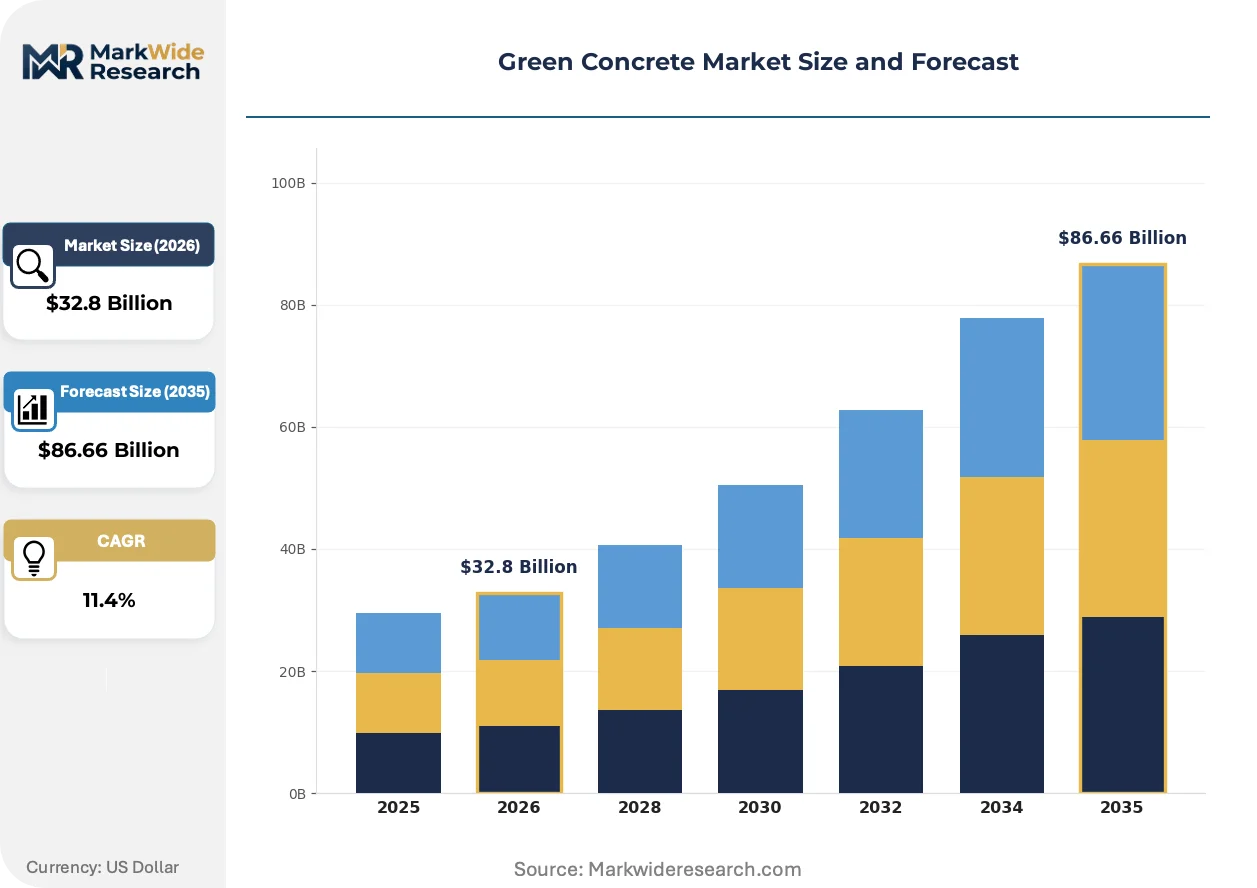
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash Concrete, Slag Cement Concrete, Silica Fume Concrete, Recycled Aggregate Concrete, Geopolymer Concrete Application: Infrastructure Development, Residential Construction, Commercial Buildings, Transportation Projects, Marine Structures End User: General Contractors, Construction Management Firms, Civil Engineers, Urban Developers, Public Works Departments Technology: Carbon Capture, Cement Replacement, Low-Emission Mix Designs, Energy Efficient Curing, Waste Material Utilization |
| Companies Covered | Heidelberg Materials, CarbonCure Technologies, Cemex, Votorantim Cimentos, Solidia Technologies, Holcim, UltraTech Cement, Anhui Conch Cement, CRH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Concrete Market Strategic Shifts & Innovations
The industrialization of sustainability is the defining theme, as processes move from niche applications to scalable, digitally integrated systems. This shift is evident in how new technologies are embedded, regulations are enacted, and procurement models are reconfigured to support mainstream adoption of low-carbon concrete.
Carbon capture and utilization (CCU) technology enables the direct injection of captured CO2 into fresh concrete, where it mineralizes and becomes permanently embedded. Major infrastructure and commercial construction projects are the primary adopters, driven by corporate and public sustainability goals. This direct CO2 utilization technology is converging with digital mix design software to optimize both carbon reduction and material performance in real-time.
China's national dual carbon policy establishes explicit targets for achieving peak carbon emissions and subsequent carbon neutrality. This top-down directive compels the construction sector to prioritize low-carbon materials, creating significant demand for green concrete. The infrastructure segment is most impacted, with state-owned enterprises now mandated to use sustainable building materials in major public works.
A transition away from single-supplier contracts for supplementary cementitious materials toward a more flexible, multi-source purchasing strategy is accelerating. This change insulates large construction project timelines from the operational volatility of any single fly ash or slag source. The trend is most visible in North America and Europe, where developers prioritize supply chain resilience to mitigate project delays.
Green Concrete Market Segmentation
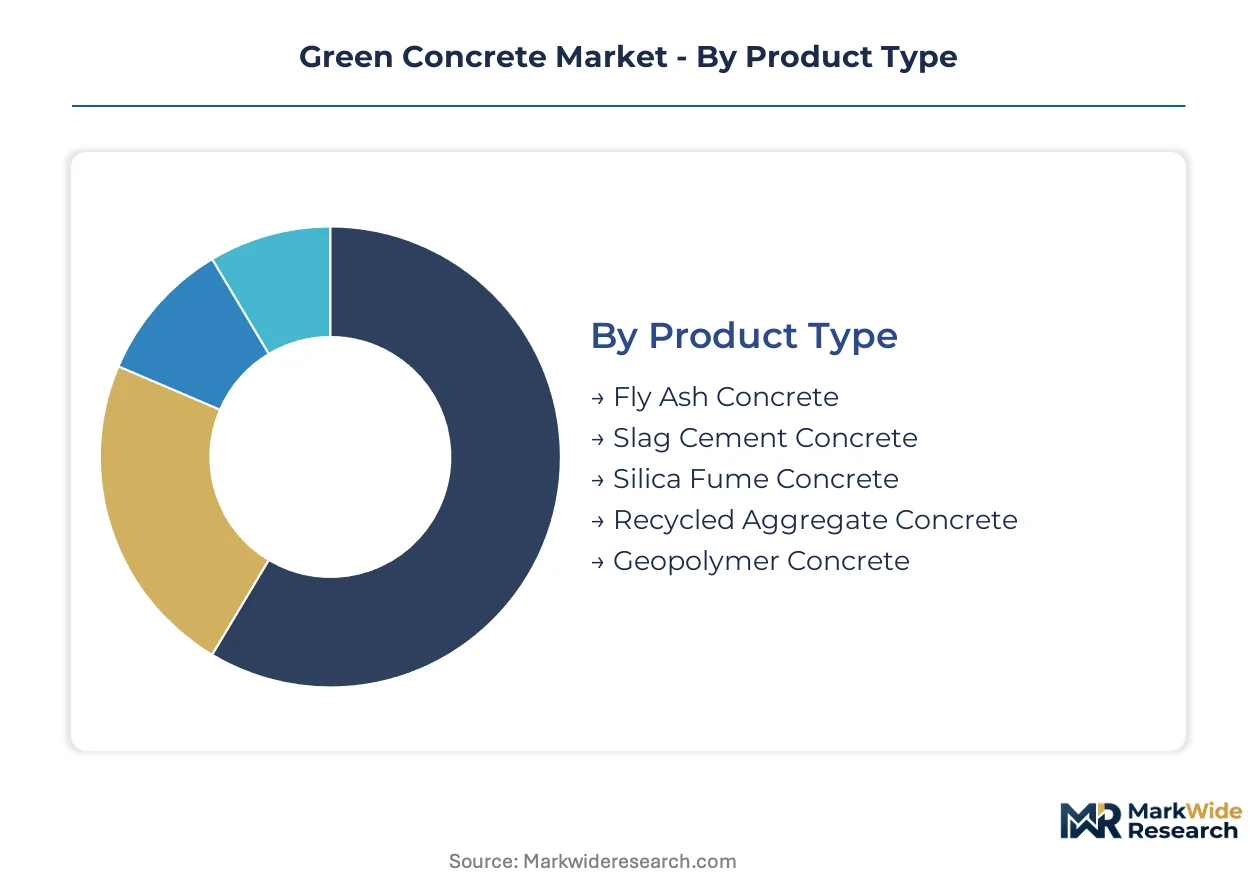
Segmentation within the green concrete market clarifies the distinct product formulations, application areas, and technological approaches driving its expansion. Understanding these segments enables producers to tailor material science innovations and supply chain strategies to specific demand patterns across various construction sectors.
Product Type:
The product type segmentation reveals a clear split between high-volume, cost-effective formulations and specialized, performance-driven green concrete solutions.
- Fly Ash Concrete:This formulation incorporates fly ash, a byproduct from coal combustion, as a partial substitute for Portland cement. Demand concentrates within large-scale infrastructure projects in China and India, driven by the material's cost-effectiveness and widespread availability.
- Slag Cement Concrete:Ground granulated blast-furnace slag, an industrial byproduct from steel production, replaces a portion of the cement content. Major commercial building developments in Europe and North America utilize this type for its enhanced durability and reduced carbon footprint.
- Silica Fume Concrete:Silica fume, a byproduct of silicon and ferrosilicon alloy production, significantly improves concrete strength and impermeability. This type is critical for high-performance applications like bridge decks and marine structures.
- Recycled Aggregate Concrete:This concrete uses processed demolition waste as a substitute for virgin aggregates. Urban construction projects in Germany and the United States frequently employ recycled aggregate concrete to reduce landfill waste.
- Geopolymer Concrete:Geopolymer concrete utilizes alkali-activated industrial waste materials, like fly ash or slag, without Portland cement. This innovative product type targets specialized applications requiring extreme chemical resistance and high early strength.
Mature deployment sits with Fly Ash Concrete. Newer deployment is concentrated in Geopolymer Concrete.
Application:
Application segments delineate where public mandates and private sustainability goals are most effectively driving the adoption of green concrete.
- Infrastructure Development:This segment includes roads, bridges, and public utility projects, representing the largest consumer of green concrete. National decarbonization goals in China and the EU Green Deal compel extensive use of sustainable materials in these large-scale public works.
- Commercial Buildings:Office complexes, retail centers, and institutional facilities frequently specify green concrete to meet LEED certification requirements and corporate sustainability targets. Developers in the United States and Germany prioritize low-emission materials for these projects.
- Residential Construction:Single-family homes and multi-unit dwellings increasingly incorporate green concrete, particularly in regions with progressive building codes. Architects and builders in Canada and Australia are integrating these materials for improved energy efficiency.
- Transportation Projects:Airports, railways, and port facilities utilize green concrete for its durability and reduced environmental impact. Major projects in Japan and the United Kingdom often specify sustainable concrete solutions.
- Marine Structures:Piers, seawalls, and offshore platforms benefit from the enhanced resistance to chloride penetration offered by certain green concrete formulations. Coastal engineering projects in the Netherlands and Singapore use these specialized materials.
Large-scale infrastructure projects consistently absorb the largest volumes, while commercial buildings are demonstrating accelerated uptake.
End User:
End-user categories highlight the diverse stakeholders influencing procurement decisions and material specifications for green concrete projects.
- General Contractors:These firms manage daily construction operations and directly procure green concrete from ready-mix suppliers. Their decisions are often influenced by project specifications, material availability, and cost-effectiveness.
- Public Works Departments:Government agencies responsible for public infrastructure set material standards and procurement requirements for roads, bridges, and municipal buildings. China's state-owned enterprises are mandated to use sustainable materials by these departments.
- Construction Management Firms:These entities oversee project planning, scheduling, and budgeting, often recommending specific green concrete solutions to clients. Their expertise guides material selection for complex commercial developments.
- Civil Engineers:Engineers design structures and specify material properties, including the type and composition of green concrete required for structural integrity. Their technical expertise is crucial for validating new formulations.
- Urban Developers:Developers initiate and finance large-scale urban projects, influencing the adoption of green concrete through sustainability commitments and market positioning. They drive demand for eco-friendly building materials in new cityscapes.
General Contractors directly implement green concrete solutions, whereas Public Works Departments often set the initial demand parameters.
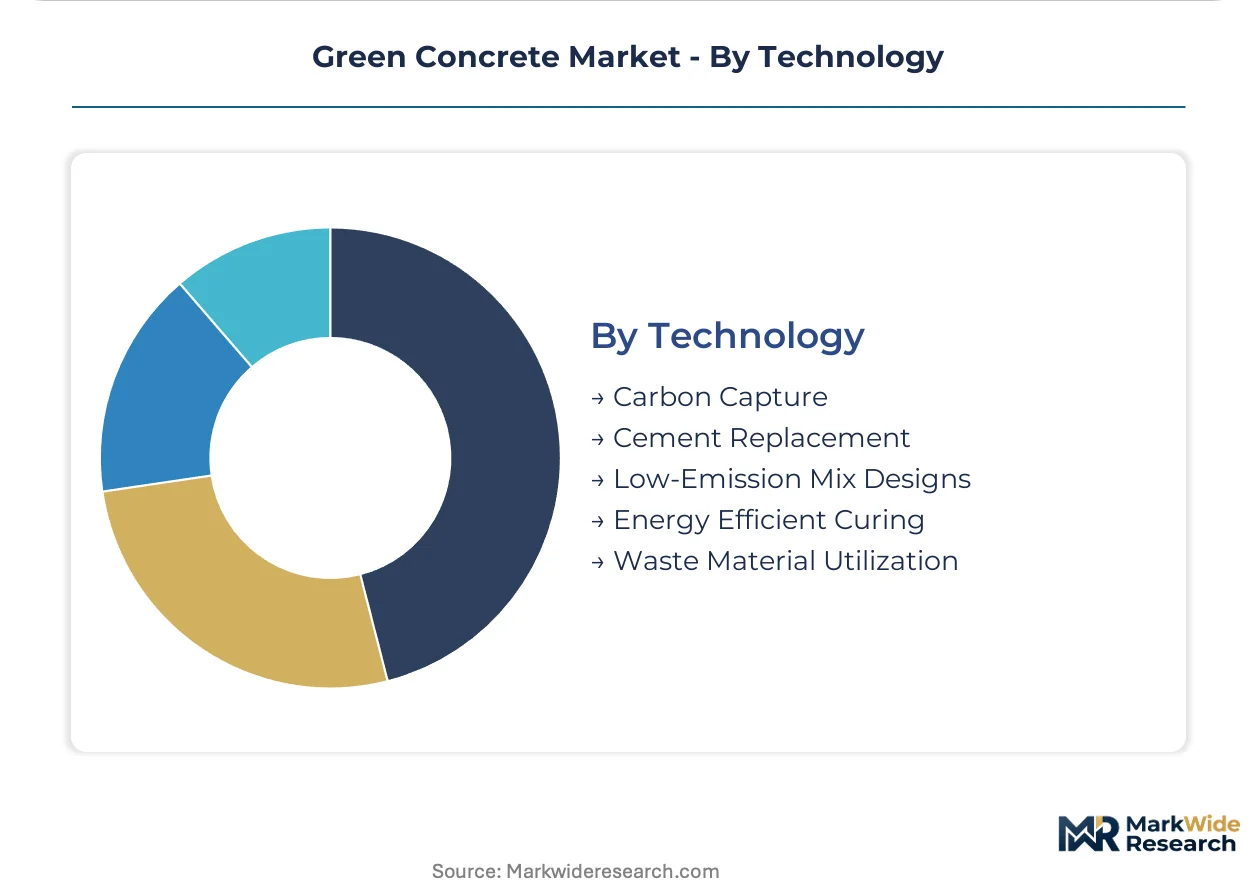
Technology:
Technology segmentation illustrates the various innovation pathways producers are pursuing to enhance both the environmental performance and material properties of green concrete.
- Carbon Capture:This technology involves injecting captured CO2 directly into fresh concrete, where it mineralizes and becomes permanently embedded. CarbonCure Technologies licenses this process to existing concrete plants.
- Low-Emission Mix Designs:These proprietary formulations optimize the blend of supplementary cementitious materials and admixtures to achieve specific performance with minimal embodied carbon. Cemex specializes in developing these designs for large commercial projects.
- Cement Replacement:This approach focuses on maximizing the substitution of traditional Portland cement with industrial byproducts like fly ash or slag. Holcim leverages its global footprint to secure diverse waste streams for this purpose.
- Energy Efficient Curing:Innovations in curing methods reduce the energy consumption required for concrete to reach its optimal strength. This includes advanced thermal curing techniques and specialized chemical accelerators.
- Waste Material Utilization:This technology segment encompasses the processing and integration of various industrial and agricultural waste streams into concrete. This broad category includes materials beyond traditional fly ash and slag, such as calcined clays.
Carbon capture technologies directly reduce embodied carbon, while advanced mix designs optimize material performance and longevity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial byproduct availability, particularly fly ash and slag cement, anchors regional green concrete market development. Governments globally mandate sustainable construction practices, driving demand for low-carbon materials across continents. This creates distinct regional dynamics for green concrete adoption and innovation.
China
China's extensive infrastructure development programs create massive demand for green concrete. The country's national dual carbon goals compel the construction sector to prioritize low-carbon materials. Major urban construction initiatives in the Yangtze River Delta region frequently specify sustainable building solutions.
United States
Federal and state sustainability mandates drive green concrete adoption in US infrastructure projects. EPA regulations on industrial emissions indirectly support the use of captured byproducts in concrete formulations. Urban construction projects in the Pacific Northwest increasingly utilize recycled aggregate concrete.
Germany
Germany's commitment to the EU Green Deal directly incentivizes low-carbon building materials across its construction sector. Public and private sustainability mandates accelerate green concrete specification in commercial and residential projects. Major urban centers like Berlin are implementing progressive building codes for sustainable materials.
India
Large-scale infrastructure development in India requires sustainable materials to meet national environmental goals. The increasing availability of fly ash from coal power plants provides a consistent raw material source. Major public works projects in the National Capital Region (NCR) increasingly integrate green concrete.
Netherlands
The Netherlands prioritizes green concrete for its critical marine structures and coastal engineering projects. Enhanced resistance to chloride penetration makes specialized green concrete formulations suitable for these applications. Port expansion projects in Rotterdam frequently specify sustainable concrete solutions.
Green Concrete Market Key Industry Players
Supply chain diversification dominates the current landscape, as producers seek to secure varied waste streams for cement replacement. The market structure exhibits a mix of large, integrated materials suppliers and specialized technology licensors. Strategic archetypes include global cement giants leveraging extensive footprints and niche innovators focusing on specific carbon reduction technologies. Technology licensing and proprietary mix design development represent key competitive moves.
Specialists in carbon capture technology, like CarbonCure Technologies, exemplify an asset-light business model through licensing their CO2 mineralization processes to existing concrete plants. Large, integrated materials suppliers such as Cemex and Holcim occupy a position at the other end of the spectrum. Cemex focuses on developing proprietary low-emission mix designs for large commercial projects, while Holcim leverages its global footprint to secure diverse waste streams for cement replacement. These companies anchor the market with their material science innovations and supply chain management capabilities.
| Leading Market Players |
|---|
| Heidelberg Materials |
| CarbonCure Technologies |
| Cemex |
| Votorantim Cimentos |
| Solidia Technologies |
| Holcim |
| UltraTech Cement |
| Anhui Conch Cement |
| CRH |
| Others |
Cost & Logistics Intelligence
The global cement price index influences green concrete pricing, as traditional Portland cement costs often set a baseline for low-carbon alternatives. This benchmark cascades through the supply chain, impacting pricing tiers for various green concrete formulations.
Pricing Analysis
Bundled performance guarantees and technical support define green concrete pricing, often reflecting the complexity of specialized mix designs. The dominant pricing structure is project-based contracting, with premium-mid-economy pricing differentiation based on embodied carbon reduction and specific performance characteristics. Price differentiation also stems from certification levels, such as LEED, and the geographic delivery costs associated with specialized materials. Pricing softness reflects the performance variability of recycled inputs, which can increase testing and quality control expenses. Infrastructure developers exhibit lower price sensitivity due to regulatory mandates, while residential builders remain highly cost-conscious.
Supply Chain Analysis
Ready-mix concrete suppliers form the primary distribution channel for green concrete, facilitating project-based delivery to construction sites. Geographic supply concentration for key supplementary cementitious materials (SCMs) centers on China and India for fly ash, and Europe for slag cement. The market draws from industrial byproducts like fly ash, slag cement, and silica fume. A structural risk exists in logistics chokepoints, stemming from the geographic mismatch between SCM sources and high-demand construction markets. Multi-source procurement strategies are emerging to mitigate these challenges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
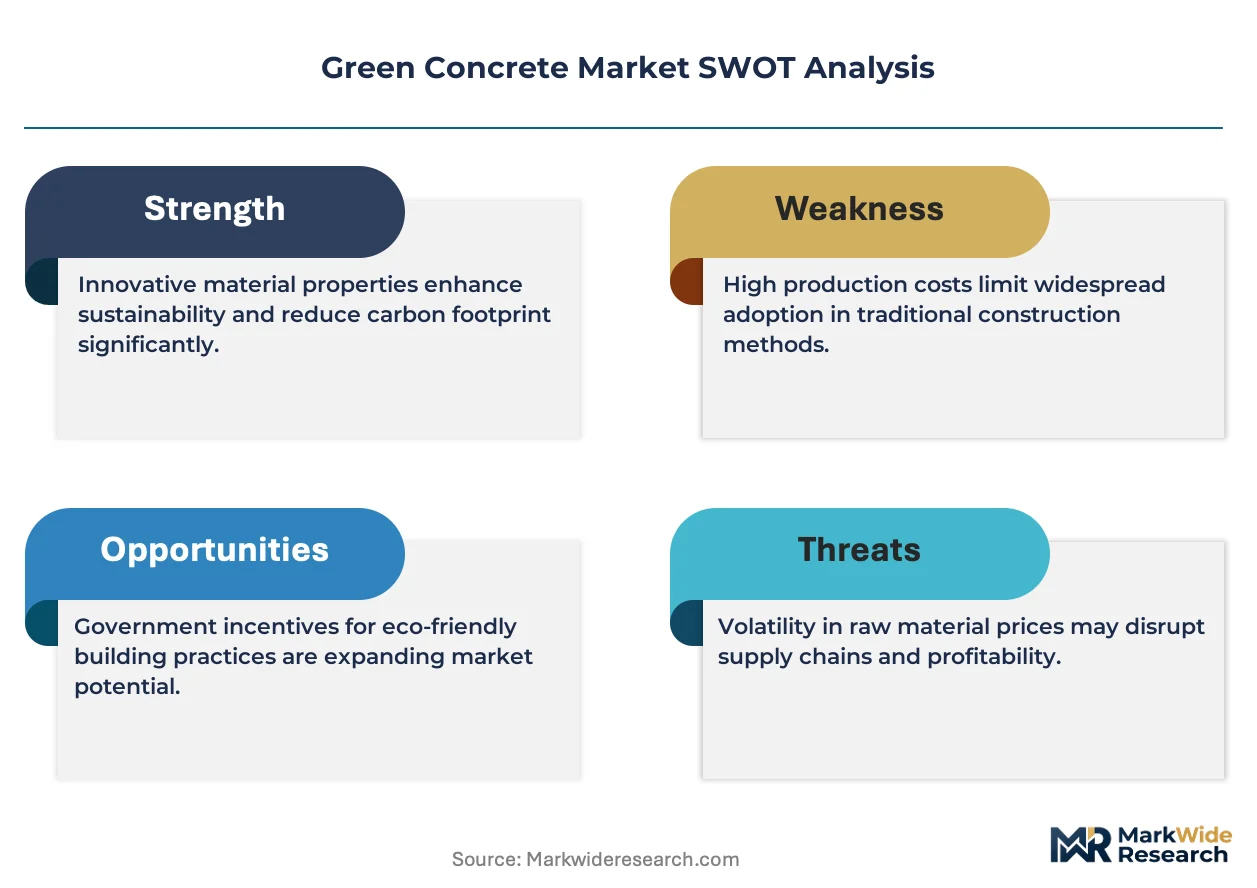
The green concrete market is largely a cost-of-compliance story, where stringent regulations compel adoption. The EU Green Deal establishes a significant barrier-to-entry moat for compliant low-carbon material producers.
For Market Incumbents: Anchor global supply chains by securing diverse waste streams for supplementary cementitious materials. Invest in advanced material science R&D to mitigate performance variability of recycled inputs. This proactive stance defends against market share erosion from emerging novel SCMs and strengthens compliance with evolving building codes. Leverage existing global footprints to optimize logistics and reduce transportation costs.
For New Entrants and Emerging Players: Price-point gaps exist between premium, high-performance green concrete and standard formulations, offering market entry opportunities. Target specialized applications requiring extreme chemical resistance, such as marine structures, or high early strength. License novel carbon capture and mineralization technologies to small and mid-sized ready-mix concrete plants. This asset-light business model allows rapid penetration into underserved regional markets.
For Investors and Strategic Acquirers: Distressed-cycle entries favor technology licensors in Europe and North America, particularly those with proven carbon capture solutions. The long-term viability of green concrete is anchored by government decarbonization mandates and increasing waste stream valorization. Target innovative material science firms specializing in novel SCM development or advanced mix designs. The acceleration of building code updates for low-carbon materials serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Calcined Clay R&D | Develops alternative supplementary cementitious materials, reducing reliance on fly ash availability. |
| License CO2 Mineralization Technology | Expands market reach for carbon capture solutions to small and mid-sized concrete plants. |
| Acquire Regional SCM Processors | Secures consistent supply of industrial byproducts, mitigating supply chain logistics risks. |
| Develop Proprietary Low-Emission Mix Designs | Caters to large commercial projects seeking specific performance and sustainability certifications. |
| Expand into Southeast Asian Infrastructure | Taps into emerging market demand driven by new green building standards and urban development. |
Research Approach
Document review covered regulatory filings from the EPA and EU Green Deal, industry association reports, and material science journals, complemented by interviews with industry stakeholders. Primary interviews included material scientists, concrete technologists, public works officials, and general contractors. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down triangulation.
Quantitative modeling generated volume and value projections across the analysis window, incorporating historical data and projected growth drivers. The framework segmented the market by product type, application, end-user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from these segment-level projections and scenario analysis. Key forecast inputs included supplementary cementitious material availability and carbon capture technology adoption rates.
Inputs from public regulatory documents and industry reports were available through the study window; gaps in real-time SCM availability data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and the pace of building code evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
United States Green Cement Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Green Rebar Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Green Cement Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Green Roof Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Waterproofing Products Market