
 Municipal Solid Waste Incineration Market | 2026-2036
Municipal Solid Waste Incineration Market Size, Share, and Industry Trends Forecast 2026-2036
Municipal Solid Waste Incineration Market Foresight
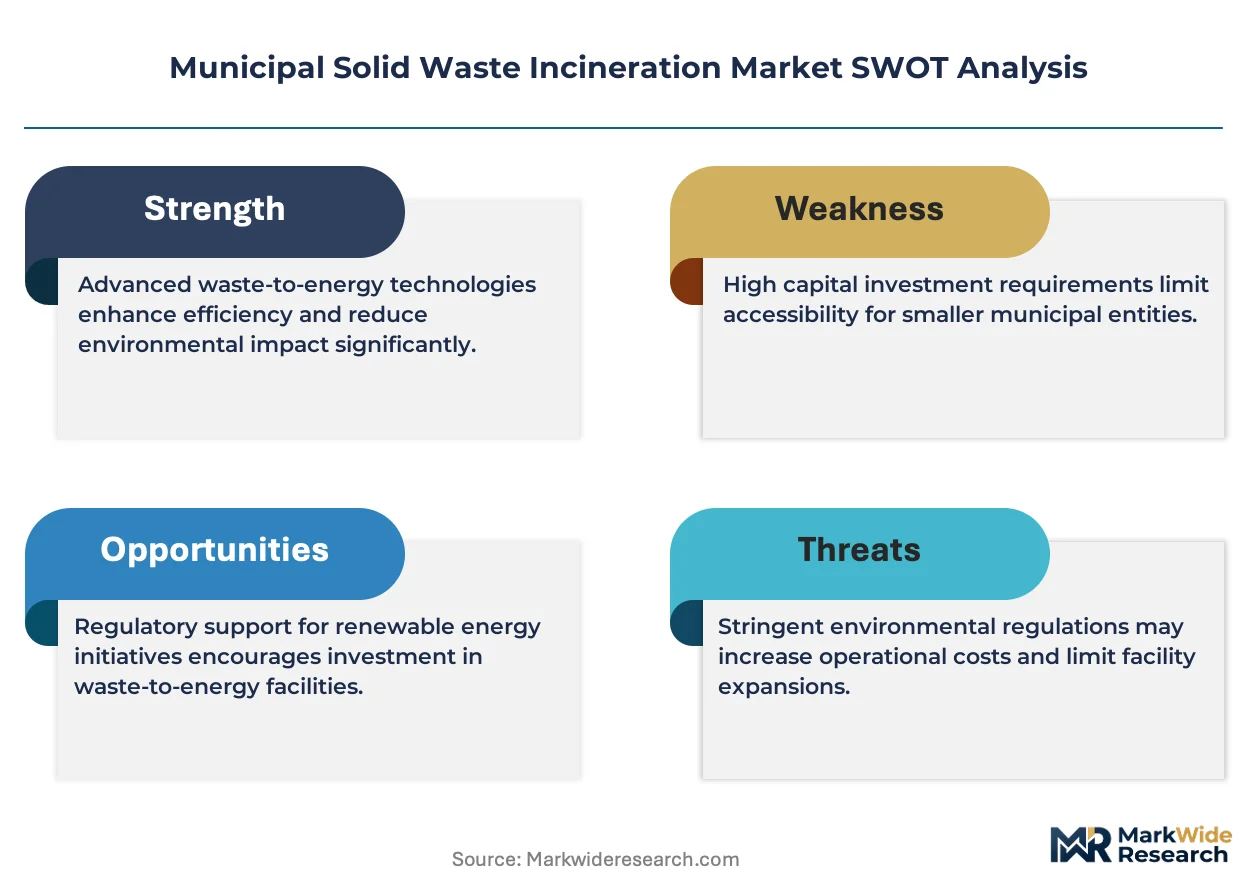
The EU Green Deal is restructuring capital deployment timelines for new incineration capacity across member states. Veolia Environment S.A. leverages its integrated waste-to-energy platform to dominate French and German municipal procurement cycles. Covanta Holding Corporation anchors North American operations through long-term service contracts with mid-Atlantic municipalities. Babcock & Wilcox Enterprises, Inc. specializes in boiler and emission control systems for retrofit markets.
Municipal solid waste incineration refers to the controlled combustion of household and commercial refuse at temperatures exceeding 850°C, producing thermal energy for electricity generation or district heating while reducing waste volume by approximately 90%. Grate incineration occupies the majority of installed global capacity due to operational flexibility with heterogeneous waste streams. Fluidized bed technology competes for industrial waste blends and RDF applications where calorific consistency supports higher combustion efficiency. Energy Producers represent the fastest-growing end user category as power utilities seek baseload renewable alternatives to fossil-fired generation.
EPA standards under the Clean Air Act shape US facility permitting, while China's MEE enforces progressively stringent dioxin limits that force technology replacement cycles. The EU's Industrial Emissions Directive and associated BAT conclusions define European operating parameters and compliance investment thresholds. Stakeholders must monitor regulatory divergence between jurisdictions to align equipment specifications and service portfolios with divergent compliance cost structures.
Market Dynamics
Landfill diversion mandates across Southeast Asian municipalities are compressing procurement timelines for waste-to-energy infrastructure, forcing technology upgrades before existing capacity reaches end-of-life.
Growth Catalysts
- China's MEE dioxin standards:The GB emission limits are accelerating replacement cycles for subscale incinerators in the Yangtze River Delta cluster.
- RDF co-combustion:Cement kilns and power utilities are expanding refuse-derived fuel intake as a baseload renewable alternative to coal.
- Greater Jakarta density:Urban waste generation outpaces sanitary landfill capacity, forcing municipal procurement toward thermal treatment.
Market Restraints
- Flue gas treatment capex:Wet scrubber and activated carbon injection systems add 25-35% to project capital intensity.
- Specialized refractory supply:High-alumina brick sourcing concentrates among German and Japanese suppliers, creating procurement bottlenecks.
- Grid interconnection queues:Waste-to-energy projects face 18-36 month utility connection timelines in saturated transmission zones.
Strategic Opportunities
- Indonesia's outer islands:Provincial capitals outside Java lack any thermal treatment capacity, creating first-mover openings for modular grate systems.
- Carbon capture retrofit:Post-combustion amine scrubbing integration with existing fleets qualifies for EU ETS credits under the Green Deal framework.
- AI-driven combustion control:Machine vision and thermal imaging convergence is reducing excess air requirements and improving heat rate performance.
Industry Challenges
- Residue management expertise:Bottom ash beneficiation and air pollution control residue stabilization require specialized chemical engineering skills in short supply.
- Permitting timeline compression:Environmental impact assessments for greenfield projects now average 4-7 years in contested jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Municipal Solid Waste Incineration Market |
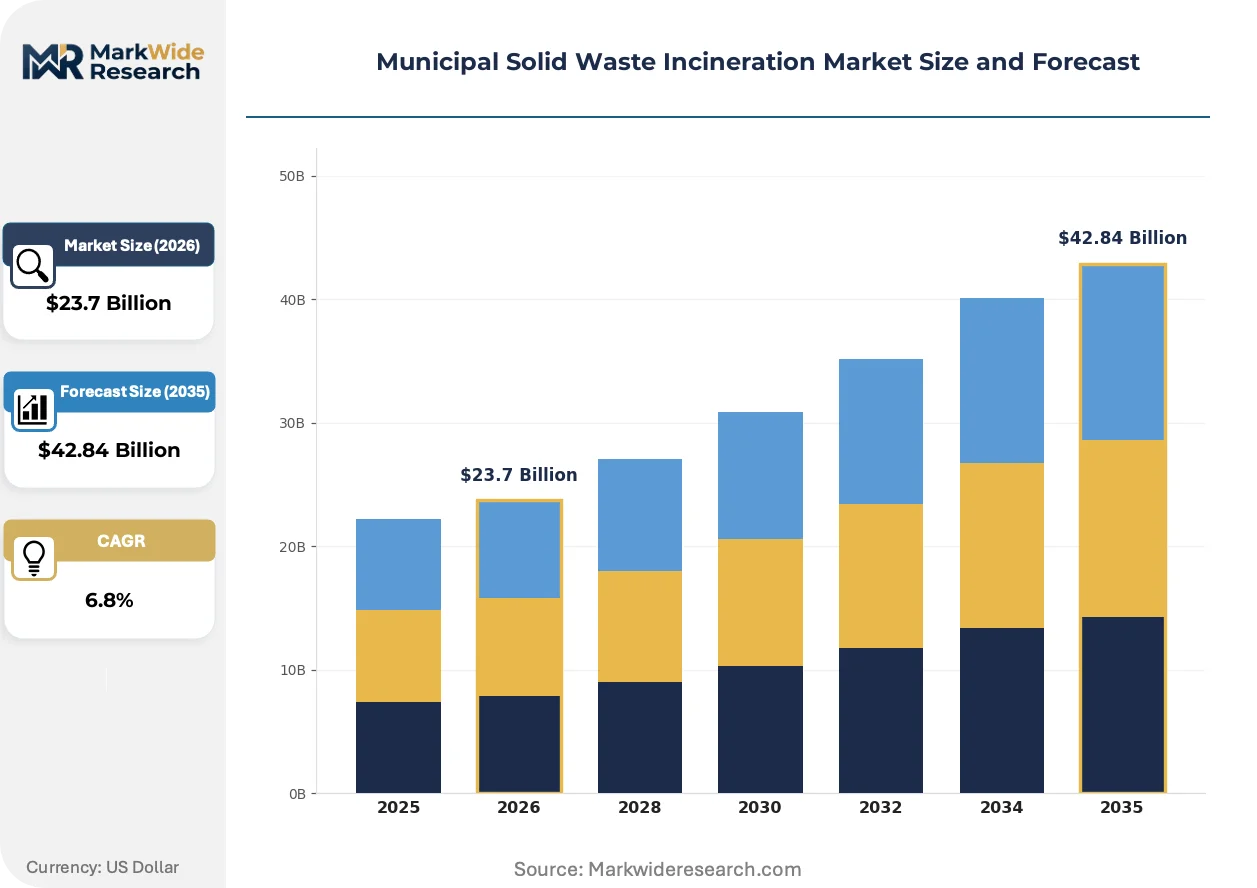
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Grate Incineration, Fluidized Bed, Rotary Kiln, Gasification End User: Municipalities, Waste Management Companies, Industrial Facilities, Energy Producers Emission Control: Scrubber Systems, Baghouse Filters, Catalytic Converters, Activated Carbon Service Type: Design & Engineering, Equipment Supply, Operation & Maintenance, Consulting |
| Companies Covered | Veolia Environment S.A., Suez Environment S.A., Covanta Holding Corporation, Hitachi Zosen Corporation, China Everbright International Limited, Keppel Seghers, Martin GmbH, Babcock & Wilcox Enterprises, Inc., Wheelabrator Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Municipal Solid Waste Incineration Market Shifts & Advancements
Advanced emission control architectures and digital combustion management are redefining operational performance thresholds for thermal waste treatment.
Plasma gasification is unifying waste destruction and syngas production in a single reactor vessel. Industrial parks in Japan and South Korea are piloting units for hazardous and medical waste streams. This convergence is unifying previously separate treatment workflows into captive on-site energy systems.
The EU's Industrial Emissions Directive BAT conclusions are mandating continuous emission monitoring for mercury and hydrogen chloride. Operators must upgrade data acquisition infrastructure or face permit revocation. German and Dutch facilities are responding with integrated digital twin platforms that predict emission excursions before they occur.
Long-term service agreements are displacing equipment-only sales for new capacity additions. Municipal buyers in France and Italy now require 15-20 year availability guarantees covering maintenance, residue disposal, and emission compliance. This contractual evolution is most visible in the Nordics, where district heating integration demands operational continuity across heating seasons.
Municipal Solid Waste Incineration Market Segmentation
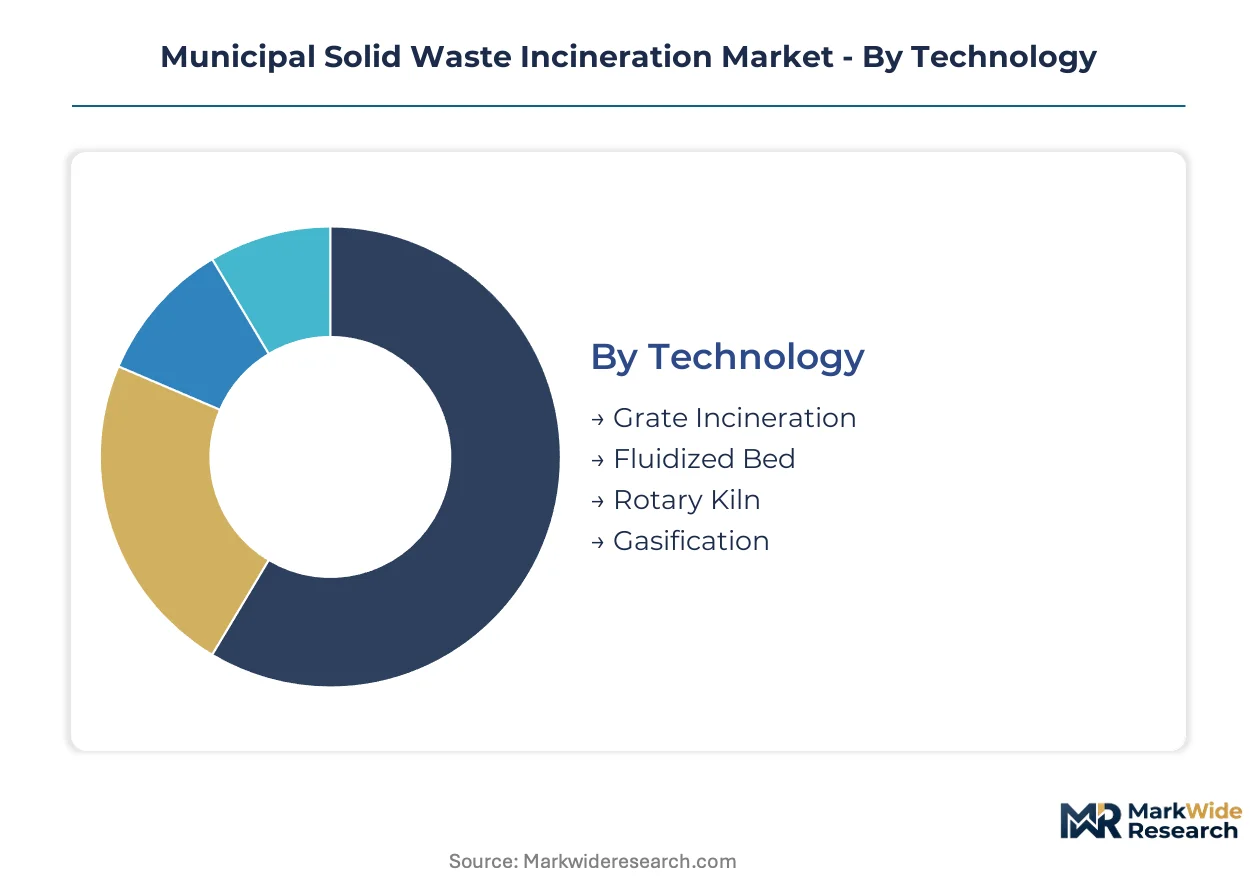
Segmentation in municipal solid waste incineration reveals how technology choices cascade through procurement decisions, emission compliance investments, and long-term service contracting. Understanding these dimensions exposes where capital concentrates and where operational complexity creates margin differentiation.
Technology:
Grate systems dominate heterogeneous municipal waste streams through mechanical robustness and fuel flexibility across moisture and calorific variation.
- Grate Incineration:Moving grate and reciprocating grate designs handle unsorted household waste with minimal preprocessing. China's Yangtze River Delta municipalities are replacing subscale units with 400-800 tonne-per-day grate systems to meet MEE dioxin standards.
- Fluidized Bed:Bubbling and circulating fluidized bed reactors achieve higher combustion efficiency with preprocessed refuse-derived fuel. Japanese industrial parks deploy these for consistent waste blends where heat recovery optimization justifies fuel preparation costs.
- Rotary Kiln:Cylindrical refractory-lined vessels rotate waste through controlled temperature zones for hazardous and medical waste destruction. Specialized applications in South Korea's industrial waste sector leverage this technology for controlled residence time.
- Gasification:Partial oxidation in oxygen-limited environments produces syngas for power generation or chemical synthesis. Plasma-enhanced variants in pilot deployment across Japanese captive industrial energy systems unify waste destruction with on-site fuel production.
Mature deployment sits with grate incineration. Newer deployment is concentrated in gasification piloting for circular economy integration.
End User:
Procurement authority determines contract structure, risk allocation, and technology specification stringency across the project lifecycle.
- Municipalities:Local government entities issue long-term concessions requiring availability guarantees and residue management accountability. French and Italian municipal tenders now mandate 15-20 year operational contracts covering maintenance, ash disposal, and emission compliance.
- Waste Management Companies:Integrated waste service providers seek technology platforms supporting landfill diversion targets and energy revenue diversification. Veolia Environment S.A. leverages its French and German municipal procurement relationships to anchor fleet standardization.
- Industrial Facilities:Cement kilns and chemical plants co-combust refuse-derived fuel for process heat and carbon reduction. European cement producers under EU ETS pressure are expanding RDF intake as a baseload renewable alternative to coal.
- Energy Producers:Power utilities and district heating operators seek baseload renewable capacity with predictable fuel costs. Nordic district heating networks integrate waste-to-energy for operational continuity across heating seasons, climbing the fastest among end user categories.
Contract maturity differentiates municipal and waste management procurement from industrial and energy producer transactions.
Emission Control:
Flue gas treatment architecture determines capital intensity, operating cost structure, and regulatory compliance margin across jurisdictions.
- Scrubber Systems:Wet and semi-dry scrubbers neutralize acid gases including hydrogen chloride and sulfur dioxide. German and Dutch facilities upgrade wet scrubber capacity to meet EU Industrial Emissions Directive BAT conclusions for continuous compliance.
- Baghouse Filters:Fabric filter systems capture particulate matter and heavy metals downstream of combustion. These systems represent standard configuration across existing Chinese fleets facing MEE enforcement of particulate limits.
- Catalytic Converters:Selective catalytic reduction and dioxin decomposition catalysts destroy nitrogen oxides and organic pollutants. Japanese facilities deploy these for mercury and dioxin control under METI emission guidelines.
- Activated Carbon:Injection systems adsorb mercury and dioxin compounds before particulate filtration. High reagent costs drive optimization through predictive dosing algorithms in digitally integrated plants.
Scrubber and baghouse configurations represent baseline compliance investment. Catalytic and carbon injection systems concentrate in jurisdictions with stringent organic pollutant limits.
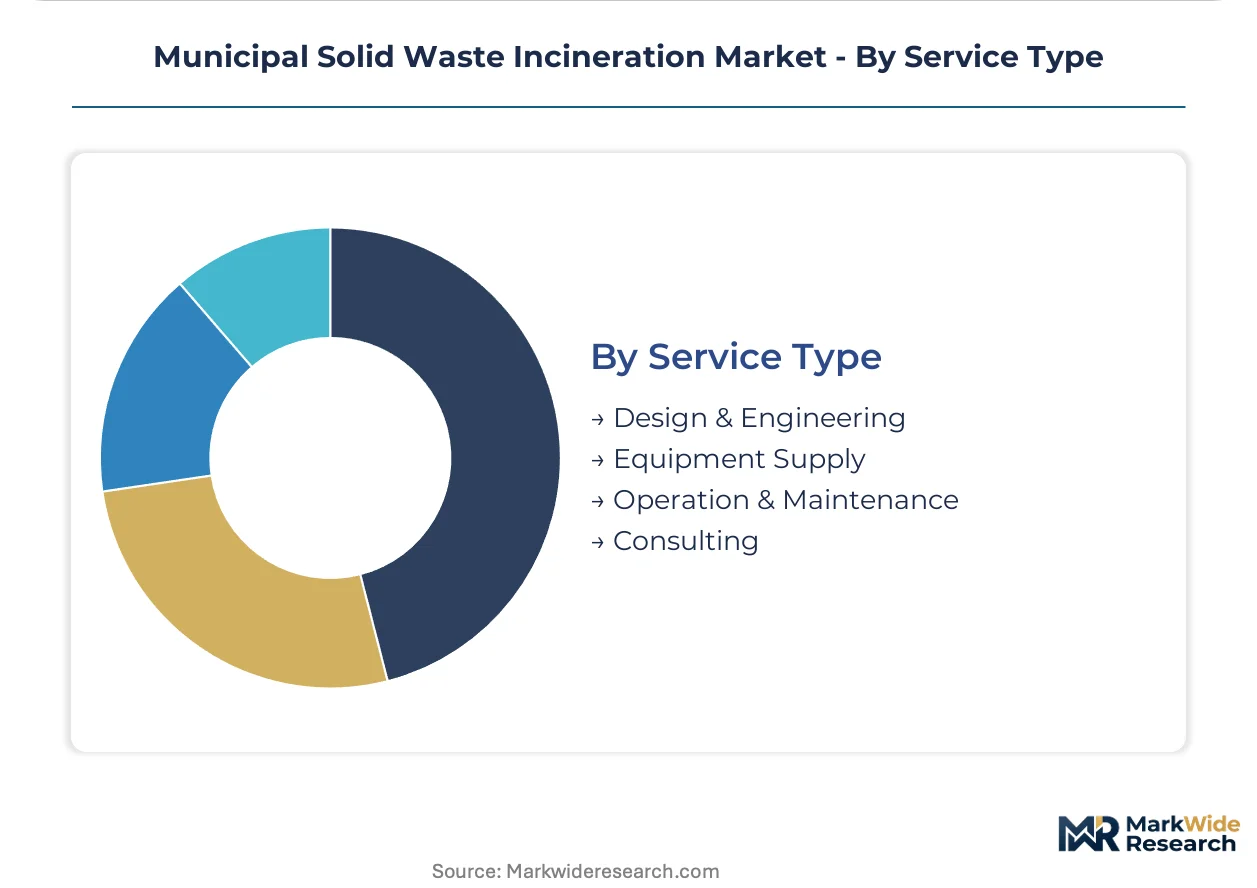
Service Type:
Contract scope evolution shifts risk allocation from equipment vendors to integrated service providers across project development and operational phases.
- Design & Engineering:Front-end engineering and feasibility studies establish technology selection, emission control architecture, and project economics. Indonesian provincial capitals outside Java require modular system design for first-mover thermal treatment capacity.
- Equipment Supply:Boiler, grate, and emission control system manufacturing concentrates among German and Japanese suppliers for high-alumina refractory specifications. Babcock & Wilcox Enterprises, Inc. specializes in boiler and emission control retrofits for existing fleet upgrades.
- Operation & Maintenance:Long-term service agreements now displace equipment-only sales in French and Italian municipal procurement. Covanta Holding Corporation anchors North American operations through mid-Atlantic municipal service contracts spanning decades.
- Consulting:Regulatory permitting, environmental impact assessment, and residue management advisory support project development. Permitting timelines now average 4-7 years in contested jurisdictions, creating specialized advisory demand.
Equipment supply historically dominated revenue capture. Integrated operation and maintenance contracts now represent the expanding commercial frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest installed capacity base, while Indonesia and Vietnam drive new procurement as landfill constraints tighten across Southeast Asian megacities.
China
The Yangtze River Delta cluster generates sufficient waste volume to justify 800-tonne-per-day grate installations. MEE enforcement of GB dioxin standards is forcing replacement cycles for subscale incinerators commissioned during the 2010-2015 expansion wave. Shanghai and surrounding Jiangsu municipalities anchor technology upgrade demand.
Indonesia
Greater Jakarta's urban density exceeds sanitary landfill capacity, compressing procurement timelines for thermal treatment infrastructure. National regulations on municipal waste management are tightening landfill diversion mandates for provincial capitals. First-mover opportunities concentrate in outer island cities lacking any existing incineration capacity.
Germany
District heating networks in the Ruhr and Bavaria integrate waste-to-energy for operational continuity across heating seasons. EU Industrial Emissions Directive BAT conclusions mandate continuous emission monitoring upgrades. Hamburg and Berlin facilities are deploying integrated digital twin platforms for predictive compliance management.
Japan
Industrial parks in the Kansai and Chubu regions pilot plasma gasification for hazardous and medical waste streams. METI emission guidelines drive mercury and dioxin control investments. Nagoya and Osaka anchor captive on-site energy system deployment unifying waste destruction with syngas production.
United States
Mid-Atlantic municipalities anchor long-term service contract structures for waste-to-energy capacity. EPA standards under the Clean Air Act shape facility permitting timelines and emission control investments. New York and New Jersey procurement cycles favor integrated operators with decades of operational continuity.
Municipal Solid Waste Incineration Market Competitive Landscape
European integrated waste service providers anchor one tier; East Asian equipment specialists hold manufacturing concentration for high-specification refractory and boiler systems. Market structure consolidates around concession-based municipal contracting in Western Europe and North America, while equipment supply fragments across German, Japanese, and Chinese fabricators. Three archetypes dominate: integrated platform operators, emission control retrofit specialists, and grate system manufacturers. Competitive dynamics center on long-term service agreement capture and carbon capture retrofit positioning.
Within the integrated platform tier, Veolia Environment S.A. and Suez Environment S.A. exemplify concession-based operators leveraging municipal procurement relationships across French and German cycles. Covanta Holding Corporation occupies a position among North American service contract anchors. Babcock & Wilcox Enterprises, Inc. sits within the retrofit specialist archetype, while Hitachi Zosen Corporation and Martin GmbH represent equipment manufacturing concentration.
| Leading Market Players |
|---|
| Veolia Environment S.A. |
| Suez Environment S.A. |
| Covanta Holding Corporation |
| Hitachi Zosen Corporation |
| China Everbright International Limited |
| Keppel Seghers |
| Martin GmbH |
| Babcock & Wilcox Enterprises, Inc. |
| Wheelabrator Technologies Inc. |
| Others |
Supply & Pricing Matrix
Carbon capture retrofit integration with existing grate fleets simultaneously raises project capital intensity and concentrates procurement power among German and Japanese refractory suppliers capable of meeting amine scrubber specifications. MEE enforcement of GB dioxin standards in China's Yangtze River Delta is compressing technology replacement timelines, forcing municipal buyers to absorb premium pricing for compliant systems or face permit revocation.
Pricing Analysis
Volume-based municipal concessions split from margin-rich carbon capture retrofits as distinct commercial segments. Project-based long-term contracting dominates municipal procurement, with 15-20 year availability guarantees bundling equipment, maintenance, and residue management. Price differentiation hinges on emission control stringency and district heating integration depth. Cost compression in standard grate systems is intensifying because Chinese fabricators are scaling 400-800 tonne-per-day capacity. Industrial facilities co-combusting RDF exhibit lowest price sensitivity due to EU ETS carbon cost pass-through mechanics.
Supply Chain Analysis
Reverse-logistics flows for spent refractory and air pollution control residue are creating specialized beneficiation service layers between operators and cement kilns. High-alumina brick manufacturing concentrates in Germany and Japan, while grate system fabrication localizes in China and South Korea. Raw material dependencies span bauxite for refractory, activated carbon for dioxin adsorption, and ammonia reagents for SCR systems. Single-source vulnerability concentrates in German suppliers of specialty refractory formulations. Distribution runs through EPC contractors integrating equipment packages with municipal concession structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform operators as MEE dioxin enforcement and EU BAT conclusions force subscale incinerators into costly upgrade-or-exit decisions.
For Market Incumbents: To counter margin erosion from Chinese equipment fabricators, anchor municipal relationships through 20-year service contracts bundling residue disposal and emission compliance. Acquire specialized refractory maintenance capabilities to capture aftermarket revenue streams locked out of new equipment sales. For New Entrants and Emerging Players: Municipal procurement officers in Indonesia's outer island provincial capitals represent the most penetrable buyer segment, with zero incumbent thermal treatment capacity and compressed landfill diversion timelines. Position modular grate systems with rapid deployment schedules against conventional EPC timelines. Partner with Japanese plasma gasification pilots to license hazardous waste co-treatment technology for industrial park captive energy systems. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated operators with district heating concessions and carbon capture retrofit positioning. Long-term viability favors platforms with operational continuity across heating seasons and EU ETS credit generation capacity. Monitor MEE enforcement intensity in secondary Chinese cities as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Integration | Post-combustion amine scrubbing qualifies EU facilities for ETS credits under Green Deal frameworks. |
| Long-Term Service Agreement Expansion | 15-20 year municipal contracts displace equipment-only sales in French and Italian procurement cycles. |
| Modular System Deployment | Standardized grate units address first-mover opportunities in Indonesian outer island cities lacking thermal capacity. |
| Digital Twin Platform Investment | Predictive emission management reduces compliance risk for German and Dutch facilities under BAT conclusions. |
| RDF Co-Combustion Partnership | Cement kiln fuel supply agreements diversify revenue for waste management companies under landfill diversion mandates. |
Research Methodology
Independent corroboration across plant engineering directors, municipal procurement officers, and emission control specialists underwrites the qualitative findings in this study. Primary interviews with EPC contractors, refractory supply managers, and district heating network operators combined with secondary validation from EPA permitting databases, MEE emission filings, and EU ETS registry data. Bottom-up project pipeline tracking triangulates against top-down capacity installation estimates across the analysis window.
Rate-of-change decomposition separates technology replacement cycles from greenfield additions across technology type, end user category, emission control architecture, and service contract structure. CAGRs derive from segment-level volume trajectories weighted by regional regulatory enforcement intensity. Forecast inputs incorporate MEE dioxin standard phase-in schedules and EU Industrial Emissions Directive BAT conclusion adoption timelines.
Caveats apply where MEE enforcement variability or EU ETS credit price volatility could materially shift the outlook. Forecasts reflect assumptions about grid interconnection queue resolution and refractory supply chain stability. Practitioners should monitor provincial landfill diversion mandate announcements in Indonesia and carbon capture subsidy clarity under EU Green Deal implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market