
 Construction and Demolition Waste Management Market | 2026-2036
Construction and Demolition Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Construction and Demolition Waste Management Market Intelligence
Germany's Ruhr industrial cluster is fragmenting as new sorting and recycling yards multiply across the former mining region. Waste Management Inc. leverages its North American landfill network to anchor long-term service contracts with municipal demolition authorities. Veolia sustains integrated collection-to-recovery operations across European urban cores. Republic Services competes through direct-haul density in fast-growing Sun Belt metropolitan areas.
Construction and demolition waste management encompasses the systematic collection, transport, processing, and disposal of debris generated from building construction, renovation, and demolition activities, with concrete typically comprising 40-50 percent of total debris mass by weight. The practice employs mechanical sorting, magnetic separation, and crushing technologies to recover usable aggregates, metals, and wood fiber for reintroduction into construction supply chains. Concrete recovery dominates volume flows across recycling stations due to the material's high recoverability and established end-markets in road base and new aggregate applications. Service type segmentation shows industrial demolition generating the highest per-project waste tonnage, while commercial renovation produces more frequent, smaller-volume collection events that favor drop-off center utilization.
The US EPA enforces landfill diversion targets under the Resource Conservation and Recovery Act that mandate tracking of construction debris streams above specified volume thresholds. Germany's Federal Environment Agency implements closed-loop recycling quotas through the Kreislaufwirtschaftsgesetz circular economy law, restricting landfill disposal of untreated demolition materials. China's Ministry of Ecology and Environment enforces dual carbon goals that penalize high-emission disposal methods while incentivizing material recovery infrastructure. Stakeholders must monitor regulatory enforcement intensity across jurisdictions to align capital deployment with shifting compliance cost structures.
Market Dynamics
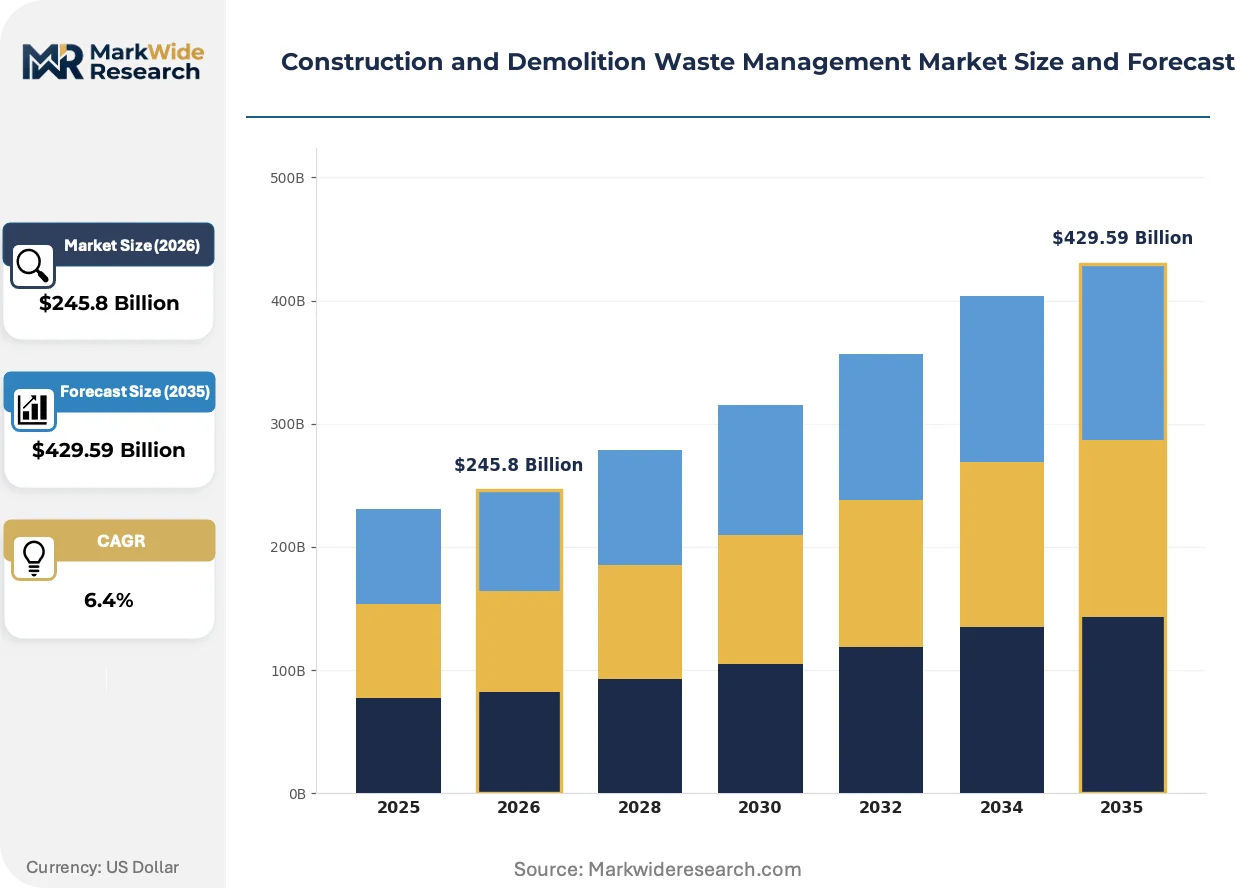
Landfill diversion mandates are compressing disposal capacity while forcing capital toward mechanical sorting and aggregate recovery infrastructure. Regulatory enforcement intensity varies sharply by jurisdiction, creating arbitrage opportunities for operators with multi-country compliance capabilities.
Growth Catalysts
- Kreislaufwirtschaftsgesetz recycling quotas:Germany's circular economy law mandates closed-loop recovery rates for demolition debris, diverting material flows from landfill toward certified processing facilities.
- Urban densification in Mumbai:Redevelopment of informal settlements generates concentrated demolition volumes that sustain dedicated collection fleet deployments and long-term service contracts.
- Concrete crushing technology:Mobile jaw crusher units enable on-site aggregate recovery, reducing haul distances and opening road base supply to mid-scale demolition contractors.
Market Restraints
- Landfill tipping fee volatility:Regional disposal price swings distort recycling economics when landfill capacity temporarily expands in Texas and Florida markets.
- Contaminated wood fiber:Treated lumber containing creosote or lead paint resists cost-effective separation, limiting recovered wood end-uses to low-value fuel applications.
- Transport fuel cost exposure:Diesel price spikes directly compress margins for haul-dependent operators serving dispersed rural demolition sites.
Strategic Opportunities
- India's Smart Cities Mission:Urban renewal funding streams in Ahmedabad and Pune create demand for integrated debris collection and recycled aggregate supply contracts.
- Digital weight tracking systems:RFID-tagged roll-off containers enable real-time fill monitoring and dynamic routing optimization for fleet operators.
- Cross-laminated timber recovery:Emerging deconstruction practices target engineered wood products from commercial demolition for resale to modular construction suppliers.
Industry Challenges
- Certified aggregate testing delays:Laboratory turnaround times for recovered concrete quality verification slow inventory release and compress working capital cycles.
- Asbestos identification skill gaps:Licensed surveyor shortages in fast-growth markets extend pre-demolition inspection timelines and stall project starts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction and Demolition Waste Management Market |
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $429.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Concrete, Wood, Metals, Plastics Collection Method: Drop-off Centers, Curbside Pickup, Recycling Stations, Direct Haul Disposal Method: Landfill, Recycling, Incineration, Composting Service Type: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Waste Management Inc., Keltbray, Bechtel, Clean Harbors Inc., Brandenburg Industrial Service Co., AECOM, Republic Services, Waste Connections, Veolia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction and Demolition Waste Management Market Strategic Shifts & Innovations
Processing technology is migrating from fixed-plant centralization toward distributed, mobile configurations that follow demolition activity. Regulatory data mandates and buyer transparency requirements accelerate digital adoption across collection and recovery operations.
Optical sorting systems are migrating from pilot installations to standard equipment at mid-capacity recycling yards. European operators in the Ruhr cluster deploy near-infrared spectroscopy to separate plastics and wood fractions at throughput rates exceeding manual sorting by an order of magnitude. This capability is compressing residual waste volumes sent to landfill and qualifying more facilities for green building certification credits.
China's Ministry of Ecology and Environment enforces dual carbon goals that penalize high-emission disposal methods while incentivizing material recovery infrastructure. Demolition contractors in Shanghai and Beijing now face carbon intensity audits that factor transportation and processing emissions into project approvals. This pressure is accelerating adoption of electric haul trucks and on-site crushing to reduce scope emissions.
Building developers increasingly specify recovered content quotas in procurement contracts for new construction. General contractors in California and New York must document aggregate sourcing from certified recycling facilities to meet municipal green building mandates. This specification shift is concentrating demand toward vertically integrated operators with captive recycling capacity and third-party certification.
Construction and Demolition Waste Management Market Segmentation
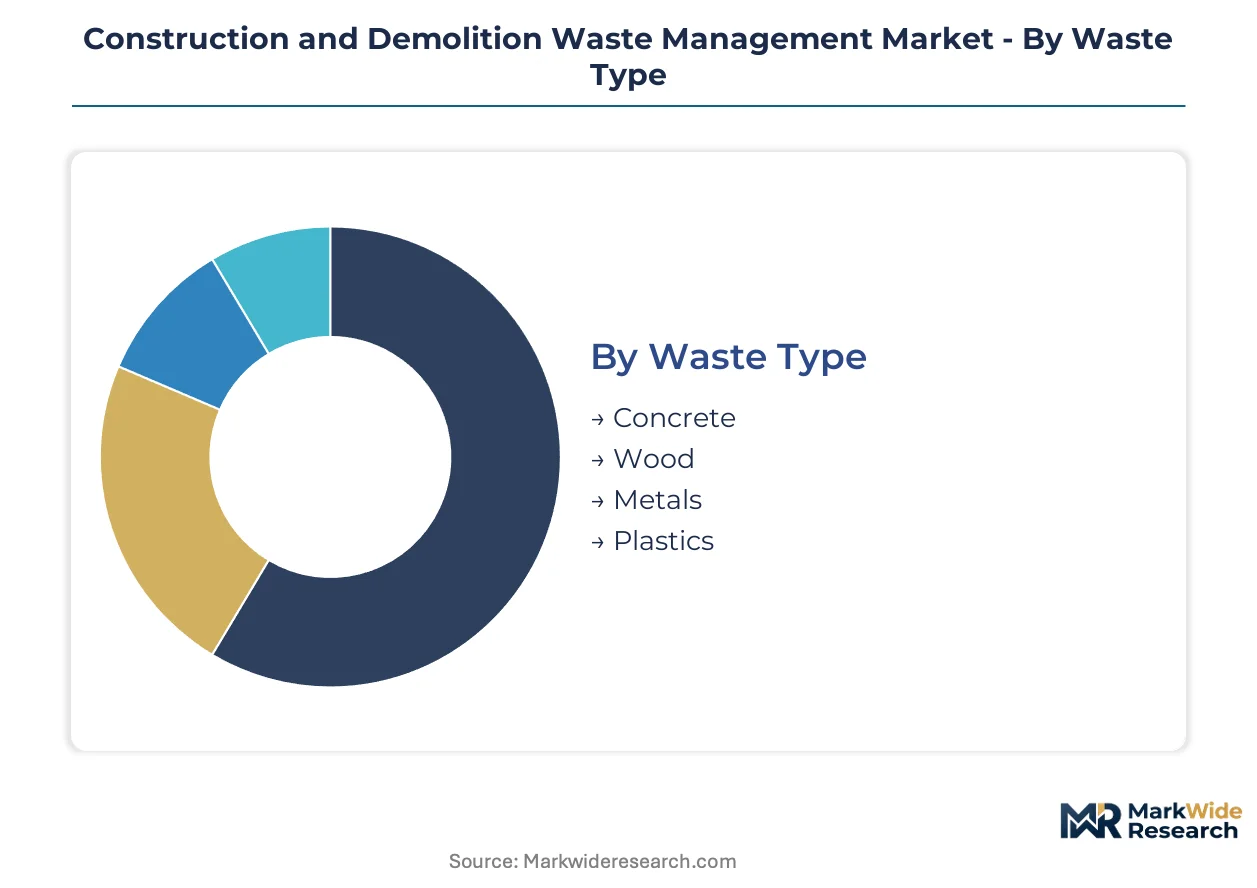
Segmentation in construction and demolition waste management reveals how material composition, logistics configuration, and customer scale dictate capital deployment and margin structure. Operators align processing technology and fleet density to specific debris streams and collection economics.
Waste Type:
The use-case spectrum spans structural demolition debris with high recoverability to contaminated fractions requiring specialized handling protocols.
- Concrete:Comprising 40-50 percent of total debris mass, concrete recovery employs mobile jaw crushers to produce road base and aggregate feedstock. Demand concentrates in urban redevelopment corridors where volume density justifies on-site processing infrastructure.
- Wood:Clean dimensional lumber commands premium resale values to modular construction suppliers, while treated lumber containing creosote or lead paint faces restricted end-uses. California and New York procurement mandates are accelerating certified deconstruction practices.
- Metals:Ferrous and non-ferrous fractions recover through magnetic and eddy-current separation, with steel rebar and copper piping tracking commodity price volatility.
- Plastics:PVC, HDPE, and mixed polymer streams require optical sorting investment that only large-scale facilities amortize effectively.
The dominant share belongs to Concrete, while Wood is closing the gap fastest as green building specifications tighten recovered content requirements.
Collection Method:
Cost tier differentiation separates capital-light access points from integrated fleet operations requiring density economics.
- Direct Haul:Dedicated roll-off container service captures high-volume commercial and industrial demolition contracts through long-term municipal agreements. Republic Services deploys this model across Sun Belt metropolitan areas where project frequency sustains route optimization.
- Drop-off Centers:Self-service facilities serve residential renovation and small contractor segments with lower per-transaction revenue but minimal fleet capital. Mumbai's informal settlement redevelopment has multiplied dedicated collection points.
- Recycling Stations:Fixed-plant facilities aggregate mixed debris for mechanical sorting and certification testing, concentrating in Germany's Ruhr industrial cluster.
- Curbside Pickup:Scheduled residential collection operates in jurisdictions with mandatory debris separation ordinances, typically bundling with municipal solid waste contracts.
Direct Haul commands the premium tier through contract duration and volume guarantees, though Recycling Stations are expanding most quickly as diversion mandates tighten.
Disposal Method:
Application maturity determines regulatory exposure and long-term asset viability across processing pathways.
- Recycling:Mechanical sorting, crushing, and aggregate recovery divert material from landfill while qualifying for green building certification credits. China's Ministry of Ecology and Environment dual carbon goals are accelerating infrastructure investment.
- Landfill:EPA demolition debris rules and state-level capacity constraints compress disposal availability, with tipping fee volatility in Texas and Florida distorting regional economics.
- Incineration:Waste-to-energy applications concentrate contaminated wood fractions with limited material recovery potential, facing emissions scrutiny under tightening air quality standards.
- Composting:Organic debris from land clearing and vegetation removal serves niche landscaping and soil amendment markets with localized demand.
Recycling holds the structural advantage under tightening diversion mandates, while Landfill retains residual share for contaminated fractions lacking cost-effective alternatives.
Service Type:
Customer scale segmentation aligns contract structure, equipment specification, and working capital intensity to project economics.
- Industrial:Large-scale demolition of manufacturing facilities, power plants, and infrastructure generates concentrated tonnage requiring specialized asbestos abatement and heavy equipment fleets. Licensed surveyor shortages in fast-growth markets extend pre-demolition timelines.
- Commercial:Office renovation and retail fit-out produce frequent, smaller-volume events favoring drop-off center utilization and flexible scheduling. Digital weight tracking systems with RFID-tagged containers are penetrating this segment fastest.
- Residential:Single-family construction and renovation debris flows through municipal contracts or homeowner self-haul, with seasonal demand patterns and lower per-project values.
- Institutional:Schools, hospitals, and government buildings face extended procurement cycles and prevailing wage requirements that favor established operators with bonding capacity.
Industrial commands the highest per-project revenue concentration, though Commercial is gaining share fastest as urban densification accelerates renovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States contractors prioritize landfill diversion through mobile crushing circuits, while German operators emphasize closed-loop aggregate certification. Chinese municipalities enforce carbon-intensity audits that reshape hauling logistics. Indian urban renewal concentrates debris flows in dense corridors that favor dedicated collection fleets.
United States
Industrial demolition in Houston and Phoenix generates concentrated concrete volumes that sustain on-site mobile jaw crusher deployments. The EPA enforces Resource Conservation and Recovery Act tracking thresholds for debris streams above specified volumes. Sun Belt metropolitan expansion concentrates Republic Services' direct-haul density in fast-growing corridors.
Germany
Ruhr industrial cluster redevelopment multiplies sorting yards across the former mining region as recycling infrastructure fragments geographically. The Federal Environment Agency implements Kreislaufwirtschaftsgesetz circular economy quotas that restrict landfill disposal of untreated materials. Near-infrared spectroscopy installations at mid-capacity yards now separate plastics and wood fractions at throughput rates exceeding manual sorting.
China
Shanghai and Beijing demolition contractors face carbon intensity audits that factor transportation and processing emissions into project approvals. The Ministry of Ecology and Environment enforces dual carbon goals that penalize high-emission disposal methods. Electric haul truck adoption accelerates in Yangtze River Delta urban cores to reduce scope emissions under tightening audits.
India
Mumbai's informal settlement redevelopment generates concentrated demolition volumes that sustain dedicated collection fleet deployments and long-term service contracts. Smart Cities Mission funding streams in Ahmedabad and Pune create demand for integrated debris collection and recycled aggregate supply. Urban densification concentrates project frequency in western metropolitan corridors.
United Kingdom
London commercial renovation produces frequent, smaller-volume collection events that favor drop-off center utilization and flexible scheduling. Cross-laminated timber recovery from commercial demolition targets resale to modular construction suppliers under emerging deconstruction practices. Digital weight tracking systems with RFID-tagged containers penetrate the commercial segment fastest in southeastern urban cores.
Construction and Demolition Waste Management Market Key Industry Players
Capability concentration sits with specialized deconstruction and certified aggregate testing operators; scale advantage sits with integrated waste management networks spanning collection through landfill disposal. The market structures around three tiers: national landfill networks anchoring municipal contracts, regional recycling specialists capturing green building specification flows, and equipment-leasing firms enabling contractor mobility. Dominant competitive moves include fleet densification in high-frequency urban corridors and backward integration into aggregate certification testing capacity.
Among North American integrated operators, Waste Management Inc. and Republic Services occupy positions anchored by landfill network density, while Veolia exemplifies the European model of integrated collection-to-recovery operations across urban cores. Clean Harbors Inc. represents the specialized environmental services archetype targeting contaminated fractions requiring licensed handling protocols.
| Leading Market Players |
|---|
| Waste Management Inc. |
| Keltbray |
| Bechtel |
| Clean Harbors Inc. |
| Brandenburg Industrial Service Co. |
| AECOM |
| Republic Services |
| Waste Connections |
| Veolia |
| Others |
Cost & Logistics Intelligence
Crusher equipment manufacturing concentrates in Germany, Italy, and China, anchoring margin pools with demolition contractors who operate mobile processing fleets rather than fixed-plant recyclers. Long-term service contracts with municipal authorities command pricing premiums that spot-market haulers cannot match, while diesel cost exposure compresses margins for operators without fleet electrification pathways.
Pricing Analysis
Long-term offtake agreements with municipal demolition authorities dominate the premium pricing tier, locking in volume guarantees that insulate operators from landfill tipping fee volatility in Texas and Florida markets. Price differentiation separates certified aggregate suppliers meeting green building procurement mandates from uncertified competitors serving low-spec road base applications. Cost compression runs through rural haul-dependent segments as diesel price spikes directly erode per-ton margins. Small residential renovation contractors exhibit highest price sensitivity, favoring drop-off center utilization over dedicated container service.
Supply Chain Analysis
Concrete debris feedstock draws from urban redevelopment corridors in Mumbai, Houston, and Shanghai where densification concentrates demolition volumes for efficient collection routing. Magnetic separation equipment and optical sorting systems rest on specialized component supply from German and Japanese precision engineering clusters. Single-source vulnerability concentrates in mobile jaw crusher manufacturing where limited qualified suppliers extend equipment lead times. Distribution runs through integrated operators with captive landfill networks and third-party certified recycling facilities serving general contractor procurement mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction and demolition waste management is entering a cyclical recovery phase as urban densification accelerates renovation cycles across metropolitan corridors. Infrastructure spending on Smart Cities Mission projects in India and carbon-intensity audits in China are compressing disposal capacity while forcing capital toward recovery infrastructure.
For Market Incumbents: Insulate landfill-dependent revenue streams by accelerating backward integration into certified aggregate testing capacity, capturing green building specification flows that municipal mandates are concentrating toward vertically integrated operators. Defend against mobile crushing technology disruption by anchoring long-term municipal contracts with density-optimized direct-haul fleets in Sun Belt metropolitan expansion corridors.
For New Entrants and Emerging Players: Secondary Indian metropolitan areas beyond Mumbai and Delhi present underpenetrated demand for integrated debris collection and recycled aggregate supply contracts under Smart Cities Mission funding. Target commercial renovation segments with digital weight tracking systems and RFID-tagged container deployments that penetrate fastest where project frequency favors flexible scheduling over industrial-scale tonnage guarantees.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized deconstruction operators with licensed asbestos abatement capabilities and certified aggregate testing infrastructure, as regulatory enforcement intensity tightens compliance cost structures across jurisdictions. Monitor carbon intensity audit expansion beyond Shanghai and Beijing as the inflection signal for electric haul truck and on-site crushing adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Crushing Fleet Expansion | On-site aggregate recovery reduces haul distances and opens road base supply to mid-scale demolition contractors. |
| Certified Aggregate Testing Investment | Green building procurement mandates in California and New York concentrate demand toward third-party certified recycling facilities. |
| Electric Haul Truck Deployment | Carbon intensity audits in Chinese urban cores accelerate fleet electrification to reduce scope emissions under tightening regulations. |
| Digital Weight Tracking Integration | RFID-tagged roll-off containers enable real-time fill monitoring and dynamic routing optimization for fleet operators. |
| Cross-Laminated Timber Recovery | Engineered wood product deconstruction targets resale to modular construction suppliers under emerging commercial demolition practices. |
Research Approach
A standing panel of demolition contractors, municipal waste authority procurement officers, aggregate testing laboratory managers, and mobile crushing equipment distributors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against EPA demolition debris tracking data, Kreislaufwirtschaftsgesetz compliance filings, and Ministry of Ecology and Environment carbon audit disclosures. Bottom-up volume estimates from individual project data triangulated against top-down infrastructure spending flows from national urban renewal programs.
Scenario-bracketing around landfill diversion mandate enforcement intensity and diesel price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include waste type composition, collection method configuration, disposal pathway certification status, and service type project scale. CAGRs derived from historical tonnage flow analysis and infrastructure pipeline tracking, with specific inputs from mobile crushing equipment deployment rates and green building specification adoption curves.
Practitioners should monitor regulatory enforcement intensity shifts and carbon audit expansion timelines for early signals of forecast revision. Cross-checking against municipal procurement database trends and certified recycling facility capacity utilization rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market