
 Nutrient Recycling Market | 2026-2036
Nutrient Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Nutrient Recycling Market Analytics
Food-grade phosphorus recovery specifications are reorganizing buyer expectations across the nutrient recycling value chain. Ostara Nutrient Recovery Technologies Inc. leverages its struvite crystallization platform to dominate municipal wastewater partnerships in North America. Veolia sustains integrated operations spanning collection, processing, and agricultural distribution across multiple European countries. Nutrien anchors its position through backward integration into mining and recycling streams, controlling both conventional and recovered nutrient supply.
Nutrient recycling encompasses the recovery and conversion of nitrogen, phosphorus, and potassium from organic waste streams into reusable agricultural inputs, typically achieving phosphorus concentrations of 10-20% P2O5 equivalent in crystalline struvite products. The process serves primarily to close elemental loops in food systems and reduce dependency on mined phosphate rock and energy-intensive nitrogen fixation. Anaerobic digestion leads technology deployment due to its co-production of biogas energy, while composting occupies the largest volume position in decentralized agricultural settings. Liquid nutrients represent the fastest-expanding product type as precision agriculture equipment demands pumpable, uniform inputs with predictable NPK ratios.
The EPA administers biosolids land-application standards under 40 CFR Part 503, while the EU Fertilizing Products Regulation sets CE-marking requirements for recovered nutrient products entering European commerce. Germany's Sewage Sludge Ordinance mandates phosphorus recovery from wastewater treatment plants exceeding 50,000 population equivalents, directly creating mandated supply volumes. Stakeholders must monitor how diverging national contamination limits for heavy metals and pathogens shape cross-border trade eligibility for recycled fertilizers.
Market Dynamics
Synthetic fertilizer price volatility is forcing agricultural buyers to secure alternative nutrient supplies through long-term offtake contracts with struvite crystallization facilities and anaerobic digestion operators.
Growth Catalysts
- Germany's Sewage Sludge Ordinance:Mandated phosphorus recovery from wastewater treatment plants exceeding 50,000 population equivalents creates guaranteed feedstock supply for crystallization facilities.
- Precision agriculture equipment:Liquid nutrient formulations with predictable NPK ratios integrate directly with variable-rate application systems, pulling demand toward pumpable recovered products.
- Anaerobic digestion:Co-production of biogas energy improves project economics for nutrient recovery investments across agricultural waste processing sites.
Market Restraints
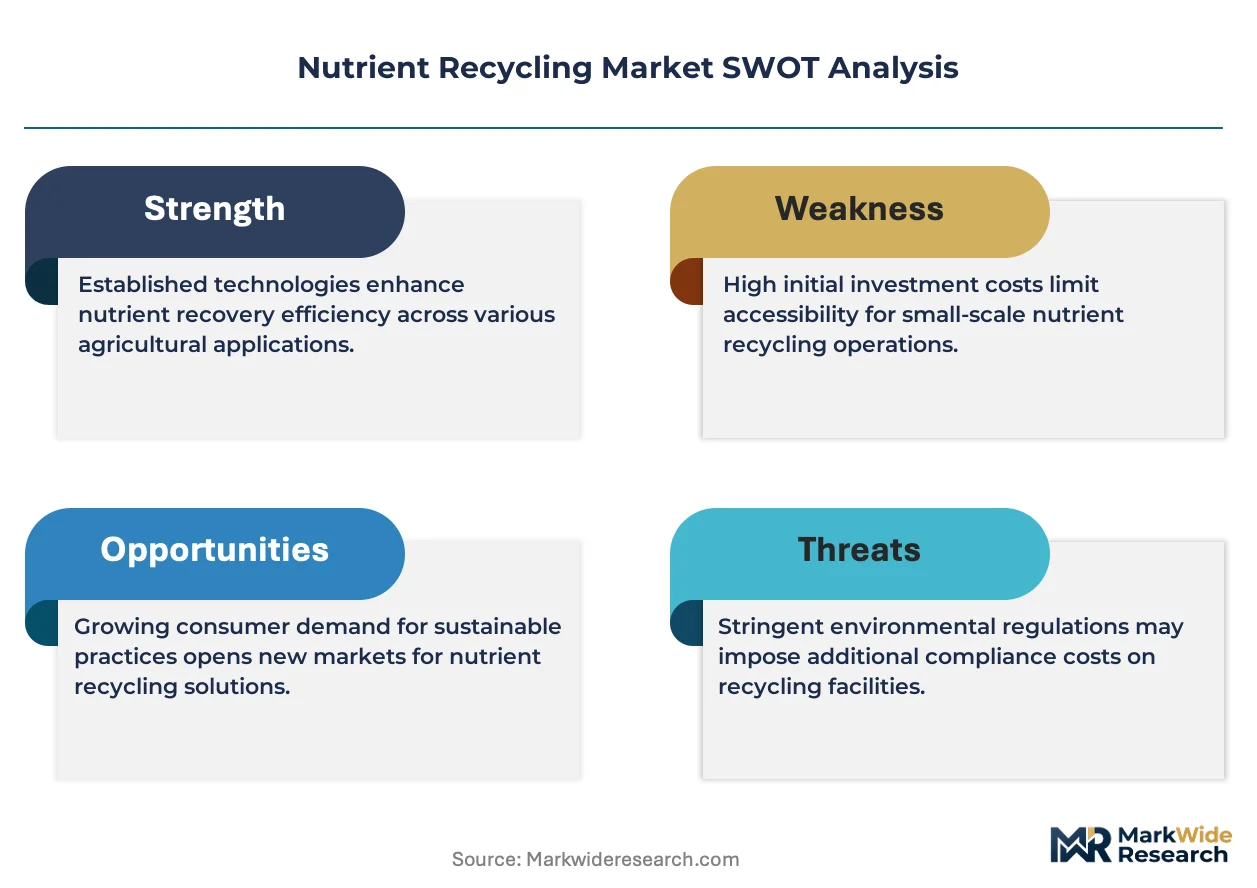
- Heavy metal contamination limits:Diverging national thresholds for cadmium and lead in recovered fertilizers fragment cross-border trade eligibility within the EU.
- Mined phosphate rock concentration:Moroccan and Chinese state-controlled suppliers control conventional phosphorus pricing, compressing margins for recovered nutrient producers.
- Pathogen inactivation standards:Thermal hydrolysis requirements for Class A biosolids add energy costs that disadvantage smaller composting operations.
Strategic Opportunities
- CE-marking under EU Fertilizing Products Regulation:Harmonized certification enables recovered nutrient products to access 27-country agricultural markets without national re-registration.
- Hydroponic cultivation systems:Closed-loop greenhouse operations in the Netherlands and Spain demand sterile, water-soluble nutrient solutions that crystalline struvite can supply.
- Blockchain traceability:Digital nutrient passports tracking origin from wastewater to field satisfy food processor ESG verification requirements.
Industry Challenges
- Process engineering talent scarcity:Struvite crystallization requires specialized chemical engineering expertise that agricultural equipment manufacturers rarely retain in-house.
- Legacy fertilizer dealer networks:Conventional distribution relationships with synthetic suppliers block shelf access for recovered nutrient products at farm retail level.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutrient Recycling Market |
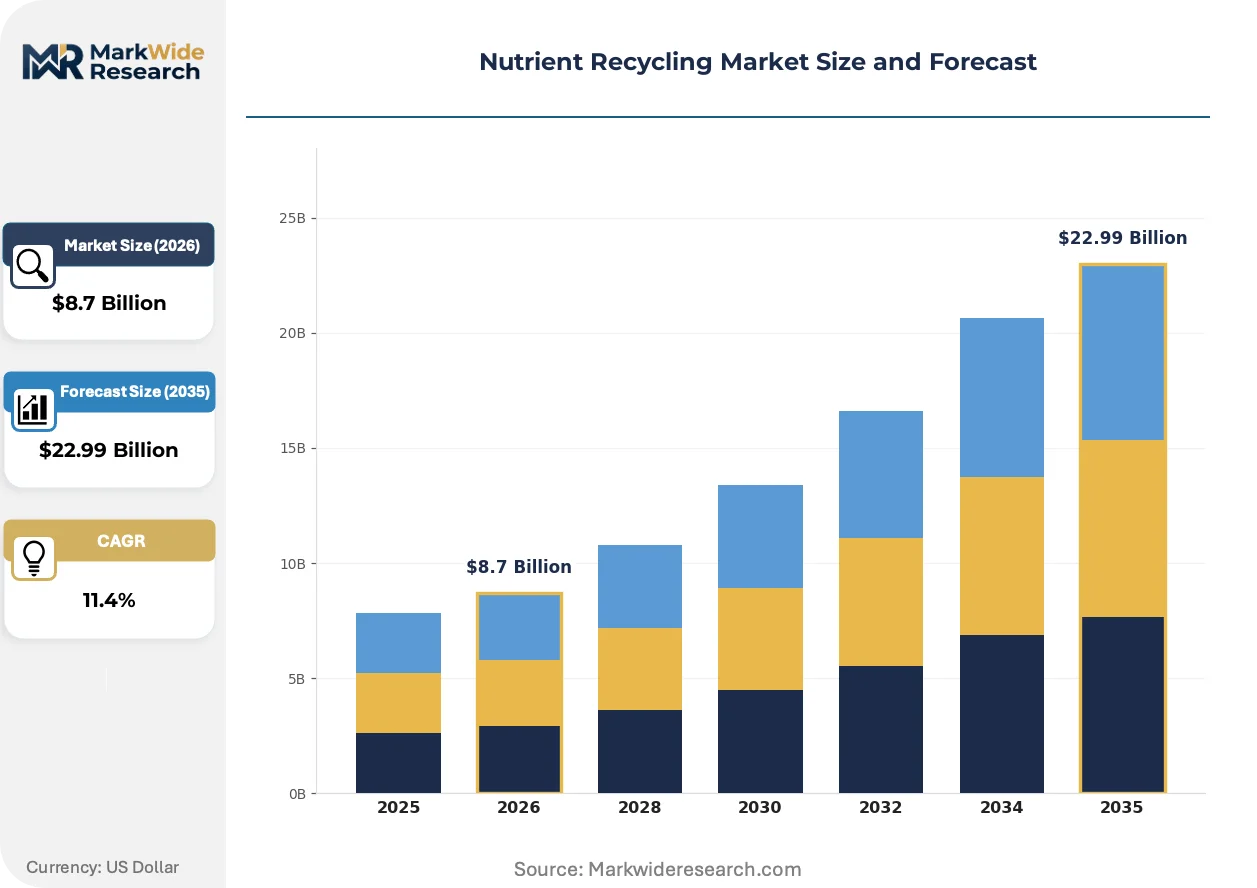
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Aerobic Digestion, Anaerobic Digestion, Composting, Fermentation End Use: Agriculture, Aquaculture, Horticulture, Landscaping Product Type: Organic Fertilizers, Soil Amendments, Biochar, Liquid Nutrients Process Type: Thermochemical, Biological, Chemical, Physical |
| Companies Covered | Ostara Nutrient Recovery Technologies Inc., Nutrient Recovery & Upcycling LLC, Cambi AS, Veolia, Suez, BioHiTech Global Inc., DVO Inc., Nutrien, EasyMining, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutrient Recycling Market Evolving Landscape
Electrochemical nutrient recovery is compressing capital requirements for phosphorus extraction while membrane filtration advances enable nitrogen concentration from dilute waste streams without thermal energy inputs.
Struvite crystallization reactors with real-time crystal size control are displacing conventional chemical precipitation systems in municipal wastewater partnerships. Operators in Denmark and Sweden have adopted continuous-flow designs that reduce chemical dosing variation. This displacement is compressing payback periods for phosphorus recovery investments below seven years.
REACH registration requirements for recovered nutrient intermediates are forcing crystallization facilities to document substance identity and hazard profiles before EU market entry. The European Chemicals Agency's 2023 guidance on UVCB substances has triggered reformulation efforts at multiple struvite producers. Agricultural cooperatives in France and Belgium now require REACH-compliant safety data sheets as procurement preconditions.
Buyers are consolidating procurement through multi-year supply agreements that bundle nutrient delivery with soil testing services. Large-scale arable farming operations in Germany and Poland are bypassing traditional agricultural merchants to contract directly with anaerobic digestion facility operators. This channel compression is most visible in the livestock-dense regions of Lower Saxony and Mecklenburg-Vorpommern.
Nutrient Recycling Market Segmentation
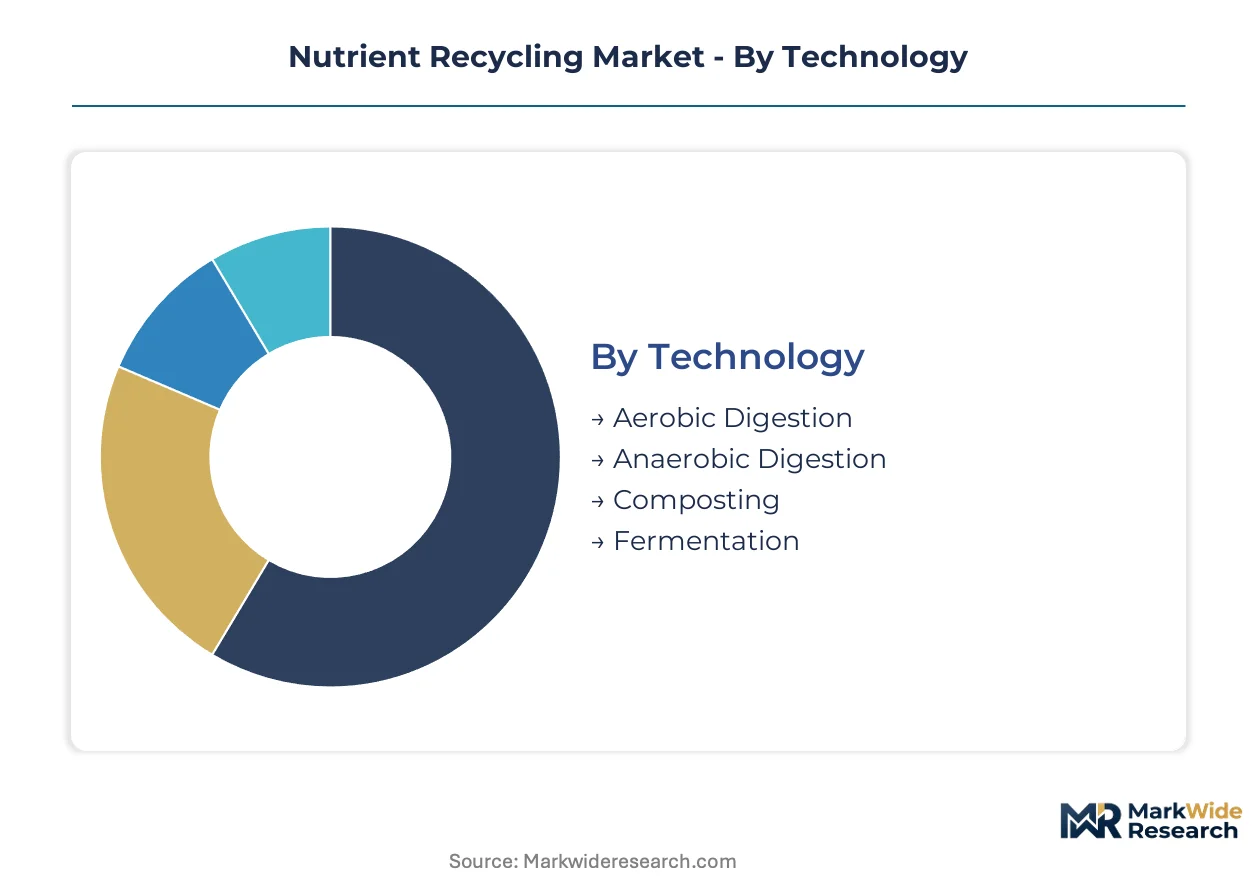
Nutrient recycling markets fragment across technology maturity, end-use sophistication, and product physical state. Channel access for crystalline struvite differs fundamentally from compost distribution. Buyers in Germany and the Netherlands sort across these dimensions based on equipment compatibility and regulatory certification status.
Technology:
Anaerobic digestion facilities contract directly with arable farming cooperatives in Lower Saxony, while composting operations move through municipal waste channels. Struvite crystallization units require specialized chemical engineering partnerships that bypass conventional agricultural merchants.
- Anaerobic Digestion:Co-digestion of agricultural residues and food waste produces biogas alongside nitrogen-rich digestate. German livestock operations in Mecklenburg-Vorpommern favor this route for energy revenue stacking. Precision agriculture equipment in Poland pulls digestate demand for variable-rate application systems.
- Composting:Open-windrow and in-vessel systems process green waste and source-separated organics into stable soil amendments. French agricultural cooperatives procure compost through regional biowaste collection contracts. Pathogen inactivation standards under EU Fertilizing Products Regulation shape facility scale decisions.
- Aerobic Digestion:Accelerated biological oxidation of sludge streams in municipal wastewater plants.
- Fermentation:Controlled microbial conversion of organic substrates into concentrated nutrient extracts.
By volume, composting leads. By growth pace, anaerobic digestion is climbing the fastest.
End Use:
Application sophistication determines pricing power and certification burden. Field-scale agriculture accepts bulk compost under national fertilizer laws. Controlled-environment horticulture demands sterile, water-soluble formulations with documented heavy metal thresholds.
- Agriculture:Broadacre cereal and oilseed producers in Germany apply recovered nutrients as phosphate substitutes amid synthetic fertilizer price volatility. Poland's arable farming sector contracts directly with anaerobic digestion operators, bypassing legacy dealer networks. Long-term offtake agreements with struvite crystallization facilities secure supply certainty.
- Horticulture:Greenhouse tomato and pepper cultivation in the Netherlands and Spain requires pumpable liquid nutrients with predictable NPK ratios. Hydroponic systems demand sterile, water-soluble inputs that crystalline struvite can supply. CE-marking under EU Fertilizing Products Regulation enables cross-border procurement.
- Aquaculture:Recirculating aquaculture systems integrate nutrient recovery from fish effluent.
- Landscaping:Municipal parks and golf courses utilize composted green waste for soil conditioning.
Agriculture dominates tonnage. Horticulture commands the steepest expansion trajectory through precision greenhouse expansion.
Product Type:
Physical state governs logistics economics and equipment compatibility. Solid products move through conventional fertilizer distribution. Liquid formulations require specialized storage and pumping infrastructure that only large-scale operations justify.
- Liquid Nutrients:Pumpable formulations with uniform NPK ratios integrate directly with precision agriculture equipment. Variable-rate application systems in German arable farming pull demand toward recovered liquid products. Real-time crystal size control in struvite crystallization reactors enables consistent nutrient concentration.
- Organic Fertilizers:Pelletized and granulated products from anaerobic digestate compete with conventional fertilizers on phosphate equivalent pricing.
- Soil Amendments:Compost and digestate products improve soil organic matter and water retention capacity.
- Biochar:Carbon-stabilized nutrient carriers from thermochemical processing of woody biomass.
Liquid nutrients gain share fastest in equipment-intensive farming regions. Organic fertilizers retain volume leadership through broad compatibility.
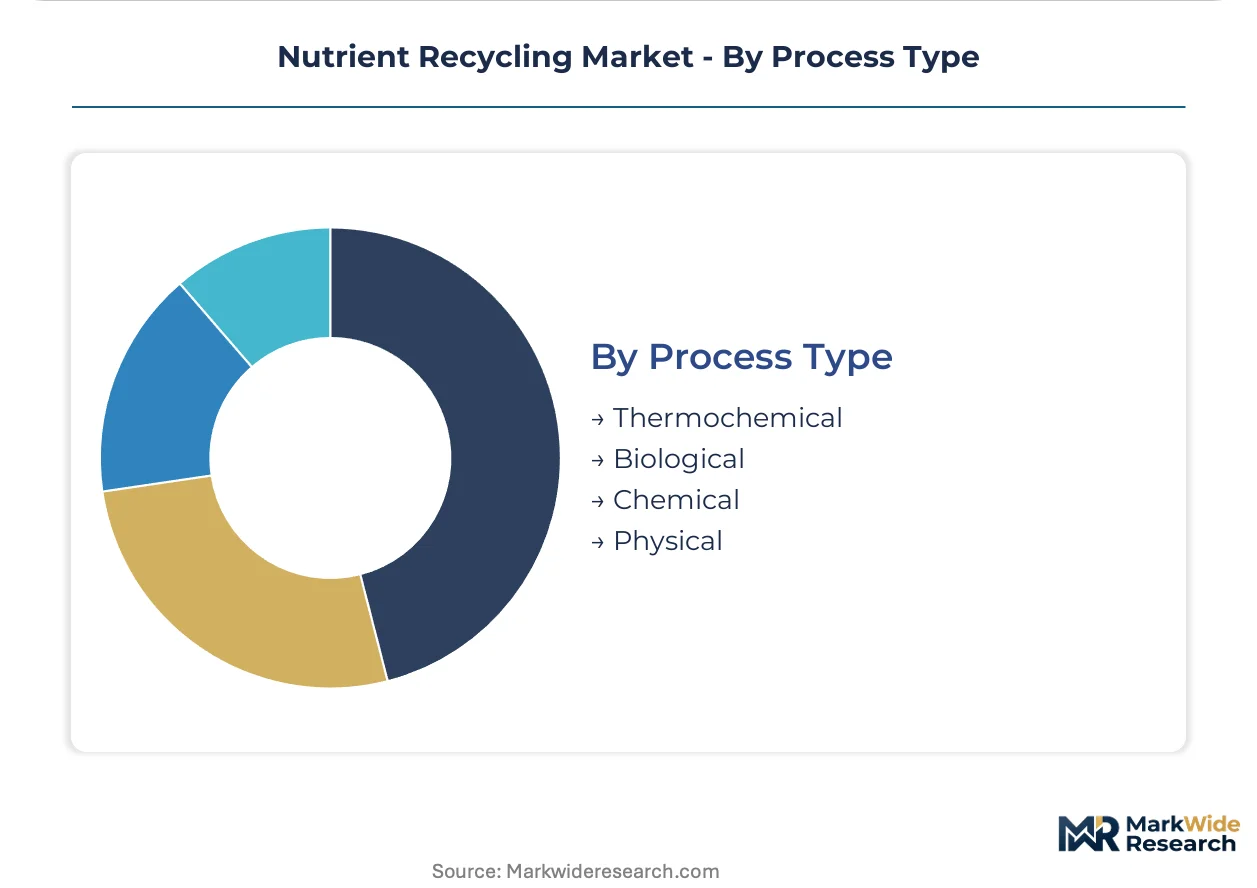
Process Type:
Energy intensity and capital requirements sort process selection by facility scale and feedstock contamination levels. Biological routes dominate agricultural waste processing. Thermochemical methods handle industrial organic residues with elevated pollutant loads.
- Biological:Anaerobic and aerobic microbial degradation pathways dominate decentralized agricultural settings. Denmark and Sweden have adopted continuous-flow anaerobic designs that reduce chemical dosing variation. Co-production of biogas energy improves project economics for nutrient recovery investments.
- Chemical:Struvite precipitation and acid extraction recover phosphorus from wastewater streams with predictable crystallization kinetics.
- Thermochemical:Pyrolysis and gasification convert contaminated feedstocks into biochar-carrying nutrients.
- Physical:Membrane filtration and centrifugation concentrate nitrogen from dilute waste streams without thermal energy inputs.
Biological processes lead by installed capacity. Chemical phosphorus recovery shows the steepest adoption curve through mandated municipal wastewater treatment upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in recovered phosphorus products while importing nitrogen-rich digestate from Polish anaerobic digestion facilities. Cross-border nutrient flows concentrate between the Rhine-Ruhr industrial corridor and Dutch greenhouse clusters.
Germany
The Sewage Sludge Ordinance mandates phosphorus recovery from wastewater treatment plants exceeding 50,000 population equivalents, creating guaranteed feedstock supply. ECHA's REACH registration requirements for recovered nutrient intermediates shape facility compliance investments. Struvite crystallization plants in Berlin-Brandenburg and North Rhine-Westphalia supply phosphate equivalents to Lower Saxony's arable farming cooperatives.
Netherlands
Closed-loop greenhouse operations in Westland and Aalsmeer demand sterile, water-soluble nutrient solutions with documented heavy metal thresholds. CE-marking under EU Fertilizing Products Regulation enables cross-border procurement from German crystallization facilities. Rotterdam's port infrastructure handles bulk liquid nutrient imports from Belgian anaerobic digestion operators.
Poland
Livestock-dense regions in Lower Silesia and Greater Poland generate feedstock for anaerobic digestion facilities contracting directly with arable farming operations. Variable-rate application systems in the Masovian Voivodeship pull demand toward pumpable liquid digestate products. National fertilizer laws accommodate recovered nutrient land application under simplified registration pathways.
France
Agricultural cooperatives in Brittany and Normandy procure compost through regional biowaste collection contracts with municipal waste operators. ANSM and national environmental regulators set contamination limits for recovered fertilizers entering food crop production. The Paris Basin's cereal producers negotiate long-term offtake agreements with anaerobic digestion facilities in Picardy.
Sweden
Continuous-flow anaerobic digestion designs in Skåne and Västra Götaland reduce chemical dosing variation for nutrient recovery investments. Swedish environmental protection standards for biosolids land application exceed EU minimum thresholds. Stockholm's wastewater treatment utilities partner with crystallization technology providers to extract phosphorus for agricultural redistribution.
Nutrient Recycling Market Competitive Landscape
Concentration sits with integrated environmental service conglomerates controlling collection, processing, and agricultural distribution infrastructure. The vendor base spans three tiers: multinational water utilities with captive nutrient recovery assets, specialized crystallization technology licensors, and regional anaerobic digestion operators. Dominant competitive moves include strategic partnerships with municipal wastewater authorities and technology licensing agreements that expand geographic footprint without capital-intensive facility construction.
Within the technology licensor tier, Ostara Nutrient Recovery Technologies Inc. and EasyMining exemplify phosphorus crystallization specialists partnering with municipal utilities. Veolia and Suez occupy positions as integrated service providers bundling nutrient recovery within broader water management contracts. Nutrien anchors the agricultural distribution tier through backward integration into both mining and recycling nutrient streams.
| Leading Market Players |
|---|
| Ostara Nutrient Recovery Technologies Inc. |
| Nutrient Recovery & Upcycling LLC |
| Cambi AS |
| Veolia |
| Suez |
| BioHiTech Global Inc. |
| DVO Inc. |
| Nutrien |
| EasyMining |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German wastewater treatment utilities and Lower Saxony arable cooperatives lock in phosphorus supply visibility while insulating crystallization facilities from spot phosphate rock volatility. These bilateral agreements bundle nutrient delivery with soil testing services, compressing channel margins for legacy fertilizer dealers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that span five-to-seven-year horizons with volume-scale discounts. Price differentiation rests on CE-marking certification under EU Fertilizing Products Regulation and heavy metal threshold compliance, with food-grade struvite commanding premiums over agricultural-grade alternatives. Cost compression in crystalline struvite is intensifying because Moroccan state-controlled phosphate suppliers manipulate conventional fertilizer benchmarks. Smallholder cooperatives in Poland exhibit highest price sensitivity, while Dutch greenhouse operators in Westland demonstrate lowest sensitivity due to sterile-input requirements.
Supply Chain Analysis
Container availability constraints on Rhine-Ruhr barge routes and Rotterdam-Antwerp liquid bulk corridors elevate inbound logistics costs for nitrogen-rich digestate shipments. Geographic supply concentrates in Germany, Poland, and the Netherlands, with crystallization facilities clustered around Berlin-Brandenburg and North Rhine-Westphalia. Raw material dependencies include municipal sewage sludge, agricultural manure, and food waste feedstocks. Single-source vulnerability sits with German phosphorus recovery mandates that tether European supply to domestic wastewater infrastructure. Distribution runs through direct contracting between anaerobic digestion operators and arable farming cooperatives, bypassing traditional agricultural merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nutrient recycling markets are approaching a platform-economics inflection where interoperability between precision agriculture equipment and liquid nutrient dosing systems determines supplier lock-in. The emergence of blockchain traceability protocols for nutrient passports signals ecosystem consolidation around data-verified supply chains.
For Market Incumbents: Secure backward integration into municipal wastewater concession contracts to defend feedstock access against emerging crystallization technology licensors. Veolia and Suez have established templates bundling nutrient recovery within integrated water management agreements that block pure-play competitors. Incumbents must accelerate CE-marking investments under EU Fertilizing Products Regulation before REACH registration deadlines harden compliance barriers.
For New Entrants and Emerging Players: Differentiate on real-time crystal size control technology that enables pumpable struvite formulations compatible with variable-rate application systems. Hydroponic cultivation systems in Spain represent the most penetrable white-space target, with sterile nutrient requirements unmet by incumbent composting operations. A licensing-plus-service revenue model partnering with regional anaerobic digestion facilities minimizes capital intensity while capturing recurring calibration revenue.
For Investors and Strategic Acquirers: The market sits at a regulatory-mandate expansion phase that favors crystallization technology specialists with proven municipal utility partnerships. Long-term viability over the next decade hinges on phosphorus recovery mandates spreading beyond Germany to France and Poland. Acquisition targets should demonstrate installed base scale in continuous-flow reactor designs. The signal to watch is ECHA guidance on UVCB substance classifications that could trigger consolidation among struvite producers facing reformulation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Municipal Utility Partnership | Long-term concession agreements in Berlin-Brandenburg secure guaranteed sewage sludge feedstock volumes. |
| CE-Marking Certification | Harmonized EU Fertilizing Products Regulation compliance enables cross-border sales to Dutch greenhouse clusters. |
| Precision Agriculture Integration | Pumpable liquid nutrient formulations integrate directly with variable-rate application systems in Polish arable farming. |
| Blockchain Traceability Deployment | Digital nutrient passports satisfy ESG verification requirements from food processors sourcing from Lower Saxony cooperatives. |
| Continuous-Flow Reactor Scale-Up | Denmark and Sweden deployments demonstrate sub-seven-year payback periods for phosphorus recovery investments. |
Research Methodology
A standing panel of wastewater treatment plant operators, anaerobic digestion facility managers, agricultural cooperative procurement leads, and precision agriculture equipment distributors provided ongoing calibration throughout the study period. Primary interviews with these stakeholders were cross-validated against secondary sources including EPA biosolids filings under 40 CFR Part 503, ECHA REACH registration databases, EU Fertilizing Products Regulation implementation guidance, and German Sewage Sludge Ordinance compliance reports. Bottom-up facility capacity assessments were triangulated with top-down nutrient flow modeling across the Rhine-Ruhr corridor and Dutch greenhouse clusters.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning technology type, end-use application, product physical state, and process energy intensity. CAGRs were derived from facility-level capacity expansion pipelines and regulatory mandate implementation timelines. Industry-specific forecast inputs included phosphorus recovery obligation phase-in schedules and precision agriculture equipment penetration rates in German arable farming regions.
Decision-makers should treat outputs as directional under assumptions of sustained synthetic fertilizer price volatility and stable EU regulatory frameworks; material deviation in phosphate rock pricing or ECHA substance classification guidance would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Waste Management Market