
 Reusable Oil Absorbents Market | 2026-2036
Reusable Oil Absorbents Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Oil Absorbents Market Outlook
Subscription-based laundering and reconditioning services for oil-absorbent pads is decoupling product ownership from consumption across industrial accounts. ITU AbsorbTech, Inc. anchors this model through nationwide collection-and-redelivery networks for manufacturing clients. New Pig Corporation differentiates via proprietary polypropylene blends that sustain higher reuse cycles without degradation. Oil-Dri Corporation of America leverages its mineral-based substrate expertise to compete in composite material segments where absorption capacity determines contract awards.
Reusable oil absorbents are engineered textile products—typically woven or needle-punched polyester, polypropylene, or cotton composites with specified oil-retention ratios and ignition resistance thresholds—designed for repeated saturation, extraction, and redeployment in hydrocarbon spill containment. Their primary purpose is to replace single-use sorbents in facilities with continuous leak or drip exposure, cutting waste generation and procurement frequency. Rolls and pads dominate current volume due to standardized deployment across machine shop floors and loading docks, while booms command premium positioning in marine applications where containment regulations mandate rapid-response readiness. Composite materials represent the fastest-expanding segment as manufacturers blend synthetic and natural fibers to balance absorption kinetics with laundering durability.
EPA SPCC rules mandate secondary containment and prompt spill response at facilities above threshold oil storage volumes, directly expanding addressable demand for reusable formats that satisfy repeat-use compliance documentation. OSHA workplace safety standards on slip hazards and chemical exposure reinforce product specification requirements for traction and fire resistance. State-level industrial discharge permits in California, Texas, and Ohio further narrow acceptable end-of-life pathways for spent absorbents, advantaging closed-loop rental programs with verified reprocessing chains. Stakeholders must track how regulatory enforcement intensity at the state level shapes customer procurement criteria between ownership and service-based models.
Market Dynamics
The subscription-based laundering model is restructuring customer-supplier relationships by separating absorbent ownership from consumption, forcing incumbents to build reverse logistics networks or cede accounts to service-oriented competitors.
Growth Catalysts
- EPA SPCC spill prevention mandates:Facilities storing above-threshold oil volumes must maintain documented response readiness, creating recurring demand for launderable formats that satisfy compliance audits.
- Polypropylene blend advances:Synthetic fiber engineering now sustains fifteen-plus wash cycles without degradation, lowering per-use cost below single-use alternatives for high-frequency drip applications.
- Ohio metalworking cluster density:Concentrated heavy machinery maintenance operations in the American Midwest generate scaled demand for pad-and-roll formats deployed across contiguous plant floors.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing margins for manufacturers without long-term supply contracts.
- Mineral substrate mining concentration:Bentonite and diatomaceous earth deposits cluster in select geographies, exposing composite material producers to concentrated supply risk.
- California industrial discharge permitting:State-level waste classification rules create compliance friction for facilities choosing ownership over rental models.
Strategic Opportunities
- Marine boom deployment gaps:Port authorities and vessel operators face escalating containment readiness requirements with limited domestic launderable boom suppliers.
- OSHA slip hazard enforcement expansion:Workplace safety inspectors are broadening traction standard applicability to loading dock and warehouse environments.
- Composite cotton-polyester blends:Natural-synthetic fiber convergence enables biodegradable end-of-life pathways that satisfy emerging procurement sustainability scorecards.
Industry Challenges
- ISO 14001 environmental management certification:Rental service providers must maintain chain-of-custody documentation across hundreds of collection points, stretching quality assurance resources.
- Laundering facility capex intensity:Centralized reprocessing plants require solvent recovery systems and wastewater treatment infrastructure that demand eight-figure capital commitments.
- Fire resistance standard harmonization:Inconsistent ignition threshold testing protocols across state fire marshals complicate product specification for multi-state operators.
Report Scope
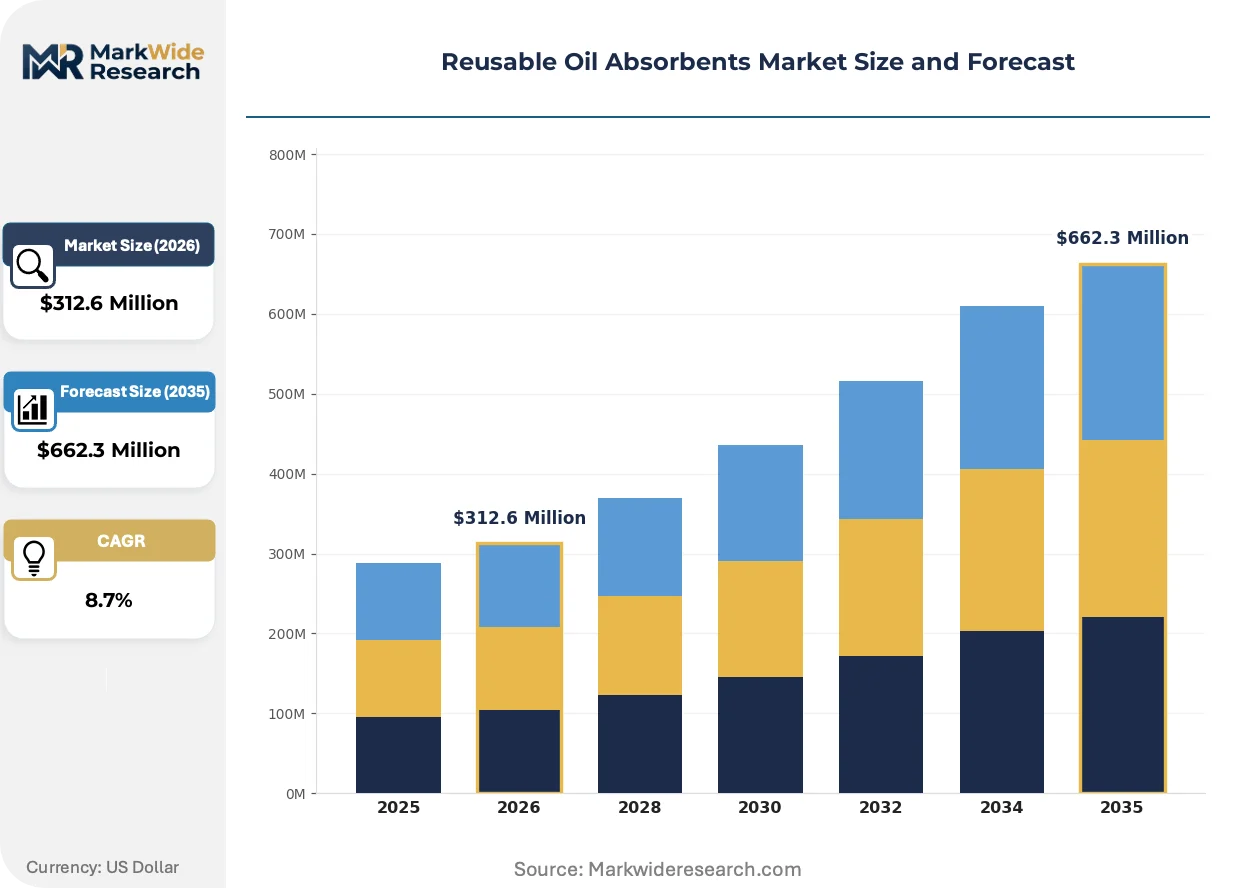
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Oil Absorbents Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pads, Rolls, Socks, Booms Material: Polyester, Polypropylene, Cotton, Composite Application: Industrial, Marine, Automotive, Home Use End User: Manufacturing, Oil & Gas, Construction, Emergency Services |
| Companies Covered | ITU AbsorbTech, Inc., New Pig Corporation, Sorbent Green LLC, Oil-Dri Corporation of America, 3M, SpillTech Environmental Incorporated, Closed Loop Recycling, Fentex Ltd., Park Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Oil Absorbents Market Strategic Shifts
Automation of absorbent tracking and reprocessing workflows is compressing service delivery costs while raising compliance documentation fidelity. Three developments are reshaping competitive positioning.
RFID-embedded textile tagging is automating inventory lifecycle management from deployment through saturation monitoring to collection scheduling. Automotive assembly plants with just-in-time maintenance protocols are adopting these systems fastest. The technology is automating audit trail generation that satisfies EPA SPCC record-keeping requirements without manual log maintenance.
REACH chemical restriction expansions in Europe are tightening permissible substance thresholds in textile treatments used for oil-repellency. Industrial laundries serving cross-border manufacturing clients must reformulate wash chemistry or risk contract termination. Composite material segments with mineral-based substrates are gaining preference where synthetic fiber treatments face regulatory scrutiny.
Facility managers are consolidating supplier relationships around full-service rental programs that bundle absorbent supply, collection, laundering, and compliance reporting into single-source contracts. Machine shop and metalworking verticals are displacing fragmented purchasing of disposable products with consolidated service agreements. The American Midwest manufacturing corridor exhibits the fastest contract conversion velocity as procurement functions centralize under corporate sustainability mandates.
Reusable Oil Absorbents Market Segmentation
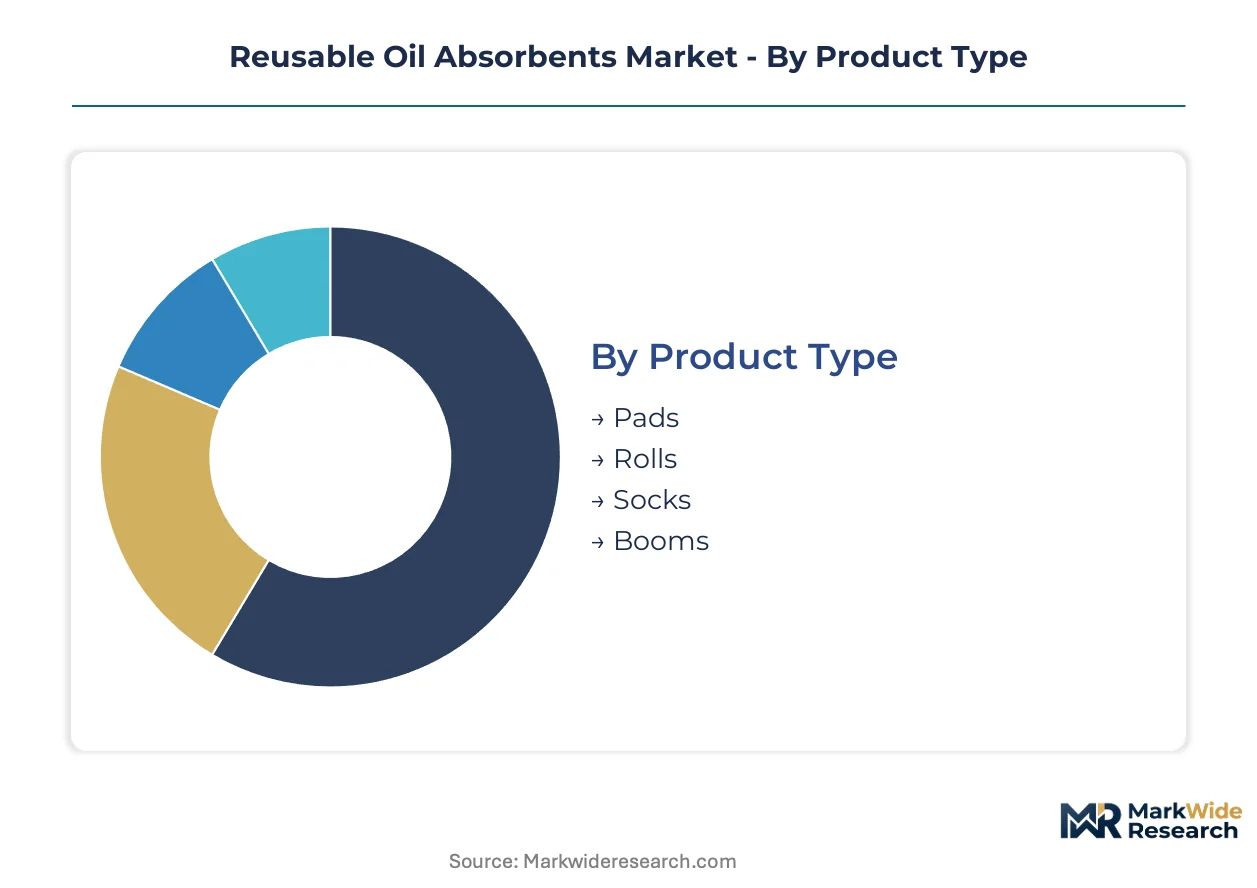
Reusable oil absorbent procurement varies sharply by deployment environment, material durability requirements, and compliance documentation needs. Specification mismatches between product format and end-use intensity drive replacement costs and regulatory exposure.
Product Type:
Format selection hinges on spill surface area, containment geometry, and laundering logistics compatibility.
- Pads:Flat-woven or needle-punched textiles in standardized dimensions for machine drip trays and maintenance bay floors. Ohio metalworking clusters deploy pad formats across contiguous plant floors where high-frequency drip exposure demands rapid saturation cycling.
- Rolls:Continuous textile lengths for custom cutting to irregular machinery footprints. Automotive assembly plants specify roll formats for just-in-time maintenance protocols where deployment flexibility reduces inventory SKUs.
- Socks:Tubular configurations for linear containment around equipment bases and loading dock edges. Manufacturing facilities use sock formats to perimeter-seal leak-prone hydraulic systems.
- Booms:Buoyant cylindrical barriers for marine surface containment with tethering hardware and rapid-deployment storage. Port authorities face escalating containment readiness requirements with limited domestic launderable boom suppliers.
Pads lead on scale; booms lead on momentum.
Material:
Fiber composition determines wash cycle tolerance, absorption kinetics, and end-of-life regulatory classification.
- Polypropylene:Thermoplastic polymer engineered for fifteen-plus wash cycles without degradation. Synthetic fiber engineering now sustains higher reuse cycles, lowering per-use cost below single-use alternatives for high-frequency drip applications.
- Composite:Blended natural and synthetic fibers balancing absorption speed with laundering durability. Composite material segments with mineral-based substrates gain preference where synthetic fiber treatments face regulatory scrutiny.
- Polyester:High-tenacity synthetic with superior ignition resistance for hot-work environments. Industrial laundries specify polyester blends for facilities with elevated fire safety thresholds.
- Cotton:Natural fiber absorbent with biodegradable end-of-life pathways. Procurement sustainability scorecards increasingly favor cotton-polyester blends for verified reprocessing chains.
Polypropylene leads on scale; composite leads on momentum.
Application:
Environmental exposure severity and containment response speed dictate format and material specifications.
- Industrial:Manufacturing floor deployment with continuous leak monitoring and scheduled collection. EPA SPCC spill prevention mandates create recurring demand for launderable formats that satisfy compliance audits.
- Marine:Port and vessel containment with rapid-response readiness requirements and saltwater corrosion resistance. Marine boom deployment gaps persist among port authorities facing escalating containment regulations.
- Automotive:Assembly plant maintenance bays with just-in-time absorbent tracking and RFID-embedded inventory management. Automotive verticals adopt automated lifecycle management systems fastest.
- Home Use:Consumer-scale garage and workshop applications with lower cycle frequency and retail distribution. Home use segments concentrate in big-box retail channels with disposable-to-reusable conversion lagging industrial adoption.
Industrial leads on scale; marine leads on momentum.
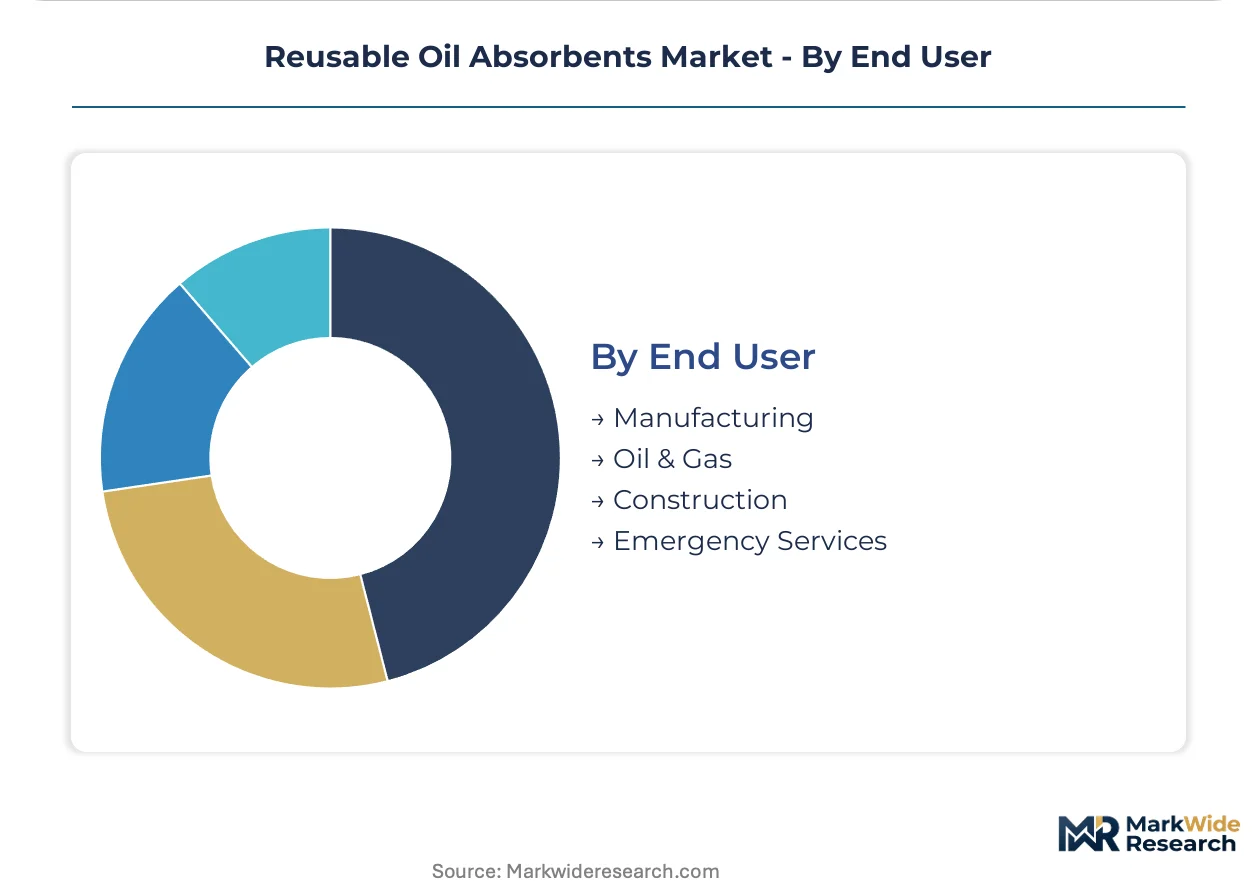
End User:
Procurement centralization and sustainability mandate intensity vary across buyer organizational structures.
- Manufacturing:Corporate sustainability functions consolidating fragmented purchasing into single-source rental contracts. Machine shop and metalworking verticals displace disposable products fastest under centralized procurement.
- Oil & Gas:Upstream and midstream facilities with threshold oil storage volumes triggering EPA SPCC secondary containment requirements. Oil & gas operators maintain documented response readiness with launderable format audit trails.
- Construction:Project-based deployment with variable site duration and decentralized equipment maintenance. Construction end users face higher logistics costs for collection-and-redelivery network access.
- Emergency Services:First responder agencies with rapid-deployment protocols and mutual aid standardization. Emergency services procurement prioritizes ignition resistance certification and multi-jurisdictional specification harmonization.
Manufacturing leads on scale; oil & gas leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Canada in reusable oil absorbent deployment density, while Germany and Japan demonstrate contrasting regulatory pathways for industrial textile reprocessing.
United States
EPA SPCC spill prevention mandates drive facility-level procurement of launderable formats across manufacturing. State-level industrial discharge permits in California, Texas, and Ohio narrow acceptable end-of-life pathways for spent absorbents. The American Midwest metalworking corridor concentrates demand, with Ohio machine shops converting fastest to rental-based service models under corporate sustainability mandates.
Germany
REACH chemical restrictions tighten permissible substance thresholds in textile treatments for oil-repellency. Industrial laundries serving cross-border manufacturing clients must reformulate wash chemistry or risk contract termination. The Baden-Württemberg automotive cluster exhibits rapid adoption of RFID-embedded inventory tracking for just-in-time maintenance protocols.
Japan
METI industrial efficiency standards promote circular economy adoption in facility maintenance supply chains. JIS ignition resistance specifications for hot-work environments shape product certification requirements. The Chubu region around Nagoya anchors demand from precision machinery manufacturers with continuous leak monitoring systems.
China
MIIT green manufacturing guidelines accelerate substitution of single-use sorbents in state-owned industrial enterprises. GB standards for workplace safety expand traction requirements to loading dock environments. The Yangtze River Delta manufacturing belt concentrates textile reprocessing infrastructure investment.
Canada
Health Canada environmental guidelines align with EPA spill prevention frameworks for cross-border facility operators. Provincial industrial discharge regulations in Ontario and Alberta favor closed-loop rental programs with verified reprocessing chains. The Ontario manufacturing corridor exhibits conversion velocity comparable to the American Midwest.
Reusable Oil Absorbents Market Competitive Environment
Top-tier vendors anchor nationwide service networks, while regional fabricators compete on specialized material formulations and local logistics responsiveness. The market structure consolidates around three strategic archetypes: subscription-based rental providers with reverse logistics infrastructure, proprietary blend manufacturers optimizing wash cycle tolerance, and mineral substrate specialists leveraging geological deposit access. Dominant competitive moves include backward integration into captive laundering facilities and geographic expansion through acquisition of regional collection networks.
Within the rental service tier, ITU AbsorbTech, Inc. and Closed Loop Recycling exemplify the subscription-based model decoupling product ownership from consumption. Among material-centric competitors, New Pig Corporation occupies a position representing synthetic fiber engineering advances, while Oil-Dri Corporation of America anchors the mineral substrate specialization segment. These three companies collectively illustrate the strategic divergence between service integration and material science differentiation reshaping customer-supplier relationships.
| Leading Market Players |
|---|
| ITU AbsorbTech, Inc. |
| New Pig Corporation |
| Sorbent Green LLC |
| Oil-Dri Corporation of America |
| 3M |
| SpillTech Environmental Incorporated |
| Closed Loop Recycling |
| Fentex Ltd. |
| Park Industries |
| Others |
Value Chain & Pricing Dynamics
Manufacturing procurement functions concentrated in Ohio metalworking clusters and automotive assembly plants anchor pricing power in the subscription-based rental model, compressing transactional spot purchases into consolidated service contracts with volume-scaled rate structures.
Pricing Analysis
Capacity additions in the American Midwest are reshaping price floors for launderable pad-and-roll formats as regional reprocessing facilities achieve solvent recovery economies. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified rental programs from basic ownership models and disposable alternatives. Pricing pressure stems from polypropylene resin volatility tied to crude benchmarks, squeezing margins for manufacturers lacking long-term feedstock contracts. Small machine shops exhibit highest price sensitivity, while automotive OEMs prioritize compliance documentation over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with concentrated bentonite and diatomaceous earth deposits in select geographies, exposing composite material producers to concentrated mining disruption. Polypropylene resin draws from petrochemical complexes in the United States, China, and South Korea, while cotton fiber sourcing rests on agricultural output in India and the United States. Tariff exposure on synthetic textile imports complicates multi-regional manufacturing footprints. Distribution runs through industrial laundry networks with reverse logistics infrastructure rather than traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement sustainability mandates are shifting specification requirements toward verified reprocessing chains and fire-resistant certified formats.
For Market Incumbents: Cement service network density through captive laundering facility expansion in the American Midwest, defending against emerging regional fabricators with specialized composite formulations. Backward integration into polypropylene fiber production insulates margin pressure from petrochemical feedstock volatility. ISO 14001 chain-of-custody certification investment locks out competitors lacking audit-ready documentation systems. For New Entrants and Emerging Players: Industrial laundry operators represent the most accessible channel partners for rapid market entry, offering embedded customer relationships and collection infrastructure without greenfield logistics buildout. Marine boom deployment gaps among port authorities present the most penetrable white-space, with limited domestic launderable suppliers and escalating containment readiness regulations. A go-to-market angle bundling RFID-embedded inventory tracking with rental service contracts differentiates against legacy pad-and-roll purveyors. For Investors and Strategic Acquirers: Private equity firms with industrial services portfolios are the most active acquirer in this space, targeting rental service providers with established reverse logistics networks and multi-state compliance documentation capabilities. Long-term viability hinges on consolidation of fragmented regional collection networks into scalable platforms with solvent recovery infrastructure. The signal to watch is EPA enforcement intensity at the state level, which accelerates contract conversion velocity from ownership to service-based models.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Laundering Facility Expansion | Backward integration into solvent recovery infrastructure locks in margin control for rental service providers. |
| RFID-Embedded Inventory Tracking Deployment | Automated lifecycle management satisfies EPA SPCC audit requirements for automotive assembly plant clients. |
| Composite Cotton-Polyester Formulation Development | Biodegradable end-of-life pathways align with emerging procurement sustainability scorecards in California and Ohio. |
| Marine Boom Rental Service Launch | Port authority containment readiness gaps create first-mover advantage in underserved rapid-response segments. |
| Regional Collection Network Acquisition | Geographic consolidation accelerates route density economies in the American Midwest metalworking corridor. |
Study Parameters
Multiple input streams — structured interviews with plant maintenance directors and industrial procurement leads, technical discussions with reprocessing facility operators, and validation sessions with regulatory compliance officers — were reconciled against customs records, EPA enforcement databases, and SEC filings from publicly traded material suppliers. Secondary sources included trade association data from textile reprocessing consortiums and state-level industrial discharge permit filings. Bottom-up volume estimates from end-use facility audits were triangulated with top-down market sizing from material flow analysis.
Data-stream reconciliation across product format, fiber composition, and end-use intensity dimensions shaped the analytical framework over the projection horizon. Modeled segments included pads, rolls, socks, and booms by polypropylene, composite, polyester, and cotton materials across industrial, marine, automotive, and emergency services applications. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA SPCC compliance audit frequency and corporate sustainability mandate penetration. Forecast inputs weighted polypropylene resin price volatility and state-level enforcement intensity differentials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical restriction expansions, petrochemical feedstock disruption, and harmonization of fire resistance testing protocols across state fire marshals. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Wheeled Bins Market