
 India Waste Management Market | 2026-2036
India Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
India Waste Management Market Outlook
The commercial end-user vertical is decoupling from traditional municipal dependence as corporate ESG mandates intensify disposal accountability. Antony Waste Handling Cell Ltd leverages its integrated landfill-to-energy infrastructure across Maharashtra and Gujarat. Ramky Enviro Engineers Ltd anchors its position through hazardous waste treatment complexes serving pharmaceutical and chemical zones. Attero Recycling Pvt Ltd specializes in e-waste recovery, extracting precious metals from discarded electronics at scale.
India waste management encompasses the systematic collection, transportation, processing, recycling, and disposal of municipal solid waste, hazardous waste, electronic waste, and industrial waste through engineered facilities meeting CPCB emission and leachate standards. Its primary purpose is environmental protection combined with material and energy recovery from discarded streams. Municipal solid waste dominates service volumes due to urban population density, though electronic waste represents the fastest-growing segment as smartphone and appliance replacement cycles compress. Collection services capture the largest revenue pool currently, while anaerobic digestion technology is attracting capital as biomethane offtake agreements with oil marketing companies stabilize project returns.
The Central Pollution Control Board enforces Consent to Establish and Consent to Operate protocols that determine facility siting and technology choices across states. BIS certification requirements for compost quality and plastic recycling outputs shape product market access for secondary material vendors. The Ministry of Environment's Extended Producer Responsibility frameworks for e-waste and plastic packaging are transferring collection accountability upstream to brand owners and importers. Stakeholders must monitor state-level urban local body concession awards, as 20-year tipping-fee contracts with escalation clauses determine long-term revenue visibility for integrated operators.
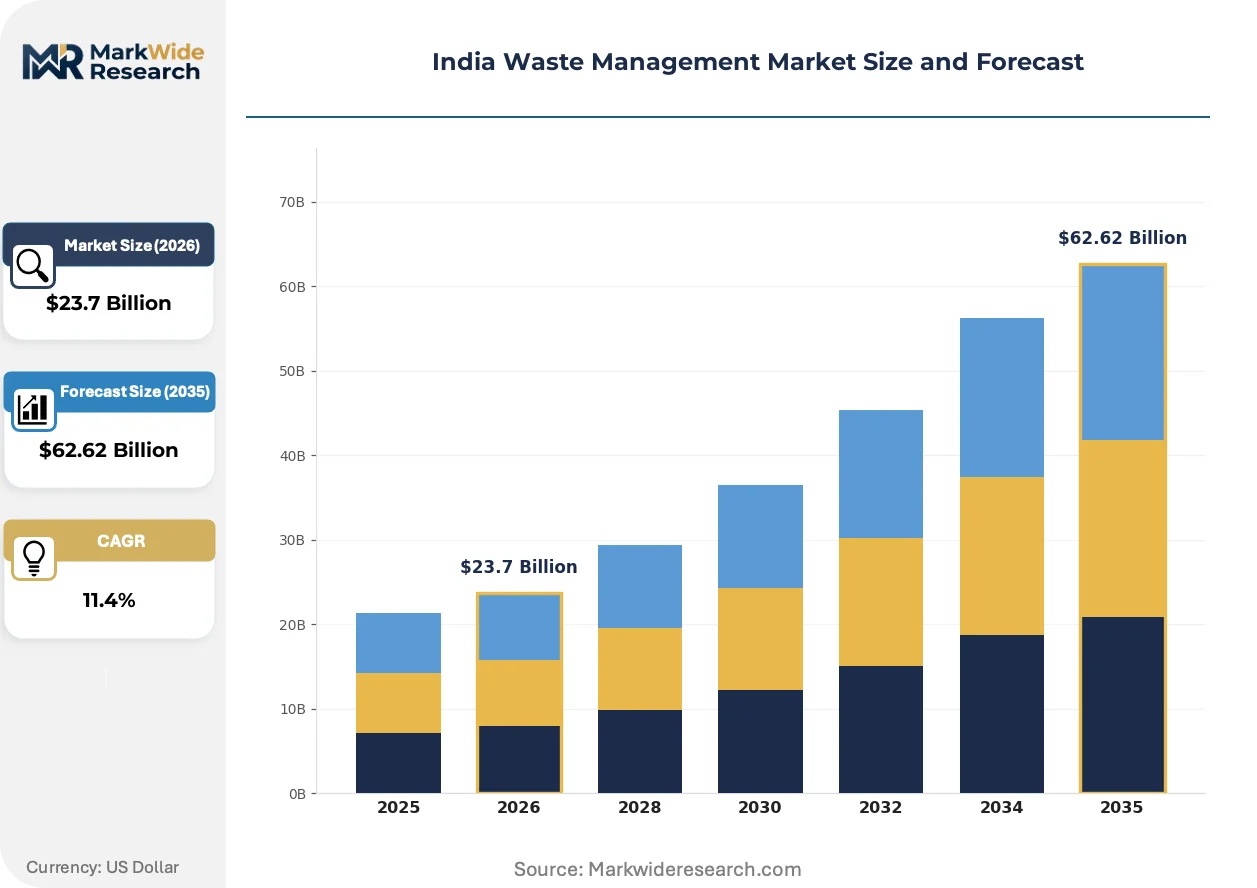
Market Dynamics
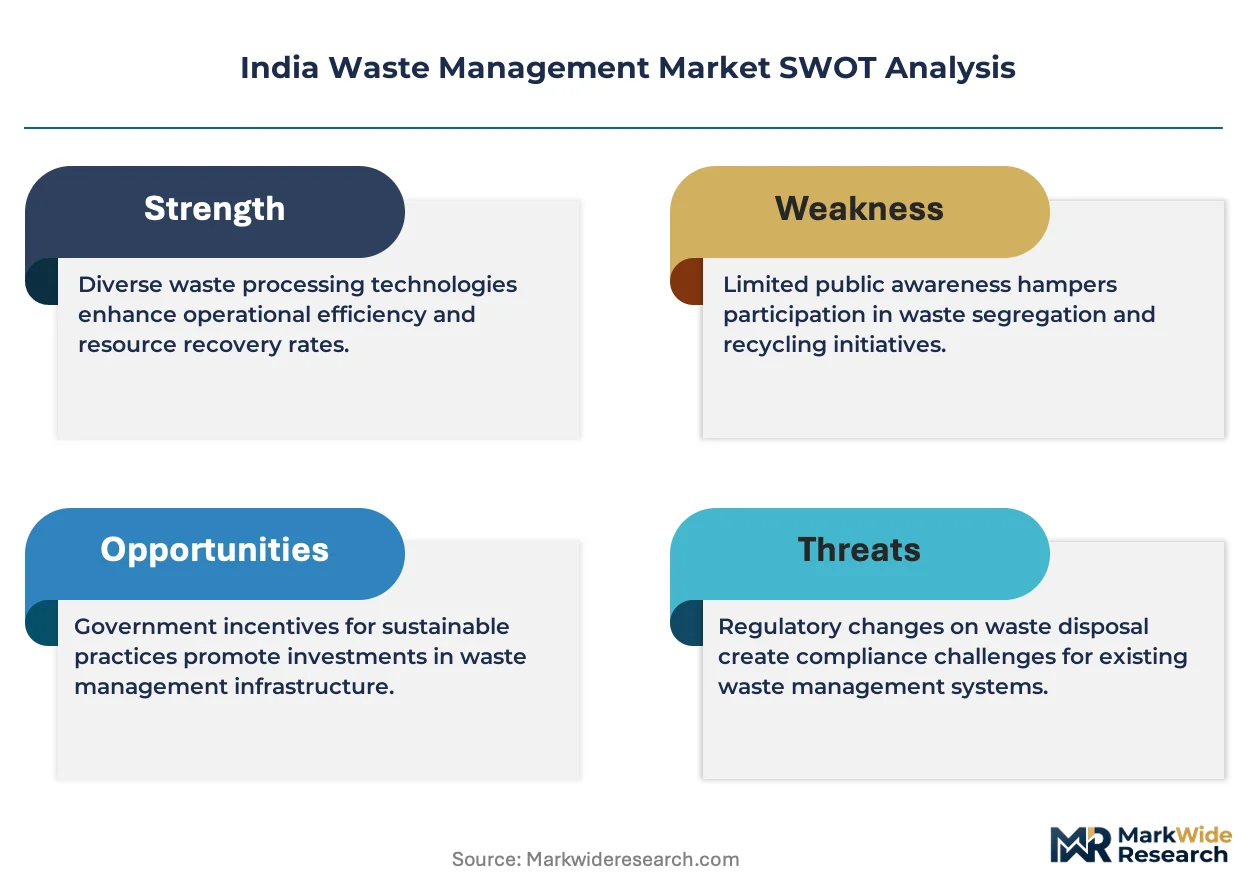
India's waste management sector is restructuring around landfill diversion mandates issued by the Ministry of Environment, Forest and Climate Change, which are compressing disposal capacity and forcing capital toward alternative treatment infrastructure.
Growth Catalysts
- Extended Producer Responsibility frameworks:The Ministry of Environment's EPR mandates for plastic packaging and e-waste transfer collection accountability to brand owners, creating contracted demand for integrated waste operators.
- Maharashtra and Gujarat industrial clustering:Concentrated pharmaceutical and chemical zones generate hazardous waste streams requiring specialized treatment, anchoring demand for complex incineration and secured landfill infrastructure.
- Anaerobic digestion technology maturation:Biomethane offtake agreements with oil marketing companies stabilize project returns, attracting capital toward organic waste processing facilities.
Market Restraints
- Land scarcity for facility siting:Urban periphery land costs in tier-1 cities have escalated sharply, compressing project IRRs for greenfield landfill and processing plants.
- Leachate treatment capex intensity:CPCB mandates for zero liquid discharge at landfill sites require advanced membrane bioreactor systems that extend payback periods by three to four years.
- Informal sector dominance in collection:Unorganized ragpicker networks control an estimated 70% of recyclable recovery in major cities, limiting formal operator feedstock security.
Strategic Opportunities
- Tier-2 and tier-3 city penetration:Municipal corporations in cities like Indore, Surat, and Coimbatore are issuing 20-year concessions with guaranteed tipping fees, offering first-mover positioning before market saturation.
- E-waste precious metal recovery:Compressed smartphone replacement cycles are expanding feedstock volumes for hydrometallurgical extraction of gold, palladium, and rare earth elements.
- Refuse-derived fuel co-processing:Cement manufacturers in Rajasthan and Andhra Pradesh are substituting coal with RDF, creating offtake contracts for dried municipal solid waste fractions.
Industry Challenges
- Environmental engineer scarcity:Specialized expertise in leachate chemistry and emission control system design commands premium compensation, constraining facility commissioning timelines.
- Legacy dump site remediation liability:Operators winning closure contracts for unmanaged legacy landfills face unpredictable geotechnical conditions and groundwater contamination extent.
- Interstate waste movement permits:Hazardous waste transporters must secure multi-state clearances under CPCB protocols, creating documentation bottlenecks that disrupt just-in-time disposal schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Waste Management Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Municipal Solid Waste, Hazardous Waste, Electronic Waste, Industrial Waste Service Type: Collection, Recycling, Landfilling, Treatment Technology: Incineration, Composting, Anaerobic Digestion, Plasma Gasification End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Antony Waste Handling Cell Ltd, A2Z Green Waste Management Ltd, Ramky Enviro Engineers Ltd, Attero Recycling Pvt Ltd, BVG India Ltd, Cerebra Integrated Technologies Ltd, Ecowise Waste Management Pvt Ltd, Saahas Zero Waste, NEPRA Resource Management Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Waste Management Market Strategic Shifts
Technology deployment is fragmenting centralized infrastructure models as distributed processing systems achieve scale economics previously reserved for large facilities.
Pyrolysis units for plastic waste are decentralizing collection-to-fuel conversion by enabling 10-50 tonne per day installations at municipal transfer stations. Urban local bodies in Kerala and Tamil Nadu are procuring containerized systems through 10-year BOOT contracts. This distributed architecture is compressing transportation costs and reducing reliance on long-haul transfer to regional hubs.
The Ministry of Environment's Solid Waste Management Rules amendment has tightened organic waste processing mandates for bulk generators exceeding 100 kg daily. Hotels, malls, and housing complexes must now install on-site composting or biogas units or face penalties. The compliance surge is accelerating demand for compact anaerobic digesters and automated composting machines in Delhi-NCR and Bengaluru.
Corporate buyers are unbundling waste services from bundled municipal contracts and contracting directly with specialized operators for zero-waste-to-landfill certifications. Information technology parks in Hyderabad and Pune are leading this disintermediation, procuring separate streams for e-waste, wet waste, and dry recyclables through distinct vendors. The procurement fragmentation is eroding integrated municipal operators' volume concentration.
India Waste Management Market Segmentation
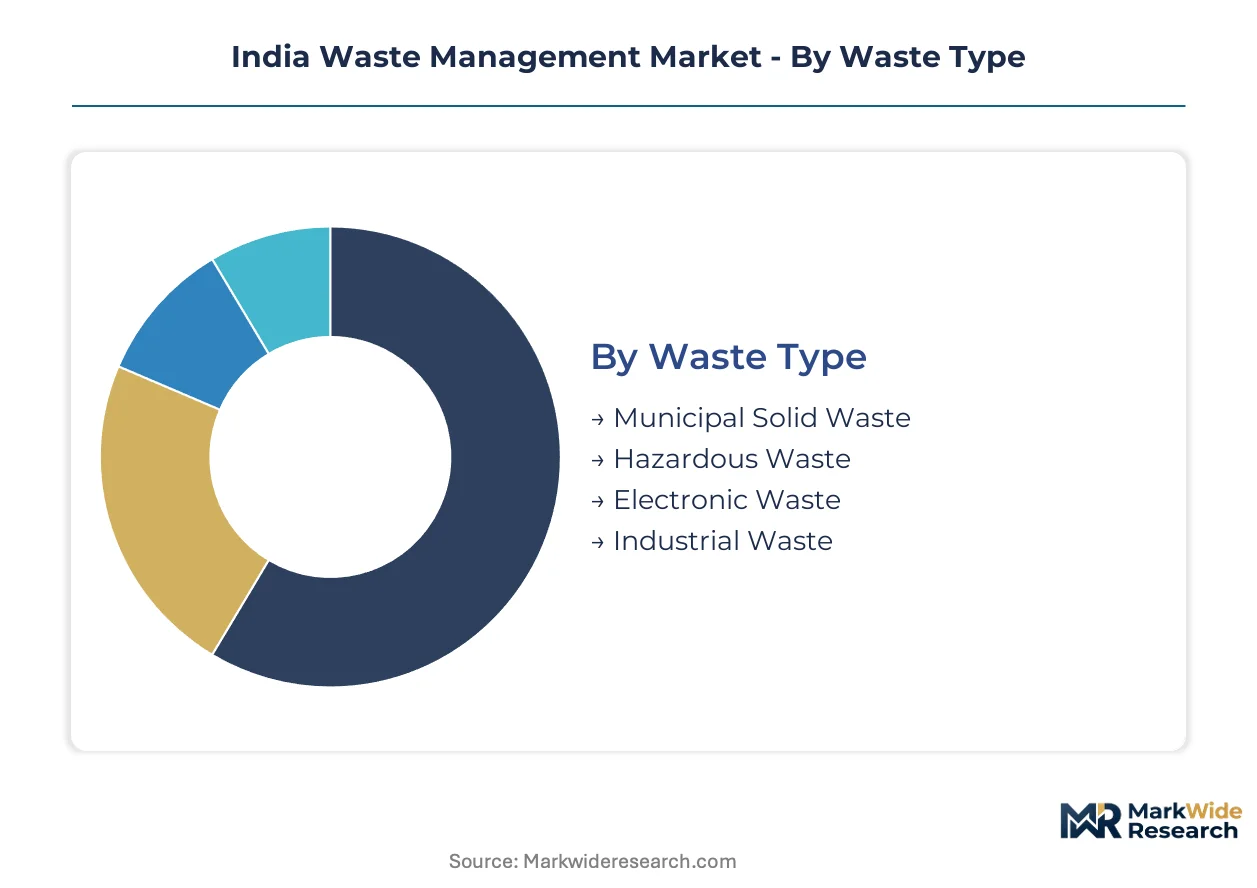
Segmentation in India's waste management sector reveals how regulatory pressure and feedstock characteristics reshape capital allocation across treatment technologies. Each category maps distinct operational requirements onto geographic and end-use demand patterns.
Waste Type:
Standardization dominates municipal streams with uniform collection protocols, while hazardous and e-waste demand specialized handling certifications that fragment operational models.
- Municipal Solid Waste:Comprises household and commercial discards with high organic fractions requiring daily collection cycles. Demand concentrates in Maharashtra and Gujarat where municipal corporations enforce source-segregation mandates under Ministry of Environment rules. Landfill diversion targets compress disposal capacity and force capital toward alternative treatment infrastructure.
- Hazardous Waste:Encompasses pharmaceutical residues, chemical sludges, and biomedical discards requiring secured landfill cells and complex incineration. Pharmaceutical clusters in Hyderabad and chemical zones in Gujarat generate concentrated streams that anchor demand for specialized treatment complexes meeting CPCB emission standards.
- Electronic Waste:Discarded smartphones, appliances, and IT hardware containing recoverable precious metals. Compressed replacement cycles expand feedstock volumes for hydrometallurgical extraction facilities.
- Industrial Waste:Manufacturing byproducts from textiles, metals, and food processing sectors. Cement manufacturers in Rajasthan co-process dried fractions as refuse-derived fuel substitutes for coal.
Leading the category by volume: Municipal Solid Waste. Expanding most quickly: Electronic Waste.
Service Type:
Revenue concentration shifts from collection toward treatment as tipping-fee contracts mature and landfill diversion mandates tighten.
- Collection:Door-to-door pickup and transfer station operations capturing the largest current revenue pool. Tier-1 cities expand source-segregation mandates that require dual-stream vehicle fleets.
- Recycling:Material recovery facilities processing dry recyclables into secondary raw materials. BIS certification requirements for compost quality and plastic recycling outputs shape product market access.
- Landfilling:Engineered disposal cells with leachate collection and gas recovery systems. CPCB mandates for zero liquid discharge extend payback periods through advanced membrane bioreactor requirements.
- Treatment:Thermal and biological processing converting waste to energy or stabilized outputs. Anaerobic digestion facilities secure biomethane offtake agreements with oil marketing companies that stabilize project returns.
Collection commands current revenue share. Treatment is gaining share fastest as diversion mandates displace raw disposal.
Technology:
Capital intensity separates proven composting and digestion systems from emerging plasma applications still seeking scale economics.
- Incineration:Controlled thermal oxidation of combustible waste fractions with energy recovery boilers. Hazardous waste complexes in pharmaceutical and chemical zones deploy rotary kiln systems meeting stringent CPCB emission protocols.
- Composting:Aerobic biological decomposition of organic waste into soil amendments. Kerala and Tamil Nadu urban local bodies procure containerized systems through BOOT contracts for municipal transfer stations.
- Anaerobic Digestion:Oxygen-free bacterial breakdown generating biogas for biomethane upgrading. Bulk generators exceeding 100 kg daily organic waste must install on-site units or face penalties under amended Solid Waste Management Rules.
- Plasma Gasification:Ultra-high temperature ionization converting waste to synthetic gas and vitrified slag. Limited commercial deployment due to power consumption intensity and feedstock preprocessing requirements.
Composting leads deployment volume. Anaerobic digestion is climbing the fastest on biomethane offtake momentum.
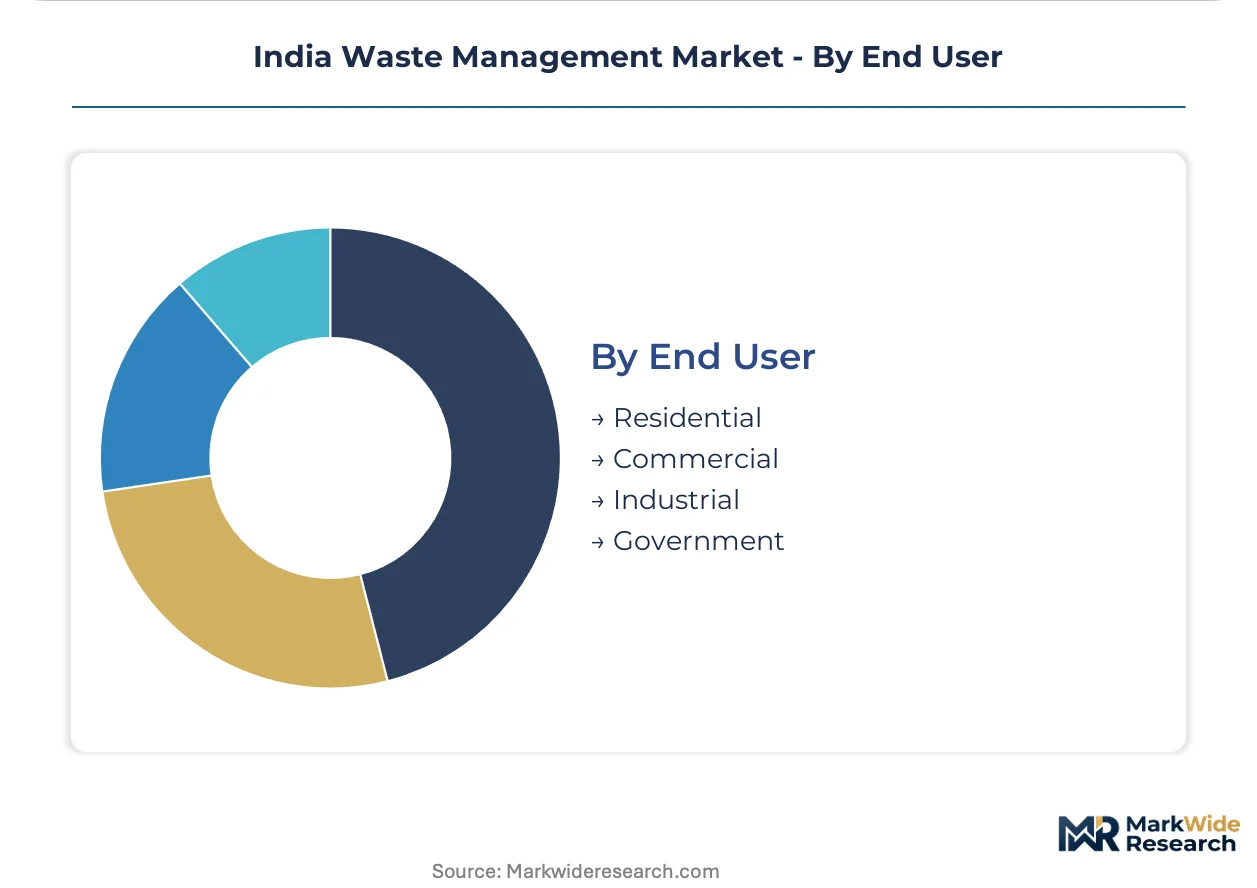
End User:
Procurement fragmentation accelerates as commercial buyers disintermediate from bundled municipal contracts to secure zero-waste-to-landfill certifications.
- Residential:Household waste generation tied to urban population density and consumption patterns. Tier-2 and tier-3 city municipal corporations issue 20-year concessions with guaranteed tipping fees.
- Commercial:Hotels, malls, and IT parks unbundling services for specialized e-waste, wet waste, and dry recyclable streams. Hyderabad and Pune information technology parks lead direct contracting with specialized operators.
- Industrial:Manufacturing facilities generating process waste requiring cradle-to-grave accountability. Extended Producer Responsibility frameworks transfer collection accountability upstream to brand owners and importers.
- Government:Municipal corporations and state pollution control boards setting service standards and awarding concessions. State-level urban local body concession awards determine long-term revenue visibility for integrated operators.
Residential dominates service volumes. Commercial is gaining share fastest on ESG mandate intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat concentrate waste treatment infrastructure through tax incentives and streamlined environmental clearances. These zones anchor India's highest-density industrial waste generation corridors.
Maharashtra
Mumbai and Pune municipal corporations enforce source-segregation mandates under Ministry of Environment rules. The Maharashtra Pollution Control Board mandates zero-liquid-discharge protocols for landfill sites. Pharmaceutical clusters in Baramati and chemical zones in Raigad generate hazardous waste streams requiring specialized incineration complexes.
Gujarat
Petrochemical and textile manufacturing in Hazira and Surat produces concentrated industrial waste volumes. The Gujarat Pollution Control Board operates India's most stringent Consent to Establish protocols for hazardous waste facilities. Dahej and Ankleshwar industrial estates host secured landfill cells and rotary kiln systems serving chemical zone exporters.
Karnataka
Bengaluru's bulk waste generators face penalties under amended Solid Waste Management Rules for exceeding 100 kg daily organic waste thresholds. The Karnataka State Pollution Control Board mandates biomethane capture for new anaerobic digestion installations. Electronics manufacturing clusters in Whitefield and Peenya expand e-waste feedstock for precious metal recovery facilities.
Tamil Nadu
Chennai and Coimbatore municipal corporations issue 20-year concessions with guaranteed tipping fees for integrated operators. The Tamil Nadu Pollution Control Board enforces plastic waste processing mandates through Extended Producer Responsibility frameworks. Leather tanning clusters in Ambur and Ranipet generate chromium-laden sludge requiring secured landfill disposal.
Telangana
Hyderabad information technology parks unbundle waste services from municipal contracts for zero-waste-to-landfill certifications. The Telangana State Pollution Control Board fast-tracks environmental clearances for waste-to-energy projects in industrial corridors. Genome Valley pharmaceutical clusters generate biomedical waste streams anchoring demand for specialized treatment infrastructure.
India Waste Management Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated landfill-to-energy operators commanding premium positioning in municipal concessions. The market structures around three tiers: diversified infrastructure conglomerates with 20-year tipping-fee contracts, technology-focused recyclers extracting precious metals from e-waste streams, and regional collection specialists serving tier-2 city municipal corporations. Strategic moves concentrate on securing long-term concession awards and deploying anaerobic digestion capacity ahead of biomethane offtake agreement deadlines.
Within the integrated infrastructure tier, Antony Waste Handling Cell Ltd and Ramky Enviro Engineers Ltd exemplify operators with landfill-to-energy and hazardous treatment complexes across Maharashtra and Gujarat. Attero Recycling Pvt Ltd occupies a specialized position in e-waste recovery, representing the technology-focused archetype extracting precious metals from discarded electronics at scale. These three companies anchor distinct competitive vectors: municipal concession depth, industrial hazardous treatment, and electronics circularity.
| Leading Market Players |
|---|
| Antony Waste Handling Cell Ltd |
| A2Z Green Waste Management Ltd |
| Ramky Enviro Engineers Ltd |
| Attero Recycling Pvt Ltd |
| BVG India Ltd |
| Cerebra Integrated Technologies Ltd |
| Ecowise Waste Management Pvt Ltd |
| Saahas Zero Waste |
| NEPRA Resource Management Pvt Ltd |
| Others |
Value Chain & Pricing Dynamics
Pyrolysis unit deployment at municipal transfer stations is compressing collection-to-processing economics while fragmenting supply concentration away from centralized regional hubs toward distributed 10-50 tonne per day installations. This technology shift simultaneously reduces long-haul transportation costs and enables urban local bodies in Kerala and Tamil Nadu to procure containerized systems through BOOT contracts, reshaping both capital deployment patterns and vendor pricing power.
Pricing Analysis
Short lead-time premiums dominate contract structures, with municipal corporations paying escalation-adjusted rates for 20-year tipping-fee agreements that guarantee service continuity. Three-tier pricing structure across integrated concession operators, technology specialists, and regional collection firms differentiates on certification depth and biomethane offtake security. Cost compression in hazardous waste treatment is intensifying because CPCB zero-liquid-discharge mandates extend facility payback periods. Tier-2 city municipal corporations exhibit highest price sensitivity, while pharmaceutical clusters in Genome Valley and Baramati prioritize compliance assurance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from cement manufacturers in Rajasthan and Andhra Pradesh mandate qualified refuse-derived fuel suppliers to prevent co-processing disruption. Equipment fabrication draws from China, Germany, and domestic engineering clusters in Pune and Ahmedabad. Membrane bioreactor systems and rotary kiln incinerators rest on specialized component imports, exposing projects to logistics chokepoints at major ports. Distribution runs through state-level pollution control board clearance protocols that determine vendor eligibility for concession awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Landfill diversion mandates are compressing disposal capacity faster than alternative treatment infrastructure can commission, propping pricing power for operators with secured concession awards and operational anaerobic digestion assets.
For Market Incumbents: Deploy biomethane offtake agreement pipelines to lock in revenue visibility before oil marketing company procurement windows close. Secure 20-year concession renewals in tier-2 cities like Indore and Coimbatore before competitive bidding intensifies, and invest in leachate chemistry expertise to accelerate facility commissioning timelines against environmental engineer scarcity. For New Entrants and Emerging Players: The premium-to-economy price-point gap in e-waste precious metal recovery offers entry traction for hydrometallurgical specialists with lower capex intensity than integrated smelters. Target containerized pyrolysis deployment for Kerala and Tamil Nadu urban local bodies procuring through BOOT structures, and lead with rapid installation timelines as the primary go-to-market angle against incumbent equipment vendors. For Investors and Strategic Acquirers: Re-rating potential sits with anaerobic digestion specialists given biomethane offtake agreement deadlines and tightening organic waste processing mandates for bulk generators. Long-term viability across the analysis window favors operators with demonstrated CPCB compliance records and secured landfill cells in Maharashtra and Gujarat industrial corridors. Monitor state-level urban local body concession award announcements as the inflection indicator for deployment capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Award Pursuit | 20-year tipping-fee contracts with escalation clauses determine revenue visibility for integrated operators. |
| Biomethane Offtake Agreement | Oil marketing company procurement stabilizes project returns for anaerobic digestion facilities. |
| Technology Licensing Partnership | Pyrolysis system deployment enables decentralized plastic waste processing at municipal transfer stations. |
| Backward Integration into Equipment | In-house production of compact digesters reduces dependence on imported membrane bioreactor systems. |
| Specialized Certification Investment | BIS compost quality certification opens secondary material markets for organic waste processors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with municipal corporation solid waste management officers, pollution control board environmental engineers, cement manufacturer procurement leads, anaerobic digestion project developers, and e-waste hydrometallurgical facility operators. CPCB consent records, Ministry of Environment EPR registry disclosures, state-level urban local body concession documents, and oil marketing company biomethane procurement circulars provided validation layers. Bottom-up project pipeline assessment triangulated against top-down sectoral expenditure estimates.
Data-stream reconciliation across installation capacity tracking, concession award monitoring, and feedstock volume estimation informed the analytical framework. Segmentation dimensions modeled include waste type, service category, treatment technology, and end-user vertical across the projection horizon. CAGRs were derived from facility commissioning timelines, concession fee escalation schedules, and technology deployment curves. Forecast inputs incorporated biomethane offtake agreement execution rates and CPCB enforcement intensity variations by state.
Underlying measurement precision varies by segment; municipal solid waste collection volumes carry tighter precision than emerging plasma gasification deployment estimates. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and concession award cadence. A model refresh is warranted upon material change in Ministry of Environment landfill diversion mandate timelines or oil marketing company biomethane procurement price revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
India Waste-To-Energy Market