
 Hazardous Waste Handling Automation Market | 2026-2036
Hazardous Waste Handling Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Waste Handling Automation Market Outlook
Skilled hazardous waste technician shortages across North America and Western Europe is unwinding capacity expansion timelines for treatment facilities and industrial generators. Veolia Environment SA leverages its integrated service footprint across collection through disposal to anchor long-term automation contracts. ABB Ltd specializes in robotic material handling architectures that extend operational reach into radiological and chemical containment zones. Konecranes competes on heavy-lift automation systems that dominate port and intermodal transfer applications for containerized hazardous cargo.
Hazardous waste handling automation encompasses electromechanical systems, sensor-integrated robotics, and AI-driven process controls engineered to manipulate, transport, treat, and store substances classified under regulatory frameworks as flammable, corrosive, reactive, or toxic, typically operating within sealed environments at negative pressure differentials of 0.5 to 2.5 inches of water column to prevent fugitive emissions. Robotics and sensor systems command the technology segment as legacy manual sorting faces ergonomic and exposure limits, while AI automation represents the fastest-growing category as machine vision enables real-time waste stream characterization. Waste management firms and healthcare facilities concentrate end-user demand, with treatment units and collection systems capturing the dominant type positions where capital intensity and regulatory compliance create durable margin pools.
EPA hazardous waste generator regulations and OSHA process safety management standards shape equipment specifications and facility upgrade cycles across the United States, while EU REACH compliance and the F-Gas Regulation drive analogous automation investments in European chemical processing clusters. Stakeholders must weigh capital deployment timing against evolving regulatory thresholds for remote-handling mandates and emissions monitoring that will determine competitive positioning in subsequent facility design cycles.
Market Dynamics
EPA hazardous waste generator standards are compressing facility upgrade timelines across the United States, forcing chemical manufacturers and treatment operators to accelerate capital deployment into remote-handling architectures before compliance deadlines lock in equipment specifications.
Growth Catalysts
- OSHA Process Safety Management:Tightened enforcement around highly hazardous chemicals is mandating engineered controls that reduce worker exposure hours in containment zones.
- Machine Vision Integration:AI-driven waste stream characterization enables real-time sorting decisions that manual operations cannot execute at equivalent throughput rates.
- German Industrial Cluster Modernization:Legacy treatment infrastructure in the Rhine-Ruhr and Bavarian chemical corridors is reaching end-of-life, triggering replacement demand for robotic handling cells.
Market Restraints
- Specialized Component Supply Concentration:Precision servo motors and radiation-hardened sensors concentrate among Japanese and German suppliers, exposing procurement to lead-time volatility.
- Capital Intensity Thresholds:Negative pressure differential systems and sealed environment construction require upfront investment that mid-scale generators cannot finance without long-term service contracts.
- EU F-Gas Regulation Friction:Restrictions on fluorinated greenhouse gases complicate cooling system specifications for temperature-sensitive waste storage automation.
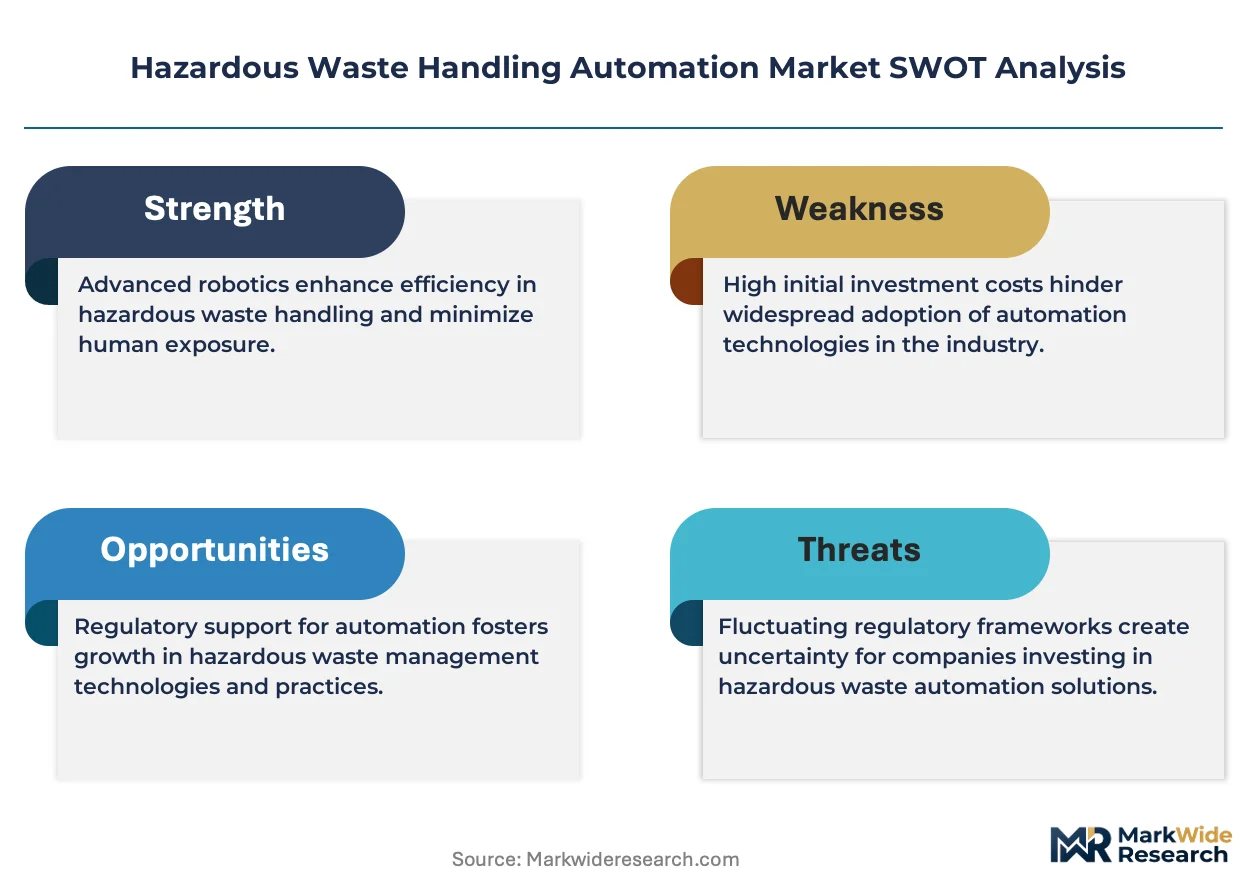
Strategic Opportunities
- South Korean Smart Factory Mandates:Government incentives for Industry 4.0 adoption in chemical processing create subsidy-backed demand for integrated waste handling robotics.
- Healthcare Facility Underpenetration:Hospital and pharmaceutical manufacturing sites in secondary US metropolitan markets remain below 15 percent automation penetration for pharmaceutical waste streams.
- Digital Twin Convergence:Integration of predictive maintenance algorithms with robotic handling hardware enables outcome-based service pricing that transfers operational risk to equipment vendors.
Industry Challenges
- Certified Technician Scarcity:Cross-trained professionals capable of servicing both mechanical robotics and radiological containment protocols command premium wages that compress operator margins.
- Legacy System Integration Complexity:Brownfield treatment facilities require custom mechanical interfaces between new robotic cells and existing conveyor infrastructure, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Waste Handling Automation Market |
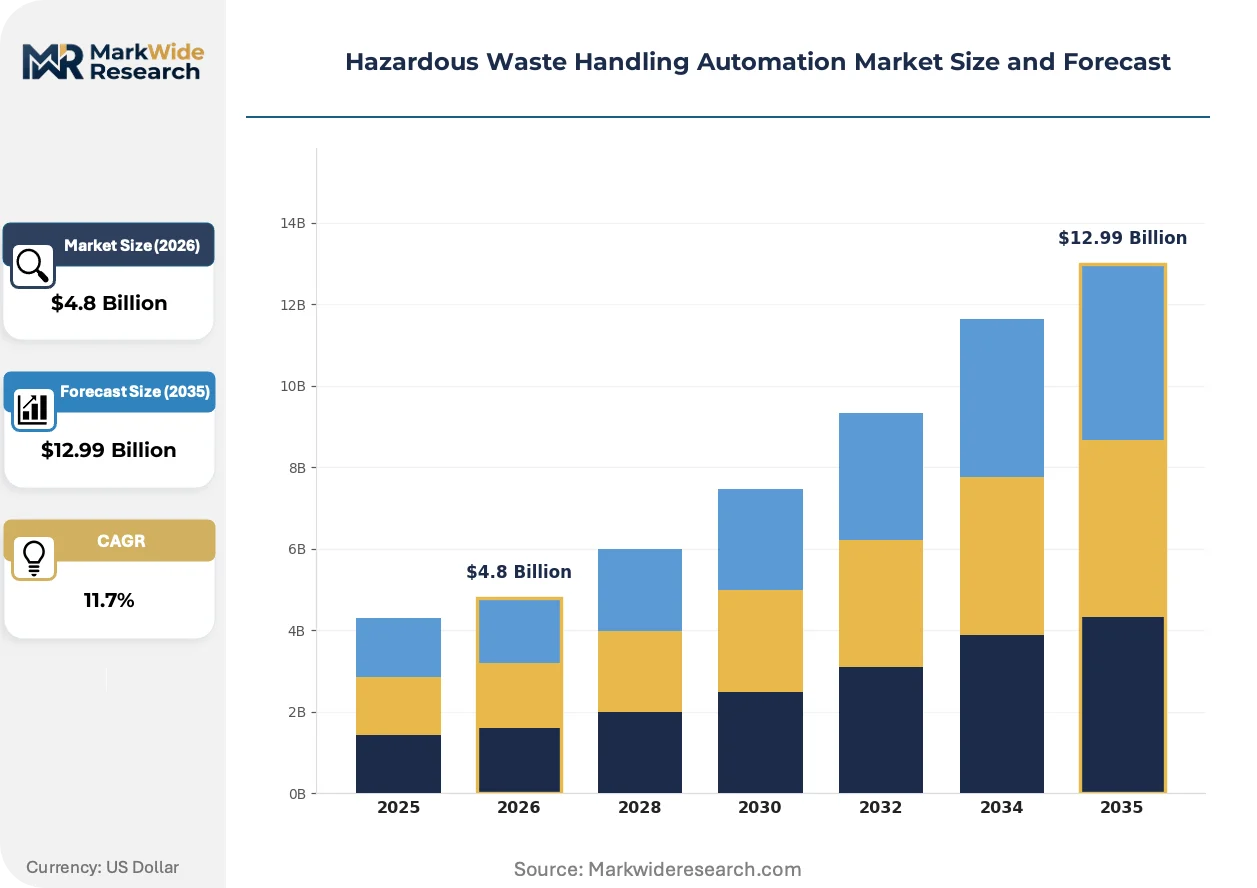
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotics, AI Automation, IoT Solutions, Sensor Systems End User: Manufacturers, Waste Management Firms, Environmental Agencies, Healthcare Facilities Type: Collection Systems, Treatment Units, Storage Solutions, Transport Vehicles Service Type: Consulting, Installation, Maintenance, Training |
| Companies Covered | Terex Corporation, Konecranes, Hiab, Pallmann Maschinenfabrik, Hosokawa Micron Powder Systems, Veolia Environment SA, Clean Harbors, ABB Ltd, PaR Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Waste Handling Automation Market Strategic Shifts
Automation architectures are fragmenting from monolithic turnkey systems toward modular, interoperable components that permit incremental upgrades without full facility shutdowns. This shift reflects pressure to maintain operational continuity during compliance-driven retrofits.
Collaborative robotic arms with force-limiting joints are fragmenting traditional industrial robot deployments in hazardous environments. Pharmaceutical manufacturers and laboratory waste handlers are adopting these systems for tasks requiring human proximity during exception handling. The technology is fragmenting the historical bifurcation between fully automated and fully manual operations, creating intermediate operational modes that reduce exposure while preserving flexibility.
REACH compliance deadlines for substance registration are forcing European chemical processors to document handling chain-of-custody with greater granularity. Automated tracking systems that log container movements, environmental conditions, and operator access are becoming embedded in facility design specifications. German and Dutch treatment operators are responding by specifying robotics with integrated data-logging capabilities that satisfy audit requirements without manual record-keeping.
Buyer concentration among large integrated waste management firms is compressing vendor negotiation cycles and unbundling after-sales service from equipment procurement. These operators are establishing preferred supplier frameworks that standardize on specific robotic platforms across multiple facility locations. The shift is most visible in the United States, where Veolia and Republic Services are consolidating vendor relationships to reduce spare parts inventory complexity and technician training overhead.
Hazardous Waste Handling Automation Market Segmentation
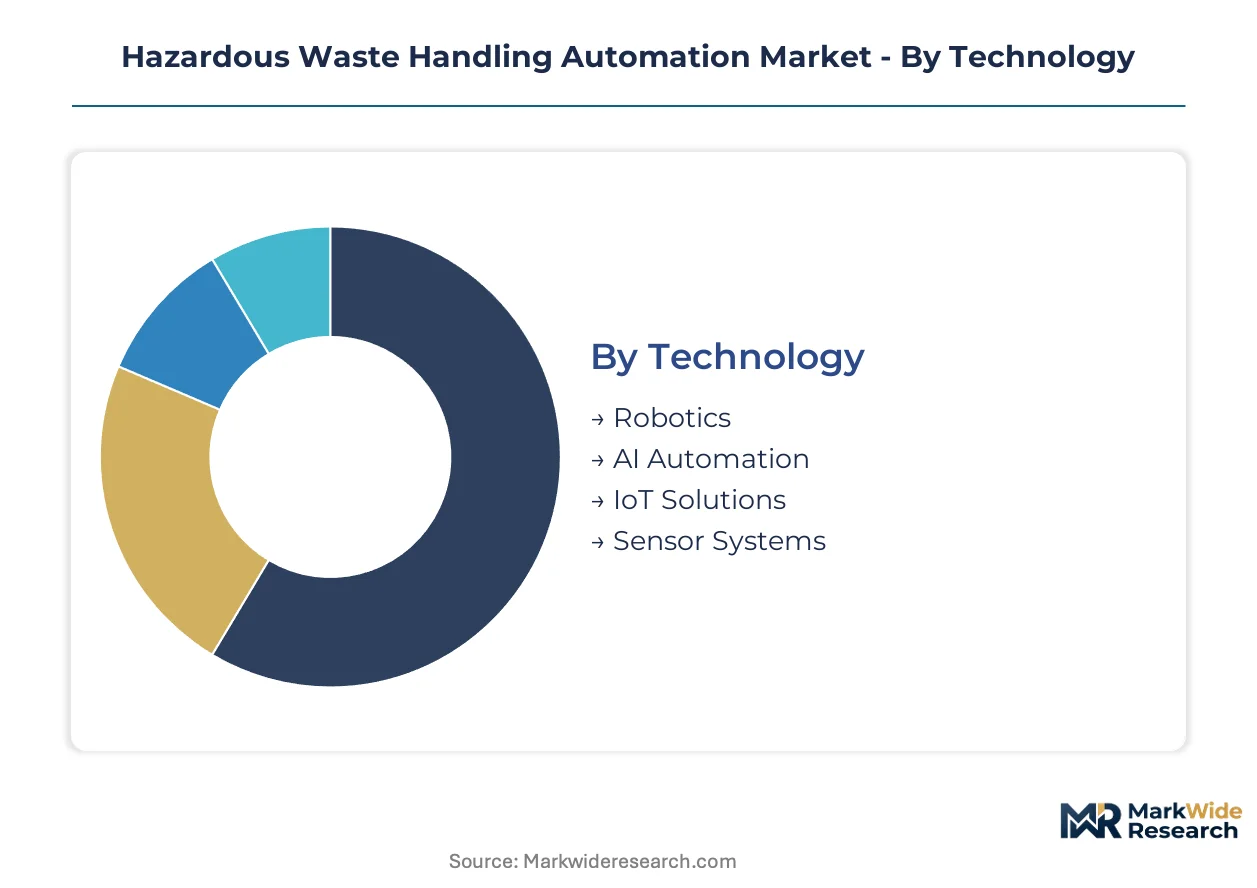
Segmentation in hazardous waste handling automation reveals distinct margin architectures shaped by capital intensity, regulatory compliance burdens, and technical differentiation. Technology choices determine equipment pricing power, while end-user concentration dictates contract structures and service attach rates.
Technology:
Margin pools concentrate in systems that reduce human exposure hours while maintaining throughput under sealed environment constraints.
- Robotics:Electromechanical manipulators with force-limiting joints and sealed bearing assemblies operate within negative pressure differentials of 0.5 to 2.5 inches water column. Demand clusters in German and South Korean chemical corridors where legacy infrastructure replacement cycles coincide with remote-handling mandates.
- AI Automation:Machine vision architectures enable real-time waste stream characterization and sorting decisions at throughput rates exceeding manual operations. Healthcare facilities in secondary US metropolitan markets drive adoption as pharmaceutical waste complexity outstrips human sorting capacity.
- IoT Solutions:Connected sensor networks for environmental monitoring and container tracking satisfy REACH chain-of-custody documentation requirements.
- Sensor Systems:Radiation-hardened and chemical-resistant detection modules concentrate procurement among Japanese and German suppliers.
The dominant share belongs to Robotics, while AI Automation is expanding most quickly as vision processing costs decline and regulatory documentation requirements tighten.
End User:
Customer type shapes contract duration, financing structures, and service bundling intensity across the value chain.
- Manufacturers:Chemical and pharmaceutical producers with continuous process operations require integrated handling cells that maintain production continuity during compliance retrofits. EPA generator standards compress upgrade timelines for US-based facilities.
- Waste Management Firms:Veolia and Republic Services consolidate vendor relationships across multi-site footprints to reduce spare parts inventory complexity and technician training overhead. These operators command preferred supplier frameworks that standardize robotic platforms.
- Environmental Agencies:Government treatment facilities prioritize equipment with extended service intervals and domestic sourcing requirements.
- Healthcare Facilities:Hospital and pharmaceutical manufacturing sites in secondary US metropolitan markets remain below 15 percent automation penetration for pharmaceutical waste streams.
Waste Management Firms capture the dominant procurement volume, while Healthcare Facilities show the steepest expansion trajectory as liability exposure drives automation investment.
Type:
Equipment category determines capital deployment timing and facility integration complexity.
- Collection Systems:Automated sorting and containerization equipment for waste stream segregation. Brownfield facilities require custom mechanical interfaces between new robotic cells and existing conveyor infrastructure.
- Treatment Units:Thermal, chemical, and biological processing automation operating under sealed containment. Rhine-Ruhr and Bavarian chemical corridors generate replacement demand as legacy infrastructure reaches end-of-life.
- Storage Solutions:Temperature-controlled and pressure-managed containment systems. EU F-Gas Regulation restricts fluorinated greenhouse gases in cooling specifications.
- Transport Vehicles:Automated guided vehicles and remote-operated container handling for intermodal transfer applications.
Treatment Units hold the dominant share, while Collection Systems are gaining share fastest as retrofit demand accelerates ahead of compliance deadlines.
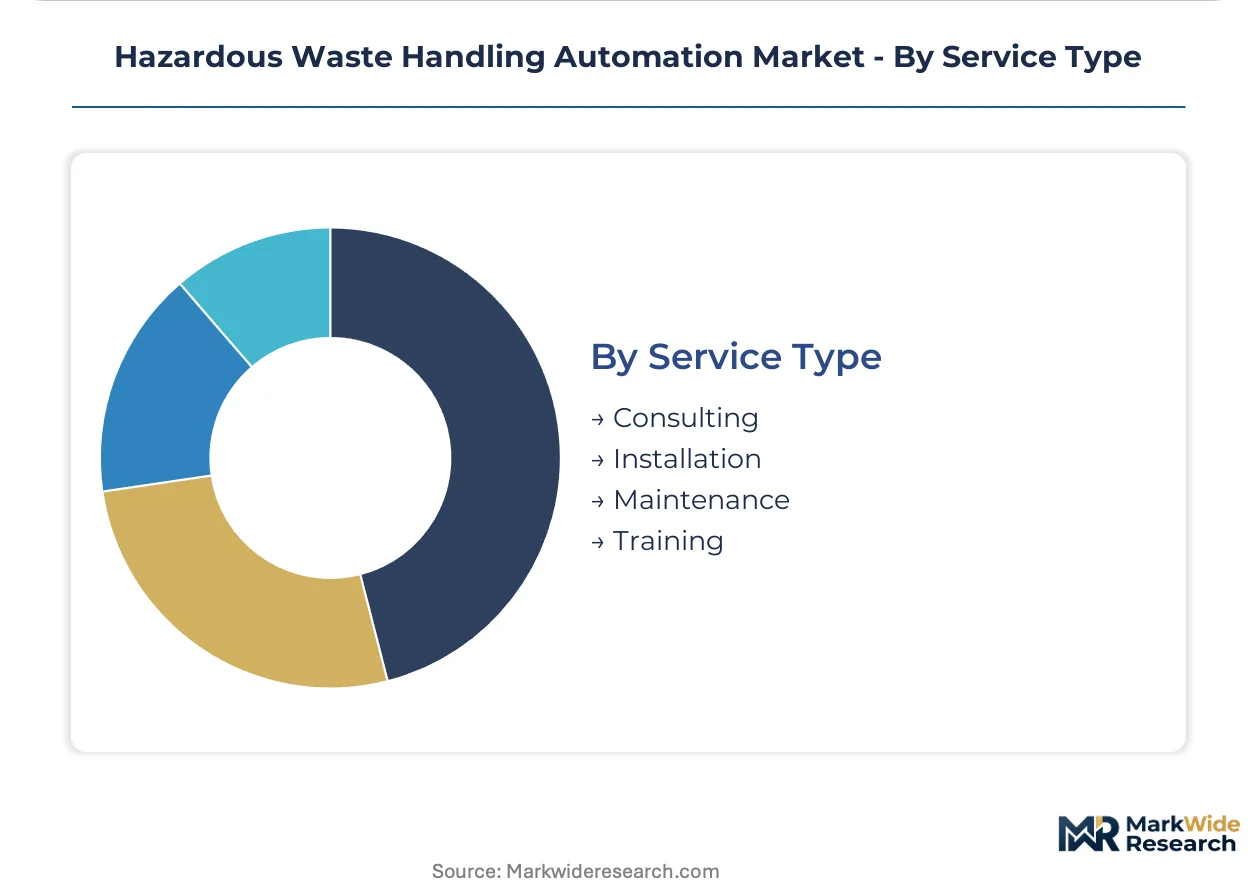
Service Type:
Recurring revenue attachment varies by equipment complexity and regulatory certification requirements.
- Consulting:Facility design and compliance pathway planning for brownfield retrofits and greenfield construction.
- Installation:Commissioning of sealed environment systems with pressure differential validation and emissions testing protocols.
- Maintenance:Predictive algorithms integrated with robotic hardware enable outcome-based service pricing that transfers operational risk to equipment vendors.
- Training:Cross-certification programs for technicians capable of servicing both mechanical robotics and radiological containment protocols command premium pricing.
Maintenance commands the dominant share, while Training shows the fastest climb as certified technician scarcity compresses operator margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA hazardous waste generator standards are compressing facility upgrade timelines across the United States, forcing chemical manufacturers and treatment operators to accelerate capital deployment into remote-handling architectures before compliance deadlines lock in equipment specifications.
United States
Chemical manufacturers along the Gulf Coast and Ohio River Valley are retrofitting legacy treatment infrastructure with robotic handling cells. EPA generator standards mandate engineered controls that reduce worker exposure hours in containment zones. Houston and Baton Rouge industrial clusters concentrate demand for automated sorting systems as facilities race to meet 2024-2026 compliance windows.
Germany
Rhine-Ruhr and Bavarian chemical corridors generate replacement demand as treatment infrastructure reaches end-of-life. EU REACH compliance deadlines force processors to document handling chain-of-custody with greater granularity. Leverkusen and Ludwigshafen industrial sites are specifying robotics with integrated data-logging capabilities that satisfy audit requirements without manual record-keeping.
Japan
Precision servo motors and radiation-hardened sensors concentrate procurement among domestic suppliers, exposing global buyers to lead-time volatility. METI industrial modernization programs subsidize Industry 4.0 adoption in chemical processing. Kawasaki and Yokkaichi petrochemical complexes anchor demand for sealed environment automation operating at negative pressure differentials.
South Korea
Government incentives for smart factory mandates in chemical processing create subsidy-backed demand for integrated waste handling robotics. MFDS pharmaceutical waste regulations tighten documentation requirements for manufacturing facilities. Ulsan and Yeosu industrial complexes are modernizing legacy treatment infrastructure with robotic handling cells to meet remote-handling mandates.
France
Nuclear decommissioning and radiological waste handling drive specialized automation demand distinct from chemical sector applications. ANSM pharmaceutical manufacturing standards enforce containment protocols that favor robotic material handling. Normandy and Rhône-Alpes treatment facilities are consolidating vendor relationships to reduce spare parts inventory complexity and technician training overhead.
Hazardous Waste Handling Automation Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the hazardous waste handling automation market. The vendor base fragments across integrated waste management conglomerates, specialized robotics manufacturers, and heavy-lift automation specialists. Three strategic archetypes dominate: full-service operators bundling equipment with long-term service contracts, precision robotics engineers targeting radiological and chemical containment applications, and port-intermodal heavy-lift specialists. Competitive positioning hardens through preferred supplier frameworks that standardize robotic platforms across multi-site footprints, and outcome-based service pricing that transfers operational risk to equipment vendors.
Among the integrated service operators, Veolia Environment SA exemplifies the full-service archetype that anchors long-term automation contracts through collection-to-disposal footprint control. ABB Ltd occupies a position within the precision robotics tier, with its specialization in sealed-environment manipulator architectures. Konecranes represents the heavy-lift automation segment, competing on containerized hazardous cargo transfer applications where port and intermodal infrastructure demands dominate procurement specifications.
| Leading Market Players |
|---|
| Terex Corporation |
| Konecranes |
| Hiab |
| Pallmann Maschinenfabrik |
| Hosokawa Micron Powder Systems |
| Veolia Environment SA |
| Clean Harbors |
| ABB Ltd |
| PaR Systems |
| Others |
Value Chain & Pricing Dynamics
Scale economies in sealed-environment fabrication anchor price floors for negative pressure differential systems, concentrating procurement leverage among Japanese and German component suppliers while compressing margins for mid-scale treatment operators lacking long-term service contract volume.
Pricing Analysis
Japanese and German suppliers command price spreads of 15-30 percent above South Korean and Chinese alternatives for radiation-hardened sensors and precision servo motors. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified systems with integrated data-logging from basic robotic cells lacking REACH audit capabilities. Cost compression in the standard tier is intensifying because waste management firms are consolidating vendor relationships across multi-site footprints. Healthcare facilities in secondary US metropolitan markets exhibit the highest price sensitivity due to capital constraint and sub-15 percent automation penetration, while integrated operators like Veolia demonstrate the lowest sensitivity through outcome-based service pricing that bundles equipment and maintenance.
Supply Chain Analysis
Inventory buffers for precision servo motors and radiation-hardened sensors have thinned to 8-12 weeks across North American and European treatment equipment assemblers. Component supply concentrates in Japan, Germany, and South Korea, with domestic content requirements complicating procurement for government treatment facilities in France and the United States. Raw material dependencies include rare-earth magnets for servo motors, borosilicate glass for containment viewports, and fluoropolymer seals for chemical resistance. Single-source vulnerability in Japanese sensor suppliers exposes procurement to lead-time volatility from seismic disruption or export licensing friction. Distribution runs through preferred supplier frameworks established by Veolia and Republic Services that standardize robotic platforms across facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA hazardous waste generator standards and OSHA process safety management enforcement are compressing facility upgrade timelines into a narrow compliance window, creating concentrated demand inflection for remote-handling architectures.
For Market Incumbents: Fortify service attach rates by embedding predictive maintenance algorithms that enable outcome-based pricing, transferring operational risk from waste management operators to equipment vendors. Deepen backward integration into precision servo motor supply through captive relationships with Japanese component houses, insulating against lead-time volatility that threatens commissioning timelines. Counter emerging modular automation entrants by bundling sealed-environment validation and emissions testing protocols into long-term contracts that lock in specification continuity. For New Entrants and Emerging Players: EPA certification fast-track for pharmaceutical waste handling systems opens white-space penetration in secondary US metropolitan markets where hospital automation remains below 15 percent. Target healthcare facilities with collaborative robotic arms featuring force-limiting joints that reduce exposure while preserving human proximity for exception handling. Pursue go-to-market partnerships with GPOs and hospital purchasing committees rather than direct capital equipment sales, aligning procurement cycles with facility budget windows. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service operators bundling equipment with predictive maintenance and compliance documentation services. Five-to-ten year viability favors vendors with established preferred supplier frameworks across multi-site waste management footprints. Acquisition target archetype: precision robotics engineers with sealed-environment manipulator architectures and existing EPA or REACH certification pathways. Signal to watch: consolidation velocity among US waste management firms as vendor relationship standardization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Preferred Supplier Framework Consolidation | Veolia and Republic Services standardize robotic platforms to reduce spare parts inventory complexity across facility networks. |
| Machine Vision Integration | AI-driven waste stream characterization enables real-time sorting decisions that exceed manual throughput rates in healthcare facilities. |
| Outcome-Based Service Pricing | Predictive maintenance algorithms transfer operational risk from waste management operators to equipment vendors through risk-sharing contracts. |
| Collaborative Robotic Deployment | Force-limiting joint architectures fragment traditional industrial robot deployments in pharmaceutical manufacturing and laboratory waste handling. |
| REACH Compliance Data-Logging | Integrated container tracking satisfies EU audit requirements without manual record-keeping in Rhine-Ruhr and Bavarian chemical corridors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors at treatment facilities, OEM procurement teams, and aftermarket service heads; and secondary validation through EPA enforcement action databases, OSHA process safety management incident reports, SEC 10-K filings from listed waste management operators, and EU ECHA REACH registration data. Bottom-up triangulation across equipment shipment records and top-down validation against capital expenditure disclosures from chemical manufacturers anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation across technology tier, end-user concentration, equipment category, and service attachment intensity. CAGRs were derived from regression analysis of historical capital deployment patterns against regulatory compliance deadline clustering. Industry-specific forecast inputs included EPA generator standard enforcement velocity, METI and MFDS subsidy program allocations, and brownfield retrofit commissioning timelines.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement pressure or supply chain disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding compliance deadline adherence and component supplier capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market