
 Carbon Management System Market | 2026-2036
Carbon Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Management System Market Analysis
Asset-light SaaS subscription and usage-based financing is rewriting competitive entry barriers for carbon management platforms. Persefoni AI leverages cloud-native architecture to reduce upfront deployment costs for mid-market manufacturers. Watershed Technology Inc anchors its position through granular supply chain emissions calculations that sustain pricing power against generic ERP modules.
A carbon management system comprises software platforms, sensor hardware, and integration services that measure, track, and report greenhouse gas emissions across organizational boundaries, typically processing data through IoT-enabled meters and cloud-based analytics engines to generate audit-grade carbon inventories. Software dominates current deployments due to recurring revenue scalability and lower marginal delivery costs. AI-powered data analysis represents the fastest-expanding technology segment as machine learning models improve emission factor matching and anomaly detection accuracy. Blockchain-enabled verification remains nascent but attracts pilot investments from energy traders seeking immutable audit trails.
The US EPA greenhouse gas reporting program and the EU CSRD mandate granular Scope 1-3 disclosures, forcing enterprises to replace spreadsheet-based tracking with certified platform solutions. California's climate disclosure regulations extend these requirements to private companies above revenue thresholds, expanding the addressable customer base. Stakeholders must monitor evolving jurisdictional fragmentation in reporting standards to avoid redundant system investments.
Market Dynamics
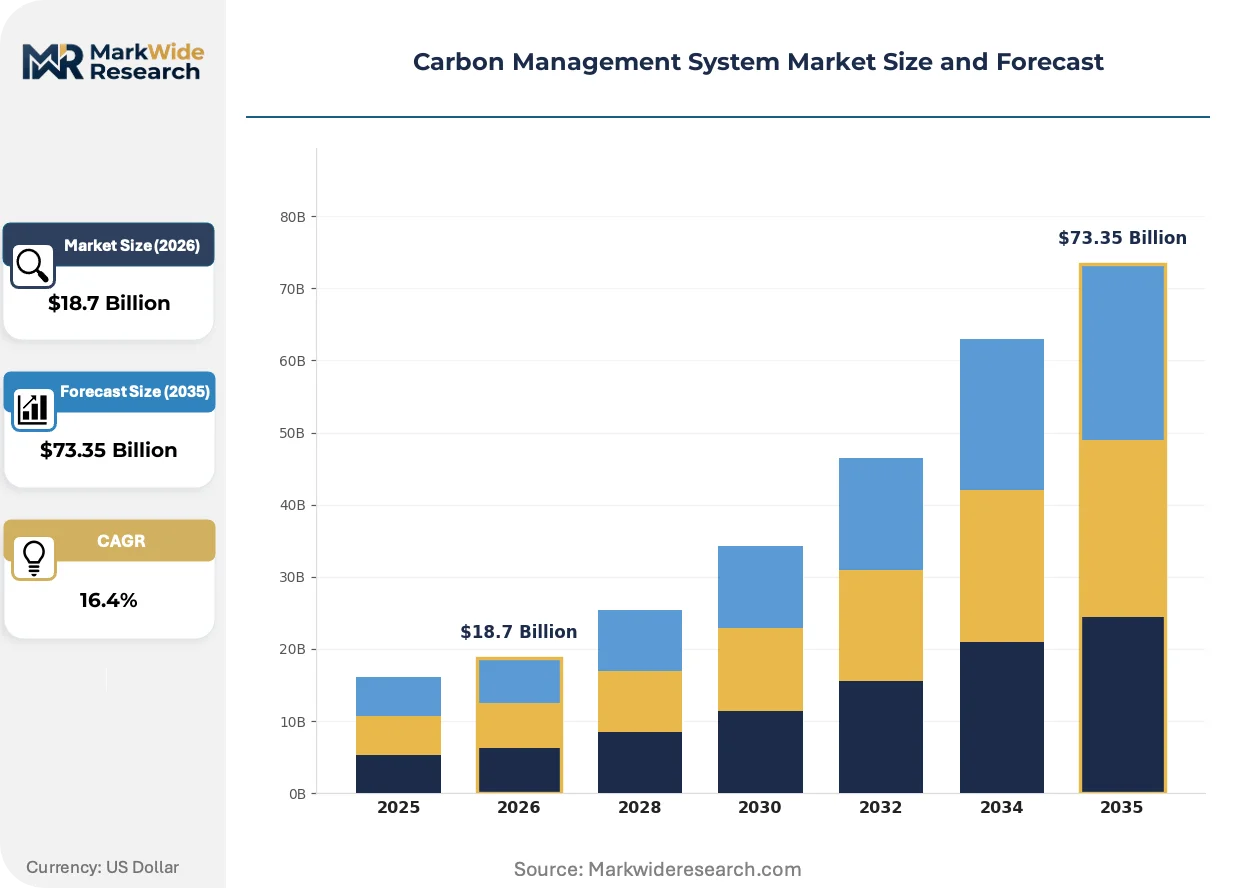
The carbon management system market is being reshaped by mandatory disclosure regimes that force enterprises to replace manual tracking with certified software platforms capable of audit-grade Scope 1-3 emissions calculations.
Growth Catalysts
- EU CSRD compliance deadlines:Large undertakings must submit granular sustainability reports starting 2024, creating immediate demand for automated data collection and verification workflows.
- California SB 253 and SB 261:Climate disclosure laws extend emissions reporting requirements to private companies above revenue thresholds, expanding the addressable customer base beyond publicly traded firms.
- Industrial cluster deployment:Germany's chemical and steel corridors are integrating sensor networks with cloud analytics to meet EU ETS verification standards and reduce compliance labor costs.
Market Restraints
- Emission factor database fragmentation:Inconsistent regional methodologies for calculating Scope 3 upstream and downstream emissions force vendors to maintain multiple calculation engines, raising R&D overhead.
- Sensor hardware supply concentration:Precision IoT metering components for fugitive methane and process emissions rely heavily on East Asian contract manufacturers, exposing deployment timelines to geopolitical friction.
- Legacy ERP integration complexity:Enterprise resource planning systems from the 2010s lack standardized APIs for emissions data, requiring costly middleware development that delays platform value realization.
Strategic Opportunities
- Blockchain-enabled verification pilots:Energy traders and commodity exchanges are testing immutable audit trails for carbon credit origination, opening a nascent revenue stream for platforms with cryptographic attestation capabilities.
- Mid-market manufacturing penetration:Asset-light SaaS subscription models reduce upfront deployment costs for sub-$500M revenue manufacturers previously excluded from enterprise-tier solutions.
- AI-powered anomaly detection:Machine learning models that flag data gaps and emission factor mismatches are commanding pricing premiums against rules-based calculation engines.
Industry Challenges
- Carbon accounting talent scarcity:Platforms struggle to hire professionals certified in GHG Protocol Corporate Standard and ISO 14064-1 implementation, slowing customer onboarding and support scaling.
- Multi-jurisdictional standard divergence:The absence of harmonized disclosure frameworks between the EU CSRD, US SEC climate rules, and emerging APAC mandates forces customers into redundant system investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Management System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Service, Integration Technology: IoT, Cloud Computing, AI, Blockchain End User: Manufacturing, Transportation, Energy, Urban Development Application: Emission Tracking, Carbon Reporting, Data Analysis, Compliance Management |
| Companies Covered | IBM, Microsoft, SAP, Salesforce, Schneider Electric, Persefoni AI, Watershed Technology Inc, ENGIE Impact, Sphera Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Management System Market Emerging Trajectories
Carbon management platforms are converging with adjacent enterprise software categories as vendors race to own the emissions data layer across procurement, logistics, and financial reporting workflows.
Sensor-to-cloud architectures are hybridizing physical metering infrastructure with software analytics layers. Industrial facilities in the US Gulf Coast petrochemical corridor are deploying edge-computing nodes that preprocess raw emissions data before transmission to central platforms. This convergence is compressing the traditional separation between hardware instrumentation vendors and pure-play SaaS providers, forcing both categories to develop hybrid competencies.
The EU CSRD's double materiality assessment requirements are mandating that sustainability disclosures cover both financial impact and environmental effect. German automotive suppliers and French luxury goods manufacturers are rebuilding data collection processes to capture supplier-tier emissions previously excluded from reporting. This regulatory architecture is accelerating procurement department involvement in platform selection decisions, displacing sole IT-department ownership of carbon software investments.
Enterprise buyers are consolidating vendor relationships around integrated sustainability suites rather than point solutions for carbon tracking alone. US-based Fortune 500 manufacturers are favoring platforms that embed emissions calculations directly into existing ERP and supply chain management workflows. This preference shift is most visible in the consumer packaged goods vertical, where procurement teams now require carbon intensity metrics alongside unit pricing in supplier scorecards.
Carbon Management System Market Segmentation
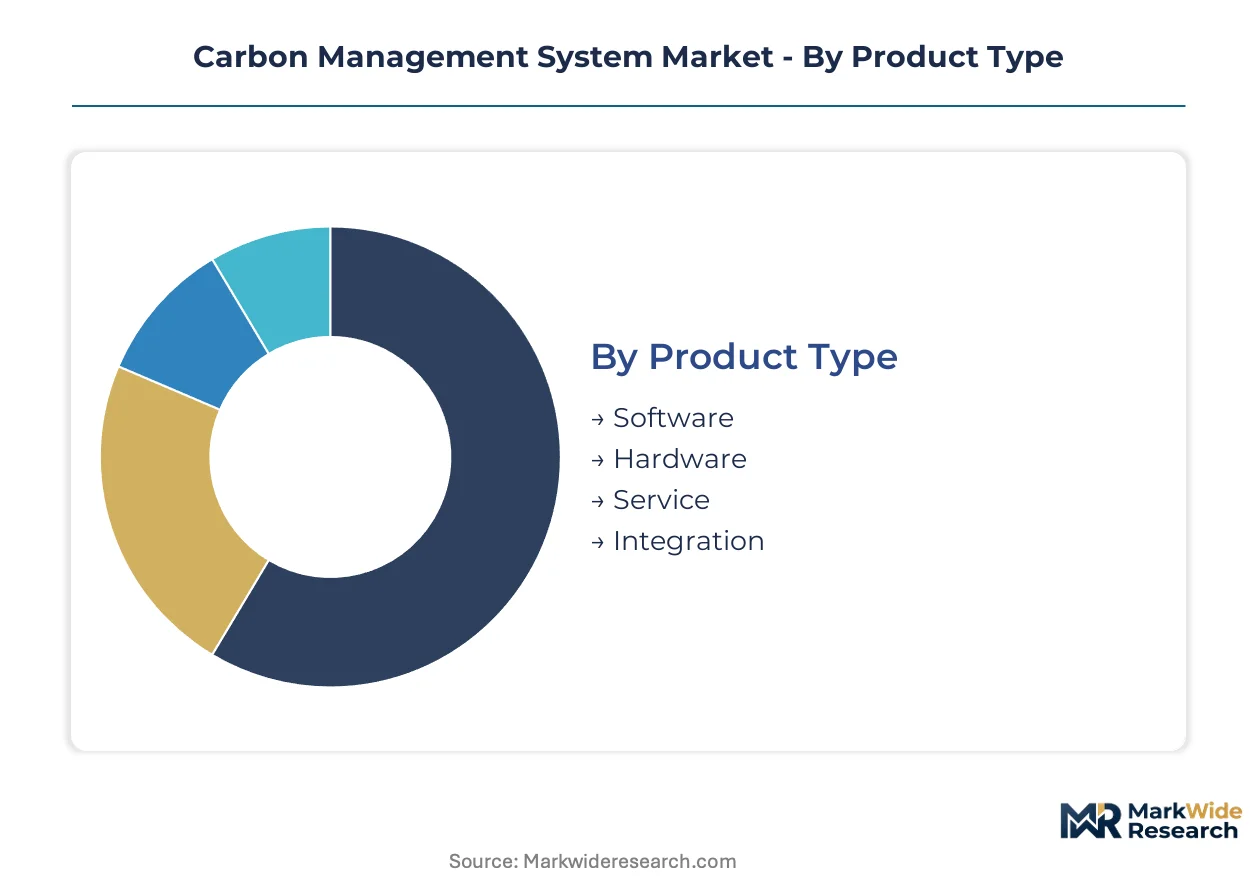
Carbon management systems fragment across product architecture, enabling technology, customer vertical, and functional use case. Each dimension shapes procurement decisions, integration complexity, and pricing models differently.
Product Type:
Cost tier separates deployment approaches, with capital intensity and recurring revenue potential varying sharply across physical instrumentation versus intangible platforms.
- Software:Cloud-native platforms process emissions data through algorithmic calculation engines, generating audit-grade carbon inventories without on-premise infrastructure. German automotive suppliers and French luxury manufacturers favor subscription models that embed directly into procurement workflows, displacing spreadsheet-based tracking.
- Hardware:IoT-enabled sensors and precision metering devices capture fugitive methane, process emissions, and energy consumption at source. Deployment concentrates in US Gulf Coast petrochemical corridors where edge-computing nodes preprocess raw data before cloud transmission, though East Asian contract manufacturing concentration exposes timelines to supply friction.
- Service:Implementation consulting, system integration, and ongoing technical support bridge capability gaps for mid-market enterprises lacking in-house carbon accounting expertise.
- Integration:Middleware and API development connect carbon platforms to legacy ERP systems from the 2010s, addressing standardized emissions data exchange where native connectivity is absent.
Software commands the established base. The steepest expansion runs through Integration as ERP connectivity gaps persist.
Technology:
Application maturity and computational sophistication differentiate technology layers, with some segments delivering immediate utility while others remain experimental.
- IoT:Distributed sensor networks stream real-time emissions telemetry from industrial equipment, building systems, and fleet assets. Chemical and steel corridors in Germany deploy these architectures to meet EU ETS verification standards.
- Cloud Computing:Scalable data infrastructure enables multi-tenant platform delivery, reducing per-customer hosting overhead and supporting usage-based pricing for sub-$500M revenue manufacturers.
- AI:Machine learning models automate emission factor matching, flag data gaps, and detect anomalies in consumption patterns. These capabilities command pricing premiums against rules-based calculation engines in procurement scorecards.
- Blockchain:Cryptographic attestation creates immutable audit trails for carbon credit origination. Energy traders and commodity exchanges pilot these capabilities, though commercial scale remains nascent.
Cloud Computing anchors current deployments. The steepest climb belongs to AI as accuracy demands intensify.
End User:
Customer type reflects regulatory exposure and operational complexity, with disclosure mandates and supply chain depth driving platform sophistication requirements.
- Manufacturing:Discrete and process manufacturers track Scope 1-3 emissions across complex supplier networks. EU CSRD double materiality assessments force German automotive suppliers to capture previously excluded tier-2 and tier-3 emissions data.
- Transportation:Fleet operators and logistics providers monitor fuel combustion and electricity consumption across mobile assets. California's SB 253 climate disclosure regulations extend reporting requirements to private trucking and aviation operators above revenue thresholds.
- Energy:Utilities and independent power producers face EPA greenhouse gas reporting program mandates requiring granular fuel-specific emission calculations.
- Urban Development:Municipal governments and real estate developers track building-level emissions and infrastructure carbon intensity for climate action planning.
Manufacturing holds the deepest installed base. The steepest expansion trajectory runs through Transportation as fleet electrification complicates emission accounting.
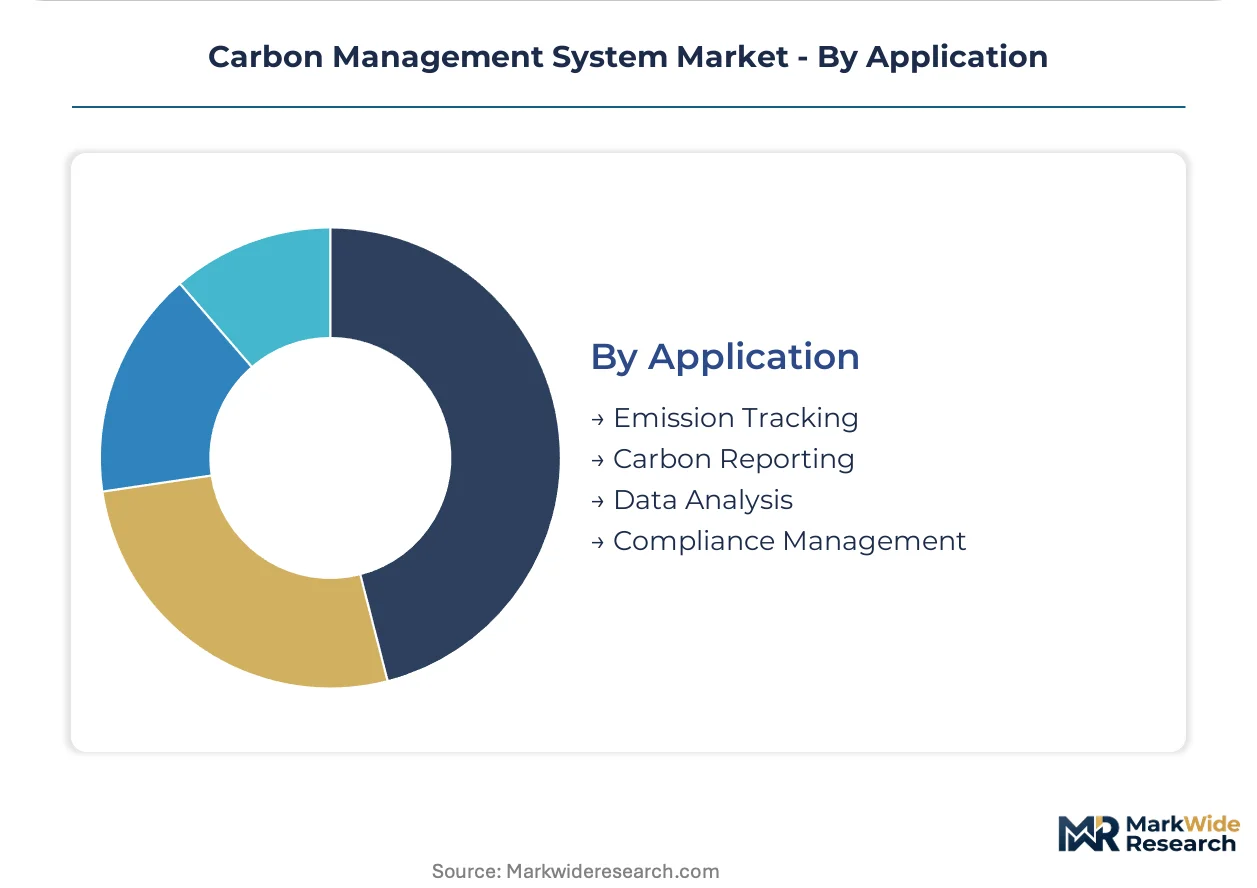
Application:
Functional use case determines workflow integration depth, with some applications operating as standalone tools while others embed into core enterprise systems.
- Emission Tracking:Continuous monitoring of greenhouse gas sources across organizational boundaries, from stationary combustion to mobile sources and process emissions.
- Carbon Reporting:Structured disclosure generation aligned with GHG Protocol Corporate Standard, ISO 14064-1, and jurisdiction-specific formats including EU CSRD and California climate filings.
- Data Analysis:Diagnostic and predictive analytics identify reduction opportunities, benchmark performance, and model decarbonization pathways.
- Compliance Management:Automated workflow engines manage verification schedules, documentation requirements, and regulator submission deadlines across multi-jurisdictional footprints.
Emission Tracking represents the foundational capability. Compliance Management is gaining share fastest as regulatory fragmentation intensifies administrative burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon disclosure mandates are concentrating platform investments in jurisdictions with binding emissions reporting laws. Regulatory deadlines in the EU, US, and Asia-Pacific are forcing enterprises to replace manual tracking with certified software systems.
United States
California's SB 253 and SB 261 climate disclosure laws extend emissions reporting requirements to private companies above revenue thresholds. The EPA greenhouse gas reporting program mandates granular fuel-specific calculations for utilities and industrial facilities. US Gulf Coast petrochemical corridors deploy edge-computing sensor networks to preprocess raw emissions data before cloud transmission.
Germany
Industrial clusters in chemical and steel corridors integrate IoT-enabled metering with cloud analytics to meet EU ETS verification standards. The EU CSRD double materiality assessment requirements force automotive suppliers to capture previously excluded tier-2 and tier-3 supplier emissions. Bavarian and North Rhine-Westphalian manufacturing hubs lead deployment of integrated monitoring systems.
France
French luxury goods manufacturers rebuild data collection processes to capture supplier-tier emissions under CSRD scope expansion mandates. The national climate and resilience law tightens corporate carbon footprint disclosure requirements for large enterprises. Paris-based headquarters operations drive procurement department involvement in platform selection decisions.
China
Dual carbon goals and provincial emissions trading pilots accelerate demand for audit-grade carbon inventory systems. The Ministry of Ecology and Environment strengthens monitoring requirements for heavy industry and power generation. Yangtze River Delta manufacturing zones deploy sensor networks to verify process emissions for regional carbon markets.
United Kingdom
Streamlined Energy and Carbon Reporting regulations mandate disclosure for quoted companies and large unquoted businesses. The Financial Conduct Authority requires climate-related financial disclosures aligned with TCFD recommendations. London-based financial services firms pilot blockchain-enabled verification for carbon credit origination and trading.
Carbon Management System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across software, hardware, and service layers. The vendor base segments into three tiers: enterprise technology conglomerates with embedded sustainability modules, pure-play carbon management specialists with vertical expertise, and industrial automation firms with sensor-to-cloud integration capabilities. Dominant competitive moves include strategic partnerships with ERP providers and geographic expansion through regulatory-driven market entry.
Within the pure-play specialist tier, Persefoni AI and Watershed Technology Inc exemplify cloud-native architectures that reduce upfront deployment costs for mid-market manufacturers. IBM, Microsoft, and SAP occupy positions as enterprise technology conglomerates leveraging existing customer relationships to embed emissions tracking into broader sustainability suites. Schneider Electric and ENGIE Impact represent industrial automation and energy service incumbents extending into carbon software through captive hardware-to-software integration.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| SAP |
| Salesforce |
| Schneider Electric |
| Persefoni AI |
| Watershed Technology Inc |
| ENGIE Impact |
| Sphera Solutions |
| Others |
Supply Flow & Price Mechanics
East Asian contract manufacturing concentration for precision IoT metering components concentrates upstream margin capture with semiconductor foundries and sensor module assemblers, while downstream pricing power accrues to platforms with AI-powered anomaly detection capabilities that command subscription premiums against rules-based alternatives.
Pricing Analysis
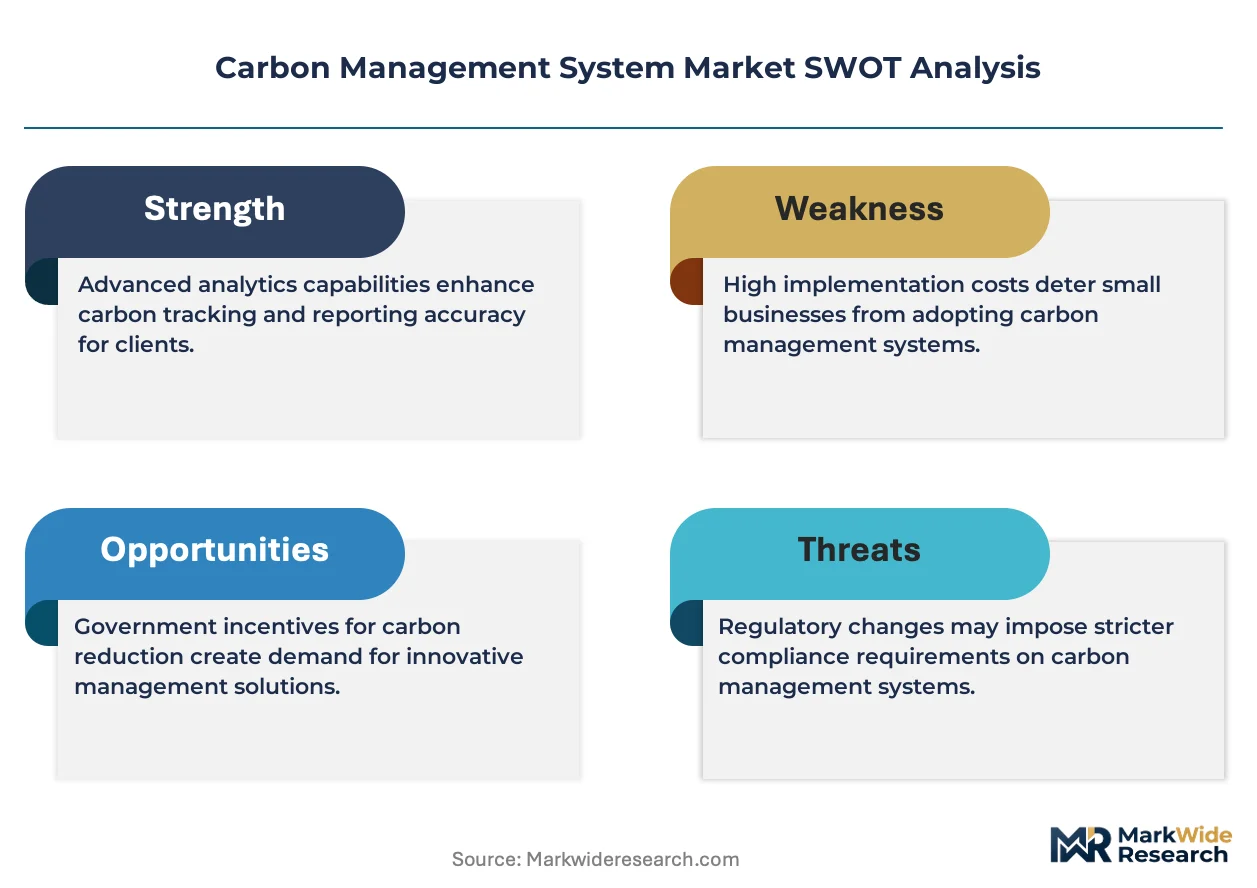
Certification level against GHG Protocol Corporate Standard and ISO 14064-1 creates the primary spread between audit-grade platforms and spreadsheet-based tracking tools. Three-tier pricing structure across enterprise, mid-market, and SMB levels segments by integration depth and supplier network complexity. Cost compression in the mid-market tier is intensifying because asset-light SaaS entrants reduce upfront deployment barriers. Procurement teams at sub-$500M revenue manufacturers exhibit highest price sensitivity, while EU CSRD-mandated filers accept premium pricing for automated verification workflows.
Supply Chain Analysis
Extended payment terms from East Asian contract manufacturers to IoT sensor assemblers compress working capital cycles for hardware vendors. Supply concentrates in Taiwan for semiconductor components, China for sensor module assembly, and South Korea for precision metering subsystems. Raw material dependencies span rare earth elements for magnetometers, silicon wafers for edge-computing chips, and specialized polymers for harsh-environment enclosures. Single-source vulnerability in precision methane detection sensors exposes deployment timelines to geopolitical friction. Distribution runs through direct enterprise sales for software platforms and systems integrators for hybrid hardware-software deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU CSRD, US SEC climate rules, and emerging APAC mandates creates white-space opportunities for specialized platforms addressing jurisdiction-specific calculation engines. Mid-market manufacturers previously excluded from enterprise-tier solutions represent the most addressable demand expansion.
For Market Incumbents: Pre-empt pure-play SaaS challengers by embedding emissions calculations directly into existing ERP and supply chain management workflows, displacing point-solution procurement. Deepen API standardization investments to reduce middleware development delays that plague legacy system integrations. Capture procurement department decision-making authority by embedding carbon intensity metrics alongside unit pricing in supplier scorecards. For New Entrants and Emerging Players: Southeast Asian manufacturing hubs with nascent emissions trading pilots offer the most penetrable geographic entry point for cloud-native platforms with localized calculation engines. Target private trucking and aviation operators in California facing SB 253 climate disclosure deadlines as a regulatory-forced adoption segment. Pursue channel partnerships with industrial automation distributors rather than direct enterprise sales to accelerate customer acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play carbon management specialists lacking ERP integration depth. Five-to-ten-year viability hinges on platforms achieving procurement workflow embedding rather than remaining standalone sustainability tools. Monitor EU CSRD implementation compliance rates as the inflection indicator for mid-market platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Integration Partnership | Salesforce and SAP alliances embed emissions tracking into procurement workflows, displacing standalone point solutions. |
| AI-Powered Anomaly Detection | Machine learning models flag data gaps in supplier-tier emissions, commanding pricing premiums against rules-based engines. |
| Blockchain Verification Pilot | Energy traders test immutable audit trails for carbon credit origination, opening nascent revenue streams for attestation-capable platforms. |
| Mid-Market SaaS Expansion | Asset-light subscription models reduce upfront costs for sub-$500M revenue manufacturers excluded from enterprise tiers. |
| Edge-Computing Sensor Deployment | Gulf Coast petrochemical facilities preprocess raw emissions data locally, compressing hardware-to-software integration timelines. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with sustainability officers, procurement directors, carbon accounting consultants, and ERP integration specialists; and secondary validation through EPA greenhouse gas reporting filings, EU CSRD regulatory texts, SEC climate disclosure proposals, and customs data on IoT sensor imports. Bottom-up platform deployment estimates triangulated against top-down regulatory mandate coverage projections.
Forecast inputs considered software subscription growth trajectories, hardware sensor shipment volumes, and service attachment rates across the projection horizon. Segmentation dimensions modeled include product architecture, enabling technology, customer vertical, and functional use case. CAGRs derived from regression analysis of disclosed platform revenues and regulatory deadline phasing. Industry-specific inputs span EU ETS verification standard adoption curves and California SB 253 implementation timelines.
Practitioners should monitor jurisdictional standard harmonization progress and sensor hardware supply chain stability for early signals of forecast deviation. Assumptions reflect current regulatory enforcement postures and platform technology roadmaps. Macroeconomic contraction reducing enterprise software budgets, regulatory rollback of disclosure mandates, or breakthrough standardization agreements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Smart Carbon Market