
 Europe Bio-Medical Waste Management Market | 2026-2036
Europe Bio-Medical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bio-Medical Waste Management Market Insights
Autoclave-grade sterilization certification is rotating through procurement specifications at major hospital groups across the continent. Veolia Environmental Services leverages its France-based incineration retrofit network to anchor high-temperature treatment capacity in saturated markets. SUEZ Group competes through integrated collection-to-disposal logistics that sustain margin capture across fragmented municipal contracting. Remondis Medison specializes in reverse-logistics packaging recovery, occupying a defensible niche in reusable container systems for laboratory waste streams.
Europe bio-medical waste management encompasses the regulated handling, treatment, and final disposition of infectious, hazardous, and pharmaceutical residues generated by healthcare facilities, with autoclaving achieving sterilization at 121–134°C and 15–30 psi pressure to neutralize pathogenic load before landfill or alternative processing. The sector serves primary industrial purposes of public health protection, environmental compliance, and occupational safety assurance across clinical and research settings. Treatment technology segments show incineration retaining volume leadership for anatomical and cytotoxic waste categories while autoclaving captures fastest expansion in standard infectious streams due to lower capital requirements and reduced emissions profiles. End user segmentation reveals hospitals commanding the deepest service contracts, though laboratories represent the fastest-growing addressable base as decentralized diagnostic testing expands across European healthcare systems.
EU Waste Framework Directive enforcement, REACH chemical handling protocols, and MDR medical device disposal traceability requirements collectively shape market access and service tier qualifications across member states. ECHA substance restrictions on mercury-containing wastes and EMA pharmaceutical residue guidelines further tighten treatment standards and documentation burdens for operators. Stakeholders must monitor pending revisions to F-Gas Regulation scope and emerging national extended producer responsibility schemes for healthcare plastics to anticipate capital allocation and technology transition timelines.
Market Dynamics
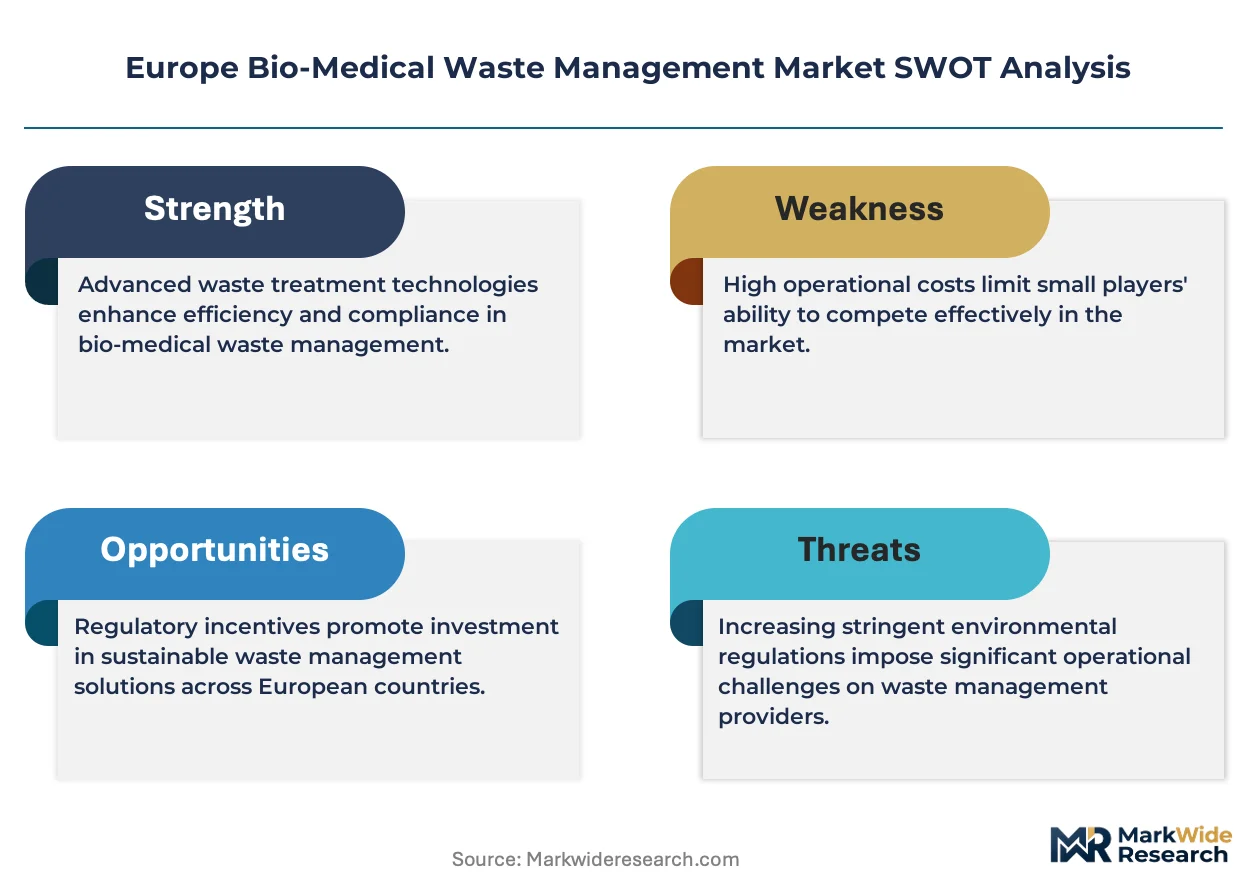
Autoclaving technology is displacing legacy incineration across European hospital networks as REACH-aligned chemical treatment standards and tightening EU Waste Framework Directive enforcement raise sterilization certification requirements for outsourced waste handling contracts.
Growth Catalysts
- EU Waste Framework Directive enforcement:Germany's federal environmental compliance mandates drive premium service demand across the Rhine-Ruhr hospital corridor, expanding outsourced contracts for certified sterilization providers.
- Decentralized diagnostic testing expansion:Laboratories represent the fastest-growing addressable base as point-of-care testing proliferates, generating infectious waste streams requiring specialized collection logistics.
- Autoclave-grade sterilization certification:Procurement specifications at major hospital groups now mandate 121–134°C and 15–30 psi pressure standards, rotating contract awards toward compliant operators.
Market Restraints
- Capital intensity of incineration retrofitting:High-temperature treatment capacity upgrades require substantial investment, limiting market entry for mid-scale operators in saturated French and Italian markets.
- ECHA substance restrictions on mercury-containing wastes:Specialized handling protocols for dental amalgam and thermometers add documentation burdens and compliance costs to service portfolios.
- Supply concentration in reusable container systems:Reverse-logistics packaging recovery networks remain concentrated among established providers, creating barriers for new entrants in laboratory waste segments.
Strategic Opportunities
- Extended producer responsibility schemes for healthcare plastics:Emerging national frameworks in Germany and France create incentive structures for integrated collection-to-recycling service models.
- Integrated collection-to-disposal logistics:Fragmented municipal contracting across Italy and Spain allows margin capture through unified service platforms spanning transport, treatment, and final disposition.
- Convergence of autoclaving with chemical pre-treatment:Hybrid sterilization systems for pharmaceutical residues address EMA residue guidelines while opening cytotoxic waste categories previously reserved for incineration.
Industry Challenges
- MDR medical device disposal traceability requirements:Documentation systems must track single-use instruments from clinical use through final treatment, straining legacy data infrastructure at smaller healthcare facilities.
- F-Gas Regulation scope revisions:Pending expansions to refrigerant-containing medical equipment disposal create uncertainty in capital allocation timelines for treatment technology investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bio-Medical Waste Management Market |
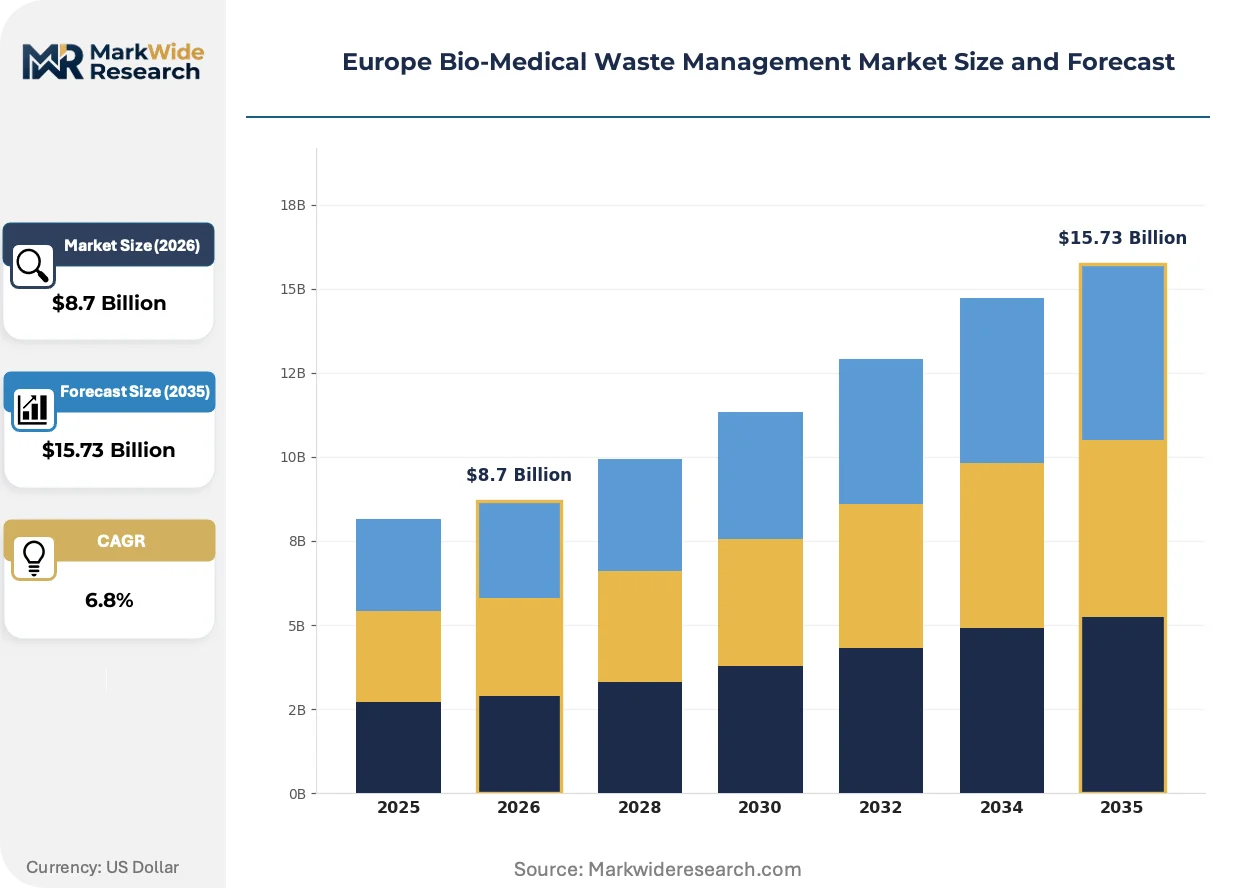
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Disposal, Recycling Waste Type: Infectious, Hazardous, Non-Hazardous, General End User: Hospitals, Clinics, Laboratories, Research Institutions Technology: Incineration, Autoclaving, Chemical Treatment, Landfilling |
| Companies Covered | Veolia Environmental Services, SUEZ Group, Remondis Medison, WM Intellectual Property Holdings, Bertin Technologies, Stericycle, Clean Harbors, Daniels Health, Biffa Waste Services, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bio-Medical Waste Management Market Trends and Innovations
Technology substitution and regulatory tightening are compressing competitive margins while opening specialized service niches across European bio-medical waste handling. Three developments dominate strategic planning.
Autoclaving systems for standard infectious waste streams are bifurcating the treatment technology landscape. German hospital groups now specify steam sterilization for 70% of regulated waste categories, compressing demand for high-temperature incineration to anatomical and cytotoxic residues exclusively. This split enables mid-cap operators to capture volume leadership in infectious streams without competing for capital-intensive incineration permits.
REACH chemical handling protocols now mandate substance-by-substance tracking for pharmaceutical residues entering waste streams. The industrial consequence is a documentation burden that favors integrated operators with in-house laboratory analysis capabilities over fragmented collection-only providers. French clinical networks are responding fastest, embedding chemists within waste management teams to pre-classify cytotoxic loads before transport.
Service unbundling is fragmenting long-term hospital contracts into modular components. German procurement teams now separately tender collection logistics, sterilization treatment, and final disposition, enabling price benchmarking across specialized providers. This pattern is most visible in North Rhine-Westphalia, where university hospitals pilot multi-vendor frameworks that displace single-source incineration agreements.
Europe Bio-Medical Waste Management Market Segmentation
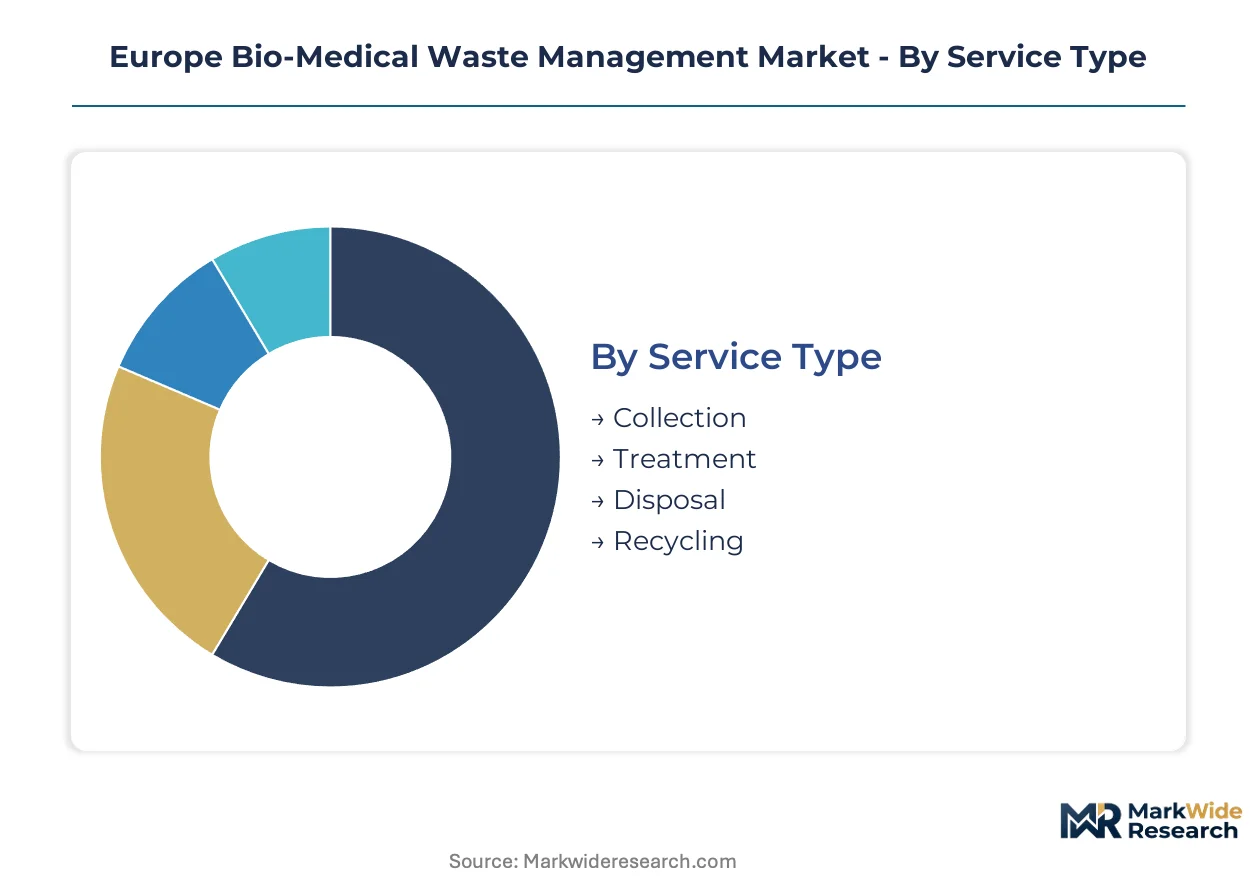
Segmentation in European bio-medical waste management reveals how regulatory pressure and technology substitution reshape contract structures across service tiers. Procurement teams now unbundle long-term agreements into specialized modules, creating distinct competitive arenas for collection logistics, sterilization treatment, and final disposition.
Service Type:
Substitution pressure concentrates in treatment and disposal segments as autoclaving displaces incineration and recycling protocols displace single-use packaging.
- Collection:Specialized logistics networks transport sealed waste containers from clinical facilities to treatment sites under EU Waste Framework Directive chain-of-custody requirements. Demand clusters in Germany's Rhine-Ruhr corridor where dense hospital networks justify dedicated fleet investments.
- Treatment:Steam sterilization at 121–134°C and 15–30 psi pressure neutralizes pathogenic load before landfill or alternative processing. REACH-aligned chemical handling standards now mandate substance-by-substance tracking, rotating contract awards toward operators with in-house laboratory analysis capabilities.
- Disposal:Final disposition covers landfill placement, energy recovery, or specialized hazardous waste repositories. French clinical networks embed chemists within waste management teams to pre-classify cytotoxic loads before transport.
- Recycling:Reverse-logistics packaging recovery systems reclaim reusable containers from laboratory waste streams. Extended producer responsibility schemes in Germany and France create incentive structures for integrated collection-to-recycling service models.
Treatment anchors the volume base while recycling gains share at the steepest rate as EPR frameworks expand.
Waste Type:
Cost tier differentiation separates high-compliance infectious and hazardous categories from lower-margin general waste handling.
- Infectious:Pathogenic materials from patient care, diagnostic procedures, and laboratory cultures require steam sterilization or high-temperature incineration. German hospital groups now specify autoclaving for 70% of regulated waste categories in this segment.
- Hazardous:Chemical, pharmaceutical, and cytotoxic residues face ECHA substance restrictions and EMA pharmaceutical residue guidelines. Documentation burdens favor integrated operators over fragmented collection-only providers.
- Non-Hazardous:Segregated clinical waste streams exclude sharps, body parts, and chemical contaminants. Italian municipal contracting fragments across this category, enabling margin capture through unified service platforms.
- General:Standard municipal waste from administrative and non-clinical hospital functions. Lowest-margin segment with minimal regulatory differentiation between healthcare and commercial waste handling.
Infectious waste commands the deepest service contracts while hazardous categories expand most quickly under tightening substance tracking mandates.
End User:
Application concentration varies sharply between centralized hospital networks and dispersed laboratory operations.
- Hospitals:Large acute-care facilities generate the highest volume of anatomical and cytotoxic residues requiring incineration. North Rhine-Westphalia university hospitals pilot multi-vendor frameworks that displace single-source agreements.
- Clinics:Outpatient and specialized care facilities produce lower volumes but require flexible collection scheduling. Spanish municipal contracting patterns favor regional operators with adaptable logistics.
- Laboratories:Decentralized diagnostic testing generates infectious waste streams requiring specialized collection logistics. Fastest-expanding addressable base as point-of-care testing proliferates across European healthcare systems.
- Research Institutions:Academic and pharmaceutical R&D facilities produce novel chemical and biological residues with uncertain classification protocols. MDR medical device disposal traceability requirements strain legacy data infrastructure.
Hospitals anchor contract value while laboratories climb the fastest on diagnostic decentralization.
Technology:
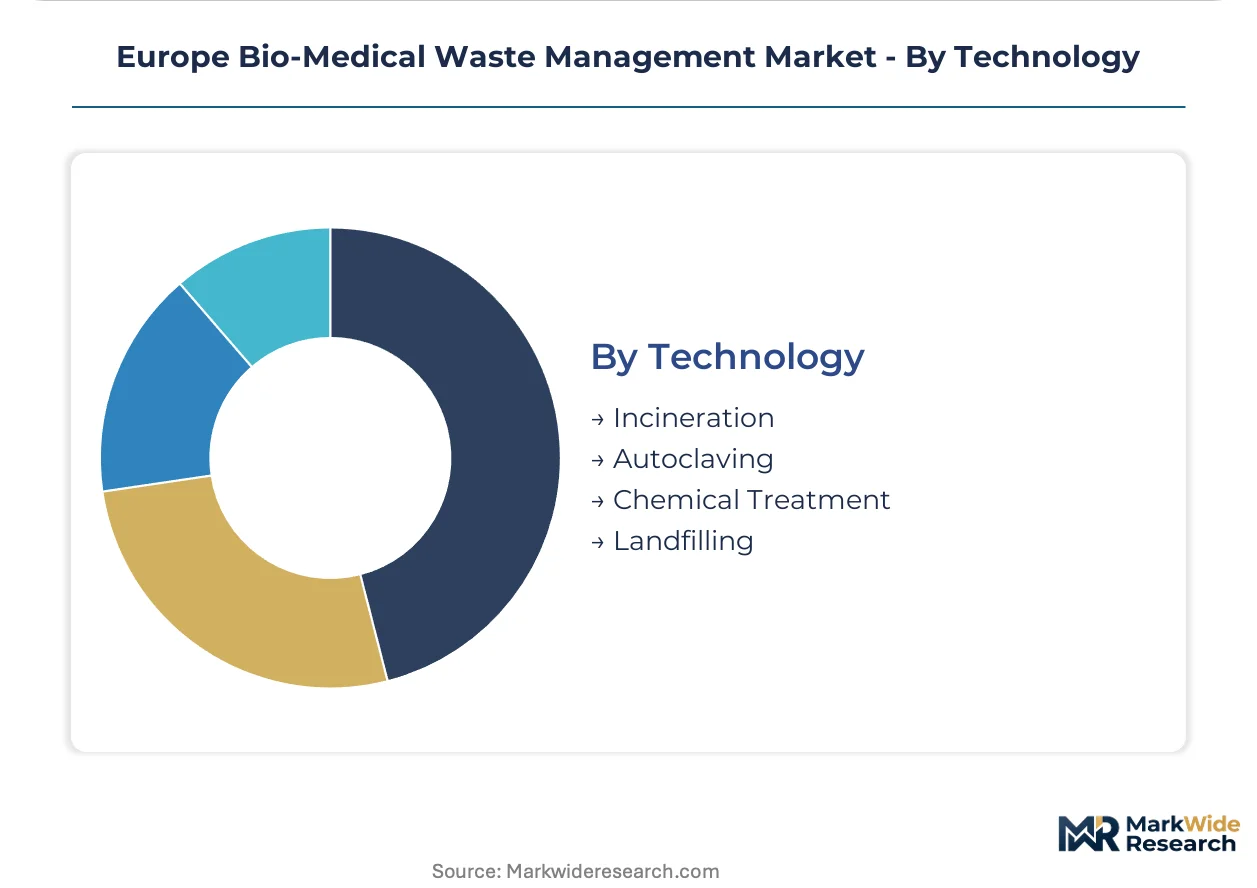
Supply concentration in incineration permits creates barriers as autoclaving and chemical treatment lower capital thresholds.
- Incineration:High-temperature combustion at 850–1,100°C handles anatomical waste and cytotoxic residues excluded from steam sterilization. Capital intensity of retrofitting limits market entry for mid-scale operators in saturated French markets.
- Autoclaving:Steam sterilization systems capture fastest expansion in standard infectious streams due to lower capital requirements and reduced emissions profiles. German procurement specifications now mandate autoclave-grade certification for major contract awards.
- Chemical Treatment:Disinfection through chlorine compounds, ozone, or alkaline hydrolysis addresses pharmaceutical residues and liquid waste streams. Hybrid systems combining autoclaving with chemical pre-treatment open cytotoxic categories previously reserved for incineration.
- Landfilling:Sanitary landfill placement follows sterilization certification for treated infectious waste. Final disposition tier with minimal technology differentiation and compressed margins.
Incineration retains premium positioning for regulated categories while autoclaving scales most aggressively on capital efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized autoclave sterilization services to French and Italian hospital networks under cross-border EU Waste Framework Directive compliance frameworks, establishing the Rhine-Ruhr corridor as the continent's primary treatment capacity hub.
Germany
North Rhine-Westphalia university hospitals pilot multi-vendor procurement frameworks that unbundle collection, sterilization, and disposal into separate contracts. The country's federal environmental agency enforces REACH-aligned chemical treatment standards that mandate 121–134°C autoclave certification. Dense clinical networks across the Rhine-Ruhr corridor justify dedicated fleet investments by specialized logistics operators.
France
Paris-based hospital groups embed chemists within waste management teams to pre-classify cytotoxic loads before transport under ANSM pharmaceutical residue guidelines. The country's national environmental regulator enforces substance-by-substance tracking for pharmaceutical residues entering waste streams. Île-de-France clinical networks represent the fastest adopters of integrated collection-to-disposal service models.
Italy
Lombardy and Emilia-Romagna municipalities fragment contracting across non-hazardous clinical waste categories, enabling margin capture through unified regional platforms. The national environmental ministry implements EU Waste Framework Directive chain-of-custody requirements that strain legacy documentation infrastructure. Milan's dense hospital network drives demand for flexible outpatient collection scheduling.
Spain
Madrid and Barcelona metropolitan areas favor regional operators with adaptable logistics for clinic-generated waste streams under decentralized healthcare administration. The country's national pharmaceutical regulator aligns with EMA pharmaceutical residue guidelines for cytotoxic handling protocols. Catalan diagnostic laboratory expansion generates infectious waste requiring specialized reverse-logistics container recovery.
Netherlands
Randstad hospital networks concentrate demand for reusable container systems in laboratory waste segments under national extended producer responsibility pilots. The country's environmental assessment agency enforces REACH chemical handling protocols for pharmaceutical residues. Amsterdam's research institutions produce novel biological residues with uncertain classification protocols that strain treatment capacity.
Europe Bio-Medical Waste Management Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity thresholds, with publicly traded environmental conglomerates controlling high-temperature incineration permits while private mid-scale operators capture autoclaving volume. The market structure fragments into three strategic archetypes: integrated collection-to-disposal platforms, specialized sterilization technology providers, and reverse-logistics packaging recovery operators. Dominant competitive moves include geographic expansion through municipal contract aggregation and technology licensing for hybrid sterilization systems.
Within the integrated platform tier, Veolia Environmental Services and SUEZ Group exemplify scale-driven operators that anchor market presence through unified service portfolios spanning transport, treatment, and final disposition. Remondis Medison occupies a specialized position in reusable container systems for laboratory waste streams, representing the reverse-logistics archetype that captures margin in fragmented municipal contracting environments. These three operators collectively illustrate how competitive positioning stratifies across capital requirements and regulatory compliance depth.
| Leading Market Players |
|---|
| Veolia Environmental Services |
| SUEZ Group |
| Remondis Medison |
| WM Intellectual Property Holdings |
| Bertin Technologies |
| Stericycle |
| Clean Harbors |
| Daniels Health |
| Biffa Waste Services |
| Others |
Pricing and Supply Chain Analysis
Long-term sterilization service contracts with embedded capacity reservations lock in both treatment access and price visibility for German hospital networks facing EU Waste Framework Directive compliance deadlines. These agreements bundle collection logistics, autoclave certification, and final disposition into fixed-rate structures that insulate buyers from spot-market volatility in high-temperature incineration capacity.
Pricing Analysis
Autoclave-generation pricing gaps separate legacy incineration premiums from next-generation hybrid sterilization systems. Three-tier pricing structure across certified sterilization, standard infectious treatment, and economy landfill diversion dominates contract structures. Price differentiation rests on REACH-aligned chemical handling certification and volume scale, with university hospital groups commanding deepest discounts through multi-site aggregation. Cost compression in economy-tier landfill placement is intensifying because EPR schemes for healthcare plastics redirect volumes toward recycling recovery. Laboratories represent the most price-sensitive segment due to decentralized waste generation and limited contract scale.
Supply Chain Analysis
Strategic stockpile preferences concentrate reusable container inventories at Netherlands Randstad consolidation hubs rather than just-in-time deployment. Geographic supply concentration centers on Germany, France, and Italy for sterilization equipment manufacturing and chemical pre-treatment agents. Raw material dependencies draw from specialized alloy suppliers for autoclave pressure vessels, chlorine compound producers for chemical disinfection, and reverse-logistics packaging fabricators. Single-source vulnerability in high-temperature incineration permitting creates bottlenecks for anatomical waste categories. Distribution runs through dedicated fleet operators under EU Waste Framework Directive chain-of-custody mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs defensive moats around established operators, as EU Waste Framework Directive compliance documentation and REACH-aligned certification create switching costs that lock hospital procurement teams into incumbent relationships.
For Market Incumbents: Consolidate municipal contract aggregation across Italy and Spain where fragmented non-hazardous waste handling invites unified platform capture. Deepen backward integration into reusable container manufacturing to defend margin position against reverse-logistics specialists. Autoclave technology substitution threatens incineration-premium revenue streams.
For New Entrants and Emerging Players: Anchor in Spanish diagnostic laboratory networks where decentralized point-of-care testing expansion outpaces specialized collection infrastructure. Target Lombardy and Emilia-Romagna municipal contracting gaps with flexible outpatient scheduling capabilities. Pursue chemist-embedded pre-classification services as differentiated entry angle against integrated incumbents.
For Investors and Strategic Acquirers: Mid-scale autoclave operators with REACH certification depth present asymmetric upside under hybrid sterilization technology convergence. Long-term viability frames around EPR scheme expansion timelines and F-Gas Regulation scope revisions. Watch ANSM pharmaceutical residue guideline enforcement intensity as inflection signal for cytotoxic handling premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Certification Investment | REACH-aligned chemical handling standards mandate 121–134°C sterilization protocols for contract eligibility. |
| Chemist-Embedded Pre-Classification | ANSM pharmaceutical residue guidelines require substance-by-substance tracking before transport authorization. |
| Reverse-Logistics Container Recovery | Extended producer responsibility pilots in Netherlands Randstad create reusable packaging incentive structures. |
| Multi-Vendor Procurement Unbundling | North Rhine-Westphalia university hospitals pilot separate tendering for collection, sterilization, and disposal. |
| Hybrid Sterilization System Licensing | Convergence of autoclaving with chemical pre-treatment opens cytotoxic categories from incineration exclusivity. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and waste treatment facility operators provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Waste Framework Directive implementation reports, ECHA substance restriction databases, EMA pharmaceutical residue guidelines, and hospital procurement database aggregations. Bottom-up treatment capacity modeling and top-down regulatory compliance cost analysis were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include service type unbundling, waste category compliance tier, end-user concentration pattern, and technology generation substitution rate. CAGRs were derived from treatment capacity expansion trajectories and regulatory enforcement intensity curves. Forecast inputs incorporated autoclave adoption velocity and EPR scheme rollout timelines.
Material uncertainties — pending F-Gas Regulation scope expansions and national EPR scheme design variations — sit outside the modeled envelope. Forecasts reflect assumptions about REACH enforcement continuity and MDR traceability system adoption rates. Revision becomes warranted when hybrid sterilization technology cost curves cross incineration retrofit economics thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Middle-East and Africa Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market