
 Visceral Pain Market | 2026-2036
Visceral Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Visceral Pain Market Intelligence
The capital-intensity divergence in clinical trial execution and marketing is bifurcating the competitive landscape. Large-scale players like Pfizer Inc. leverage extensive R&D pipelines and global commercial reach to dominate established therapy areas. In contrast, specialists such as Grunenthal GmbH compete by focusing on novel pain mechanisms and specific patient populations. AbbVie Inc. sustains its market position through a strong portfolio addressing pain associated with immunological conditions.
Visceral pain refers to pain that originates from internal organs within the thoracic, abdominal, or pelvic cavities. It is typically characterized by a diffuse, poorly localized, and deep sensation, often accompanied by autonomic motor and sensory responses. The primary function of this pain is to signal organ dysfunction, inflammation, or injury to the central nervous system. Analgesics and opioids constitute the largest product type segments, though scrutiny of the latter is increasing. Within therapy areas, treatments for gastrointestinal disorders command a significant share of research and development efforts.
Regulatory oversight from bodies like the U.S. FDA and the European Medicines Agency (EMA) imposes strict efficacy and safety requirements for new drug approvals. Japan's PMDA also mandates rigorous clinical data for market authorization, particularly for novel analgesics and opioid formulations. Stakeholder success depends on navigating the complex guidelines for opioid prescription and the distinct development pathways for alternative pain management therapies.
Market Dynamics
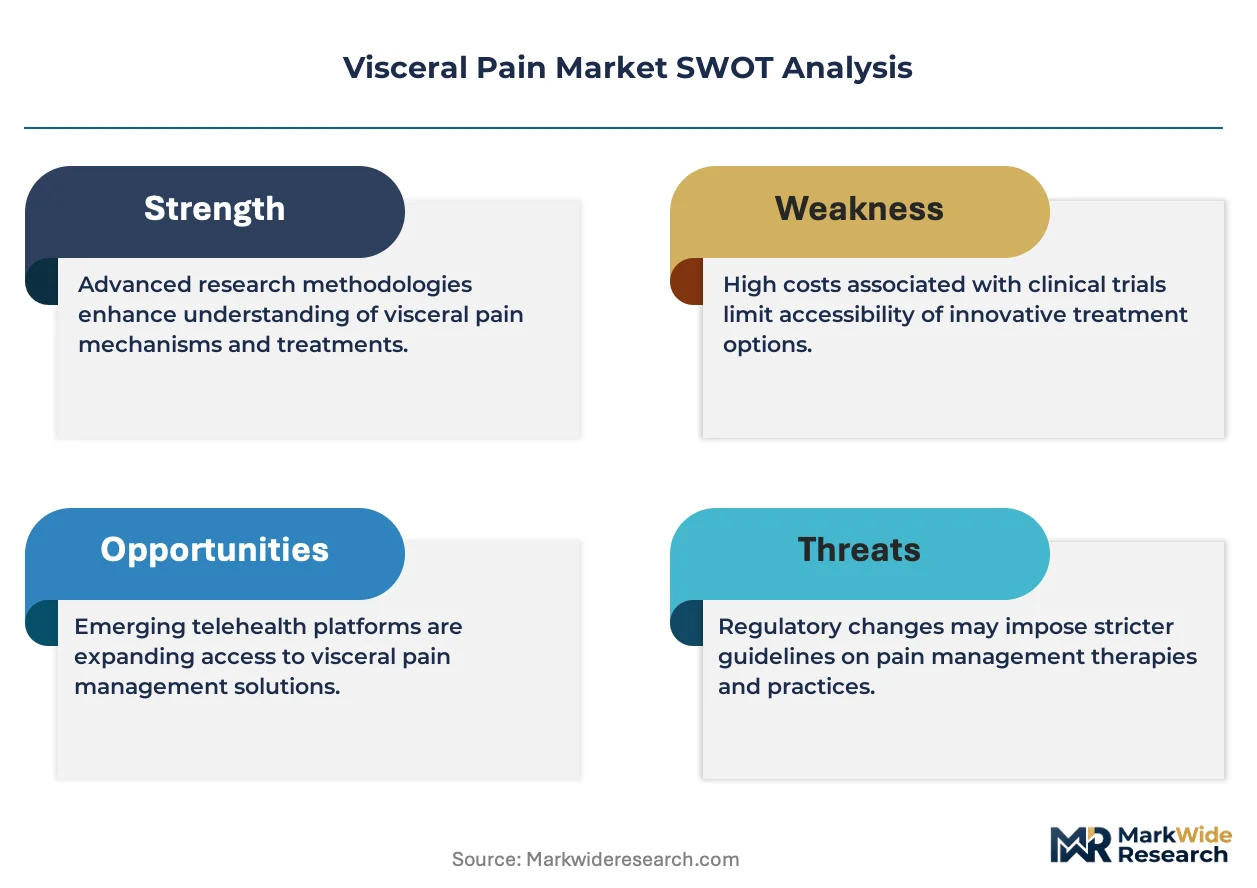
The primary structural force shaping the visceral pain market is the regulatory and clinical pivot away from traditional opioids. This shift is driven by a deeper understanding of pain mechanisms, creating demand for targeted, non-addictive therapeutic alternatives.
Growth Catalysts
- Non-Opioid Development Incentives:Regulatory frameworks from the U.S. FDA that fast-track non-addictive analgesics are accelerating the development of novel therapies, reducing time-to-market for qualifying drug candidates.
- Expanding Geriatric Population:An increasing prevalence of chronic gastrointestinal and pelvic disorders in aging populations, particularly in Japan and Germany, is expanding the addressable patient base for long-term pain management solutions.
- Biomarker Discovery:Technological progress in proteomics and genomics is enabling the identification of specific biomarkers for visceral hypersensitivity, facilitating the creation of highly targeted and personalized pain treatments.
Market Restraints
- High Placebo Response:The inherent subjectivity of pain measurement and high placebo response rates in clinical trials for conditions like IBS create significant hurdles for demonstrating statistically significant drug efficacy.
- Opioid Prescription Scrutiny:Strict government controls on opioid distribution, including monitoring programs in the United States and parts of Europe, create access challenges for patients with legitimate needs for potent analgesics.
- Complex Pain Pathophysiology:The poor understanding of the exact mechanisms underlying many visceral pain conditions hinders the identification of reliable drug targets, leading to high failure rates in preclinical and clinical development.
Strategic Opportunities
- Digital Therapeutics Integration:Combining pharmacological agents with digital therapeutics (DTx) for behavioral modification and symptom tracking offers a novel approach to managing chronic visceral pain, creating a new service-based revenue stream.
- Orphan Disease Indications:Focusing development on rare diseases characterized by visceral pain, such as interstitial cystitis, allows access to regulatory incentives like the FDA's orphan drug designation, which grants market exclusivity.
- Emerging Asian Markets:Expanding commercial operations into markets like South Korea and Brazil, where healthcare infrastructure is improving and awareness of chronic pain is rising, opens new growth avenues beyond saturated markets.
Industry Challenges
- Complex Reimbursement Pathways:Securing favorable reimbursement from payers for novel, high-cost non-opioid therapies is a major hurdle, requiring extensive health-economic outcome data to justify value propositions.
- Clinical Trial Recruitment:Identifying and recruiting sufficient patient populations with well-defined visceral pain conditions for clinical trials is a persistent operational challenge, often leading to extended development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Visceral Pain Market |
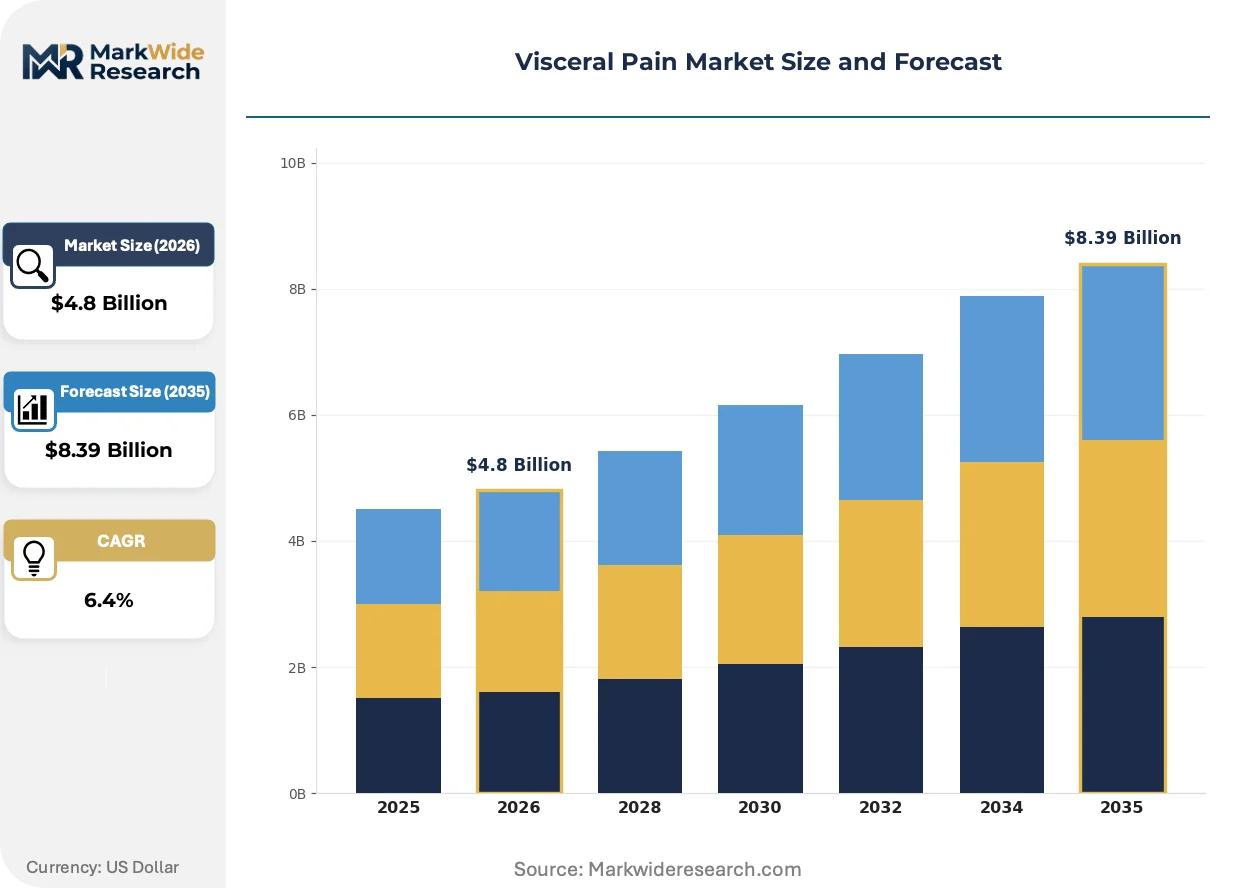
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antispasmodics, Opioids, Antidepressants, Anesthetics Therapy Area: Gastrointestinal Disorders, Urological Conditions, Gynecological Disorders, Cardiovascular Conditions, Musculoskeletal Disorders End User: Hospitals, Ambulatory Surgical Centers, Pain Clinics, Research Institutes, Primary Care Facilities Delivery Mode: Oral, Injectable, Transdermal, Rectal, Intravenous |
| Companies Covered | Pfizer Inc, AstraZeneca, AbbVie Inc, Novartis AG, Bristol-Myers Squibb Company, Johnson & Johnson Services Inc, Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd, Grunenthal GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Visceral Pain Market Strategic Shifts & Innovations
A fundamental shift towards precision medicine is defining the development of new visceral pain therapies. This evolution is driven by advanced diagnostics that can stratify patient populations, moving the market away from one-size-fits-all analgesics towards targeted treatments.
Monoclonal antibodies represent a significant product evolution, designed to selectively block specific pain signaling molecules like Nerve Growth Factor. Biopharmaceutical firms are advancing these therapies for patient populations with refractory chronic pain. The introduction of these highly specific biologics is bifurcating the treatment landscape between generalized analgesics and precision-targeted, high-cost therapies.
Regulatory actions from the U.S. FDA and the European Medicines Agency are establishing clearer development pathways for non-opioid pain therapeutics. These policies provide incentives, including potential fast-track status, for drugs that demonstrate a lower risk of addiction and abuse. As a result, the pipeline for analgesics is heavily skewed towards novel mechanisms of action, as developers seek to meet the high safety and efficacy bars for approval.
Patient-centric care models are altering treatment paradigms from simple symptom suppression to addressing the underlying pathophysiology of pain. This shift is challenging the dominance of general analgesics, with educated patients and clinicians seeking therapies that offer disease modification. This demand-side change is particularly evident in the United States and Germany for chronic conditions like inflammatory bowel disease.
Visceral Pain Market Segmentation
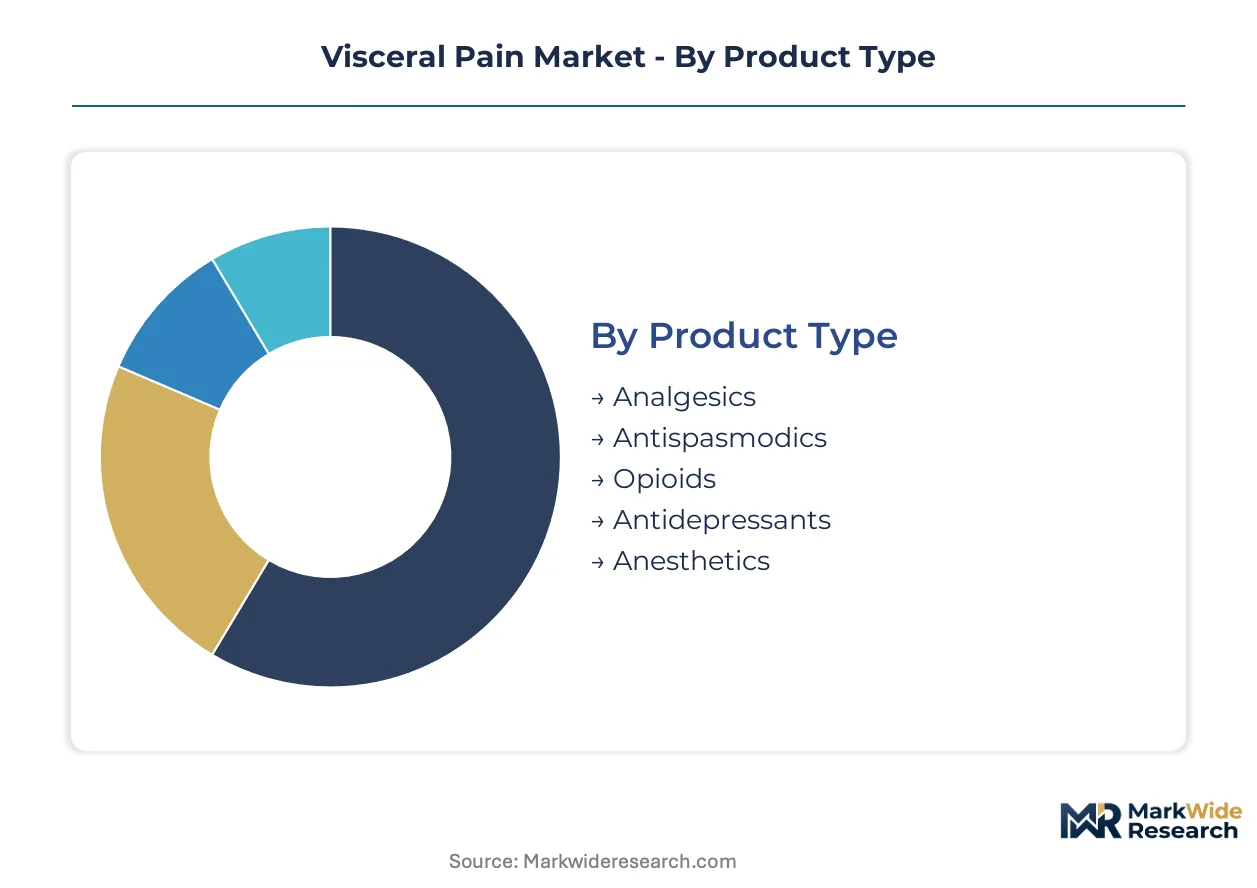
Market segmentation provides a granular understanding of the Visceral Pain market's intricate structure, highlighting areas of concentrated demand and emerging therapeutic needs. Analyzing these segments is crucial for stakeholders seeking to optimize product development and commercial strategies within this complex pain management landscape.
Product Type:
Segments within product type face varying substitution pressures, particularly as non-opioid alternatives gain traction and regulatory scrutiny on traditional options intensifies.
- Analgesics:Analgesics encompass a broad range of pain-relieving medications, including NSAIDs and acetaminophen, that target various pain pathways. Demand for these agents remains high in primary care settings across the United States due to their accessibility and established efficacy for mild to moderate visceral pain.
- Opioids:Opioids are potent pain relievers derived from opium or synthetic analogues, acting on opioid receptors in the brain and spinal cord. Despite their efficacy, their market position is challenged by stringent regulatory controls in Europe aimed at curbing addiction and misuse.
- Antispasmodics:Antispasmodics relieve muscle spasms, particularly in the gastrointestinal tract, offering symptomatic relief for conditions like Irritable Bowel Syndrome.
- Antidepressants:Certain antidepressants are utilized for their neuromodulatory effects on pain pathways, particularly in chronic visceral pain conditions.
- Anesthetics:Anesthetics are employed for localized pain relief or during interventional procedures to block nerve signals temporarily.
Opioids maintain a significant volume base, while non-opioid therapies, including certain antidepressants, are gaining share at the steepest rate.
Therapy Area:
Application-specific demand shapes the therapy area segmentation, with research and development efforts concentrating on high-prevalence conditions and underserved patient populations.
- Gastrointestinal Disorders:Gastrointestinal disorders include conditions such as Irritable Bowel Syndrome (IBS) and Inflammatory Bowel Disease (IBD), frequently manifesting as chronic abdominal pain. Research and development investment is substantial in this area, particularly in Germany, driven by the need for targeted, long-term management solutions.
- Urological Conditions:Urological conditions like interstitial cystitis and chronic prostatitis involve pelvic pain and dysfunction, often requiring specialized therapeutic approaches. The expanding geriatric population in Japan contributes to a growing addressable patient base for these conditions.
- Gynecological Disorders:Gynecological disorders, such as endometriosis and chronic pelvic pain, present significant visceral pain challenges for women.
- Cardiovascular Conditions:Visceral pain associated with cardiovascular conditions, such as angina, requires specific diagnostic and treatment protocols.
- Musculoskeletal Disorders:While primarily somatic, some musculoskeletal conditions can refer pain to visceral regions, necessitating careful differential diagnosis.
Gastrointestinal Disorders command the largest patient pool, and Urological Conditions are experiencing the most rapid growth in treatment innovation.
End User:
Customer type dictates the care model, with specialized facilities offering advanced interventions for complex visceral pain management and broader settings providing foundational care.
- Hospitals:Hospitals serve as primary points of contact for acute and severe visceral pain, offering comprehensive diagnostic and treatment capabilities. High patient throughput in hospitals across the United States ensures a substantial volume of analgesic prescriptions and procedures.
- Pain Clinics:Pain Clinics specialize in the multidisciplinary management of chronic pain conditions, providing targeted therapies and interventional procedures. The growing focus on non-opioid and personalized treatments drives patient referrals to these specialized centers in European nations.
- Ambulatory Surgical Centers:Ambulatory Surgical Centers perform minimally invasive procedures for pain relief, offering a cost-effective alternative to hospital-based care.
- Research Institutes:Research Institutes are critical for advancing the understanding of visceral pain pathophysiology and developing novel therapeutic targets.
- Primary Care Facilities:Primary Care Facilities manage initial diagnoses and provide first-line treatment for less severe or newly presenting visceral pain cases.
Hospitals manage the highest volume of initial presentations, while Pain Clinics show the fastest uptake in specialized chronic care management.
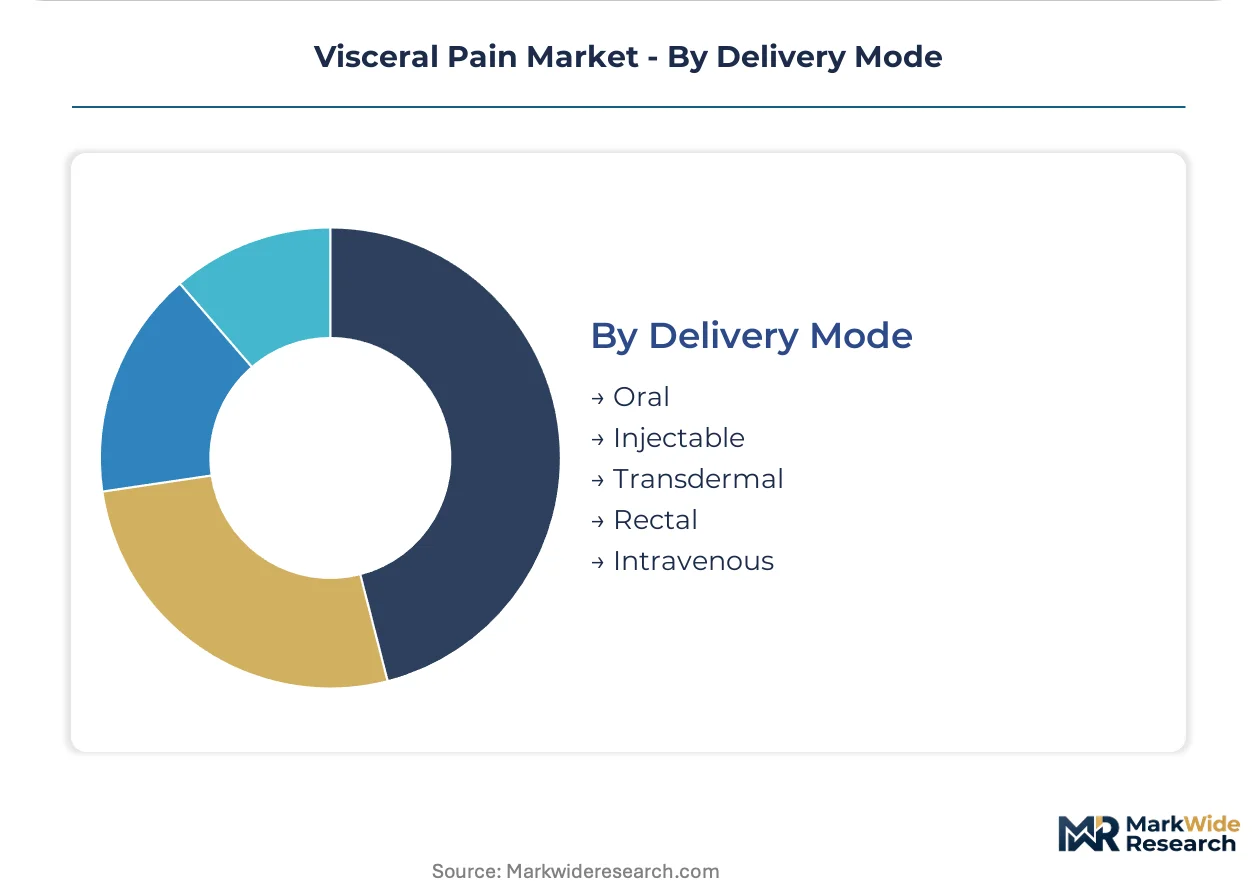
Delivery Mode:
Maturity levels differentiate delivery modes, with established administration routes providing foundational access while novel methods emerge to enhance patient convenience and efficacy.
- Oral:Oral formulations represent the most common and convenient method for visceral pain medication delivery, suitable for chronic management. Their widespread use in primary care settings across most developed markets ensures high patient compliance and accessibility.
- Injectable:Injectable delivery modes, including subcutaneous, intramuscular, and intravenous routes, offer rapid onset of action and precise dosing for acute or severe pain. These methods are frequently employed in hospital emergency departments and specialized pain interventions.
- Transdermal:Transdermal patches provide continuous drug delivery through the skin, offering sustained pain relief and bypassing first-pass metabolism.
- Rectal:Rectal administration is used when oral intake is difficult or for local effects, particularly in lower gastrointestinal or pelvic pain.
- Intravenous:Intravenous delivery ensures immediate systemic availability of medication, critical for severe acute pain management in hospital settings.
Oral delivery constitutes the broadest access point, and Transdermal applications are seeing accelerating adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The visceral pain market exhibits a complex global trade dynamic, where regions with advanced pharmaceutical R&D often serve as net exporters of novel therapies, while others prioritize importing established treatments. This creates a reliance on a balanced approach to internal market development and external sourcing for specialized pain management solutions.
United States
Demand in the United States remains concentrated due to high healthcare expenditure and the significant prevalence of gastrointestinal disorders. The U.S. FDA actively fast-tracks non-addictive analgesics, reducing time-to-market for qualifying drug candidates. Major biotech hubs in Boston and San Francisco continue to drive the development of novel, targeted pain therapies.
Germany
Germany's expanding geriatric population contributes to a substantial addressable patient base for long-term pain management, particularly in gastrointestinal disorders. The European Medicines Agency (EMA) imposes strict efficacy and safety requirements for new drug approvals. Pharmaceutical clusters in Bavaria and North Rhine-Westphalia focus on research and development for targeted pain solutions.
Japan
An increasing prevalence of chronic gastrointestinal and pelvic disorders in Japan's aging population expands the patient base for visceral pain treatments. Japan's PMDA mandates rigorous clinical data for market authorization, especially for novel analgesics. Research centers in Tokyo and Osaka are at the forefront of innovating pain management strategies.
South Korea
South Korea's improving healthcare infrastructure and rising awareness of chronic pain conditions are opening new growth avenues. The Ministry of Food and Drug Safety (MFDS) often streamlines drug approval processes for essential medicines. Biotech parks in Seoul and Gyeonggi-do attract significant investment in advanced pain therapy development.
United Kingdom
The United Kingdom demonstrates a growing focus on chronic pain management through specialized pain clinics. Regulatory bodies like NICE guidelines influence the adoption of non-opioid and personalized treatment approaches. Biomedical campuses in London and Cambridge continue to advance fundamental research into pain mechanisms.
Visceral Pain Market Key Industry Players
Concentration sits with large pharmaceutical companies that command significant market share through diversified portfolios and global commercial networks. The competitive landscape bifurcates between these established players and specialized firms focusing on niche indications or novel pain mechanisms. Strategic partnerships and extensive R&D investment are dominant competitive moves.
Within the established therapy areas, large pharmaceutical entities like Pfizer Inc. and AbbVie Inc. exemplify extensive research and development capabilities, driving innovation in broad pain management. These global players often anchor positions through diversified portfolios and significant commercial reach. In contrast, Grunenthal GmbH represents a specialist archetype, focusing on novel pain mechanisms and specific patient populations to carve out distinct market niches.
| Leading Market Players |
|---|
| Pfizer Inc |
| AstraZeneca |
| AbbVie Inc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Johnson & Johnson Services Inc |
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd |
| Grunenthal GmbH |
| Others |
Cost & Logistics Intelligence
Non-opioid analgesic development, driven by regulatory incentives, is reshaping the supply geography away from traditional opioid sources and introducing new pricing economics for targeted therapies.
Pricing Analysis
The customization-premium spread in visceral pain therapeutics reflects the bifurcation between generalized analgesics and precision-targeted biologics. Value-based pricing models often apply to novel biologics, while established analgesics maintain transactional pricing. Price differentiation drivers include clinical efficacy for specific biomarkers and regulatory fast-track status. Pricing pressure stems from payer scrutiny on high-cost non-opioids, driven by health-economic outcome requirements. Hospitals and pain clinics are less price-sensitive for novel therapies demonstrating superior outcomes, while primary care settings remain highly price-sensitive for basic analgesics.
Supply Chain Analysis
Inbound logistics costs for specialized raw materials and active pharmaceutical ingredients (APIs) for visceral pain treatments are influenced by global shipping lane disruptions. Geographic supply concentrates in India and China for generic APIs, while the United States and Germany lead advanced biologics manufacturing. Raw material dependencies include complex chemical intermediates and cell culture media for biologics production. Single-source vulnerability for proprietary excipients poses a significant supply chain risk. Distribution runs through specialized pharmaceutical wholesalers and hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The visceral pain market faces a platform-economics inflection, driven by the integration of digital therapeutics into pharmacological treatment ecosystems for chronic pain management.
For Market Incumbents: Fortify existing market share by expanding non-opioid analgesic pipelines through strategic acquisitions of specialist biotechs. Invest heavily in biomarker-driven research and development to address the regulatory scrutiny on opioids and rising competition from targeted therapies. Focus R&D investment on precision medicine to differentiate offerings. Secure long-term supply agreements for critical raw materials to mitigate supply chain risks.
For New Entrants and Emerging Players: Service-layer gaps exist in personalized behavioral modification programs integrated with pharmacological agents for visceral pain. Target digital therapeutics for Irritable Bowel Syndrome management and orphan drug development for rare visceral pain conditions. The most penetrable segment is chronic gastrointestinal pain in Western Europe, leveraging regulatory incentives. Implement a direct-to-patient digital health platform with physician referral partnerships for market entry.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized pain management clinics and early-stage biotech firms developing novel non-opioid mechanisms. The market demonstrates long-term viability over the next decade, driven by an aging population and unmet needs in chronic pain. Identify acquisition targets with validated biomarker discovery platforms or advanced clinical-stage non-opioid candidates. Successful Phase 3 clinical trial readouts for non-opioid therapies in high-prevalence visceral pain indications represent a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates approval for non-opioid therapies addressing unmet patient needs. |
| Regulatory Approval Pathway | Leverages fast-track designations to reduce time-to-market for innovative drugs. |
| Licensing Agreement | Accesses novel pain mechanisms and expands product portfolios efficiently. |
| Manufacturing Scale-Up | Ensures commercial readiness for high-demand biologic and advanced therapies. |
| Digital Therapeutics Integration | Enhances patient outcomes and creates new revenue streams through combined solutions. |
Research Approach
Desk research of clinical trial registries, regulatory filings, and academic literature preceded structured interviews with pain specialists, pharmaceutical R&D executives, and hospital formulary managers. This approach combined primary insights from industry stakeholders with secondary validation from public and proprietary data sources. Patient advocacy group leaders also contributed perspectives, ensuring a comprehensive bottom-up and top-down triangulation of market dynamics.
Variance decomposition models elucidated the relative contributions of demographic shifts, technological advancements, and regulatory changes to market growth. Segmentation dimensions modeled included product type, therapy area, end user, delivery mode, and regional patient population prevalence across the analysis window. Compound annual growth rates were derived from historical growth trends and projected future market dynamics. Non-opioid drug pipeline progression and geriatric population expansion served as key industry-specific forecast inputs.
Material uncertainties — including unforeseen clinical trial failures or dramatic shifts in global healthcare policies — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive data analysis and expert consensus. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chronic Pain Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Migraine Management Market
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Cancer Pain Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Cold Pain Therapy Market
Pain Management
Ketorolac Market
Pain Management
Chronic Lower Back Pain Treatment Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Neuralgia Treatment Market