
 Generalized Myasthenia Gravis (GMG) Management Market | 2026-2036
Generalized Myasthenia Gravis (GMG) Management Market Size, Share, and Industry Trends Forecast 2026-2036
Generalized Myasthenia Gravis (GMG) Management Market Foresight
North American biologics manufacturing is expanding to meet rising demand for FcRn inhibitors and complement-targeted therapies. Horizon Therapeutics leverages its neurology franchise to sustain leadership in the autoimmune rare disease space. Alexion Pharmaceuticals anchors its position through deep expertise in complement pathway modulation. Argenx competes aggressively with its differentiated FcRn blocker, drawing prescriber attention from traditional immunosuppressant protocols.
Generalized Myasthenia Gravis management encompasses the clinical and therapeutic interventions directed at controlling autoimmune-mediated destruction of acetylcholine receptors at the neuromuscular junction, typically involving immunomodulation, symptomatic relief, and crisis prevention strategies. Treatment protocols combine acetylcholinesterase inhibitors for rapid symptomatic control with longer-acting immunosuppressants or biologic agents to reduce pathogenic autoantibody production. Biologic agents represent the fastest-expanding product category, driven by superior efficacy in refractory patients and premium positioning within specialty pharmacy channels. Oral medications retain the largest volume share due to established prescribing patterns and favorable access through retail pharmacy networks, though margin pools increasingly concentrate in intravenous infusion and subcutaneous injection delivery modes.
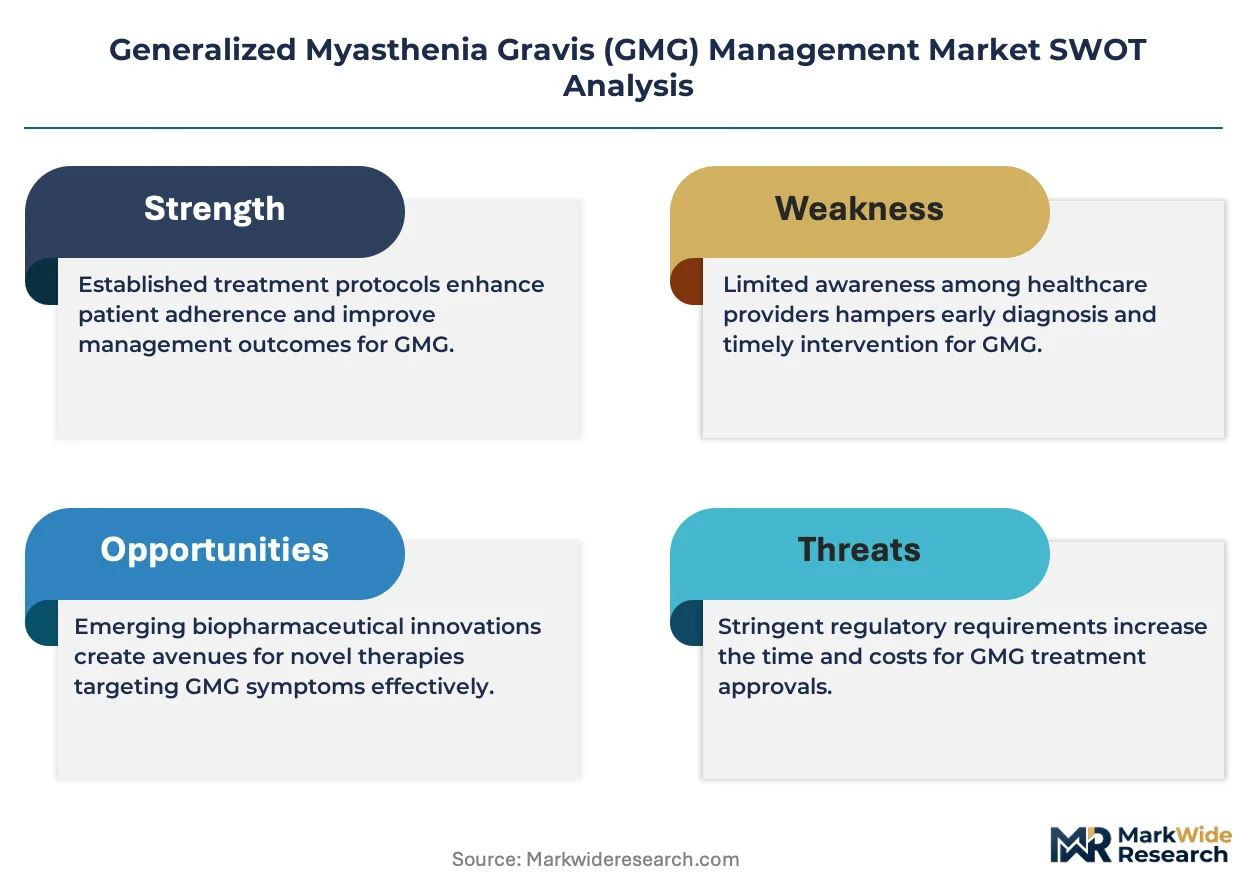
FDA orphan drug designations and EMA PRIME eligibility criteria shape development priorities and commercial timelines for emerging therapies, while HIPAA and GDPR frameworks govern real-world evidence collection that supports label expansion. The EU AI Act introduces compliance complexity for algorithmic diagnostic tools used in treatment response monitoring, particularly across multinational clinical trial programs. Stakeholders must weigh pipeline concentration in FcRn and complement pathways against the risk of mechanism class commoditization as multiple entrants advance toward regulatory submission.
Market Dynamics
FcRn inhibitor biologics are compressing treatment protocols previously dominated by chronic corticosteroid regimens, forcing incumbent immunosuppressant manufacturers to defend formulary position through value-based contracting.
Growth Catalysts
- FDA Accelerated Approval Pathway:The orphan drug designation streamlines Phase II-to-approval transitions for complement-targeted therapies, compressing development timelines by 18-24 months versus standard neurology indications.
- Specialty Infusion Center Expansion:United States academic medical centers are building dedicated neuroimmunology infusion suites, creating infrastructure pull for intravenous biologic administration.
- Real-World Evidence Frameworks:HIPAA-compliant patient registries enable post-market efficacy tracking that supports label expansion into pediatric and seronegative subpopulations.
Market Restraints
- Plasma-Derived Input Volatility:Complement inhibitor manufacturing depends on fractionated human plasma supplies concentrated in United States and German collection networks, exposing production to donor availability shocks.
- EMA Pricing and Reimbursement Heterogeneity:Germany's AMNOG assessment diverges from France's HAS evaluation timelines, forcing parallel market access strategies that inflate commercial overhead.
- Subcutaneous Formulation Substitution:Self-administered FcRn blockers threaten intravenous infusion center volumes, compressing service revenue for hospital-based neurology departments.
Strategic Opportunities
- Japan's Sakigake Designation:PMDA's priority review system offers 6-month approval timelines for innovative neurology therapies, enabling first-mover positioning in Asia-Pacific's second-largest pharmaceutical market.
- Telehealth-Enabled Titration Monitoring:Remote acetylcholine receptor antibody testing and video-based strength assessment are opening rural United States patient cohorts previously excluded from specialty center catchment areas.
- EU AI Act Diagnostic Tailwinds:Algorithmic treatment response prediction tools qualify for streamlined CE marking under medical device software pathways, creating differentiation for integrated biologic-digital offerings.
Industry Challenges
- Neuroimmunology Specialist Scarcity:United States fellowship programs graduate fewer than 150 certified neuromuscular specialists annually, constraining prescriber bandwidth for complex biologic initiation protocols.
- Cold Chain Integrity Requirements:FcRn and complement protein stability demands sustained 2-8°C distribution from manufacturing through patient administration, elevating logistics complexity and spoilage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generalized Myasthenia Gravis (GMG) Management Market |
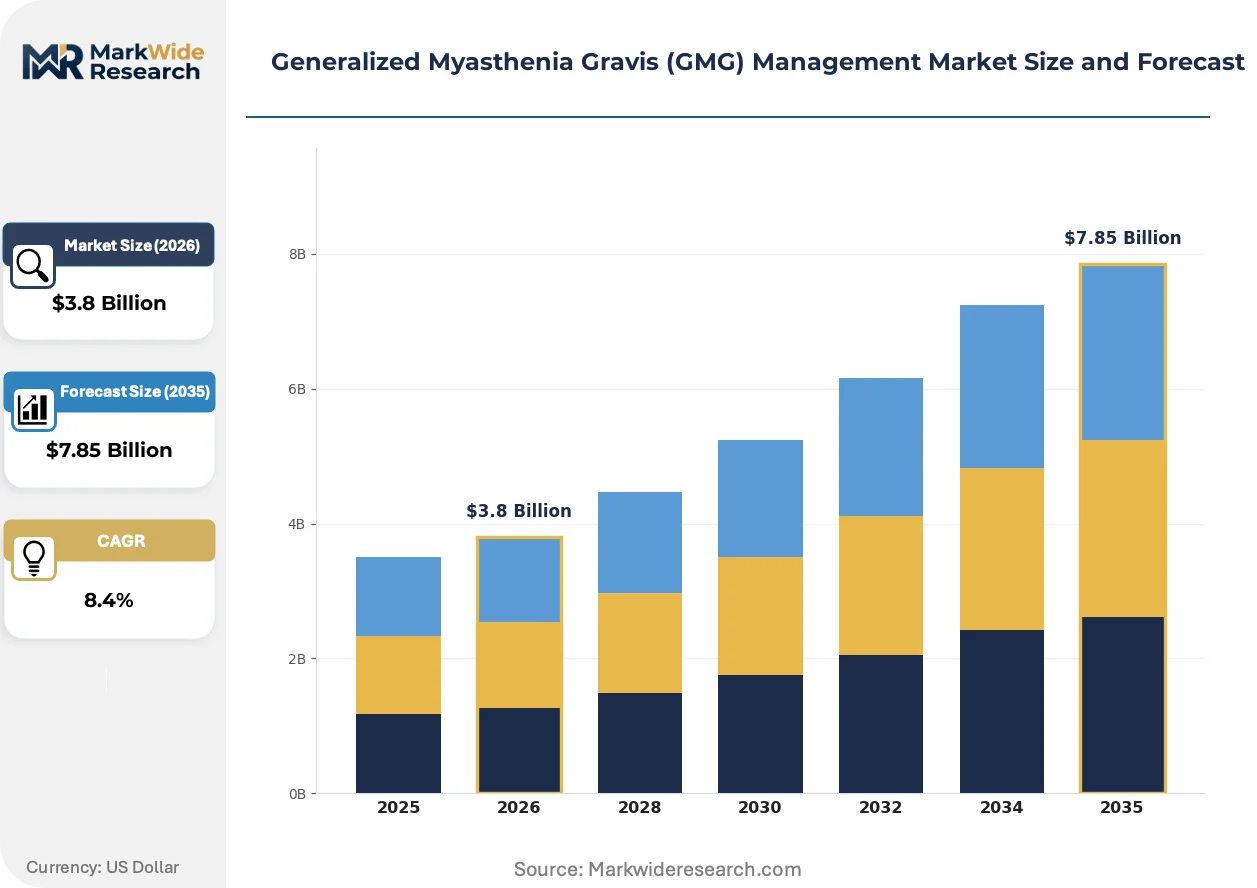
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Autoimmune Disorders, Neuromuscular Diseases, Chronic Illnesses, Rare Diseases Product Type: Immunosuppressants, Acetylcholinesterase Inhibitors, Corticosteroids, Biologic Agents, Plasma Exchange Therapies End User: Specialty Clinics, Neurology Centers, Research Institutes, Home Healthcare Providers Delivery Mode: Oral Medications, Intravenous Infusions, Subcutaneous Injections, Therapeutic Plasmapheresis |
| Companies Covered | Horizon Therapeutics, Novartis AG, Alexion Pharmaceuticals, Janssen Research & Development, Pfizer Inc., Argenx, Bristol Myers Squibb, Immunovant Sciences GmbH, UCB Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generalized Myasthenia Gravis (GMG) Management Market Shifts & Advancements
Biologic delivery mode innovation and regulatory data science integration are restructuring how neuromuscular therapies reach refractory patient populations.
Subcutaneous FcRn antagonist formulations are overtaking intravenous infusion protocols in prescriber preference surveys. Academic medical centers in the United States are piloting home-based self-injection programs for stable patients. This modality shift is compressing hospital outpatient revenue while expanding addressable geography beyond specialty center catchments.
EMA's PRIME eligibility criteria are reshaping development prioritization for European biotechnology firms. Early dialogue with the Committee for Medicinal Products for Human Use accelerates adaptive trial design acceptance. Small and mid-cap developers are restructuring Phase II protocols to capture biomarker endpoints that satisfy PRIME's unmet medical need threshold.
Integrated pharmacy benefit managers are consolidating prior authorization workflows for high-cost neurology biologics. United States commercial payers are mandating step-therapy documentation through proprietary digital platforms, displacing fax-based peer-to-peer review. This administrative concentration is visible most acutely in Medicare Advantage plans operating in Florida and Texas retirement corridors.
Generalized Myasthenia Gravis (GMG) Management Market Segmentation
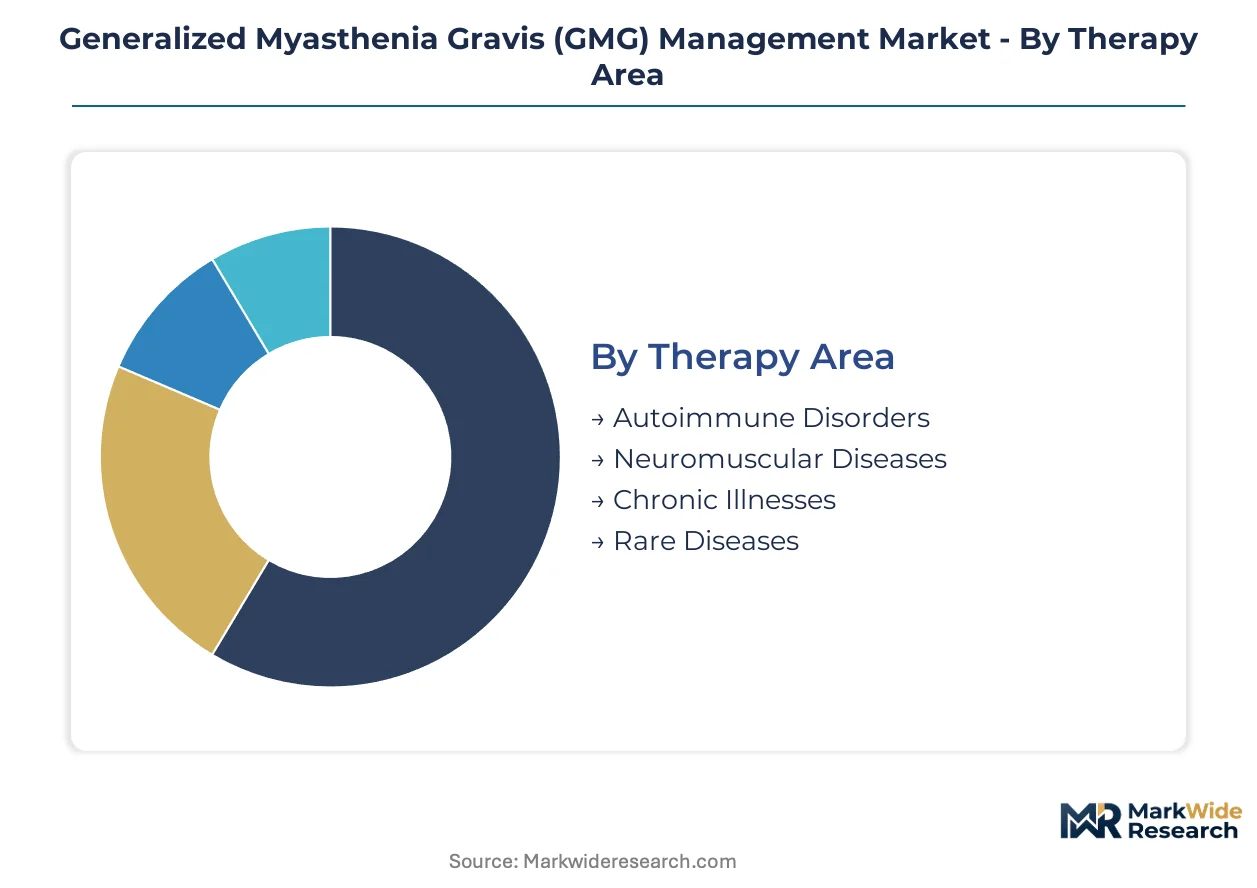
Segmentation in the GMG management market determines reimbursement pathways, prescriber access, and manufacturing scale requirements. FDA orphan drug status and EMA PRIME eligibility apply unevenly across therapy areas and product types, creating divergent commercial timelines.
Therapy Area:
FDA breakthrough therapy designation concentrates in autoimmune disorder and rare disease segments, while neuromuscular disease applications face extended Phase III requirements.
- Autoimmune Disorders:GMG falls within the broader autoimmune classification where FcRn inhibitors and complement modulators have transformed treatment paradigms. Academic medical centers in the United States concentrate demand for these advanced immunomodulators, driven by refractory patient volumes and clinical trial access.
- Neuromuscular Diseases:This segment encompasses disorders affecting peripheral nerve, neuromuscular junction, and muscle function. Prescriber bandwidth constraints in the United States limit biologic initiation to certified neuromuscular specialists, creating access bottlenecks in rural catchment areas.
- Chronic Illnesses:Long-term management protocols characterize this classification, requiring sustained medication adherence and monitoring infrastructure.
- Rare Diseases:Orphan drug incentives and accelerated approval pathways define commercial strategy here.
Autoimmune disorders sit at the top of the volume ranking, with rare diseases climbing the fastest.
Product Type:
Cost tier stratification separates premium biologics from generic-accessible small molecules, with plasma exchange occupying a service-revenue category distinct from pharmaceutical margins.
- Immunosuppressants:Azathioprine, mycophenolate mofetil, and calcineurin inhibitors constitute traditional maintenance therapy. Retail pharmacy networks in the United States dominate distribution, though formulary placement faces pressure from FcRn inhibitor step-therapy requirements.
- Acetylcholinesterase Inhibitors:Pyridostigmine bromide remains first-line symptomatic treatment with rapid onset of action. Generic manufacturing concentrates in Indian and Chinese API suppliers, exposing procurement to import inspection variability.
- Corticosteroids:Prednisone and methylprednisolone bridge acute crisis management to chronic immunosuppression.
- Biologic Agents:Eculizumab, efgartigimod, and rozanolixizumab command specialty pharmacy channels with cold chain distribution requirements.
- Plasma Exchange Therapies:Apheresis-based antibody removal serves myasthenic crisis intervention and pre-surgical optimization.
Acetylcholinesterase inhibitors anchor volume leadership, though biologic agents are expanding most quickly.
End User:
Customer type determines service revenue capture versus pharmaceutical margin accrual, with site-of-care shifting toward lower-acuity settings.
- Specialty Clinics:Dedicated neuroimmunology practices coordinate biologic initiation and monitoring. United States metropolitan clusters concentrate prescriber expertise, leaving exurban patients dependent on telehealth-enabled referral networks.
- Neurology Centers:Academic medical centers command clinical trial enrollment and complex case referral volumes. Infusion suite infrastructure investments at Johns Hopkins, Mayo Clinic, and UCSF Medical Center create competitive moats for intravenous biologic administration.
- Research Institutes:NIH-funded centers and contract research organizations drive biomarker discovery and adaptive trial design.
- Home Healthcare Providers:Subcutaneous formulation availability enables self-administration programs, compressing hospital outpatient revenue while expanding geographic reach.
Neurology centers hold the volume advantage, with home healthcare providers gaining share fastest.
Delivery Mode:
Supply concentration in sterile injectable manufacturing and plasma fractionation shapes availability and pricing dynamics across administration routes.
- Oral Medications:Tablet and capsule formulations of pyridostigmine, prednisone, and azathioprine dominate prescription volume. United States retail pharmacy networks and Medicare Part D formularies ensure broad access, though prior authorization requirements for dose escalation create administrative friction.
- Intravenous Infusions:Eculizumab and IVIG products require specialized infusion center infrastructure. Plasma-derived input dependence on United States and German collection networks exposes production to donor availability constraints.
- Subcutaneous Injections:Efgartigimod alfa and rozanolixizumab formulations enable patient self-administration after loading doses.
- Therapeutic Plasmapheresis:Apheresis equipment and trained operator availability limits service expansion.
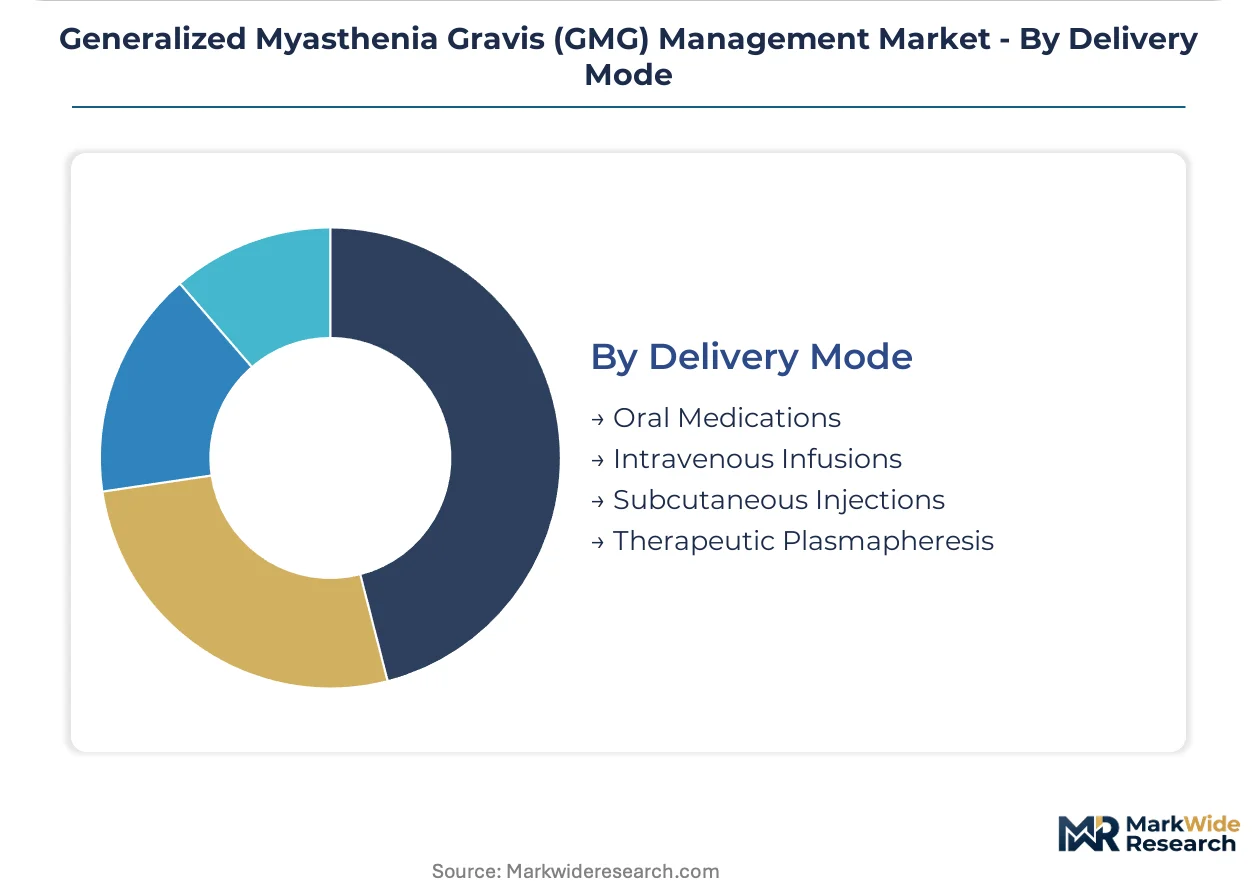
Oral medications command the highest prescription volumes, while subcutaneous injections show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing is migrating toward jurisdictions with streamlined rare disease approval pathways and concentrated plasma collection infrastructure. The United States and Germany maintain cost-of-compliance advantages for complement inhibitor production. Japan and Switzerland offer accelerated review mechanisms that compress commercialization timelines.
United States
Specialty infusion networks at Johns Hopkins, Mayo Clinic, and UCSF Medical Center drive demand for intravenous FcRn inhibitors. FDA orphan drug designation and breakthrough therapy pathways compress Phase II-to-approval timelines by 18-24 months. Plasma collection networks in Texas and Florida anchor fractionation supply for eculizumab manufacturing.
Germany
AMNOG assessment procedures create pricing transparency that attracts biologics licensing negotiations. EMA centralized review through Frankfurt-based rapporteurs accelerates complement-targeted therapy approvals. Bavarian plasma fractionation clusters in Munich and Heidelberg supply raw material for European manufacturing.
Japan
PMDA's Sakigake designation offers six-month priority review timelines for innovative neurology therapies. METI's regenerative medicine and cellular therapy commercialization framework supports FcRn inhibitor market entry. Tokyo and Osaka academic medical centers concentrate prescriber expertise for biologic initiation protocols.
Switzerland
Swissmedic's streamlined procedures for rare disease therapies attract European headquarters placement. Basel and Zurich host contract manufacturing organizations specializing in cold chain biologics. The country's dual EU-EFTA regulatory alignment enables parallel EMA and Swiss market access strategies.
United Kingdom
MHRA's Innovative Licensing and Access Pathway (ILAP) compresses timelines for refractory patient populations. London's National Hospital for Neurology and Neurosurgery anchors clinical trial enrollment for seronegative subpopulation studies. Cambridge biotech clusters develop algorithmic diagnostic tools under emerging UK AI regulation frameworks.
Generalized Myasthenia Gravis (GMG) Management Market Competitive Landscape
United States biopharmaceutical conglomerates anchor the premium biologics tier; European mid-cap specialists hold differentiated positions in FcRn pathway modulation. Market structure concentrates around three strategic archetypes: large-cap diversified pharmas with neurology franchises, rare disease pure-plays with complement expertise, and emerging biotechs with subcutaneous formulation platforms. Competitive moves center on portfolio diversification into adjacent autoimmune indications and strategic partnerships for plasma supply security.
Within the rare disease pure-play tier, Horizon Therapeutics and Alexion Pharmaceuticals exemplify complement pathway commercialization expertise, while Argenx occupies a position representing FcRn inhibitor differentiation. Novartis AG and Pfizer Inc. sit within the diversified pharma archetype, leveraging established specialty pharmacy relationships. These five entities collectively represent the competitive core around which reimbursement contracting and prescriber access strategies revolve.
| Leading Market Players |
|---|
| Horizon Therapeutics |
| Novartis AG |
| Alexion Pharmaceuticals |
| Janssen Research & Development |
| Pfizer Inc. |
| Argenx |
| Bristol Myers Squibb |
| Immunovant Sciences GmbH |
| UCB Biopharma |
| Others |
Supply & Pricing Matrix
Captive plasma fractionation in United States and German collection networks anchors both supply security and premium pricing power for complement-targeted therapies. This vertical integration choice insulates manufacturers from donor availability shocks while supporting sustained margin structures in specialty pharmacy channels.
Pricing Analysis
Distributor margin capture in United States specialty pharmacy channels stratifies across three tiers: premium biologics command 40-50% markups over acquisition cost, standard immunosuppressants flow through retail networks at compressed spreads, and economy generics face reimbursement ceiling pressure from Medicare Part D. Price differentiation hinges on FDA orphan drug exclusivity and cold chain certification tier. Cost compression in the oral generic segment intensifies as Indian API suppliers expand volume. Hospital procurement committees exhibit highest price sensitivity; academic medical centers with captive infusion suites show lowest.
Supply Chain Analysis
Workforce availability constraints in Bavarian and Texan plasma collection centers limit fractionation capacity expansion despite rising FcRn inhibitor demand. Supply concentrates in United States and German collection networks, with secondary processing clusters in Switzerland and Japan. Raw material dependencies include source plasma, chromatography resins, and single-use bioreactor components. Single-source vulnerability in protein A resin supply exposes production to logistics disruption. Distribution runs through cold chain logistics partners with 2-8°C validated packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in GMG management rests on subcutaneous formulation shifts that capture home administration premiums while compressing hospital outpatient costs. FcRn inhibitor developers who internalize fill-finish capacity capture additional 15-20 points of gross margin.
For Market Incumbents: Lock in plasma supply security through long-term collection network agreements in Texas and Florida corridors. Defend formulary position against subcutaneous FcRn blockers by embedding clinical pharmacists in academic medical center infusion suites. Prioritize backward integration into plasma fractionation to insulate against donor availability volatility. For New Entrants and Emerging Players: Telehealth-enabled prescriber networks offer the most penetrable route for reaching rural United States patients excluded from specialty center catchments. Target seronegative subpopulations with algorithmic diagnostic companions that satisfy EU AI Act compliance pathways. Pursue white-label manufacturing partnerships with Swiss CMOs to accelerate European market entry. For Investors and Strategic Acquirers: Roll-up economics work for subcutaneous formulation platforms because administration mode shifts are compressing hospital outpatient revenue and expanding addressable geography. Five-to-ten year viability favors developers with integrated digital therapeutics capabilities. Watch FDA breakthrough therapy designation velocity as inflection indicator for competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables patient self-administration and expands beyond infusion center catchments. |
| Plasma Supply Security Agreement | Locks in fractionated raw material access against donor availability volatility. |
| Orphan Drug Designation Pursuit | Compresses FDA review timelines and establishes seven-year exclusivity protection. |
| Digital Diagnostic Companion Development | Creates algorithmic differentiation under emerging EU AI Act frameworks. |
| Specialty Pharmacy Partnership | Secures prior authorization workflow integration with United States commercial payers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neuromuscular specialists, formulary directors at United States commercial payers, plasma collection network operators, and regulatory affairs leads at EMA rapporteur offices with secondary validation through FDA orphan drug designations, ClinicalTrials.gov entries, EMA PRIME eligibility decisions, and hospital procurement database extracts. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation anchored volume and value outputs.
Segment-weighting across therapy area, product type, end user, and delivery mode dimensions structured the analytical framework. CAGRs derived from spline interpolation between base and terminal year estimates, calibrated against historical biologic adoption curves in comparable autoimmune indications. Forecast inputs incorporated prescriber bandwidth constraints in United States fellowship programs and cold chain logistics capacity expansion plans.
The model assumes a particular technology adoption path; alternative pathways for subcutaneous self-injection would alter the outlook if patient adherence rates diverge from infusion center protocols. Forecasts reflect assumptions about FDA accelerated approval pathway utilization and EMA pricing negotiation timelines. Material deviation in plasma collection network expansion or neuroimmunology specialist graduation rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pigmentosa Treatment Market
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market