
 Global Gastrointestinal Therapeutics Market | 2026-2036
Global Gastrointestinal Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastrointestinal Therapeutics Market Foresight
Ireland is rewriting its position in gastrointestinal biologics manufacturing through expanded fill-finish capacity and active pharmaceutical ingredient synthesis hubs. AbbVie leverages its Humira infrastructure to sustain dominance in immunology-driven GI indications. Takeda Pharmaceutical anchors its global position through Osaka-based R&D and Osaka-manufactured vedolizumab supply chains. Pfizer competes through differentiated biosimilar strategies across ulcerative colitis and Crohn's disease portfolios.
Gastrointestinal therapeutics comprise pharmacological agents formulated to modulate mucosal inflammation, acid secretion, gut motility, or microbiome composition, typically manufactured through recombinant protein expression, small-molecule synthesis, or live-culture fermentation with specified purity thresholds and stability profiles. These agents serve to induce remission, maintain disease control, or alleviate symptomatic burden across acute and chronic digestive conditions. Anti-inflammatory agents command the largest revenue pool due to biologic pricing and chronic administration requirements, while probiotics represent the fastest-expanding category as microbiome science validates strain-specific clinical outcomes. Oral tablets maintain volume leadership across all therapy areas, though injectable solutions capture disproportionate margins in biologic-intensive inflammatory bowel disease segments.
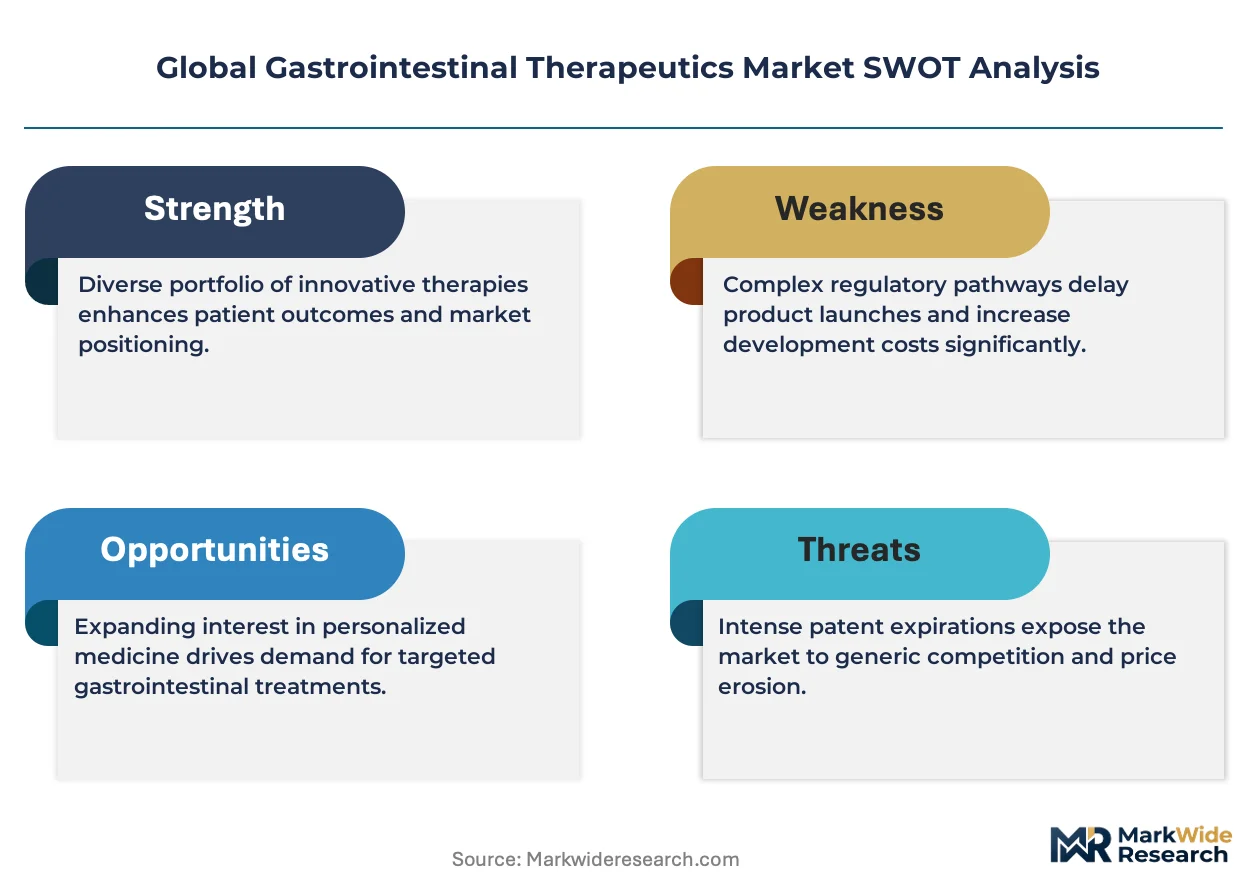
The FDA's Risk Evaluation and Mitigation Strategy requirements for biologic GI therapies shape prescriber certification and patient monitoring protocols, while the EMA's Committee for Medicinal Products for Human Use maintains stringent immunogenicity review standards that filter market entry in Europe. Japan's PMDA operates accelerated review Sakigake designation pathways that compress timelines for novel GI mechanisms. Stakeholders must monitor evolving biosimilar interchangeability rulings and country-specific pricing negotiations that will determine brand defense economics and portfolio prioritization across major markets.
Market Dynamics
The FDA's accelerated approval pathways for orphan GI indications are compressing development timelines and forcing incumbents to defend biologic franchises through manufacturing scale rather than patent exclusivity alone. Specialty clinics now demand rapid therapeutic switching capabilities that strain legacy supply chains.
Growth Catalysts
- Japan's PMDA Sakigake designation:The accelerated review pathway compresses approval timelines for novel GI mechanisms, drawing R&D investment toward first-in-class biologics.
- Specialty clinic expansion:Ambulatory infusion centers dedicated to inflammatory bowel disease are expanding biologic administration capacity across Germany and the United States.
- Microbiome strain validation:Live-culture fermentation advances are enabling probiotics with specified clinical outcomes to command premium positioning.
Market Restraints
- EMA immunogenicity standards:The Committee for Medicinal Products for Human Use maintains stringent review thresholds that filter market entry and extend validation timelines for European launches.
- Fill-finish capacity concentration:Active pharmaceutical ingredient synthesis and final formulation capacity clusters in Ireland, creating geographic single-point vulnerabilities.
- Biologic cold chain requirements:Temperature-controlled distribution infrastructure limits market access in regions lacking specialized logistics networks.
Strategic Opportunities
- India's CDSCO biosimilar pathway:The abbreviated approval framework for biologics creates white space for ulcerative colitis and Crohn's disease portfolio entries.
- Oral biologic delivery:Intestinal permeation technologies are converging with peptide stabilization chemistry to enable non-injectable administration.
- Direct-to-specialist distribution:Bypassing wholesale channels through captive pharmacy networks is capturing margin in United States gastroenterology practices.
Industry Challenges
- Biologic manufacturing talent scarcity:Recombinant protein expression expertise concentrates at established hubs, constraining new facility staffing.
- Interchangeability certification complexity:The FDA's biosimilar switching study requirements demand extensive clinical investment before pharmacy-level substitution approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastrointestinal Therapeutics Market |
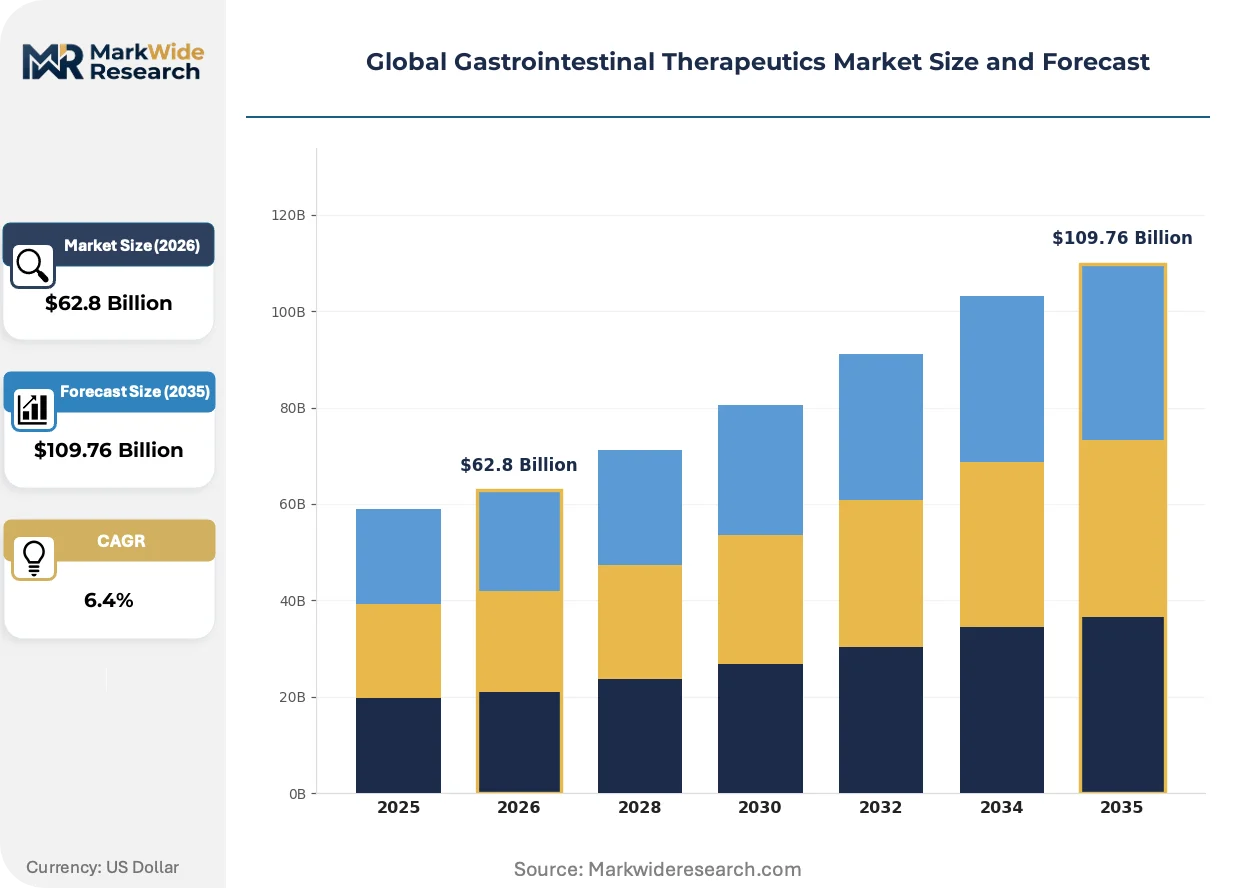
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $109.76 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antacids, Laxatives, Anti-inflammatory Agents, Probiotics, Antispasmodics Therapy Area: Peptic Ulcer, Inflammatory Bowel Disease, Gastroesophageal Reflux, Irritable Bowel Syndrome, Constipation End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Pharmaceutical Distributors, Diagnostic Centers Delivery Mode: Oral Tablets, Injectable Solutions, Topical Gels, Capsules, Oral Suspension |
| Companies Covered | AbbVie, AstraZeneca, Takeda Pharmaceutical, Pfizer, Sanofi, Johnson & Johnson, GlaxoSmithKline, Novartis, Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastrointestinal Therapeutics Market Shifts & Advancements
Artificial intelligence is digitizing target identification and patient stratification workflows, compressing discovery timelines while regulatory bodies scramble to adapt oversight frameworks. These shifts are reshaping competitive advantage around data infrastructure rather than chemistry platforms alone.
Machine learning algorithms trained on multi-omics datasets are digitizing biomarker discovery for inflammatory bowel disease subtyping. Large academic medical centers in the United States and Germany are deploying these tools to predict therapeutic response before biologic initiation. The technology is digitizing prescriber decision support, shifting competitive differentiation toward diagnostic-therapeutic bundling.
The European Medicines Agency's evolving stance on real-world evidence acceptance is reshaping post-market study obligations for GI biologics. Sponsors now face expanded pharmacovigilance requirements that extend data collection obligations beyond traditional randomized trial endpoints. Inflammatory bowel disease portfolios face the steepest compliance burden as EMA reviewers demand longitudinal safety datasets.
Specialty pharmacies are consolidating purchasing influence through centralized formulary management across integrated delivery networks. United States gastroenterology practices are migrating toward white-bagging arrangements that bypass traditional wholesale channels. This channel compression is most visible in Massachusetts and California health systems where captive specialty pharmacies control biologic dispensing.
Global Gastrointestinal Therapeutics Market Segmentation
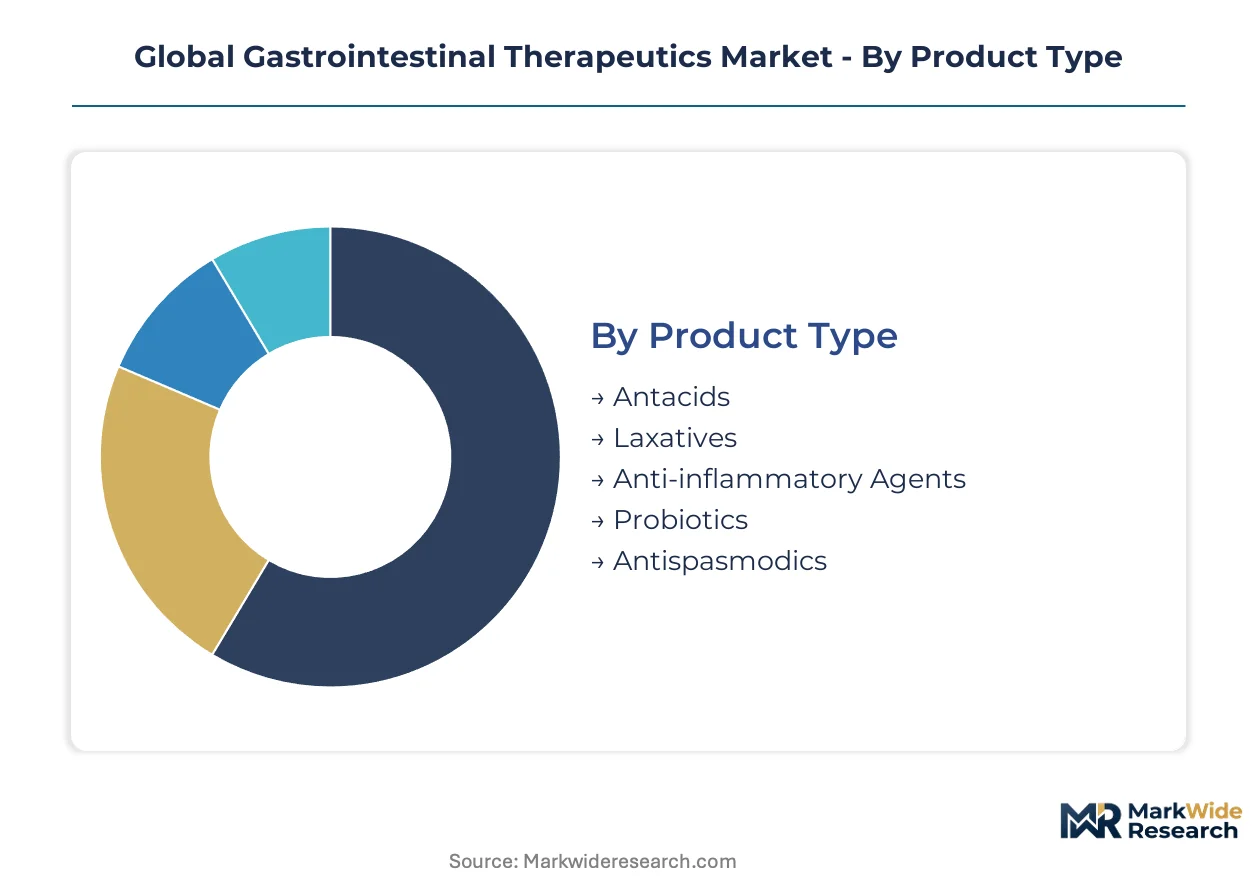
Gastrointestinal therapeutics segment along four dimensions that determine pricing power, regulatory pathway, and channel strategy. Product type and therapy area define clinical positioning, while delivery mode and end user shape margin structure and cold chain requirements.
Product Type:
Mature small-molecule categories dominate volume, while emerging biologic platforms capture premium positioning and chronic administration revenue pools.
- Anti-inflammatory Agents:Recombinant monoclonal antibodies and fusion proteins targeting TNF-alpha, integrins, and interleukins. Demand concentrates in United States and Germany where specialty clinics administer biologics for Crohn's disease and ulcerative colitis, constrained by EMA immunogenicity review thresholds.
- Probiotics:Live-culture formulations with specified strain identities and colony-forming unit counts, manufactured through controlled fermentation. Japan's PMDA Sakigake designation accelerates approval for microbiome-targeted mechanisms, drawing R&D investment toward strain-specific clinical outcomes.
- Antacids:Aluminum, magnesium, and calcium salt formulations neutralizing gastric acid.
- Laxatives:Osmotic, stimulant, and bulk-forming agents modulating colonic transit.
- Antispasmodics:Smooth muscle relaxants targeting gastrointestinal motility disorders.
Anti-inflammatory agents handle the majority of throughput; probiotics are gaining share fastest on microbiome science validation.
Therapy Area:
Chronic autoimmune conditions generate recurring revenue, while acute symptom management operates on episodic demand patterns.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis requiring immunomodulatory intervention. United States specialty clinics and German ambulatory infusion centers drive biologic uptake, supported by FDA accelerated approval pathways for orphan indications.
- Irritable Bowel Syndrome:Functional disorder with microbiome, neuromodulatory, and motility-targeted therapeutic approaches. Japan's aging demographics and diagnostic infrastructure support premium therapy adoption for IBS-D and IBS-C subtypes.
- Peptic Ulcer:Acid-related mucosal damage managed through suppression and eradication protocols.
- Gastroesophageal Reflux:Chronic acid exposure managed through proton pump inhibitors and surgical intervention.
- Constipation:Functional and opioid-induced variants addressed through multiple mechanistic classes.
Inflammatory bowel disease commands the steepest pricing; irritable bowel syndrome shows the steepest expansion trajectory on diagnostic recognition.
End User:
Channel configuration determines reimbursement mechanics and patient access controls, with institutional purchasers wielding consolidated formulary influence.
- Specialty Clinics:Dedicated inflammatory bowel disease infusion centers with captive pharmacy networks. Massachusetts and California health systems deploy white-bagging arrangements that bypass traditional wholesale channels, capturing margin through direct-to-specialist distribution.
- Hospitals:Inpatient and outpatient departments managing acute GI bleeding, severe flares, and surgical complications. Germany's integrated care structures concentrate high-cost biologic administration within hospital-affiliated day clinics.
- Ambulatory Surgery Centers:Procedure-focused settings with limited therapeutic dispensing scope.
- Pharmaceutical Distributors:Wholesale intermediaries facing margin compression from channel consolidation.
- Diagnostic Centers:Endoscopy and imaging facilities with adjacent prescription authority in select markets.
Specialty clinics handle the majority of biologic throughput; ambulatory surgery centers are expanding fastest on procedure-therapy bundling.
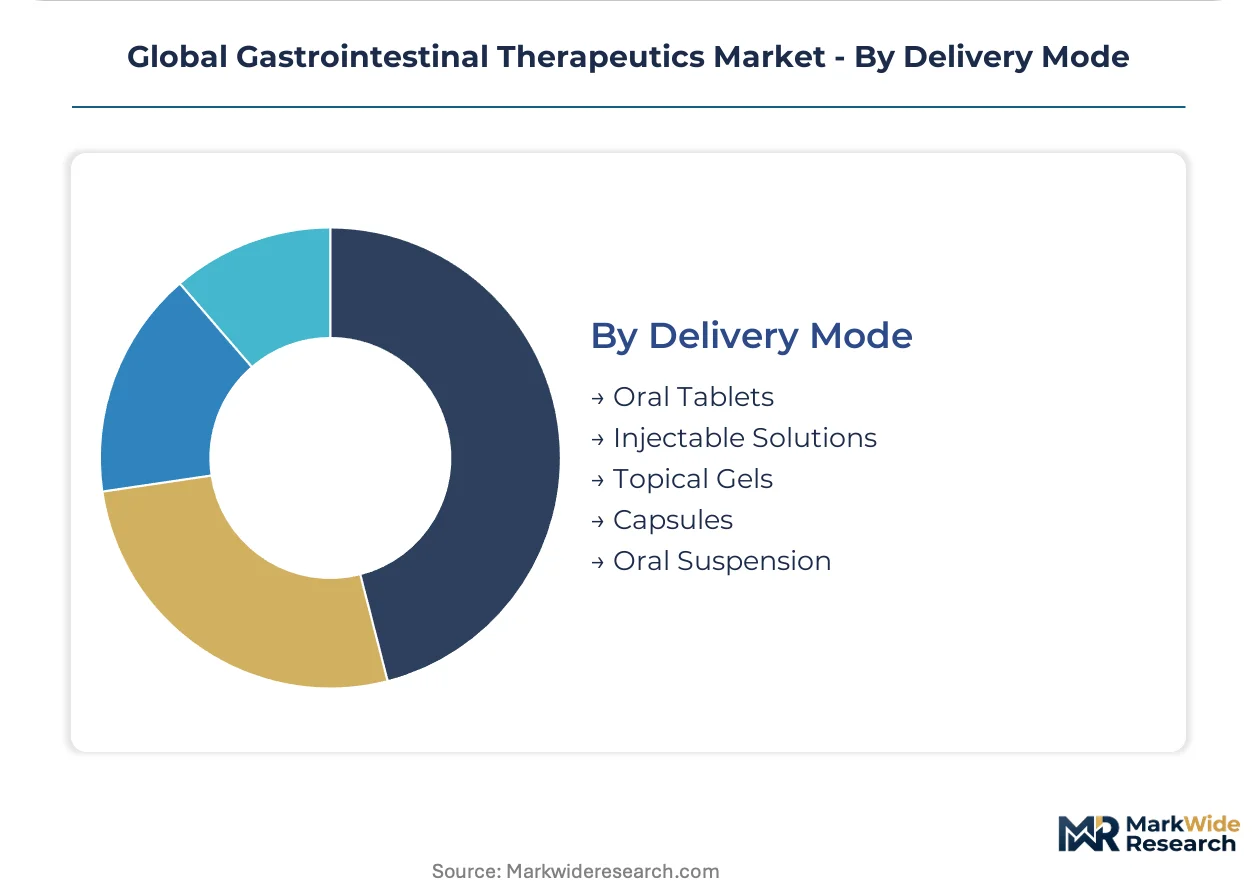
Delivery Mode:
Route of administration dictates manufacturing complexity, stability requirements, and patient compliance economics.
- Injectable Solutions:Subcutaneous and intravenous biologics requiring cold chain distribution and infusion infrastructure. Ireland's fill-finish capacity clusters create geographic concentration risk for European supply security.
- Oral Tablets:Small-molecule formulations with established bioavailability profiles and ambient storage requirements. Volume leadership across all therapy areas, though margin compression intensifies in commoditized antacid and laxative categories.
- Capsules:Encapsulated formulations including delayed-release and enteric-coated variants.
- Oral Suspension:Liquid formulations for pediatric and dysphagia populations.
- Topical Gels:Rectal and perianal preparations for localized mucosal delivery.
Oral tablets handle the majority of throughput; injectable solutions are climbing the fastest on biologic portfolio expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for orphan gastrointestinal indications anchor the United States as the dominant geography, while Japan's PMDA Sakigake designation and Germany's EMA-aligned immunogenicity standards create divergent regulatory environments across major markets.
United States
Specialty clinic expansion and white-bagging arrangements in Massachusetts and California health systems drive biologic uptake for inflammatory bowel disease. FDA Risk Evaluation and Mitigation Strategy requirements shape prescriber certification protocols. Greater Boston and San Francisco Bay Area clusters concentrate machine learning biomarker discovery platforms for therapeutic response prediction.
Germany
Ambulatory infusion centers and integrated care structures concentrate high-cost biologic administration within hospital-affiliated day clinics. EMA Committee for Medicinal Products for Human Use immunogenicity review thresholds filter market entry and extend validation timelines. North Rhine-Westphalia and Bavaria host the densest networks of gastroenterology-focused specialty pharmacies.
Japan
Aging demographics and diagnostic infrastructure support premium therapy adoption for irritable bowel syndrome subtypes. PMDA Sakigake designation compresses approval timelines for novel GI mechanisms, drawing R&D investment toward first-in-class biologics. Osaka anchors Takeda Pharmaceutical's vedolizumab manufacturing supply chains and R&D operations.
Ireland
Expanded fill-finish capacity and active pharmaceutical ingredient synthesis hubs rewrite the country's position in gastrointestinal biologics manufacturing. EMA regulatory alignment enables streamlined European market access from Irish production facilities. Dublin and Cork clusters create geographic concentration risk for European supply security.
India
CDSCO abbreviated approval framework for biologics creates white space for ulcerative colitis and Crohn's disease portfolio entries. Domestic fermentation expertise supports live-culture probiotic manufacturing expansion. Maharashtra and Gujarat pharmaceutical corridors attract contract development and manufacturing organization investment for GI therapeutic production.
Global Gastrointestinal Therapeutics Market Competitive Landscape
Capability concentration sits with biologic manufacturing specialists; scale advantage sits with diversified immunology franchises. The market structure tiers around legacy patent-protected portfolios, biosimilar challengers, and microbiome-focused entrants. Dominant competitive moves include manufacturing capacity expansion in Ireland and India, plus strategic partnerships for oral biologic delivery technologies.
Within the diversified immunology tier, AbbVie and Takeda Pharmaceutical occupy positions shaped by legacy infrastructure and geographic manufacturing concentration. AbbVie leverages established fill-finish networks to sustain presence in inflammatory bowel disease segments. Takeda Pharmaceutical anchors its competitive position through Osaka-based supply chain integration. Pfizer exemplifies the biosimilar challenger archetype, competing through differentiated portfolio strategies across ulcerative colitis and Crohn's disease indications.
| Leading Market Players |
|---|
| AbbVie |
| AstraZeneca |
| Takeda Pharmaceutical |
| Pfizer |
| Sanofi |
| Johnson & Johnson |
| GlaxoSmithKline |
| Novartis |
| Eli Lilly |
| Others |
Supply & Pricing Matrix
Fill-finish capacity concentration in Ireland creates geographic single-point vulnerability that simultaneously compresses margin buffers for European biologic launches and forces pricing stratification across cold-chain-capable versus ambient-stable delivery modes. This structural dependency rewards manufacturers with captive synthesis infrastructure while penalizing portfolio-heavy players exposed to third-party tolling markups.
Pricing Analysis
United States biologic pricing runs 40-60 percent above German ambulatory infusion center reimbursement rates, with Japan's PMDA Sakigake-designated therapies commanding intermediate positioning. Three-tier pricing structure across premium biologics, standard small-molecules, and economy antacid categories reflects EMA immunogenicity certification thresholds and cold chain logistics burden. Pricing pressure stems from biosimilar interchangeability rulings compressing originator defense windows. Hospital procurement committees exhibit highest price sensitivity; specialty clinics with captive pharmacy networks demonstrate lowest.
Supply Chain Analysis
Export-control restrictions on recombinant protein expression technologies limit knowledge transfer to emerging manufacturing hubs, constraining capacity expansion outside established clusters. Active pharmaceutical ingredient synthesis concentrates in Ireland, India, and China; final fill-finish capacity clusters in Ireland and Germany. Supply chains draw from temperature-sensitive biologic substrates, specialized fermentation media, and single-use disposable systems. Single-source vulnerability around Irish fill-finish infrastructure threatens European supply security. Distribution runs through specialty pharmacy networks bypassing traditional wholesale channels in United States gastroenterology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastrointestinal therapeutics market sits at a post-patent-cliff recovery phase where biosimilar absorption of legacy biologic revenue pools creates cyclical reinvestment opportunity for first-in-class mechanism developers.
For Market Incumbents: Pre-empt biosimilar erosion by accelerating Osaka-based vedolizumab manufacturing scale-up and securing Irish fill-finish captive capacity. Defend inflammatory bowel disease positioning through vertical integration into active pharmaceutical ingredient synthesis rather than relying on third-party tolling relationships exposed to capacity bottlenecks. For New Entrants and Emerging Players: Pursue India's CDSCO abbreviated biologic approval pathway for ulcerative colitis and Crohn's disease portfolio entries where regulatory whitespace exists. Target probiotic strain-specific clinical outcome validation as the most penetrable category, leveraging Maharashtra fermentation corridor infrastructure for cost-advantaged live-culture manufacturing. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturing-specialist acquisition targets with captive fill-finish infrastructure. Long-term viability over the next decade hinges on oral biologic delivery technology ownership rather than injectable-dependent portfolios. Watch FDA biosimilar interchangeability certification timelines as the critical inflection signal for originator defense economics.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | AbbVie's Humira infrastructure expansion in Ireland secures European biologic supply continuity against geographic concentration risk. |
| Regulatory Approval Pathway | PMDA Sakigake designation compresses novel GI mechanism timelines, drawing R&D investment toward Osaka-based development. |
| Pipeline Diversification | Microbiome strain validation programs in Japan address fastest-expanding therapeutic category with specified clinical outcomes. |
| Strategic Partnership | Oral biologic delivery technology alliances bypass injectable cold chain limitations for inflammatory bowel disease administration. |
| Geographic Expansion | White-bagging arrangements in Massachusetts and California health systems capture margin through direct-to-specialist distribution. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases anchors the qualitative findings. Bottom-up patient-flow modeling and top-down revenue reconciliation triangulate market sizing across therapy areas.
Calibration against historical biologic launch trajectories and biosimilar absorption patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, therapy area, delivery mode, and end user, with regional regulatory cluster effects modeled separately. CAGRs derive from patent expiry schedules, pipeline advancement rates, and diagnostic infrastructure expansion curves.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement compression rates or biologic cold chain logistics costs would shift the trajectory. Forecasts reflect assumptions around EMA immunogenicity standard stability and FDA interchangeability ruling timelines. Material shifts in Irish manufacturing capacity availability or PMDA Sakigake designation criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market