
 Ketorolac Market | 2026-2036
Ketorolac Market Size, Share, and Industry Trends Forecast 2026-2036
Ketorolac Market Outlook
Hospital group purchasing organization consolidation is expanding across the United States, concentrating buying power among fewer procurement entities. Fresenius Kabi leverages its vertically integrated injectable manufacturing to secure long-term supply contracts with these consolidated buyers. Dr. Reddy's Laboratories anchors its position through high-volume generic production of ketorolac tromethamine injection. Pfizer sustains brand recognition in the segment through its original formulation heritage and hospital formulary relationships.
Ketorolac tromethamine is a non-steroidal anti-inflammatory drug (NSAID) of the pyrrolo-pyrrole class, synthesized through condensation of pyrrole derivatives followed by tromethamine salt formation to enhance aqueous solubility for parenteral delivery. It functions primarily as a potent analgesic for moderate-to-severe acute pain, with its injectable form achieving peak plasma concentration within approximately 45 minutes. The injection dosage form dominates volume due to perioperative use in hospital settings, while ophthalmic solution represents a higher-margin niche driven by cataract surgery protocols. Parenteral route administration leads in value contribution, though nasal spray formats attract development interest for migraine indication expansion.
FDA bioequivalence requirements for parenteral generics, enforced through its Office of Generic Drugs, elevate manufacturing compliance costs and filter subscale producers from contract eligibility. USP monograph standards for ketorolac tromethamine injection specify stringent particulate matter limits and stability profiles that shape formulation development priorities. The Drug Enforcement Administration's opioid prescribing restrictions indirectly bolster ketorolac positioning within multimodal analgesia protocols. Stakeholders must monitor FDA complex generic guidance evolution and hospital antimicrobial stewardship committee influence on NSAID substitution patterns.
Market Dynamics
Hospital group purchasing organization consolidation is concentrating procurement power among fewer entities, forcing generic injectable manufacturers to secure long-term supply contracts through manufacturing scale and vertical integration rather than price competition alone.
Growth Catalysts
- DEA opioid prescribing restrictions:The Drug Enforcement Administration's tightened controls on opioid dispensing are pushing surgical centers toward multimodal analgesia protocols where ketorolac serves as a primary non-narcotic alternative.
- Ambulatory surgical volume expansion:Same-day discharge protocols for orthopedic and ophthalmic procedures are expanding the addressable patient base for perioperative NSAID administration in outpatient settings.
- FDA complex generic guidance evolution:The Office of Generic Drugs is clarifying bioequivalence pathways for parenteral formulations, reducing regulatory uncertainty for manufacturers investing in injectable capacity.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for ketorolac tromethamine concentrates among a limited number of Indian and Chinese manufacturers, creating vulnerability to export restrictions or quality enforcement actions.
- USP particulate matter standards:United States Pharmacopeia monograph requirements for subvisible particles in parenteral solutions demand specialized filtration infrastructure that elevates capital costs for new market entrants.
- Acetaminophen-NSAID combination substitution:Fixed-dose oral combinations of acetaminophen and ibuprofen are capturing mild-to-moderate acute pain indications previously served by single-agent ketorolac therapy.
Strategic Opportunities
- Nasal spray migraine indication:Intranasal ketorolac formulations targeting emergency department headache management represent an underserved acute pain segment with faster onset than oral routes.
- Indian CDSCO manufacturing incentives:India's Production Linked Incentive scheme for pharmaceuticals is subsidizing domestic injectable capacity expansion for export-oriented generic producers.
- Ophthalmic surgery protocol integration:Cataract surgery guidelines are incorporating topical NSAID drops into standard postoperative regimens, expanding the higher-margin ophthalmic solution segment.
Industry Challenges
- Injectable formulation expertise scarcity:Sterile manufacturing competency for parenteral NSAIDs requires specialized aseptic processing skills that compete with biologics and vaccine production for limited talent pools.
- Legacy ERP integration with track-and-trace systems:Serialization requirements under the Drug Supply Chain Security Act are forcing manufacturers to reconfigure warehouse management infrastructure for unit-level verification.
- Antimicrobial stewardship committee influence:Hospital pharmacy and therapeutics committees are scrutinizing all perioperative medications for infection risk, creating formulary access friction despite ketorolac's non-antibiotic status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ketorolac Market |
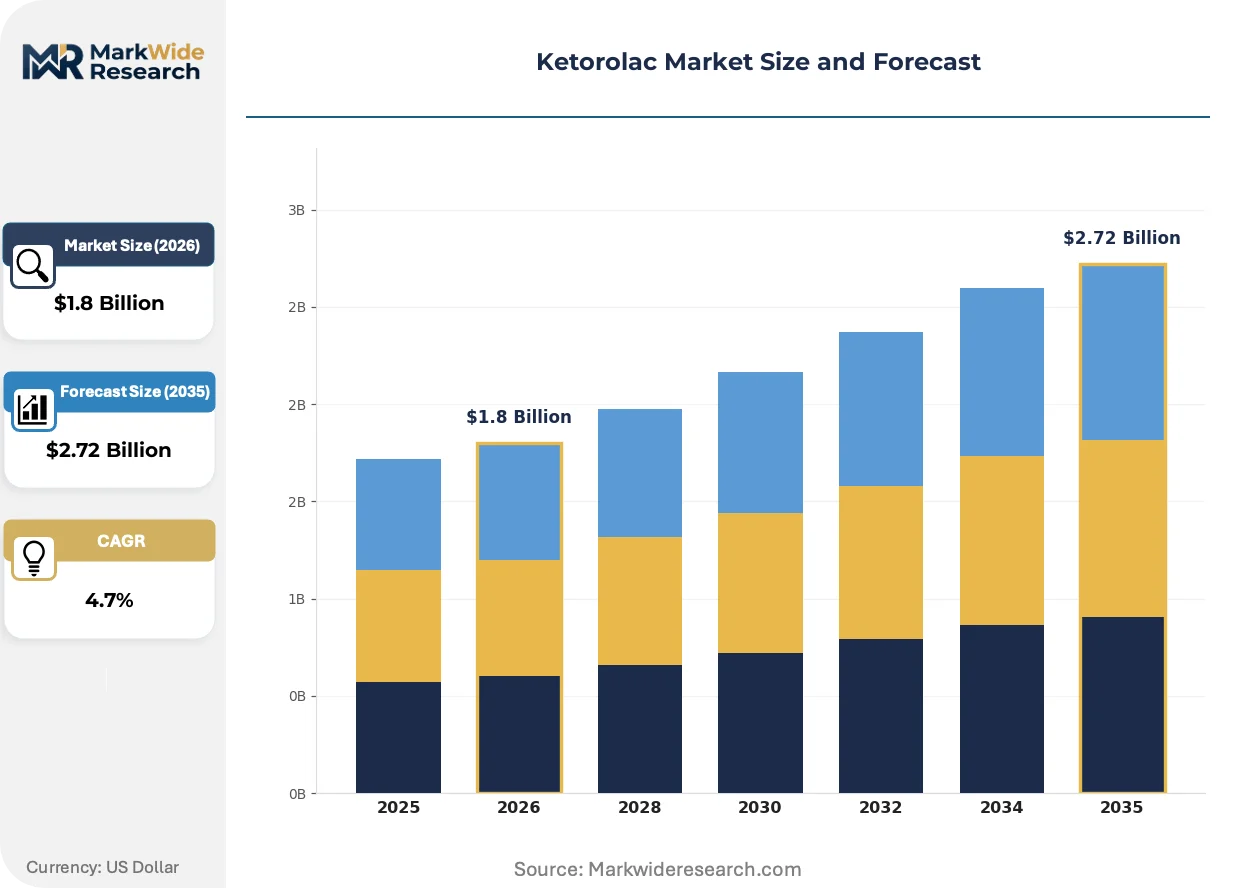
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Dosage Form: Tablet, Injection, Nasal Spray, Ophthalmic Solution End User: Hospitals, Clinics, Home Care, Pharmacies Route of Administration: Oral, Parenteral, Nasal, Topical Indication: Postoperative Pain, Acute Pain, Inflammation, Migraine |
| Companies Covered | Fresenius Kabi, Dr. Reddy's Laboratories, Pfizer, West Ward Pharmaceuticals, Gland Pharma Limited, Allergan, Teva Pharmaceuticals, Cadila Healthcare Limited, Omeros Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ketorolac Market Strategic Shifts
Formulation technology advances and regulatory clarity are reshaping how ketorolac reaches patients, with delivery mechanism innovation outpacing molecular modification as the primary vector for competitive differentiation.
Ready-to-use prefilled syringe formats are displacing traditional vial-and-ampoule presentations in perioperative settings. Hospital pharmacies are adopting these units to reduce compounding labor and medication error risk. This shift is decentralizing preparation responsibility from centralized pharmacy operations to point-of-care anesthesia teams, compressing the value captured by traditional contract compounding services.
The FDA's Office of Generic Drugs is tightening bioequivalence demonstration requirements for parenteral NSAIDs through refined statistical methodologies for pharmacokinetic comparison. Manufacturers must now conduct more rigorous in vivo studies with narrower confidence intervals. Generic injectable specialists with established clinical trial infrastructure are absorbing these compliance costs more readily than emerging competitors, consolidating contract manufacturing relationships.
Hospital supply chain directors are consolidating injectable procurement through single-source agreements with vertically integrated suppliers. Group purchasing organizations are replacing multi-vendor bidding with sole-source contracts spanning three-to-five year horizons. This concentration is most visible in the United States, where health system mergers have reduced the number of independent formulary decision-makers by nearly half over the past decade.
Ketorolac Market Segmentation
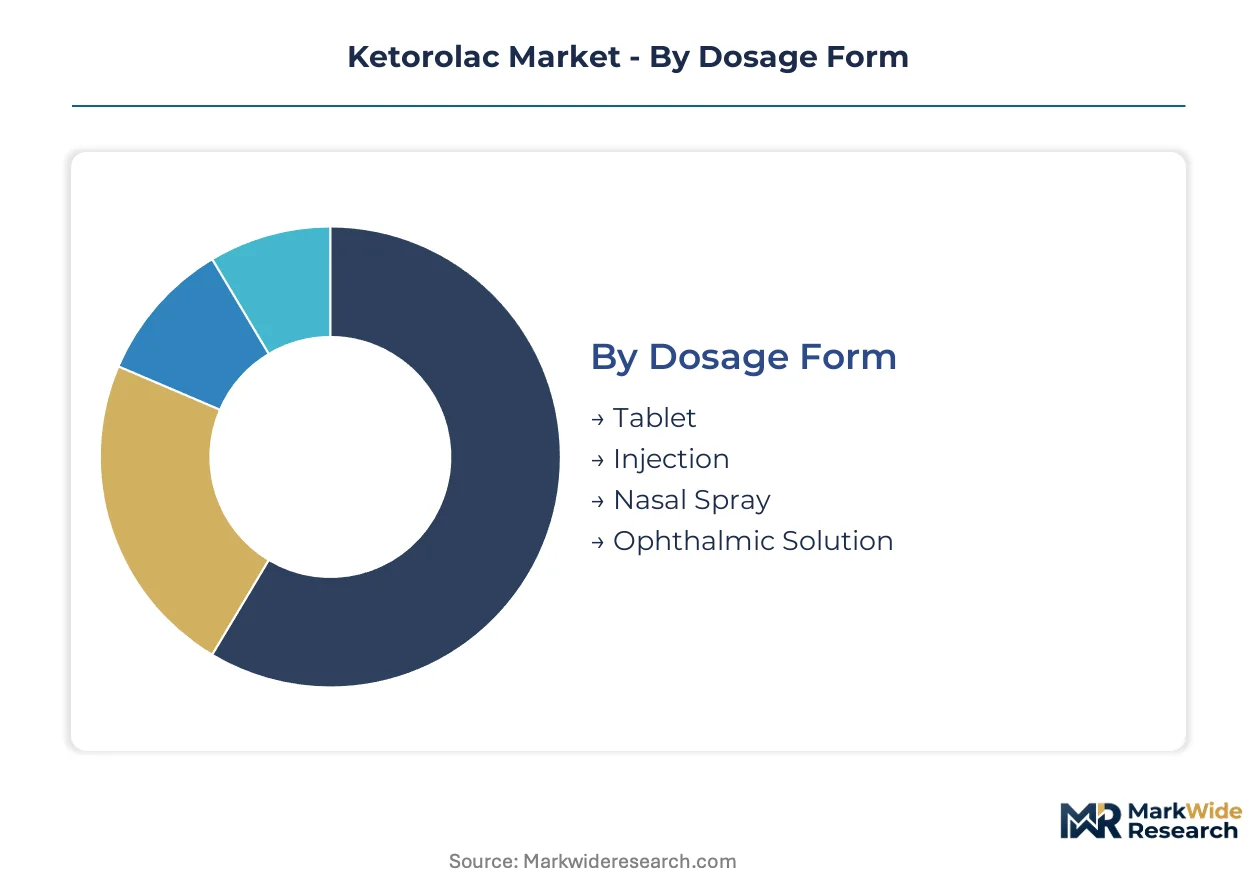
Ketorolac's therapeutic utility fragments across delivery mechanisms and care settings, with each segment commanding distinct manufacturing competencies and reimbursement pathways. Understanding these divides clarifies where capital deployment yields margin protection versus volume capture.
Dosage Form:
Standalone injectable formats dominate hospital procurement, while embedded combination therapies and patient-administered alternatives reshape competitive boundaries.
- Injection:Sterile aqueous solution of ketorolac tromethamine in vial or prefilled syringe presentation, requiring aseptic manufacturing under USP <797> standards. Hospital surgical suites in the United States anchor demand as multimodal analgesia protocols displace opioid monotherapy; Fresenius Kabi and Dr. Reddy's Laboratories compete through vertical manufacturing scale and FDA bioequivalence dossier depth.
- Tablet:Oral solid dosage form containing ketorolac tromethamine for short-term acute pain management, subject to FDA dissolution profile requirements. Outpatient clinics and discharge prescribing in India and the United States concentrate volume, though fixed-dose acetaminophen-ibuprofen combinations are eroding single-agent positioning in mild-to-moderate indications.
- Nasal Spray:Intranasal aqueous formulation delivering rapid systemic absorption bypassing first-pass metabolism. Emergency department migraine protocols and pediatric needle-averse populations drive development interest, with faster onset kinetics than oral routes.
- Ophthalmic Solution:Isotonic topical drop for post-cataract surgery inflammation and pain, commanding premium pricing within single-use preservative-free unit-dose formats. Cataract surgery volume expansion in ambulatory surgical centers supports segment margins.
Injection leads volumes today; ophthalmic solution is gaining share fastest.
End User:
Procurement authority concentrates among institutional buyers with formulary control, while direct-to-patient channels remain fragmented and price-sensitive.
- Hospitals:Integrated health systems and academic medical centers with centralized pharmacy operations and group purchasing organization contracts. US hospital consolidation has halved independent formulary decision-makers over the past decade, concentrating negotiating leverage with vertically integrated injectable suppliers.
- Clinics:Ambulatory surgical centers and specialty pain practices with limited on-site compounding infrastructure. Same-day discharge protocols for orthopedic and ophthalmic procedures are expanding perioperative NSAID administration in these settings.
- Home Care:Post-acute and hospice settings where oral tablet administration predominates. Reimbursement compression through Medicare Part D and Medicaid preferred drug lists constrains brand retention.
- Pharmacies:Retail and mail-order dispensaries handling outpatient prescriptions with generic substitution mandates. State-level opioid prescribing restrictions indirectly bolster non-controlled NSAID dispensing volumes.
Hospitals anchor procurement scale; clinics are expanding most quickly.
Route of Administration:
Systemic exposure requirements and onset speed demands determine route selection, with invasive delivery commanding technical premiums.
- Parenteral:Intramuscular or intravenous injection achieving peak plasma concentration within approximately 45 minutes. Perioperative settings requiring rapid analgesic onset sustain this route's value contribution despite higher administration costs.
- Oral:Gastrointestinal absorption with delayed onset versus parenteral alternatives. Discharge prescribing and step-down protocols from injectable therapy concentrate demand in this route.
- Nasal:Olfactory and respiratory mucosa absorption with intermediate pharmacokinetic profile. Migraine indication expansion and needle-phobia addressing applications support development pipelines.
- Topical:Local ocular or dermal application with minimal systemic exposure. Ophthalmic surgery protocols specifically favor this route for inflammation control without bleeding risk elevation.
Parenteral administration dominates value capture; nasal delivery is climbing the fastest.
Indication:
Pain severity stratification and procedure-specific protocols segment demand, with acute surgical applications defending pricing power against chronic use restrictions.
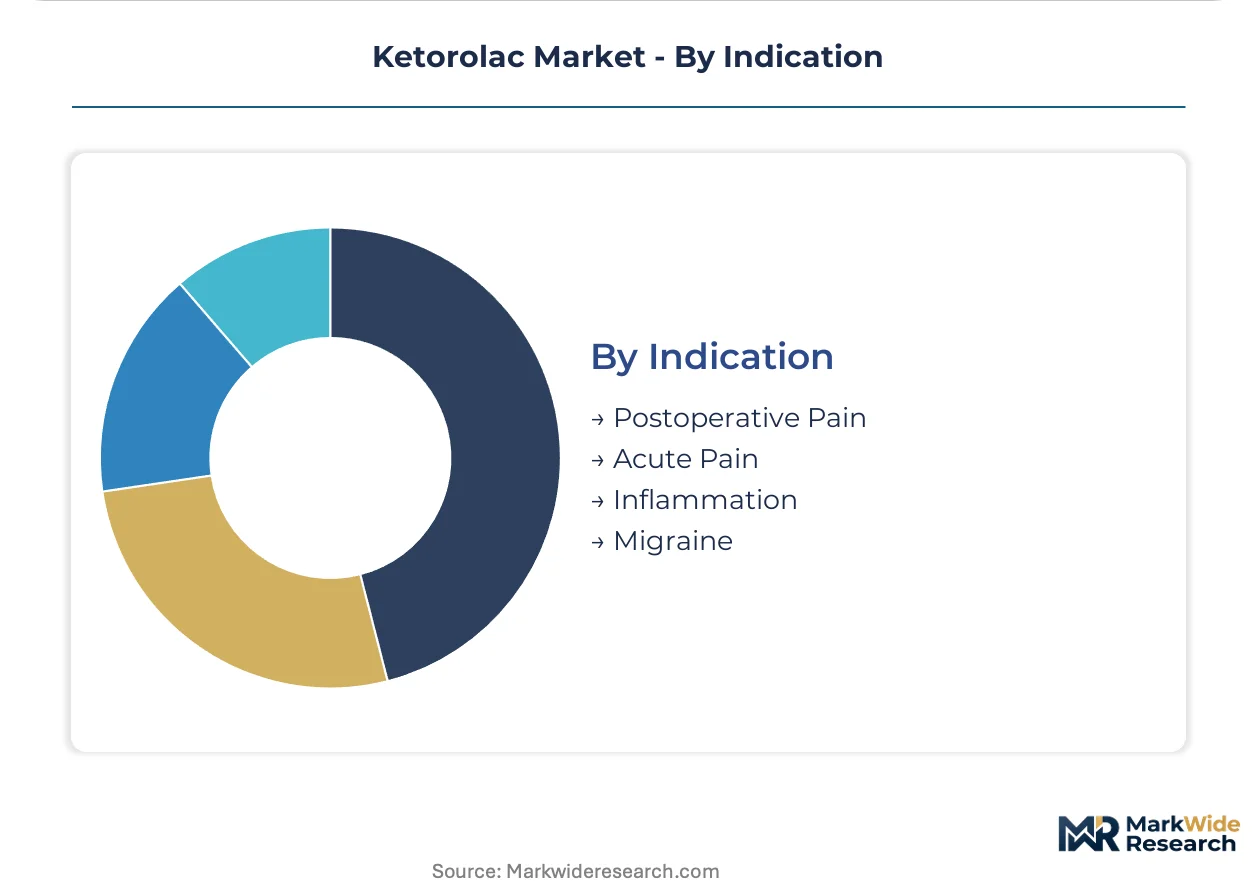
- Postoperative Pain:Moderate-to-severe acute pain following surgical intervention, where ketorolac's opioid-sparing profile aligns with enhanced recovery after surgery protocols. Orthopedic and general surgery departments in US hospitals anchor volume through multimodal analgesia order sets.
- Acute Pain:Non-surgical trauma, renal colic, and other time-limited severe pain presentations in emergency departments. DEA opioid prescribing restrictions are pushing emergency medicine toward NSAID-first approaches in appropriate candidates.
- Inflammation:Postoperative ocular inflammation following cataract extraction, where topical NSAID drops reduce macular edema incidence. Ophthalmology-specific protocols support premium pricing within this indication.
- Migraine:Severe headache presentations in emergency settings where rapid onset parenteral or intranasal delivery offers advantages over oral triptans. This indication remains underpenetrated relative to established migraine therapeutics.
Postoperative pain leads indication volumes today; migraine is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands higher ketorolac procurement volumes than Germany, though India's export-oriented manufacturing base supplies active pharmaceutical ingredients to both markets. Hospital consolidation and opioid prescribing restrictions drive divergent demand patterns across these three economies.
United States
Ambulatory surgical centers in Florida and Texas are expanding same-day discharge protocols for orthopedic procedures, driving perioperative NSAID consumption. FDA bioequivalence standards for parenteral generics filter subscale producers from hospital formulary eligibility. Fresenius Kabi leverages vertically integrated manufacturing to secure sole-source contracts with consolidated group purchasing organizations in the Midwest and Southeast.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia prioritize multimodal analgesia within enhanced recovery after surgery frameworks. EMA pharmacovigilance requirements for NSAID cardiovascular risk labeling shape prescribing guidelines issued by the country's national pharmaceutical regulator. Stuttgart-based hospital networks are standardizing prefilled syringe formats to reduce compounding labor in centralized pharmacy operations.
India
Domestic cataract surgery volume in Maharashtra and Tamil Nadu supports ophthalmic solution demand alongside export manufacturing. CDSCO manufacturing incentives under the Production Linked Incentive scheme subsidize sterile injectable capacity expansion in Hyderabad and Ahmedabad. Gland Pharma Limited and Cadila Healthcare Limited anchor output from these clusters for North American and European contract supply.
China
Renal colic and trauma presentations in Shanghai and Beijing emergency departments sustain parenteral NSAID utilization. NMPA quality consistency evaluation requirements for generic injectables elevate compliance costs for domestic manufacturers. Yangtze River Delta pharmaceutical zones are consolidating sterile processing infrastructure to meet dual carbon goals while maintaining export competitiveness.
Japan
Postoperative pain protocols in Kanto region university hospitals favor opioid-sparing regimens for aging surgical populations. PMDA post-marketing surveillance requirements for NSAID gastrointestinal bleeding risk influence formulary placement decisions. Osaka-based generic specialists are licensing parenteral manufacturing technology to compete for hospital procurement contracts.
Ketorolac Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across ketorolac supply tiers, creating a bifurcated structure where manufacturing scale and regulatory dossier depth determine contract eligibility. Hospital procurement consolidation favors suppliers with captive active pharmaceutical ingredient production and multi-site sterile processing redundancy. Three archetypes dominate: vertically integrated hospital suppliers, high-volume generic exporters, and originator brand holders with legacy formulary relationships. Competitive positioning hinges on backward integration into API supply and strategic partnerships with group purchasing organizations.
Among vertically integrated hospital suppliers, Fresenius Kabi exemplifies the archetype through European manufacturing footprints and US distribution infrastructure. Dr. Reddy's Laboratories and Gland Pharma Limited occupy positions within the high-volume generic exporter tier, leveraging Indian manufacturing clusters for cost-competitive parenteral output. Pfizer represents the originator brand holder archetype, sustaining hospital formulary access through decades of perioperative protocol integration. These three anchors illustrate how regulatory compliance scale and geographic manufacturing distribution determine contract capture in consolidated procurement environments.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Dr. Reddy's Laboratories |
| Pfizer |
| West Ward Pharmaceuticals |
| Gland Pharma Limited |
| Allergan |
| Teva Pharmaceuticals |
| Cadila Healthcare Limited |
| Omeros Corporation |
| Others |
Value Chain & Pricing Dynamics
API procurement costs for ketorolac tromethamine flow from Indian and Chinese chemical manufacturers through sterile formulation processors to hospital group purchasing organizations, with each transfer point layering compliance premiums that stratify final contract values across premium, standard, and economy tiers.
Pricing Analysis
Capacity additions in India under CDSCO's Production Linked Incentive scheme are reshaping price floors for injectable ketorolac exports. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved sterile processors from emerging WHO-GMP certified suppliers and basic export-grade manufacturers. Cost compression in the economy tier is intensifying because European hospital networks are consolidating procurement through sole-source agreements. Group purchasing organizations demonstrate highest price sensitivity, while academic medical centers with embedded pharmacy operations retain brand preference for originator heritage products.
Supply Chain Analysis
Single-source vulnerability sits with pyrrole derivative intermediates concentrated among specialty chemical manufacturers in the Yangtze River Delta. Finished dosage form production draws from India, China, and the United States, with sterile injectable capacity resting on specialized aseptic processing infrastructure. Tariff exposure on API imports into North American markets elevates landed costs for non-vertically integrated formulators. Distribution runs through hospital group purchasing organization contracts and regional wholesale distributors serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ketorolac market compounds steadily as surgical volume expansion and opioid substitution protocols create durable demand for non-narcotic perioperative analgesia.
For Market Incumbents: Deepen backward integration into pyrrole derivative supply through captive chemical synthesis or long-term offtake agreements with Yangtze River Delta intermediates manufacturers. Expand sterile processing redundancy across multiple FDA-inspected sites to defend against quality enforcement actions that could trigger formulary exclusion. Reinforce GPO contract tenure by embedding prefilled syringe formats into anesthesia workflow protocols that raise switching costs. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with established CDSCO-registered sterile processors to bypass capital-intensive aseptic infrastructure buildout. Target the nasal spray migraine indication segment where bioequivalence pathways remain less crowded than injectable generics. Pursue emergency department formulary access through headache specialist advocacy rather than broad hospital system contracting. For Investors and Strategic Acquirers: Consolidation pressure builds where subscale injectable specialists face FDA bioequivalence study cost burdens that exceed their revenue base. The 5-to-10 year viability window favors manufacturers with captive API supply and multi-site sterile redundancy. Target acquisition archetype: Indian CDSCO-registered injectable specialists with established US distribution relationships and pending FDA facility inspections. Monitor FDA complex generic guidance publication timing as inflection indicator for regulatory cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Supply | Captive pyrrole derivative production insulates against Yangtze River Delta export restriction risk. |
| Prefilled Syringe Format Conversion | Ready-to-use presentations reduce hospital pharmacy compounding labor and medication error liability. |
| Nasal Spray Migraine Development | Intranasal delivery bypasses crowded injectable generic competition for emergency department headache protocols. |
| Multi-Site Sterile Redundancy | FDA-inspected facility diversification protects against quality enforcement-driven supply interruption. |
| GPO Sole-Source Contracting | Three-to-five year exclusive supply agreements lock out competitors from consolidated hospital procurement. |
Study Parameters
Coverage spans the United States, Germany, India, China, and Japan, with primary inputs from each market combining executive interviews with sterile manufacturing specialists and secondary validation through regulatory filings. Drug development executives, regulatory affairs leads, hospital formulary directors, GPO contracts managers, and CDSCO manufacturing inspectors contributed primary perspective. FDA approval databases, EMA assessment reports, ClinicalTrials.gov entries, CDSCO manufacturing inspection records, and USP monograph revision histories anchored secondary triangulation. Bottom-up volume modeling across dosage forms and administration routes cross-checked against top-down market sizing from trade flow analysis.
Rate-of-change decomposition across the analysis window isolates volume drivers from pricing dynamics and mix shifts between dosage forms. Segmentation dimensions modeled include treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for policy intervention effects. Forecast inputs incorporated ambulatory surgical center expansion trajectories, DEA opioid prescribing restriction enforcement intensity, and FDA complex generic guidance implementation timing.
Several conditions sit outside the modeled scope, including novel molecular entity competition in acute pain, biosimilar substitution for perioperative analgesia, and pandemic-driven surgical volume disruption. Forecasts reflect documented assumptions about regulatory pathway stability and hospital consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Heat Therapy Market
Pain Management
Dyspareunia Market
Pain Management
Neuralgia Treatment Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Painkillers Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Pain Patches Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Arthralgia Management Market
Pain Management
Pain Relief Oil Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Opioid Withdrawal Management Market