
 Acetaminophen Injection Market | 2026-2036
Acetaminophen Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Acetaminophen Injection Market Insights
Lyophilization and aseptic fill-finish technology is fragmenting manufacturing footprints across the injectable acetaminophen supply base, pushing producers toward modular bioprocessing suites and isolator-based production lines. Mallinckrodt Pharmaceuticals anchors North American supply through captive API-to-dosage verticality. Fresenius Kabi AG leverages European hospital channel dominance to sustain premixed bag volumes. Baxter International Inc. competes on integrated delivery systems that pair drug with infusion hardware.
Acetaminophen injection delivers the analgesic and antipyretic agent N-acetyl-p-aminophenol directly into systemic circulation via sterile parenteral formulation, typically dosed at 1,000 mg per 100 mL solution for adult intravenous administration over 15 minutes. The compound functions as a perioperative opioid adjunct or substitute in multimodal analgesia protocols across surgical, emergency, and critical care settings. Solution and premixed bag formats lead volume owing to nursing workflow efficiency and reduced compounding error risk, while concentrate vials retain share in cost-sensitive institutional settings where pharmacy dilution controls unit economics. Intravenous administration dominates route-based segmentation due to immediate bioavailability requirements in acute pain episodes, though subcutaneous delivery is gaining protocol inclusion for step-down transitions in homecare environments.
The US FDA enforces current Good Manufacturing Practice (cGMP) standards for sterile injectables through facility inspections and warning letter escalation, directly constraining batch release velocity for non-compliant manufacturers. The European Medicines Agency (EMA) applies Annex 1 revision requirements for contamination control strategy documentation, elevating capital barriers for firms serving EU hospital tenders. Stakeholders must monitor regulatory divergence between FDA and EMA aseptic processing expectations when configuring multi-jurisdictional manufacturing assets and quality management systems.
Market Dynamics
The FDA's opioid-sparing mandate is restructuring perioperative anesthesia workflows, forcing hospital formularies to substitute intravenous acetaminophen for traditional narcotic protocols and rewiring procurement priorities across acute care networks.
Growth Catalysts
- Enhanced Recovery After Surgery (ERAS) protocols:Multimodal analgesia guidelines from the American Society of Anesthesiologists embed non-opioid IV agents as standard of care, expanding institutional purchasing volume.
- US FDA REMS restrictions on opioids:Risk evaluation and mitigation strategies tighten prescribing limits, redirecting hospital pharmacy budgets toward parenteral acetaminophen as a compliant substitute.
- Critical care sedation minimization:ICU delirium reduction initiatives favor opioid-sparing pain management, driving continuous infusion demand in mechanically ventilated patient populations.
Market Restraints
- API supply concentration in India and China:N-acetyl-p-aminophenol active pharmaceutical ingredient production clusters in Asian chemical manufacturing hubs, exposing finished dose manufacturers to geopolitical disruption and customs delay risk.
- EMA Annex 1 revision compliance costs:Contamination control strategy documentation requirements for sterile injectables elevate capital expenditure barriers for European market entry, constraining new supplier participation.
- Oral acetaminophen substitution in step-down care:Bioequivalent tablet and liquid formulations capture post-discharge analgesia demand, limiting injectable volume to acute inpatient windows.
Strategic Opportunities
- Ambulatory surgery center expansion:Freestanding ASCs in the United States adopt same-day discharge protocols requiring rapid-onset, short-duration analgesics without opioid recovery complications.
- Home infusion therapy reimbursement:Medicare and commercial payer coverage expansion for subcutaneous acetaminophen administration enables post-acute care market penetration beyond hospital walls.
- WHO Essential Medicines List inclusion:Parenteral acetaminophen designation as a priority analgesic for low-resource surgical programs opens procurement channels through international health agency tenders.
Industry Challenges
- Aseptic processing workforce scarcity:Qualified personnel for isolator-based fill-finish operations remain concentrated among legacy sterile injectable manufacturers, constraining capacity expansion timelines.
- Lyophilization cycle validation complexity:Freeze-dried formulation development requires extended stability testing protocols, compressing product launch windows against patent cliff pressures.
- Legacy ERP integration with track-and-trace systems:DSCSA compliance deadlines force serialization infrastructure upgrades incompatible with aging hospital pharmacy inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetaminophen Injection Market |
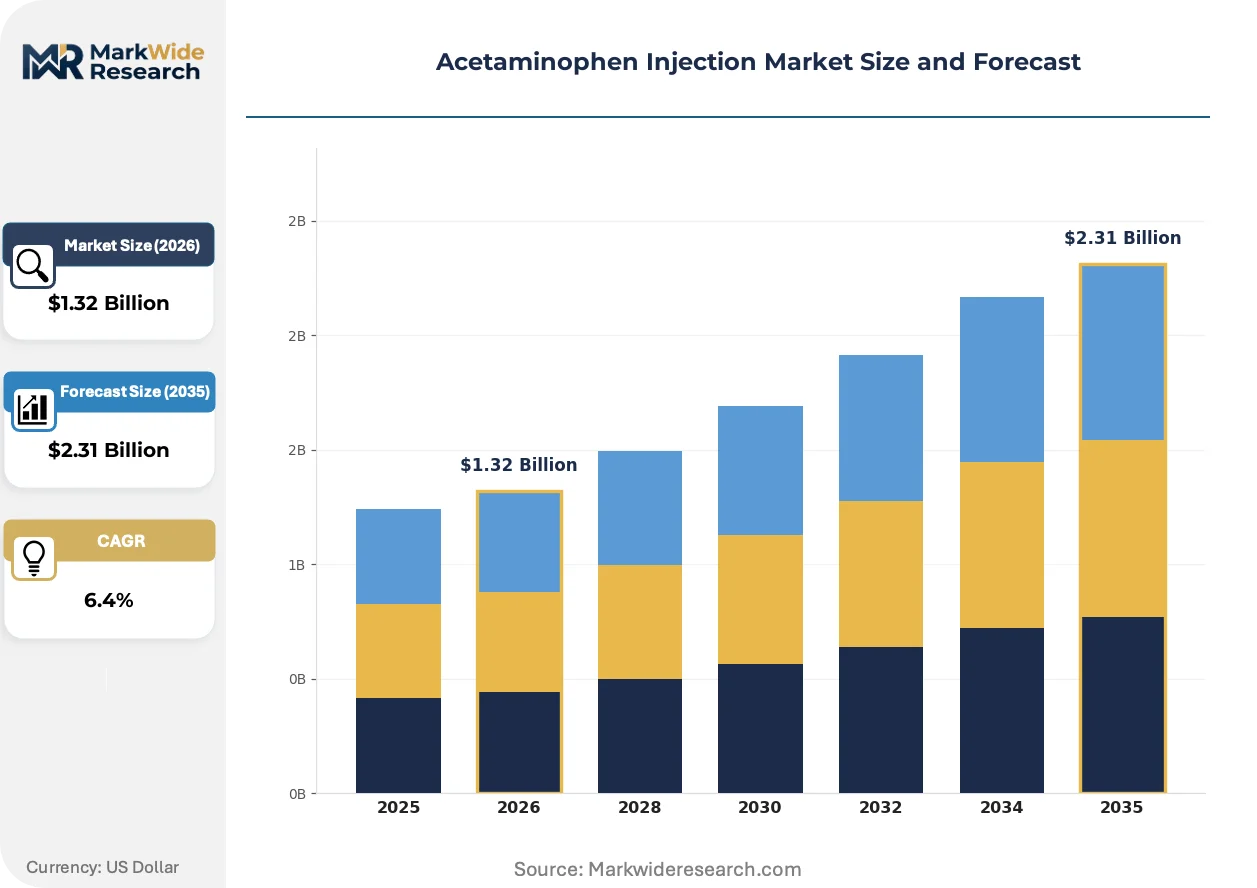
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solution, Concentrate, Premixed Bags, Vials End User: Hospitals, Clinics, Homecare, Pharmacies Route of Administration: Intravenous, Intramuscular, Subcutaneous, Epidural Packaging Type: Single Dose, Multi Dose, Glass Bottles, Plastic Containers |
| Companies Covered | Mallinckrodt Pharmaceuticals, B. Braun Melsungen, Fresenius Kabi AG, Baxter International Inc., Cipla Inc., Lupin, Sun Pharmaceutical Industries, Aurobindo Pharma, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetaminophen Injection Market Trends and Innovations
Manufacturing technology convergence and regulatory documentation requirements are compressing batch release timelines while expanding the addressable patient population beyond traditional surgical wards into ambulatory and home settings.
Closed-system transfer devices and needle-free connectors are hybridizing medication delivery safety engineering with parenteral acetaminophen administration. Hospital infection control committees mandate these interfaces for hazardous drug handling, extending their adoption to all IV analgesics. Device-agnostic drug vial designs are compressing supplier lock-in and enabling pharmacy flexibility across competing hardware platforms.
EMA's Annex 1 revision on sterile medicinal products mandates quality risk management documentation for contamination control strategies. European manufacturers face facility requalification timelines stretching 18-24 months for legacy cleanroom suites. German and French hospital tenders now require supplier evidence of isolator-based production, filtering contract awards toward capital-intensive operators.
Hospital pharmacy consolidation into centralized service centers is compressing purchasing autonomy at individual facilities. Multi-hospital health systems negotiate enterprise-wide analgesia contracts, displacing fragmented SKU procurement. United States integrated delivery networks in Texas and Florida lead this concentration, driving volume commitments that favor premixed bag formats over pharmacy-compounded alternatives.
Acetaminophen Injection Market Segmentation
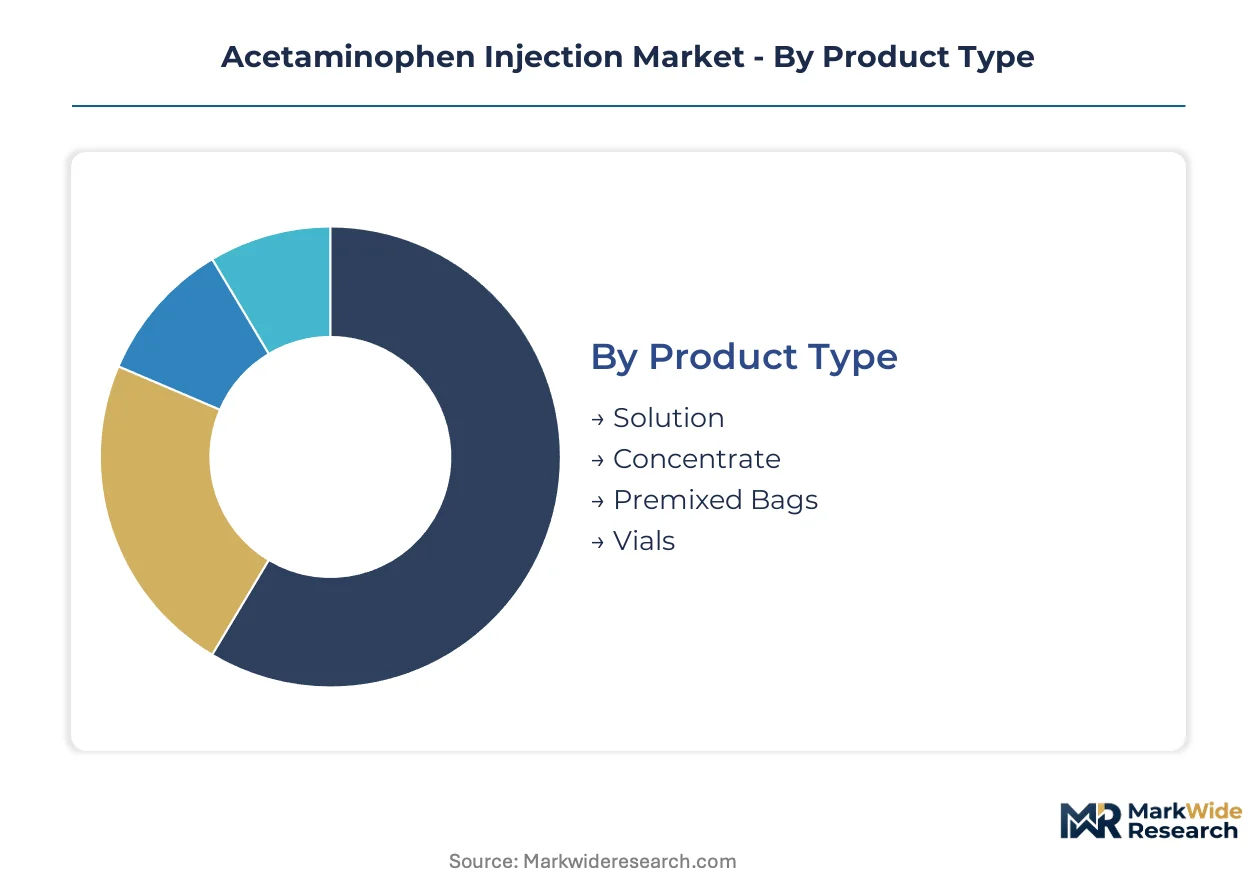
Injectable acetaminophen procurement varies sharply across clinical settings and administration workflows. Product format, delivery route, and packaging configuration each impose distinct regulatory, operational, and reimbursement constraints that reshape supplier positioning.
Product Type:
Cost tier differentiation separates pharmacy-compounded formats from ready-to-administer systems with embedded nursing labor savings.
- Solution:Liquid formulation in vials or bags requires pharmacy dilution before patient administration. Hospital systems in Texas and Florida favor this format for formulary flexibility and per-dose cost control in high-volume surgical centers.
- Premixed Bags:Factory-prepared 1,000 mg per 100 mL units eliminate compounding steps and reduce medication error risk. United States integrated delivery networks specify these for ERAS protocol compliance and anesthesia workflow standardization.
- Concentrate:High-potency vials demand precise dilution protocols suited to institutional settings with dedicated pharmacy infrastructure.
- Vials:Glass or plastic primary containers support both single and multi-dose extraction patterns across varied clinical environments.
Premixed bags command the established base. The steepest expansion runs through solution formats in cost-sensitive health systems.
End User:
Customer type determines reimbursement pathway, purchase autonomy, and formulary control intensity.
- Hospitals:Tertiary acute care facilities with centralized pharmacy operations and opioid-sparing mandates drive bulk procurement through GPO contracts. FDA REMS restrictions on perioperative narcotics redirect anesthesia budgets toward IV acetaminophen in surgical wards across the United States.
- Homecare:Subcutaneous administration protocols enable post-acute pain management outside institutional walls. Medicare reimbursement expansion for home infusion services opens this channel for step-down surgical patients in Florida and California markets.
- Clinics:Ambulatory settings with limited pharmacy infrastructure favor prefilled formats and rapid-turnover inventory models.
- Pharmacies:Retail and specialty dispensaries handle limited injectable volumes under prescriber-specific protocols and cold-chain requirements.
Hospitals anchor volume concentration. Homecare represents the fastest-growing trajectory as reimbursement shifts toward site-neutral payment models.
Route of Administration:
Application urgency and bioavailability requirements segment delivery methods across acute versus transitional care settings.
- Intravenous:Direct systemic circulation achieves peak plasma concentration within 15 minutes, mandatory for perioperative multimodal analgesia in United States tertiary surgical centers. Immediate bioavailability satisfies ERAS protocol timelines and PACU discharge targets.
- Subcutaneous:Slower absorption profile suits step-down transitions where oral intake remains compromised. Home health agencies in Texas deploy this route for post-discharge pain management under remote nursing supervision.
- Intramuscular:Alternative parenteral access when vascular placement is contraindicated or unavailable in emergency settings.
- Epidural:Regional delivery for targeted anesthesia augmentation in select obstetric and orthopedic procedures.
Intravenous administration holds dominant share. Subcutaneous delivery is climbing the fastest as home infusion capabilities mature.
Packaging Type:
Volume scale and contamination risk tolerance differentiate single-patient units from multi-extract systems.
- Single Dose:Unit-of-use packaging eliminates microbial contamination risk between administrations. United States hospital infection control committees mandate these formats for all IV analgesics in immunocompromised patient populations.
- Multi Dose:Preservative-containing vials support repeated extraction for cost-efficient pharmacy operations in high-throughput surgical centers with controlled compounding environments.
- Glass Bottles:Inert primary barrier material preferred for stability-sensitive formulations and extended shelf-life requirements.
- Plastic Containers:Polymer-based systems reduce breakage risk and enable flexible storage configurations in space-constrained clinical areas.
Single dose formats dominate infection-controlled environments. Multi dose packaging is gaining share fastest in ambulatory surgery centers prioritizing cost per procedure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for acetaminophen injection reveal a structural deficit in finished sterile formulations across Western markets, with API surplus concentrated in Asian chemical manufacturing hubs. Finished dose manufacturers in North America and Europe rely on imported N-acetyl-p-aminophenol from India and China, creating customs exposure and geopolitical vulnerability. Hospital procurement networks in developed markets prioritize domestic fill-finish capacity to reduce supply chain latency.
United States
Perioperative opioid-sparing mandates from the FDA REMS program redirect hospital anesthesia budgets toward intravenous acetaminophen in tertiary surgical centers across Texas and Florida. Integrated delivery networks negotiate enterprise-wide contracts favoring premixed bag formats for ERAS protocol compliance. Mallinckrodt Pharmaceuticals maintains vertical API-to-dosage production in Missouri, insulating domestic supply from import disruption.
Germany
Fresenius Kabi AG leverages hospital channel dominance across Bavaria and North Rhine-Westphalia to sustain premixed bag volumes in European acute care networks. The EMA Annex 1 revision on contamination control strategies forces facility requalification timelines of 18-24 months for legacy cleanroom operations. German hospital tenders now mandate isolator-based production evidence, filtering contract awards toward capital-intensive operators with modular bioprocessing suites.
India
API manufacturing clusters in Gujarat and Maharashtra supply N-acetyl-p-aminophenol to global finished dose producers, though domestic injectable formulation capacity remains underdeveloped relative to tablet exports. The CDSCO enforces Schedule M compliance for sterile injectable facilities, constraining batch release velocity for non-compliant manufacturers. Cipla, Lupin, and Sun Pharmaceutical anchor injectable development in Mumbai and Hyderabad, targeting regulated market filings.
China
NMPA oversight of sterile injectable manufacturing intensifies facility inspection frequency, elevating compliance costs for domestic producers serving hospital procurement tenders. The Yangtze River Delta concentration of chemical API synthesis supports global acetaminophen raw material demand, though finished dose lyophilization capacity concentrates in Shandong and Jiangsu provinces. Export-oriented manufacturers face dual carbon goals pressure to reduce energy-intensive lyophilization cycle footprints.
Japan
PMDA quality standards for parenteral formulations sustain premium pricing for domestic hospital procurement, limiting import penetration from lower-cost Asian suppliers. The Kanto region around Tokyo concentrates sterile injectable manufacturing for acute care networks implementing multimodal analgesia protocols. METI industrial policy supports advanced aseptic processing technology adoption to maintain competitiveness against Korean and Taiwanese contract manufacturers.
Acetaminophen Injection Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: captive API-to-dosage vertically integrated operators, European hospital channel specialists with premixed format dominance, and integrated delivery system vendors pairing drug with infusion hardware. Competitive intensity centers on isolator-based production qualification speed and ERAS protocol formulary inclusion. Dominant moves include capacity expansion into modular bioprocessing suites and strategic partnerships with ambulatory surgery center networks.
Within the vertically integrated tier, Mallinckrodt Pharmaceuticals represents North American supply security through captive manufacturing. Fresenius Kabi AG and Baxter International Inc. occupy positions at the format-specialist and delivery-system integration vectors respectively, with the former exemplifying European hospital channel concentration and the latter representing hardware-agnostic drug design approaches.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| B. Braun Melsungen |
| Fresenius Kabi AG |
| Baxter International Inc. |
| Cipla Inc. |
| Lupin |
| Sun Pharmaceutical Industries |
| Aurobindo Pharma |
| Pfizer Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European isolator-based fill-finish capacity is tightening supplier pricing power for sterile injectable acetaminophen, pushing hospital procurement toward multi-year offtake commitments that lock in volume discounts against supply security premiums.
Pricing Analysis
Hospital systems anchor pricing structure through formulary tier contracts that stratify across premixed bag, solution vial, and concentrate formats. Price differentiation hinges on nursing labor savings certification and GPO-negotiated volume tiers, with FDA REMS-driven opioid substitution intensifying cost compression in the standard-solution segment. Cost-sensitive integrated delivery networks in Texas and Florida exhibit highest price sensitivity, while tertiary surgical centers prioritize infection-control premium formats regardless of unit cost.
Supply Chain Analysis
Export-control scrutiny on advanced aseptic processing equipment limits technology transfer to Indian and Chinese API manufacturers, concentrating finished dose lyophilization capacity in Germany, the United States, and Japan. N-acetyl-p-aminophenol raw material feeds from Gujarat and Maharashtra chemical clusters, with Shandong province providing secondary API volumes. Single-source vulnerability runs through the Yangtze River Delta for sterile packaging components. Distribution runs through hospital GPO contracts and ASC direct purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acetaminophen injection market functions as a service-attach opportunity where closed-system transfer device compatibility consulting and pharmacy workflow optimization generate recurring revenue expanding faster than commodity drug sales.
For Market Incumbents: Harden formulary position through backward integration into captive API production, insulating against Indian and Chinese supply disruption. Lock in multi-year ERAS protocol sponsorships with United States integrated delivery networks before EMA Annex 1 compliance costs filter new competitors from European tenders. Isolator-based production qualification speed is the critical defensive lever.
For New Entrants and Emerging Players: Build out ambulatory surgery center channel presence in Florida and Texas, where same-day discharge protocols create demand for rapid-onset analgesics without pharmacy infrastructure. Home infusion therapy reimbursement expansion in California offers the most penetrable white-space target. Lead with subcutaneous administration training services as the differentiated go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across isolator-based sterile injectable manufacturing, favoring asset-heavy operators with existing EMA qualification documentation. Long-term viability across the analysis window rests on regulatory compliance infrastructure rather than molecule differentiation. Target acquisition archetype: European hospital channel specialists with premixed bag format dominance and existing Fresenius Kabi-tier GPO relationships. Watch for FDA warning letter escalation against Indian API suppliers as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Production Qualification | EMA Annex 1 revision mandates contamination control documentation, filtering contract awards toward capital-intensive operators with modular suites. |
| ERAS Protocol Sponsorship | American Society of Anesthesiologists guideline embedding creates formulary lock-in across United States tertiary surgical centers. |
| Captive API Integration | Mallinckrodt's Missouri verticality insulates domestic supply from Indian and Chinese customs disruption exposure. |
| Home Infusion Reimbursement Strategy | Medicare site-neutral payment expansion enables subcutaneous acetaminophen penetration beyond hospital walls into Texas home health markets. |
| Closed-System Device Compatibility | Needle-free connector hybridization with drug vial design reduces pharmacy lock-in and enables hardware-agnostic formulary inclusion. |
Research Methodology
Desk research of FDA warning letters, EMA inspection databases, and hospital GPO contract filings preceded structured interviews with anesthesia department chairs, hospital pharmacy directors, sterile manufacturing quality leads, and ambulatory surgery center administrators. Secondary triangulation drew from CDSCO facility inspection records, United States customs import data for N-acetyl-p-aminophenol, and Medicare reimbursement code analysis. Bottom-up volume modeling across dosage formats and administration routes converged with top-down expenditure tracking through integrated delivery network procurement disclosures.
Assumptions held fixed include FDA REMS enforcement intensity on perioperative opioids and EMA Annex 1 facility requalification timelines stretching 18-24 months for legacy cleanroom operations. Variables tested across the projection horizon encompass home infusion reimbursement expansion velocity, ambulatory surgery center same-day discharge protocol adoption, and WHO Essential Medicines List procurement channel development. CAGR derivation applied segment-level volume elasticity to anesthesia workflow substitution rates, with lyophilization cycle validation timelines and aseptic processing workforce scarcity as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian or Chinese finished dose manufacturers would shift outcomes beyond modeled ranges. Material shifts in FDA opioid-sparing mandate enforcement intensity or EMA contamination control strategy documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market