
 Provoked Vestibulodynia Treatment Market | 2026-2036
Provoked Vestibulodynia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Provoked Vestibulodynia Treatment Market Analytics
Topical lidocaine formulations are restructuring first-line treatment economics by displacing systemic analgesics in mild-to-moderate cases. Johnson & Johnson Services Inc leverages its dermatology heritage to sustain shelf presence in institutional formularies. Pfizer Inc competes through neuropathic pain R&D pipelines that extend into off-label vestibulodynia applications. Eli Lilly and Company anchors its position via CNS-focused development channels that navigate chronic pain regulatory pathways.
Provoked vestibulodynia denotes localized vulvar pain triggered by touch or pressure, characterized by allodynia and hyperalgesia at the vulvar vestibule with onset typically following hormonal shifts, infection, or trauma. The condition primarily serves gynecological and sexual medicine by requiring coordinated neuromodulatory, musculoskeletal, and psychological intervention. Pharmacotherapy dominates current revenue flows due to established reimbursement for oral and topical agents, while physical therapy represents the fastest-expanding segment as pelvic floor specialization spreads through private clinics. Intravaginal delivery modes capture concentrated margin pools where compounding pharmacies control customized formulations.
The FDA shapes demand through its chronic pain clinical trial guidance, while HIPAA frameworks constrain how digital therapeutics collect pelvic health data. The EU MDR and national health technology assessment bodies in France and Germany determine market access for novel vulvodynia devices and biologics. Stakeholders must monitor how pelvic floor physical therapy gains recognition as a billable specialty service across divergent payer systems.
Market Dynamics
Pelvic floor physical therapy is absorbing market share from pharmacotherapy as specialized clinics in Germany, the United States, and France secure reimbursement codes that elevate musculoskeletal intervention to parity with drug-based protocols.
Growth Catalysts
- FDA Chronic Pain Guidance:The FDA's evolving framework for chronic pain drug development is expanding acceptable clinical trial endpoints for vulvodynia therapeutics, enabling broader label indications for neuropathic pain agents.
- Germany's Specialized Centers:Concentrated investment in vulvar pain centers across Berlin, Munich, and Hamburg is integrating physical therapy with pharmacotherapy, creating reproducible care models for export.
- Compounding Pharmacy Networks:Intravaginal formulation customization is capturing margin pools through localized production of lidocaine-based preparations tailored to patient-specific vestibular sensitivity profiles.
Market Restraints
- Reimbursement Fragmentation:Divergent payer recognition of pelvic floor physical therapy as a billable specialty service creates geographic access inequities, particularly in Medicaid-managed care plans.
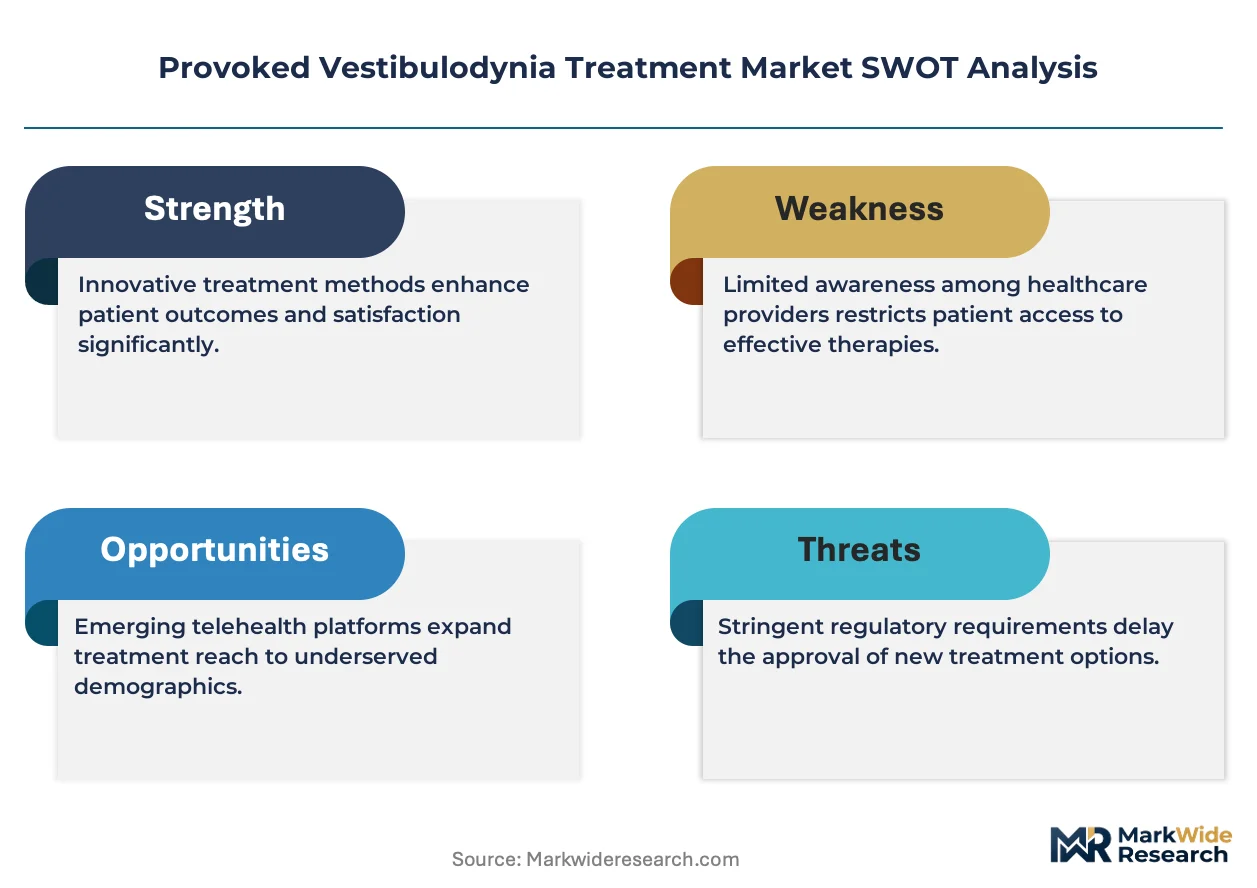
- Diagnostic Delay Cycles:Average time from symptom onset to provoked vestibulodynia diagnosis exceeds 24 months in most health systems, compressing addressable patient pools and treatment initiation rates.
- Topical Formulation Limitations:Mucosal absorption variability and vestibular tissue sensitivity restrict effective drug concentrations for lidocaine and capsaicin preparations, limiting efficacy in moderate-to-severe presentations.
Strategic Opportunities
- Digital Therapeutic Integration:HIPAA-compliant pelvic health platforms are enabling remote monitoring of dilator compliance and pain journaling, extending clinic reach beyond metropolitan catchment areas.
- EU MDR Device Pathways:The Medical Device Regulation's enhanced clinical evidence requirements for vulvodynia neuromodulation devices are creating first-mover advantages for manufacturers with robust pelvic pain trial data.
- Multimodal Protocol Export:United States gynecology clinic networks are licensing their integrated physical therapy-pharmacotherapy-psychology protocols to health systems in Australia and Canada.
Industry Challenges
- Pelvic Floor Specialist Scarcity:Board-certified women's health physical therapists remain concentrated in urban academic medical centers, constraining protocol rollout to community-based gynecology practices.
- Patient-Reported Outcome Standardization:Absence of validated, regulatory-accepted endpoints for vestibular pain severity is complicating cross-trial comparison and payer evidence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Provoked Vestibulodynia Treatment Market |
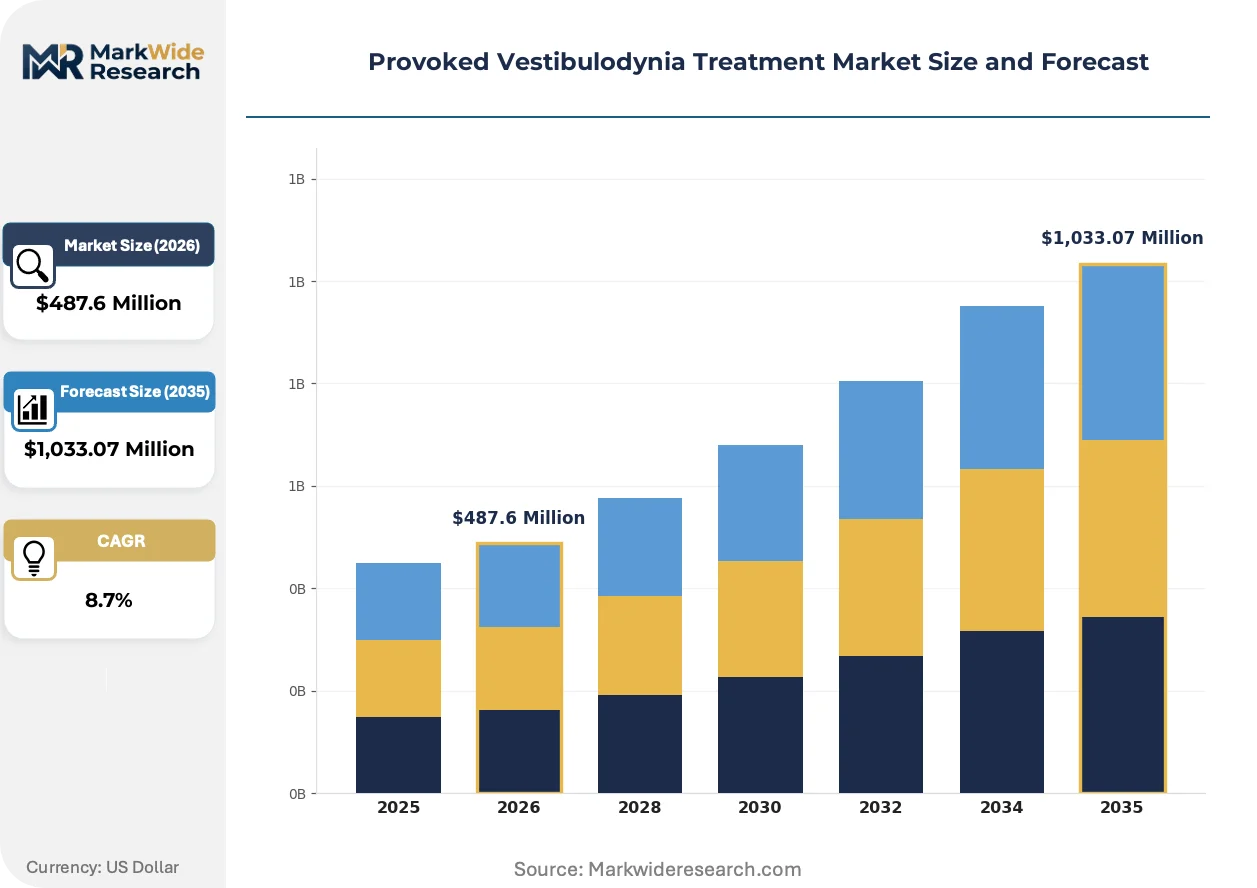
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Cognitive Behavioral Therapy, Physical Therapy, Pharmacotherapy, Surgical Intervention Delivery Mode: Oral, Topical, Injectable, Intravaginal Age Group: Adolescents, Adults, Seniors, Women End User: Private Clinics, Hospitals, Home Care, Research Institutions |
| Companies Covered | Mycovia Pharmaceuticals Inc, Johnson & Johnson Services Inc, GlaxoSmithKline plc, Scynexis Inc, Allergan plc, AstraZeneca plc, Pfizer Inc, Sanofi, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Provoked Vestibulodynia Treatment Market Evolving Landscape
Neuromodulatory device development and digital pelvic health platforms are converging to displace reliance on systemic analgesics, while regulatory pressure for sex-specific pain trial data is reshaping clinical development economics.
Low-level laser therapy devices targeting vulvar vestibular tissue are absorbing capital allocation from pharmaceutical R&D programs as gynecology clinics in the United States and Germany adopt photobiomodulation for recalcitrant allodynia cases. Academic medical centers in Boston and Heidelberg are publishing outcomes data that supports device procurement committee approvals. This technology is absorbing market positioning previously held by compounded topical anesthetics in moderate-to-severe patient segments.
The EU MDR's strengthened clinical evidence requirements for vulvodynia treatment devices are extending time-to-market for novel neuromodulation systems by 18-36 months. Manufacturers must now submit pelvic floor-specific safety data rather than relying on generalized pain device predicates. French and German notified bodies are applying divergent interpretation standards, forcing parallel regulatory strategies for market access.
Subscription-based pelvic health platforms are replacing episodic clinic visits as the primary touchpoint for dilator therapy compliance monitoring and pain tracking. These digital channels are disintermediating traditional pharmacy dispensing for topical agents by integrating e-prescription workflows. The model is concentrating uptake among commercially insured populations in California and Texas where employer wellness programs subsidize access.
Provoked Vestibulodynia Treatment Market Segmentation
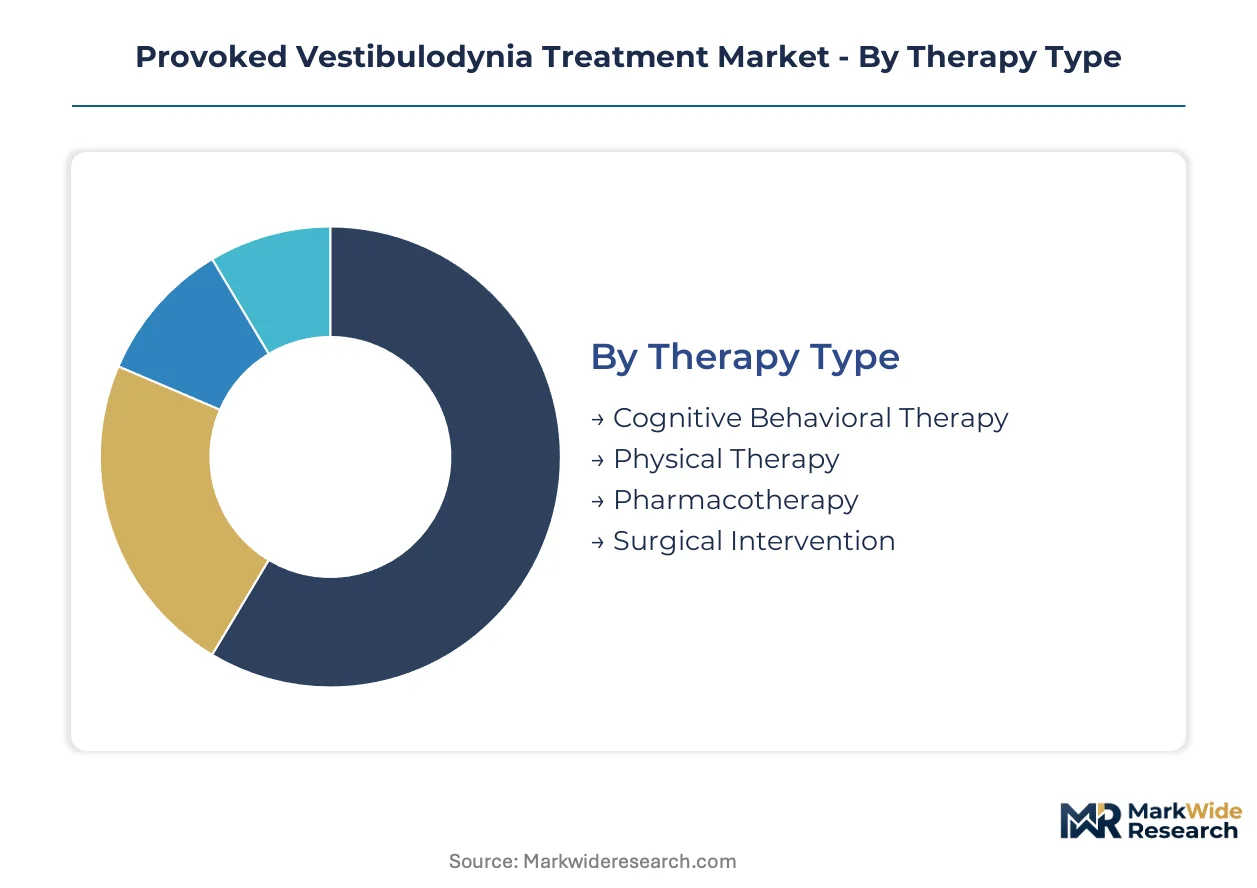
Segmentation in provoked vestibulodynia treatment reveals how reimbursement patterns and clinical specialization fragment demand across delivery modes and care settings. Understanding these divisions exposes where capital concentrates and where protocol standardization remains weakest.
Therapy Type:
Cost tier separates patients seeking first-line intervention from those requiring escalated multimodal care.
- Pharmacotherapy:Oral and topical agents dominate revenue flows through established insurance codes for neuropathic pain and compounded lidocaine formulations. Demand concentrates in United States gynecology clinics where formulary access for pregabalin and duloxetine remains broad, though FDA chronic pain guidance is tightening evidentiary requirements for new molecular entities.
- Physical Therapy:Pelvic floor specialization is displacing drug-first protocols in Germany and select United States metropolitan markets where reimbursement parity with pharmacotherapy has been secured. Berlin and Munich pain centers report highest utilization rates among privately insured populations seeking non-systemic alternatives.
- Cognitive Behavioral Therapy:Psychosexual intervention addresses pain catastrophization and penetration anxiety through licensed therapists in academic medical center networks.
- Surgical Intervention:Vestibulectomy remains reserved for refractory cases with localized provoked pain unresponsive to conservative measures.
Volume sits with Pharmacotherapy; growth tilts toward Physical Therapy.
Delivery Mode:
Application context determines whether patients receive care in supervised clinical settings or manage treatment autonomously.
- Topical:Lidocaine-based preparations applied to vulvar vestibule offer localized anesthesia with minimal systemic absorption. Compounding pharmacies in California and Texas control margin pools through customized concentration adjustments for vestibular sensitivity profiles.
- Intravaginal:Suppositories and compounded creams deliver agents directly to posterior vestibular tissue, capturing concentrated margins where pharmacy networks bypass traditional retail dispensing.
- Oral:Systemic neuropathic pain agents require psychiatric or pain medicine co-management in most United States health plans.
- Injectable:Botulinum toxin and trigger point interventions remain confined to specialized vulvar pain centers with procedural reimbursement expertise.
Margins concentrate in Intravaginal compounding; patient preference is shifting fastest toward Topical self-administration.
Age Group:
Hormonal life stage dictates both symptom etiology and treatment modality suitability.
- Adults:Premenopausal women between 20 and 45 years constitute the core addressable population, with onset frequently following oral contraceptive initiation, infection, or childbirth trauma. Demand clusters in reproductive medicine and sexual health clinics across France and Germany.
- Adolescents:Pediatric gynecology services in Boston and Toronto academic centers are developing age-appropriate dilator protocols and cognitive behavioral interventions for primary provoked vestibulodynia.
- Seniors:Genitourinary syndrome of menopause overlaps with vestibular atrophy, complicating differential diagnosis in postmenopausal populations.
- Women:This designation captures pregnancy-related and lactation-associated presentations requiring modified pharmacologic safety profiles.
Patient volume centers on Adults; protocol development investment is accelerating fastest for Adolescents.
End User:
Supply concentration varies sharply between institutional purchasers with formulary committees and dispersed private practice decision-makers.
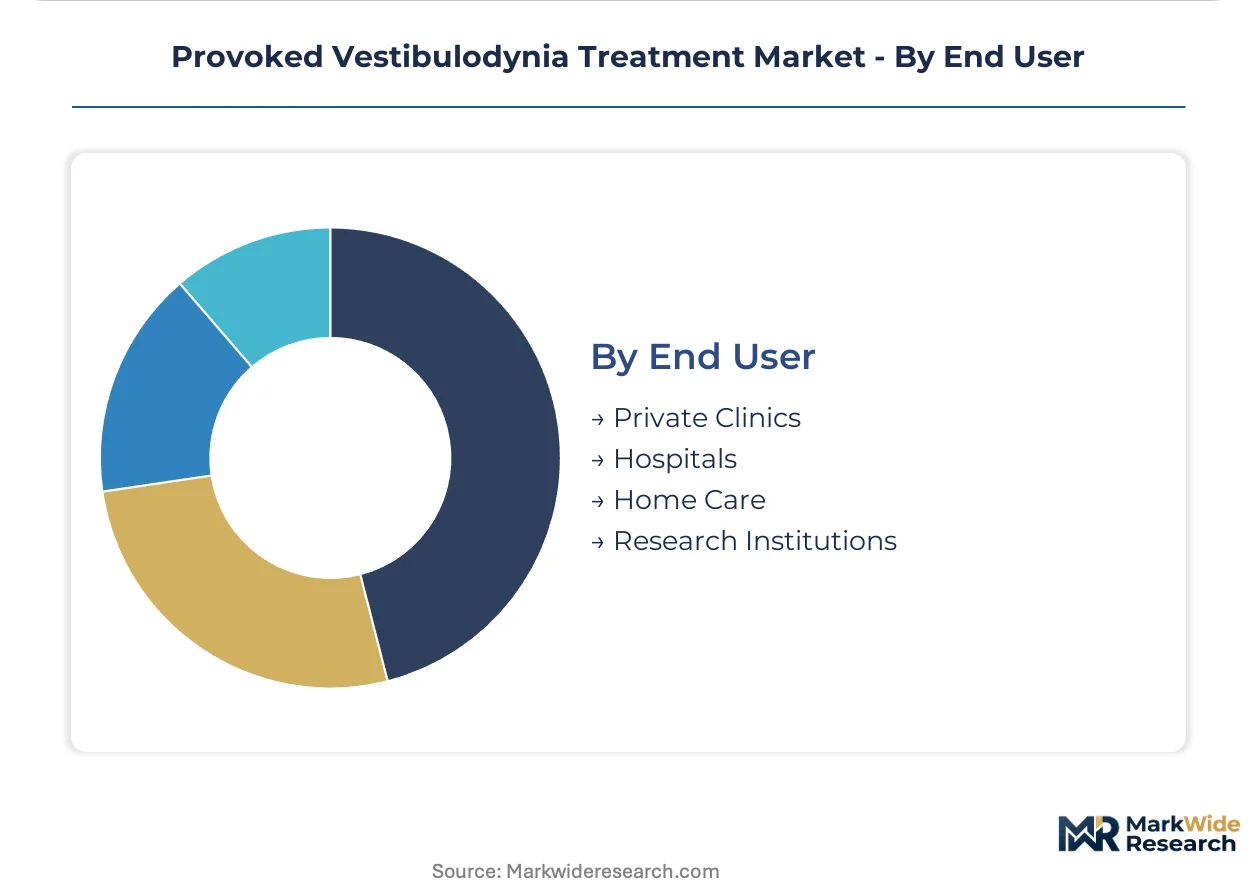
- Private Clinics:Specialized vulvar pain and pelvic health practices in Hamburg, Berlin, and select United States metropolitan areas integrate physical therapy, psychology, and pharmacotherapy under single ownership. These entities drive adoption of neuromodulatory devices and subscription-based digital therapeutic platforms.
- Hospitals:Academic medical centers in Heidelberg and Boston anchor surgical intervention volumes and complex multimodal protocol development.
- Home Care:Dilator therapy and topical agent self-administration expand addressable geography beyond specialist catchment areas.
- Research Institutions:NIH-funded and EMA-affiliated trial networks generate regulatory-accepted endpoints for novel device and biologic development.
Revenue concentration remains with Private Clinics; patient reach is expanding fastest through Home Care digital integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for provoked vestibulodynia treatment clusters in health systems with established pelvic pain specialization and favorable reimbursement for multimodal care. Germany, the United States, France, Canada, and Australia concentrate both patient volume and protocol innovation.
United States
Gynecology clinics in Boston, New York, and California are expanding integrated physical therapy-pharmacotherapy protocols as first-line care pathways. FDA chronic pain guidance is reshaping clinical trial endpoints for vulvodynia therapeutics, enabling broader label indications for neuropathic pain agents. Academic medical centers in Massachusetts anchor surgical intervention volumes and complex multimodal protocol development for refractory cases.
Germany
Specialized vulvar pain centers in Berlin, Munich, and Hamburg are driving adoption of pelvic floor physical therapy through reimbursement parity with pharmacotherapy. The EU MDR determines market access for novel vulvodynia devices and biologics, with German notified bodies applying stringent clinical evidence requirements. Private clinics in Hamburg integrate neuromodulatory devices and subscription-based digital therapeutic platforms under single ownership models.
France
Reproductive medicine and sexual health clinics in Paris and Lyon constitute core demand centers for premenopausal women seeking non-systemic alternatives. ANSM and national health technology assessment bodies regulate market access for novel vulvodynia therapeutics, creating divergence with German interpretation standards. The Île-de-France region concentrates both patient volume and protocol development investment for adolescent presentations.
Canada
Pediatric gynecology services in Toronto academic centers are developing age-appropriate dilator protocols for primary provoked vestibulodynia. Health Canada regulates device and pharmaceutical approvals for vulvodynia indications, with provincial formularies determining pharmacotherapy access. United States gynecology clinic networks are licensing their integrated protocols to health systems in Ontario and British Columbia.
Australia
Subscription-based pelvic health platforms are concentrating uptake among commercially insured populations where employer wellness programs subsidize access. The TGA regulates medical devices for vulvodynia treatment, with enhanced clinical evidence requirements extending time-to-market for novel neuromodulation systems. Sydney and Melbourne anchor demand for home care digital integration extending specialist reach beyond metropolitan catchment areas.
Provoked Vestibulodynia Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical incumbents dominating revenue flows through established neuropathic pain portfolios while device innovators capture margin pools in physical therapy and neuromodulation. The vendor base concentrates around three strategic archetypes: dermatology heritage players leveraging institutional formulary relationships, CNS-focused developers navigating chronic pain regulatory pathways, and compounding pharmacy networks controlling customized intravaginal formulations. Competitive moves center on M&A to secure pelvic floor physical therapy capabilities and strategic partnerships to integrate digital therapeutic platforms with clinic workflows.
Among pharmaceutical incumbents, Johnson & Johnson Services Inc, Pfizer Inc, and Eli Lilly and Company occupy positions reflecting divergent R&D heritage. Johnson & Johnson Services Inc exemplifies the dermatology heritage archetype sustaining shelf presence in institutional formularies. Pfizer Inc represents the neuropathic pain pipeline extension strategy into off-label vestibulodynia applications. Eli Lilly and Company anchors the CNS-focused development channel navigating chronic pain regulatory pathways with established psychiatric and pain medicine co-management relationships.
| Leading Market Players |
|---|
| Mycovia Pharmaceuticals Inc |
| Johnson & Johnson Services Inc |
| GlaxoSmithKline plc |
| Scynexis Inc |
| Allergan plc |
| AstraZeneca plc |
| Pfizer Inc |
| Sanofi |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Low-level laser therapy device manufacturing is compressing production economics for photobiomodulation systems while concentrating component sourcing among German and United States optical equipment suppliers, simultaneously elevating price premiums for FDA-cleared platforms and squeezing margins on uncertified alternatives.
Pricing Analysis
Volume concentrates in compounded topical lidocaine formulations where California and Texas pharmacy networks capture standard-margin pools, while neuromodulatory devices and subscription-based pelvic health platforms absorb premium pricing tiers. Price differentiation rests on FDA clearance status and pelvic floor physical therapy reimbursement parity, with German and United States private clinics commanding highest rates for integrated multimodal protocols. Pricing pressure stems from EU MDR compliance costs extending device development timelines and compressing returns. Medicaid-managed care plans exhibit highest price sensitivity, constraining access to compounded intravaginal preparations in United States public payer segments.
Supply Chain Analysis
Regional distribution centers in Hamburg, Berlin, and Boston anchor hub-and-spoke patterns for neuromodulatory devices and digital therapeutic platforms, with compounding pharmacy networks in California and Texas operating localized intravaginal formulation production. Component sourcing draws from German optical equipment manufacturers for laser therapy systems and United States software developers for HIPAA-compliant pelvic health platforms. Single-source vulnerability concentrates in FDA-cleared device predicates, where predicate shortages delay 510(k) pathways. Distribution runs through specialized vulvar pain center procurement committees and direct-to-clinic digital platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR compliance costs and pelvic floor specialist scarcity force undercapitalized compounding pharmacies and device startups toward acquisition or exit.
For Market Incumbents: Anchor formulary position through backward integration into compounding pharmacy networks, securing lidocaine supply chains against California regulatory shifts. Deepen vertical control over pelvic floor physical therapy training programs to constrain specialist pipeline access for emerging competitors. Defend against digital therapeutic disintermediation by embedding e-prescription workflows into existing clinic relationships. For New Entrants and Emerging Players: Subscription-based telehealth platforms offer the most penetrable route for bypassing concentrated specialist geography in Texas and California employer wellness channels. Target adolescent protocol development in Toronto and Boston academic centers where pediatric gynecology services lack standardized dilator therapy offerings. Pursue white-label partnerships with United States gynecology clinic networks seeking to license multimodal protocols internationally. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by dermatology heritage pharmaceutical incumbents seeking pelvic floor physical therapy capabilities. Long-term viability favors platforms with FDA-cleared device predicates and established HIPAA-compliant data infrastructure. Monitor FDA chronic pain guidance revisions as the signal indicating whether neuropathic pain label expansions will sustain pharmaceutical incumbent positioning or accelerate device-based displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Pelvic Floor Specialist Training Program | Addresses specialist scarcity constraining protocol rollout to community gynecology practices in Germany and the United States. |
| FDA 510(k) Predicate Device Acquisition | Accelerates neuromodulatory device market entry under evolving chronic pain clinical trial guidance. |
| HIPAA-Compliant Platform Integration | Enables remote dilator compliance monitoring extending clinic reach beyond metropolitan catchment areas. |
| EU MDR Clinical Evidence Buildout | Satisfies German notified body requirements for vulvodynia device approvals under strengthened regulations. |
| Compounding Pharmacy Network Partnership | Secures margin pools for customized intravaginal lidocaine formulations in California and Texas. |
Research Methodology
Document review covered FDA filings, ClinicalTrials.gov vulvodynia protocol registrations, EMA device submission databases, and hospital procurement records, complemented by interviews with pelvic floor physical therapy directors, gynecology clinic formulary managers, compounding pharmacy network executives, and EU MDR regulatory consultants. Secondary validation drew from CMS Medicare reimbursement data, German national health technology assessment publications, and private payer policy documents. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing across therapy type and delivery mode segments.
Cross-reference approaches married historical utilization patterns from Heidelberg and Boston academic medical centers with expert panel input on reimbursement trajectory and regulatory timeline evolution across the analysis window. Segmentation modeling incorporated therapy type, delivery mode, age group, and end user dimensions with regional regulatory cluster overlays. CAGRs derived from weighted scenario analysis blending conservative FDA guidance adherence with accelerated digital therapeutic adoption curves, with forecast inputs including pelvic floor physical therapy reimbursement code expansion rates and EU MDR notified body processing timelines.
The model holds under stable FDA chronic pain guidance and sustained German reimbursement parity assumptions; deviation in EU MDR interpretation standards across French and German notified bodies or Medicaid formulary restriction tightening would shift device and pharmacotherapy penetration trajectories respectively. Forecasts reflect documented assumptions regarding specialist training pipeline expansion and HIPAA framework evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Chronic Lower Back Pain Treatment Market
Pain Management
Topical Pain Relief Market
Pain Management
Cancer Pain Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Heat Therapy Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
OTC Painkiller Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Postoperative Pain Market
Pain Management
Over-The-Counter Pain Medication Market