
 Global Non-Opioid Pain Patch Market | 2026-2036
Global Non-Opioid Pain Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Opioid Pain Patch Market Foresight
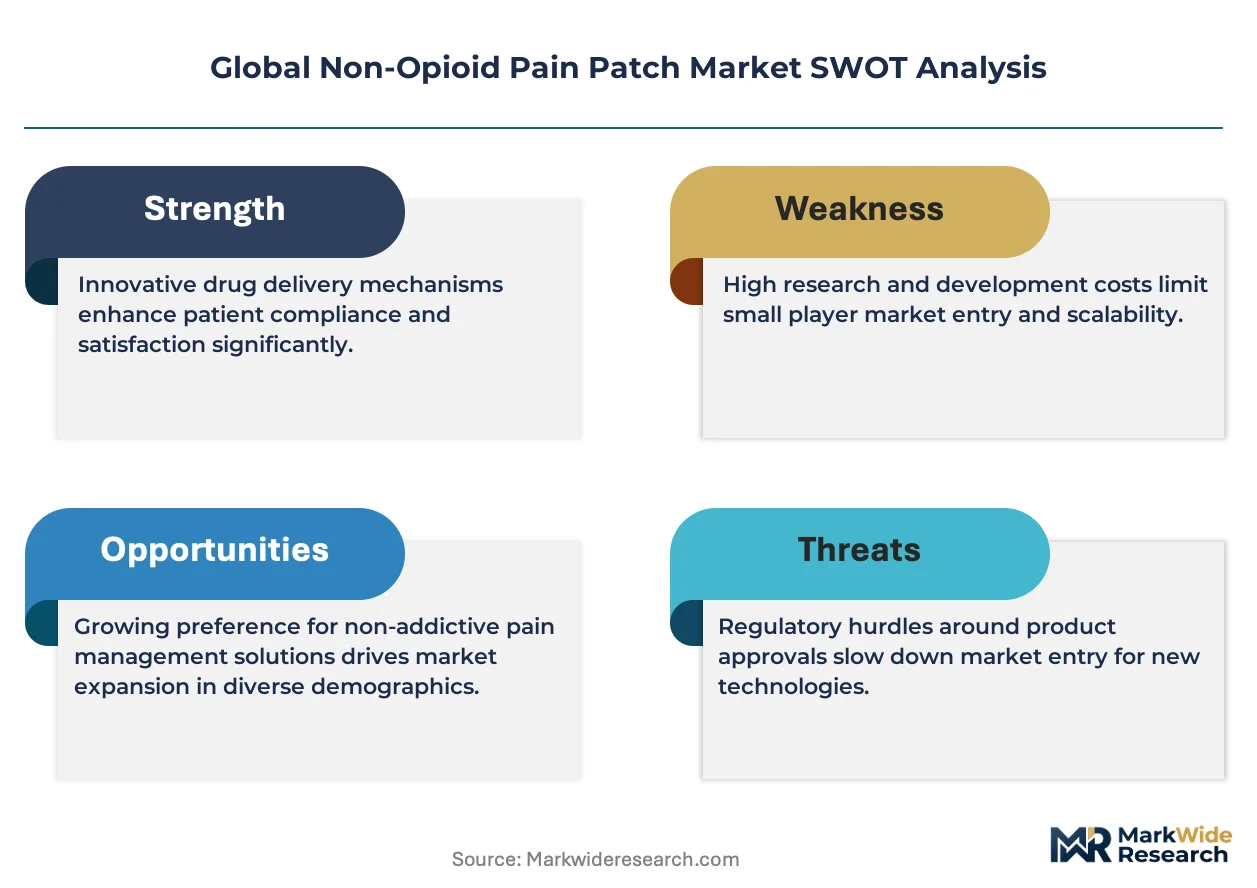
Hospital formularies is unwinding their historical opioid-default protocols and redirecting procurement budgets toward transdermal non-opioid alternatives. Hisamitsu Pharmaceutical Co., Inc. dominates the lidocaine patch segment through proprietary reservoir technology and established relationships with Japanese and North American distributors. Grünenthal anchors European prescription access through its fentanyl-free portfolio and specialized pain-management field force. Teva Pharmaceutical Industries Ltd. competes on manufacturing scale, leveraging its generic infrastructure to supply private-label ketoprofen and diclofenac patches across multiple retail pharmacy chains.
Non-opioid pain patches are transdermal or topical delivery systems containing active pharmaceutical ingredients such as lidocaine, capsaicin, ketoprofen, or diclofenac, formulated in adhesive matrices or hydrogel layers designed for sustained release over 8-24 hour wear periods. Their primary commercial purpose is to provide localized analgesia for musculoskeletal, neuropathic, or post-operative pain while eliminating systemic opioid exposure and associated dependency risk. The lidocaine patch category leads in prescription volume within the United States, whereas microneedle technology represents the fastest-growing segment as manufacturers seek to enhance dermal penetration rates for hydrophilic actives previously excluded from passive transdermal formats. Homecare settings command expanding share as post-surgical pain protocols shift toward ambulatory recovery models that prioritize patient self-administration outside institutional settings.
The FDA regulates these products through its Center for Drug Evaluation and Research, requiring demonstration of bioequivalence or therapeutic equivalence for generic transdermal entrants, while the EMA's Committee for Medicinal Products for Human Use enforces comparability standards that influence patch reformulation cycles across European markets. Japan's PMDA maintains distinct pharmacovigilance reporting requirements for topical NSAID patches that shape post-market surveillance obligations for exporters. Stakeholders must monitor evolving reimbursement thresholds for non-opioid alternatives as payors recalibrate formularies in response to public health mandates on opioid reduction.
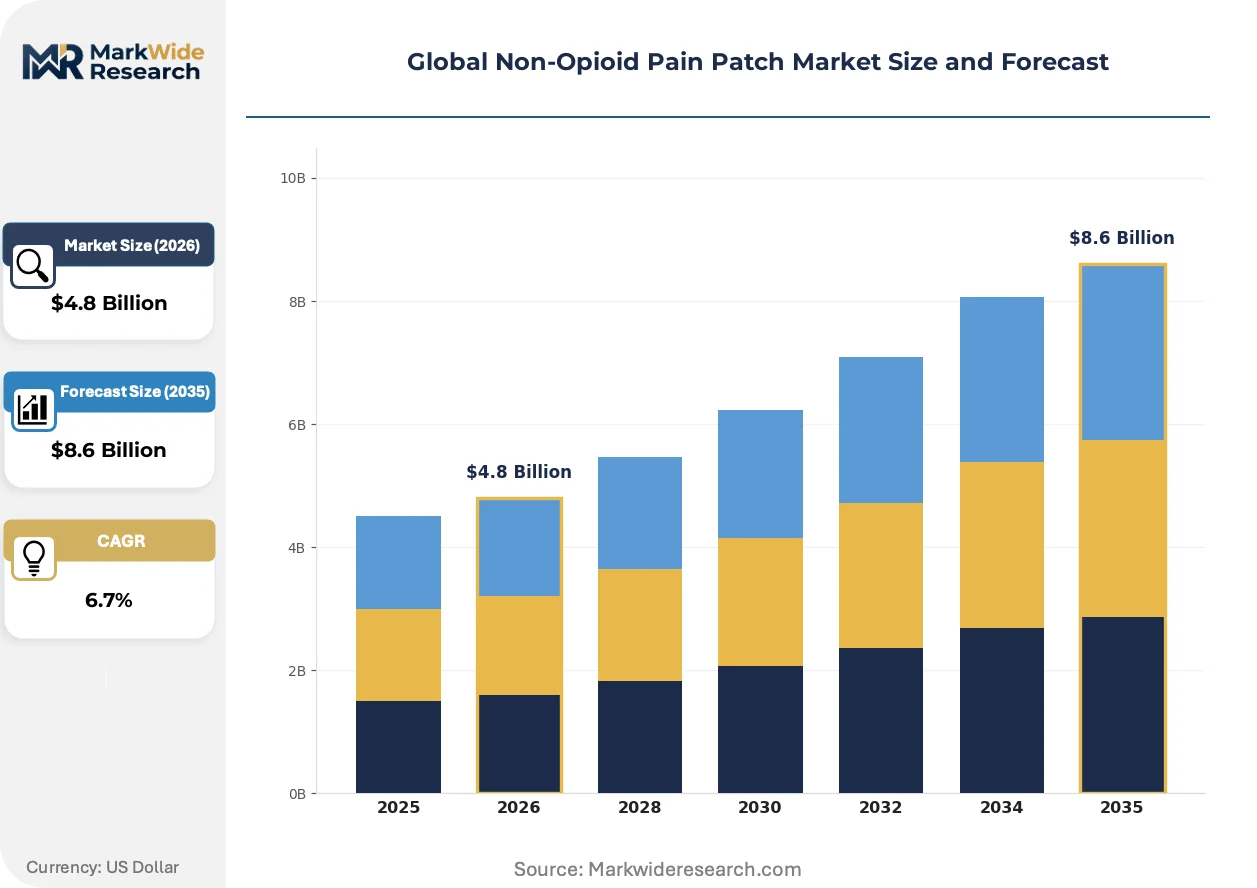
Market Dynamics
FDA's tightened opioid prescribing guidelines are forcing hospital formularies to unwind opioid-default protocols and redirect procurement budgets toward transdermal non-opioid alternatives, fundamentally restructuring the competitive landscape for localized analgesia delivery systems.
Growth Catalysts
- Post-Surgical Protocol Reform:Ambulatory recovery models in the United States are expanding self-administration outside institutional settings, concentrating demand for extended-wear lidocaine and diclofenac patches.
- REACH Compliance Migration:European manufacturers are reformulating adhesive matrices to eliminate phthalate plasticizers, creating first-mover advantages for compliant patch suppliers across EMA-regulated markets.
- Microneedle Array Advancement:Solid-state microprojection technology is enabling dermal delivery of hydrophilic actives previously excluded from passive transdermal formats, opening new therapeutic categories.
Market Restraints
- API Supply Concentration:Lidocaine base production concentrates among a limited cohort of Indian and Chinese bulk manufacturers, exposing formulators to input volatility and quality inconsistency risks.
- Skin Permeation Ceiling:The stratum corneum barrier restricts molecular weight thresholds for passive diffusion, excluding high-potency peptides and proteins from conventional patch formats.
- Reimbursement Compression:US Medicare and Medicaid formularies impose prior authorization requirements for branded non-opioid patches, favoring generic ketoprofen and diclofenac alternatives.
Strategic Opportunities
- Brazilian Regulatory Opening:ANVISA's accelerated review pathway for transdermal NSAIDs is reducing time-to-market for exporters seeking access to Latin America's largest pharmaceutical market.
- Wearable Biosensor Convergence:Integration of microneedle drug delivery with continuous glucose monitoring platforms is creating closed-loop pain management systems for diabetic neuropathy patients.
- Direct-to-Patient Subscription:Telehealth platforms are bypassing traditional pharmacy distribution, enabling recurring revenue models for chronic pain patch replenishment.
Industry Challenges
- Adhesion Engineering Talent Scarcity:Formulation chemists with expertise in pressure-sensitive adhesive rheology and skin biocompatibility are in critically short supply across contract development organizations.
- Bioequivalence Study Complexity:FDA's draft guidance on transdermal generics requires novel clinical endpoint designs, extending development timelines and escalating program costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Opioid Pain Patch Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketoprofen Patch, Lidocaine Patch, Capsaicin Patch, Diclofenac Patch Application: Chronic Pain, Acute Pain, Post-Surgical Pain, Sports Injuries End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Technology: Transdermal Delivery, Microneedle Technology, Iontophoresis, Electroporation |
| Companies Covered | Hisamitsu Pharmaceutical Co., Inc., Teva Pharmaceutical Industries Ltd., Grünenthal, Endo International plc, GSK plc, Teikoku Seiyaku Co., Ltd., Scilex Pharmaceuticals Inc., IBSA Institut Biochimique SA, Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Opioid Pain Patch Market Shifts & Advancements
Active pharmaceutical ingredient delivery mechanisms are fragmenting across multiple technological platforms, each targeting distinct pain etiologies and wear-time preferences that reshape manufacturing investment priorities.
Microneedle-based transdermal systems are fragmenting the traditional passive diffusion market by enabling bolus delivery of lidocaine and capsaicin through biodegradable arrays. Sports medicine clinics in Germany and Australia are piloting 30-minute wear protocols that compress treatment cycles. This technology is fragmenting the historical 12-24 hour wear paradigm into procedure-specific applications.
EMA's Medical Device Regulation recalibration is reclassifying certain combination patches as drug-device products, triggering additional conformity assessment requirements. Manufacturers with existing CE-marked hydrogel patches face portfolio-wide technical documentation overhauls. The lidocaine-reservoir segment is responding by segregating European and non-European supply chains to isolate regulatory risk.
Homecare procurement through specialty pharmacy distributors is displacing hospital-centric purchasing for post-operative pain management. United States health systems are consolidating vendor contracts with mail-order pharmacies that manage patient onboarding and adherence monitoring. This channel migration is most visible in orthopedic surgery verticals where same-day discharge protocols dominate.
Global Non-Opioid Pain Patch Market Segmentation
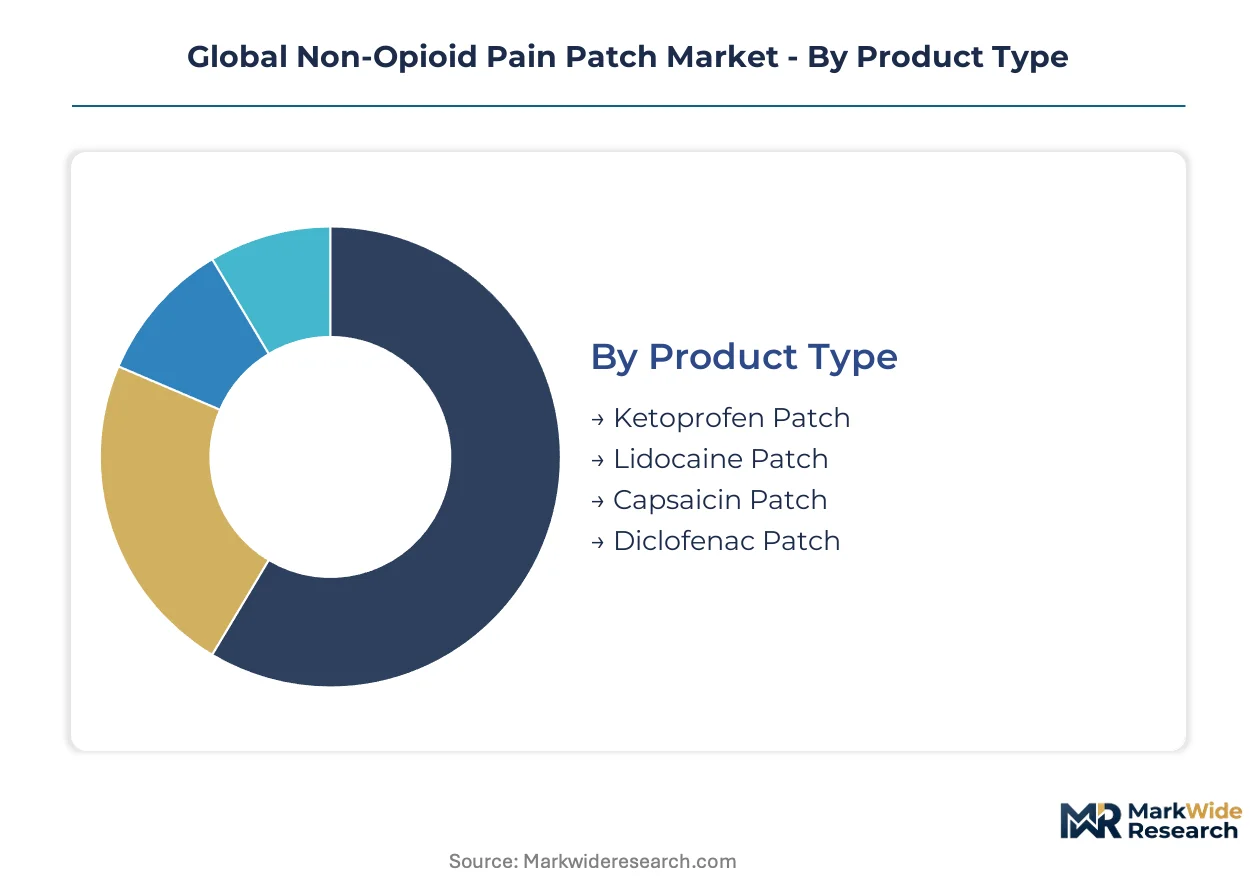
Non-opioid pain patch procurement decisions fragment across four intersecting dimensions: active ingredient chemistry, clinical indication, care setting, and delivery mechanism. Manufacturers must align formulation investments with where prescribing authority and reimbursement pathways concentrate.
Product Type:
Margin pools concentrate in prescription-grade lidocaine formulations protected by reservoir technology patents, while commoditized NSAID patches compete on manufacturing scale.
- Lidocaine Patch:Reservoir-matrix designs enable sustained 12-hour release of amide-type local anesthetic through proprietary adhesive systems. Hospital formularies in the United States prioritize these patches for post-surgical neuropathic pain, driven by FDA's opioid prescribing restrictions that redirect physicians toward transdermal local anesthetics.
- Ketoprofen Patch:Propionic acid NSAID delivered through hydrogel matrices targets acute musculoskeletal inflammation with faster onset than oral equivalents. German and Japanese sports medicine clinics are expanding procurement for ligament and tendon injuries, responding to patient demand for non-systemic anti-inflammatory delivery.
- Diclofenac Patch:Phenylacetic acid derivative formulated in emulsion-gel adhesives for osteoarthritis and soft tissue trauma.
- Capsaicin Patch:High-concentration transdermal formulation depleting substance P from sensory neurons for peripheral neuropathy.
The dominant share belongs to Lidocaine Patch, while Microneedle Technology (within Technology category) is closing the gap fastest.
Application:
Volume concentrates in acute pain management where institutional procurement contracts secure formulary placement, though chronic pain presents recurring revenue potential through repeat prescriptions.
- Post-Surgical Pain:Ambulatory surgery centers in the United States are standardizing lidocaine and diclofenac patches for same-day discharge protocols, eliminating opioid-first approaches from orthopedic and general surgery pathways. Medicare reimbursement shifts for post-operative pain management are accelerating this substitution.
- Chronic Pain:Long-term neuropathic and musculoskeletal conditions require sustained patch therapy over months or years. Homecare settings in Japan and Germany dominate procurement, with patients self-administering capsaicin and lidocaine formulations under remote physician monitoring.
- Acute Pain:Short-duration trauma and injury management through emergency departments and urgent care clinics.
- Sports Injuries:Athletic training facilities and physiotherapy practices targeting rapid return-to-play protocols.
Post-Surgical Pain commands the largest procurement volumes, while Chronic Pain generates the stickiest patient relationships.
End User:
Channel economics diverge sharply: hospitals negotiate consolidated contracts on annual cycles, while homecare routes through specialty pharmacies capture higher per-unit margins.
- Hospitals:Integrated delivery networks in the United States are unwinding opioid-default protocols and redirecting anesthesia department budgets toward transdermal non-opioid alternatives. P&T committees now require evidence of reduced opioid consumption for formulary approval of new patch entrants.
- Homecare Settings:Post-surgical patients discharged within 24 hours require self-administered pain management outside institutional monitoring. United States mail-order pharmacies and Japanese home nursing services are consolidating vendor relationships for chronic pain patch replenishment.
- Clinics:Outpatient pain management and sports medicine practices prescribing procedure-specific patch protocols.
- Rehabilitation Centers:Physical therapy facilities integrating patches into multimodal recovery programs.
Hospital purchasing still dominates absolute volume, though Homecare Settings are expanding their share fastest.
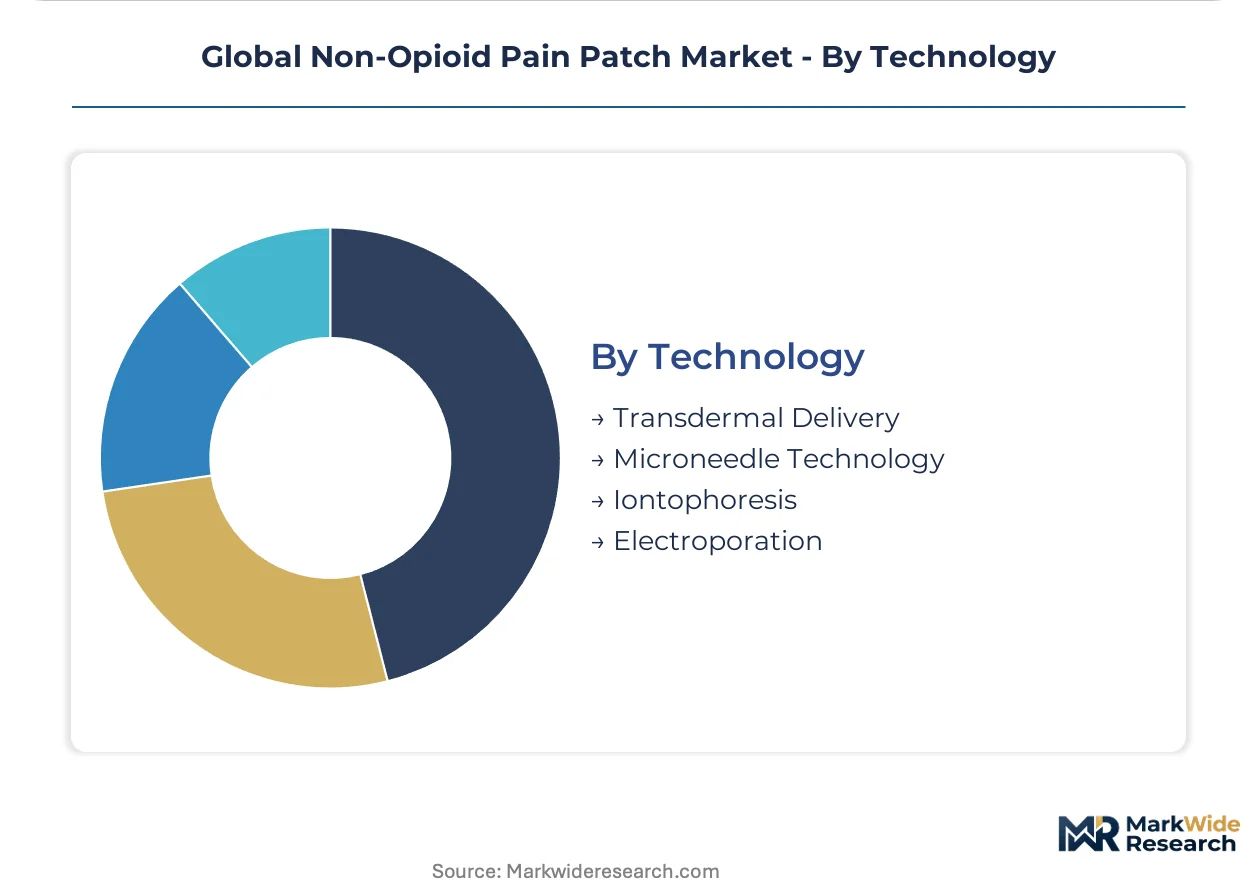
Technology:
Investment intensity clusters in active delivery systems that overcome stratum corneum barriers, while passive diffusion platforms compete on manufacturing cost.
- Microneedle Technology:Biodegradable microprojection arrays create transient channels for hydrophilic actives previously excluded from transdermal formats. Australian and German sports medicine clinics are piloting 30-minute lidocaine protocols that compress treatment cycles and displace historical 12-hour wear paradigms.
- Transdermal Delivery:Passive diffusion through adhesive matrices remains the workhorse platform for lipophilic NSAIDs and local anesthetics. Indian and Chinese contract manufacturers supply private-label ketoprofen and diclofenac patches to retail pharmacy chains across North America and Europe.
- Iontophoresis:Electrically-assisted delivery using mild current to enhance ionized drug penetration for physical therapy applications.
- Electroporation:Pulsed electrical fields temporarily disrupting lipid bilayers for macromolecule delivery in research-stage applications.
Transdermal Delivery retains installed base dominance, while Microneedle Technology is climbing the fastest toward commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States concentrate the largest absolute purchasing volumes for non-opioid pain patches, while Japanese and German homecare markets generate the highest per-unit margins through chronic pain subscription models.
United States
Ambulatory surgery centers and integrated delivery networks are consolidating vendor contracts for post-surgical lidocaine patches as same-day discharge protocols eliminate opioid-first prescribing pathways. FDA's Center for Drug Evaluation and Research enforces bioequivalence standards for generic transdermal entrants that extend development timelines. The Greater Boston cluster hosts specialized pain-management field forces targeting orthopedic surgery verticals.
Japan
Home nursing services and mail-order pharmacies are expanding procurement of ketoprofen and capsaicin patches for chronic neuropathic pain management under remote physician monitoring. PMDA maintains distinct pharmacovigilance reporting requirements for topical NSAID patches that shape post-market surveillance obligations. The Kanto region around Tokyo anchors domestic manufacturing of hydrogel matrix patches.
Germany
Sports medicine clinics in Bavaria and North Rhine-Westphalia are piloting microneedle-based lidocaine protocols that compress treatment cycles to 30-minute wear periods. EMA's Medical Device Regulation recalibration is reclassifying certain combination patches as drug-device products, triggering additional conformity assessments. The Munich-Stuttgart corridor concentrates formulation chemists with pressure-sensitive adhesive expertise.
China
Contract manufacturers in the Yangtze River Delta supply private-label diclofenac and ketoprofen patches to retail pharmacy chains across North America and Europe. NMPA's accelerated review pathways for transdermal generics are reducing time-to-market for domestic exporters. Zhejiang and Jiangsu provinces host the largest concentration of lidocaine base bulk production.
Brazil
ANVISA's accelerated review pathway for transdermal NSAIDs is attracting exporters seeking access to Latin America's largest pharmaceutical market. Post-surgical pain protocols in São Paulo and Rio de Janeiro are shifting toward ambulatory recovery models that prioritize patient self-administration. The São Paulo metro area concentrates specialty pharmacy distributors managing chronic pain patch replenishment.
Global Non-Opioid Pain Patch Market Competitive Landscape
Player mix skews toward pharmaceutical incumbents with transdermal manufacturing infrastructure and specialized pain-management commercialization capabilities. The competitive structure concentrates around three archetypes: Japanese reservoir-technology specialists, European prescription-access anchors, and generic-scale manufacturers leveraging contract development organizations. Dominant competitive moves include M&A targeting microneedle technology platforms and strategic partnerships with telehealth providers for direct-to-patient distribution channels.
Within the technology-specialist tier, Hisamitsu Pharmaceutical Co., Inc. and Teikoku Seiyaku Co., Ltd. occupy positions defined by proprietary adhesive systems and established distributor relationships across Japanese and North American markets. Grünenthal exemplifies the European prescription-access archetype through its fentanyl-free portfolio positioning. Teva Pharmaceutical Industries Ltd. sits within the scale-driven generic segment, supplying private-label ketoprofen and diclofenac patches through manufacturing infrastructure distributed across multiple retail pharmacy chains.
| Leading Market Players |
|---|
| Hisamitsu Pharmaceutical Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Grünenthal |
| Endo International plc |
| GSK plc |
| Teikoku Seiyaku Co., Ltd. |
| Scilex Pharmaceuticals Inc. |
| IBSA Institut Biochimique SA |
| Mylan N.V. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with API suppliers in India and China lock in lidocaine base access while capping price volatility for North American and European formulators. These arrangements concentrate procurement power among pharmaceutical incumbents with sufficient volume to secure minimum purchase commitments, while smaller players absorb spot-market swings in active pharmaceutical ingredient costs.
Pricing Analysis
Cost-plus contracts indexed to Indian bulk chemical price indices dominate lidocaine patch procurement between formulators and API suppliers. Three-tier pricing structure across premium reservoir-matrix, standard hydrogel, and economy private-label tiers differentiates based on FDA bioequivalence certification status and wear-time performance claims. Cost compression in the generic ketoprofen and diclofenac segments is intensifying because Medicare prior authorization requirements favor lowest-cost alternatives. Hospital procurement committees exhibit the highest price sensitivity, while Japanese home nursing services prioritize adhesion reliability over unit cost.
Supply Chain Analysis
Strategic stockpiling of lidocaine base and pressure-sensitive adhesive raw materials prevails over just-in-time approaches due to Indian and Chinese API supply concentration. Zhejiang and Jiangsu provinces in China, alongside Gujarat and Maharashtra states in India, anchor global lidocaine base production. Formulation chemistry expertise in pressure-sensitive adhesive rheology rests on German and Japanese specialty chemical suppliers. Single-source vulnerability for microneedle array manufacturing equipment creates bottleneck risk for technology adopters. Distribution runs through specialty pharmacy distributors in the United States and hospital purchasing consortia in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patch replenishment subscription services through telehealth platforms are expanding faster than hardware unit sales, creating a service-attach opportunity where recurring revenue multiples exceed traditional product margins. Remote patient monitoring and adherence coaching layers now capture disproportionate enterprise value relative to the underlying transdermal delivery systems.
For Market Incumbents: Shield reservoir-technology patent positions through formulation trade-secret layering and accelerated microneedle platform development to preempt generic erosion in lidocaine segments. Backward integration into pressure-sensitive adhesive manufacturing reduces dependency on German and Japanese specialty chemical suppliers facing REACH compliance migration costs. Capacity addition in the Greater Boston cluster strengthens orthopedic surgery vertical access before ambulatory surgery center consolidation accelerates. For New Entrants and Emerging Players: Lead with microneedle-based procedure-specific protocols targeting German and Australian sports medicine clinics where 30-minute wear paradigms displace incumbent 12-hour formats. Brazilian ANVISA accelerated review pathways offer the most penetrable regulatory entry point for transdermal NSAID exporters seeking Latin American market access. Direct-to-patient telehealth partnerships bypass entrenched hospital formulary gatekeepers and capture higher-margin chronic pain subscription relationships. For Investors and Strategic Acquirers: Capital is best deployed toward technology-specialist contract development organizations with captive microneedle array manufacturing capabilities and established bioequivalence study execution track records. Long-term viability hinges on regulatory navigation expertise across FDA, EMA, and PMDA jurisdictions rather than commodity manufacturing scale. Watch for FDA draft guidance finalization on transdermal generic clinical endpoints as the inflection signal for development timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Microneedle Platform Acquisition | Secures biodegradable array technology for hydrophilic active delivery previously excluded from passive formats. |
| Telehealth Distribution Partnership | Enables direct-to-patient chronic pain subscription models bypassing traditional pharmacy intermediaries. |
| REACH-Compliant Adhesive Reformulation | Positions European supply chains ahead of EMA Medical Device Regulation recalibration deadlines. |
| ANVISA Registration Acceleration | Reduces time-to-market for transdermal NSAID access to Latin America's largest pharmaceutical market. |
| Hospital System GPO Contracting | Locks in formulary placement as integrated delivery networks consolidate vendor relationships. |
Research Methodology
Operator-level perspectives from formulary directors at integrated delivery networks, procurement managers at ambulatory surgery centers, regulatory affairs leads at transdermal manufacturers, and pharmacy benefit managers anchored the qualitative base. Secondary validation drew from FDA Center for Drug Evaluation and Research filings, EMA Committee for Medicinal Products for Human Use submissions, PMDA pharmacovigilance reports, and hospital procurement database extracts. Bottom-up patient-volume modeling and top-down pharmaceutical market sizing triangulated volume and value estimates.
Sensitivity analysis tested forecast outputs against variable assumptions for microneedle technology adoption curves, opioid prescribing guideline enforcement intensity, and reimbursement threshold shifts across Medicare, Medicaid, and private payor formularies. Segmentation dimensions spanned active ingredient chemistry, clinical indication, care setting, and delivery mechanism alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves applied to base-year estimates and cross-referenced against historical analogs from comparable therapeutic category maturation patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA opioid restriction enforcement, stable API supply from Indian and Chinese bulk manufacturers, and continued EMA regulatory alignment would require recalibration. Forecasts embed assumptions regarding ambulatory surgery expansion rates and telehealth platform penetration in chronic pain management. Revision becomes warranted when microneedle bioequivalence study failure rates cross thresholds that extend generic development timelines beyond manufacturer investment horizons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Neuropathic Pain Market
Pain Management
OTC Painkiller Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Global Morphine Market
Pain Management
Pain Patches Market
Pain Management
Bone Pain Treatment Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Cancer Pain Market
Pain Management
Ketorolac Market
Pain Management
Palliative Care Market
Pain Management
Asia-Pacific Tattoo Numbing Cream Market