
 Cancer Pain Market | 2026-2036
Cancer Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Pain Market Analysis
Market Context
Modular combination therapy packaging is realigning how oncology departments procure analgesic portfolios, bundling opioids with adjuvant medications into protocol-driven formularies. Pfizer Inc. leverages its hospital channel infrastructure to sustain formulary positioning across major cancer centers. Johnson & Johnson anchors its market presence through diversified analgesic portfolios spanning both opioid and non-opioid modalities. Teva Pharmaceutical Industries Ltd. competes on generic injectable opioids, controlling cost-sensitive procurement decisions in institutional settings.
Technical Definition and Segment Structure
Cancer pain encompasses nociceptive and neuropathic pain syndromes arising from tumor invasion, metastatic compression, or treatment-related tissue damage, typically managed through WHO analgesic ladder protocols combining pharmacological and interventional modalities. The primary purpose is restoring functional capacity and quality of life during curative or palliative oncology treatment. Opioids retain the largest revenue share within product type segmentation, though adjuvant medications represent the fastest-expanding margin pool as serotonin-norepinephrine reuptake inhibitors and anticonvulsants gain protocol inclusion. Transdermal delivery modes are capturing disproportionate growth in homecare settings, where patient self-administration and steady-state plasma levels reduce breakthrough episodes.
Regulatory Frame and Outlook
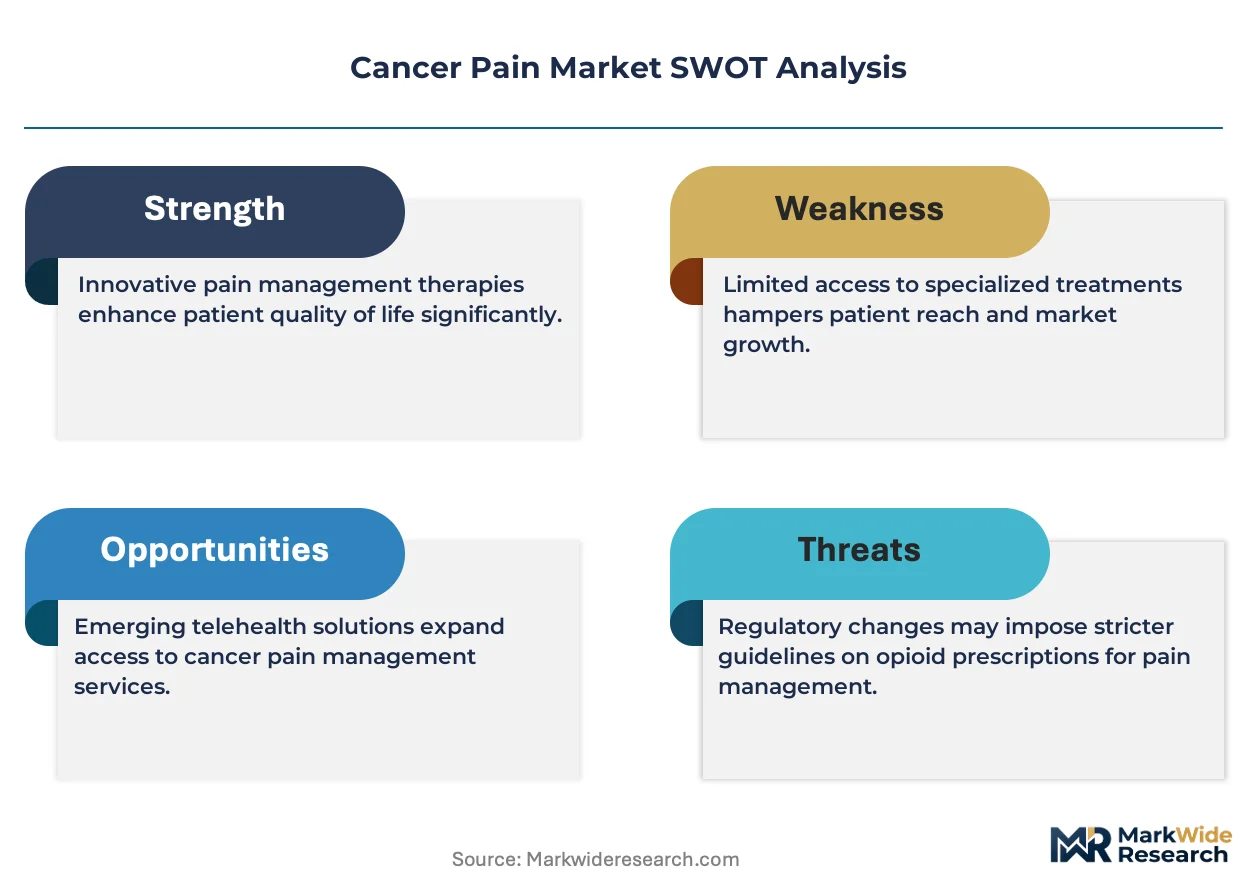
FDA Risk Evaluation and Mitigation Strategy requirements, DEA production quotas, and state-level prescription drug monitoring programs collectively constrain opioid prescribing volumes while accelerating investment in non-pharmacological alternatives. EMA pharmacovigilance frameworks and WHO essential medicines list revisions similarly pressure European manufacturers toward abuse-deterrent formulations and multimodal portfolios. Stakeholders must monitor evolving REMS modifications and parallel track approvals for novel non-opioid mechanisms to anticipate formulary access shifts before competitor positioning solidifies.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategy for extended-release opioids has compressed prescribing volumes while simultaneously accelerating hospital investment in multimodal pain protocols that bundle non-opioid adjuvants with interventional techniques.
Growth Catalysts
- Opioid stewardship mandates:Hospital systems across the United States are institutionalizing multimodal protocols that mandate adjuvant medication inclusion, expanding formulary slots for serotonin-norepinephrine reuptake inhibitors and anticonvulsants.
- Homecare infrastructure expansion:Transdermal delivery systems are capturing expanded reimbursement codes as integrated cancer centers discharge patients earlier to ambulatory settings.
- WHO analgesic ladder revisions:Updated essential medicines list guidelines are pressuring national formularies in Europe and Asia-Pacific to elevate non-opioid mechanisms to first-line status in neuropathic pain syndromes.
Market Restraints
- DEA production quotas:Annual manufacturing limits on Schedule II opioids constrain supply flexibility for injectable morphine and fentanyl formulations used in inpatient palliative care.
- Abuse-deterrent formulation costs:Polymer matrix and prodrug technologies add manufacturing complexity that inflates per-dose pricing beyond reach of cost-sensitive institutional procurement committees.
- Specialist workforce scarcity:Board-certified pain physicians and palliative care nurse practitioners concentrate in academic medical centers, leaving community oncology practices dependent on generalists with limited interventional training.
Strategic Opportunities
- Digital therapeutics integration:FDA breakthrough device designations for virtual reality distraction platforms and biofeedback applications are opening reimbursement pathways previously closed to non-pharmacological modalities.
- Subcutaneous pump miniaturization:Convergence of MEMS sensors and wireless connectivity is enabling patient-controlled analgesia devices for home infusion that bypass hospital pharmacy intermediaries.
- India's pharmaceutical manufacturing:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are attracting technology transfer agreements for abuse-deterrent opioid generics targeting emerging market tenders.
Industry Challenges
- REMS compliance infrastructure:Extended-release opioid manufacturers must maintain prescriber certification portals, patient registries, and distribution lock-in programs that fragment IT resources across incompatible state monitoring databases.
- Interventional training pipelines:Celiac plexus neurolysis and intrathecal pump placement require fellowship-level expertise that academic programs have not scaled to match community demand for outpatient procedural pain management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Pain Market |
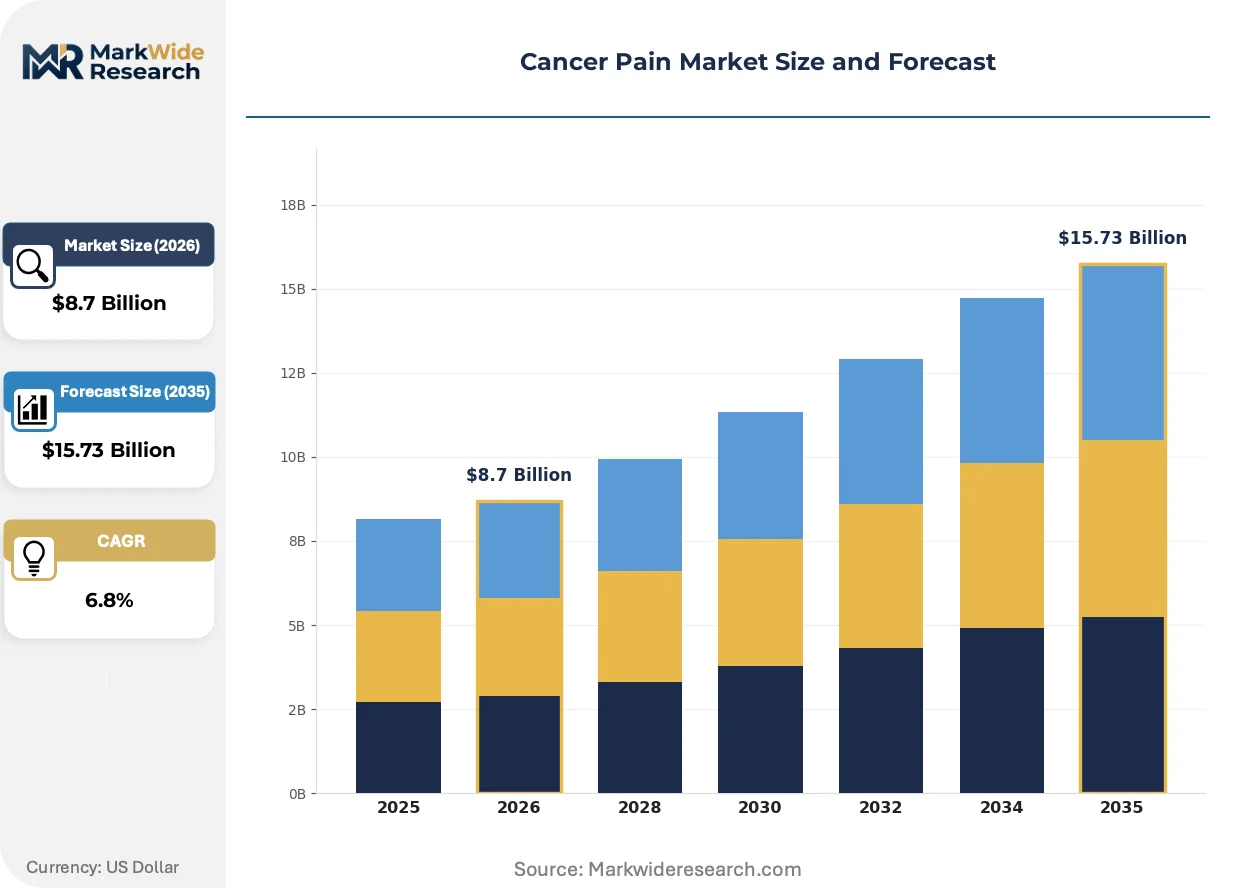
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Opioids, Adjuvant Medications, Non-Pharmacological Therapies Therapy Area: Palliative Care, Oncology, Pain Management, Neuropathic Pain Delivery Mode: Intravenous, Oral, Transdermal, Subcutaneous End User: Hospitals, Homecare, Specialty Clinics, Palliative Care Centers |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Novartis AG, Teva Pharmaceutical Industries Ltd., Purdue Pharma L.P., AstraZeneca plc, Mallinckrodt Pharmaceuticals, Eli Lilly and Company, Grünenthal Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Pain Market Emerging Trajectories
Digital biomarker platforms and closed-loop delivery systems are compressing the feedback cycle between patient-reported outcomes and dosing adjustments, displacing static prescribing protocols in both curative and palliative settings.
Closed-loop patient-controlled analgesia systems is unifying continuous vital sign monitoring with algorithmic dose modulation. Major cancer centers in the United States are piloting these platforms in bone marrow transplant units where opioid-induced respiratory depression poses acute risk. The technology is unifying anesthesiology and oncology workflows into single accountability structures that reduce nursing handoff errors.
EMA pharmacovigilance frameworks now mandate real-world evidence collection for extended-release opioids through patient registries and prescriber re-certification cycles. European manufacturers are reconfiguring commercial operations to capture post-market safety data as a competitive differentiator in tender processes. Abuse-deterrent formulations with polymer matrix barriers are absorbing disproportionate development resources as companies anticipate parallel regulatory pressure from WHO essential medicines committees.
Hospital procurement committees are consolidating analgesic purchasing through modular combination therapy contracts that bundle opioids, adjuvants, and antiemetics into protocol-driven formularies. This purchasing consolidation is displacing individual drug rebates with outcome-based guarantees tied to reduced breakthrough pain episodes. The shift is most visible in United States integrated delivery networks where pharmacy benefit managers have ceded formulary control to oncology clinical pathways committees.
Cancer Pain Market Segmentation
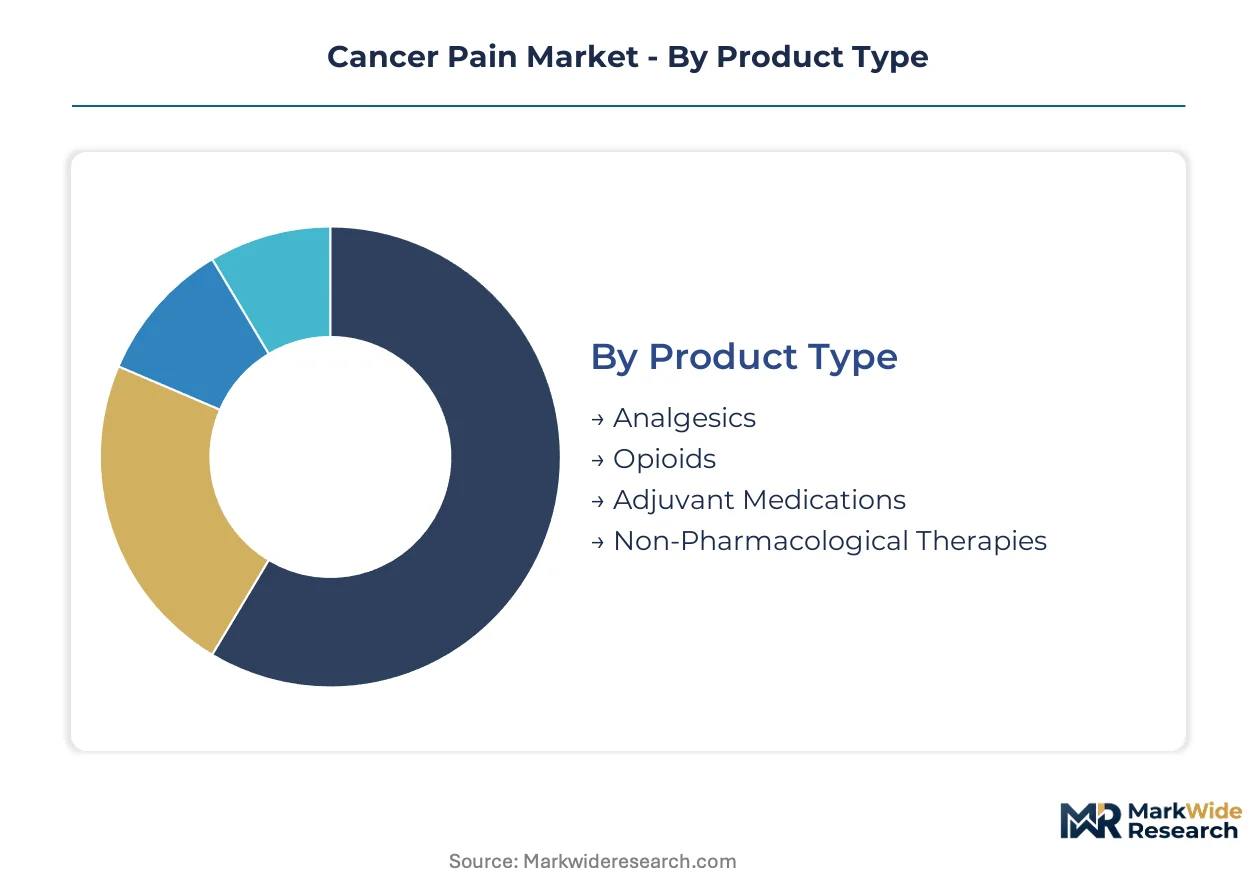
Cancer pain management requires precise therapeutic matching across tumor origin, pain mechanism, and care setting. Segmentation reveals where pharmacological dominance yields to interventional and digital modalities.
Product Type:
Formulation chemistry determines reimbursement tiering and formulary access across integrated delivery networks.
- Opioids:Extended-release morphine and fentanyl formulations maintain inpatient palliative care dominance through rapid titration capability. DEA production quotas constrain supply flexibility at major cancer centers in the United States, forcing protocol standardization around fewer SKUs.
- Adjuvant Medications:Serotonin-norepinephrine reuptake inhibitors and anticonvulsants are displacing opioids in neuropathic pain syndromes through hospital stewardship mandates. Memorial Sloan Kettering and MD Anderson have elevated duloxetine and pregabalin to first-line status in their electronic order sets.
- Analgesics:Non-opioid systemic agents including NSAIDs and acetaminophen combinations address bone pain from metastatic disease. These agents anchor step-one WHO ladder protocols in European oncology departments facing EMA pharmacovigilance pressure.
- Non-Pharmacological Therapies:Virtual reality distraction platforms and biofeedback applications are capturing breakthrough device designations from FDA. Cedars-Sinai and Stanford Health Care have deployed these modalities in bone marrow transplant units to reduce opioid exposure.
Mature deployment sits with Opioids. Newer deployment is concentrated in Non-Pharmacological Therapies.
Therapy Area:
Clinical endpoint definitions reshape competitive positioning across curative versus palliative intent.
- Palliative Care:End-of-life pain protocols prioritize rapid onset and patient-controlled dosing. Hospice providers in the United States are consolidating procurement through modular contracts bundling opioids with antiemetics and laxatives.
- Oncology:Active treatment phases demand analgesia that preserves cognitive function for chemotherapy scheduling. Major academic medical centers are piloting closed-loop delivery systems in this segment to reduce nursing handoff errors.
- Pain Management:Dedicated pain services perform celiac plexus neurolysis and intrathecal pump placement for refractory cases. Fellowship-trained interventionalists concentrate at Mayo Clinic, Cleveland Clinic, and Johns Hopkins, leaving community gaps.
- Neuropathic Pain:Chemotherapy-induced peripheral neuropathy drives demand for anticonvulsants and topical agents. This segment is expanding most quickly as taxane and platinum regimen volumes rise in breast and colorectal protocols.
Established practice patterns center on Palliative Care. Emerging protocol penetration is shifting toward Neuropathic Pain.
Delivery Mode:
Route selection determines care setting economics and patient autonomy thresholds.
- Intravenous:Patient-controlled analgesia pumps enable rapid titration in inpatient oncology units. This mode retains dominance in bone marrow transplant and surgical oncology recovery settings where respiratory monitoring infrastructure exists.
- Transdermal:Fentanyl and buprenorphine patches enable early discharge to homecare with steady-state plasma levels. CMS reimbursement code expansions are accelerating adoption in United States integrated delivery networks.
- Oral:Immediate-release formulations remain standard for breakthrough pain episodes. Abuse-deterrent polymer matrix technologies are inflating per-dose pricing beyond reach of cost-sensitive institutional procurement committees.
- Subcutaneous:Miniaturized MEMS-enabled pumps are bypassing hospital pharmacy intermediaries for home infusion. These devices are gaining traction in German and Dutch ambulatory oncology programs with established remote monitoring infrastructure.
Volume concentration persists in Intravenous delivery. Steepest expansion trajectory belongs to Subcutaneous systems.
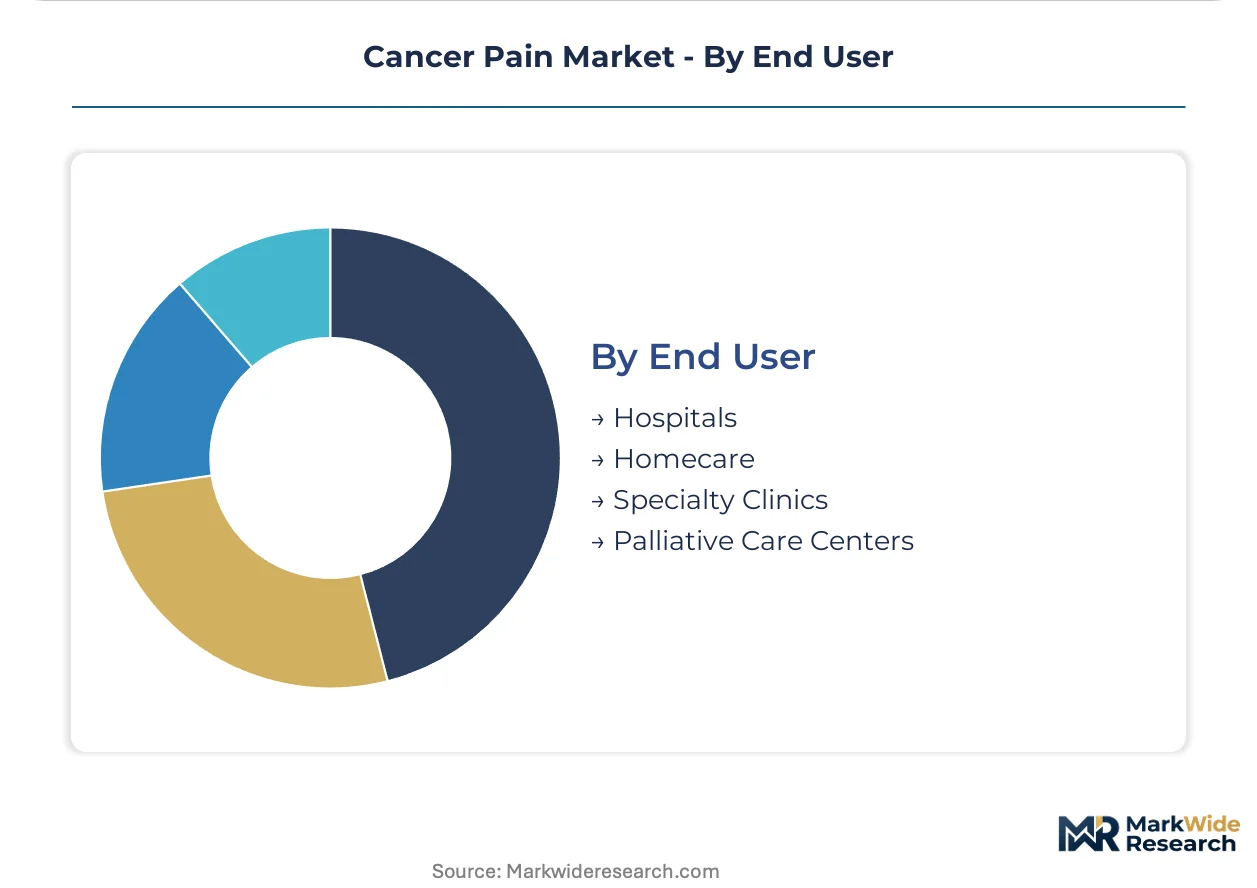
End User:
Site-of-care migration is reallocating purchasing authority from pharmacy benefit managers to clinical pathway committees.
- Hospitals:Inpatient oncology departments anchor formulary decisions through protocol-driven order sets. Stewardship mandates from Joint Commission accreditation requirements are forcing multimodal inclusion in electronic health record workflows.
- Homecare:Early discharge programs are transferring infusion and monitoring responsibilities to family caregivers. Transdermal and subcutaneous modalities are capturing disproportionate growth as reimbursement shifts to ambulatory codes.
- Specialty Clinics:Community oncology practices lack interventional expertise and rely on generalist prescribing. These sites represent untapped penetration opportunity for digital therapeutics requiring minimal infrastructure.
- Palliative Care Centers:Dedicated facilities concentrate expertise in complex symptom management. These centers are piloting outcome-based contracts with manufacturers guaranteeing reduced breakthrough pain episodes.
Procurement authority remains concentrated in Hospitals. Patient volume is migrating fastest toward Homecare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of abuse-deterrent opioid formulations concentrates in the United States and Western Europe, while consumption demand spreads across oncology centers in Asia-Pacific and Latin America where pain management infrastructure remains underdeveloped.
United States
Integrated cancer centers at MD Anderson and Memorial Sloan Kettering anchor multimodal protocol adoption, driving adjuvant medication inclusion in electronic order sets. FDA Risk Evaluation and Mitigation Strategy requirements constrain extended-release opioid prescribing while accelerating investment in non-pharmacological alternatives. The Research Triangle Park corridor in North Carolina hosts contract manufacturing organizations producing polymer matrix technologies for abuse-deterrent generics.
Germany
University hospitals in Heidelberg and Munich pilot closed-loop patient-controlled analgesia systems for bone marrow transplant units, reducing opioid-induced respiratory depression incidents. EMA pharmacovigilance frameworks mandate real-world evidence collection through patient registries and prescriber re-certification cycles. The Baden-Württemberg pharmaceutical cluster specializes in transdermal delivery system manufacturing for export to European ambulatory oncology programs.
Japan
PMDA parallel track approvals for novel non-opioid mechanisms are compressing time-to-market for serotonin-norepinephrine reuptake inhibitors in chemotherapy-induced peripheral neuropathy. METI subsidies support MEMS-enabled subcutaneous pump development for home infusion applications. The Kansai region around Osaka concentrates generic injectable opioid production for domestic hospital procurement and Southeast Asian export tenders.
India
Hyderabad and Ahmedabad contract development and manufacturing organizations attract technology transfer agreements for abuse-deterrent opioid generics targeting emerging market tenders. CDSCO streamlined approval pathways for fixed-dose combination analgesics are expanding formulary access in government cancer hospitals. The Gujarat pharmaceutical corridor specializes in cost-sensitive injectable morphine production for institutional procurement across South Asia and Africa.
Brazil
ANVISA updated essential medicines list revisions are elevating non-opioid mechanisms to first-line status in neuropathic pain syndromes at public oncology institutes. São Paulo's Hospital das Clínicas anchors protocol standardization for multimodal pain management in Latin America. The São Paulo state pharmaceutical cluster manufactures generic adjuvant medications for distribution through Brazil's unified health system regional pharmacies.
Cancer Pain Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and delivery technology vectors. The vendor base organizes into three tiers: global pharmaceutical majors with hospital channel infrastructure, regional generic manufacturers with cost-optimized production, and emerging device developers with digital therapeutics platforms. Consolidation pressure intensifies as procurement committees demand outcome-based contracts bundling drugs with monitoring technologies. Dominant competitive moves include strategic partnerships between drug manufacturers and digital health platforms, plus geographic licensing agreements for abuse-deterrent formulation technologies.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Johnson & Johnson occupy positions spanning both opioid and non-opioid modalities through hospital formulary relationships. Teva Pharmaceutical Industries Ltd. exemplifies the generic-focused archetype with institutional procurement positioning in injectable opioids. These three anchors represent distinct strategic postures: conglomerate diversification, integrated hospital channel control, and cost-driven generic scale.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Purdue Pharma L.P. |
| AstraZeneca plc |
| Mallinckrodt Pharmaceuticals |
| Eli Lilly and Company |
| Grünenthal Group |
| Others |
Supply Flow & Price Mechanics
FDA Risk Evaluation and Mitigation Strategy compliance infrastructure gates qualified supply for extended-release opioid manufacturers while simultaneously restricting premium-tier pricing access to those bearing abuse-deterrent formulation certification. This regulatory filtering concentrates pricing power among polymer matrix technology holders while generic injectable producers compete on procurement committee cost thresholds.
Pricing Analysis
Margin tightening in institutional procurement reflects Joint Commission stewardship mandates forcing multimodal protocol adoption. Three-tier pricing structure across abuse-deterrent branded, standard generic, and economy vial formats dominates hospital formulary negotiations. Price differentiation hinges on REMS certification status and polymer matrix complexity. Cost-down pressure on immediate-release oral formulations accelerates because DEA production quotas constrain supply flexibility. Community oncology practices exhibit highest price sensitivity; integrated cancer centers prioritize outcome-based guarantees over per-dose economics.
Supply Chain Analysis
Specialized workforce availability in Research Triangle Park, Baden-Württemberg, and the Kansai region anchors manufacturing concentration for transdermal and subcutaneous delivery systems. Active pharmaceutical ingredient sourcing draws from Gujarat and Hyderabad for injectable morphine, while polymer matrix feedstocks rest on German chemical cluster output. Single-source vulnerability pervades abuse-deterrent excipient supply. Distribution runs through integrated delivery network pharmacy benefit managers consolidating into oncology clinical pathway committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cancer Pain Market sits in a technology-transition phase where closed-loop patient-controlled analgesia systems displace static prescribing protocols in academic medical centers.
For Market Incumbents: To counter digital therapeutics encroachment on breakthrough pain management, Pfizer Inc. and Johnson & Johnson should deepen hospital channel control through outcome-based contracts bundling opioids with remote monitoring platforms. Backward integration into MEMS sensor supply secures subcutaneous pump manufacturing capacity against device developer competition. For New Entrants and Emerging Players: Launch via direct-to-homecare distribution models targeting family caregiver-managed infusion in markets with established remote monitoring infrastructure. Community oncology practices represent the most penetrable segment given specialist workforce scarcity and limited interventional expertise. White-space exists in digital biomarker platforms for chemotherapy-induced peripheral neuropathy where FDA breakthrough device designation opens reimbursement pathways. For Investors and Strategic Acquirers: FDA parallel track approval for novel non-opioid mechanisms is the leading indicator that serotonin-norepinephrine reuptake inhibitor portfolios warrant long-term viability framing. Acquisition targets should display MEMS-enabled delivery technology or virtual reality distraction platform assets. Watch for REMS modification announcements as formulary access inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop PCA System Deployment | Mayo Clinic pilots reduce nursing handoff errors in bone marrow transplant units. |
| Abuse-Deterrent Formulation Licensing | Polymer matrix technology transfers to Indian CDMOs target emerging market tenders. |
| Digital Therapeutics Reimbursement Strategy | Cedars-Sinai virtual reality platforms capture CMS code expansion for non-pharmacological modalities. |
| Multimodal Protocol Bundle Contracts | Memorial Sloan Kettering consolidates procurement through outcome-based analgesic guarantees. |
| Subcutaneous Pump Miniaturization | German ambulatory oncology programs adopt MEMS-enabled home infusion bypassing hospital pharmacy. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and palliative care nurse practitioners. FDA REMS documentation, EMA pharmacovigilance frameworks, DEA production quota disclosures, and hospital procurement databases supplied quantitative validation. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation cross-verified segment sizing.
Reconciliation of prescription volume data, reimbursement code expansions, and clinical trial enrollment figures supported CAGR derivation across the projection horizon. Segmentation dimensions spanned product type, therapy area, delivery mode, and end-user site-of-care migration. Modeled inputs incorporated WHO analgesic ladder protocol adoption rates, stewardship mandate implementation timelines, and interventional training pipeline capacity constraints.
REMS modification timing, DEA quota allocation shifts, and digital therapeutics FDA designation velocity are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
OTC Painkiller Market
Pain Management
Visceral Pain Market
Pain Management
Postoperative Pain Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Neuropathic Pain Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Cancer Pain Management Market
Pain Management
Spine Pain Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Cluster Headache Market