
 Vial Adaptors for Reconstitution Drug Market | 2026-2036
Vial Adaptors for Reconstitution Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Vial Adaptors for Reconstitution Drug Market Intelligence
The capability gap between integrated system manufacturers and component-only suppliers is collapsing the market into distinct performance tiers. West Pharmaceutical Services specializes in advanced containment and delivery systems, integrating adaptors with its proprietary vial technologies. Becton Dickinson leverages its vast manufacturing scale and distribution network within hospital settings. B. Braun competes with a broad portfolio of drug administration products, including a variety of needleless adaptors for different therapy areas.
Vial adaptors for reconstitution drugs are sterile medical devices designed to transfer liquid diluents into vials of lyophilized medication. These devices, often made from medical-grade polycarbonate or copolyester, ensure a closed system to prevent contamination and needlestick injuries. Needleless adaptors represent the fastest-growing product type due to enhanced safety protocols for healthcare workers. The oncology therapy area commands the largest share, driven by the high volume of injectable chemotherapy agents requiring reconstitution before administration.
Regulatory oversight from bodies like the US FDA and the European Medicines Agency (EMA) dictates stringent standards for material biocompatibility and sterility. In China, NMPA approval processes for Class II medical devices govern market access for new adaptor designs. Navigating these varied international requirements for device-drug combination product submissions remains a critical challenge for manufacturers seeking to serve multiple regions.
Market Dynamics
The market's central dynamic is the convergence of stringent healthcare worker safety regulations and the proliferation of high-value lyophilized biologics. This forces a move away from traditional reconstitution methods towards closed-system transfer devices to protect both personnel and expensive drug products.
Growth Catalysts
- Advanced Polymers:The development of new copolyester and medical-grade polycarbonate formulations enhances chemical compatibility with aggressive chemotherapy agents, improving device reliability and safety in oncology settings.
- Home Infusion Expansion:A rising preference for administering therapies, including biologics and immunoglobulins, in home-care settings drives demand for user-friendly, safe reconstitution devices for patients and non-specialist caregivers.
- Occupational Safety Mandates:Regulations like Germany's TRGS 525 and guidance from the US National Institute for Occupational Safety and Health (NIOSH) promote the use of closed-system transfer devices, directly boosting adaptor adoption.
Market Restraints
- Cost Pressures:The higher per-unit cost of advanced needleless vial adaptors compared to traditional needles and syringes remains a significant adoption barrier for hospitals and clinics in price-sensitive healthcare systems.
- Substitution by Ready-to-Use Drugs:Pharmaceutical manufacturers are increasingly developing ready-to-use liquid formulations or pre-filled syringes for biologics, which eliminates the need for reconstitution and the associated adaptor market.
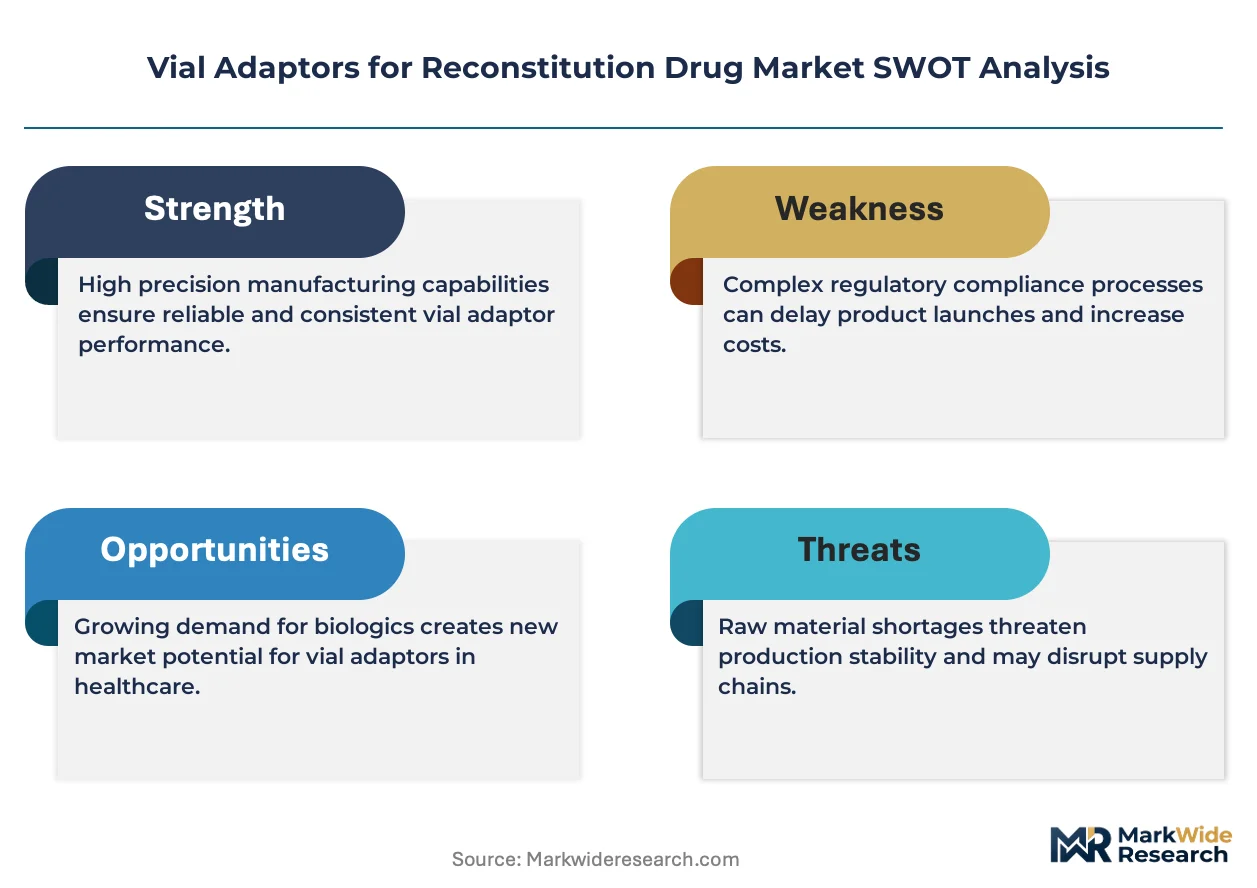
- Device-Drug Compatibility Hurdles:Stringent testing protocols required by regulators like the EMA and FDA to validate the compatibility of an adaptor with a specific drug create lengthy and costly development cycles for manufacturers.
Strategic Opportunities
- Emerging Market Penetration:Healthcare infrastructure upgrades and rising safety standards in countries like Brazil and India present significant growth opportunities for vial adaptor manufacturers as hospitals adopt more advanced practices.
- Cell and Gene Therapy Applications:Designing specialized adaptors for the unique handling and sterility requirements of cell and gene therapies offers a high-value niche, as these treatments often involve complex, small-batch reconstitution.
- Digital Integration:Incorporating features like RFID tags or QR codes into adaptors to enable digital tracking and administration verification aligns with the broader hospital trend of medication management system digitalization.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face significant operational burdens in navigating disparate regulatory submission requirements for device-drug combination products across the US FDA, European EMA, and Chinese NMPA.
- Polymer Supply Chain Volatility:The reliance on a concentrated number of suppliers for specialty medical-grade polymers, such as polycarbonate, exposes device manufacturers to price fluctuations and potential supply disruptions.
- Interoperability Requirements:Ensuring a single adaptor design is compatible with the vast array of vial neck diameters, stopper thicknesses, and syringe types used globally presents a persistent engineering and quality assurance challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vial Adaptors for Reconstitution Drug Market |
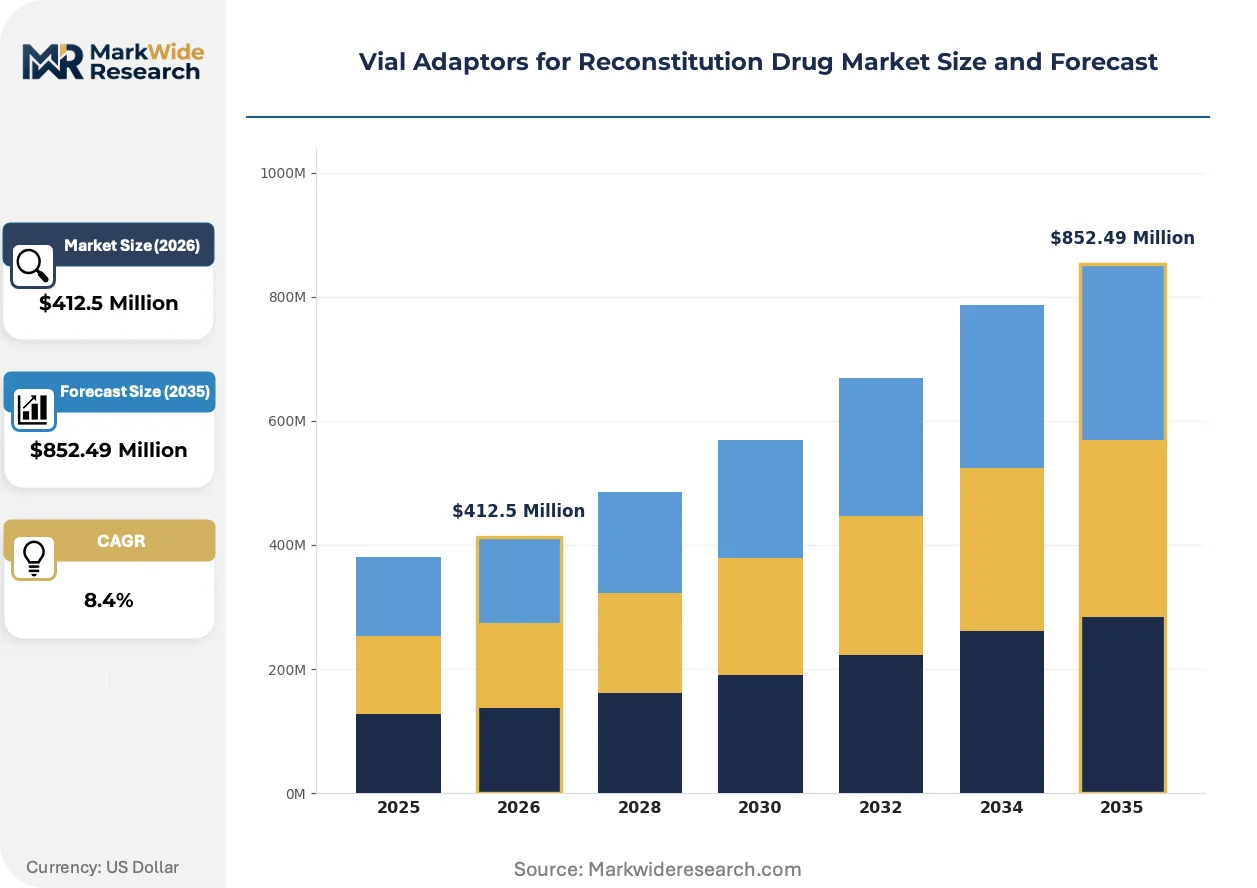
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luer Lock Adaptors, Spike Adaptors, Needleless Adaptors, Winged Adaptors, Screw Cap Adaptors Therapy Area: Oncology, Infectious Diseases, Endocrinology, Neurology, Immunology, Hematology End User: Hospitals, Specialty Clinics, Home Healthcare Providers, Pharmacies, Diagnostic Centers Packaging Type: Single-Use Blister Packs, Multi-Unit Boxes, Sterile Pouches, Bulk Packs |
| Companies Covered | Becton Dickinson, B. Braun, West Pharmaceutical Services, Simplivia Healthcare, Cardinal Health, Baxter International, EQUASHIELD LLC, Vygon SA, Miltenyi Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vial Adaptors for Reconstitution Drug Market Strategic Shifts & Innovations
The market is defined by a push toward integrated systems that enhance safety, traceability, and efficiency in medication preparation. Innovation focuses not just on the physical device but on its role within a connected and automated pharmacy workflow, especially for high-risk oncology drugs.
Integration of digital identifiers like RFID tags and 2D barcodes into the adaptor body is a key innovation. Hospital pharmacies are adopting these devices to automate drug tracking, verify dosage, and reduce manual data entry errors. This digitally-enabled hardware is supplanting passive, non-traceable plastic components in high-value oncology and specialty biologic workflows.
The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance requirements on all medical devices, including vial adaptors. This regulation forces manufacturers to generate more extensive data on device performance, material biocompatibility, and long-term safety. The oncology segment is most affected, as devices used with hazardous drugs now face the highest level of regulatory scrutiny under MDR.
Consolidated purchasing by large Group Purchasing Organizations (GPOs) and Integrated Delivery Networks (IDNs) is altering procurement patterns. These powerful buyers are shifting from single-component purchasing towards contracts for bundled drug delivery systems that include vials, adaptors, and administration sets from a single or pre-qualified set of vendors. This trend is most prominent in the United States healthcare market, where it favors suppliers with broad product portfolios.
Vial Adaptors for Reconstitution Drug Market Segmentation
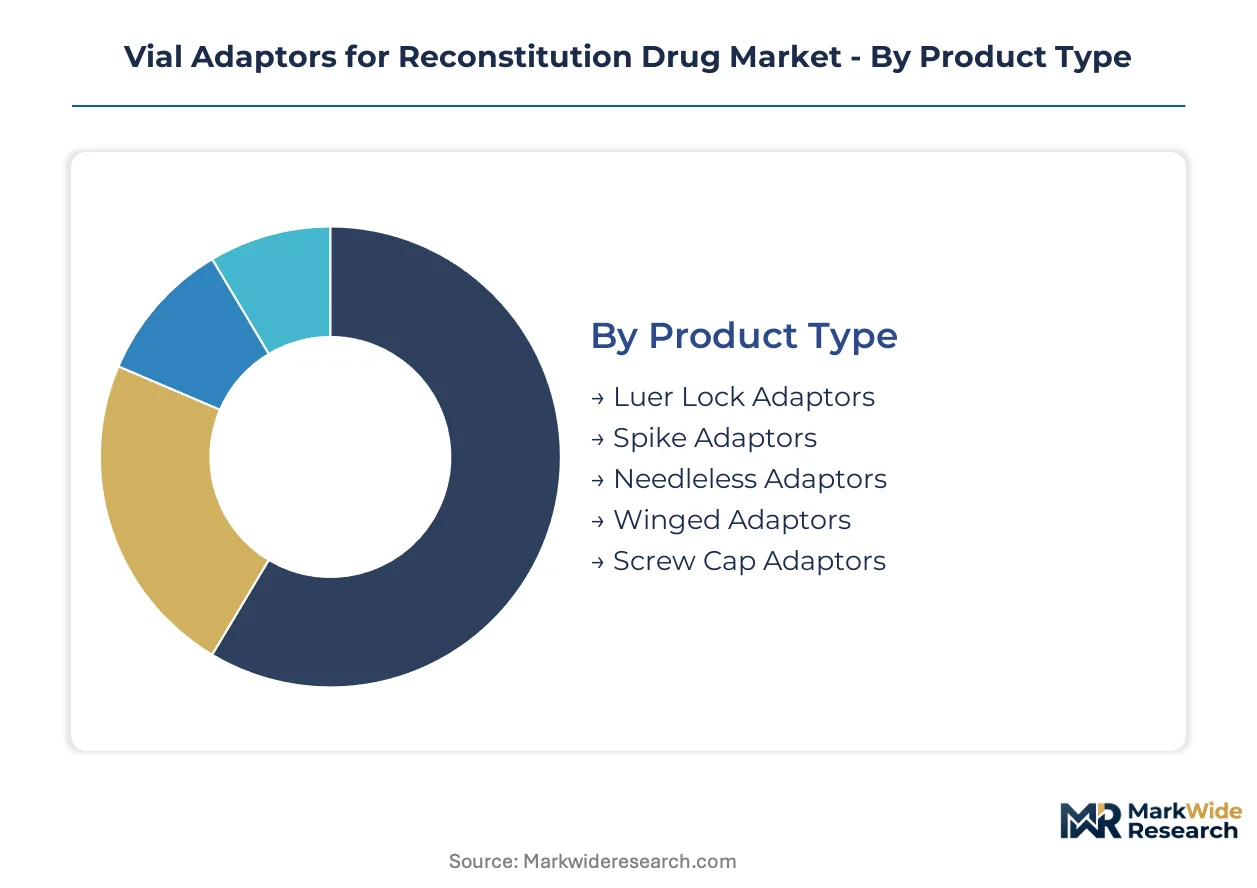
The Vial Adaptors for Reconstitution Drug Market segments into distinct categories reflecting varied user needs, safety protocols, and therapeutic applications. Understanding these segments reveals how device design and material science advancements address critical challenges in medication preparation and administration. Each segment addresses specific operational requirements across different healthcare settings.
Product Type:
The global distribution patterns for vial adaptors show different product types gaining traction based on regional safety mandates and healthcare infrastructure maturity.
- Needleless Adaptors:These devices incorporate a blunt cannula or a valved connection, eliminating the sharp needle entirely to prevent needlestick injuries for healthcare workers. Demand for these adaptors is surging in developed healthcare systems like Germany and the United States, driven by stringent occupational safety regulations and a focus on infection control.
- Luer Lock Adaptors:Designed with a secure threaded connection, Luer Lock adaptors provide a leak-proof interface between the vial and a Luer-compatible syringe or infusion line. Their widespread use in hospital settings across Europe and North America reflects established standards for secure drug transfer during reconstitution.
- Spike Adaptors:These adaptors feature a sharp spike that pierces the vial stopper, facilitating drug withdrawal or diluent addition.
- Winged Adaptors:Equipped with side wings for easier handling and stability, these adaptors improve grip during reconstitution, particularly in busy clinical environments.
- Screw Cap Adaptors:Designed to securely fasten onto vials with screw-thread finishes, these adaptors ensure a tight seal for specialized drug formulations.
Luer Lock Adaptors command the established base. The steepest expansion runs through Needleless Adaptors.
Therapy Area:
Adaptor selection varies significantly across different therapy areas, driven by drug characteristics, administration frequency, and patient safety considerations.
- Oncology:This segment represents the largest share, primarily due to the high volume of injectable chemotherapy agents that require precise reconstitution from lyophilized forms. Specialized adaptors for oncology drugs prioritize chemical compatibility with aggressive agents and enhanced protection against hazardous drug exposure for clinicians.
- Immunology:Vial adaptors for immunology applications, including biologics and immunoglobulins, focus on maintaining drug integrity during reconstitution for sensitive protein-based therapies. Their use is critical for treatments administered in both clinical and expanding home-care settings, ensuring sterile transfer.
- Infectious Diseases:Adaptors for infectious disease treatments facilitate the safe reconstitution of antibiotics and antiviral agents, often in acute care settings.
- Endocrinology:These adaptors support the preparation of hormone therapies and other endocrine-related medications, which frequently involve multi-dose vials.
- Neurology:Adaptors in neurology assist with reconstituting medications for neurological disorders, where precise dosing and sterile conditions are paramount.
- Hematology:This area utilizes adaptors for blood-related therapies, including clotting factors and other specialized agents requiring careful handling.
Oncology applications drive the largest volume, while the increasing complexity of biologic therapies expands requirements across immunology and hematology.
End User:
Different end-user segments exhibit distinct purchasing patterns and require adaptors tailored to their operational workflows and patient care models.
- Hospitals:Hospitals represent the primary end-user segment, procuring adaptors in large volumes for centralized pharmacy operations and bedside administration across diverse departments. Their demand is influenced by bulk purchasing agreements and the need for devices compatible with a wide range of drug formulations.
- Home Healthcare Providers:This rapidly expanding segment requires user-friendly and highly safe adaptors for administration by non-specialist caregivers or patients themselves. The focus here is on simplifying reconstitution processes for therapies like immunoglobulins and certain biologics outside traditional clinical environments.
- Specialty Clinics:These clinics, often focusing on oncology or rheumatology, demand adaptors that meet specific safety standards for hazardous drug handling.
- Pharmacies:Retail and compounding pharmacies utilize adaptors for preparing custom formulations and dispensing reconstituted medications to outpatients.
- Diagnostic Centers:While less prominent, diagnostic centers use adaptors for preparing contrast agents or other diagnostic substances requiring reconstitution.
Hospitals remain the foundational market, but the shift towards decentralized patient care elevates the significance of Home Healthcare Providers.
Packaging Type:
The choice of packaging for vial adaptors reflects varying needs for sterility, inventory management, and ease of access in clinical settings.
- Single-Use Blister Packs:These individual, sterile blister packs ensure aseptic presentation of each adaptor, critical for preventing contamination in sensitive drug reconstitution processes. They are widely adopted in oncology and immunology settings where sterility is paramount for patient safety.
- Multi-Unit Boxes:Multi-unit boxes contain multiple adaptors, often individually wrapped or in smaller sterile pouches, offering a balance between cost-effectiveness and maintaining sterility for high-volume users. Hospitals and large clinics frequently prefer this packaging for efficiency.
- Sterile Pouches:These flexible, sealed pouches provide a sterile barrier for individual adaptors, suitable for settings requiring quick access and minimal waste.
- Bulk Packs:Designed for cost-efficiency, bulk packs contain a large quantity of non-sterile adaptors intended for further processing or use in less critical applications.
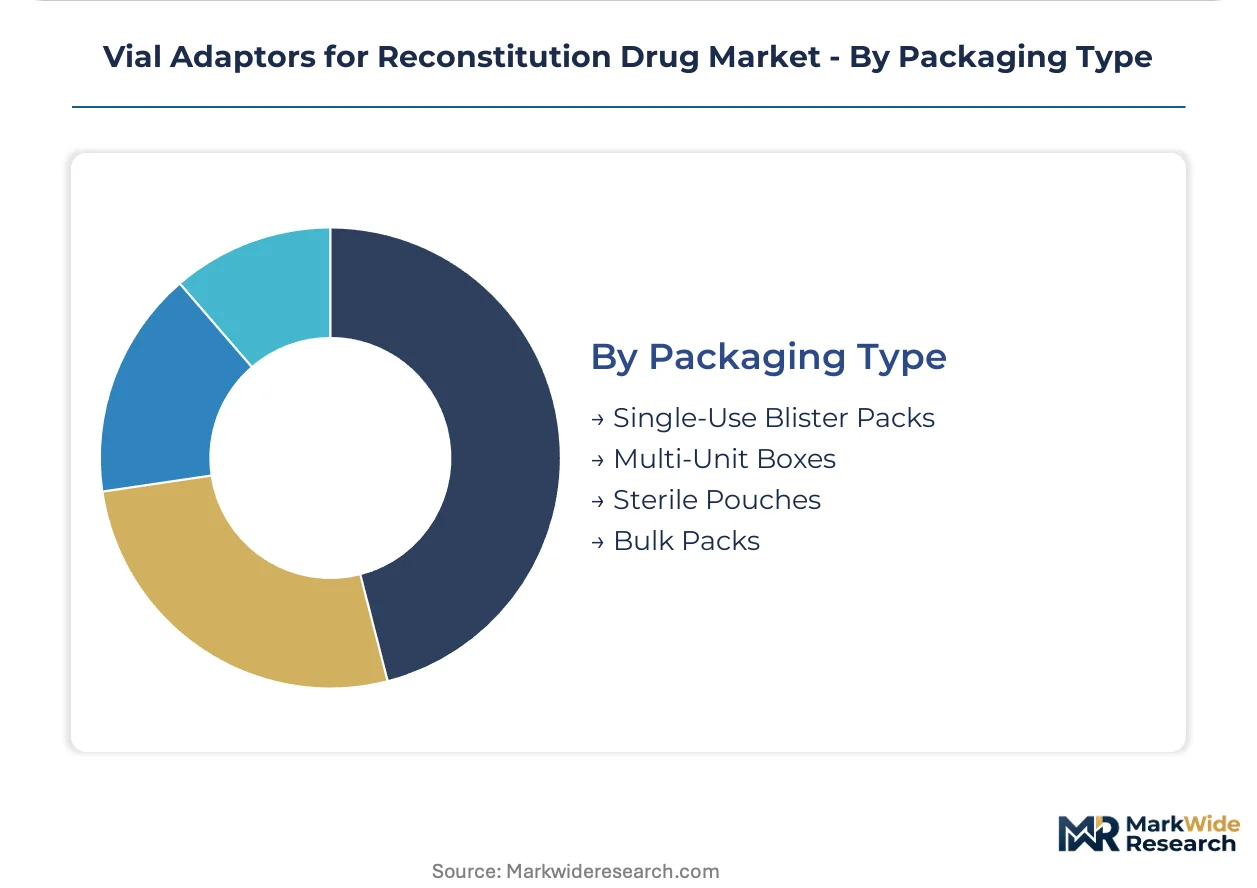
Single-Use Blister Packs prioritize individual sterility, while Multi-Unit Boxes optimize for procurement efficiency in high-volume environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for vial adaptors exhibits varying elasticity across regions, with highly developed healthcare systems prioritizing advanced safety features over cost. Conversely, price sensitivity remains a significant factor in emerging markets, influencing the adoption rate of premium needleless adaptors. This dichotomy shapes market penetration strategies globally.
United States
Demand for needleless adaptors in the United States stems from stringent occupational safety mandates and complex biologic therapies. The US FDA's emphasis on device-drug combination product safety drives innovation. Major pharmaceutical hubs like Boston and San Francisco foster research into specialized adaptors for advanced therapeutics.
Germany
Germany's advanced healthcare infrastructure and high standards for medication safety fuel closed-system transfer device adoption. Regulations like TRGS 525 promote safer reconstitution methods, reducing healthcare worker exposure. The Rhine-Main region, a key pharmaceutical cluster, develops integrated drug delivery systems.
Japan
Japan experiences growing demand for user-friendly adaptors due to an aging population and complex drug regimens. The PMDA ensures rigorous approval processes for medical devices, emphasizing sterility. Osaka, a prominent biomedical research center, focuses on designing adaptors for sensitive biologics.
China
China's expanding healthcare infrastructure and rising safety standards drive increased adoption of advanced vial adaptors. NMPA approval processes for Class II medical devices govern market access. Shanghai's biomedical parks are becoming centers for local manufacturing of cost-effective, safe reconstitution solutions.
India
India's pharmaceutical manufacturing growth and upgrading hospital facilities increase the need for sterile, efficient reconstitution devices. The CDSCO oversees medical device regulations, pushing for improved quality. Hyderabad, a major pharmaceutical hub, sees investments in local production of vial adaptors to meet domestic demand.
Vial Adaptors for Reconstitution Drug Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure for vial adaptors. The market exhibits consolidation among established medical device manufacturers, while smaller innovators target niche applications. Strategic archetypes include integrated system providers, specialized component manufacturers, and regional suppliers. Companies often pursue portfolio diversification and strategic partnerships to strengthen their market positions.
At the scale-driven end, Becton Dickinson leverages its vast manufacturing scale and distribution network within hospital settings, representing a major player in standardized adaptors. This firm's extensive reach allows for broad market penetration across diverse healthcare environments. West Pharmaceutical Services exemplifies an integrated system provider, specializing in advanced containment and delivery systems that combine adaptors with proprietary vial technologies, focusing on high-value biologics. B. Braun occupies a position as a comprehensive drug administration product supplier, offering a broad portfolio including various needleless adaptors for different therapy areas, catering to a wide range of clinical needs.
| Leading Market Players |
|---|
| Becton Dickinson |
| B. Braun |
| West Pharmaceutical Services |
| Simplivia Healthcare |
| Cardinal Health |
| Baxter International |
| EQUASHIELD LLC |
| Vygon SA |
| Miltenyi Biotec |
Cost & Logistics Intelligence
Economies of scale in medical-grade polymer production strongly influence the supply concentration of vial adaptor components and establish competitive price floors. This dynamic shapes how manufacturers source materials and distribute finished products globally.
Pricing Analysis
After-sales service and integrated system support drive lifetime value for advanced vial adaptors, particularly in complex oncology workflows. The dominant pricing model remains per-unit transactional, often influenced by long-term contract-based offtake agreements with large Group Purchasing Organizations. Price differentiation stems from certification levels, such as FDA or EMA approvals, and the volume scale of procurement. Pricing softness stems from intense cost pressures from hospital systems in price-sensitive healthcare environments. Hospitals in emerging markets exhibit high price sensitivity, while specialty oncology clinics prioritize safety features over cost.
Supply Chain Analysis
Reliance on a concentrated number of suppliers for specialty medical-grade polymers, such as polycarbonate and copolyester, presents a critical chokepoint. Geographic supply concentration for these materials centers on a few specialized chemical manufacturers globally, with downstream fabrication occurring in countries like China, Germany, and the United States. Raw material dependencies include medical-grade polycarbonate and advanced copolyester formulations. Polymer supply chain volatility represents a structural risk due to potential single-source vulnerabilities and price fluctuations. Distribution runs through direct sales channels to large hospital networks and medical device distributors for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vial Adaptors for Reconstitution Drug Market is experiencing an early-cycle expansion, primarily driven by the increasing adoption of high-value lyophilized biologics and stringent safety regulations.
For Market Incumbents:Shield core market share by deepening integration with proprietary vial technologies, offering comprehensive drug delivery systems that minimize interoperability challenges. Expand broad product portfolios to cater to diverse therapy areas, countering the threat of specialized new entrants. Invest in advanced polymer research to enhance compatibility with aggressive chemotherapy agents, securing long-term regulatory compliance and market leadership. Leverage extensive distribution networks and GPO contracts to maintain competitive pricing and market penetration.
For New Entrants and Emerging Players:Service-layer gaps in digital integration and specialized therapeutic niches offer significant entry points. Target the cell and gene therapy segment, designing adaptors for complex, small-batch reconstitution with unique sterility requirements. Emerging markets like India and Brazil present penetrable geographies due to upgrading healthcare infrastructure and rising safety standards. A go-to-market angle focusing on user-friendly, digitally-enabled devices for home care settings can differentiate offerings.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors companies with strong intellectual property in advanced materials or digital integration capabilities. Long-term viability remains robust over the next 5-10 years, supported by persistent growth in biologics and increasing safety mandates. Acquisition targets should include niche innovators specializing in adaptors for cell and gene therapies or firms with established digital tracking solutions. The signal to watch is the accelerated adoption of closed-system transfer devices across new therapeutic areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Acceleration | Streamlines market access for advanced adaptors across key regions like the US and EU. |
| Product Launch (Digital Integration) | Introduces smart adaptors with RFID/QR codes, enhancing medication traceability and safety. |
| Strategic Partnership (GPOs) | Secures high-volume procurement contracts, ensuring stable demand and market presence. |
| Capacity Expansion (Emerging Markets) | Addresses rising demand from upgrading hospital facilities in countries such as India and Brazil. |
| R&D Investment (Advanced Polymers) | Enhances chemical compatibility with complex biologics, improving device reliability and safety. |
Research Approach
A standing panel of clinicians, pharmacists, medical device engineers, and GPO representatives provided ongoing calibration and validation for the market insights. Primary interviews with these industry stakeholders were combined with rigorous secondary data validation. Secondary sources included US FDA filings, European Medicines Agency submissions, and NMPA approval databases, alongside specialized medical device industry reports. This approach ensured a robust bottom-up and top-down triangulation of market data.
Outputs were validated against external benchmarks and existing market intelligence to ensure consistency and accuracy across the analysis window. The analytical framework modeled market segmentation across product type, therapy area, end user, packaging type, and regional regulatory cluster. Compound annual growth rates were derived from historical data trend analysis and future market growth projections. Key forecast inputs included the global lyophilized drug pipeline and updates to healthcare worker safety regulations.
Forecasts assume regulatory continuity in regimes like the US, EU, and China; material policy shifts would require re-modeling. This analysis reflects assumptions regarding the continued expansion of biologics and increasing focus on healthcare worker safety. Practitioners should keep alternative scenarios live as drug formulation trends and polymer supply dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Automated Drug Kiosk Market