
 Flexible Manufacturing Systems for Pharmaceutical Industry Market | 2026-2036
Flexible Manufacturing Systems for Pharmaceutical Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Manufacturing Systems for Pharmaceutical Industry Market Foresight
Germany is rewriting capacity expectations for pharmaceutical flexible manufacturing through its cluster of engineering specialists serving multi-product biologics facilities. Thermo Fisher Scientific leverages integrated automation portfolios to sustain competitive positioning across North American and European installations. Lonza Group AG anchors its reputation on single-use technology leadership for contract biologics manufacturing. Cytiva competes through deep specialization in chromatography and filtration modules that plug into larger flexible system architectures.
Flexible manufacturing systems for pharmaceutical production integrate programmable hardware with software-controlled process orchestration to enable rapid changeover between drug products without full facility revalidation. These systems typically employ single-use bioreactors, automated guided vehicles, and distributed control architectures maintaining closed processing environments from formulation through fill-finish. Continuous manufacturing systems represent the fastest-expanding technology segment as oral solid dosage producers pursue real-time release testing and reduced footprint operations. Modular control platforms capture concentrated margin pools because their software layers lock in recurring service revenues and regulatory documentation packages. Robotic automation dominates physical throughput in packaging and material handling applications where repeatability requirements exceed human precision thresholds.
The FDA's quality-by-design initiative and EU GMP Annex 15 on qualification and validation shape system architecture requirements by mandating documented process understanding for every intended product changeover. Germany's KBA-equivalent pharmaceutical regulator and Health Canada's ICH Q9 quality risk management guidelines further constrain acceptable automation configurations for facilities exporting into multiple jurisdictions. Stakeholders must monitor how emerging AI-guided process analytical technology integrations trigger new software validation precedents from the FDA and EMA.
Market Dynamics
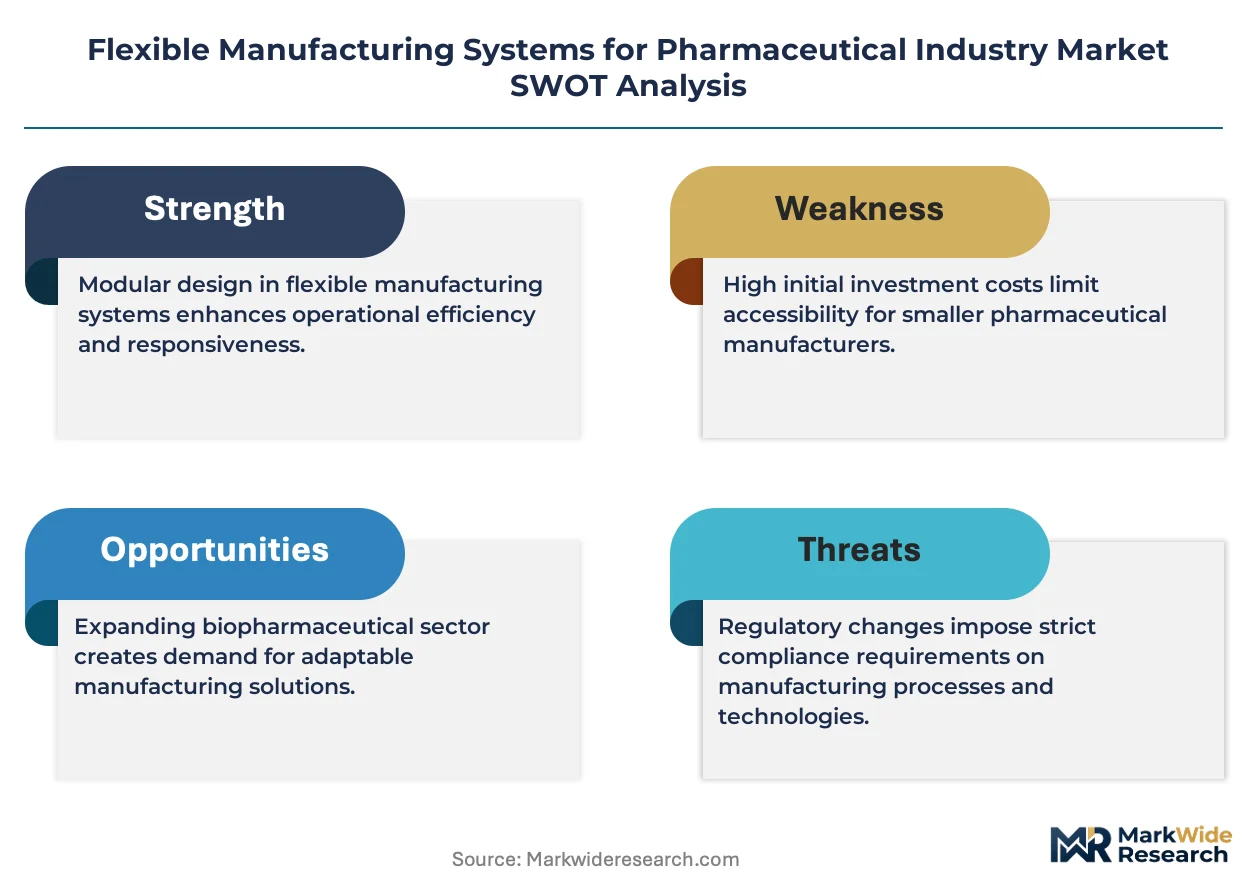
Continuous processing architectures are compressing facility footprints while forcing wholesale revalidation of batch-based quality systems across oral solid dosage and biologics manufacturing.
Growth Catalysts
- EU GMP Annex 15 Revisions:Updated qualification mandates for multi-product facilities accelerate replacement of fixed stainless steel trains with modular single-use platforms.
- Personalized Medicine Pipelines:Cell and gene therapy developers require micro-batch flexibility that only distributed control architectures can deliver at commercial scale.
- Real-Time Release Testing:Process analytical technology integration enables parametric release, eliminating quarantine inventory and accelerating working capital velocity.
Market Restraints
- Stainless Steel Residual Value:Sunk capital in traditional bioreactor infrastructure creates accounting drag on facility retrofit decisions.
- Filtration Membrane Supply Concentration:Three suppliers dominate high-performance tangential flow filtration cassettes, exposing capacity planning to single-source risk.
- FDA Software Validation Burden:21 CFR Part 11 compliance for configurable distributed control systems extends commissioning timelines by eight to fourteen months.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Maharashtra and Telangana lack flexible containment infrastructure for potent compound handling.
- AI-Driven Process Control:Machine learning modules for predictive bioreactor optimization remain pre-competitive white space outside chromatography applications.
- Prefabricated Modular Facilities:Skid-mounted cleanroom pods reduce construction duration from thirty-six to eighteen months for greenfield biologics sites.
Industry Challenges
- Automation Engineering Talent Scarcity:Programmers competent in both ISA-88 batch standards and pharmaceutical GMP command premium compensation that strains mid-tier facility budgets.
- Legacy SCADA Integration Friction:Proprietary communication protocols from 1990s-vintage distributed control systems resist interoperability with modern manufacturing execution systems.
- Cross-Contamination Documentation Burden:Cleaning validation for antibody-drug conjugate changeovers requires residue detection limits below one microgram per square centimeter.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Manufacturing Systems for Pharmaceutical Industry Market |
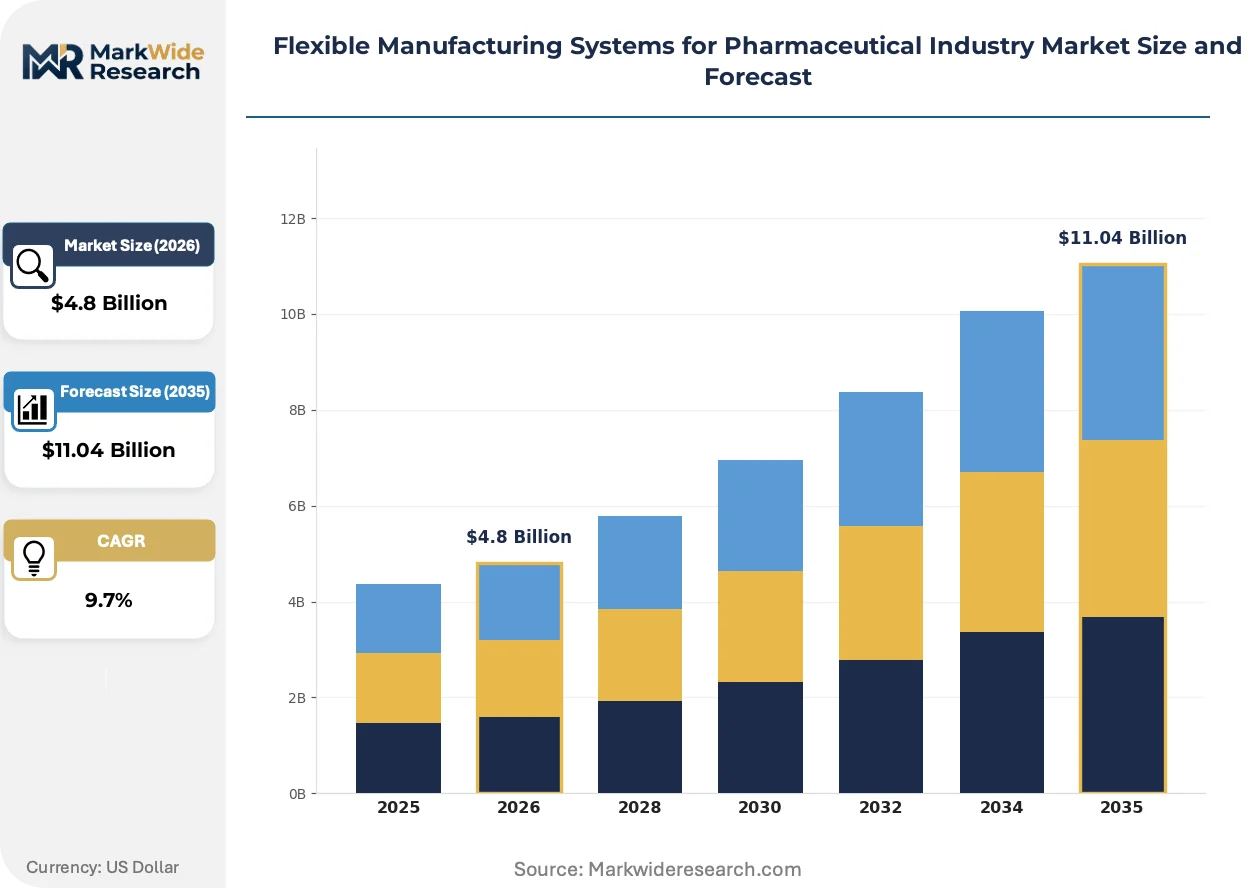
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Robotic Automation, Modular Control, Batch Processing, Continuous Manufacturing, Conveyor Systems Technology: CNC Machines, Programmable Logic Controllers, SCADA, MES, Vision Systems Use Case: Formulation, Packaging, Quality Inspection, Material Handling, Labeling End User: Contract Development, Biologics Manufacturers, Generic Producers, API Manufacturers, Biosimilar Companies |
| Companies Covered | G-CON Manufacturing, Germfree Laboratories Inc., Cytiva, Thermo Fisher Scientific Inc., Lonza Group AG, Jacobs Engineering Inc., KeyPlants AB, Catalent Inc., Exyte GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Manufacturing Systems for Pharmaceutical Industry Market Shifts & Advancements
Digitization of batch records and migration toward autonomous process control are collapsing the boundary between quality assurance and manufacturing operations.
Single-use bioreactor technology is hybridizing with traditional stainless steel infrastructure as mid-scale manufacturers pursue hybrid facilities that split seed train operations from production bioreactors. Biologics contract manufacturers in Germany and Switzerland are adopting this architecture fastest, driven by multi-product campaign requirements. The resulting capital efficiency is compressing facility breakeven thresholds from twelve campaigns annually to six.
EMA's draft guideline on decentralized manufacturing for cell therapies is forcing regulators to confront distributed production models where cryopreserved intermediates ship between processing nodes. The guidance creates precedent for validating discontinuous supply chains rather than fixed-site facilities. Autologous therapy developers in the Netherlands and Spain are piloting the first compliant network configurations.
Buyer consolidation among top-twenty pharmaceutical manufacturers is concentrating procurement leverage and forcing equipment vendors to unbundle hardware from service contracts. Mid-sized CDMOs in Ireland and Singapore now purchase automation platforms through third-party systems integrators rather than direct OEM relationships. This channel shift is compressing vendor margins while expanding implementation risk for buyers lacking internal validation expertise.
Flexible Manufacturing Systems for Pharmaceutical Industry Market Segmentation
Flexible manufacturing systems fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct procurement patterns and margin structures that shape vendor strategy and facility investment decisions.
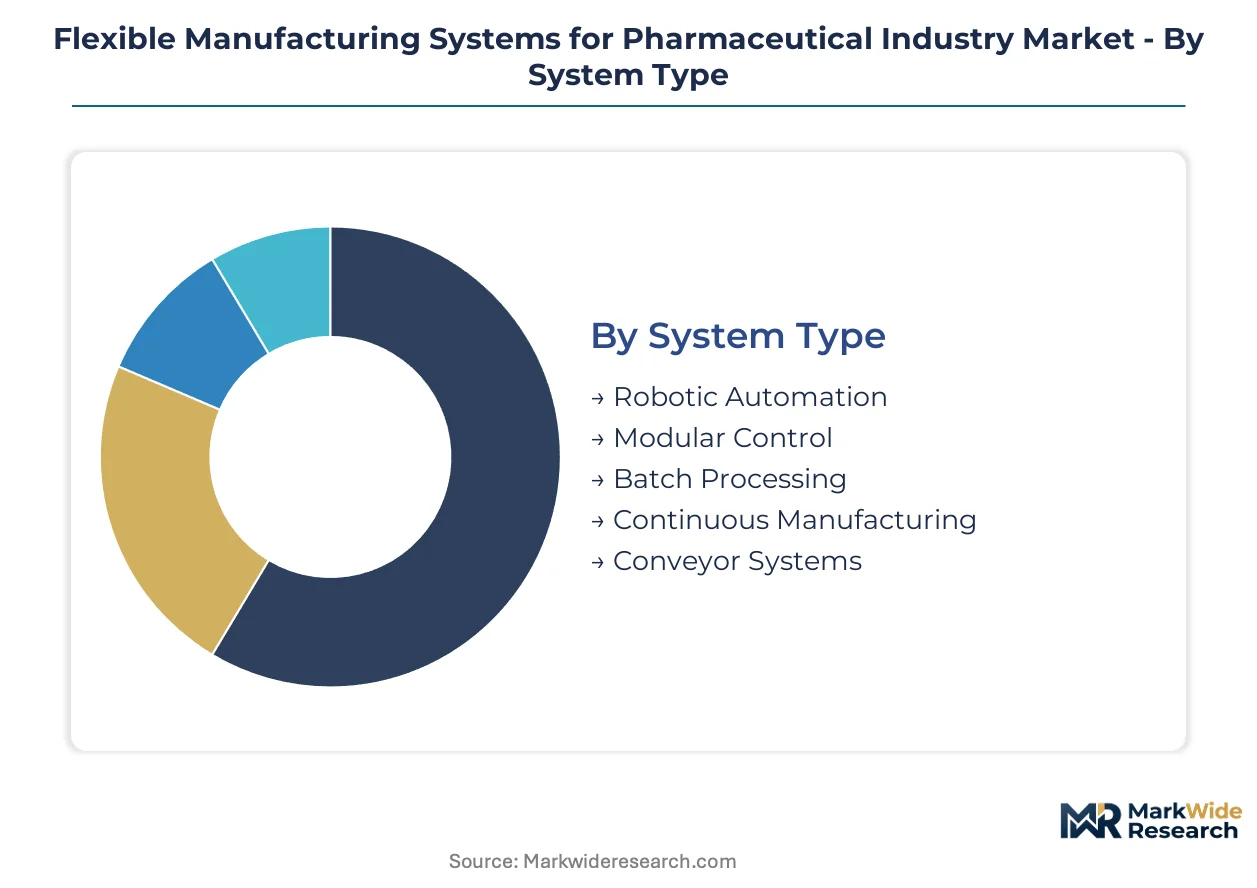
System Type:
Cost tier determines capital deployment sequencing and payback horizons across pharmaceutical facilities.
- Robotic Automation:Articulated and collaborative robots execute pick-and-place, aseptic filling, and packaging operations with repeatability below 0.1 millimeters. Demand concentrates in Germany and Switzerland where labor costs and batch integrity requirements exceed human capability thresholds.
- Modular Control:Distributed control platforms with ISA-88 batch management enable rapid reconfiguration of unit operations without hardware replacement. Biologics manufacturers in Basel and Boston deploy these systems to compress campaign changeover intervals from weeks to days.
- Batch Processing:Traditional stainless steel and hybrid single-use trains remain prevalent in generic oral solid dosage facilities.
- Continuous Manufacturing:Direct compression and hot-melt extrusion systems integrate real-time release testing for oral solid dosage forms.
- Conveyor Systems:Automated guided vehicles and track-based transport manage material flow between isolated processing suites.
Modular control commands the established base. The steepest expansion runs through continuous manufacturing.
Technology:
Application specificity drives technology selection, with process criticality determining validation depth and service contract attachment rates.
- SCADA:Supervisory control and data acquisition layers aggregate sensor data from distributed unit operations into centralized visualization dashboards. FDA 21 CFR Part 11 compliance requirements extend commissioning timelines, creating recurring service revenue pools for systems integrators.
- MES:Manufacturing execution systems bridge ERP planning layers with shop-floor control, enforcing electronic batch records and deviation management. Biologics facilities in Ireland and Singapore prioritize MES deployments to satisfy EMA and Health Canada audit requirements for multi-product campaigns.
- Programmable Logic Controllers:Industrial controllers execute discrete logic for valve manifolds and pump sequences.
- CNC Machines:Computer numerical control systems machine tooling and containment hardware for personalized medicine batches.
- Vision Systems:Machine learning-enabled cameras inspect vial seals, label placement, and particulate contamination.
MES anchors current procurement budgets. Vision systems are climbing the fastest as AI inspection modules mature.
Use Case:
Volume scale and regulatory exposure vary dramatically across pharmaceutical manufacturing stages, fragmenting equipment specifications.
- Formulation:Mixing, granulation, and blending operations require contained processing for potent compounds. Demand clusters in Germany and Switzerland where antibody-drug conjugate pipelines drive investment in isolator-based flexible suites.
- Quality Inspection:Automated visual and analytical testing replaces manual sampling for parametric release. Contract manufacturers in Ireland deploy inspection systems to satisfy FDA real-time release testing expectations for export batches.
- Packaging:Serialization and aggregation systems integrate track-and-trace compliance.
- Material Handling:Automated storage and retrieval systems manage temperature-controlled intermediates.
- Labeling:Print-and-apply systems manage multilingual packaging for multi-jurisdiction distribution.
Formulation retains the largest installed base. Quality inspection is gaining share fastest as process analytical technology matures.
End User:
Customer type dictates procurement sophistication, with contract manufacturers demanding rapid reconfiguration and biologics specialists prioritizing closed processing.
- Biologics Manufacturers:Monoclonal antibody and recombinant protein producers require single-use bioreactor trains with automated seed transfer. Facilities in Germany and Massachusetts lead adoption of modular cleanroom pods to accommodate multi-product campaign volatility.
- Contract Development:CDMOs serving early-phase pipelines prioritize equipment mobility and rapid changeover over throughput maximization. Operations in India and Singapore source prefabricated skids to compress facility qualification timelines.
- Generic Producers:Cost-pressured manufacturers seek hybrid batch-continuous systems for oral solid dosage.
- API Manufacturers:Active pharmaceutical ingredient suppliers deploy flexible containment for high-potency compounds.
- Biosimilar Companies:Follow-on biologics producers replicate innovator process architectures with single-use equivalents.
Biologics manufacturers anchor technology roadmaps. Contract development is expanding most quickly as outsourcing penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites the Netherlands' distribution role for flexible manufacturing equipment moving between German engineering clusters and Atlantic markets. This infrastructure anchors Europe's multi-product biologics supply chain integration.
Germany
Exyte GmbH and KeyPlants AB anchor major capacity installations for multi-product biopharma facilities in the Rhine-Main industrial corridor. Germany's KBA-equivalent pharmaceutical regulator enforces stringent qualification standards under EU GMP Annex 15 revisions. The Stuttgart engineering cluster produces modular cleanroom pods that compress facility construction timelines for Basel-bound biologics manufacturers.
United States
Thermo Fisher Scientific leverages integrated automation portfolios across North American installations serving Boston-Cambridge biotech concentrations. The FDA's quality-by-design framework mandates documented process understanding for every product changeover, extending commissioning timelines. Massachusetts facilities deploy single-use bioreactor trains with automated seed transfer to accommodate personalized medicine pipeline volatility.
Switzerland
Lonza Group AG anchors single-use technology leadership for contract biologics manufacturing from Basel operations. Swissmedic maintains alignment with EMA guidance on decentralized manufacturing for cell therapies, creating precedent for distributed production models. The Basel-Lucerne corridor hosts hybrid facilities splitting seed train operations from production bioreactors.
India
Contract development and manufacturing organizations in Maharashtra and Telangana lack flexible containment infrastructure for potent compound handling. The CDSCO's evolving standards for multi-product facility qualification create compliance gaps for domestic manufacturers. Hyderabad's pharmaceutical cluster imports prefabricated modular skids to compress facility qualification timelines for export-oriented biologics production.
United Kingdom
Biologics contract manufacturers in Ireland and Singapore now purchase automation platforms through third-party systems integrators rather than direct OEM relationships, compressing vendor margins. The MHRA's post-Brexit alignment with ICH Q9 quality risk management guidelines constrains acceptable automation configurations. The Cambridge-Oxford biotech corridor pilots AI-guided process analytical technology integrations pending FDA and EMA software validation precedents.
Flexible Manufacturing Systems for Pharmaceutical Industry Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in filtration, chromatography, and control architecture layers. The vendor base concentrates around three capability clusters: full-service automation houses, modular facility fabricators, and consumables-dominant technology suppliers. Two strategic archetypes predominate: engineering-led integrators bundling hardware with validation documentation, and technology-origin specialists defending margin through proprietary membrane and resin portfolios. Competitive moves center on unbundling hardware from service contracts to capture mid-sized CDMO procurement, and prefabricated modular facility offerings that halve greenfield construction duration.
Among Germany-based engineering specialists, Exyte GmbH and KeyPlants AB occupy positions anchoring European multi-product facility installations. Thermo Fisher Scientific Inc. represents the integrated automation portfolio archetype spanning North American and European deployments. Cytiva exemplifies the component specialist model through chromatography and filtration module specialization that plugs into larger flexible system architectures. Lonza Group AG sits within the contract manufacturing tier, leveraging single-use technology leadership to influence equipment specification downstream. These five entities collectively span the value chain from facility construction through process technology supply.
| Leading Market Players |
|---|
| G-CON Manufacturing |
| Germfree Laboratories Inc. |
| Cytiva |
| Thermo Fisher Scientific Inc. |
| Lonza Group AG |
| Jacobs Engineering Inc. |
| KeyPlants AB |
| Catalent Inc. |
| Exyte GmbH |
| Others |
Supply & Pricing Matrix
German engineering clusters for modular cleanroom pods and Swiss filtration membrane production anchor margin pools downstream at North American biologics facilities and Indian CDMOs. Equipment vendors extract premium pricing through bundled validation documentation while facing cost compression from third-party systems integrators unbundling hardware from service contracts.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across distributed control platforms, with compliance-grade MES deployments commanding premium positioning against standard SCADA configurations. Three-tier pricing structure across premium, standard, and economy levels separates fully validated biologics suites from semi-configurable oral solid dosage systems and basic material handling automation. Pricing pressure stems from buyer consolidation among top-twenty pharmaceutical manufacturers forcing equipment vendors to unbundle hardware from service contracts. Contract development and manufacturing organizations in India and Singapore exhibit highest price sensitivity due to compressed facility qualification timelines, while biologics manufacturers in Massachusetts and Basel absorb premium tiers for rapid campaign changeover capabilities.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for programmable logic controllers and vision system components. Manufacturing concentrates in Germany for modular cleanroom pods, Switzerland for chromatography and filtration modules, and the United States for integrated automation portfolios. Raw material dependencies include high-performance tangential flow filtration cassettes, single-use bioreactor film substrates, and ISA-88 compliant control hardware. Single-source vulnerability concentrates in filtration membrane supply where three suppliers dominate high-performance tangential flow filtration cassettes. Distribution runs through the Port of Rotterdam's pharmaceutical logistics corridor connecting German engineering clusters to Atlantic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible manufacturing systems for pharmaceutical production are approaching a platform-economics inflection where modular control architectures create winner-take-most dynamics through software layer lock-in and recurring regulatory documentation revenues.
For Market Incumbents: Insulate service revenue streams by deepening captive validation expertise and expanding prefabricated modular facility offerings that compress construction timelines for greenfield biologics sites. Threat substitution from third-party systems integrators unbundling hardware from service contracts demands channel control through exclusive partnerships with mid-sized CDMOs in Ireland and Singapore. Certification investment in FDA and EMA software validation precedents for AI-guided process analytical technology creates switching costs that defend margin position. For New Entrants and Emerging Players: Establish a beachhead in AI-driven process control for predictive bioreactor optimization, a pre-competitive white space outside chromatography applications where machine learning modules remain undersupplied. Target Maharashtra and Telangana CDMOs lacking flexible containment infrastructure for potent compound handling, where regulatory compliance gaps create procurement urgency. Go-to-market angle should emphasize rapid facility qualification through skid-mounted cleanroom pods that halve construction duration versus traditional buildouts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across prefabricated modular facility sub-segments as standardized cleanroom pods displace bespoke engineering. Long-term viability over the next decade favors platform integrators with software layer differentiation over component specialists exposed to hardware commoditization. Acquisition target archetype: engineering-led integrators bundling hardware with validation documentation for multi-product biopharma facilities. Signal to monitor: FDA and EMA software validation precedents for AI-guided process analytical technology integrations.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Modular Facility Deployment | Skid-mounted cleanroom pods compress greenfield construction duration from thirty-six to eighteen months for Basel-bound biologics manufacturers. |
| AI-Driven Process Control Integration | Machine learning modules for predictive bioreactor optimization unlock pre-competitive white space outside chromatography applications. |
| Single-Use Technology Leadership | Proprietary membrane and resin portfolios defend margin through consumables attachment rates at multi-product contract manufacturing facilities. |
| Third-Party Systems Integrator Partnership | Channel control through exclusive relationships with mid-sized CDMOs counters hardware unbundling pressure from buyer consolidation. |
| Decentralized Manufacturing Validation | EMA guidance on cell therapy distributed production models creates precedent for validating discontinuous supply chains across Netherlands and Spain pilot networks. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with biopharma manufacturing executives, automation engineering directors, regulatory affairs leads, and CDMO procurement managers; and secondary validation through FDA 21 CFR Part 11 guidance documents, EMA GMP Annex 15 revisions, EU GMP qualification standards, and equipment vendor SEC filings. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis and facility investment tracking.
Forecast inputs span system type, technology layer, use case stage, and end-user archetype across the projection horizon, with specific weighting applied to continuous manufacturing adoption curves and modular control platform penetration at multi-product biologics facilities. CAGRs derive from segment-level growth rate blending anchored to disclosed capacity expansion timelines and regulatory validation cycle analysis. Industry-specific inputs include single-use bioreactor deployment rates and prefabricated modular facility construction velocity.
Sensitivities concentrate around FDA software validation burden for configurable distributed control systems and filtration membrane supply concentration risk. Forecasts reflect assumptions regarding EU GMP Annex 15 revision implementation timelines and personalized medicine pipeline commercialization rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market