
 Automated Drug Kiosk Market | 2026-2036
Automated Drug Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Drug Kiosk Market Analysis
North American manufacturing capacity for automated dispensing hardware is rewriting competitive dynamics in the kiosk supply base. Capsa Healthcare leverages its vertical integration in cabinet fabrication to sustain cost advantages across hospital deployments. Omnicell Inc. anchors its position through R&D intensity in cloud-connected inventory management. ScriptPro LLC differentiates via specialized workflow software that controls prescription verification protocols in high-volume retail settings.
An automated drug kiosk is a self-service terminal engineered to store, dispense, and track pharmaceutical products through integrated robotics, temperature-controlled compartments, and software-managed inventory systems, typically operating within 2-8°C cold-chain parameters for biologics. Its primary commercial purpose is to extend pharmacy operating hours, reduce labor dependency, and enforce dispensing accuracy through automated pill-counting and barcode verification. Standalone kiosks dominate installed base volume in retail pharmacy corridors where floor space commands premium allocation, while networked kiosk architectures are capturing margin pools through subscription-based remote monitoring and centralized inventory pooling across health system networks. Biometric authentication modules represent the fastest-growing technology insertion as dispensers seek to satisfy DEA-controlled substance custody requirements without on-site pharmacist presence.
FDA oversight of 510(k) clearance pathways for medication dispensing devices shapes product development timelines and clinical validation burdens for kiosk manufacturers seeking hospital entry. DEA regulations on controlled substance storage and access logging directly influence safe design specifications, including dual-authentication vaults and audit-trail retention. The EU MDR and FDA quality system harmonization pressures are forcing stakeholders to monitor regulatory convergence in software-as-medical-device classifications that could recast cloud-based kiosk platforms under premarket scrutiny.
Market Dynamics
Biometric authentication modules are compressing pharmacist staffing requirements while DEA custody rules harden hardware specifications across retail and hospital deployments.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates for pharmaceutical dispensing are accelerating biometric module integration across kiosk portfolios. Hospital pharmacy departments prioritize compliant hardware to avoid audit penalties.
- Cloud-connected inventory pooling:Health system networks are adopting subscription-based remote monitoring architectures that centralize stock visibility across distributed kiosk fleets. This reduces carrying costs for refrigerated biologics.
- United States retail pharmacy corridors:Floor space premiums in urban drugstore locations favor compact standalone kiosks over traditional counter layouts. Chains pilot 24-hour pickup networks to capture after-hours prescription volume.
Market Restraints
- Stainless steel and cold-chain compressor inputs:Temperature-controlled compartments require medical-grade fabrication materials subject to commodity price volatility. Input cost swings compress hardware margins for cabinet fabricators.
- Dual-authentication vault specifications:DEA regulations mandate redundant locking mechanisms for Schedule II-V substances. These design requirements add per-unit hardware costs that deter budget-constrained independent pharmacies.
- Manual pill verification:High-error-risk biologics and narrow-therapeutic-index drugs still require human pharmacist oversight. This limits full automation penetration in oncology and anticoagulant categories.
Strategic Opportunities
- Rural United States pharmacy deserts:Federally qualified health centers seek kiosk deployments to restore medication access in counties without brick-and-mortar pharmacies. USDA rural development grants partially offset capital costs.
- EU MDR software-as-medical-device convergence:Harmonized quality system pressures could recast cloud-based kiosk platforms under premarket scrutiny. Early compliance investments position vendors for streamlined CE marking.
- Computer vision and robotic pill-counting convergence:Integrated dispensing accuracy systems reduce verification labor while generating audit-trail data for liability defense. Retail chains pilot these modules in high-volume locations.
Industry Challenges
- Embedded systems cybersecurity certification:Kiosk manufacturers face extended validation timelines for FDA 510(k) clearance when network-connected inventory modules trigger software-as-medical-device classification.
- Legacy pharmacy management system integration:Health system IT departments struggle to synchronize kiosk dispensing logs with existing electronic health record workflows. Custom API development stretches deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Drug Kiosk Market |
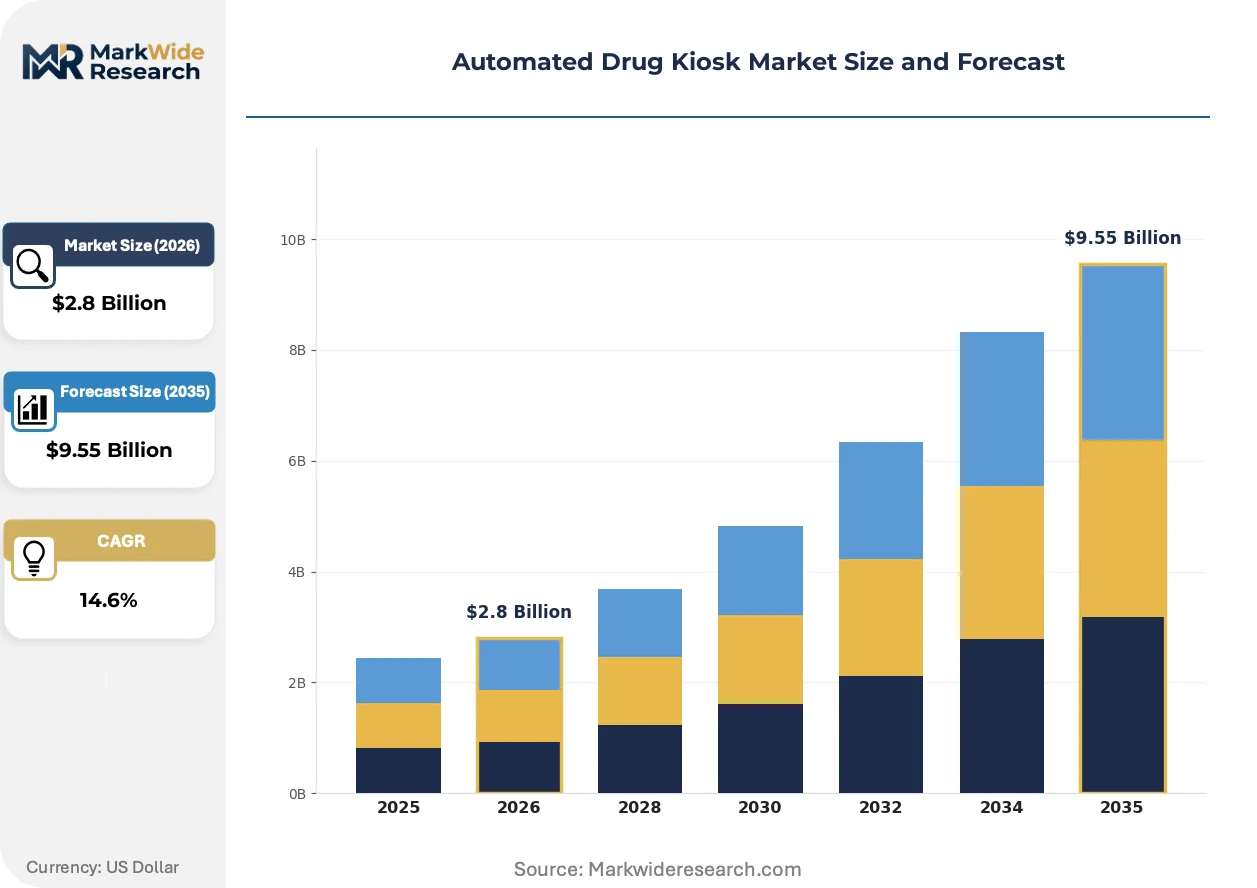
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Kiosks, Networked Kiosks, Mobile Kiosks, Prescription Kiosks Technology: RFID, Barcode Scanning, Touchscreen, Biometric Authentication End User: Pharmacies, Hospitals, Clinics, Home Healthcare Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Capsa Healthcare, Asteres Inc., MedAvail Technologies Inc., Pickpoint, Smart RX Systems, Omnicell Inc., ScriptPro LLC, MC HealthGrid Pvt Ltd., BD (Becton Dickinson), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Drug Kiosk Market Emerging Trajectories
Automation architectures are bifurcating between standalone retail units and networked health system deployments, with authentication technologies and regulatory frameworks determining competitive positioning.
Robotic dispensing mechanisms with integrated computer vision are hybridizing pill-counting accuracy with real-time inventory tracking. Hospital pharmacy departments in the United States are adopting these systems fastest, driven by Joint Commission medication safety mandates. The technology is hybridizing hardware and software value capture, compressing margins for pure-play cabinet fabricators while expanding recurring revenue pools for platform vendors.
EU MDR and FDA quality system harmonization pressures are forcing kiosk manufacturers to document software lifecycle processes for cloud-connected inventory modules. This regulatory convergence extends product development timelines but creates certification moats against unvalidated competitors. European health systems and United States hospital networks are responding by consolidating procurement around vendors with dual-continent regulatory clearance.
Subscription-based remote monitoring contracts are displacing capital-intensive kiosk ownership models across health system networks. Pharmacy benefit managers and integrated delivery networks favor per-dispensing fee structures that align vendor incentives with uptime performance. This shift is most visible in United States metropolitan markets where health system consolidation has concentrated buying power among regional pharmacy administrators.
Automated Drug Kiosk Market Segmentation
Automated drug kiosk segmentation reveals how hardware configurations, authentication technologies, and deployment architectures align with distinct operational constraints across retail pharmacy corridors and health system networks. Understanding these divisions clarifies where capital flows concentrate and which technology bundles command premium positioning.
Product Type:
Use-case spectrum spans from compact retail floor units to integrated health system fleets with centralized inventory visibility.
- Standalone Kiosks:Self-contained cabinets with embedded robotics and temperature-controlled compartments operate without network dependencies. United States retail pharmacy chains deploy these in urban corridors where 24-hour prescription pickup captures after-hours patient volume.
- Networked Kiosks:Cloud-connected architectures enable real-time inventory pooling and remote monitoring across distributed fleets. Health system networks favor these configurations to reduce carrying costs for refrigerated biologics through centralized stock visibility.
- Mobile Kiosks:Portable units on wheeled chassis serve temporary clinical deployments and disaster response scenarios.
- Prescription Kiosks:Specialized terminals engineered solely for patient pickup of pre-verified medications.
Established volume favors standalone configurations; emerging adoption favors networked architectures.
Technology:
Cost tier differentiation separates basic identification systems from biometric modules that satisfy controlled substance custody requirements.
- Biometric Authentication:Fingerprint, iris, and facial recognition modules enforce dual-authentication protocols for DEA Schedule II-V substances. Hospital pharmacy departments prioritize these to eliminate on-site pharmacist presence while maintaining custody compliance.
- RFID:Radio-frequency identification tracks individual medication packages through dispensing workflows with automated inventory reconciliation. Retail chains with high-volume locations deploy RFID to reduce manual counting labor.
- Barcode Scanning:Linear and 2D code readers provide cost-effective verification for standard prescription fulfillment.
- Touchscreen:Capacitive interfaces manage patient interaction layers without authentication capabilities.
Biometric modules gain share fastest in hospital deployments; barcode scanning retains dominance in budget-constrained independent pharmacies.
End User:
Customer type determines authentication stringency and cold-chain specifications across the installed base.
- Hospitals:Inpatient pharmacy departments require 2-8°C cold-chain compartments for biologics and Joint Commission-mandated dispensing accuracy systems. These installations command the highest per-unit hardware specifications.
- Pharmacies:Retail chains and independents prioritize compact footprints and 24-hour operational capability over clinical-grade temperature control.
- Clinics:Outpatient facilities seek intermediate configurations balancing space constraints with controlled substance access.
- Home Healthcare:Patient-directed units for chronic disease management operate with simplified authentication and ambient temperature storage.
Hospital procurement concentrates premium-tier demand; pharmacy retail channels drive volume scale.
Deployment:
Margin structure varies sharply between capital ownership and subscription-based service models.
- Cloud-Based:SaaS architectures shift kiosk economics from upfront capital to per-dispensing fees that align vendor incentives with uptime performance. United States metropolitan health systems favor this model where consolidation has concentrated regional buying power.
- Managed Services:Full outsourcing bundles hardware, software, maintenance, and compliance monitoring under single-vendor accountability. Federally qualified health centers in rural pharmacy deserts leverage USDA grants to offset these operational contracts.
- On-Premises:Customer-owned infrastructure with perpetual software licenses retains capital intensity.
- Hybrid:Mixed architectures keep sensitive dispensing logic local while pushing inventory analytics to cloud platforms.
Cloud-based subscriptions displace on-premises ownership fastest; managed services capture emerging rural deployment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware fabrication for temperature-controlled dispensing cabinets clusters in the United States, Germany, and Japan, where medical-grade stainless steel supply chains and precision robotics engineering concentrate. Kiosk deployment patterns diverge sharply across regulatory environments and pharmacy infrastructure maturity.
United States
Retail pharmacy chains in urban corridors deploy 24-hour standalone kiosks to capture after-hours prescription volume. FDA 21 CFR Part 11 mandates accelerate biometric authentication module adoption across hospital pharmacy departments. The Dallas-Fort Worth metroplex anchors pilot networks for cloud-connected inventory pooling across health system federations.
Germany
Hospital networks prioritize EU MDR-compliant dispensing systems with documented software lifecycle processes. EMA quality system harmonization pressures extend product development timelines for kiosk manufacturers seeking CE marking. The Baden-Württemberg industrial cluster around Stuttgart hosts precision robotics suppliers serving medical automation OEMs.
Japan
Aging demographics and pharmacist shortages drive kiosk adoption in rural prefectures lacking brick-and-mortar pharmacies. PMDA oversight of software-as-medical-device classifications shapes validation requirements for network-connected inventory modules. The Kansai region around Osaka concentrates pharmaceutical distribution automation engineering.
United Kingdom
NHS pharmacy deserts in northern England and rural Scotland prompt pilot deployments at community health centers. MHRA alignment with EU MDR transitional provisions creates regulatory uncertainty for cloud-based kiosk platforms. The Cambridge-Oxford corridor hosts emerging ventures in computer vision dispensing verification.
India
CDSCO medical device regulations tighten quality system requirements for imported kiosk hardware. Government PLI scheme incentives attract domestic fabrication of temperature-controlled cabinet components. The Maharashtra-Gujarat pharmaceutical manufacturing belt experiments with kiosk deployments at corporate hospital chains.
Automated Drug Kiosk Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in cabinet fabrication, authentication modules, and inventory software. The vendor base splits between vertically integrated hospital equipment conglomerates and focused kiosk specialists. Three archetypes dominate: hardware fabricators with captive cold-chain engineering, software-centric platform vendors monetizing subscription telemetry, and hybrid players bundling managed compliance services. Consolidation pressures intensify as health system procurement centralization favors vendors with dual-continent regulatory clearance.
Among North American platform vendors, Capsa Healthcare and Omnicell Inc. exemplify divergent strategic positioning within the hospital pharmacy automation tier. Asteres Inc. and ScriptPro LLC occupy distinct niches in retail corridor deployment and high-volume prescription workflow management respectively. MedAvail Technologies Inc. represents the managed-service archetype, bundling hardware deployment with remote pharmacist verification infrastructure.
| Leading Market Players |
|---|
| Capsa Healthcare |
| Asteres Inc. |
| MedAvail Technologies Inc. |
| Pickpoint |
| Smart RX Systems |
| Omnicell Inc. |
| ScriptPro LLC |
| MC HealthGrid Pvt Ltd. |
| BD (Becton Dickinson) |
| Others |
Supply Flow & Price Mechanics
Commodity volatility in medical-grade stainless steel and cold-chain compressor inputs compresses hardware margins while simultaneously widening pricing spreads between premium hospital-grade units and economy retail configurations. This input cost instability forces cabinet fabricators toward backward integration into temperature-controlled component production, reshaping vendor tier structures across both United States and European procurement channels.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across automated drug kiosk portfolios, with biometric authentication modules commanding substantial premiums over baseline barcode-scanning configurations. Price differentiation hinges on DEA dual-authentication vault certification and Joint Commission dispensing accuracy validation, with hospital pharmacy departments showing lowest price sensitivity due to audit penalty avoidance. Cost compression in standard retail-tier units is intensifying because independent pharmacies face capital constraints against chain purchasing power.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for temperature-controlled cabinet assemblies. Hardware fabrication clusters in the United States, Germany, and Japan, drawing from precision robotics engineering and medical-grade stainless steel supply chains. Component dependencies rest on cold-chain compressors, embedded biometric sensors, and cloud-connected inventory modules. Distribution runs through health system GPO contracts and retail pharmacy chain direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated drug kiosk market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning. Switching costs for hospital pharmacy departments escalate once biometric authentication workflows integrate with existing electronic health record systems.
For Market Incumbents: Build certification moats through simultaneous FDA 510(k) and EU MDR quality system documentation for cloud-connected inventory platforms. Incumbent vendors should anchor backward integration into cold-chain compressor supply to offset stainless steel commodity swings. Emerging software-as-medical-device classifications threaten unvalidated competitors, creating acquisition opportunities for compliant platforms. For New Entrants and Emerging Players: Rural United States pharmacy deserts present the most penetrable white-space opportunity, with USDA rural development grants partially offsetting capital barriers for managed-service deployments. New entrants should pursue computer vision dispensing verification as a differentiated entry angle against established barcode-scanning incumbents. Federally qualified health centers offer concentrated pilot sites with lower competitive density than metropolitan health systems. For Investors and Strategic Acquirers: EU MDR software-as-medical-device convergence reshapes the acquisition landscape toward platform vendors with dual-continent regulatory clearance already secured. Long-term viability across the projection horizon favors hybrid players bundling managed compliance services rather than pure hardware fabricators. The signal to monitor is health system procurement centralization trends, which concentrate buying power among vendors with proven uptime performance in subscription contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Certification Investment | FDA 21 CFR Part 11 compliance eliminates audit penalty exposure for hospital pharmacy deployments. |
| Cloud Inventory Platform Development | SaaS architectures align vendor incentives with health system uptime performance through per-dispensing fees. |
| Rural Managed Service Expansion | USDA grant-funded deployments restore medication access in pharmacy deserts while building recurring revenue pools. |
| Computer Vision Dispensing Integration | Robotic pill-counting with audit-trail generation reduces liability exposure in high-volume retail locations. |
| Dual-Continent Regulatory Clearance | Simultaneous FDA and EMA quality system documentation creates certification moats against unvalidated competitors. |
Methodological Framework
Desk research of FDA 510(k) filings, EMA quality system documentation, and hospital procurement databases preceded structured interviews with pharmacy informatics officers, GPO contracts managers, biomedical engineers, and retail pharmacy operations directors. Primary fieldwork with kiosk manufacturers and health system pharmacy administrators was cross-validated against secondary sources including DEA controlled substance regulations, EU MDR technical documentation, and SEC filings from publicly traded automation vendors. Bottom-up unit economics modeling was triangulated with top-down health system capital expenditure surveys.
Assumptions regarding regulatory timeline stability and stainless steel commodity price bands were held fixed across the modeling period, while cloud adoption rates and biometric module cost curves were varied under sensitivity scenarios. Segmentation dimensions modeled include product architecture, authentication technology tier, end-user category, and deployment model, with additional granularity on cold-chain specification levels. CAGRs were derived from installed base growth trajectories and average revenue per unit trends, incorporating biologics dispensing volume expansion and subscription contract penetration as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting health system capital budgets or trade policy shifts impacting stainless steel tariffs would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market