
 Slip Tip Syringe Market | 2026-2036
Slip Tip Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Slip Tip Syringe Market Analytics
Market Context
Asian polymer conversion capacity is shifting toward medical-grade polypropylene and cyclic olefin copolymer resins for precision-molded slip tip barrels. BD leverages backward integration into resin compounding to secure batch-to-batch dimensional consistency for Luer-slip interfaces. Terumo sustains dominant position in Japanese hospital procurement through automated tip-forming lines that reduce flash variation below 0.05 millimeters. Hindustan Syringes & Medical Devices anchors South Asian supply with high-volume disposable output targeting national immunization programs.
Technical Definition and Segment Structure
A slip tip syringe employs a friction-fit tapered nozzle—typically 6% Luer taper per ISO 594-2—without threaded collar engagement, enabling rapid needle attachment and removal for high-throughput clinical settings. The barrel wall thickness, plunger stopper elastomer formulation, and silicone lubrication level determine dosing accuracy and break-loose force for manual injection. Plastic syringes occupy the volume-dominant position across vaccination and drug delivery applications, while glass variants retain margin concentration in parenteral nutrition where chemical inertness commands premium positioning. Hospital end users represent the structural demand anchor, though home care channels are gaining fastest as self-injection therapies for diabetes and autoimmune conditions expand beyond clinical settings.
Regulatory Environment and Outlook
FDA 510(k) clearance pathways and EU MDR Class IIa device classifications enforce biocompatibility testing per ISO 10993 and endotoxin limits for sterilized slip tip syringes entering regulated markets. India's CDSCO and BIS standards mandate ethylene oxide residual thresholds and package integrity verification for domestically manufactured and imported devices. ISO 7886-1 dimensional tolerances for conical fittings function as the de facto global interoperability standard, preventing tip-leakage failures that compromise dose delivery. Stakeholders must monitor evolving FDA guidance on pyrogenicity testing methods and EU F-Gas Regulation implications for sterilization gas alternatives.
Market Dynamics
Hospital procurement consolidation and FDA sterilization validation requirements are compressing supplier margins while forcing capital upgrades to automated tip-forming equipment. Batch-to-batch dimensional precision has become the primary competitive differentiator as health systems reject lots exceeding 0.05 millimeter flash tolerance.
Growth Catalysts
- ISO 7886-1 standardization:Global interoperability mandates for conical fittings are eliminating regional specification fragmentation. Medical device distributors now stock single-SKU inventories serving multiple national markets.
- Diabetes self-injection expansion:Home care channels for insulin delivery are absorbing high-volume plastic syringe output previously directed toward clinical settings. Patient training programs now emphasize Luer-slip familiarity over threaded alternatives.
- India's national immunization scale-up:CDSCO procurement tenders for disposable injection devices are anchoring regional production capacity. Domestic manufacturers command preferential bidding status under local content requirements.
Market Restraints
- Medical-grade polypropylene supply concentration:Asian resin converters dominate polymer feedstock for precision-molded barrels. European and North American molders face 12-16 week lead times for certified material lots.
- Ethylene oxide sterilization phase-down:EU F-Gas Regulation restrictions are forcing capital-intensive conversion to gamma irradiation or nitrogen dioxide alternatives. Validation timelines for new sterilization protocols extend 18-24 months.
- Glass-to-plastic substitution ceiling:Parenteral nutrition formulations requiring chemical inertness retain glass syringe specifications. Premium pricing in this segment cannot offset volume erosion in standard applications.
Strategic Opportunities
- Brazilian ANVISA prequalification pathway:Latin American hospital procurement is opening to manufacturers with established FDA 510(k) clearances. Simplified technical dossier requirements reduce market entry costs versus full domestic registration.
- Connected device convergence:Bluetooth-enabled dose-logging attachments are integrating with standard Luer-slip interfaces. Chronic disease management platforms are subsidizing hardware costs to capture adherence data.
- Japanese PMDA quality premium recognition:Automated tip-forming certification programs are creating tiered supplier status. Hospitals in Tokyo and Osaka medical clusters now specify JIS-compliant sourcing for high-risk injections.
Industry Challenges
- Multi-standard compliance engineering:Simultaneous FDA, EU MDR, and BIS validation requires redundant testing protocols. Quality teams must maintain parallel documentation systems with non-harmonized biocompatibility endpoints.
- Legacy equipment retooling cycles:Converting flash-limited production lines to medical-grade tolerances demands precision machining investments. Mid-capitalization manufacturers face 36-48 month payback periods on automated inspection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slip Tip Syringe Market |
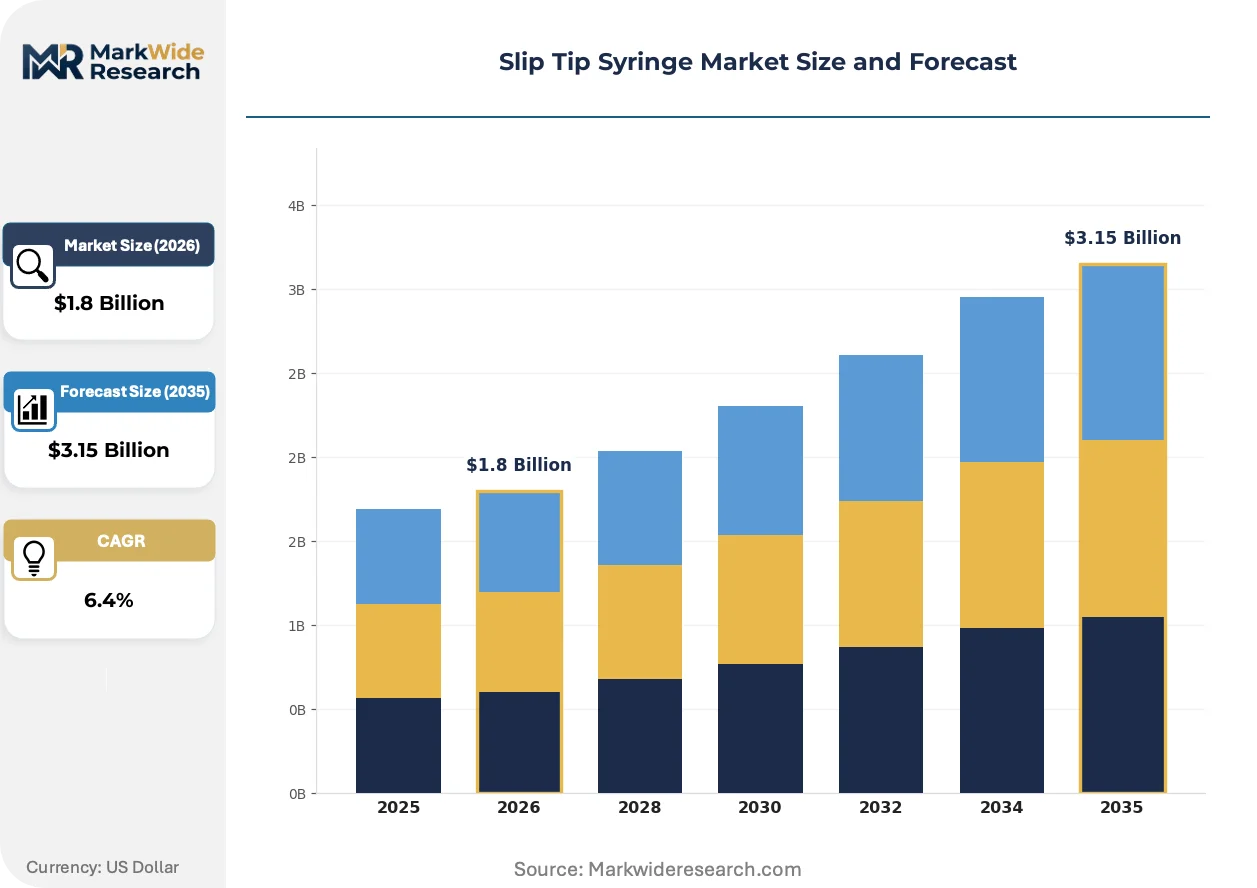
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Needles, Catheters, Infusion Sets Material: Plastic, Glass, Rubber, Silicone End User: Hospitals, Clinics, Home Care, Laboratories Application: Vaccination, Drug Delivery, Blood Collection, Parenteral Nutrition |
| Companies Covered | BD (Becton, Dickinson and Company), Terumo Corporation, Nipro Corporation, Cardinal Health, Medline Industries, Smiths Medical, B. Braun, Hindustan Syringes & Medical Devices, Poly Medicure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slip Tip Syringe Market Evolving Landscape
Silicone lubrication chemistry and cyclic olefin copolymer barrel materials are converging to reduce break-loose force variability. Manufacturers now compete on dosing precision metrics rather than unit cost alone.
Cyclic olefin copolymer is integrating into high-volume disposable syringe barrels to replace polypropylene in applications requiring enhanced moisture barrier properties. Japanese hospital procurement groups are specifying COC content for parenteral drug compatibility testing. This material shift is integrating premium resin positioning into standard vaccination device categories previously dominated by commodity polymers.
The EU MDR Class IIa device classification is mandating expanded clinical evidence packages for legacy products with decades of safe use history. Notified bodies in Germany and the Netherlands are imposing supplemental biocompatibility testing for silicone lubricant formulations. Sterile single-use syringe suppliers are responding by consolidating product portfolios to focus validation resources on highest-volume SKUs.
Direct contracting between hospital systems and molders is displacing traditional distributor intermediaries in high-volume therapeutic categories. Group purchasing organizations in the United States are unbundling syringe procurement from broader anesthesia and critical care bundles. This channel compression is most visible in Texas and Florida health networks where self-distribution warehouses now handle container-direct shipments from manufacturing plants.
Slip Tip Syringe Market Segmentation
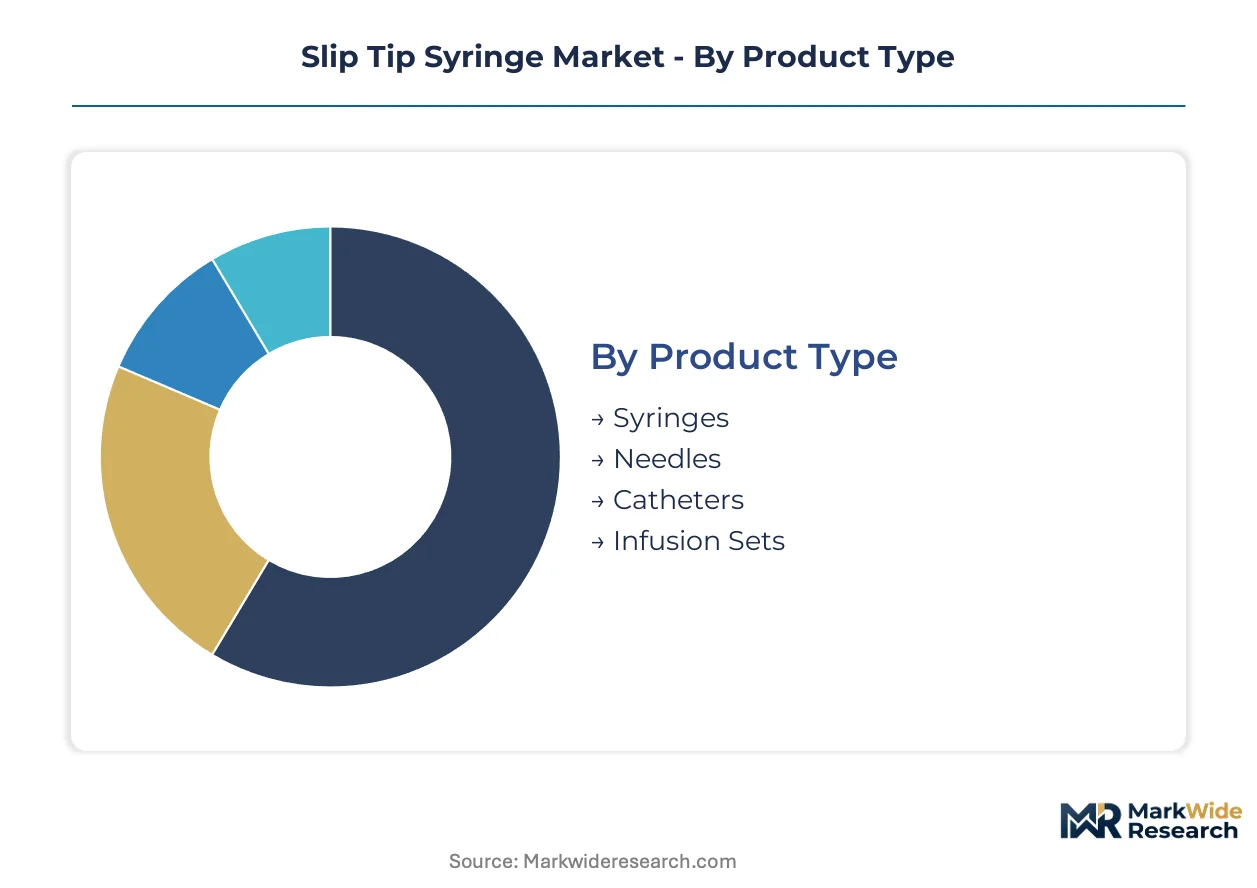
Slip tip syringe procurement patterns diverge sharply across clinical settings, material specifications, and therapeutic applications. Manufacturers must calibrate production capacity against distinct compliance burdens and volume economics within each segment cluster.
Product Type:
Procurement scale and sterilization protocol intensity separate buyers across device categories.
- Syringes:Plastic barrels with 6% Luer taper interfaces dominate high-throughput vaccination campaigns. Hospital systems in the United States and India absorb bulk volume through national immunization tenders and diabetes self-injection programs.
- Needles:Hypodermic configurations with friction-fit hubs require separate sterilization validation from barrel assemblies. German hospital procurement groups now specify single-source needle-syringe compatibility testing to prevent interface failures.
- Catheters:Peripheral venous access devices with slip tip adapters serve emergency medicine and anesthesia workflows.
- Infusion Sets:Gravity and pump-compatible tubing systems integrate Luer-slip connectors for intermittent medication boluses.
Volume sits with Syringes; growth tilts toward Infusion Sets.
Material:
Cost thresholds and chemical compatibility requirements stratify raw material selection across therapeutic applications.
- Plastic:Medical-grade polypropylene and cyclic olefin copolymer formulations enable precision molding at scale. Japanese PMDA quality certifications and EU MDR biocompatibility testing are elevating resin purity specifications for parenteral drug contact surfaces.
- Glass:Borosilicate barrels retain specification for parenteral nutrition and biologic formulations demanding inert contact surfaces. Premium pricing in this segment reflects limited supplier capacity for Type I neutral glass conversion.
- Rubber:Bromobutyl and chlorobutyl plunger stoppers provide elastomeric sealing with controlled extractables profiles.
- Silicone:Lubricant coatings reduce break-loose force variability in manual injection devices.
Plastic commands absolute volume; glass maintains margin concentration.
End User:
Channel economics and regulatory exposure shape supplier relationships across care delivery settings.
- Hospitals:Acute care facilities with centralized pharmacy operations drive bulk purchasing through group purchasing organizations. FDA 510(k) clearance and EU MDR Class IIa certification are mandatory for vendor qualification in Texas and Florida health networks.
- Home Care:Self-injection therapy patients require simplified Luer-slip training and disposal systems. Diabetes management platforms in Germany are subsidizing connected dose-logging attachments to capture adherence data.
- Clinics:Outpatient settings with limited storage capacity favor compact packaging configurations.
- Laboratories:Research and diagnostic applications demand non-sterile bulk packaging for liquid handling protocols.
Hospitals anchor procurement volume; home care channels are climbing the fastest.
Application:
Therapeutic urgency and dosing precision requirements determine device specification stringency.
- Vaccination:Mass immunization campaigns require single-use disposables with minimal dead space. India's CDSCO national tenders specify domestic manufacturing content for polio and routine immunization programs.
- Drug Delivery:Chronic disease injection regimens demand consistent break-loose force across temperature storage ranges. Insulin delivery systems in Japanese hospital clusters now specify JIS-compliant automated tip-forming certification.
- Blood Collection:Venipuncture applications integrate slip tip adapters with vacuum tube holders.
- Parenteral Nutrition:Lipid emulsion compatibility requires glass or COC barrier materials to prevent leachables.
Vaccination drives peak volume spikes; drug delivery sustains recurring consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polypropylene resin production concentrates in South Korea and Saudi Arabia, supplying precision molders across Germany, India, and the United States with certified feedstock for ISO 7886-1 compliant barrels.
United States
Texas and Florida health networks drive container-direct procurement from manufacturing plants, bypassing traditional distributor intermediaries. FDA 510(k) clearance remains mandatory for vendor qualification in acute care settings. BD anchors supply through backward integration into resin compounding near its North Carolina operations.
Germany
Hospital procurement groups in Munich and Hamburg specify single-source needle-syringe compatibility testing to prevent Luer-slip interface failures. EU MDR Class IIa device classification mandates expanded clinical evidence packages even for legacy products. Notified bodies in the Netherlands impose supplemental biocompatibility testing for silicone lubricant formulations.
India
National immunization scale-ups through CDSCO procurement tenders anchor regional production capacity for polio and routine vaccination programs. Domestic manufacturers command preferential bidding status under local content requirements. Hindustan Syringes & Medical Devices concentrates high-volume disposable output in Faridabad to serve government tenders.
Japan
Tokyo and Osaka medical clusters now specify JIS-compliant sourcing for high-risk injections, creating tiered supplier status through automated tip-forming certification. PMDA quality premium recognition rewards manufacturers with flash variation below 0.05 millimeters. Terumo sustains dominant position through precision tip-forming lines.
Slip Tip Syringe Market Competitive Landscape
Global majors compete with regional champions across sterilization validation capabilities and resin supply security. The vendor base separates into three tiers: integrated resin compounders with captive polymer supply, precision molders with automated tip-forming certification, and high-volume disposable specialists serving government tenders. Dominant competitive moves include capacity expansion in medical-grade polypropylene conversion and strategic partnerships with notified bodies for EU MDR compliance acceleration.
Among US-based diversified health technology corporations, BD and Cardinal Health exemplify the integrated archetype through upstream control over resin compounding and sterilization infrastructure. Terumo Corporation represents the precision-tier position anchored in Japanese PMDA quality certification. Hindustan Syringes & Medical Devices occupies the high-volume disposable specialist role serving India's national immunization programs with domestic manufacturing concentration.
| Leading Market Players |
|---|
| BD (Becton, Dickinson and Company) |
| Terumo Corporation |
| Nipro Corporation |
| Cardinal Health |
| Medline Industries |
| Smiths Medical |
| B. Braun |
| Hindustan Syringes & Medical Devices |
| Poly Medicure |
| Others |
Value Network & Pricing Analysis
Medical-grade polypropylene resin costs cascade through three pricing tiers as Asian polymer converters supply precision molders in Germany, India, and the United States with certified feedstock for ISO 7886-1 compliant barrels.
Pricing Analysis
After-sales service bundling separates premium suppliers from commodity competitors, with JIS-compliant automated tip-forming certification commanding price premiums in Tokyo and Osaka hospital clusters. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, EU MDR Class IIa certification, and volume scale commitments. Cost compression in standard plastic syringes is intensifying because CDSCO procurement tenders in India prioritize domestic manufacturing content over imported alternatives. Government tender participants exhibit highest price sensitivity; Japanese PMDA quality premium recognition segments show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Texas and Florida health networks mandate multi-supplier qualification for container-direct procurement, preventing single-source dependency on any one molder. Supply concentrates in South Korea and Saudi Arabia for medical-grade polypropylene resin, with precision molding anchored in Germany, India, and the United States. Raw material dependencies center on polymer feedstock, silicone lubricant formulations, and bromobutyl plunger stoppers. Single-source vulnerability persists in automated tip-forming equipment where Japanese and German machinery suppliers dominate. Distribution runs through group purchasing organizations in acute care and diabetes management platforms in home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into resin compounding has become the decisive vertical-integration race, with BD's North Carolina operations demonstrating how captive polymer supply secures batch-to-batch dimensional consistency.
For Market Incumbents: Extend automated tip-forming certification programs to capture JIS-compliant sourcing specifications in Japanese hospital clusters. Consolidate validation resources on highest-volume SKUs to manage EU MDR Class IIa expanded clinical evidence requirements. Capacity addition in medical-grade polypropylene conversion near Gulf Coast resin production mitigates 12-16 week lead time exposure.
For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer the most penetrable route around entrenched group purchasing organization relationships in Texas and Florida health networks. Target Brazilian ANVISA prequalification pathways where FDA 510(k) clearances reduce technical dossier burdens versus full domestic registration. White-space exists in connected dose-logging attachments subsidized by chronic disease management platforms.
For Investors and Strategic Acquirers: EU F-Gas Regulation sterilization protocol conversions extending 18-24 months is the leading indicator that gamma irradiation and nitrogen dioxide alternative specialists will command acquisition premiums. Five-to-ten year viability favors precision molders with automated inspection systems already deployed. Watch for CDSCO procurement tender awards to domestic manufacturers as inflection signal for regional production capacity consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks vendor qualification in Texas and Florida acute care networks. |
| EU MDR Class IIa Certification | Mandates expanded clinical evidence for legacy products in German hospital procurement. |
| Backward Integration into Resin Compounding | Secures batch-to-batch dimensional consistency for Luer-slip interfaces. |
| Hospital System Partnership | Displaces distributor intermediaries through container-direct procurement arrangements. |
| Software Companion Development | Enables Bluetooth-enabled dose-logging attachments for chronic disease adherence platforms. |
Research Methodology
FDA 510(k) filings, EU MDR notified body documentation, and CDSCO procurement tender records formed the secondary backbone, supplemented by customs data on medical-grade polypropylene trade flows. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs directors at precision molding operations validated secondary findings. Bottom-up and top-down triangulation reconciled production capacity estimates against national immunization program consumption data.
Bottom-up modeling built volume outputs from individual country procurement patterns and therapeutic application dosing frequencies, while top-down analysis cross-checked against healthcare expenditure benchmarks. Segmentation dimensions included product type, material specification, end-user channel, and application across the analysis window. CAGRs derived from weighted average of historical immunization campaign volumes and projected diabetes self-injection therapy expansion. Sterilization protocol conversion timelines and resin supply lead times served as critical forecast inputs.
The model holds under stable FDA and EU MDR regulatory frameworks; deviation in ethylene oxide phase-down acceleration or medical-grade polypropylene supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Suture Wire Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market