
 Serum Vials Market | 2026-2036
Serum Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Serum Vials Market Analytics
The migration from borosilicate to aluminosilicate glass formulations is narrowing the acceptable range of hydrolytic resistance specifications across parenteral packaging supply chains. Gerresheimer AG leverages its European furnace network to sustain high-volume output of Type I molded vials for mRNA platforms. SCHOTT AG anchors its position through proprietary FIOLAX tubing that dominates pre-filled syringe compatibility testing. West Pharmaceutical Services differentiates via integrated elastomer closure systems that reduce contamination risk in fill-finish operations.
Serum vials are cylindrical primary containers, typically 2–20 mL in fill volume, manufactured from neutral borosilicate or aluminosilicate glass to achieve chemical durability below 0.7 mL hydrolytic class per USP <660>, designed to preserve sterility and stability of injectable biologics through shelf life. Glass vials retain dominance in high-value therapeutic applications where oxygen and moisture ingress must remain below 0.1 cc per year, while plastic vials, primarily cyclic olefin polymer constructions, gain share in diagnostic and point-of-care segments where breakage tolerance outweighs barrier demands. Pre-filled vials command premium positioning through reduced compounding error rates and accelerated clinical trial enrollment timelines.
The FDA enforces container closure integrity per USP <1207> that mandates deterministic leak detection methods for all parenteral products, while the EMA MDR framework requires full supply chain traceability for Class III implantable-adjacent devices including drug-device combination vials. ISO 15378 pharmaceutical packaging standards shape quality management expectations across contract manufacturers in Europe and North America. Stakeholders must monitor evolving USP <1660> guidance on glass delamination propensity as next-generation protein formulations impose more aggressive pH and ionic strength profiles on primary contact surfaces.
Market Dynamics
The migration from borosilicate to aluminosilicate glass formulations is compressing acceptable hydrolytic resistance tolerances across parenteral packaging supply chains, forcing manufacturers to recalibrate furnace chemistry and annealing protocols. This materials transition intersects with tightening FDA and EMA extractables testing mandates, creating simultaneous pressure on barrier performance and analytical verification capacity.
Growth Catalysts
- EMA MDR traceability mandates:Full supply chain documentation requirements for Class III implantable-adjacent devices are expanding demand for serialized, trackable vial systems with integrated data matrix capabilities.
- mRNA platform proliferation:Biopharmaceutical developers are scaling lipid nanoparticle formulation pipelines that require specialized Type I molded vials with ultra-low extractable profiles and thermal shock resistance.
- German glass production clusters:Concentrated specialized borosilicate manufacturing infrastructure in Mainz and Mitterteich regions anchors European supply security for high-barrier parenteral containers.
Market Restraints
- Energy-intensive furnace operations:Natural gas and electricity input cost volatility directly compresses margin structures for tubular and molded glass vial production, particularly affecting mid-volume European manufacturers.
- Single-source alumina supply concentration:High-purity alumina for aluminosilicate formulations depends on limited Chinese and Australian mining and refining capacity, creating raw material security exposure.
- USP glass delamination guidance:Evolving USP standards on surface degradation propensity impose extended qualification timelines and retrospective stability testing burdens on existing product portfolios.
Strategic Opportunities
- Point-of-care diagnostic expansion:Cyclic olefin polymer vial adoption in decentralized testing workflows creates alternative material pathways where breakage tolerance outweighs oxygen barrier requirements.
- Pre-filled vial integration:Reduced compounding error rates and accelerated clinical trial enrollment timelines are driving biopharmaceutical sponsors toward ready-to-use container closure systems.
- ISO 15378 certification differentiation:Quality management system accreditation for pharmaceutical packaging is becoming a procurement threshold, enabling certified contract manufacturers to capture premium positioning.
Industry Challenges
- Deterministic leak detection capability gaps:USP container closure integrity requirements mandate mass spectrometry or laser-based methods that exceed equipment availability at smaller fill-finish contract manufacturers.
- Elastomer-closure formulation complexity:Matching halobutyl and bromobutyl stopper compositions to aggressive biologic formulations requires extended extractables profiling and accelerated aging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serum Vials Market |
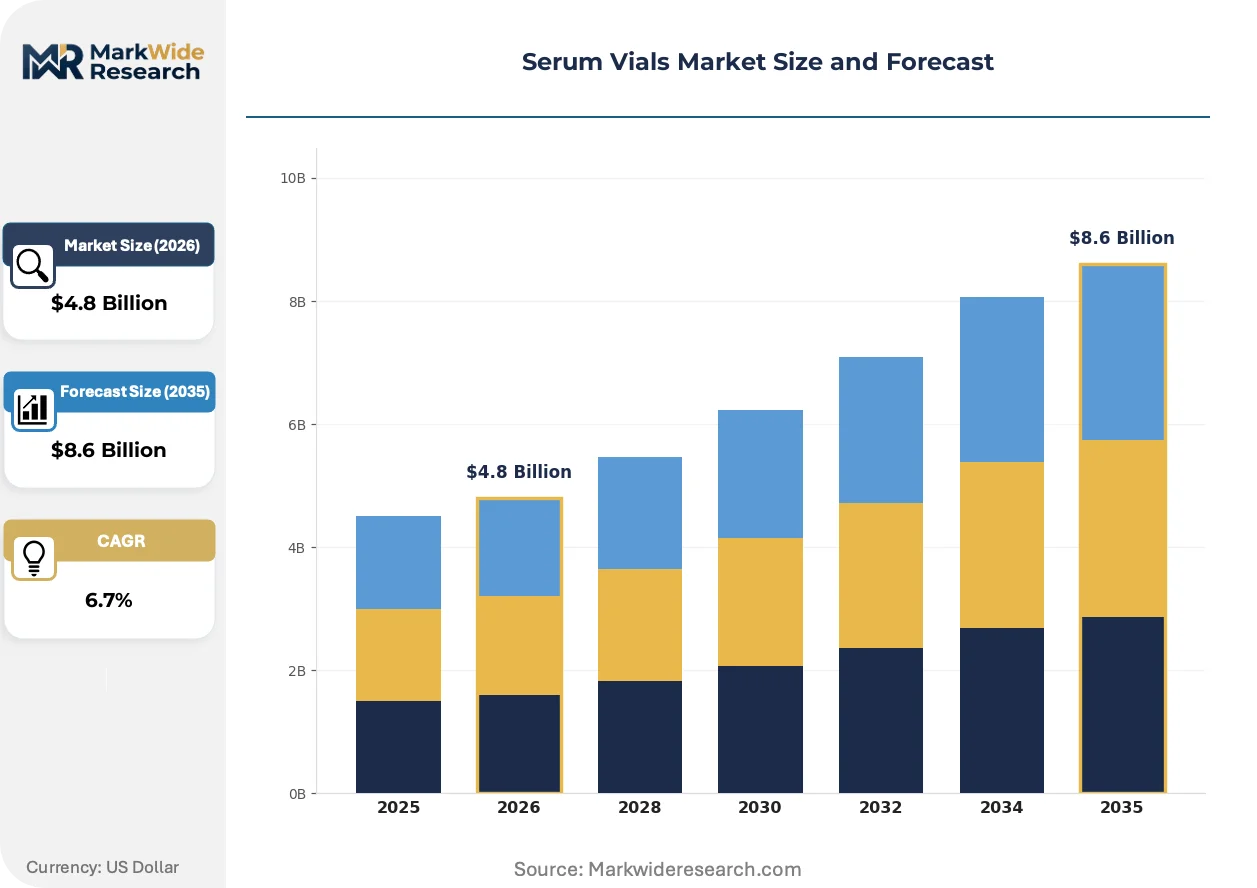
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Ampoules, Pre-filled Vials End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Hospitals Closure Type: Rubber Stoppers, Aluminum Seals, Snap-off Caps, Luer Locks Application: Vaccines, Therapeutics, Diagnostics, Clinical Trials |
| Companies Covered | Gerresheimer AG, SCHOTT AG, West Pharmaceutical Services, Stevanato Group, SGD Pharma, Corning Incorporated, DWK Life Sciences, Adelphi Healthcare Packaging, Pacific Vial Manufacturing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serum Vials Market Evolving Landscape
Material science advances are converging with regulatory precision medicine frameworks to redefine primary packaging performance specifications. Three developments are restructuring competitive positioning across glass and polymer vial segments.
Aluminosilicate glass is hybridizing barrier and mechanical properties previously segmented between borosilicate and polymer alternatives. Biopharmaceutical formulators developing high-pH protein therapeutics are adopting these formulations at accelerating rates to mitigate delamination risk. The technology is hybridizing traditional glass vial and pre-filled syringe supply chains as single-source manufacturers qualify dual-format outputs from common tubing stock.
EMA MDR framework implementation is compressing supplier qualification timelines for drug-device combination vials. Full supply chain traceability requirements are forcing pharmaceutical sponsors to consolidate vendor bases and demand real-time batch documentation. Small-volume parenteral manufacturers in Southern Europe are responding by investing in serialized production lines ahead of notified body audit schedules.
Contract development and manufacturing organizations are consolidating procurement authority over primary packaging specifications. Large biopharmaceutical sponsors are transferring container closure selection decisions to CDMO partners with integrated analytical capabilities. This concentration is most visible in the Boston-Cambridge and Basel biotech corridors, where fill-finish providers now specify vial formats during early-phase protocol design.
Serum Vials Market Segmentation
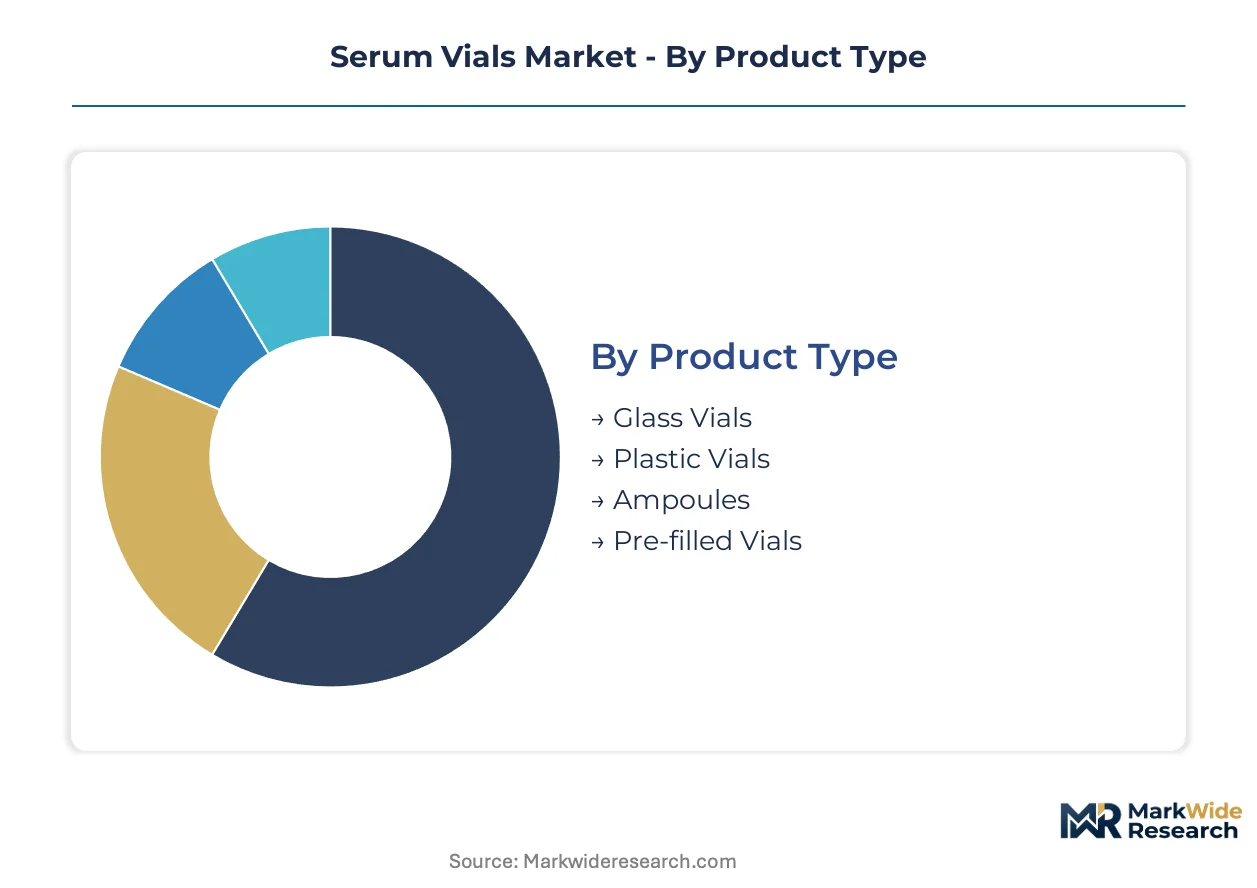
Serum vial segmentation reflects divergent barrier requirements across biologics storage, diagnostic workflows, and point-of-care delivery. Product material selection and closure system design determine compatibility with specific therapeutic modalities and regulatory filing pathways.
Product Type:
Glass formulations dominate high-barrier biologics, while polymer alternatives capture diagnostic and decentralized care applications where mechanical tolerance outweighs oxygen exclusion.
- Glass Vials:Manufactured from Type I borosilicate or aluminosilicate tubing with hydrolytic resistance below 0.7 mL per USP standards. Demand concentrates in Germany's Mainz and Mitterteich production clusters, driven by EMA MDR traceability mandates for Class III implantable-adjacent drug-device combinations.
- Plastic Vials:Cyclic olefin polymer constructions sacrifice ultra-low oxygen ingress for impact resistance in field-deployed diagnostic kits. Adoption accelerates in decentralized testing workflows where breakage tolerance outweighs barrier demands.
- Ampoules:Single-dose glass containers with fused-tip closures eliminate elastomer extractables concerns for sensitive protein formulations.
- Pre-filled Vials:Ready-to-use container closure systems reduce compounding error rates and accelerate clinical trial enrollment timelines through integrated fill-finish qualification.
Established volume favors Glass Vials; emerging adoption favors Plastic Vials.
End User:
Procurement authority concentrates with organizations bearing direct regulatory filing responsibility and integrated analytical capabilities.
- Pharmaceutical Companies:Sponsors of monoclonal antibody and mRNA platforms specify Type I molded vials with ultra-low extractable profiles. CDMO partners in Boston-Cambridge and Basel corridors increasingly control container closure selection during early-phase protocol design.
- Biotechnology Firms:Venture-backed developers prioritize pre-filled formats to compress clinical trial startup timelines and reduce site training burdens.
- Research Laboratories:Academic and government facilities source lower-volume catalog configurations with flexible lot sizing for investigational protocols.
- Hospitals:Pharmacy compounding operations demand serialized trackable systems with integrated data matrix capabilities for EMA MDR compliance.
Procurement concentration sits with Pharmaceutical Companies; fastest capability buildout occurs in Biotechnology Firms.
Closure Type:
Elastomer formulation and sealing mechanism selection directly determines extractables profiles and container closure integrity performance.
- Rubber Stoppers:Halobutyl and bromobutyl compositions require extended extractables profiling and accelerated aging protocols to match aggressive biologic formulations. West Pharmaceutical Services differentiates via integrated elastomer closure systems that reduce contamination risk in fill-finish operations.
- Aluminum Seals:Crimped metal closures provide tamper-evidence and mechanical security for multi-dose vial presentations in hospital pharmacy settings.
- Snap-off Caps:Fracture-based opening mechanisms suit single-use diagnostic applications where luer connectivity is unnecessary.
- Luer Locks:Standardized connector interfaces enable direct syringe attachment for point-of-care reconstitution workflows.
Technical complexity concentrates in Rubber Stoppers; fastest standardization progress occurs in Luer Locks.
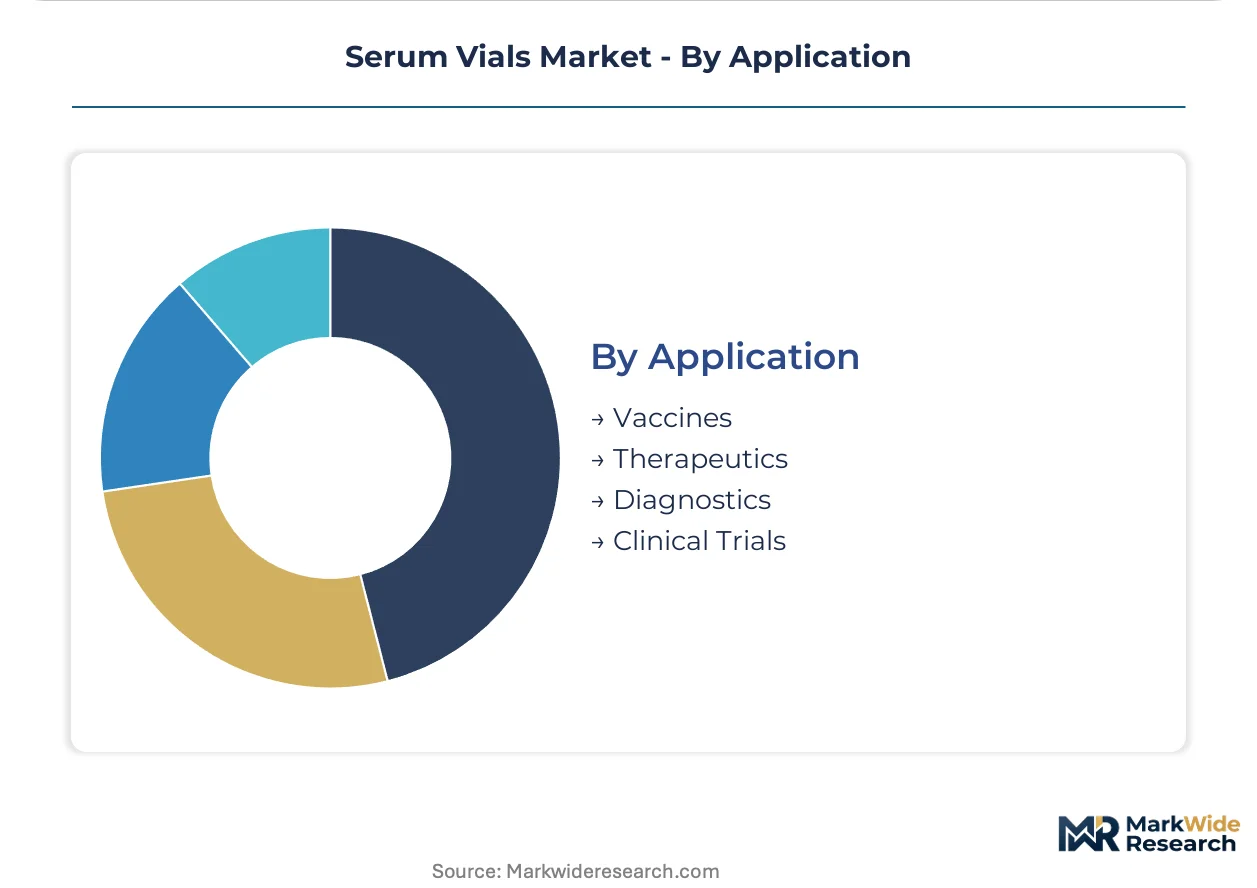
Application:
Therapeutic value and regulatory scrutiny intensity shape barrier performance requirements and qualification timeline expectations.
- Vaccines:Large-volume parenteral presentations require thermal shock-resistant formulations to withstand cold chain distribution stress. mRNA lipid nanoparticle platforms drive specialized Type I molded vial specifications.
- Therapeutics:High-value monoclonal antibodies and protein formulations demand oxygen and moisture ingress below 0.1 cc per year through shelf life, favoring aluminosilicate glass adoption to mitigate USP glass delamination guidance risks.
- Diagnostics:Reagent vials prioritize cost efficiency and breakage tolerance over ultra-high barrier performance, expanding polymer format share.
- Clinical Trials:Investigational product supplies require flexible lot sizing, accelerated stability protocols, and documentation packages supporting multinational regulatory submissions.
Barrier stringency peaks in Therapeutics; volume expansion steepest in Diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical sponsors and contract manufacturers concentrate procurement authority in corridors with integrated fill-finish capabilities and direct FDA or EMA filing pathways. Regional demand patterns track monoclonal antibody and mRNA pipeline density.
United States
The Boston-Cambridge corridor hosts dense CDMO networks where fill-finish providers now specify vial formats during early-phase protocol design. FDA container closure integrity requirements per USP <1207> mandate deterministic leak detection methods that exceed equipment availability at smaller contract manufacturers. New Jersey and North Carolina clusters anchor high-volume parenteral packaging operations for Phase III supplies.
Germany
Mainz and Mitterteich production clusters anchor European supply security for high-barrier borosilicate and aluminosilicate formulations. EMA MDR traceability mandates for Class III implantable-adjacent devices expand demand for serialized vial systems with integrated data matrix capabilities. SCHOTT AG and Gerresheimer AG sustain specialized furnace networks for Type I molded vial output.
Switzerland
Basel biotech corridor procurement patterns concentrate container closure selection decisions with CDMO partners possessing integrated analytical capabilities. Swissmedic requirements for drug-device combination filings compress supplier qualification timelines. Zurich and Geneva clusters support clinical trial material packaging for multinational sponsors.
China
NMPA standards on pharmaceutical packaging materials are converging with USP hydrolytic resistance specifications, elevating quality expectations for domestic borosilicate suppliers. Yangtze River Delta pharmaceutical manufacturing bases drive demand for pre-filled vial formats in biosimilar development. High-purity alumina supply concentration creates raw material security exposure for aluminosilicate formulations.
India
CDSCO filing pathways for complex generic injectables are accelerating adoption of Type I glass vials with documented extractables profiles. Maharashtra and Gujarat pharmaceutical manufacturing zones build fill-finish capacity for export markets. Domestic borosilicate tubing supply remains limited, sustaining import dependence for high-barrier applications.
Serum Vials Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Glass tubing manufacturers with captive furnace networks occupy positions of supply security, while integrated closure system providers capture value through contamination risk reduction. Strategic archetypes include: (1) European furnace-network operators with proprietary tubing formulations, (2) North American integrated closure-elastomer specialists, and (3) Asian scale-driven molded vial fabricators. Dominant competitive moves center on backward integration into alumina supply and capacity expansion for mRNA-compatible Type I molded formats.
Among European furnace-network operators, Gerresheimer AG and SCHOTT AG exemplify the tubing-to-vial integration archetype. West Pharmaceutical Services occupies a position within the integrated closure system tier. These three anchors represent divergent strategic postures: German AG-structured entities with legacy glass chemistry expertise versus US-based specialists combining elastomer formulation with fill-finish contamination control.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT AG |
| West Pharmaceutical Services |
| Stevanato Group |
| SGD Pharma |
| Corning Incorporated |
| DWK Life Sciences |
| Adelphi Healthcare Packaging |
| Pacific Vial Manufacturing Inc. |
| Others |
Value Network & Pricing Analysis
Single-source alumina dependency for aluminosilicate formulations determines both pricing tier spreads and supply chain shape across serum vial manufacturing, compressing margin structures for furnace operators while elevating premiums for backward-integrated producers with captive raw material access.
Pricing Analysis
Cost-plus contracts indexed to natural gas and electricity benchmarks dominate long-term pharmaceutical supply agreements, with ISO 15378 certification status and extractables testing depth driving price differentiation between tiers. Premium-mid-economy pricing stratification separates validated Type I molded formats from standard borosilicate catalog items. Pricing pressure stems from energy input volatility at European furnace networks. Contract research organizations and mid-volume biotech sponsors exhibit highest price sensitivity, while Big Pharma sponsors prioritize barrier performance over unit economics.
Supply Chain Analysis
Fill-finish contract manufacturers in Germany, Switzerland, and the United States hold concentrated capacity for serialized, EMA MDR-compliant vial systems. High-purity alumina from Chinese and Australian refining capacity feeds aluminosilicate glass chemistry, while halobutyl elastomer formulations hinge on petrochemical feedstock security. Single-source vulnerability concentrates in alumina supply for next-generation glass transitions. Distribution runs through direct pharmaceutical sponsor procurement and CDMO-specified channels with integrated closure system bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA platform proliferation and EMA MDR traceability mandates are accelerating demand inflection for specialized Type I molded formats, creating a high-growth disruption window for suppliers with validated serialization infrastructure.
For Market Incumbents: Harden furnace network reliability through captive alumina supply arrangements or long-term offtake agreements with Australian and Chinese refiners. Lock in CDMO partnership exclusives in the Boston-Cambridge and Basel corridors before notified body audit deadlines compress vendor consolidation timelines. Prioritize dual-format qualification from common tubing stock to capture pre-filled syringe adjacencies. For New Entrants and Emerging Players: Establish a beachhead in cyclic olefin polymer diagnostic vials for decentralized testing workflows, where breakage tolerance requirements create lower barrier-to-entry positioning against entrenched glass specialists. Target mid-tier biotech sponsors in India and China seeking documented extractables profiles for CDSCO and NMPA filings. Lead with flexible lot sizing and accelerated stability protocols as the go-to-market wedge. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated closure-system specialists with in-house elastomer formulation capabilities. Five-to-ten-year viability rests on backward integration into raw material supply and CDMO procurement authority concentration. Monitor FDA USP <1660> delamination guidance enforcement as the signal for accelerated aluminosilicate adoption and stranded borosilicate asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | Captive high-purity alumina access insulates margin structures from Chinese export restriction volatility. |
| Dual-Format Tubing Qualification | Common FIOLAX stock serving vial and pre-filled syringe formats captures mRNA platform volume. |
| Serialized Production Line Investment | Integrated data matrix capabilities satisfy EMA MDR traceability mandates for Class III combinations. |
| CDMO Partnership Exclusives | Early-phase protocol design influence locks in container closure specification authority. |
| Accelerated Extractables Profiling | Reduced qualification timelines attract biotech sponsors compressing clinical trial startup schedules. |
Research Methodology
The analysis maps glass formulation transitions, closure system integrations, and diagnostic polymer alternatives, each validated through primary interviews with fill-finish operations directors, regulatory affairs leads at biopharmaceutical sponsors, pharmaceutical packaging procurement managers, and notified body auditors. Secondary sources include FDA USP guidance documents, EMA MDR implementation guidelines, ISO 15378 certification registries, and pharmaceutical trade customs data. Bottom-up volume builds triangulate against top-down therapeutic pipeline assessments.
Fixed assumptions across the projection horizon include sustained EMA MDR enforcement timelines, continued mRNA platform expansion, and stable natural gas pricing bands for European furnace operations. Segmentation dimensions modeled encompass material chemistry, closure mechanism, end-user procurement authority, therapeutic application, and regional regulatory cluster. CAGRs derive from therapeutic pipeline density correlations and fill-finish capacity expansion schedules. Industry-specific inputs include monoclonal antibody development stage distributions and lipid nanoparticle formulation growth trajectories.
Sensitivities concentrate around alumina supply disruption, USP <1660> delamination guidance acceleration, and CDMO procurement authority shifts. Forecasts reflect modeling assumptions subject to revision from regulatory enforcement intensity or raw material security events. Quarterly review of EMA notified body audit schedules, FDA guidance publication cadence, and Chinese alumina export permit volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
US Pharmaceutical Isolators Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Pharmacy Automation Market