
 Hepatic Antiviral Drugs Market | 2026-2036
Hepatic Antiviral Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatic Antiviral Drugs Market Foresight
CE marking under the EU Medical Device Regulation is unwinding competitive access for European manufacturers of combination diagnostic-drug platforms. Gilead Sciences, Inc. leverages its captive supply of sofosbuvir intermediates to maintain manufacturing scale across multiple hepatitis indications. Bristol-Myers Squibb Company anchors its position through specialized R&D intensity in immunomodulatory antiviral approaches. AbbVie Inc. competes via differentiated pangenotypic coverage that simplifies prescribing decisions for hepatology clinics.
Hepatic antiviral drugs are pharmaceutical agents engineered to suppress or eradicate hepatotropic viruses through targeted inhibition of viral replication machinery, with nucleos(t)ide analogues functioning as chain terminators that interrupt reverse transcription at specific polymerase active sites. These therapies serve the primary commercial purpose of preventing cirrhosis progression and reducing hepatocellular carcinoma incidence in chronic hepatitis populations. Nucleos(t)ide analogues occupy the largest revenue pool within the product type dimension due to decades of clinical validation in hepatitis B maintenance therapy. Oral delivery mode leads volume consumption as fixed-dose combinations displace injectable interferon regimens, while protease inhibitors represent the fastest-growing chemistry class following their integration into curative hepatitis C protocols.
The FDA, EMA, and WHO prequalification programme collectively shape market access through divergent evidentiary standards for hepatitis B cure endpoints versus sustained virologic response definitions. REACH compliance in Europe and EPA manufacturing discharge rules in the United States add layer complexity to active pharmaceutical ingredient sourcing for nucleotide prodrugs. Stakeholders must monitor how regulatory divergence on hepatitis D orphan drug incentives reshapes portfolio prioritization across the development pipeline.
Market Dynamics
The transition from interferon-based regimens to interferon-free direct-acting antiviral combinations constitutes the dominant structural force compressing treatment duration from 48 weeks to 8-12 weeks while elevating cure thresholds.
Growth Catalysts
- Medicare reimbursement expansion:The United States Medicare framework now covers broad access to combination therapies for hepatitis C, eliminating prior authorization barriers that previously restricted patient eligibility.
- FDA Breakthrough Therapy pathway:This designation accelerates clinical review timelines for novel polymerase inhibitors, compressing development cycles for hepatitis B functional cure candidates.
- Hospital procurement centralization:Health systems are consolidating formulary decisions for direct-acting antivirals, creating volume commitments that stabilize manufacturing capacity utilization.
Market Restraints
- API sourcing concentration:Nucleotide prodrug intermediates concentrate among a limited supplier base in China and India, exposing manufacturers to geopolitical friction and export license volatility.
- REACH compliance costs:The EU's chemical registration requirements impose substantial documentation burdens on European manufacturers of combination diagnostic-drug platforms, elevating fixed costs for market access.
- Generic nucleos(t)ide analogue substitution:Patent expirations for foundational hepatitis B therapies enable low-cost alternatives that compress pricing power for originator products in maintenance therapy segments.
Strategic Opportunities
- Hepatitis D orphan drug incentives:Regulatory frameworks in the United States and Europe offer extended market exclusivity and tax credits for therapies addressing this co-infection population, attracting portfolio investment.
- Point-of-care diagnostic integration:Convergence of rapid viral load testing with treatment initiation protocols enables same-day prescribing in community health settings, expanding addressable patient pools.
- Japan's aging hepatitis C cohort:The country's concentrated population of untreated chronic infections represents a discrete demand reservoir for pangenotypic regimens with simplified resistance profiles.
Industry Challenges
- Virology specialist scarcity:Hepatology clinics face recruitment gaps for clinicians trained in resistance-associated substitution interpretation, creating bottlenecks in treatment optimization.
- EPA discharge compliance:Manufacturing facilities for nucleotide prodrugs must navigate evolving environmental discharge rules for active pharmaceutical ingredient synthesis, requiring capital deployment for wastewater treatment upgrades.
- Cross-border IP fragmentation:Patent thickets around sofosbuvir derivatives generate licensing complexity that delays generic entry in middle-income markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatic Antiviral Drugs Market |
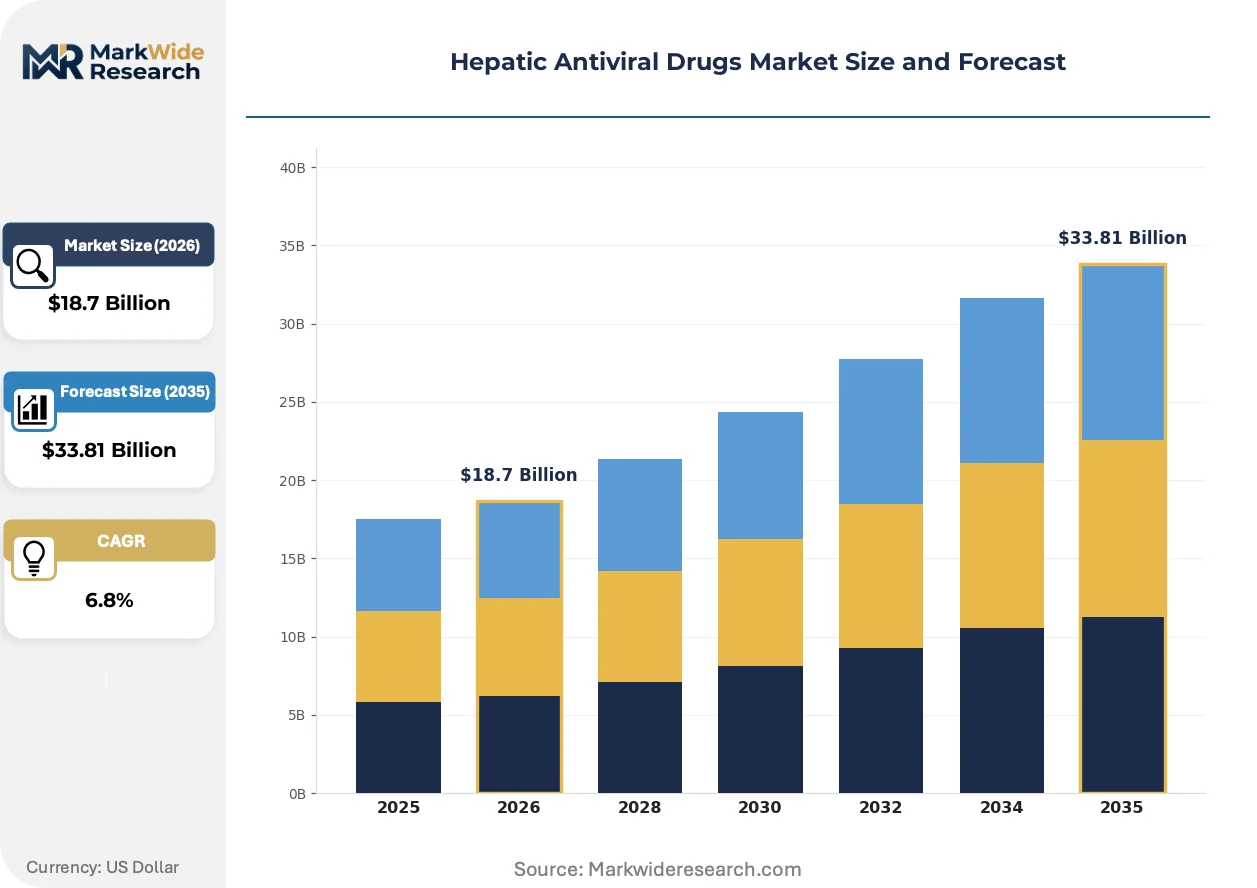
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interferons, Nucleos(t)ide Analogues, Protease Inhibitors, Polymerase Inhibitors Indication: Hepatitis B, Hepatitis C, Hepatitis D, Nonalcoholic Steatohepatitis Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Gilead Sciences, Inc., F. Hoffmann-La Roche Ltd., Bristol-Myers Squibb Company, AbbVie Inc., GlaxoSmithKline plc, Merck & Co., Inc., Novartis AG, Johnson & Johnson, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatic Antiviral Drugs Market Shifts & Advancements
Clinical development pipelines are pivoting toward functional cure endpoints for hepatitis B, while manufacturing processes adapt to accommodate smaller-batch personalized regimens and companion diagnostic bundling.
Next-generation capsid assembly modulators are bifurcating the hepatitis B therapeutic landscape. These agents disrupt viral core particle formation, offering mechanistic complementarity to polymerase inhibitors. Hepatology clinics in tertiary academic centers are piloting triple-combination protocols incorporating these modulators. The technology is bifurcating development risk between incremental maintenance improvements and transformative finite-duration regimens.
The EU Medical Device Regulation's CE marking requirements are reshaping competitive access for combination diagnostic-drug platforms. Manufacturers must now demonstrate clinical utility for integrated testing-treatment workflows, not merely analytical performance. European hepatology clinics are responding by consolidating procurement around suppliers with established IVDR technical documentation.
Hospital pharmacy benefit managers are consolidating formulary control over direct-acting antiviral procurement, displacing physician-directed prescribing through pre-negotiated therapeutic substitution protocols. This concentration is most pronounced in United States integrated delivery networks, where centralized committees now mandate specific combination regimens based on contracted rebates rather than individual resistance profiles.
Hepatic Antiviral Drugs Market Segmentation
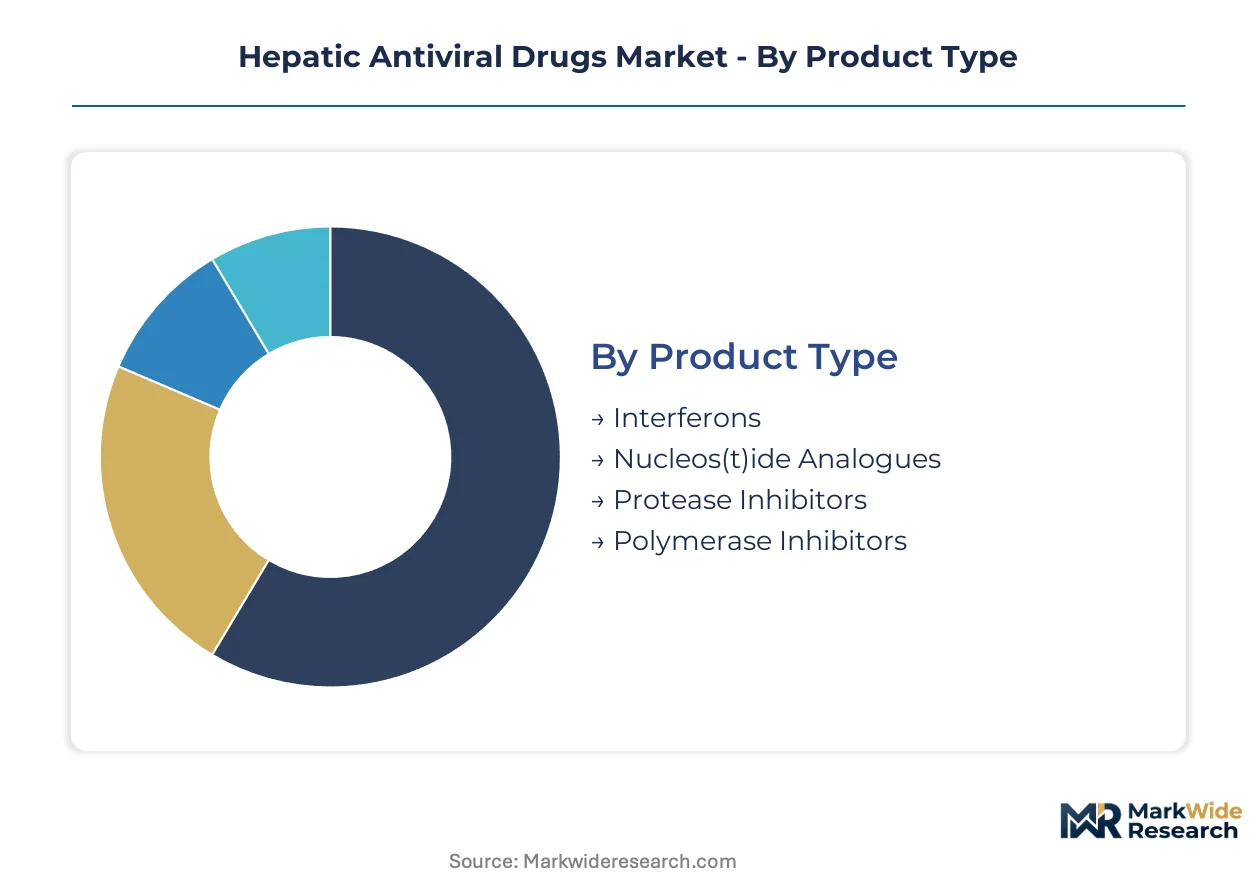
Segmentation in hepatic antivirals reveals divergent margin structures across chemistry classes and care settings. Procurement patterns vary sharply between hospital formulary systems and outpatient retail channels, while regulatory pathways differ by viral target and delivery mechanism.
Product Type:
Nucleos(t)ide analogues and polymerase inhibitors concentrate manufacturing in Asian API clusters, while interferon production retains European and North American finishing capacity.
- Nucleos(t)ide Analogues:Chain-terminating agents interrupt viral reverse transcription at polymerase active sites through incorporation into nascent DNA strands. Demand concentrates in China and India for hepatitis B maintenance therapy, where government tenders favor established oral regimens over novel mechanisms. Domestic manufacturing scale in these markets suppresses import dependency for first-line therapy.
- Protease Inhibitors:These agents cleave viral polyproteins into functional units, blocking replication assembly. Hepatitis C curative protocols in the United States and Japan drive procurement, with hospital systems negotiating exclusive contracts for NS3/4A inhibitors. Export-led demand from European reference pricing markets constrains pricing autonomy.
- Interferons:Immunomodulatory cytokines with broad-spectrum antiviral activity now face declining utilization as interferon-free regimens dominate hepatitis C. Remaining demand localizes in hepatitis B combination protocols and resource-limited settings with restricted access to direct-acting antivirals.
- Polymerase Inhibitors:Non-nucleoside agents target allosteric sites on viral polymerases, offering resistance-profile differentiation. Clinical development pipelines concentrate in the United States and Europe for hepatitis B functional cure candidates.
Nucleos(t)ide analogues hold the largest share; momentum sits with protease inhibitors.
Indication:
Cost tier stratification separates curative hepatitis C regimens from chronic hepatitis B maintenance, with hepatitis D commanding orphan-drug premiums.
- Hepatitis C:Direct-acting antiviral combinations achieve sustained virologic response in 8-12 week courses. Procurement concentrates in United States integrated delivery networks and Japan's aging untreated cohort, where pangenotypic coverage simplifies prescribing.
- Hepatitis B:Lifelong nucleos(t)ide analogue suppression dominates, with functional cure endpoints driving next-generation pipeline investment. Demand clusters in China and Southeast Asia where vertical transmission persists.
- Hepatitis D:Co-infection with hepatitis B creates severe disease progression, with limited therapeutic options and extended regulatory exclusivity incentives in the United States and Europe.
- Nonalcoholic Steatohepatitis:Emerging antiviral-adjacent indication with overlapping hepatology clinic infrastructure, though mechanistically distinct from viral suppression therapies.
Hepatitis B generates the highest patient volume; hepatitis C delivers the steepest revenue per treated patient.
Delivery Mode:
Volume concentration favors oral fixed-dose combinations, while margin protection concentrates in specialized injectable formulations for non-adherent populations.
- Oral:Fixed-dose combinations of direct-acting antivirals displace prior multi-pill regimens. Manufacturing scale concentrates in India for export to African and Southeast Asian markets under voluntary licensing agreements.
- Injectable:Pegylated interferon persists in hepatitis B combination trials and salvage therapy. Production localizes in European facilities subject to EMA GMP inspections.
- Intravenous:Limited to hospitalized decompensated cirrhosis patients with acute hepatitis flares, constraining addressable volume.
- Transdermal:Experimental delivery for nucleoside analogues in early development, targeting adherence improvement in maintenance populations.
Oral administration commands absolute volume share; intravenous delivery shows the narrowest expansion trajectory.
End User:
Customer type determines procurement sophistication, with hospital pharmacy benefit managers extracting steeper rebates than independent clinic purchasers.
- Hospitals:Centralized formulary committees in United States health systems mandate specific regimens through therapeutic substitution protocols. REACH compliance costs for European hospital procurement elevate supplier qualification barriers.
- Clinics:Hepatology specialty practices in tertiary academic centers pilot triple-combination protocols with capsid assembly modulators. Resistance-associated substitution interpretation capability constrains prescriber pool.
- Homecare:Oral direct-acting antiviral distribution through specialty pharmacies expands, supported by Medicare reimbursement frameworks in the United States.
- Research Institutions:Clinical trial supply for hepatitis B functional cure endpoints concentrates in academic medical centers with NIH or EMA-funded investigator networks.
Hospitals dominate procurement value; homecare channels are climbing the fastest as oral regimens enable decentralized treatment initiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States anchor buyer concentration, while health system centralization in Germany and Japan shapes formulary access patterns for direct-acting antiviral regimens.
United States
Medicare reimbursement frameworks eliminate prior authorization barriers for hepatitis C combination therapies, expanding patient eligibility for interferon-free regimens. The FDA's Breakthrough Therapy designation accelerates clinical review timelines for novel polymerase inhibitors targeting functional cure endpoints. Hospital pharmacy benefit managers in integrated delivery networks now mandate specific regimens through therapeutic substitution protocols based on contracted rebates.
Germany
Reference pricing mechanisms for hepatitis C direct-acting antivirals constrain pricing autonomy for manufacturers serving statutory health insurance funds. REACH compliance under ECHA requirements imposes substantial documentation burdens on European manufacturers of combination diagnostic-drug platforms. The Rhine-Main metropolitan cluster hosts centralized procurement operations for university hospital networks piloting triple-combination protocols with next-generation capsid assembly modulators.
Japan
An aging hepatitis C cohort concentrated in urban centers generates discrete demand for pangenotypic regimens with simplified resistance profiles. PMDA regulatory pathways prioritize sustained virologic response endpoints for hepatitis C curative protocols over hepatitis B functional cure candidates. The Kansai region around Osaka maintains specialized hepatology referral networks for interferon salvage therapy in treatment-experienced populations.
China
Government tenders for hepatitis B maintenance therapy favor established oral nucleos(t)ide analogue regimens over novel mechanisms, suppressing import dependency for first-line therapy. NMPA manufacturing standards for active pharmaceutical ingredient synthesis concentrate nucleotide prodrug intermediate production in Jiangsu and Zhejiang provinces. Domestic manufacturing scale in these coastal clusters enables export supply to African and Southeast Asian markets under voluntary licensing agreements.
India
CDSCO regulatory pathways for fixed-dose combination approvals support manufacturing scale for oral direct-acting antiviral export to resource-limited settings. Government procurement programs for hepatitis B nucleos(t)ide analogues prioritize low-cost generic substitution over originator products. The Hyderabad-Bengaluru pharmaceutical corridor hosts formulation facilities subject to WHO prequalification for supply to Global Fund procurement mechanisms.
Hepatic Antiviral Drugs Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with captive API supply chains and specialized biotech innovators pursuing hepatitis B functional cure endpoints. The market structure concentrates around three strategic archetypes: large-cap developers with vertically integrated manufacturing, mid-tier specialists in immunomodulatory approaches, and emerging players in capsid assembly modulation. Dominant competitive moves include strategic partnerships for diagnostic-drug platform integration and geographic licensing arrangements to navigate patent thickets in middle-income markets.
Within the large-cap integrated tier, Gilead Sciences, Inc. and Bristol-Myers Squibb Company occupy positions reflecting divergent R&D intensity strategies. Gilead exemplifies the API-captive manufacturing archetype through intermediate supply control across multiple hepatitis indications. Bristol-Myers Squibb represents the immunomodulatory specialization vector with focused pipeline investment. AbbVie Inc. anchors the pangenotypic simplification strategy, reducing prescriber decision complexity for hepatology clinics through differentiated resistance-profile coverage.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Novartis AG |
| Johnson & Johnson |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Captive manufacturing scale for sofosbuvir intermediates anchors Gilead's cost position across multiple hepatitis indications, compressing price floors for originator nucleos(t)ide analogues while elevating barriers for generic entrants in hepatitis C curative regimens. This concentration of upstream capacity in specific geographic clusters simultaneously shapes procurement leverage for hospital pharmacy benefit managers and exposes the market to export-license volatility from concentrated API sourcing.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers index to raw material baskets and energy benchmarks, stabilizing input costs for nucleotide prodrug manufacturers. Three-tier pricing structure across premium originator, authorized generic, and compulsory-licensed economy levels segments the hepatitis B maintenance market by prescriber sophistication and payer type. Pricing pressure stems from government tender mechanisms in China and India that favor low-cost generic nucleos(t)ide analogue substitution. Hospital systems in the United States demonstrate lowest price sensitivity due to Medicare reimbursement frameworks, while outpatient clinics in Southeast Asia face acute budget constraints.
Supply Chain Analysis
China and India anchor active pharmaceutical ingredient synthesis for nucleotide prodrugs, with Jiangsu and Zhejiang provinces hosting specialized intermediate manufacturing clusters. European finishing facilities in Germany and Switzerland draw from Asian API feedstocks for final formulation and packaging. Supply chain risk centers on single-source vulnerability for sofosbuvir derivative intermediates concentrated among limited Chinese suppliers. Distribution runs through hospital procurement committees in integrated delivery networks, with specialty pharmacy channels expanding for oral direct-acting antiviral homecare delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hepatic antiviral development sits in early-cycle expansion as interferon-free combination protocols displace legacy regimens, with Medicare reimbursement expansion in the United States accelerating patient access to curative hepatitis C therapies.
For Market Incumbents: Fortify manufacturing scale through backward integration into nucleotide prodrug intermediate production, securing supply continuity against export-license volatility from Chinese API clusters. Deepen hospital formulary relationships through therapeutic substitution protocols that preempt generic entry in hepatitis B maintenance segments. Resistance-associated substitution interpretation capability scarcity constrains prescriber pools; invest in clinician education programs to defend prescribing share.
For New Entrants and Emerging Players: Lead with point-of-care diagnostic integration targeting community health settings in the United States and Japan, where same-day prescribing protocols expand addressable patient pools beyond tertiary academic centers. Hepatitis D orphan drug incentives in the United States and Europe offer extended market exclusivity with limited competitive density. Pursue capsid assembly modulator development through academic medical center partnerships to access NIH-funded investigator networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotech innovators with hepatitis B functional cure pipelines over mature hepatitis C asset holders facing patent cliff exposure. Long-term viability hinges on regulatory divergence between FDA Breakthrough Therapy pathways and EMA evidentiary standards for cure endpoints. Watch hepatitis B functional cure readouts as the primary inflection indicator for portfolio reallocation between maintenance and curative mechanism investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Capsid assembly modulator triple-combination protocols in tertiary academic centers accelerate hepatitis B functional cure endpoints. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses development timelines for novel polymerase inhibitors targeting curative regimens. |
| Licensing Agreement | Voluntary licensing arrangements with Indian manufacturers expand access to African and Southeast Asian markets under WHO prequalification. |
| Manufacturing Scale-Up | Hospital procurement centralization creates volume commitments that stabilize capacity utilization for direct-acting antiviral production. |
| Pipeline Diversification | Hepatitis D orphan drug development attracts portfolio investment through extended exclusivity incentives in the United States and Europe. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration against market developments throughout the study period. Primary interviews with formulary directors in United States integrated delivery networks and hepatology clinic administrators in Germany and Japan were cross-referenced against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled chemistry class, indication, delivery mode, and end user as core segmentation dimensions, with regional regulatory cluster as an additional stratification layer. CAGRs were derived from patient population epidemiology, treatment penetration assumptions, and pricing trajectory analysis. Forecast inputs incorporated Medicare reimbursement policy evolution, REACH compliance cost burdens, and generic substitution timelines for nucleos(t)ide analogues.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement expansion, stable API export licensing from China and India, or continued FDA Breakthrough Therapy pathway utilization would require recalibration. Forecasts reflect documented assumptions regarding hepatitis B functional cure endpoint definitions, hospital formulary consolidation rates, and interferon-free regimen adoption curves. Recalibration cycles align with material shifts in regulatory divergence on hepatitis D orphan incentives and capsid assembly modulator clinical readouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Global Osteoporosis Drugs Market