
 Medication Dispenser Market | 2026-2036
Medication Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Medication Dispenser Market Outlook
FDA 21 CFR Part 820 quality system regulation is broadening the cost-of-entry calculus for medication dispenser manufacturers seeking US market access. Becton, Dickinson and Company leverages its vertically integrated manufacturing footprint to sustain competitive positioning in automated dispensing systems. Omnicell Inc. anchors its presence through proprietary software-hardware integration across hospital networks. Capsa Healthcare differentiates via specialized cart-based dispensing solutions for long-term care environments.
A medication dispenser is an electromechanical or mechanical device engineered to store, organize, and release pharmaceutical doses at predetermined intervals, typically incorporating sensors, locking mechanisms, and compliance-tracking software with dispensing accuracy tolerances of plus or minus one pill. The primary purpose is reducing medication errors and improving therapeutic adherence in clinical and ambulatory settings. Electronic dispensers command the dominant installed base in hospitals, though smart dispensers with Bluetooth connectivity represent the fastest-expanding margin pool as remote patient monitoring protocols mature. RFID-based technology segments lead in acute care due to real-time inventory tracking requirements, while voice-assisted interfaces gain traction in home care applications serving cognitively impaired users.
FDA 21 CFR Part 820 and HIPAA privacy standards collectively determine product certification pathways and data handling architectures for US-bound devices. The EU Medical Device Regulation imposes additional clinical evidence requirements on smart dispenser manufacturers accessing European markets. Stakeholders must monitor evolving interoperability mandates between dispensers and electronic health record systems as a decisive factor for procurement decisions.
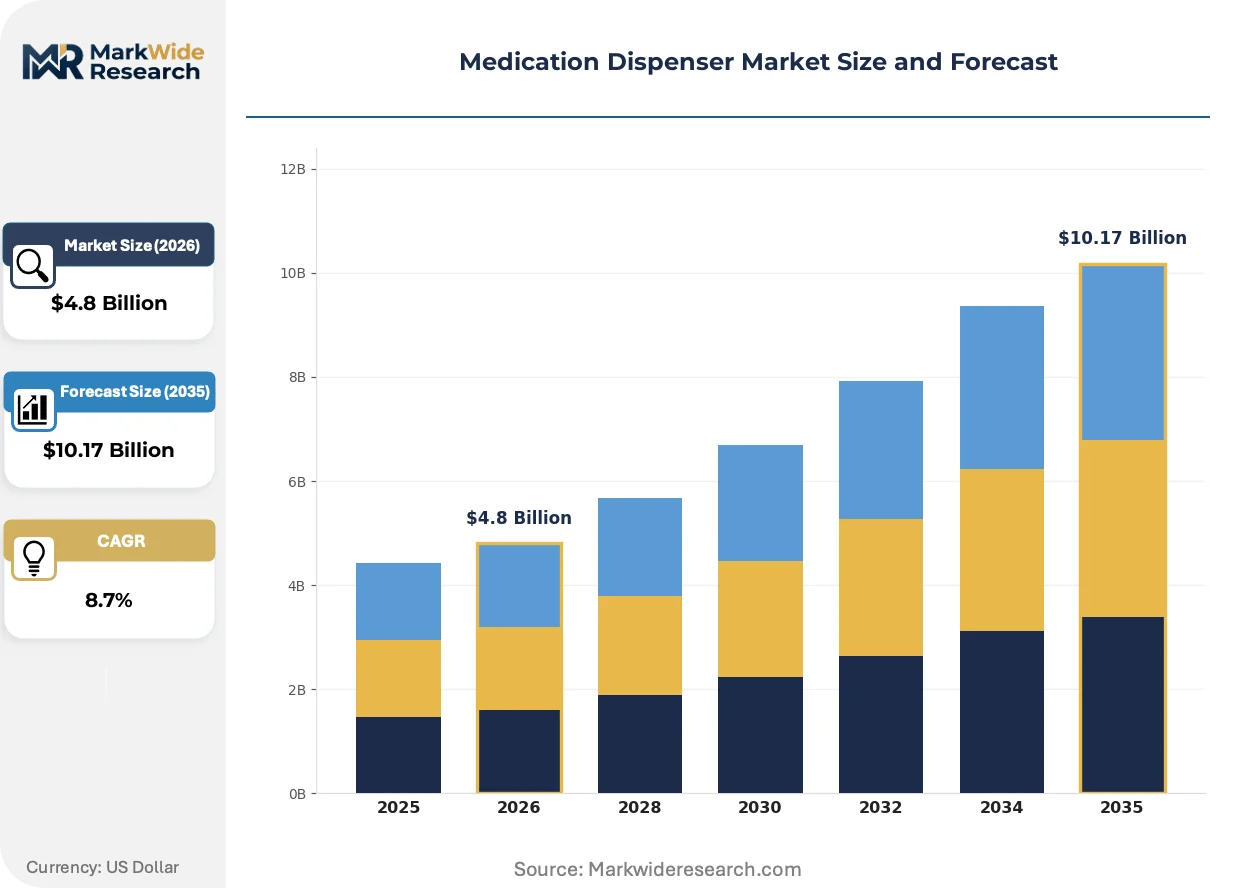
Market Dynamics
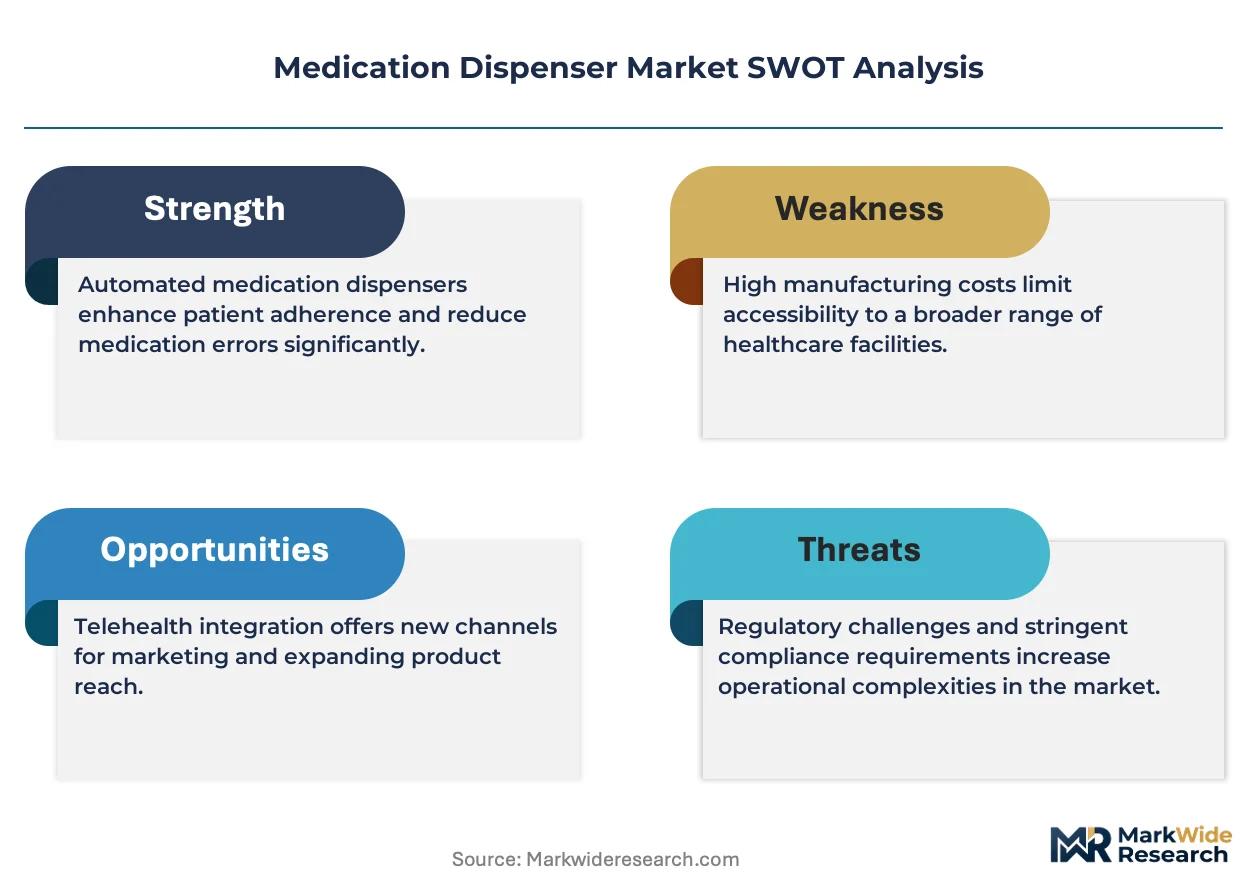
Medicare reimbursement policies favoring adherence technologies are concentrating demand in the United States, while FDA 21 CFR Part 820 compliance costs are filtering out undercapitalized entrants across automated dispensing systems.
Growth Catalysts
- Polypharmacy management demand:Aging populations managing five-plus concurrent prescriptions are driving home care adoption of electronic dispensers with compliance-tracking software.
- Medicare reimbursement alignment:US federal policies now cover remote therapeutic monitoring devices, reducing out-of-pocket barriers for Medicare Advantage enrollees.
- Bluetooth-enabled remote monitoring:Smart dispensers with wireless connectivity are capturing share in post-acute care settings as telehealth protocols mature.
Market Restraints
- FDA 21 CFR Part 820 compliance burden:Quality system documentation and validation requirements add twelve-to-eighteen-month certification timelines for new hardware entrants.
- Semiconductor supply concentration:Sensor and microcontroller sourcing from concentrated Asian foundries creates vulnerability for electromechanical dispenser production.
- Mechanical dispenser substitution:Low-cost pill organizers without electronic features retain price-sensitive segments in developing markets.
Strategic Opportunities
- Voice-assisted interfaces:Speech recognition technology convergence with dispensing hardware opens cognitive-impairment segments in home care.
- EU Medical Device Regulation clinical evidence pathways:Manufacturers with existing FDA 510(k) clearances can leverage predicate device strategies for European market entry.
- Long-term care facility penetration:Specialized cart-based dispensing solutions remain underdeployed in skilled nursing environments outside the United States.
Industry Challenges
- EHR interoperability certification:HL7 FHIR integration requirements demand specialized health informatics talent scarce among traditional medical device engineering teams.
- HIPAA-compliant cloud architecture:Real-time adherence data transmission requires hardened data handling infrastructure with audit trail capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medication Dispenser Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispensers, Electronic Dispensers, Smart Dispensers, Pill Organizers End User: Hospitals, Home Care, Long-term Care Facilities, Pharmacies Technology: RFID-Based, Barcode Scanning, Bluetooth Connectivity, Voice Assisted Application: Chronic Disease Management, Medication Adherence, Post-Surgery Care, Elderly Care |
| Companies Covered | Becton, Dickinson and Company, Omnicell Inc., Cerner Corporation, Capsa Healthcare, ScriptPro LLC, McKesson Corporation, Yuyama Co., Ltd., Swisslog Holding AG, InstyMeds Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medication Dispenser Market Strategic Shifts
RFID-based inventory tracking is overtaking barcode systems in acute care, while voice-assisted interfaces are penetrating cognitive-impairment segments. Regulatory pressure on data interoperability is forcing architecture redesigns.
RFID-enabled medication dispensers with real-time inventory visibility are overtaking legacy barcode scanning systems in hospital pharmacy operations. Acute care networks in the United States and Germany are deploying these systems to reduce nursing medication administration errors. The technology is compressing dispensing cycle times and enabling automated replenishment workflows that reduce pharmacy labor intensity.
EU Medical Device Regulation clinical evidence requirements are elevating documentation burdens for smart dispenser manufacturers accessing European markets. Manufacturers must now submit post-market surveillance data and usability validation studies previously exempt under the Medical Device Directive. Small-to-mid-sized hardware developers are responding by partnering with notified bodies early in design phases.
Hospital procurement committees are bundling dispenser purchases with electronic health record integration contracts rather than acquiring hardware standalone. Health systems in the United States are favoring vendors with pre-certified interoperability modules over those requiring custom interface development. This pattern is most visible in Medicare Advantage network expansions where value-based care metrics require seamless adherence data flow.
Medication Dispenser Market Segmentation
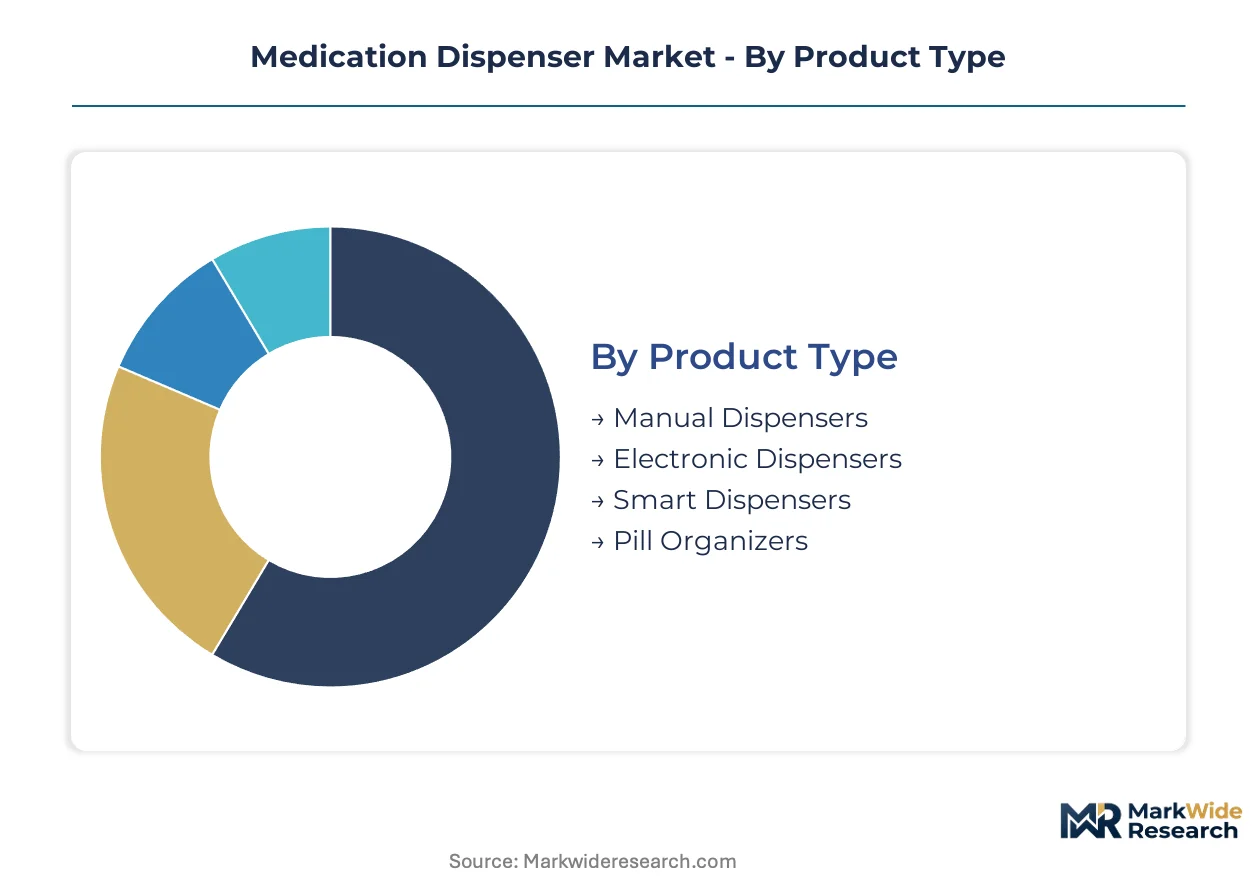
Segmentation in medication dispensers determines which regulatory pathways manufacturers must navigate and where pricing power concentrates. Technology sophistication and care setting requirements create distinct margin pools across product architectures.
Product Type:
FDA 21 CFR Part 820 compliance requirements escalate sharply from mechanical to connected systems, with smart dispensers demanding full quality system documentation and software validation protocols.
- Manual Dispensers:Spring-loaded or gravity-fed mechanical devices with no electronic components, typically fabricated from pharmaceutical-grade polymers. Demand clusters in price-sensitive developing markets and institutional bulk purchasing programs where capital constraints override feature requirements.
- Electronic Dispensers:Electromechanical systems incorporating programmable timers, locking mechanisms, and basic compliance logging with dispensing accuracy tolerances of plus or minus one pill. Hospital pharmacies in the United States and Germany deploy these for unit-dose automation where FDA and BfArM (Germany's Federal Institute for Drugs and Medical Devices) quality system requirements apply.
- Smart Dispensers:Connected devices with Bluetooth, Wi-Fi, or cellular modules enabling real-time adherence monitoring and caregiver alerts. These require FCC certification in the United States, CE marking under EU MDR, and HIPAA or GDPR compliance for data transmission.
- Pill Organizers:Non-electronic compartmentalized containers for weekly or monthly medication sorting. Retail pharmacy chains and direct-to-consumer channels dominate distribution.
Electronic dispensers sit at the top of the volume ranking, with smart dispensers climbing the fastest.
End User:
Procurement authority and reimbursement pathways diverge sharply across care settings, with Medicare Advantage policies favoring home-based adherence technologies.
- Hospitals:Acute care networks require enterprise-grade dispensing systems with EHR integration, barcode or RFID verification, and centralized inventory management. US health systems prioritize vendors with pre-certified HL7 FHIR modules.
- Home Care:Individual patients and family caregivers purchase standalone or subscription-based dispensers, often through Medicare Advantage supplemental benefits or private pay. Bluetooth-enabled devices with remote monitoring capabilities are gaining share fastest in this segment.
- Long-term Care Facilities:Skilled nursing and assisted living environments need cart-based or wall-mounted dispensing systems with multi-patient capacity and tamper-resistant design. Regulatory oversight falls to state-level departments of health in the United States.
- Pharmacies:Retail and specialty pharmacies deploy behind-the-counter automation for prescription fulfillment and adherence packaging programs.
Hospitals command the largest installed base, while home care shows the steepest expansion trajectory.
Technology:
Hardware authentication methods determine integration complexity and cybersecurity exposure for dispenser networks handling protected health information.
- RFID-Based:Radio-frequency identification tags on medication packaging enable real-time inventory tracking and automated restocking workflows. Acute care networks in the United States and Germany favor this technology for its error-reduction capabilities in high-volume settings.
- Barcode Scanning:Legacy optical scanning systems for medication verification, now declining in new installations as RFID infrastructure spreads.
- Bluetooth Connectivity:Low-energy wireless protocols linking dispensers to smartphones, tablets, or hub devices for remote monitoring. Post-acute care and home care applications are driving adoption where telehealth reimbursement supports remote therapeutic monitoring.
- Voice Assisted:Speech recognition interfaces guiding cognitively impaired users through dosing routines. Long-term care facilities serving dementia populations represent the primary demand concentration.
RFID-based systems lead in revenue contribution, with voice-assisted interfaces expanding most quickly in specialized care segments.
Application:
Clinical use case determines feature prioritization, from simple reminder functions to complex multi-drug regimens with dose escalation protocols.
- Chronic Disease Management:Long-term medication adherence for diabetes, hypertension, cardiovascular conditions, and respiratory diseases. Medicare Advantage plans in the United States increasingly cover connected dispensers as remote therapeutic monitoring devices.
- Medication Adherence:General-purpose compliance improvement across polypharmacy regimens, typically five or more concurrent prescriptions. Aging populations in Japan and Western Europe drive demand for automated dispensing with caregiver notification.
- Post-Surgery Care:Short-term pain management and antibiotic protocols requiring precise timing and dose tapering. Hospital discharge planning programs incorporate take-home dispensers to reduce readmission risk.
- Elderly Care:Age-specific dispensing with large-format displays, simplified interfaces, and fall-safe medication access for independent living or assisted care.
Chronic disease management anchors volume, with elderly care gaining share fastest as demographic aging accelerates across developed economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Minneapolis-St. Paul, Boston-Cambridge, and the Research Triangle anchor North American dispenser innovation. German precision manufacturing expertise concentrates in Baden-Württemberg and Bavaria. Japanese robotics competency centers on Nagoya and Osaka-Kobe corridors.
United States
Medicare Advantage expansion and remote therapeutic monitoring reimbursement are accelerating home care dispenser deployment. FDA 21 CFR Part 820 quality system requirements filter hardware entrants through extended validation timelines. The Minneapolis-St. Paul corridor hosts concentrated automated dispensing engineering talent serving hospital network procurement.
Germany
BfArM medical device oversight and statutory health insurance digitization mandates are elevating smart dispenser standards. Acute care networks in North Rhine-Westphalia prioritize RFID-enabled inventory systems for nursing error reduction. The Baden-Württemberg precision manufacturing cluster supplies electromechanical components to European dispenser OEMs.
Japan
Super-aging demographics and PMDA streamlined approval pathways for software-as-medical-device are expanding connected dispenser access. The Nagoya robotics engineering corridor develops compact dispensing units for constrained home care environments. METI regional healthcare digitization subsidies support voice-assisted interface adoption in dementia care facilities.
China
NMPA Class II medical device registration reforms and tiered diagnosis-treatment system expansion are opening hospital automation procurement. The Yangtze River Delta biomedical device manufacturing belt scales electromechanical dispenser production for domestic and Southeast Asian markets. Shanghai-based health informatics vendors develop EHR interoperability modules for dispenser integration.
United Kingdom
NHS Long Term Plan digital pharmacy commitments and MHRA post-Brexit regulatory autonomy are reshaping procurement specifications. The Greater London health tech cluster attracts dispenser software startups targeting medication adherence analytics. Cambridge-based sensor technology firms supply microcontroller components to European dispenser manufacturers.
Medication Dispenser Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with vertically integrated manufacturing footprints. Hospital pharmacy automation demands enterprise-scale quality systems and regulatory documentation capabilities that favor established players with captive supply chains. Two strategic archetypes dominate: diversified health technology conglomerates leveraging cross-portfolio synergies, and specialized automation vendors with concentrated dispensing expertise. Competitive moves center on EHR interoperability certification racing and strategic partnerships with telehealth platform providers.
Among diversified health technology conglomerates, Becton, Dickinson and Company and McKesson Corporation exemplify scale-driven positioning through integrated distribution and device manufacturing capabilities. Omnicell Inc. and Capsa Healthcare occupy specialized automation tiers, with the former representing software-hardware integration archetypes and the latter exemplifying care-setting-specific hardware design. Yuyama Co., Ltd. and Swisslog Holding AG anchor precision manufacturing and logistics automation expertise respectively, reflecting geographic concentration of electromechanical engineering competency in Japanese and German industrial clusters.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Omnicell Inc. |
| Cerner Corporation |
| Capsa Healthcare |
| ScriptPro LLC |
| McKesson Corporation |
| Yuyama Co., Ltd. |
| Swisslog Holding AG |
| InstyMeds Corporation |
| Others |
Value Chain & Pricing Dynamics
Medicare Advantage procurement committees bundling dispenser purchases with EHR integration contracts are forcing manufacturers to absorb software development costs into hardware pricing, compressing margins on standalone units while elevating bundled service premiums.
Pricing Analysis
Bundled hardware-software service contracts dominate hospital procurement, while unbundled transactional sales persist in home care direct-to-consumer channels. Pricing stratifies across FDA 510(k)-cleared enterprise systems, CE-marked mid-tier connected devices, and non-certified mechanical dispensers for price-sensitive institutional buyers. Cost compression in the mechanical tier is intensifying because low-cost Asian manufacturers are flooding developing markets with unregulated alternatives. Home care patients purchasing through Medicare Advantage supplemental benefits show lowest price sensitivity, while long-term care facilities operating on fixed state reimbursement rates exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundries producing microcontroller units and Japanese suppliers of precision stepper motors for electromechanical dispensing mechanisms. Electromechanical dispenser production draws from China for pharmaceutical-grade polymer housings, Germany for sensor assemblies, and South Korea for Bluetooth module chipsets. Tariff exposure on Chinese-sourced plastics and metal stampings threatens margin stability for mid-tier manufacturers. Distribution runs through GPO contracts for hospital networks, direct sales forces for long-term care, and retail pharmacy chains for home care consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medication dispenser market functions as a stable compounder anchored by irreversible demographic aging and polypharmacy prevalence across developed economies.
For Market Incumbents: Deepen proprietary software-hardware integration to lock in hospital network switching costs against emerging cloud-native dispenser startups. Fortify FDA 510(k) predicate device portfolios to accelerate European MDR clearance through established clinical evidence pathways. Prioritize captive production of sensor assemblies in Germany or Japan to reduce Taiwanese foundry concentration risk. For New Entrants and Emerging Players: The mid-tier price gap between Omnicell-tier enterprise systems and basic mechanical dispensers offers fertile ground for voice-assisted home care devices with simplified Bluetooth connectivity. Skilled nursing facilities outside the United States remain dramatically underpenetrated by cart-based dispensing automation. Pursue white-label partnerships with telehealth platform providers to bypass direct hospital procurement committee barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized automation vendors possessing concentrated dispensing expertise but lacking enterprise-scale regulatory documentation capabilities. The five-to-ten-year viability window favors acquisition targets with pre-certified HL7 FHIR interoperability modules and existing Medicare Advantage network relationships. Watch for inflection when CMS expands remote therapeutic monitoring reimbursement to include voice-assisted adherence devices.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Device Expansion | Accelerates EU MDR market entry through leveraged clinical evidence documentation. |
| HL7 FHIR Interoperability Certification | Unlocks hospital procurement committee preference for pre-integrated EHR connectivity. |
| Voice Interface Development Partnership | Captures dementia care segments in Japan's METI-subsidized facility digitization programs. |
| Cart-Based Dispensing System Localization | Addresses regulatory gaps in German BfArM oversight for long-term care environments. |
| Remote Therapeutic Monitoring Reimbursement Strategy | Aligns product positioning with CMS Medicare Advantage supplemental benefit expansion. |
Study Parameters
Direct dialogue with hospital pharmacy directors, biomedical engineering procurement leads, long-term care facility administrators, and Medicare Advantage plan formulary managers anchored the primary research foundation. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement bulletins, EU MDR notified body guidance documents, and hospital GPO contract award disclosures. Bottom-up installed base estimates triangulated against top-down spending projections from national health accounts.
Segment-level value outputs across the projection horizon reflect modeled interactions between product type sophistication, end-user procurement authority, and technology authentication requirements. The analytical framework incorporated dispensing accuracy tolerances, software validation burden, and interoperability certification status as medication-dispenser-specific forecast inputs. CAGRs emerged from regression-weighted scenario analysis rather than single-point extrapolation.
Caveats apply where FDA quality system enforcement intensity or EU MDR clinical evidence requirement evolution could materially shift the outlook for smart dispenser market access timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Small Molecule CDMO Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market