
 ASEAN Contract Development and Manufacturing Organization (CDMO) Market | 2026-2036
ASEAN Contract Development and Manufacturing Organization (CDMO) Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Contract Development and Manufacturing Organization (CDMO) Market Intelligence
Asset-light project financing and build-to-suit facility leasing is fragmenting competitive dynamics across the ASEAN CDMO landscape. Lonza leverages its Singapore biologics campus to anchor high-value mammalian cell culture capacity for regional biotech clients. Thermo Fisher Scientific competes through integrated analytical testing and clinical trial material networks spanning multiple ASEAN jurisdictions. Samsung Biologics extends its Korean bioprocessing expertise into Singapore through dedicated contract manufacturing infrastructure.
A Contract Development and Manufacturing Organization provides outsourced pharmaceutical development services spanning drug substance synthesis, formulation design, stability validation, and commercial-scale production under current Good Manufacturing Practice standards. These entities manage technology transfer, process characterization, and regulatory filing support to accelerate time-to-market for sponsor molecules. Biologics manufacturing leads service type revenue pools given capital intensity and specialized cleanroom requirements, while analytical testing sustains recurring margin streams through long-term stability protocols. High-throughput screening and cell culture platforms represent the fastest-expanding technology segments as gene therapy and monoclonal antibody pipelines multiply across ASEAN research institutes.
Singapore's Health Sciences Authority enforces stringent GMP inspections that shape facility investment thresholds and qualification timelines for CDMO entrants. Thailand's Food and Drug Administration and Malaysia's National Pharmaceutical Regulatory Agency apply ASEAN Common Technical Dossier standards that harmonize submission pathways across member states. Stakeholders must monitor evolving biosimilar guidance from ASEAN harmonization bodies and assess captive versus outsourced manufacturing trade-offs before committing to greenfield capacity.
Market Dynamics
Biologics manufacturing adoption is fragmenting capacity ownership across ASEAN biotechnology firms, as asset-light financing models enable sponsor companies to access specialized mammalian cell culture infrastructure without committing to multi-year facility construction timelines.
Growth Catalysts
- ASEAN Common Technical Dossier harmonization:Thailand's Food and Drug Administration and Malaysia's National Pharmaceutical Regulatory Agency now align submission standards, compressing cross-border trial approval cycles for regional sponsors.
- Gene therapy pipeline expansion:High-throughput screening platforms at Singapore's Tuas Biomedical Park are attracting monoclonal antibody developers seeking integrated process characterization services.
- Singapore biologics cluster concentration:Health Sciences Authority GMP inspection rigor creates qualification benchmarks that regional CDMOs leverage for credibility with multinational sponsors.
Market Restraints
- Single-use bioreactor supply concentration:Film and sensor components for disposable manufacturing systems originate from limited East Asian suppliers, exposing ASEAN CDMOs to input volatility.
- Specialized talent scarcity:Cell culture process engineers with current Good Manufacturing Practice experience command premium compensation, elevating operating cost structures.
- Regulatory inspection backlog:Health Sciences Authority qualification timelines extend facility revenue recognition delays for new market entrants.
Strategic Opportunities
- Indonesia biopharma underpenetration:Southeast Asia's largest population base lacks domestic biologics manufacturing depth, creating first-mover positioning for CDMOs establishing Jakarta satellite operations.
- Continuous processing technology convergence:Perfusion bioreactor systems integrated with real-time quality analytics enable smaller-footprint facilities with higher throughput economics.
- Vietnam clinical trial material demand:Emerging biotechnology research institutes in Ho Chi Minh City seek regional partners for Phase I comparator drug sourcing.
Industry Challenges
- Technology transfer complexity:Sponsor-to-CDMO process characterization protocols require 12-18 month validation cycles that compress contracted revenue windows.
- Quality systems integration friction:Legacy enterprise resource planning platforms at sponsor organizations resist seamless data exchange with CDMO laboratory information management systems.
- IP licensing fragmentation:Platform cell line patents held by diversified tool vendors create royalty stacking that erodes project margin visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Contract Development and Manufacturing Organization (CDMO) Market |
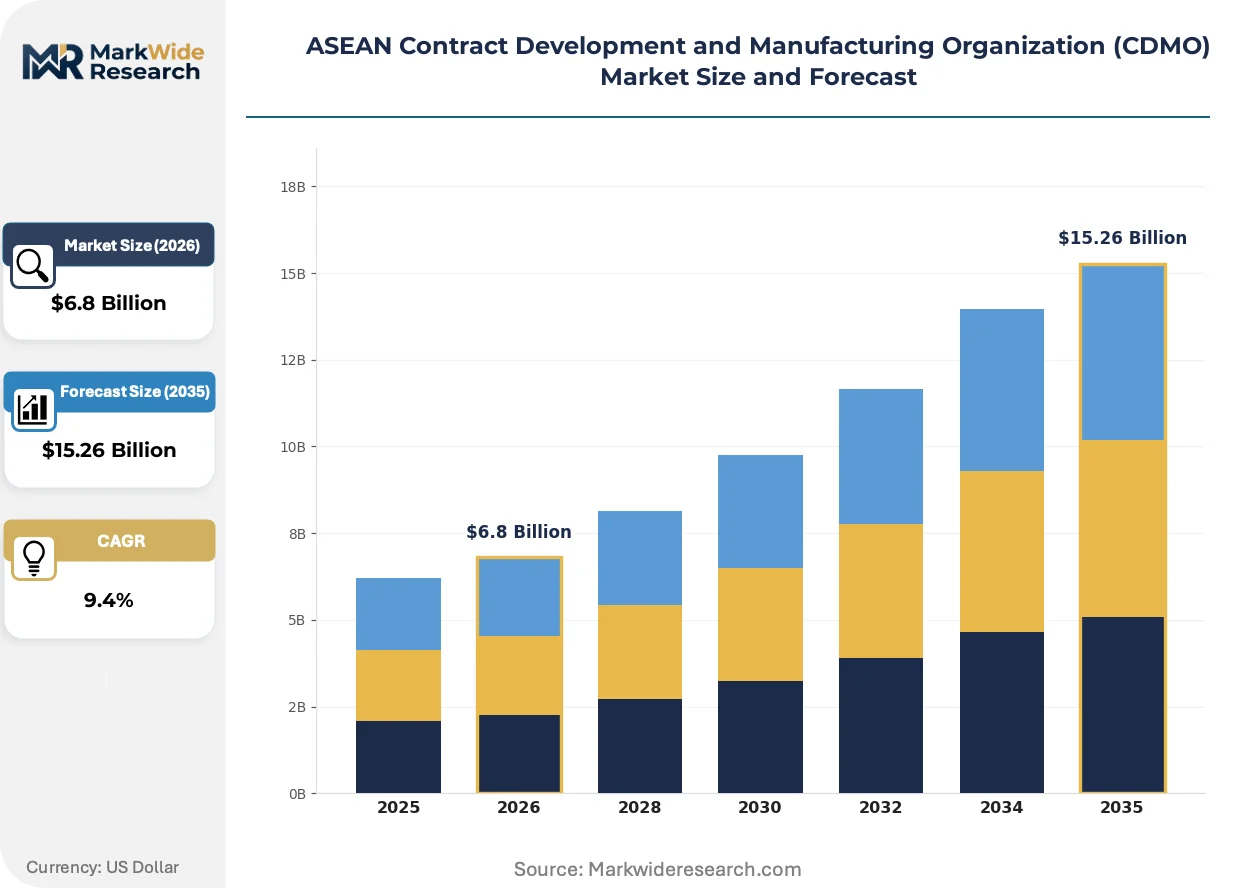
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Formulation Development, Analytical Testing, Biologics Manufacturing, Clinical Trial Material Production, Packaging, Stability Studies Technology: Small Molecule Synthesis, Bioprocessing, Cell Culture, High-Throughput Screening, Chromatography, Lyophilization Application: Oncology, Vaccines, Infectious Diseases, Cardiovascular, Dermatology, Neurology End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Generic Manufacturers, Nutraceutical Producers |
| Companies Covered | Parexel International Corporation, PPD International, Lonza, Recipharm, Thermo Fisher Scientific Inc., Catalent Inc., IQVIA, Cambrex Corporation, Samsung Biologics, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Contract Development and Manufacturing Organization (CDMO) Market Strategic Shifts & Innovations
Process intensification technologies are compressing batch cycle times while regulatory data harmonization efforts reshape cross-border submission strategies across ASEAN pharmaceutical outsourcing networks.
Continuous bioprocessing is migrating from stainless-steel fed-batch systems toward perfusion-based manufacturing platforms. Mid-cap biotechnology sponsors in Singapore and Malaysia are adopting these systems to reduce facility capital intensity. The technology is migrating from early-phase clinical material production into commercial-scale antibody manufacturing, enabling 10,000-liter equivalent output from 2,000-liter single-use footprints.
ASEAN's harmonized pharmaceutical regulatory frameworks are streamlining multi-country trial approvals through mutual recognition protocols. Thailand's Food and Drug Administration now accepts Singapore Health Sciences Authority inspection reports for facility qualification. Regional CDMOs with Singapore-registered sites are capturing sponsor contracts that previously required separate Malaysia and Indonesia regulatory filings.
Sponsor procurement patterns favor integrated service contracts spanning drug substance synthesis through commercial fill-finish. Biotechnology firms in Singapore's One-North research corridor are consolidating vendor relationships to reduce technology transfer handoff risks. This concentration is most visible among gene therapy developers seeking single-accountability partners for viral vector manufacturing and regulatory filing support.
ASEAN Contract Development and Manufacturing Organization (CDMO) Market Segmentation
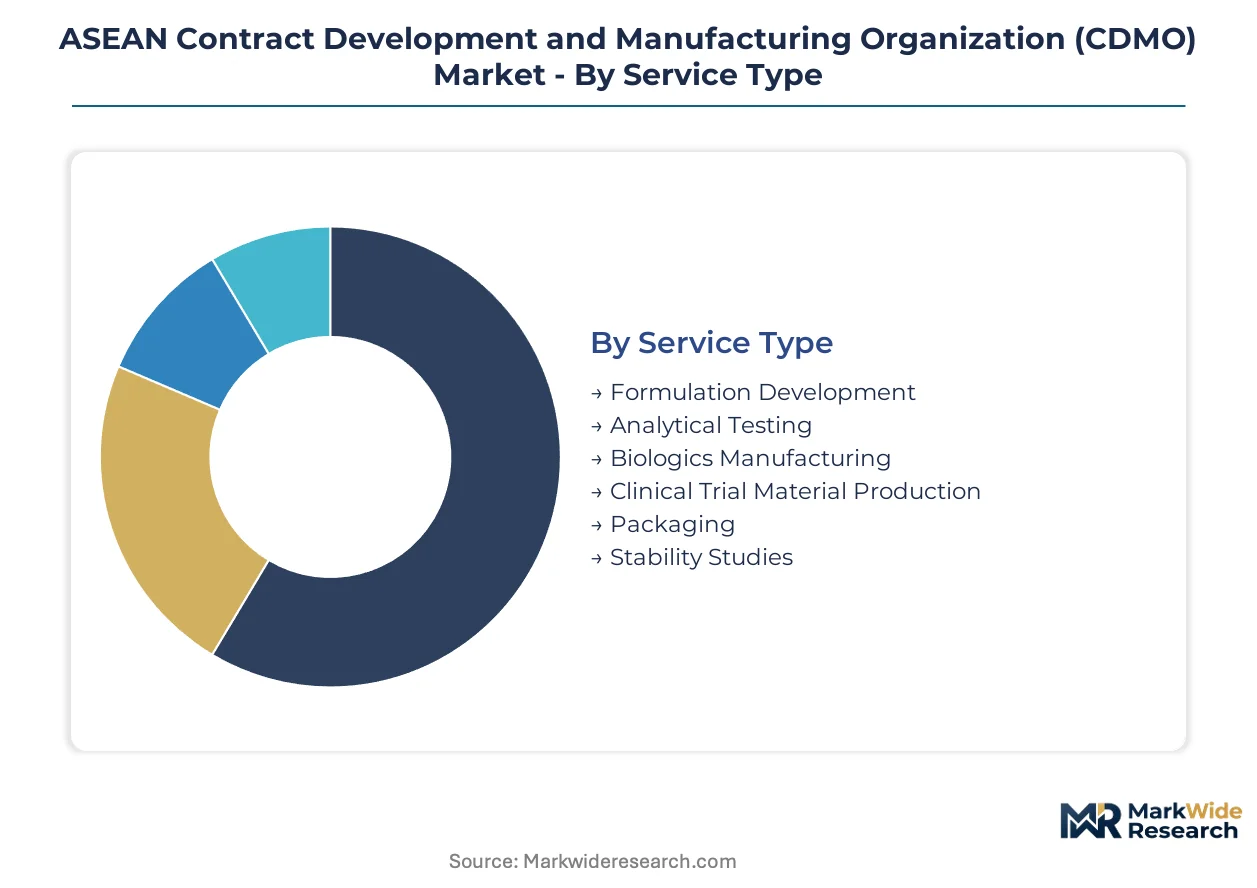
ASEAN CDMO procurement patterns fragment across service complexity tiers, technology platforms, therapeutic applications, and sponsor organizational types. Each dimension shapes facility investment thresholds, regulatory qualification pathways, and margin structures differently across Singapore, Thailand, Malaysia, and Indonesia.
Service Type:
CDMO engagements span discovery-phase analytical support through commercial-scale biologics production, with capital intensity and contract duration varying sharply across the spectrum.
- Biologics Manufacturing:Mammalian cell culture and microbial fermentation under current Good Manufacturing Practice standards command premium pricing due to specialized cleanroom infrastructure and single-use bioreactor requirements. Singapore's Tuas Biomedical Park concentrates regional demand for monoclonal antibody and viral vector production as biotechnology firms outsource capacity rather than build captive facilities.
- Analytical Testing:Method development, release testing, and long-term stability protocols generate recurring revenue streams with lower capital barriers to entry. Thailand's Food and Drug Administration and Malaysia's National Pharmaceutical Regulatory Agency both accept Singapore Health Sciences Authority inspection reports, enabling regional CDMOs to serve multi-country sponsor portfolios from single qualified sites.
- Formulation Development:Preclinical and early-phase dosage design for small molecules and biologics.
- Clinical Trial Material Production:Phase I-III comparator drug sourcing and investigational product manufacturing.
- Packaging:Commercial fill-finish, labeling, and serialization for ASEAN distribution.
- Stability Studies:ICH-compliant storage and accelerated degradation testing for regulatory submissions.
The dominant share belongs to Biologics Manufacturing, while Analytical Testing is closing the gap fastest.
Technology:
Platform selection determines facility footprint, skill requirements, and technology transfer complexity for sponsor-CDMO partnerships.
- Bioprocessing:Continuous perfusion systems and fed-batch platforms for recombinant protein production. Singapore-based CDMOs are migrating from stainless-steel infrastructure toward single-use footprints that reduce cross-contamination risk and accelerate batch turnaround for regional biotechnology clients.
- Cell Culture:CHO, HEK293, and proprietary platform cell lines for therapeutic protein and gene therapy vector manufacturing. Indonesia's underdeveloped domestic biologics infrastructure creates first-mover positioning for CDMOs establishing Jakarta satellite operations to serve Southeast Asia's largest population base.
- Small Molecule Synthesis:API development and scale-up for traditional pharmaceutical sponsors.
- High-Throughput Screening:Automated assay platforms for lead optimization and process characterization.
- Chromatography:Purification method development for downstream bioprocessing.
- Lyophilization:Freeze-drying for thermally sensitive biologic formulations.
Bioprocessing claims the largest installed base, with Cell Culture expanding most quickly through gene therapy pipeline growth.
Application:
Therapeutic area concentration shapes CDMO capability investments and regulatory submission experience requirements.
- Oncology:Monoclonal antibodies, antibody-drug conjugates, and immuno-oncology biologics dominate high-value manufacturing contracts. Singapore's Health Sciences Authority GMP inspection rigor creates qualification benchmarks that regional CDMOs leverage for credibility with multinational oncology sponsors.
- Vaccines:Viral vector and recombinant protein platforms for infectious disease prophylaxis. Vietnam's emerging biotechnology research institutes in Ho Chi Minh City seek regional partners for Phase I comparator drug sourcing, creating demand concentration for clinical trial material production.
- Infectious Diseases:Antiviral and antibacterial therapeutic manufacturing.
- Cardiovascular:Small molecule and biologic therapies for metabolic and heart failure indications.
- Dermatology:Topical and systemic formulations for inflammatory skin conditions.
- Neurology:CNS-targeted biologics with specialized delivery requirements.
Oncology maintains the revenue lead, though Vaccines is gaining share fastest through pandemic-response infrastructure investments.
End User:
Sponsor organizational type determines risk tolerance, outsourcing depth, and contract structure preferences.
- Biotechnology Firms:Asset-light development-stage companies accessing specialized mammalian cell culture infrastructure without multi-year facility construction commitments. Singapore's One-North research corridor concentrates demand for integrated service contracts spanning drug substance synthesis through commercial fill-finish.
- Pharmaceutical Companies:Established manufacturers supplementing captive capacity or accessing ASEAN market entry through local production partnerships. Thailand and Malaysia offer cost-competitive alternatives to Singapore for late-stage small molecule manufacturing.
- Research Institutes:Academic and government laboratories requiring process characterization and regulatory filing support.
- Generic Manufacturers:Cost-sensitive sponsors seeking bioequivalence study materials and scaled production.
- Nutraceutical Producers:Dietary supplement and functional food ingredient manufacturing under pharmaceutical-grade standards.
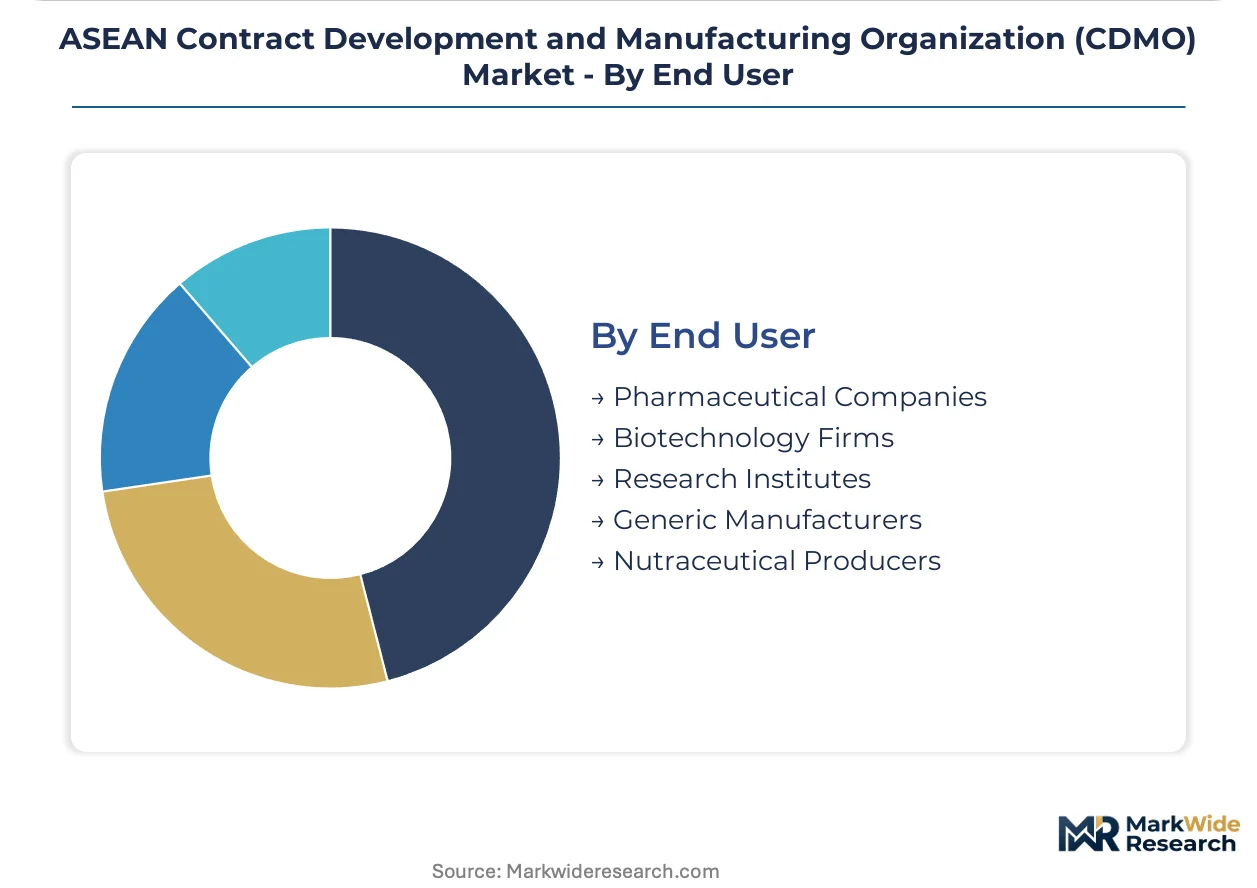
Biotechnology Firms command the highest service premiums, while Pharmaceutical Companies represent the deepest contract volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASEAN CDMO capacity flows reflect a pronounced import dependency for biologics manufacturing inputs, with specialized single-use bioreactor components and chromatography resins sourced predominantly from East Asian suppliers. Singapore's export-oriented biologics infrastructure offsets regional trade imbalances through high-value finished therapeutic exports to North American and European markets. Cross-border service delivery now dominates as Thailand and Malaysia accept Singapore Health Sciences Authority inspection reports for facility qualification.
Singapore
Tuas Biomedical Park concentrates the region's most sophisticated mammalian cell culture capacity, attracting biotechnology firms seeking outsourced viral vector and monoclonal antibody production. The Health Sciences Authority enforces GMP inspection standards that regional CDMOs leverage for credibility with multinational sponsors. One-North research corridor generates integrated service demand spanning drug substance synthesis through commercial fill-finish.
Thailand
The Food and Drug Administration's adoption of ASEAN Common Technical Dossier standards compresses cross-border trial approval cycles for regional sponsors. Bangkok and surrounding industrial zones host growing analytical testing capacity serving multi-country sponsor portfolios. Cost-competitive small molecule manufacturing alternatives to Singapore attract late-stage pharmaceutical production contracts.
Malaysia
The National Pharmaceutical Regulatory Agency aligns submission pathways with Singapore through mutual recognition protocols, enabling single-site qualification for regional service delivery. Penang and Greater Kuala Lumpur industrial corridors develop formulation development and clinical trial material production capabilities. Generic manufacturers seek bioequivalence study materials from emerging domestic CDMO infrastructure.
Indonesia
Southeast Asia's largest population base lacks domestic biologics manufacturing depth, creating first-mover positioning for CDMOs establishing Jakarta satellite operations. The national pharmaceutical regulator applies evolving biosimilar guidance that shapes facility investment thresholds for new entrants. Emerging biotechnology research institutes in Greater Jakarta seek regional partners for process characterization services.
Vietnam
Ho Chi Minh City biotechnology research institutes generate Phase I comparator drug sourcing demand from regional CDMO networks. The Ministry of Health's pharmaceutical regulatory framework continues harmonization with ASEAN standards, though inspection capacity lags Singapore benchmarks. Northern industrial zones near Hanoi attract packaging and serialization investments for ASEAN distribution networks.
ASEAN Contract Development and Manufacturing Organization (CDMO) Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in analytical testing and cell line development. The ASEAN CDMO structure fragments across three discernible tiers: global biologics specialists with Singapore-anchored campuses, mid-scale regional operators serving multi-country sponsor portfolios, and emerging domestic players capturing late-stage small molecule contracts. Strategic moves concentrate on capacity expansion through build-to-suit facility leasing and technology licensing partnerships that accelerate platform cell line access.
Among global biologics specialists, Lonza, Thermo Fisher Scientific, and Samsung Biologics exemplify contrasting geographic anchoring strategies. Lonza leverages its Singapore campus to anchor high-value mammalian cell culture capacity for regional biotechnology clients. Thermo Fisher Scientific competes through integrated analytical testing networks spanning multiple ASEAN jurisdictions. Samsung Biologics extends Korean bioprocessing expertise into Singapore through dedicated contract manufacturing infrastructure, representing the Korean chaebol model of overseas capacity replication.
| Leading Market Players |
|---|
| Parexel International Corporation |
| PPD International |
| Lonza |
| Recipharm |
| Thermo Fisher Scientific Inc. |
| Catalent Inc. |
| IQVIA |
| Cambrex Corporation |
| Samsung Biologics |
| Others |
Cost & Logistics Intelligence
Singapore's Tuas Biomedical Park concentrates specialized mammalian cell culture capacity that shapes regional pricing power for biologics manufacturing services. Biotechnology sponsors seeking outsourced viral vector production face limited qualified alternatives, compressing price elasticity for high-complexity contracts.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across ASEAN CDMO engagements. Pricing stratifies across GMP certification tiers, with Singapore Health Sciences Authority-qualified facilities commanding premiums over Thailand FDA-registered alternatives. Cost compression in late-stage small molecule manufacturing intensifies as Malaysian generic manufacturers expand analytical testing capacity. Emerging biotechnology firms exhibit highest price sensitivity, while multinational pharmaceutical sponsors prioritize qualification speed over unit economics.
Supply Chain Analysis
Lonza, Thermo Fisher Scientific, and Samsung Biologics hold concentrated bioprocessing capacity across Singapore and emerging Thai facilities. Raw material dependencies center on Japanese chromatography resins, Korean single-use bioreactor films, and German sensor components. Single-source vulnerability in East Asian film suppliers exposes ASEAN CDMOs to input volatility. Distribution runs through sponsor-directed logistics networks with cold-chain validation requirements for clinical trial materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
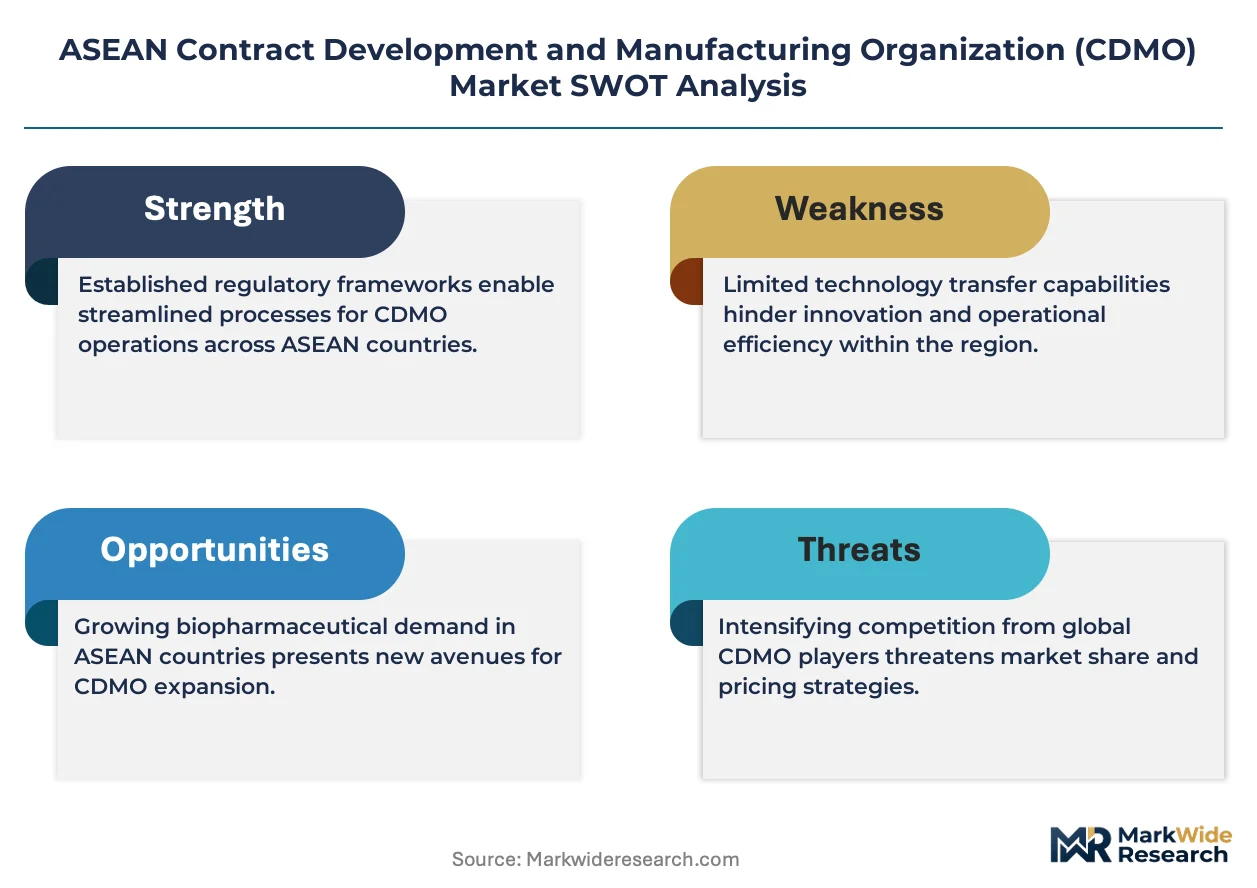
ASEAN CDMO market fragmentation creates positioning niches as gene therapy developers consolidate vendor relationships around single-accountability partners. Sponsor procurement patterns favor integrated service contracts spanning drug substance through commercial fill-finish.
For Market Incumbents: Insulate qualification advantages by accelerating Health Sciences Authority pre-approval inspection readiness and expanding perfusion bioreactor capacity before continuous processing becomes standard. Emerging Korean and Chinese bioprocessing specialists threaten Singapore's regional anchoring position. Vertical integration into proprietary platform cell lines reduces royalty stacking exposure.
For New Entrants and Emerging Players: Build out Jakarta satellite operations to capture Indonesia's underpenetrated biologics manufacturing demand from Southeast Asia's largest population base. Vietnam's Ho Chi Minh City research institutes generate underserved Phase I comparator drug sourcing requirements. Partner with established Singapore CDMOs for technology transfer validation rather than pursuing independent Health Sciences Authority qualification.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CDMOs with validated continuous processing capabilities and existing ASEAN regulatory harmonization credentials. Long-term viability hinges on differentiation from commodity analytical testing providers. Monitor Health Sciences Authority inspection backlog clearance rates as inflection indicator for facility revenue recognition timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Technology Adoption | Perfusion bioreactor integration enables 10,000-liter equivalent output from reduced facility footprints. |
| ASEAN Regulatory Harmonization Alignment | Mutual recognition protocols between Singapore HSA and Thailand FDA compress multi-country filing timelines. |
| Platform Cell Line Licensing Partnership | Proprietary CHO and HEK293 access reduces royalty stacking and accelerates sponsor technology transfer. |
| Build-to-Suit Facility Expansion | Asset-light leasing models lower capital barriers for biotechnology sponsors seeking mammalian cell culture capacity. |
| Integrated Service Contract Consolidation | Single-accountability partnerships spanning drug substance through fill-finish reduce technology transfer handoff risks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads at Singapore's Health Sciences Authority, CDMO facility managers, and biotechnology sponsor procurement directors. Secondary validation drew from FDA filings, EMA submission databases, ASEAN harmonization body guidance documents, and customs trade data for bioprocessing equipment imports. Bottom-up facility capacity assessments were triangulated against top-down sponsor outsourcing spend estimates.
Calibration against historical capacity utilization rates and sponsor pipeline announcements shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service complexity tier, technology platform type, therapeutic application area, and sponsor organizational archetype. CAGRs were derived from facility investment announcements and regulatory approval velocity trends. Forecast inputs incorporated single-use bioreactor supply lead times and Health Sciences Authority inspection queue dynamics.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Korean bioprocessing specialists or accelerated ASEAN regulatory convergence would shift outcomes. Supply chain disruption in East Asian film and sensor components, or extended Health Sciences Authority qualification timelines for new entrants, represent specific revision risks. Quarterly review of sponsor pipeline progression and regulatory inspection clearance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market