
 Global Pharmaceutical Membrane Filtration Market | 2026-2036
Global Pharmaceutical Membrane Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Membrane Filtration Market Outlook
Contract manufacturing organizations are unwinding traditional reliance on in-house filtration infrastructure as biologics developers outsource downstream processing. Merck KGaA leverages its integrated membrane and single-use portfolio to capture bioprocessing workflows. Danaher Corporation sustains competitive intensity through Pall Corporation's depth in continuous filtration architectures. Sartorius AG anchors European supply chains with specialized ultrafiltration cassettes for vaccine purification.
Pharmaceutical membrane filtration employs polymeric or ceramic barriers with defined pore size distributions—typically 0.1 to 10 micrometers for microfiltration, 1 to 100 nanometers for ultrafiltration—to separate particulates, microorganisms, and macromolecules from process fluids. Crossflow filtration dominates commercial bioprocessing because tangential flow minimizes membrane fouling during extended monoclonal antibody harvest operations. Ultrafiltration cassettes command the deepest margin pools in product type segments due to their irreplaceable role in protein concentration and buffer exchange. Continuous filtration architectures within technology segments are displacing batch configurations as manufacturers pursue real-time release and reduced hold-up volumes.
FDA process validation guidelines and EMA Annex 1 sterile manufacturing standards compel membrane suppliers to demonstrate extractables profiles, integrity test correlations, and gamma-irradiation stability. ISO 13485 quality management systems and USP Class VI biological reactivity testing further constrain vendor qualification timelines. Stakeholders must monitor how FDA quality metrics guidance and EU MDR traceability requirements reshape procurement criteria for filtration consumables.
Market Dynamics
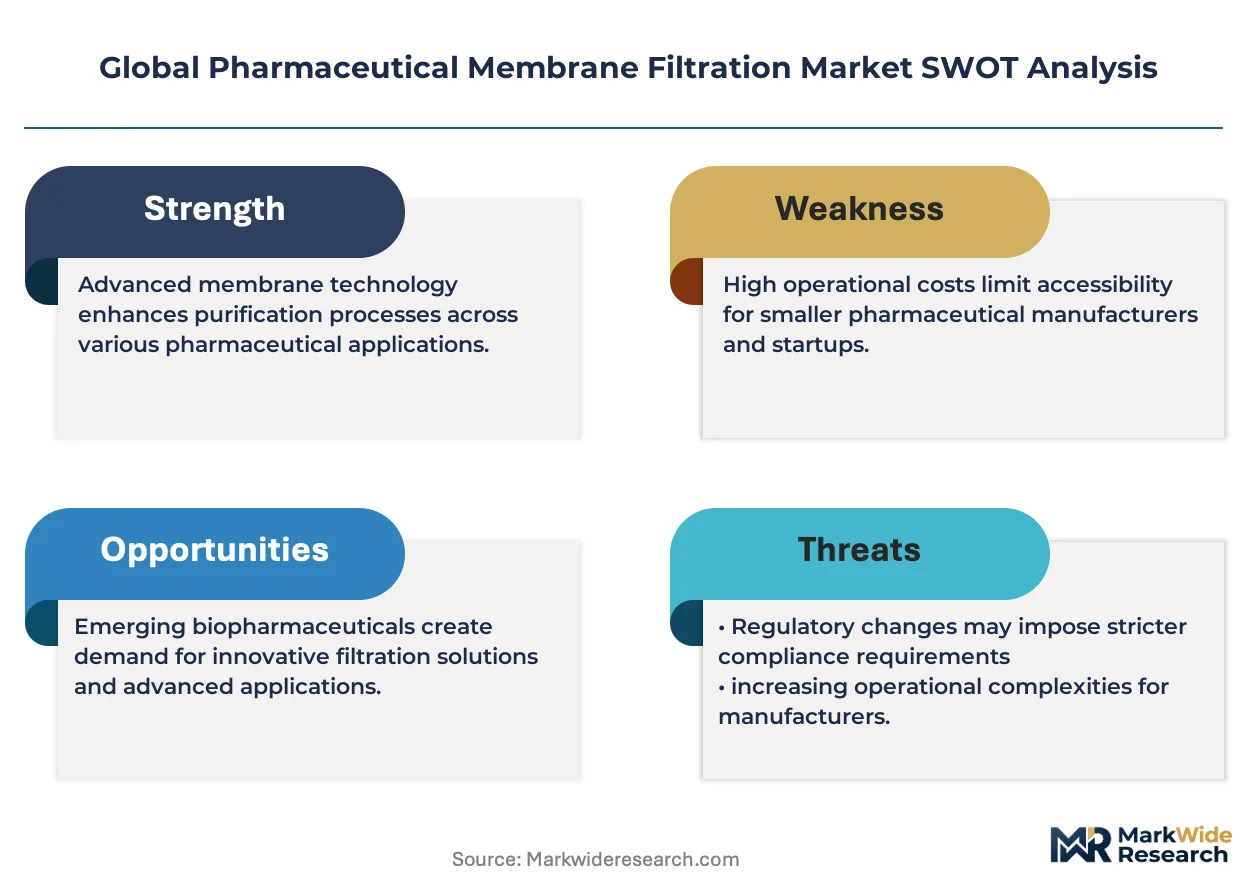
Continuous filtration architectures are displacing batch configurations as biologics manufacturers pursue real-time release and reduced hold-up volumes, fundamentally restructuring capital deployment patterns across downstream processing.
Growth Catalysts
- EMA Annex 1 Revisions:The European Medicines Agency's sterile manufacturing standards mandate enhanced filtration integrity testing, compelling facility upgrades across contract manufacturing networks.
- Gene Therapy Pipelines:Viral vector purification requirements are expanding demand for nanofiltration membranes with precise molecular weight cutoffs.
- China Bioprocessing Clusters:Concentrated investments in Suzhou and Shanghai biotech parks are localizing membrane consumption within the world's fastest-expanding biologics production base.
Market Restraints
- Polymer Feedstock Volatility:Specialized polysulfone and polyethersulfone resins face price instability tied to benzene derivative markets, compressing margin predictability for cassette manufacturers.
- Supplier Concentration:Gamma-irradiation sterilization capacity clusters in Germany and the United States, creating single-point vulnerability for European membrane vendors.
- Extractables Documentation Burden:FDA process validation guidelines demand extensive chemical characterization studies that extend vendor qualification timelines by 12-18 months.
Strategic Opportunities
- India Biosimilar Manufacturing:CDSCO regulatory alignment with ICH Q5A standards is opening qualification pathways for international membrane suppliers in Mumbai and Hyderabad production corridors.
- Single-Use Integration:Convergence of pre-sterilized membrane capsules with automated skid systems eliminates cleaning validation requirements for multi-product facilities.
- Continuous Bioprocessing Adoption:Perfusion cell culture expansion creates parallel demand for steady-state filtration trains that operate at constant flux over 60-day campaigns.
Industry Challenges
- Membrane Fouling Expertise Gap:Computational fluid dynamics modeling for crossflow optimization requires specialized bioprocess engineering talent that remains scarce outside Boston and Basel clusters.
- Legacy Stainless Steel Integration:Hybrid facilities struggle to interface disposable filtration manifolds with existing CIP/SIP infrastructure without compromising containment boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Membrane Filtration Market |
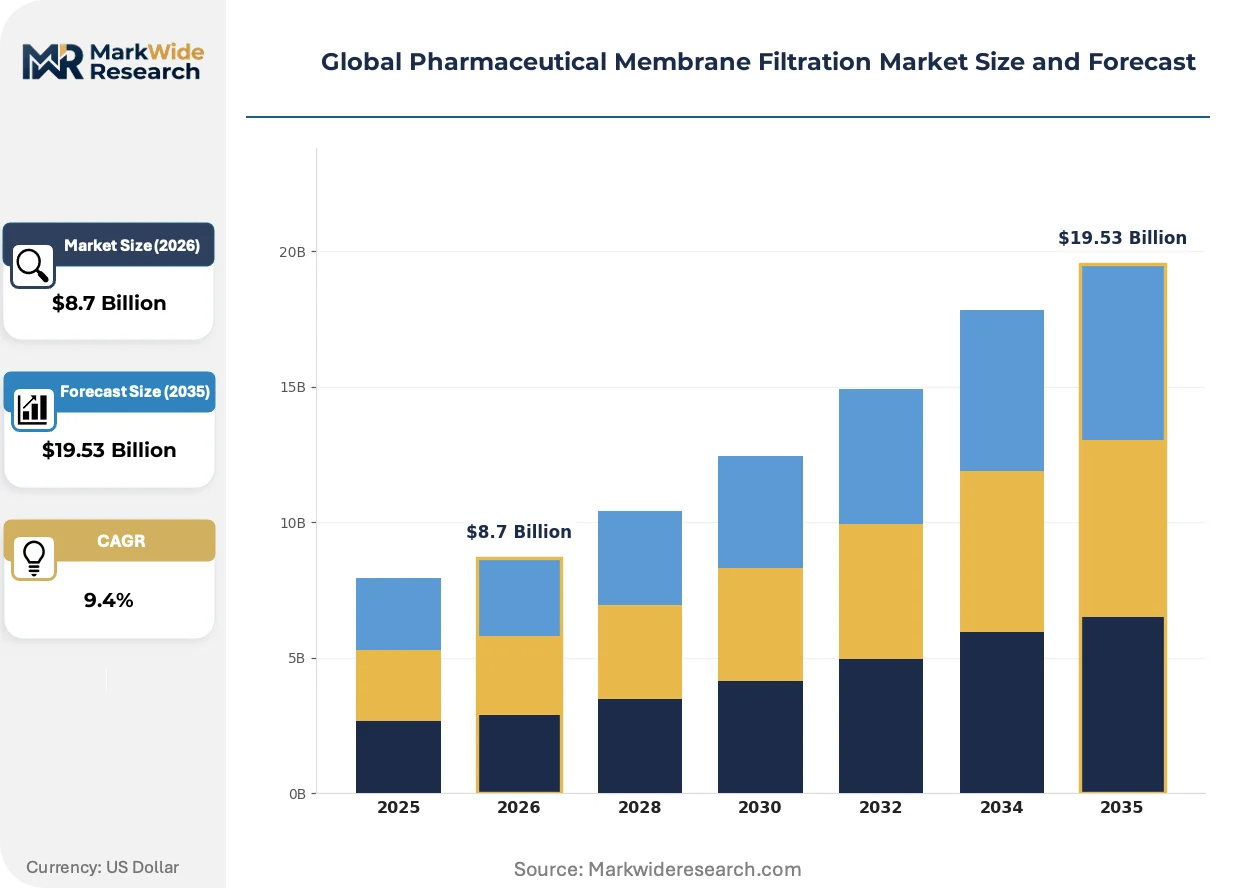
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Drug Purification, Water Treatment, Biological Manufacturing, Vaccine Production End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Contract Manufacturing Organizations Technology: Crossflow Filtration, Batch Filtration, Continuous Filtration, Ultrasonic Filtration |
| Companies Covered | Merck KGaA, Danaher Corporation, Sartorius AG, 3M Company, Thermo Fisher Scientific, Parker Hannifin Corporation, Repligen Corporation, Donaldson Company, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Membrane Filtration Market Strategic Shifts
Digital process analytical technologies are embedding sensors directly into filtration cassettes, enabling predictive maintenance algorithms that anticipate membrane failure before product loss occurs.
Single-use tangential flow filtration systems are decomposing traditional reusable hardware economics by eliminating cleaning validation overhead and reducing campaign changeover times from days to hours. Contract manufacturers in Massachusetts and North Carolina are adopting these platforms for multi-product antibody facilities. The shift is compressing total cost of ownership calculations and accelerating depreciation schedules for stainless steel assets.
REACH substance restrictions on perfluorinated compounds are forcing membrane suppliers to reformulate hydrophobic vent filters using alternative surface chemistries. The European Chemicals Agency's 2023 PFAS roadmap imposes disclosure thresholds that cascade through pharmaceutical supply chains. German and Swiss filtration vendors are accelerating silicone-based and ceramic alternatives to maintain CE marking compliance.
Integrated service contracts now bundle membrane supply with on-site technical support and performance guarantees, displacing transactional procurement models. Large biologics developers in California and Massachusetts are consolidating vendor relationships to secure dedicated field engineering coverage. This consolidation concentrates purchasing power among three to four preferred suppliers per therapeutic category.
Global Pharmaceutical Membrane Filtration Market Segmentation
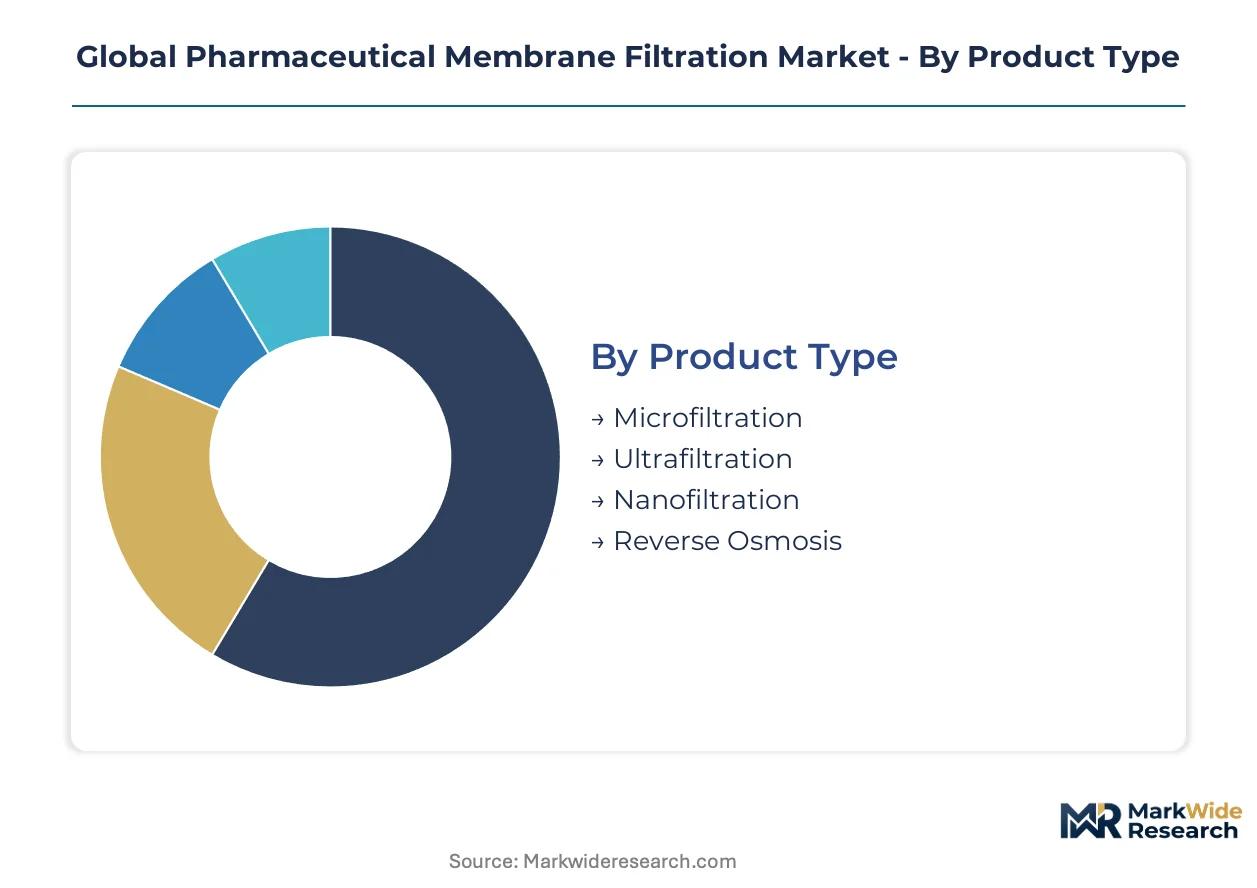
Membrane filtration segmentation determines procurement patterns across biopharmaceutical value chains. Product specifications cascade into facility design, validation protocols, and total cost of ownership calculations that lock buyers into multi-year supply relationships.
Product Type:
Ultrafiltration cassettes face intensifying substitution pressure from integrated single-use systems that bundle concentration and diafiltration steps.
- Ultrafiltration:Polyethersulfone or regenerated cellulose membranes with 1-100 kDa molecular weight cutoffs enable protein concentration and buffer exchange. Monoclonal antibody manufacturers in Massachusetts and Basel drive demand for high-capacity cassettes that sustain flux over 60-hour campaigns.
- Microfiltration:Polysulfone or polyvinylidene fluoride membranes with 0.1-10 micrometer pore ratings remove particulates and microorganisms. Final fill-finish operations in German sterile facilities require validated integrity test correlations that extend qualification timelines.
- Nanofiltration:Tight-pore membranes separate viral vectors and endotoxins based on size and charge. Gene therapy developers specify precise molecular weight cutoffs for AAV purification.
- Reverse Osmosis:Dense polyamide barriers remove dissolved ions and small organics. WFI generation systems in Chinese bioprocessing clusters deploy multi-pass configurations for pharmacopeia compliance.
Ultrafiltration retains volume leadership; nanofiltration holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive biological manufacturing from utility-scale water treatment.
- Biological Manufacturing:Harvest and purification of monoclonal antibodies, recombinant proteins, and cell therapies. Perfusion culture expansion in North Carolina and Singapore creates demand for steady-state filtration trains.
- Vaccine Production:Clarification and concentration of viral and bacterial antigens. Adjuvant removal and sterile filtration steps require validated endotoxin retention.
- Drug Purification:Small-molecule API isolation through solvent-resistant nanofiltration. High-value oncology compounds justify membrane replacement after single campaigns.
- Water Treatment:Purified water and WFI generation for facility operations. Multi-effect distillation pretreatment uses reverse osmosis for energy efficiency.
Biological manufacturing commands premium pricing; vaccine production is climbing fastest on pandemic preparedness investments.
End User:
Customer type determines contract structure, with CMOs demanding flexible supply terms versus captive biotech facilities.
- Contract Manufacturing Organizations:Multi-product facilities prioritize single-use filtration to eliminate cleaning validation. CDMOs in Hyderabad and Suzhou consolidate vendor relationships for technical support coverage.
- Pharmaceutical Companies:Large developers maintain dedicated engineering teams for process optimization. Internal manufacturing sites in California and New Jersey specify customized cassette configurations.
- Biotechnology Firms:Emerging developers outsource downstream processing to preserve capital. Virtual biotechs in Boston and San Francisco rely on pre-validated filtration platforms.
- Research Laboratories:Pilot-scale operations require small-batch cassettes with rapid turnaround. Academic facilities prioritize cost over performance for early-stage screening.
Contract manufacturing organizations drive volume; biotechnology firms are expanding most quickly on pipeline maturation.
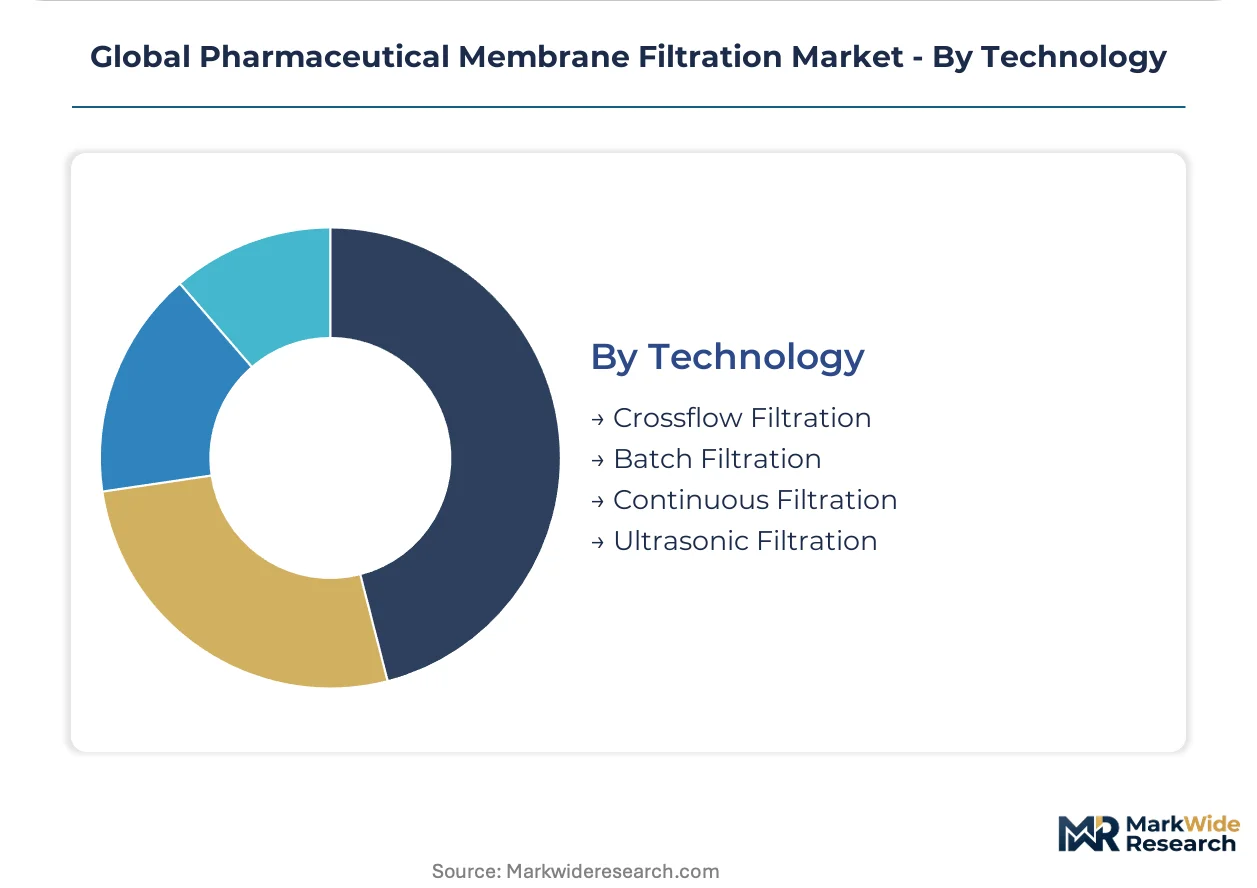
Technology:
Supply concentration in continuous filtration architectures is restructuring vendor qualification requirements.
- Continuous Filtration:Steady-state operation at constant flux enables real-time release and reduced hold-up volumes. Integrated PAT sensors in German-designed skids predict membrane failure before product loss.
- Crossflow Filtration:Tangential flow minimizes fouling during extended monoclonal antibody harvest. Computational fluid dynamics optimization requires scarce bioprocess engineering talent.
- Batch Filtration:Dead-end configurations persist in small-volume applications and legacy facilities. Stainless steel housings face displacement by pre-sterilized capsules.
- Ultrasonic Filtration:Acoustic energy reduces cake layer formation in high-solids applications. Limited commercial deployment restricts vendor options.
Crossflow filtration retains installed base dominance; continuous filtration is gaining share fastest on bioprocessing modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics developers concentrate purchasing power in three national clusters. Contract manufacturers in the United States, Germany, and China absorb the majority of membrane filtration capacity as these countries host the largest biopharmaceutical production bases.
United States
Massachusetts and North Carolina biotech corridors drive ultrafiltration cassette demand for monoclonal antibody manufacturing. FDA process validation guidelines compel membrane suppliers to demonstrate extractables profiles and integrity test correlations. Greater Boston contract manufacturers are adopting single-use tangential flow filtration systems to eliminate cleaning validation overhead.
Germany
Baden-Württemberg and Bavaria sterile manufacturing facilities anchor European demand for microfiltration membranes. EMA Annex 1 revisions mandate enhanced filtration integrity testing that extends vendor qualification timelines. Gamma-irradiation sterilization capacity concentrates in southern Germany, creating single-point vulnerability for membrane vendors serving EU markets.
China
Suzhou and Shanghai biotech parks localize membrane consumption within the fastest-expanding biologics production base. NMPA alignment with ICH Q5A standards opens qualification pathways for international suppliers. Yangtze River Delta bioprocessing clusters are deploying multi-pass reverse osmosis configurations for pharmacopeia-compliant WFI generation.
India
Hyderabad and Mumbai production corridors scale biosimilar manufacturing that requires validated nanofiltration membranes. CDSCO regulatory alignment with international standards creates procurement pathways for global membrane suppliers. Maharashtra-based contract manufacturers are consolidating vendor relationships to secure technical support coverage.
Switzerland
Basel biopharmaceutical cluster sustains premium demand for continuous filtration architectures with integrated PAT sensors. Swissmedic sterile manufacturing standards enforce rigorous membrane performance documentation. Lake Geneva region facilities are pursuing real-time release protocols that displace batch filtration configurations.
Global Pharmaceutical Membrane Filtration Market Competitive Environment
Player mix skews toward diversified life science conglomerates with integrated filtration portfolios. The vendor base concentrates around three to four preferred suppliers per therapeutic category as large biologics developers consolidate relationships. Strategic archetypes include integrated membrane-single-use platform providers, specialized ultrafiltration cassette manufacturers, and continuous filtration architecture specialists. Competitive intensity manifests through capacity expansion in gamma-irradiation sterilization and strategic partnerships for on-site technical support coverage.
Within the integrated platform tier, Merck KGaA and Danaher Corporation exemplify diversified conglomerates that anchor competitive positioning through breadth of downstream processing portfolios. Sartorius AG occupies a specialist position among European filtration vendors. These three entities represent the consolidation pattern concentrating purchasing power among preferred suppliers serving monoclonal antibody and gene therapy manufacturers.
| Leading Market Players |
|---|
| Merck KGaA |
| Danaher Corporation |
| Sartorius AG |
| 3M Company |
| Thermo Fisher Scientific |
| Parker Hannifin Corporation |
| Repligen Corporation |
| Donaldson Company |
| Alfa Laval |
| Others |
Value Chain & Pricing Dynamics
FDA process validation guidelines gate both supplier qualification timelines and price differentiation across membrane filtration tiers, compressing margins for vendors unable to demonstrate extractables profiles while enabling premium positioning for gamma-irradiation certified alternatives.
Pricing Analysis
Next-generation continuous filtration architectures command substantial premiums over legacy batch configurations and early single-use systems. Pricing stratifies across premium, standard, and economy tiers based on certification depth and after-sales engineering bundling. Cost compression in standard ultrafiltration cassettes is intensifying because polymer feedstock volatility feeds through benzene derivative markets. Contract manufacturing organizations exhibit highest price sensitivity due to multi-product campaign economics, while large pharmaceutical developers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Gamma-irradiation sterilization capacity clustering in Germany and the United States creates a chokepoint that European membrane vendors cannot easily circumvent. Specialized polysulfone and polyethersulfone resins draw from benzene derivative feedstocks concentrated in German and Chinese chemical manufacturing. Single-source vulnerability in sterilization infrastructure exposes vendors to regulatory inspection backlogs. Distribution runs through authorized distributors with technical service capabilities rather than commodity chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical membrane filtration market is entering a cyclical recovery phase as biologics capacity expansion resumes following pandemic-era project delays and EMA Annex 1 compliance investments accelerate replacement demand.
For Market Incumbents: Consolidate gamma-irradiation sterilization capacity through captive facility investments or long-term offtake agreements with German and U.S. service providers. Deepen field engineering coverage in Suzhou and Shanghai biotech parks before local Chinese suppliers achieve EMA-equivalent certification depth. Single-use platform substitution from emerging Asian entrants threatens cassette margin pools.
For New Entrants and Emerging Players: Differentiate on continuous filtration architecture integration with process analytical technology sensors, a capability gap outside Boston and Basel engineering clusters. Target India biosimilar manufacturing corridors where CDSCO alignment with ICH Q5A standards has opened qualification pathways but incumbent technical support coverage remains thin. Pursue integrated service contracts bundling membrane supply with on-site validation support.
For Investors and Strategic Acquirers: EMA Annex 1 revisions reshape the acquisition landscape by extending vendor qualification timelines and concentrating purchasing power among three to four preferred suppliers per therapeutic category. Five-to-ten-year viability favors specialists with gamma-irradiation certification depth over undifferentiated commodity membrane producers. Watch for FDA quality metrics guidance implementation as the inflection signal for procurement consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Gamma-Irradiation Capacity Expansion | Captive sterilization infrastructure in Germany reduces single-point vulnerability for EMA-compliant membrane supply. |
| Continuous Filtration Platform Integration | Real-time release protocols with embedded PAT sensors displace batch configurations in Basel biopharmaceutical clusters. |
| Single-Use Tangential Flow System Launch | Pre-sterilized capsules eliminate cleaning validation overhead for Massachusetts contract manufacturers. |
| India Biosimilar Manufacturing Partnership | CDSCO regulatory alignment opens qualification pathways for international membrane suppliers in Hyderabad corridors. |
| Alternative Surface Chemistry Development | Silicone-based and ceramic alternatives maintain CE marking compliance under ECHA PFAS disclosure thresholds. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bioprocess engineering directors, regulatory affairs leads at membrane vendors, contract manufacturing procurement managers, and sterile facility validation specialists. Secondary validation drew from FDA guidance documents, EMA Annex 1 revision drafts, USP Class VI biological reactivity testing protocols, and ISO 13485 quality management system audits. Bottom-up membrane consumption estimates triangulated against top-down biologics capacity expansion projections.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, application, end user, and technology dimensions with additional stratification by regional regulatory cluster and therapeutic category. CAGRs were derived from installed base depreciation schedules and replacement demand curves tied to perfusion cell culture expansion. Forecast inputs incorporated polymer feedstock price indices and gamma-irradiation capacity utilization rates.
Material uncertainties — regulatory inspection backlogs, REACH substance restriction scope expansions, and biologics pipeline failure rates — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EMA Annex 1 implementation timelines and FDA quality metrics guidance finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market