
 Global Pharmaceutical Granulation Equipment Market | 2026-2036
Global Pharmaceutical Granulation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Granulation Equipment Market Foresight
Biotech firms is recalibrating the buyer landscape as these end users scale internal manufacturing capabilities once outsourced to contract manufacturers. GEA Group leverages its integrated process technology portfolio to anchor large-scale fluid bed installations across North American and European facilities. Romaco Group specializes in compact granulation lines that occupy niche positions where space-constrained pharmaceutical operations require modular footprints.
Pharmaceutical granulation equipment encompasses mechanical systems that agglomerate fine drug powders into uniform granules through shear, compaction, or fluidization processes, typically achieving particle size distributions between 100 and 1000 microns to ensure flowability and compressibility for downstream tableting. High-shear mixers dominate current installed bases due to proven batch consistency, while continuous granulation configurations represent the fastest-growing installation category as manufacturers pursue real-time release strategies. Fluid bed granulators command premium pricing positions where aqueous coating and drying functions must integrate within single-unit operations, and roller compactors sustain steady demand from generic manufacturers seeking dry granulation pathways for moisture-sensitive APIs.
The FDA's Quality by Design framework and the EU's MDR both elevate documentation burdens for equipment qualification, compelling vendors to embed automated process analytical technology that generates audit-ready data trails. EMA's evolving stance on continuous manufacturing submissions creates additional specification pressure for systems capable of demonstrating steady-state control over extended production runs. Stakeholders must weigh batch flexibility against continuous throughput economics when committing capital to granulation line upgrades.
Market Dynamics
The transition from batch to continuous manufacturing is compressing equipment replacement cycles and forcing vendors to reengineer validation protocols around real-time process analytical technology.
Growth Catalysts
- Continuous Manufacturing Guidance:FDA's 2023 revised guidance on continuous process validation is compelling facility upgrades that favor modular granulation trains over legacy batch suites.
- Biologics Formulation Complexity:Monoclonal antibody and cell therapy developers require specialized containment and shear control that standard oral solid dose equipment cannot deliver.
- German Precision Engineering Cluster:Concentrated supplier density around Stuttgart and Karlsruhe enables rapid prototyping of custom fluid bed configurations for pharmaceutical OEMs.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L price swings and extended lead times from specialty mills are inflating equipment base costs and compressing vendor margins.
- Validation Documentation Burden:EU MDR's enhanced technical file requirements for process equipment are extending qualification timelines and freezing capital deployment decisions.
- Dry Granulation Substitution:Roller compaction pathways for moisture-sensitive APIs are displacing wet granulation demand in generic manufacturing portfolios.
Strategic Opportunities
- Indian Contract Manufacturing Expansion:CDSCO's streamlined approval pathways for export-oriented facilities are attracting greenfield investments that specify integrated granulation-coating lines.
- Process Analytical Technology Convergence:Raman spectroscopy and near-infrared sensors embedded in fluid bed systems enable real-time release and command 15-25% pricing premiums over conventional units.
- Service Revenue Unbundling:Predictive maintenance contracts and remote diagnostic subscriptions are creating recurring revenue streams that offset cyclical equipment sales.
Industry Challenges
- Continuous Process Engineering Talent Scarcity:Pharmaceutical manufacturers struggle to recruit personnel capable of steady-state process design and PAT system integration.
- Legacy System Interoperability:Brownfield facilities face complex data architecture challenges when retrofitting continuous granulation modules into existing SCADA environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Granulation Equipment Market |
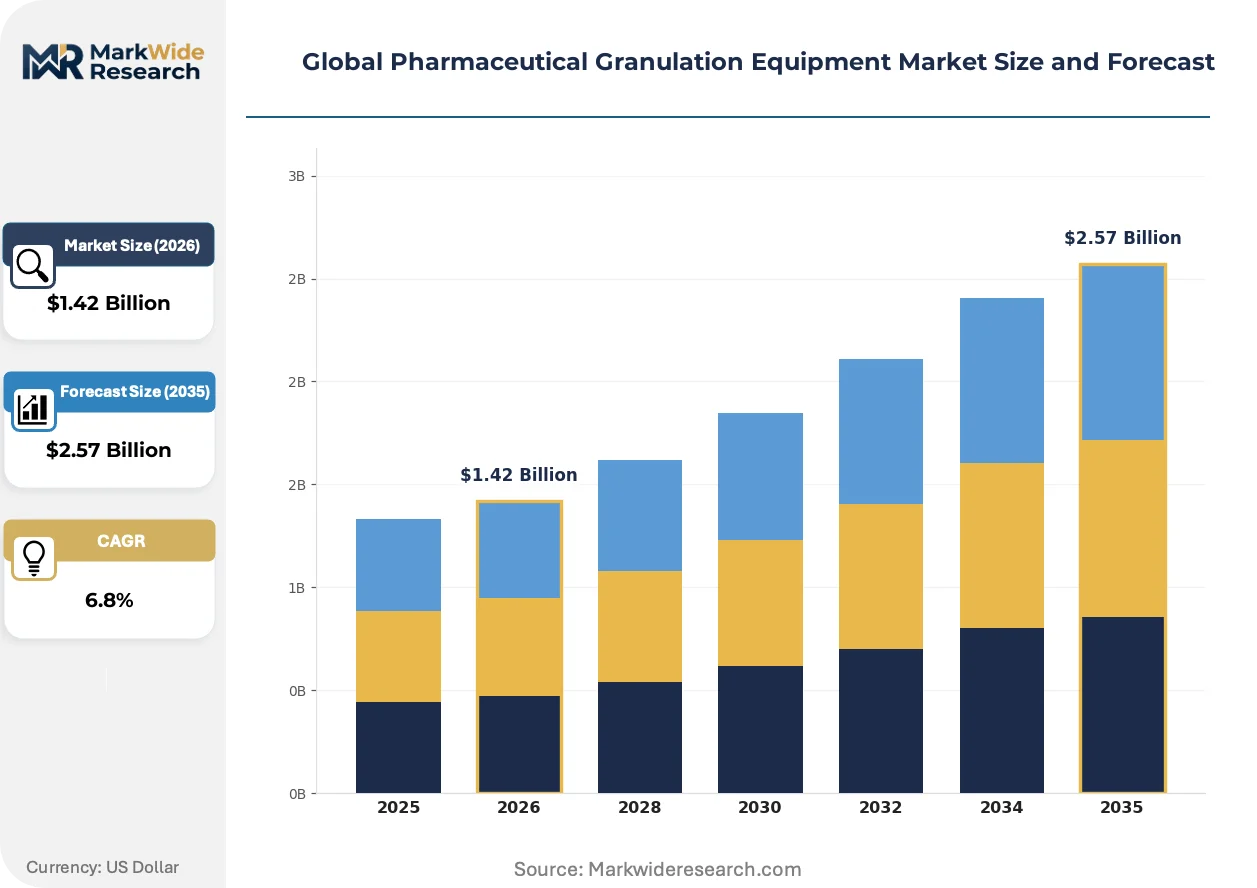
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Shear Mixers, Fluid Bed Granulators, Roller Compactors, Granulation Tools Application: Tablets, Capsules, Powder, Pellets End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Biotech Firms Installation: Batch, Continuous, Modular, Integrated |
| Companies Covered | L.B. Bohle Maschinen und Verfahren, Romaco Group, GEA Group, Diosna, Fette Compacting, Glatt Group, Syntegon Technology, HOSOKAWA MICRON, Alexanderwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Granulation Equipment Market Shifts & Advancements
Digital twin implementations and advanced process control architectures are displacing manual parameter adjustment, while regulatory pressure for data integrity is embedding automated audit trails into equipment design specifications.
Continuous twin-screw granulation is rewriting equipment procurement patterns by enabling real-time quality assurance that eliminates intermediate testing steps. Mid-size pharmaceutical manufacturers in the United States and Germany are adopting these systems at twice the rate of smaller facilities. The technology is compressing batch release timelines from weeks to hours and forcing legacy high-shear mixer vendors to defend installed bases through aggressive retrofit programs.
EMA's evolving position on continuous manufacturing dossier submissions is creating specification pressure for extended run demonstrations and steady-state control documentation. Equipment vendors must now supply validation packages that prove process capability across 72-hour continuous operations rather than traditional three-batch qualification. Oral solid dose manufacturers in Ireland and Switzerland are front-running these requirements to secure first-mover advantages in regulatory filings.
After-sales service unbundling is disrupting traditional capital equipment sales models as pharmaceutical buyers separate hardware procurement from validation support and maintenance contracts. Third-party engineering consultancies in the Netherlands and Denmark are capturing PAT integration work that equipment OEMs previously bundled with system sales. This fragmentation is most visible among biotech firms building internal manufacturing capabilities, where specialized integrators now outbid full-line vendors on total project economics.
Global Pharmaceutical Granulation Equipment Market Segmentation
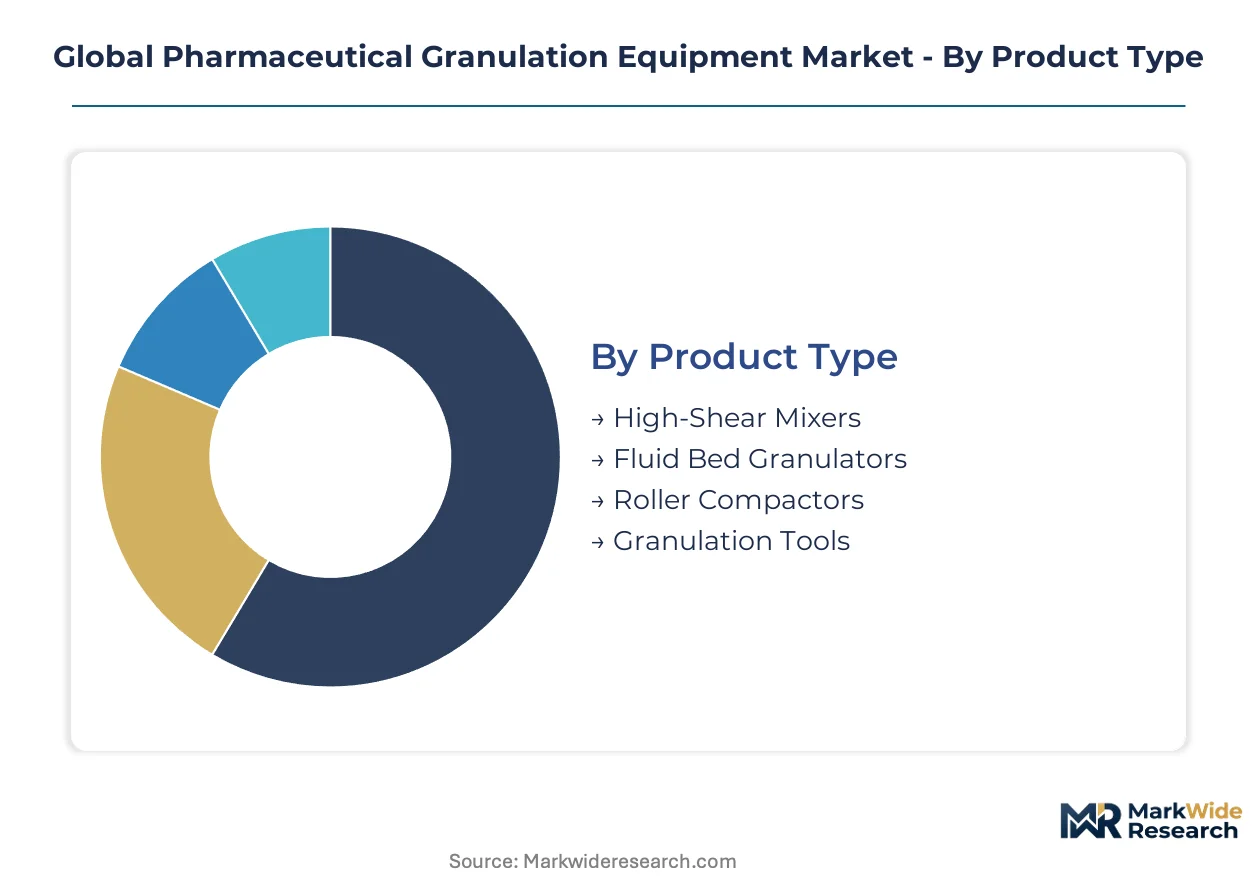
Equipment segmentation in pharmaceutical granulation reveals how technology specifications align with manufacturing scale and regulatory complexity. Buyers match mixer configurations to API sensitivity, batch volume, and continuous processing ambitions.
Product Type:
Technology specifications determine equipment selection based on shear intensity, thermal exposure limits, and integration with downstream unit operations.
- High-Shear Mixers:These systems employ impeller-driven mechanical shear to achieve rapid liquid distribution and dense granule formation within enclosed bowls. Demand concentrates among generic manufacturers in India and Eastern Europe seeking proven batch consistency for high-volume oral solid dose production.
- Fluid Bed Granulators:Pneumatic fluidization enables simultaneous granulation and drying in a single vessel, with integrated spray nozzles for binder application. German and Swiss innovators dominate procurement for complex biologic formulations requiring precise temperature control and containment.
- Roller Compactors:Dry granulation through mechanical compression suits moisture-sensitive APIs without solvent exposure. Adoption is climbing among generic portfolios reformulating legacy products.
- Granulation Tools:Auxiliary components include sizing mills, cone mills, and vacuum transfer systems that complete processing trains. These attach to primary units from multiple OEMs.
High-shear mixers lead on scale; fluid bed granulators lead on momentum.
Application:
End-product format dictates particle size targets, density requirements, and coating compatibility needs across formulation development.
- Tablets:Direct compression and wet granulation pathways both serve tableting, with granule flowability and compressibility determining press performance. US and German facilities prioritize real-time release configurations for immediate-release formulations.
- Capsules:Granule fill weight uniformity and powder flow into dosing discs require narrower particle size distributions than tableting. Biotech firms in Massachusetts and California specify containment-integrated lines for potent compound handling.
- Powder:Granulation for powder applications addresses caking prevention and dosing accuracy in sachet and bulk packaging. This segment serves nutritional and OTC portfolios with simpler validation requirements.
- Pellets:Multi-particulate systems enable modified-release profiles and taste masking through layered coating. European CDMOs in Ireland and Italy specialize in pellet technology for pediatric and geriatric formulations.
Tablets dominate volume; capsules are expanding most quickly.
End User:
Customer type shapes procurement patterns around capital intensity, technical staffing, and regulatory filing responsibilities.
- Pharmaceutical Companies:Integrated multinationals specify fully validated trains with embedded PAT and automated documentation. These buyers in Switzerland and Japan favor single-source accountability for qualification packages.
- Contract Manufacturers:CDMOs prioritize equipment flexibility to accommodate diverse client products and rapid changeover. Indian export-oriented facilities specify integrated granulation-coating lines under CDSCO streamlined pathways.
- Biotech Firms:Emerging biologics developers build internal capabilities once outsourced, requiring specialized containment and shear control. These buyers fragment procurement between hardware vendors and third-party integrators.
- Research Institutions:University and government labs specify bench-scale and pilot units for formulation development and process characterization. Procurement emphasizes modularity and scale-up correlation data.
Pharmaceutical companies lead on scale; biotech firms are gaining share fastest.
Installation:
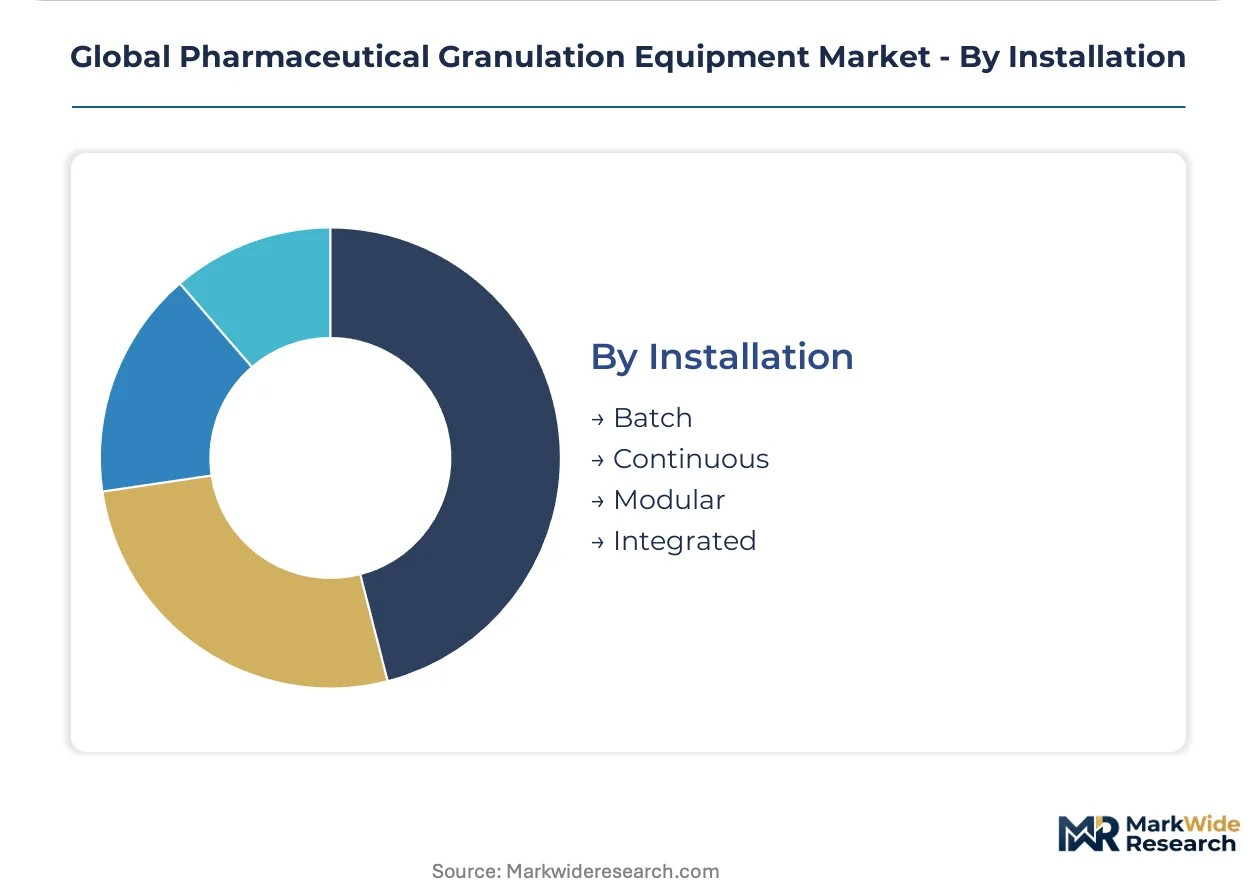
System architecture determines capital deployment, facility footprint, and regulatory validation strategy for brownfield and greenfield projects.
- Batch:Discrete processing with defined start and end points remains prevalent in validated legacy facilities. These installations dominate current installed bases but face replacement pressure from continuous alternatives.
- Continuous:Steady-state operation with real-time quality assurance eliminates intermediate testing and compresses release timelines. FDA's revised guidance on continuous process validation is accelerating US and German adoption.
- Modular:Skid-mounted units enable rapid deployment and future relocation for capacity scaling or facility consolidation. These configurations serve emerging market greenfields and leased manufacturing space.
- Integrated:Fully coupled granulation-drying-coating sequences minimize material handling and contamination risk. Irish and Swiss manufacturers front-run these specifications for EMA continuous manufacturing dossiers.
Batch installations lead on scale; continuous systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting granulation equipment procurement toward jurisdictions where compliance costs align with manufacturing scale advantages. CDSCO's streamlined pathways for export-oriented Indian facilities attract greenfield investments specifying integrated lines. EMA's evolving continuous manufacturing dossier requirements concentrate specification pressure on Irish and Swiss manufacturers.
United States
FDA's 2023 revised guidance on continuous process validation is accelerating replacement of legacy batch suites with modular granulation trains. Massachusetts and California biotech clusters specify containment-integrated lines for potent compound handling. Real-time release configurations dominate immediate-release formulation procurement.
Germany
Precision engineering density around Stuttgart and Karlsruhe enables rapid prototyping of custom fluid bed configurations. EMA's MDR technical file requirements extend qualification timelines for equipment vendors. North Rhine-Westphalia hosts the densest concentration of pharmaceutical OEM supplier relationships.
India
CDSCO's export-oriented approval pathways attract contract manufacturing investments specifying integrated granulation-coating lines. Generic manufacturers in Gujarat and Maharashtra prioritize high-shear mixer procurement for volume oral solid dose production. Hyderabad and Ahmedabad clusters concentrate equipment specification authority.
Switzerland
Swissmedic's alignment with EMA continuous manufacturing submissions drives 72-hour steady-state validation requirements. Basel and Zurich facilities front-run integrated granulation-drying-coating specifications. Single-source accountability dominates procurement patterns among integrated multinationals.
China
NMPA's evolving stance on process analytical technology integration shapes fluid bed system specifications for domestic biologic developers. Yangtze River Delta pharmaceutical manufacturers adopt continuous twin-screw configurations at accelerated rates. Shanghai and Suzhou clusters concentrate precision equipment demand.
Global Pharmaceutical Granulation Equipment Market Competitive Landscape
Service revenue unbundling dominates the current landscape as pharmaceutical buyers separate hardware procurement from validation support and maintenance contracts. The vendor base stratifies across three tiers: integrated process technology conglomerates anchoring large-scale installations, precision engineering specialists occupying niche modular positions, and regional fabricators serving emerging market price sensitivity. Strategic archetypes include PAT-embedded system innovators, compact footprint specialists for space-constrained operations, and predictive maintenance platform operators. Competitive intensity concentrates around technology licensing partnerships and backward integration into stainless steel component supply.
Within the precision engineering tier, L.B. Bohle Maschinen und Verfahren and Romaco Group exemplify German fabrication excellence serving pharmaceutical OEM clusters. GEA Group occupies a position among integrated process technology conglomerates anchoring fluid bed installations across North American and European facilities. These three entities represent distinct competitive vectors: specialized modular engineering, integrated multi-unit operations, and large-scale project accountability.
| Leading Market Players |
|---|
| L.B. Bohle Maschinen und Verfahren |
| Romaco Group |
| GEA Group |
| Diosna |
| Fette Compacting |
| Glatt Group |
| Syntegon Technology |
| HOSOKAWA MICRON |
| Alexanderwerk |
| Others |
Supply & Pricing Matrix
Family-owned precision engineering specialists concentrated around Stuttgart and Karlsruhe anchor supply-side discipline through captive fabrication capabilities, enabling pricing power that resists commodity erosion even as stainless steel input costs fluctuate. This ownership structure sustains premium positioning for fluid bed configurations while compressing margins for distributors lacking direct mill relationships.
Pricing Analysis
Distributor margins on granulation equipment compress as direct-to-OEM procurement channels expand, particularly for large-scale fluid bed installations where GEA Group and Glatt Group negotiate volume discounts. Three-tier pricing structure across premium PAT-embedded systems, standard batch configurations, and economy modular units separates validation-bundled offerings from hardware-only transactions. Cost compression in the economy tier intensifies because Indian and Chinese fabricators compete on stainless steel conversion costs. Generic manufacturers in Gujarat and Maharashtra exhibit the highest price sensitivity, while Swiss and German biotech firms prioritize containment-integrated specifications over unit economics.
Supply Chain Analysis
Freight cost inflation on oversized fluid bed vessel shipments from Germany to North American facilities has prompted regional fabrication partnerships near Boston and Raleigh. Supply concentrates in Germany, Switzerland, and India, with precision machining clusters around Stuttgart, Basel, and Ahmedabad feeding final assembly. Grade 316L stainless steel, ceramic spray nozzles, and process analytical technology sensors constitute critical input dependencies. Single-source vulnerability persists for specialized containment isolators sourced from Swiss specialists. Distribution runs through pharmaceutical OEM procurement teams, third-party engineering integrators in the Netherlands and Denmark, and direct sales forces for validated project accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market reads as a late-cycle quality story where FDA's continuous manufacturing guidance and EMA's evolving dossier requirements concentrate procurement authority with vendors capable of 72-hour steady-state validation packages. This specification shift favors integrated process technology conglomerates over fragmented regional fabricators.
For Market Incumbents: Deploy predictive maintenance platform subscriptions to offset cyclical equipment sales and capture recurring revenue from biotech firms building internal capabilities. Incumbents must accelerate backward integration into stainless steel component supply to defend margins against commodity price volatility from specialty mills. Continuous twin-screw granulation technology from emerging specialists threatens high-shear mixer installed bases, requiring aggressive retrofit programs and technology licensing partnerships to preserve account control. For New Entrants and Emerging Players: Digital-channel routes through third-party engineering consultancies in the Netherlands and Denmark offer lower customer acquisition costs than direct OEM sales forces for PAT integration work. White-space targets include compact modular lines for space-constrained biotech facilities in Massachusetts and California, plus remote diagnostic services unbundled from hardware procurement. The most penetrable segment comprises mid-size pharmaceutical manufacturers in the United States adopting continuous configurations at twice the rate of smaller facilities. A go-to-market angle emphasizing 72-hour steady-state documentation packages for EMA submissions differentiates against legacy vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among precision engineering specialists with captive fabrication capabilities but limited PAT integration expertise, as these firms face margin compression from stainless steel volatility without offsetting service revenue. Long-term viability over a five-to-ten year horizon hinges on continuous manufacturing adoption rates and regulatory filing success for real-time release configurations. The acquisition target archetype combines modular engineering competence with embedded process analytical technology platforms. The signal to watch is CDSCO approval velocity for export-oriented Indian facilities, which drives greenfield investment specifications and equipment procurement timing.| Strategic Initiative | Industry Significance |
|---|---|
| PAT-Embedded System Development | FDA's revised continuous process validation guidance mandates real-time process analytical technology for new facility approvals. |
| Backward Integration into Component Supply | Grade 316L stainless steel price volatility from specialty mills compresses margins for vendors lacking captive fabrication. |
| Service Revenue Unbundling | Predictive maintenance contracts and remote diagnostic subscriptions create recurring revenue streams offsetting cyclical equipment sales. |
| Modular Footprint Engineering | Space-constrained biotech facilities in Massachusetts and California specify compact granulation lines requiring skid-mounted configurations. |
| Continuous Manufacturing Validation Packages | EMA's evolving dossier requirements demand 72-hour steady-state documentation for extended run demonstrations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical process engineers, regulatory affairs leads at biotech firms, CDMO procurement managers, and aftermarket service heads with secondary validation against FDA guidance documents, EMA submission databases, CDSCO approval records, and stainless steel trade flow data. Bottom-up equipment shipment tracking and top-down pharmaceutical capital expenditure analysis provided triangulation anchors for market sizing.
Segment-weighting approaches applied differential growth assumptions across high-shear mixers, fluid bed granulators, roller compactors, and granulation tools, with additional stratification by batch versus continuous installation architecture and by end-user type across pharmaceutical companies, contract manufacturers, biotech firms, and research institutions. CAGRs derived from regression analysis of historical procurement patterns and regulatory filing velocity. Forecast inputs incorporated FDA continuous manufacturing guidance implementation timelines and EMA dossier evolution for steady-state validation requirements.
The model assumes a particular technology adoption path; alternative pathways for continuous twin-screw granulation or dry granulation substitution would alter the outlook for wet granulation equipment demand. Forecasts reflect assumptions about regulatory filing success rates and stainless steel price stabilization that carry material uncertainty. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
US Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market