
 Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market | 2026-2036
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market Insights
SFDA serialization mandates are decoupling low-cost suppliers from tender eligibility across Gulf Cooperation Council procurement channels. Schott AG leverages its German-engineered borosilicate platform to anchor premium vial contracts with Saudi biologics manufacturers. Gerresheimer AG competes through regional distribution hubs that sustain just-in-time delivery for Egyptian and South African fill-finish operations.
Pharmaceutical glass vials and ampoules are tubular or molded containers fabricated from borosilicate or soda-lime glass, engineered to meet chemical durability standards specified in pharmacopeial chapters on hydrolytic resistance and thermal shock tolerance. Their primary function is to maintain sterility, prevent drug-container interaction, and enable precise dosing of parenteral medicines across liquid, lyophilized, and powder formulations. Vials occupy the dominant volume position across the Middle East and Africa because multi-dose biologics and vaccine campaigns require scalable, resealable primary packaging with validated closure integrity. Type I borosilicate glass commands the fastest expansion trajectory within the material dimension, driven by alkaline leachate sensitivity in monoclonal antibody and mRNA-based therapeutics that disqualify lower-grade alternatives.
Saudi Food and Drug Authority (SFDA) and South African Health Products Regulatory Authority (SAHPRA) enforce divergent but equally stringent pharmacopeial compliance pathways, compelling manufacturers to maintain dual certification portfolios for cross-border commercialization. The South African Bureau of Standards (SABS) and Egypt's Drug Authority align progressively with International Council for Harmonisation (ICH) guidelines, narrowing the gap between local and export-grade production standards. Stakeholders must monitor harmonization momentum between national regulators to anticipate which certification investments will unlock multi-territory supply contracts versus strand capital in obsolete compliance architectures.
Market Dynamics
SFDA serialization mandates are compressing supplier eligibility across Gulf Cooperation Council tender channels, forcing fill-finish operators to abandon uncertified glass sources and consolidate procurement around traceability-verified borosilicate platforms.
Growth Catalysts
- Biologic injectables expansion:Hospital networks across Saudi Arabia and South Africa are scaling refrigerated storage capacity for monoclonal antibody therapies, directly amplifying demand for Type I borosilicate vials with validated thermal shock resistance.
- SFDA Drug Track and Trace System:Saudi Arabia's mandatory serialization infrastructure requires unit-level vial traceability, disqualifying informal suppliers and redirecting tender volumes toward certified manufacturers with integrated data-matrix capabilities.
- Egyptian pharmaceutical cluster formation:The 10th of Ramadan City and New Borg El-Arab industrial zones are aggregating temperature-sensitive formulation capacity, absorbing rising volumes of molded borosilicate vials for export-oriented biologics production.
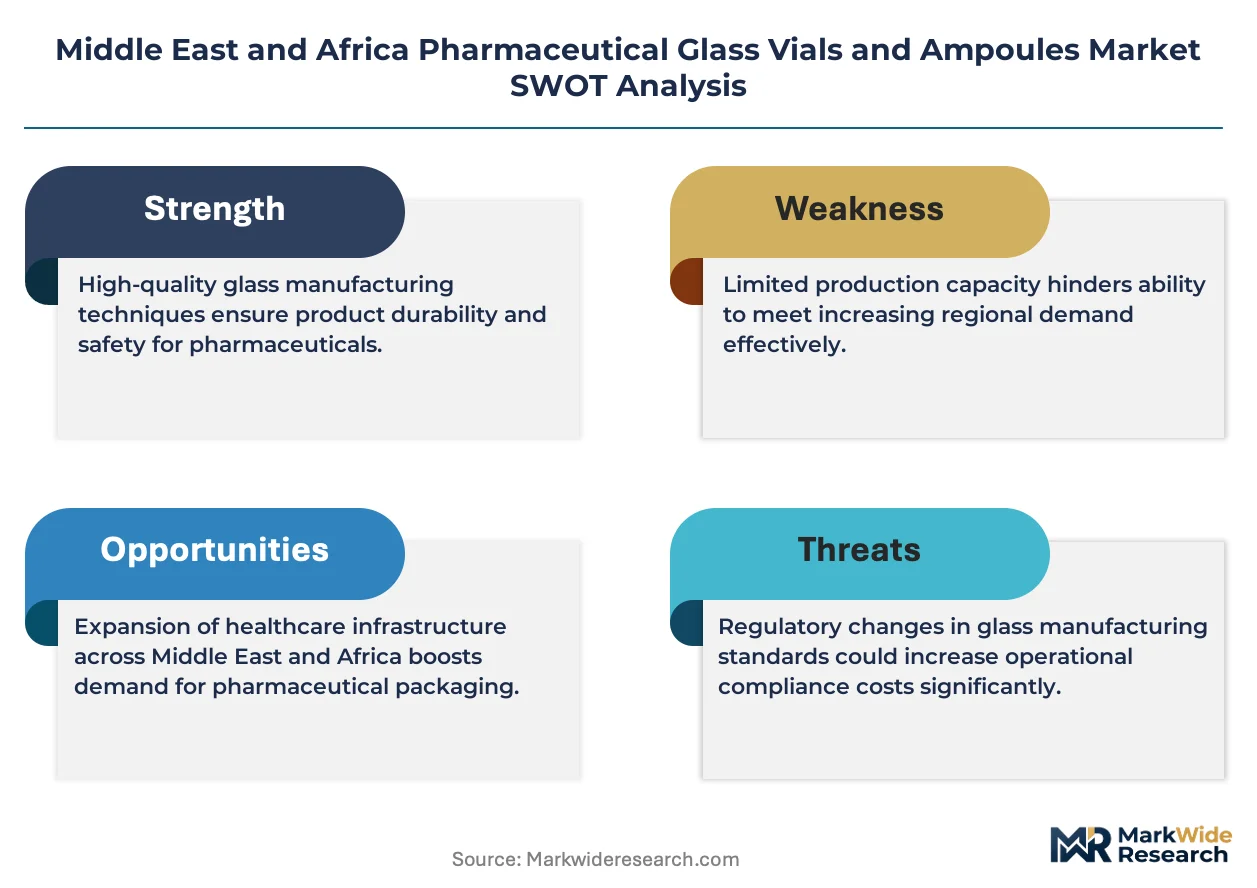
Market Restraints
- High-purity silica sand concentration:Egyptian and Saudi glassworks depend on imported silica from select Mediterranean quarries, exposing input costs to shipping rate volatility and currency fluctuation risk.
- Type I borosilicate technical limitation:Higher melting temperatures required for hydrolytic resistance-grade glass constrain furnace throughput and elevate energy intensity versus soda-lime alternatives.
- Dual certification burden:Divergent SFDA and SAHPRA pharmacopeial compliance pathways force manufacturers to maintain parallel quality systems, elevating overhead for cross-border commercialization.
Strategic Opportunities
- North African fill-finish underpenetration:Morocco and Tunisia lack domestic Type I vial production, creating import substitution potential for Egyptian and South African manufacturers with excess molded glass capacity.
- mRNA cold-chain infrastructure:Ultra-low temperature storage requirements for lipid nanoparticle formulations are accelerating demand for borosilicate ampoules with specialized thermal profile validation.
- ICH guideline harmonization:Progressive alignment between Egypt's Drug Authority and International Council for Harmonisation standards is narrowing export-grade certification gaps, unlocking multi-territory supply contracts.
Industry Challenges
- Specialized furnace engineering talent scarcity:Borosilicate glass production requires operators trained in platinum-lined refractory management, a skillset concentrated in European and Asian technical institutes with limited Middle East and Africa pipeline.
- Serialization equipment capex intensity:SFDA-mandated track-and-trace infrastructure demands laser-etching and vision-system investments that strain mid-cap vial converters with limited access to project finance.
- SAHPRA certification timeline compression:South African regulatory review cycles for imported primary packaging are extending, delaying product launches and straining working capital for distributors holding pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market |
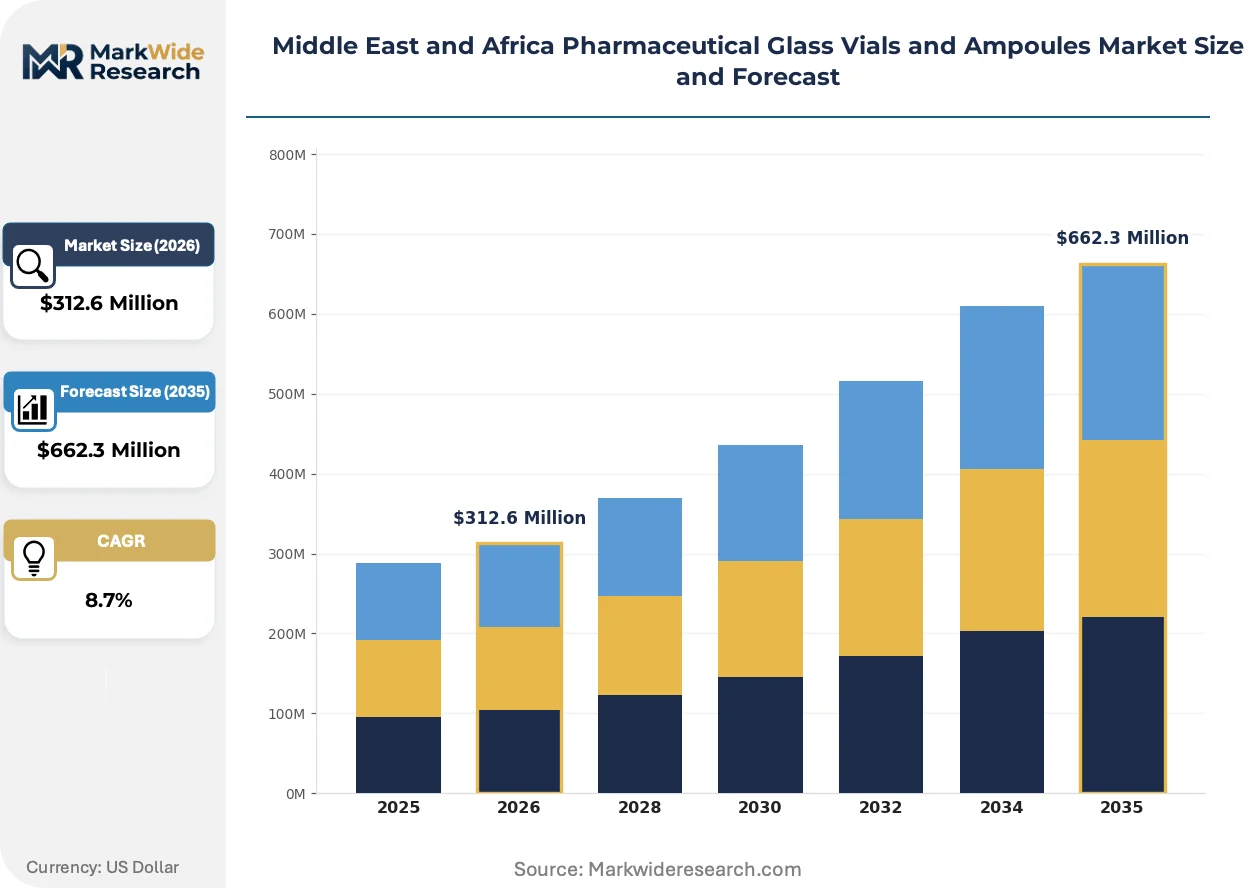
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Cartridges, Bottles Material: Type I Glass, Type II Glass, Type III Glass, Plastic End User: Pharmaceutical Companies, Contract Manufacturers, Research Laboratories, Healthcare Facilities Application: Liquid Medicines, Vaccines, Injectable Solutions, Diagnostic Reagents |
| Companies Covered | Stevanato Group S.P.A, Schott AG, Gerresheimer AG, DWK Life Sciences, Borosil Limited, RAK Ghani Glass LLC, Arab Pharmaceutical Glass Co., Bormioli Pharma, Sisecam, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market Trends and Innovations
Glass manufacturing platforms are converging with digital traceability infrastructure, compressing the gap between primary packaging production and regulatory compliance verification.
Ready-to-use (RTU) sterilized vial formats are consolidating procurement patterns across Saudi and South African fill-finish operations. Contract manufacturing organizations are abandoning in-house washing and depyrogenation lines in favor of pre-sterilized, nested container systems. This shift is consolidating supplier relationships around integrated RTU platform providers capable of delivering validated closure integrity without downstream processing.
SFDA Drug Track and Trace System mandates are restructuring tender eligibility across Gulf Cooperation Council procurement channels. Serialization requirements now disqualify suppliers lacking integrated data-matrix printing and aggregation capabilities. Biologics manufacturers in Riyadh and Jeddah are responding by consolidating vendor panels around German and regional converters with certified track-and-trace infrastructure.
Hospital network procurement is compressing supplier tiers through direct contracting with certified vial manufacturers. Large Saudi health systems are bypassing traditional distribution intermediaries, negotiating volume commitments directly with borosilicate converters for multi-year biologics campaigns. This disintermediation is most visible in Riyadh's King Faisal Specialist Hospital network, where centralized purchasing is consolidating annual vial volumes under single-source agreements with traceability-verified suppliers.
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market Segmentation
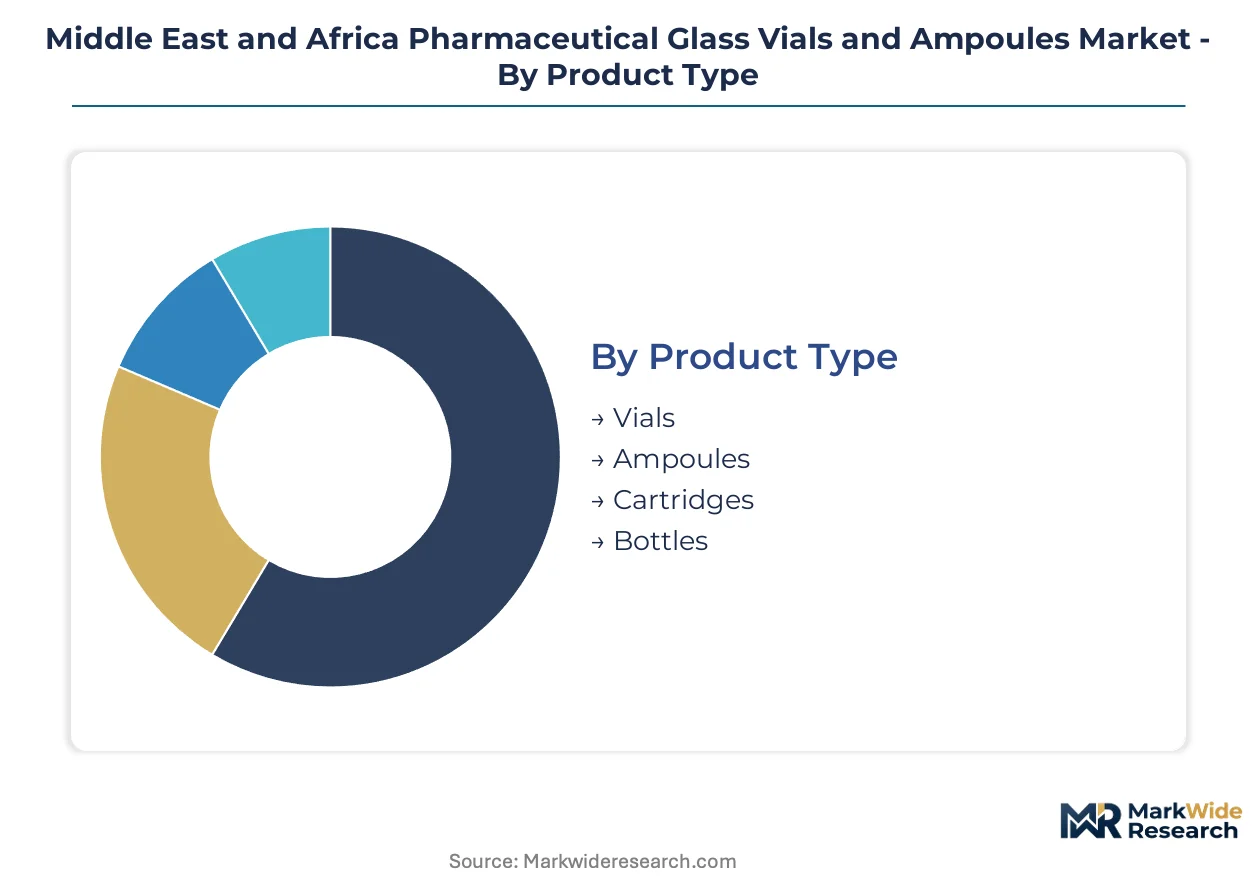
Segmentation in this market maps directly to regulatory compliance tiers and thermal performance requirements. Material chemistry, container geometry, and end-use sterilization protocols create distinct procurement channels that suppliers must navigate simultaneously.
Product Type:
Container geometry dictates closure system compatibility and dosing precision, with upgrade cycles tracking biologics formulation complexity.
- Vials:Multi-dose borosilicate containers with validated resealability for refrigerated biologics. Saudi hospital networks and Egyptian fill-finish clusters are consolidating procurement around screw-cap and crimp-seal formats for monoclonal antibody campaigns.
- Ampoules:Single-dose sealed glass units requiring snap-break administration. South African vaccine distributors favor these for field immunization programs where sterility assurance must survive last-mile temperature excursions.
- Cartridges:Pre-filled syringe-compatible cylinders with integrated plunger systems. Pen-injector adoption for diabetes and hormone therapies is absorbing molded glass volumes in UAE and Morocco.
- Bottles:Larger-format containers for diagnostic reagents and bulk API storage. Research laboratories in Cairo and Johannesburg source these for non-parenteral pharmaceutical intermediates.
Vials sit at the top of the volume ranking, with cartridges climbing the fastest.
Material:
Glass chemistry determines hydrolytic resistance and leachate profiles, with cost tiers separating export-grade from domestic-use production.
- Type I Glass:Borosilicate formulations with low alkali content and thermal shock tolerance exceeding 200°C differential. SFDA-mandated serialization is restricting tender eligibility to Type I-certified suppliers for Saudi biologics manufacturing.
- Type II Glass:Surface-treated soda-lime glass with delamination-resistant coating. Contract manufacturers in 10th of Ramadan City deploy these for cost-sensitive liquid generics targeting North African export markets.
- Type III Glass:Standard soda-lime composition for non-reactive oral and topical preparations. Domestic Egyptian pharmaceutical packaging for local distribution absorbs these volumes.
- Plastic:Cyclic olefin polymer and copolymer alternatives for protein-sensitive biologics. South African mRNA vaccine cold-chain infrastructure is piloting polymer pre-filled syringes for ultra-low temperature stability.
Type I Glass dominates value concentration, with plastic alternatives gaining share fastest in specialized cold-chain applications.
End User:
Customer scale and sterilization capability create divergent procurement patterns, from bulk tender volumes to specialized research quantities.
- Pharmaceutical Companies:Integrated manufacturers with captive fill-finish lines and validated supplier audits. Saudi Arabia's domestic biologics producers maintain direct contracts with German-engineered borosilicate converters.
- Contract Manufacturers:Third-party fill-finish operators serving multiple drug sponsors. Egyptian clusters in New Borg El-Arab are aggregating ready-to-use vial demand across European and Gulf export clients.
- Research Laboratories:Academic and clinical trial sites requiring small-batch flexibility. South African medical research institutes source nested, pre-sterilized formats to eliminate in-house depyrogenation.
- Healthcare Facilities:Hospital pharmacies with direct procurement authority. King Faisal Specialist Hospital network in Riyadh bypasses distributors for multi-year vial commitments with traceability-verified sources.
Pharmaceutical companies anchor volume procurement, with contract manufacturers expanding most quickly as Egyptian and South African outsourcing capacity deepens.
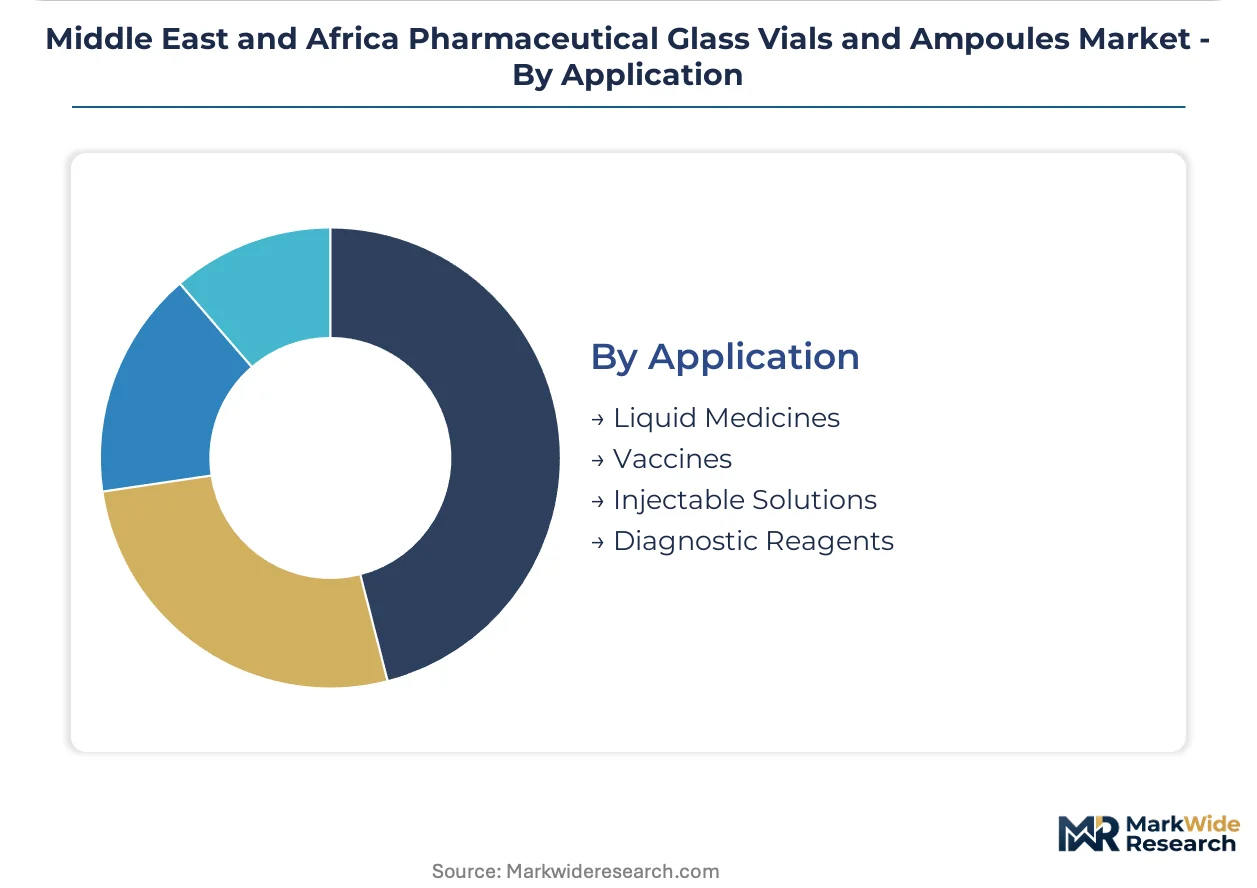
Application:
Formulation stability requirements and administration routes segment demand across temperature sensitivity and closure integrity specifications.
- Liquid Medicines:Aqueous and solvent-based parenteral solutions requiring hydrolytic resistance validation. Saudi hospital networks scale refrigerated storage for antibiotic and analgesic injectables in Type I borosilicate.
- Vaccines:Temperature-sensitive immunological preparations with strict cold-chain protocols. Egyptian government procurement for export-oriented vaccine fill-finish is absorbing rising molded vial volumes.
- Injectable Solutions:Biologics and biosimilars demanding delamination-resistant contact surfaces. SAHPRA certification timelines are compressing supplier selection for South African monoclonal antibody launches.
- Diagnostic Reagents:In-vitro chemistry and immunoassay components with shelf-life stability requirements. Research laboratories in Casablanca and Nairobi source amber glass variants for light-sensitive formulations.
Liquid medicines hold the largest installed base, with injectable solutions on the steepest expansion trajectory as biologics penetration accelerates across Gulf and South African health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical glass manufacturing in the Middle East and Africa traces its modern lineage to post-1970s industrialization drives, when Egyptian and Saudi state-led programs established the region's first borosilicate furnace operations to reduce import dependence on European container suppliers.
Saudi Arabia
King Faisal Specialist Hospital and Saudi Aramco's healthcare subsidiaries are scaling refrigerated biologics storage for monoclonal antibody therapies. SFDA serialization mandates now require unit-level data-matrix traceability on every primary container, disqualifying uncertified suppliers from government tender channels. The Riyadh-based King Salman Biotech Cluster is aggregating fill-finish capacity for domestic insulin and vaccine production.
Egypt
Contract manufacturers in 10th of Ramadan City and New Borg El-Arab are absorbing rising volumes of Type I borosilicate vials for temperature-sensitive formulations targeting European export markets. The Egyptian Drug Authority has accelerated ICH guideline alignment, narrowing certification gaps that previously stranded capital in obsolete quality systems. Cairo's pharmaceutical packaging corridor now hosts the region's largest concentration of molded glass conversion capacity.
South Africa
SAHPRA's extended review timelines for imported primary packaging are compressing working capital cycles for distributors holding pre-certified inventory. Hospital networks in Johannesburg and Cape Town are consolidating procurement around direct contracts with traceability-verified borosilicate suppliers. The Western Cape biotech hub is piloting polymer alternatives for mRNA cold-chain infrastructure.
United Arab Emirates
MOHAP's pharmaceutical traceability requirements are tightening container documentation standards across Dubai and Abu Dhabi free zones. The Jebel Ali pharmaceutical logistics corridor is absorbing rising volumes of ready-to-use sterilized vial formats for regional redistribution. Pen-injector adoption for diabetes therapies in UAE health systems is pulling molded glass cartridge demand.
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market Competitive Landscape
The competitive structure tilts toward European-engineered premium suppliers with certified serialization infrastructure. Three to five integrated converters dominate tender eligibility across Gulf Cooperation Council procurement channels, while regional fabricators compete on logistics proximity for Egyptian and North African fill-finish clusters. Two strategic archetypes prevail: German-engineered borosilicate specialists with integrated track-and-trace platforms, and regional converters leveraging distribution hub proximity for just-in-time delivery. Capacity expansion and strategic partnerships represent the dominant competitive moves, as mid-cap players seek to bridge certification gaps without full vertical integration into furnace operations.
Among European-engineered specialists, Schott AG and Gerresheimer AG exemplify the premium-tier archetype with validated borosilicate platforms. Stevanato Group S.P.A occupies a position within the integrated containment and delivery system segment. Regional fabricators including RAK Ghani Glass LLC and Arab Pharmaceutical Glass Co. represent the proximity-driven competitive vector, serving Egyptian and Gulf fill-finish operators with reduced logistics lead times.
| Leading Market Players |
|---|
| Stevanato Group S.P.A |
| Schott AG |
| Gerresheimer AG |
| DWK Life Sciences |
| Borosil Limited |
| RAK Ghani Glass LLC |
| Arab Pharmaceutical Glass Co. |
| Bormioli Pharma |
| Sisecam |
| Others |
Pricing and Supply Chain Analysis
Backward integration into high-purity silica sourcing anchors supply position and pricing power for Egyptian and Saudi glassworks, while European-engineered specialists leverage captive furnace technology to command premium positioning across Gulf Cooperation Council tender channels. SFDA serialization mandates are compressing supplier eligibility, forcing procurement consolidation around traceability-verified borosilicate platforms with integrated data-matrix capabilities.
Pricing Analysis
Bundled ready-to-use sterilized formats versus unbundled bulk vial supply splits procurement patterns across Saudi and South African fill-finish operations. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered Type I borosilicate from Egyptian molded alternatives and domestic soda-lime generics. Pricing pressure stems from SFDA-mandated serialization capex burdens that strain mid-cap converters without project finance access. Contract manufacturers exhibit highest price sensitivity, while Saudi hospital networks prioritize certification grade over unit cost.
Supply Chain Analysis
Freight cost volatility from Mediterranean silica quarries to Egyptian and Saudi furnace operations exposes input cost structures to shipping rate fluctuation and currency risk. Manufacturing concentrates in Germany, Egypt, and the UAE, with borosilicate glass production drawing from imported high-purity silica sand, platinum-lined refractory components, and specialized furnace engineering talent. Single-source vulnerability sits with European technical institutes for operator training. Distribution runs through Jebel Ali pharmaceutical logistics corridor for regional redistribution across Gulf and North African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the shift toward Type I borosilicate specifications for monoclonal antibody and mRNA-based therapeutics that disqualify lower-grade alternatives. Premium certification tiers are consolidating procurement around traceability-verified suppliers with integrated serialization infrastructure.
For Market Incumbents: Deepen backward integration into high-purity silica sourcing to defend margin position against Egyptian and Saudi furnace cost volatility. Anchor premium positioning through SFDA and SAHPRA dual certification investments that strand mid-cap competitors in obsolete quality systems. Consolidate vendor relationships with King Faisal Specialist Hospital network and other Gulf health systems through multi-year direct contracting agreements. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Type I borosilicate supply creates white-space opportunity for regional converters with logistics proximity to North African fill-finish clusters. Target Morocco and Tunisia import substitution demand where domestic Type I vial production remains absent. Penetrate through ready-to-use sterilized format partnerships with Egyptian contract manufacturers in 10th of Ramadan City. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap regional fabricators with distribution hub proximity because SFDA serialization mandates are disqualifying uncertified suppliers and consolidating tender volumes toward integrated track-and-trace platforms. Acquisition targets should demonstrate validated borosilicate furnace operations or captive ready-to-use sterilization capacity. Watch SAHPRA certification timeline compression as the inflection signal for South African market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sourcing | Egyptian and Saudi glassworks reduce exposure to Mediterranean shipping rate volatility and currency fluctuation. |
| Dual Certification Investment | Manufacturers unlock multi-territory supply contracts across SFDA and SAHPRA jurisdictions. |
| Ready-to-Use Sterilized Format Expansion | Contract manufacturers in New Borg El-Arab eliminate downstream washing and depyrogenation processing steps. |
| Serialization Infrastructure Deployment | Laser-etching and vision-system investments qualify suppliers for Gulf Cooperation Council government tender channels. |
| North African Distribution Hub Establishment | Proximity to Morocco and Tunisia fill-finish operations captures import substitution demand for Type I borosilicate. |
Research Methodology
Coverage spans the Middle East and Africa, with primary inputs from each major market cluster combining interviews with regulatory affairs leads at SFDA and SAHPRA, procurement managers at Saudi hospital networks, plant managers at Egyptian glassworks, and fill-finish operators in 10th of Ramadan City. Secondary validation draws from pharmacopeial compliance databases, customs trade records for silica sand imports, and pharmaceutical packaging tender documentation. Bottom-up facility capacity assessments triangulate against top-down regional demand modeling.
Granularity-level framing segments the market by material chemistry, container geometry, end-user sterilization capability, and application temperature sensitivity. Volume and value outputs reflect modeling across the projection horizon with CAGRs derived from biologics penetration rates and regulatory compliance investment cycles. Forecast inputs incorporate SFDA serialization mandate implementation timelines and Egyptian Drug Authority ICH guideline alignment momentum.
The model assumes a particular technology adoption path; alternative pathways for polymer alternatives in mRNA cold-chain infrastructure would alter the outlook for borosilicate glass demand. Forecasts reflect assumptions about regulatory harmonization momentum and furnace engineering talent pipeline development. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Automated Drug Kiosk Market