
 Radiochemical Synthesizers Market | 2026-2036
Radiochemical Synthesizers Market Size, Share, and Industry Trends Forecast 2026-2036
Radiochemical Synthesizers Market Analysis
Copper-64 is consolidating its position as a preferred alternative to gallium-68 for certain theranostic applications, altering isotope economics across the installed base. BV Cyclotron VU leverages its European cyclotron network to sustain regional supply security for zirconium-89 and copper-64. IBA RadioPharma Solutions anchors its competitive position through integrated cyclotron-to-synthesizer system architectures. NorthStar Medical Technologies differentiates via non-uranium-based molybdenum-99 production technology that reshapes reactor dependency assumptions.
A radiochemical synthesizer is an automated or semi-automated system engineered to produce radiopharmaceuticals through controlled chemical reactions involving short-lived radioisotopes, typically operating within lead-shielded hot cells with synthesis times under 60 minutes to accommodate half-lives ranging from 110 minutes for fluorine-18 to 68 minutes for gallium-68. Its primary purpose is to transform cyclotron- or generator-produced radionuclides into injectable diagnostic or therapeutic agents with reproducible radiochemical purity exceeding 95 percent. Diagnostic radioisotopes currently occupy the largest product segment due to entrenched fluorodeoxyglucose protocols, while therapeutic radioisotopes represent the fastest-expanding category as lutetium-177 and actinium-225 programs advance through clinical pipelines. Cyclotron technology leads installed capacity globally, though reactor-based systems retain critical importance for technetium-99m and iodine-131 production where regional reactor infrastructure persists.
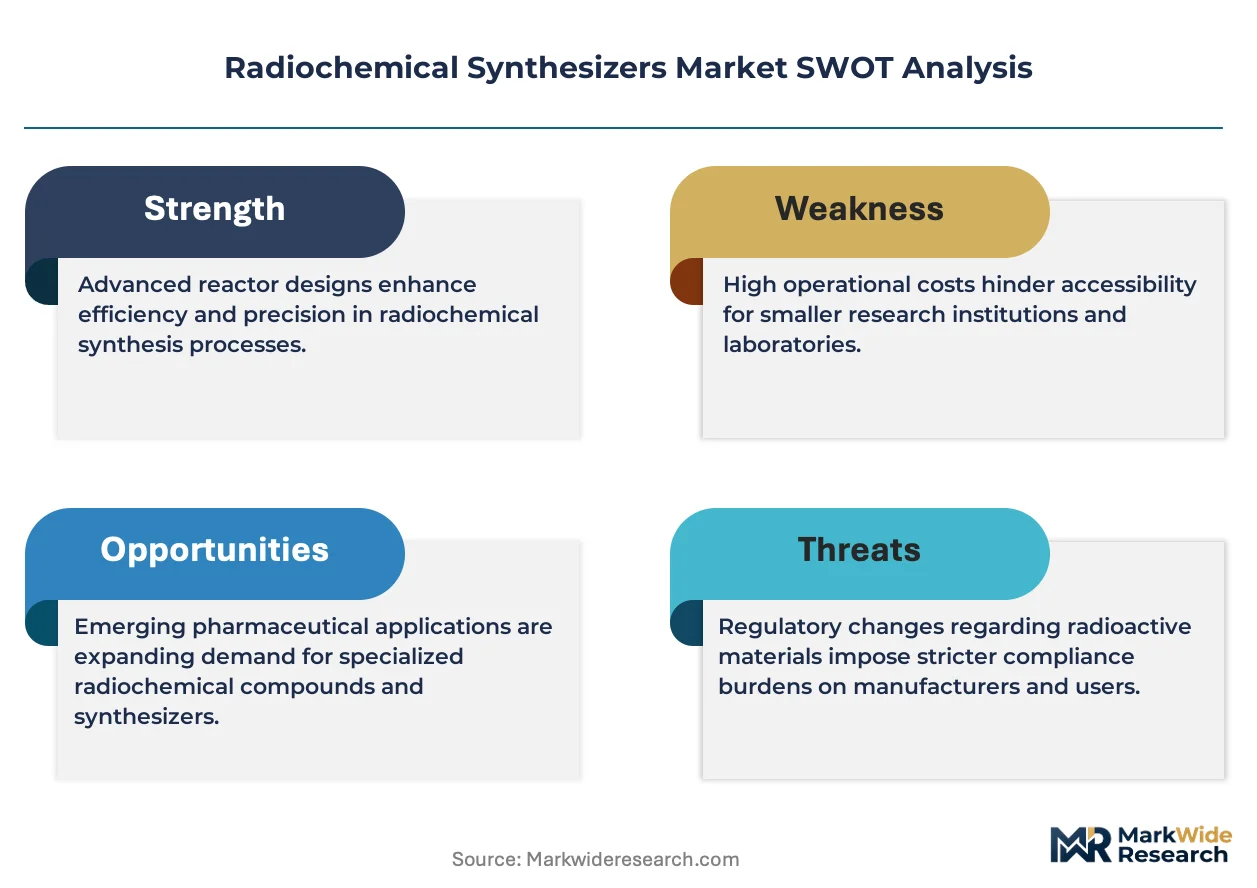
The FDA governs radiopharmaceutical manufacturing under 21 CFR Part 212 for PET drugs, while the EMA's GMP Annex 3 and the IAEA's safety standards shape European and international quality expectations respectively. These frameworks compel vendors to engineer synthesizers with embedded process analytical technology and electronic batch records that satisfy divergent jurisdictional documentation requirements. Stakeholders must weigh capital deployment between cyclotron-based regional production hubs and centralized reactor supply chains as isotope portfolios fragment across diagnostic and therapeutic modalities.
Market Dynamics
Automated synthesis platforms are compressing production timelines for short-lived isotopes, forcing capital redeployment toward integrated cyclotron-to-dispenser architectures that reduce human handling errors and batch-to-batch variability in radiopharmaceutical manufacturing.
Growth Catalysts
- Theranostic Expansion:Lutetium-177 and actinium-225 clinical pipelines are pulling demand for multi-isotope synthesis systems capable of switching between diagnostic and therapeutic production modes within single facilities.
- FDA 21 CFR Part 212 Enforcement:Tightened current good manufacturing practice requirements for PET drugs are mandating process analytical technology integration that only advanced synthesizer architectures can deliver.
- Cyclotron Network Densification:Germany, Japan, and the United States are adding regional production nodes to reduce radionuclide transport distances and decay losses for fluorine-18 and gallium-68.
Market Restraints
- Helium-3 Supply Concentration:Neutron detection systems critical for synthesis quality control face input scarcity concentrated in Russian and Qatari export channels.
- Lead Shielding Cost Volatility:Hot cell construction materials have experienced price swings that inflate total installed system costs beyond budgeted capital allocations at academic medical centers.
- Technetium-99m Generator Dependency:Reactor-based molybdenum-99 supply chains in Canada and the Netherlands create single-point vulnerabilities that retard full cyclotron transition.
Strategic Opportunities
- India Nuclear Medicine Infrastructure:CDSCO regulatory pathways for radiopharmaceutical manufacturing are opening as the country's atomic energy establishment licenses additional cyclotron sites in Mumbai, Bengaluru, and New Delhi.
- Copper-64 Zirconium-89 Portfolio Expansion:Longer half-life isotopes are enabling centralized production with validated cold-chain distribution to satellite imaging centers lacking on-site synthesis capability.
- AI-Enabled Batch Optimization:Machine learning algorithms trained on synthesis parameter datasets are reducing radiochemical yield variability and cutting quality control release times.
Industry Challenges
- Qualified Radiochemist Scarcity:Specialized personnel capable of validating automated systems under FDA and EMA frameworks command premium compensation that strains operational budgets.
- Legacy Hot Cell Retrofit Complexity:Existing lead-shielded facilities designed for manual synthesis require structural modifications to accommodate robotic component integration and updated HVAC specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiochemical Synthesizers Market |
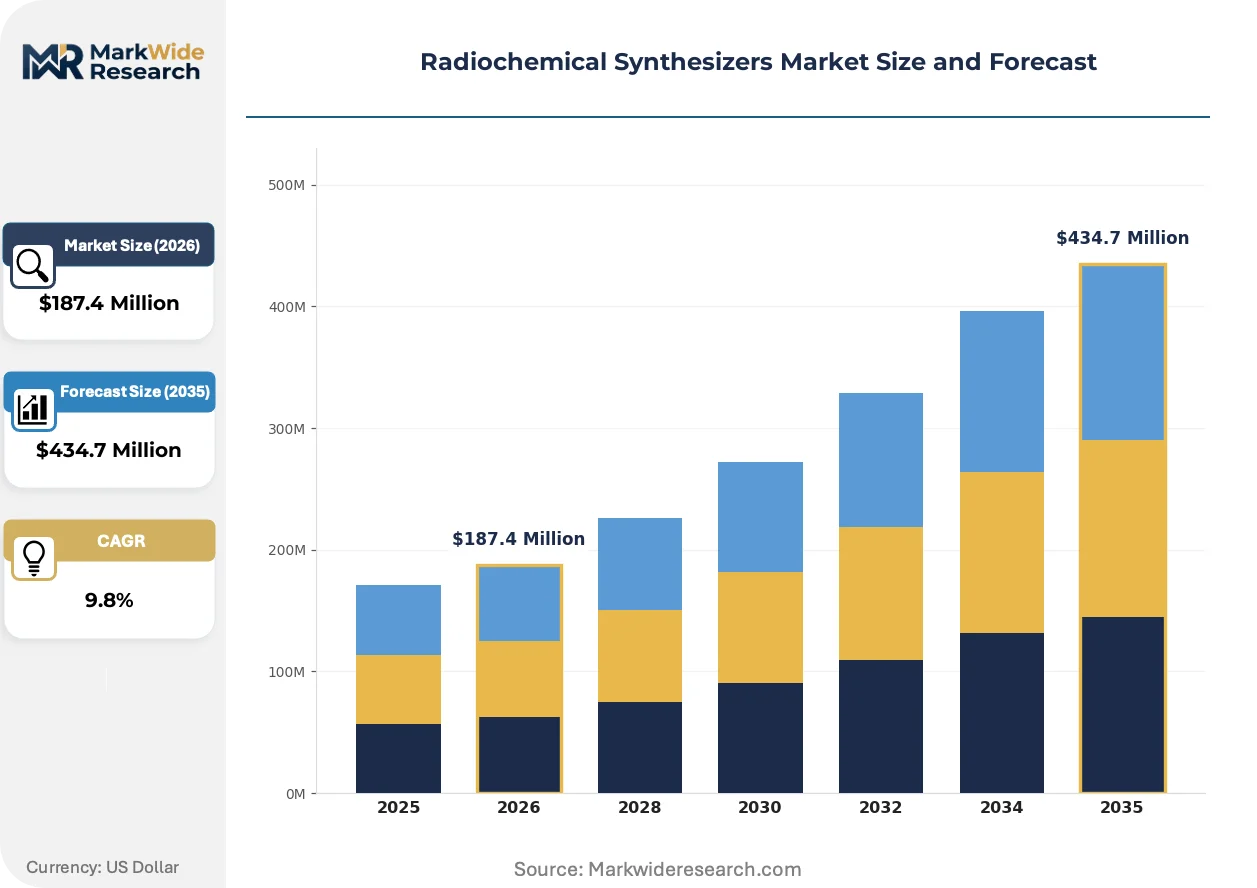
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Radioisotopes, Diagnostic Radioisotopes, Radiolabeling Kits, Radionuclide Generators Technology: Cyclotron, Reactor-based, HPLC, PET/CT Imaging Application: Cancer Treatment, Medical Imaging, Nuclear Medicine, Research Activities End User: Hospitals, Research Institutions, Diagnostic Centers, Pharmaceutical Companies |
| Companies Covered | BV Cyclotron VU, LabLogic Systems Ltd, IBA RadioPharma Solutions, Advion, Inc, Mercurius Health, NorthStar Medical Technologies, Elysia, Lantheus Medical Imaging, Inc, Advanced Cyclotron Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiochemical Synthesizers Market Emerging Trajectories
Continuous-flow microreactor architectures are displacing conventional batch synthesis methods, enabling real-time reaction monitoring and reducing radioactive waste volumes. These platforms are reshaping capital deployment priorities across nuclear medicine departments.
Microfluidic synthesis cartridges are automating the precision metering of reagents and radionuclides in sub-milliliter reaction volumes. Academic medical centers in the United States and Germany are adopting these systems to reduce precursor consumption and improve radiochemical purity consistency. The technology is automating quality assurance steps previously requiring manual sampling and chromatographic analysis.
EMA's GMP Annex 3 revisions for radiopharmaceuticals are mandating electronic batch records and enhanced environmental monitoring. European manufacturers must retrofit synthesizers with additional sensors and data-logging capabilities to maintain market authorization. Germany's nuclear pharmacy sector is absorbing compliance costs fastest, driving vendor consolidation toward integrated hardware-software platforms.
Academic medical centers are unbundling equipment procurement from long-term service contracts, negotiating separate agreements for preventive maintenance and software updates. This disintermediation pressures synthesizer vendors to compete on transparent lifecycle cost models rather than bundled financing. The pattern is most pronounced in Japan, where hospital procurement committees now require detailed total cost of ownership disclosures before capital committee approval.
Radiochemical Synthesizers Market Segmentation
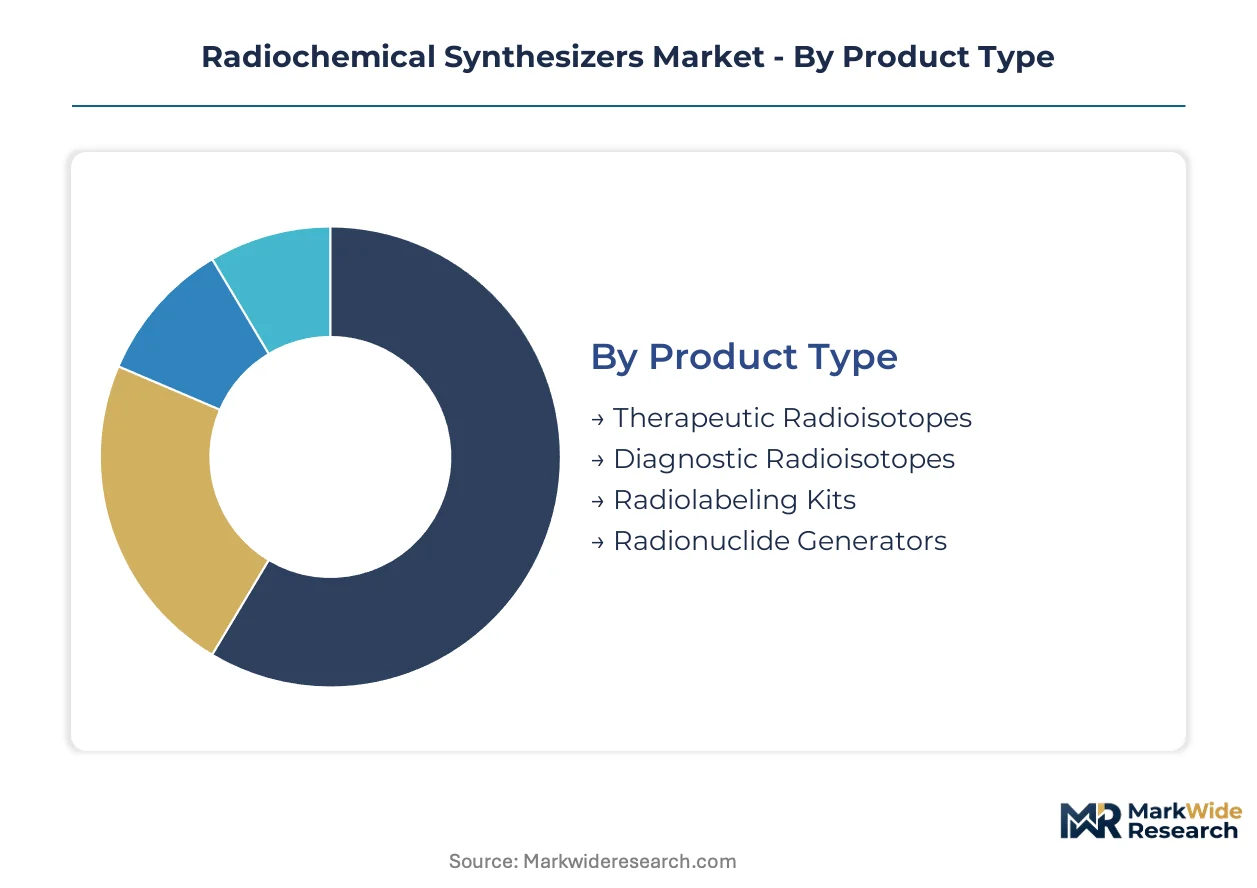
Radiochemical synthesizer procurement decisions hinge on matching isotope half-life characteristics to facility infrastructure and regulatory pathways. Segmentation reveals how FDA 21 CFR Part 212, EMA GMP Annex 3, and IAEA safety standards differentially constrain each product category and end-use configuration.
Product Type:
FDA 21 CFR Part 212 imposes current good manufacturing practice requirements on PET drug production that vary sharply across isotope categories, while EMA GMP Annex 3 adds layer-specific environmental monitoring mandates for European facilities.
- Diagnostic Radioisotopes:Fluorine-18 and gallium-68 formulations dominate installed synthesis capacity, with fluorodeoxyglucose protocols anchoring demand at academic medical centers in Germany and Japan. Cyclotron infrastructure investments in the United States concentrate procurement around 110-minute and 68-minute half-life isotopes that reward proximity production.
- Therapeutic Radioisotopes:Lutetium-177 and actinium-225 pipelines are pulling capital toward multi-isotope systems capable of switching production modes. CDSCO regulatory pathways in India are opening as atomic energy establishments license additional cyclotron sites in Mumbai and New Delhi.
- Radiolabeling Kits:Pre-packaged reagent sets reduce precursor consumption and improve batch-to-batch consistency for satellite imaging centers lacking full synthesis capability.
- Radionuclide Generators:Molybdenum-99 technetium-99m systems retain critical importance where regional reactor infrastructure persists in Canada and the Netherlands.
Leading the category by volume: Diagnostic Radioisotopes. Growing fastest: Therapeutic Radioisotopes.
Technology:
Capital deployment splits between cyclotron-based regional hubs and centralized reactor supply chains as isotope portfolios fragment, with total cost of ownership calculations now disaggregating equipment from long-term service contracts.
- Cyclotron:Proton acceleration systems anchor global installed capacity for fluorine-18 and gallium-68 production. Germany's nuclear pharmacy sector absorbs compliance costs fastest, driving vendor consolidation toward integrated hardware-software platforms.
- Reactor-based:Neutron capture systems retain dominance for technetium-99m and iodine-131 where uranium-derived molybdenum-99 supply chains persist.
- HPLC:High-performance liquid chromatography modules automate quality assurance steps previously requiring manual sampling and chromatographic analysis.
- PET/CT Imaging:Hybrid scanner integration demands synthesizer architectures that compress production timelines to match imaging appointment scheduling.
Cyclotron systems command the largest installed base. Reactor-based technology faces steepest regulatory headwinds from non-uranium production mandates.
Application:
Clinical trial pipelines and reimbursement frameworks determine synthesis volume allocation across diagnostic and therapeutic modalities, with theranostic expansion blurring traditional boundaries.
- Medical Imaging:PET protocols for oncology and neurology anchor fluorodeoxyglucose consumption at hospitals and diagnostic centers.
- Cancer Treatment:Targeted radionuclide therapy programs pull demand for lutetium-177 and actinium-225 production systems.
- Nuclear Medicine:Departmental expansion at academic medical centers drives automated synthesis capacity additions.
- Research Activities:Preclinical and translational studies require flexible synthesizer configurations for novel radiotracer development.
Medical Imaging holds the largest volume share. Cancer Treatment applications are climbing the fastest as therapeutic pipelines mature.
End User:
Procurement authority concentrates differently across facility types, with Japanese hospital committees now requiring detailed total cost of ownership disclosures before capital approval.
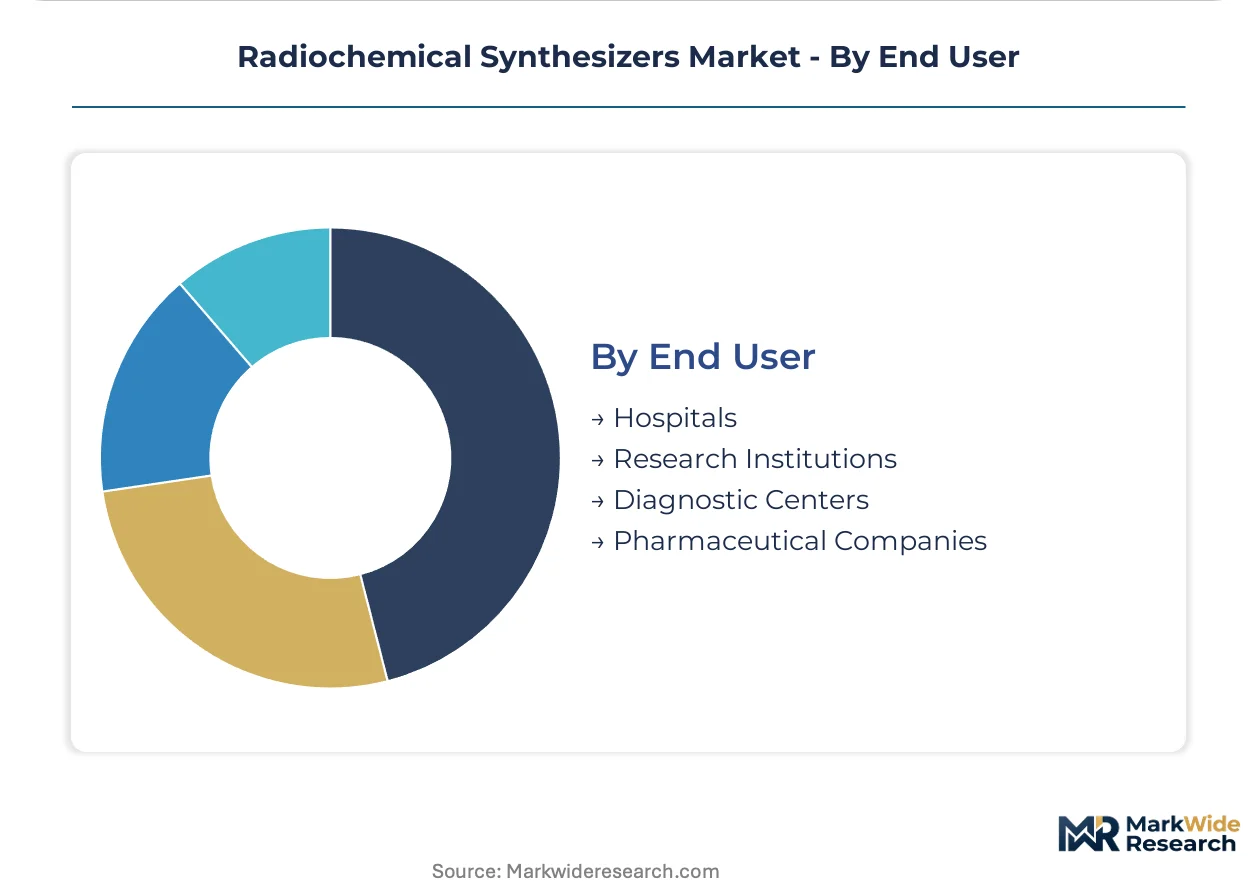
- Hospitals:Academic medical centers in the United States, Germany, and Japan lead cyclotron infrastructure expansion to reduce radionuclide transport distances and decay losses.
- Diagnostic Centers:Satellite imaging facilities lacking on-site synthesis capability depend on validated cold-chain distribution from centralized production hubs.
- Research Institutions:Universities and national laboratories pioneer microfluidic synthesis cartridges and continuous-flow microreactor architectures.
- Pharmaceutical Companies:Radiopharmaceutical developers invest in multi-isotope systems to support theranostic drug candidates through clinical trials.
Hospitals represent the largest procurement volume. Pharmaceutical Companies are gaining share fastest as therapeutic radiopharmaceutical pipelines advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in cyclotron-dense markets where reimbursement frameworks and regulatory clarity enable capital deployment. Academic medical centers in the United States, Germany, and Japan anchor procurement volumes. Cyclotron infrastructure investments in these markets compress radionuclide transport distances and decay losses.
United States
Academic medical centers at Duke University Medical Center and Memorial Sloan Kettering Cancer Center expand automated synthesis capacity for fluorine-18 and gallium-68 radiotracers. FDA 21 CFR Part 212 enforcement tightens current good manufacturing practice requirements for PET drug production. Cyclotron networks densify across the Northeast Corridor and California to reduce decay losses during transport.
Germany
Nuclear pharmacy sectors in Munich and Heidelberg absorb compliance costs fastest under EMA GMP Annex 3 revisions for radiopharmaceuticals. Germany's atomic energy establishment licenses additional cyclotron sites to sustain regional supply security for zirconium-89 and copper-64. Vendor consolidation accelerates toward integrated hardware-software platforms as procurement committees demand total cost of ownership disclosures.
Japan
Hospital procurement committees at Tokyo and Osaka academic medical centers now require detailed lifecycle cost models before capital committee approval. METI frameworks shape cyclotron infrastructure planning for molecular imaging reimbursement. The Kanto region anchors domestic synthesis capacity expansion for fluorodeoxyglucose protocols.
India
CDSCO regulatory pathways for radiopharmaceutical manufacturing open as the Department of Atomic Energy licenses cyclotron sites in Mumbai, Bengaluru, and New Delhi. Theranostic expansion pulls demand for multi-isotope synthesis systems capable of switching between diagnostic and therapeutic modes. Mumbai's nuclear medicine infrastructure concentrates early adoption of automated synthesis platforms.
Canada
Reactor-based molybdenum-99 supply chains at Chalk River create single-point vulnerabilities that retard full cyclotron transition for technetium-99m production. Health Canada and PMRA frameworks govern radiopharmaceutical manufacturing alongside provincial procurement policies. Ontario's academic medical centers balance legacy hot cell retrofits against new automated system installations.
Radiochemical Synthesizers Market Vendor Landscape
Integrated cyclotron-to-synthesizer system architectures dominate the current landscape as vendors compete on total solution ownership rather than discrete equipment sales. The vendor base clusters around three strategic archetypes: cyclotron manufacturers extending downstream into synthesis automation, pure-play synthesizer specialists, and radiopharmaceutical developers backward integrating into production equipment. Capacity expansion and technology licensing represent the dominant competitive moves, with European and North American players densifying regional service networks.
Among European cyclotron-to-synthesizer integrators, BV Cyclotron VU and IBA RadioPharma Solutions exemplify the architecture-driven archetype, leveraging cyclotron network density to sustain regional supply security. NorthStar Medical Technologies occupies a position within the non-uranium production technology tier, reshaping reactor dependency assumptions for molybdenum-99 supply chains. These three anchors illustrate how competitive positioning fragments across isotope portfolio breadth, regulatory compliance depth, and service network geographic coverage.
| Leading Market Players |
|---|
| BV Cyclotron VU |
| LabLogic Systems Ltd |
| IBA RadioPharma Solutions |
| Advion, Inc |
| Mercurius Health |
| NorthStar Medical Technologies |
| Elysia |
| Lantheus Medical Imaging, Inc |
| Advanced Cyclotron Systems |
| Others |
Supply Flow & Price Mechanics
Academic medical centers in the United States, Germany, and Japan concentrate procurement authority and negotiate unbundled equipment and service contracts, driving transparent lifecycle cost models rather than bundled financing arrangements. This buyer concentration compresses margins for synthesizer vendors while rewarding integrated hardware-software platforms that demonstrate total cost of ownership advantages.
Pricing Analysis
Volume-heavy diagnostic radioisotope systems operate on thinner margins than therapeutic-capable multi-isotope platforms that command premium positioning. Pricing stratifies across premium, standard, and economy tiers based on FDA 21 CFR Part 212 compliance depth and after-sales service bundling. Cost compression in standard-tier cyclotron-synthesizer bundles intensifies as Japanese hospital procurement committees mandate detailed lifecycle disclosures. Satellite imaging centers lacking on-site synthesis capability exhibit highest price sensitivity, while academic medical centers with cyclotron infrastructure prioritize compliance certification over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle academic medical center demand, while distributor networks serve satellite diagnostic facilities lacking capital committee authority. Component manufacturing concentrates in Belgium, the Netherlands, and the United States for lead-shielded hot cells and robotic synthesis modules. Helium-3 neutron detection systems draw from Russian and Qatari export channels, creating single-source vulnerability for quality control instrumentation. Distribution runs through regional cyclotron networks that compress radionuclide transport distances and decay losses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow microreactor architectures are displacing conventional batch synthesis methods, compressing production timelines and reducing radioactive waste volumes for facilities transitioning from legacy manual systems.
For Market Incumbents: To counter unbundled procurement demands from Japanese and German hospital committees, deepen service network density across cyclotron-dense corridors and anchor pricing through embedded process analytical technology that satisfies FDA 21 CFR Part 212 and EMA GMP Annex 3 documentation requirements simultaneously. For New Entrants and Emerging Players: Enter via CDSCO regulatory pathway specialization for Mumbai and New Delhi cyclotron sites, where atomic energy establishment licensing creates white-space demand for multi-isotope systems capable of switching between diagnostic fluorine-18 production and therapeutic lutetium-177 modes. For Investors and Strategic Acquirers: The window for entry favors non-uranium molybdenum-99 production technology specialists, as reactor dependency assumptions reshape and Health Canada pressures accelerate cyclotron transition timelines; watch for helium-3 supply disruption as inflection signal for neutron detection system substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Cyclotron-to-Synthesizer System Launch | IBA RadioPharma Solutions anchors competitive positioning through unified architecture control. |
| Non-Uranium Production Technology Licensing | NorthStar Medical Technologies reshapes reactor dependency assumptions for molybdenum-99 supply. |
| Regional Cyclotron Network Densification | BV Cyclotron VU sustains European supply security for zirconium-89 and copper-64 isotopes. |
| Microfluidic Synthesis Cartridge Development | Academic medical centers in Germany and the United States reduce precursor consumption through automation. |
| AI-Enabled Batch Optimization Platform | Machine learning algorithms trained on synthesis parameters cut quality control release times for PET drug manufacturing. |
Methodological Framework
Multi-period observation of cyclotron installation rates, FDA 212 compliance audit frequencies, and EMA GMP Annex 3 revision implementation timelines anchored the trend analysis, supplemented by interviews with nuclear medicine department heads, radiopharmaceutical manufacturing directors, cyclotron facility engineers, and hospital procurement committee chairs. Secondary validation drew from FDA 510(k) filings, EMA marketing authorization databases, IAEA safety standard publications, and academic medical center capital expenditure disclosures. Bottom-up synthesizer shipment tracking and top-down nuclear medicine infrastructure investment flows were triangulated to constrain volume estimates.
Segment-weighting applied differential growth assumptions across diagnostic and therapeutic radioisotope categories, with cyclotron versus reactor-based technology splits modeled separately. Isotope half-life characteristics, regional reimbursement framework maturity, and regulatory compliance depth shaped the projection horizon. CAGRs were derived from installed base expansion curves and replacement cycle dynamics. Forecast inputs incorporated helium-3 supply channel concentration, lead shielding material cost volatility, and qualified radiochemist labor market tightness.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained reactor supply disruption or accelerated FDA enforcement of process analytical technology mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Radiosynthesis Equipment Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market