
 Global Autoimmune Disease Therapeutics Market | 2026-2036
Global Autoimmune Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autoimmune Disease Therapeutics Market Foresight
Buyer concentration among hospital systems and specialty pharmacy networks is rebalancing procurement power toward large integrated delivery networks. Pfizer leverages its manufacturing scale to supply biologics across multiple therapy areas. Bristol-Myers Squibb anchors its position through deep R&D investment in immunology. Eli Lilly and Company differentiates via product specialization in type 1 diabetes and related autoimmune conditions.
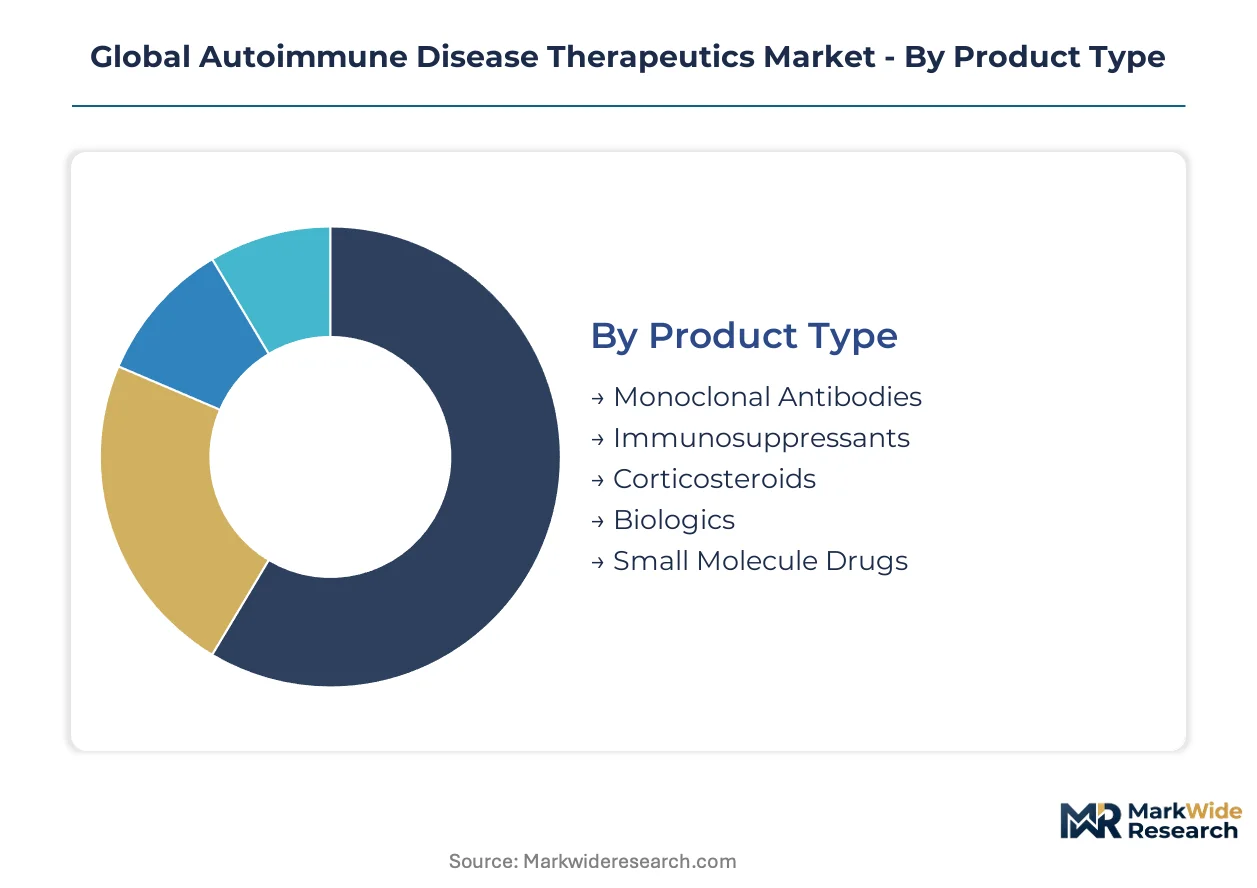
Autoimmune disease therapeutics comprise pharmacological agents engineered to modulate pathological immune responses, including monoclonal antibodies produced through mammalian cell culture and recombinant protein synthesis with defined glycosylation profiles for targeted cytokine blockade. These therapeutics serve to arrest disease progression, induce remission, and prevent irreversible tissue destruction in chronic inflammatory disorders. Monoclonal antibodies occupy the largest revenue pool due to premium pricing and chronic administration requirements. Small molecule drugs compete on oral convenience and biosimilar erosion of injectable biologics. Biologics sustain the fastest expansion trajectory as subcutaneous delivery modes reduce infusion center dependency.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines while raising evidentiary standards for autoimmune indications. The EU AI Act and GDPR constrain real-world data deployment for adaptive clinical trials across European markets. REACH and RoHS compliance requirements shape excipient selection and manufacturing site qualification for global supply. Stakeholders must monitor evolving pharmacovigilance obligations and health technology assessment methodologies as access gates tighten.
Market Dynamics
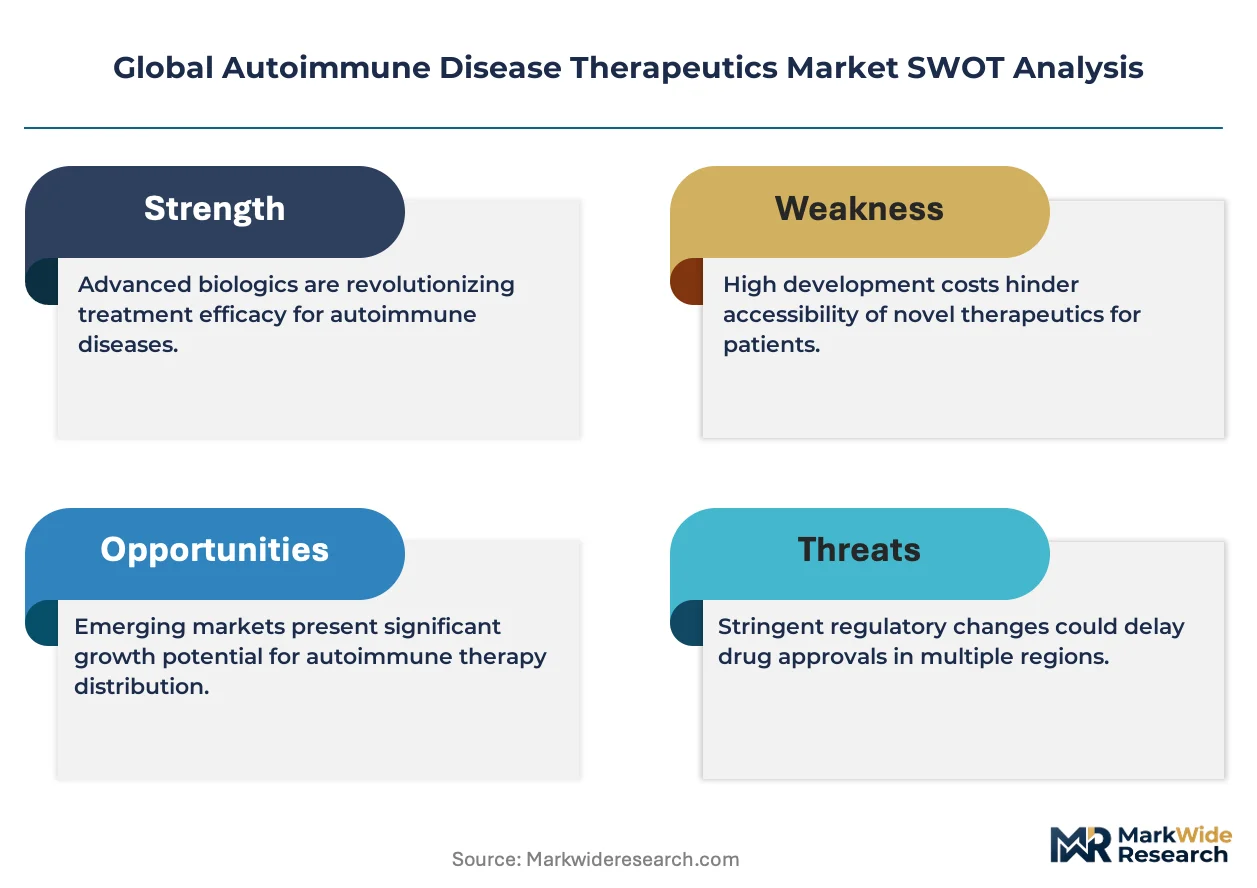
Hospital systems and integrated delivery networks are consolidating procurement of biologic therapies, shifting bargaining power toward large buyers who demand outcome guarantees and volume-based contracting. This concentration is compressing margins for manufacturers while accelerating the shift from infusion centers to subcutaneous delivery modes.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway compresses development timelines for novel immunomodulators, enabling earlier patient access and faster commercialization.
- Subcutaneous Biologics:Self-administration formats reduce infusion center dependency and expand addressable patient populations in rural and underserved areas.
- United States Specialty Pharmacy Networks:Dominant distribution infrastructure supports chronic therapy adherence through centralized patient monitoring and refill management.
Market Restraints
- EMA GDPR Constraints:Real-world data deployment for adaptive clinical trials faces operational friction across European markets, limiting post-market evidence generation.
- Bioreactor Capacity Concentration:Mammalian cell culture manufacturing clusters in the United States and Ireland, creating single-source vulnerability for monoclonal antibody supply.
- Small Molecule Substitution:Oral JAK inhibitors compete on convenience and cost, eroding market position of injectable biologics in rheumatoid arthritis.
Strategic Opportunities
- Japan's Aging Demographics:Underpenetrated rheumatology and dermatology markets offer expansion potential for biosimilars with PMDA-aligned quality frameworks.
- EU AI Act Compliance:Predictive biomarker algorithms for patient stratification create differentiation for manufacturers investing in machine learning infrastructure.
- Home Infusion Services:Channel innovation bypasses traditional hospital outpatient departments, capturing margin and improving patient retention.
Industry Challenges
- Glycoengineering Expertise Scarcity:Defined glycosylation profile optimization requires specialized talent pools that remain concentrated at a limited number of contract development organizations.
- REACH Excipient Qualification:Manufacturing site certification timelines extend 18-24 months for European supply, constraining rapid capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autoimmune Disease Therapeutics Market |
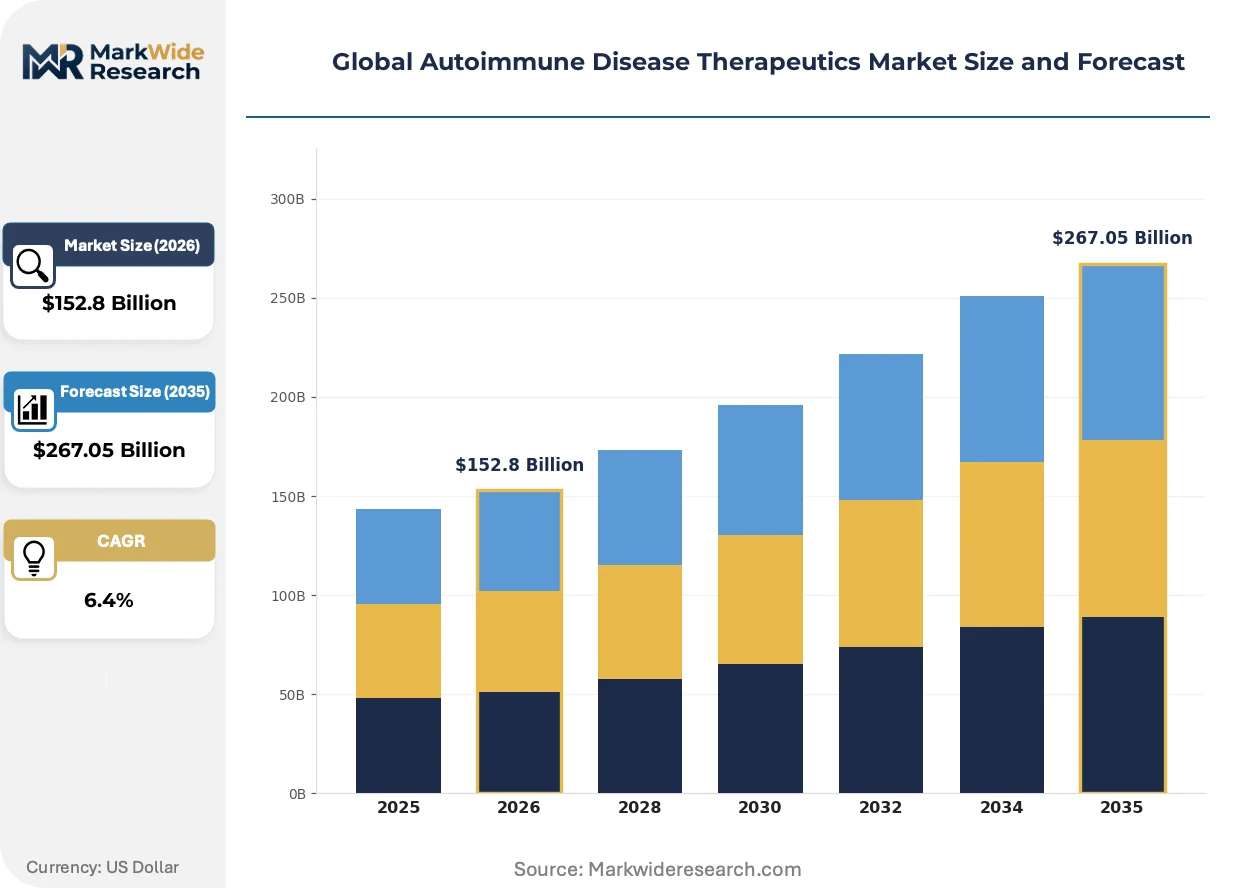
| Market Size in 2026 | $152.8 Billion |
| Market Size in 2035 | $267.05 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Immunosuppressants, Corticosteroids, Biologics, Small Molecule Drugs Therapy Area: Rheumatoid Arthritis, Lupus Erythematosus, Multiple Sclerosis, Psoriasis, Type 1 Diabetes End User: Specialized Clinics, Research Institutions, Ambulatory Care Centers, Diagnostic Laboratories Delivery Mode: Injectable, Oral, Intravenous, Subcutaneous, Topical Administration |
| Companies Covered | Merck, Bristol-Myers Squibb, Pfizer, F. Hoffmann-La Roche, Amgen, Novartis, Sanofi, Eli Lilly and Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autoimmune Disease Therapeutics Market Shifts & Advancements
Biologic manufacturing and patient access models are undergoing parallel transformation. Technology convergence, regulatory adaptation, and buyer consolidation are redefining competitive requirements across therapy areas.
Bispecific antibodies are integrating dual-target cytokine blockade into single therapeutic constructs. Large hospital systems in the United States are adopting these formats for refractory lupus and inflammatory bowel disease. This integration is compressing the development-to-adoption cycle and raising the bar for single-target competitors.
REACH and RoHS compliance requirements are reshaping excipient selection and manufacturing site qualification for global supply. ECHA substance restrictions limit certain stabilizers and process chemicals, forcing reformulation of established biologic products. European manufacturers are responding by qualifying alternative suppliers and investing in green chemistry process development.
Consolidated procurement by integrated delivery networks is displacing fragmented purchasing across independent rheumatology practices. Specialty pharmacy direct-to-patient distribution is replacing wholesale-to-retail channels for chronic autoimmune therapies. This concentration is most visible in the United States, where three national pharmacy benefit managers control formulary placement for biologics.
Global Autoimmune Disease Therapeutics Market Segmentation
Segmentation in autoimmune therapeutics reveals where capital deployment, regulatory complexity, and patient access intersect. Manufacturers configure R&D portfolios and manufacturing assets around therapy-area concentration and delivery-mode economics. Procurement patterns diverge sharply across end-user channels.
Product Type:
Capital intensity peaks with mammalian cell culture infrastructure for biologics, while small-molecule manufacturing requires less upfront investment but faces compressed margins.
- Monoclonal Antibodies:These therapeutics require dedicated bioreactor trains and defined glycosylation control. Demand concentrates in United States hospital systems where infusion center networks support chronic administration. FDA breakthrough therapy designation accelerates development timelines for novel constructs.
- Biologics:Recombinant protein synthesis with post-translational modification demands specialized talent pools concentrated at contract development organizations. European REACH compliance requirements extend manufacturing site qualification timelines, constraining rapid capacity scaling.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites serve transplant and severe autoimmune indications with established generic competition.
- Corticosteroids:Low-cost oral and injectable formulations remain first-line therapy for acute flares across rheumatology practices.
- Small Molecule Drugs:Oral JAK inhibitors compete on convenience against injectable biologics in rheumatoid arthritis, eroding market position through payer preference.
Monoclonal antibodies absorb the bulk of installed capacity; biologics are expanding most quickly.
Therapy Area:
Application concentration determines clinical trial infrastructure investment and specialist physician targeting strategies.
- Rheumatoid Arthritis:The largest addressable population drives biosimilar competition and formulary placement battles among United States pharmacy benefit managers. Subcutaneous delivery formats reduce infusion center dependency.
- Psoriasis:Dermatology biologics command premium pricing with strong patient adherence. IL-17 and IL-23 pathway inhibitors dominate this segment with convenient dosing intervals.
- Multiple Sclerosis:Disease-modifying therapies span injectable, oral, and infusion formats with distinct safety profiles guiding neurologist selection.
- Lupus Erythematosus:Refractory cases drive adoption of bispecific antibodies in large United States hospital systems. EMA pharmacovigilance obligations remain stringent for this indication.
- Type 1 Diabetes:Immunomodulatory approaches target disease modification rather than glucose control, requiring distinct regulatory pathways from metabolic therapies.
Rheumatoid arthritis commands the deepest clinical infrastructure; psoriasis is gaining share fastest.
End User:
Customer-type fragmentation shapes distribution economics and patient retention strategies.
- Specialized Clinics:Rheumatology and dermatology practices concentrate biologic prescribing with direct-to-patient specialty pharmacy coordination.
- Ambulatory Care Centers:These facilities handle infusion administration for intravenous biologics with Medicare reimbursement driving site selection.
- Research Institutions:Academic medical centers anchor clinical trial recruitment for novel immunomodulators with FDA breakthrough therapy designation.
- Diagnostic Laboratories:Companion diagnostic development for predictive biomarker algorithms supports patient stratification in EU AI Act-compliant frameworks.
Specialized clinics capture the highest-margin dispensing; ambulatory care centers are scaling fastest.
Delivery Mode:
Supply concentration and patient convenience trade off across administration formats.
- Subcutaneous:Self-administration devices reduce healthcare system costs and expand rural access. United States specialty pharmacy networks support patient training and adherence monitoring.
- Intravenous:Infusion center administration requires capital-intensive infrastructure with consolidated procurement by integrated delivery networks compressing margins.
- Injectable:Intramuscular and subcutaneous formats span acute and chronic indications with varying needle anxiety and training requirements.
- Oral:Small molecule convenience drives payer preference where clinical equivalence permits substitution from biologics.
- Topical Administration:Localized psoriasis and dermatitis therapies avoid systemic immunosuppression with limited biologic competition.
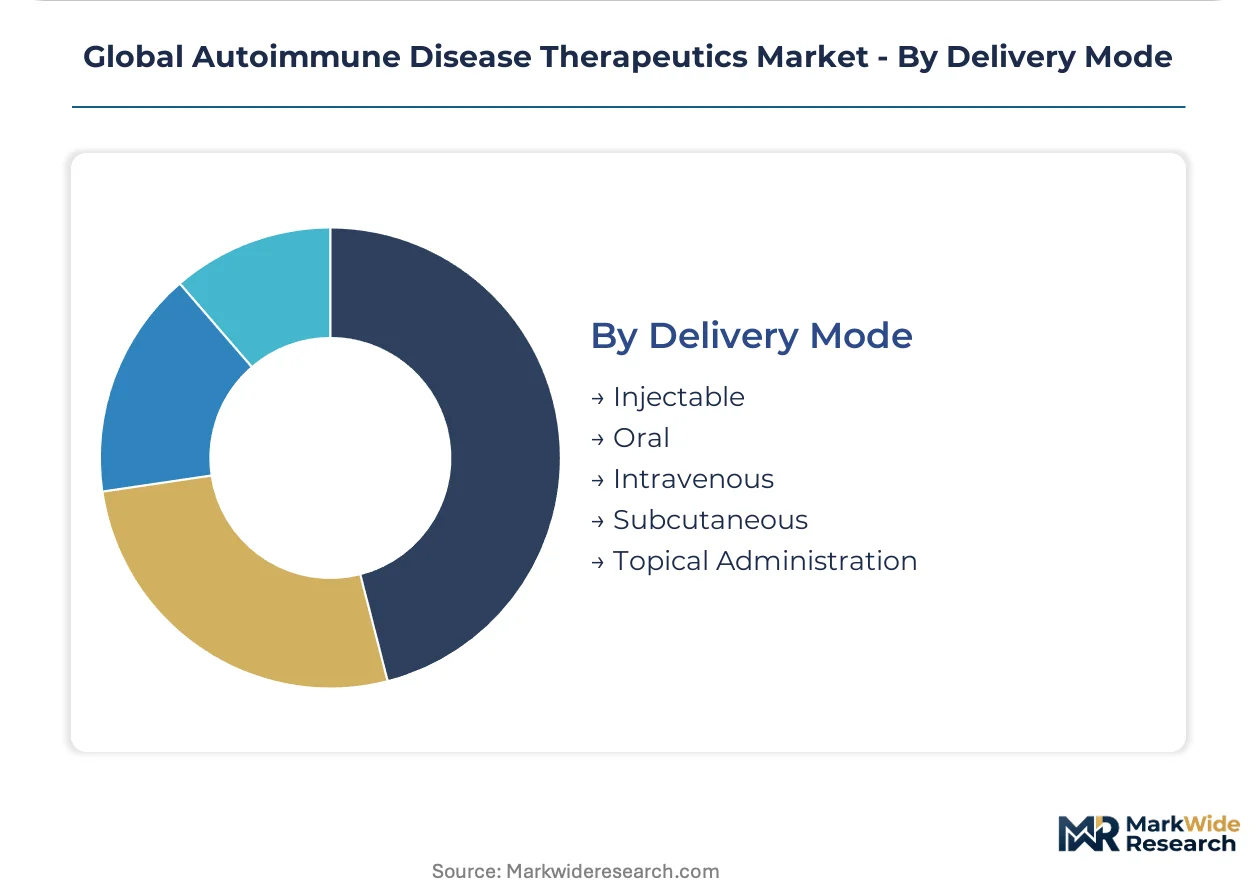
Intravenous delivery anchors current revenue; subcutaneous formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmacy networks and hospital system consolidation concentrate autoimmune therapeutics procurement in the United States, while manufacturing capacity clusters in select European and Asian markets. Japan's aging demographics and Germany's biologics production infrastructure shape regional competitive positioning. Regulatory divergence between FDA accelerated pathways and EMA pharmacovigilance obligations creates operational complexity for multinational portfolios.
United States
Specialty pharmacy networks dominate biologic distribution with direct-to-patient delivery models. FDA breakthrough therapy designation compresses development timelines for novel immunomodulators. The Boston-Cambridge biotech corridor anchors monoclonal antibody R&D with concentrated venture funding and academic medical center partnerships.
Germany
Rheumatology and dermatology prescribing volumes sustain premium biologic demand across statutory health insurance funds. EMA pharmacovigilance obligations and REACH excipient compliance requirements shape manufacturing site qualification. The Rhine-Main region concentrates mammalian cell culture production with integrated fill-finish capabilities serving European supply.
Japan
Aging demographics expand the addressable patient population for rheumatoid arthritis and psoriasis biologics. PMDA-aligned quality frameworks govern biosimilar approval pathways with distinct reference product requirements. The Kanto region hosts contract development organizations specializing in glycoengineering for defined glycosylation profiles.
Switzerland
Swissmedic regulatory frameworks support early access programs for breakthrough immunotherapies. Basel and Zurich anchor biologics manufacturing with integrated chemical and biological production campuses. The country's bilateral agreements with the EU facilitate streamlined market access despite non-membership status.
India
CDSCO regulatory evolution and PLI scheme incentives attract biologics manufacturing investment for export markets. Mumbai-Pune and Hyderabad clusters develop biosimilar capabilities with cost-competitive mammalian cell culture infrastructure. Domestic demand for rheumatology and diabetes immunomodulators expands with urban hospital network consolidation.
Global Autoimmune Disease Therapeutics Market Competitive Landscape
United States-based pharmaceutical conglomerates anchor one tier; Swiss and German specialists hold differentiated positions in biologics manufacturing. The market structure concentrates revenue among ten to fifteen entities with diversified immunology portfolios. Three archetypes dominate: diversified biopharmaceutical conglomerates with manufacturing scale, immunology-focused mid-cap specialists with deep R&D pipelines, and emerging biosimilar developers with cost-optimized production. Capacity expansion through bioreactor train additions and strategic partnerships for co-development of bispecific antibodies represent the dominant competitive moves.
Within the diversified conglomerate tier, Pfizer, Bristol-Myers Squibb, and Eli Lilly and Company exemplify scale-driven positioning across multiple autoimmune indications. These entities occupy positions defined by manufacturing infrastructure breadth and therapeutic area diversification rather than single-product concentration. Their competitive posture reflects procurement power consolidation among United States hospital systems and integrated delivery networks demanding outcome guarantees and volume-based contracting structures.
| Leading Market Players |
|---|
| Merck |
| Bristol-Myers Squibb |
| Pfizer |
| F. Hoffmann-La Roche |
| Amgen |
| Novartis |
| Sanofi |
| Eli Lilly and Company |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Glycoengineering specialists concentrated in the Boston-Cambridge corridor and Basel region command wage premiums that compress margins for standard-tier biologics while sustaining premium pricing for defined glycosylation profiles. Labor-cost differentials between these talent clusters and emerging CDO hubs in India widen the spread between premium originator and economy biosimilar tiers.
Pricing Analysis
Volume concentrates in subcutaneous formats while margins cling to intravenous biologics with complex glycosylation requirements. Three-tier pricing structure across premium originator, standard biosimilar, and economy non-glycoengineered levels reflects FDA breakthrough designation status and REACH compliance certification. Cost compression in the standard tier intensifies because integrated delivery networks demand outcome guarantees. Price-sensitive independent rheumatology practices drive substitution toward oral JAK inhibitors where clinical equivalence permits.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States hospital systems and European integrated delivery networks force qualification of backup mammalian cell culture facilities. Supply concentrates in the United States, Ireland, and Switzerland for bioreactor capacity, with Germany and Japan anchoring fill-finish capabilities. Raw material dependencies span recombinant protein media, single-use bioreactor bags, and defined glycosylation enzymes. Single-source vulnerability clusters in the Boston-Ireland corridor for novel bispecific constructs. Distribution runs through United States specialty pharmacy networks and European hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA pharmacovigilance obligations and REACH excipient restrictions erect barrier-to-entry moats favoring manufacturers with pre-qualified European manufacturing footprints.
For Market Incumbents: Deploy glycoengineering talent retention programs to defend against CDO poaching in the Basel and Boston corridors. Lock in long-term bioreactor capacity reservations in Ireland and Switzerland before qualification timelines extend further. Consolidate procurement relationships with the three dominant United States pharmacy benefit managers to secure formulary placement against oral JAK substitution. For New Entrants and Emerging Players: Specialty pharmacy direct-to-patient networks offer the most penetrable channel for biosimilar entrants lacking hospital system relationships. Target Japan's aging rheumatology market where PMDA-aligned quality frameworks favor manufacturers with documented glycosylation consistency. Pursue home infusion service partnerships to bypass saturated ambulatory care center access. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap immunology specialists possessing FDA breakthrough therapy designations and EU AI Act-compliant biomarker infrastructure given accelerated approval pathway expansion. Acquisition focus should center on CDOs with captive glycoengineering talent pools in the Kanto region. Watch FDA breakthrough therapy designation velocity as the inflection indicator for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Qualification in Switzerland and Ireland hedges against REACH timeline extensions for European supply security. |
| Bispecific Antibody Pipeline Advancement | Dual-target cytokine blockade commands premium pricing in refractory lupus within consolidated United States hospital systems. |
| Subcutaneous Formulation Development | Self-administration devices reduce infusion center dependency and expand rural patient capture through specialty pharmacy networks. |
| EU AI Act Compliance Investment | Predictive biomarker algorithms for patient stratification differentiate portfolios in European health technology assessments. |
| Japan PMDA Biosimilar Registration | Aging demographics and distinct reference product requirements reward early entrants with established glycosylation documentation. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors at United States pharmacy benefit managers, and hospital procurement managers underwrites the qualitative findings. Secondary validation draws from FDA breakthrough therapy designation filings, EMA pharmacovigilance submissions, ClinicalTrials.gov immunology trial registries, and formulary database audits. Bottom-up patient population sizing and top-down manufacturer revenue triangulation anchor the quantitative framework.
Comparable-period anchoring to historical biologic launch trajectories and biosimilar erosion curves shapes the projection horizon. Segmentation dimensions span product type, therapy area, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derive from patient population epidemiology, pricing elasticity assumptions, and therapy-line progression rates. Forecast inputs incorporate bioreactor capacity utilization rates and specialty pharmacy network expansion trajectories.
Caveats apply where FDA breakthrough therapy designation criteria tightening, EMA GDPR constraints on real-world evidence, or bioreactor single-source disruption could materially shift the outlook. Deviation in integrated delivery network procurement consolidation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market