
 Veterinary Services Market | 2026-2036
Veterinary Services Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Services Market Analysis
Telemedicine integration into clinical workflows is fragmenting traditional service delivery models across veterinary practices. Mars Inc. leverages its multi-brand hospital network to sustain geographic density in North American metropolitan markets. IDEXX Laboratories anchors diagnostic technology leadership through in-clinic laboratory platforms and reference laboratory services. IVC Evidensia competes across European veterinary consolidator markets with standardized operational protocols.
Veterinary services encompass medical, surgical, and preventive care delivered by licensed practitioners to companion, production, and exotic animals, incorporating diagnostic imaging, laboratory analysis, anesthesia protocols, and pharmaceutical administration to maintain animal health and public health zoonotic controls. General practice constitutes the volume base while surgical services and emergency care command premium fee structures due to specialized equipment and staffing requirements. Telemedicine within the delivery mode dimension is expanding fastest as state boards revise practice acts, though in-clinic care retains dominance for procedures requiring physical examination and intervention.
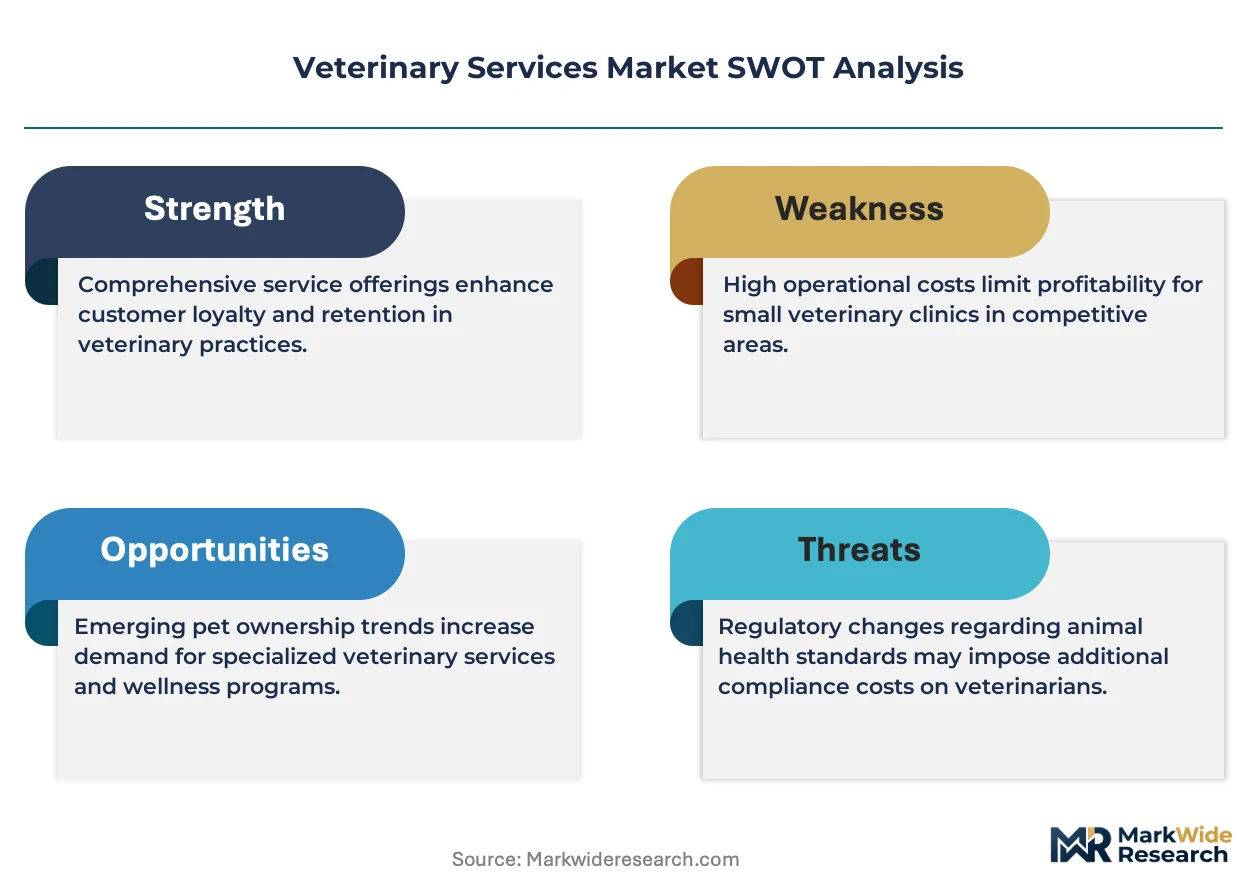
The FDA Center for Veterinary Medicine regulates veterinary pharmaceuticals and medicated feeds, while USDA APHIS oversees interstate health certificates and disease eradication programs that shape service documentation requirements. State veterinary medical boards govern scope-of-practice rules that directly determine whether telemedicine, mobile services, or home visits operate under valid veterinarian-client-patient relationships. Stakeholders must monitor evolving state-level telehealth legislation and DEA controlled substance prescribing rules as these frameworks determine competitive positioning between digital-first platforms and brick-and-mortar establishments.
Market Dynamics
Telemedicine platform adoption is fragmenting traditional clinic-centric service delivery, forcing brick-and-mortar operators to reconfigure physical infrastructure and staffing models around hybrid care workflows.
Growth Catalysts
- State telehealth legislation:Veterinary medical boards across the United States are revising practice acts to permit remote consultations, expanding addressable service reach beyond clinic catchment areas.
- Companion animal humanization:Pet owners now allocate discretionary spending toward preventive diagnostics and specialty referrals previously reserved for production animal portfolios.
- Point-of-care diagnostics:In-clinic laboratory platforms compress turnaround times for blood chemistry and immunoassay testing, driving visit frequency and compliance adherence.
Market Restraints
- Veterinarian supply constraint:Accredited DVM program output limits workforce expansion, creating appointment scarcity that caps service volume growth in metropolitan clusters.
- DEA controlled substance rules:Federal prescribing restrictions on opioids and anesthetics complicate telemedicine protocols, requiring in-person examinations for script authorization.
- Real estate cost escalation:Urban commercial lease rates for specialty surgical centers absorb margin expansion, particularly in coastal United States markets.
Strategic Opportunities
- Mobile veterinary units:Deploying equipped vehicles for home euthanasia and wellness examinations captures aging pet owner demographics unwilling to transport animals.
- USDA APHIS export certification:Expanding accredited veterinarian networks for international health documentation serves commercial breeding and companion animal relocation demand.
- AI-assisted radiography:Machine learning algorithms integrated with digital imaging systems enable general practitioners to flag orthopedic and thoracic abnormalities without specialist referral.
Industry Challenges
- Specialist credentialing pipelines:Residency positions in surgery, oncology, and cardiology remain insufficient to match referral case growth, creating access bottlenecks.
- Legacy practice management software:Outdated electronic health record systems resist interoperability with telemedicine platforms and client-facing mobile applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Services Market |
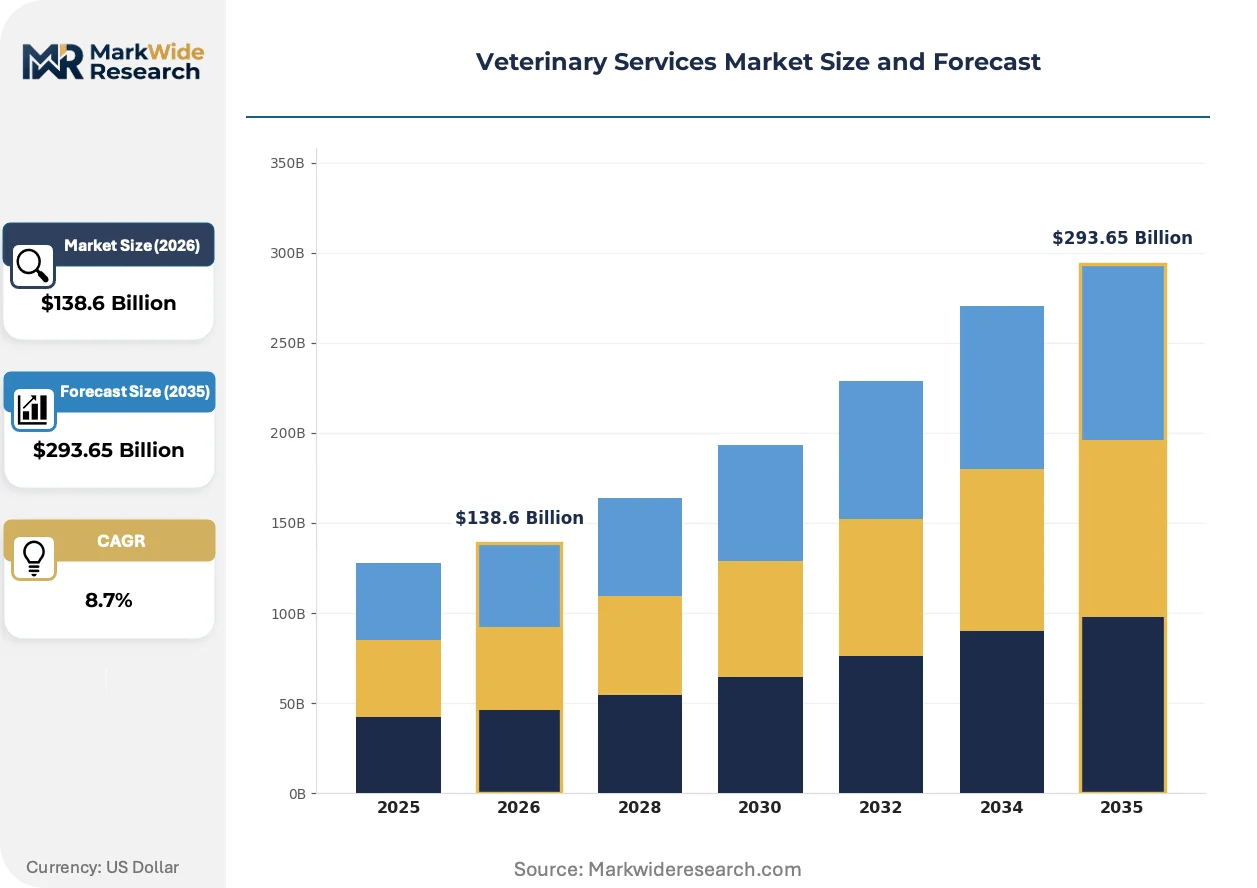
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $293.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: General Practice, Surgical Services, Emergency Care, Nutritional Counseling Animal Type: Dogs, Cats, Horses, Exotic Animals Delivery Mode: In-clinic, Mobile Services, Telemedicine, Home Visits Care Setting: Private Clinics, Animal Hospitals, Shelters, Research Institutions |
| Companies Covered | Mars Inc., National Veterinary Associates, CVS Group PLC, IVC Evidensia, VetPartners, Ethos Veterinary Health, Greencross Vets, Pets at Home Group PLC, IDEXX Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Services Market Emerging Trajectories
Diagnostic automation and client-facing digital interfaces are compressing traditional service hierarchies, enabling general practitioners to retain cases previously escalated to specialty networks.
Artificial intelligence is digitizing radiographic interpretation workflows, with convolutional neural networks flagging pulmonary patterns and skeletal lesions for generalist review. Small animal clinics in suburban United States markets are deploying these tools to reduce specialist referral dependency. The technology is digitizing diagnostic gatekeeping functions, compressing the traditional hierarchy where imaging interpretation resided exclusively with boarded radiologists.
The FDA Center for Veterinary Medicine has tightened adverse event reporting requirements for compounded medications, elevating documentation burdens for telemedicine platforms prescribing customized formulations. Compounding pharmacies serving digital-first veterinary networks must now implement batch tracking systems that mirror human pharmaceutical standards. Telemedicine operators in California and Texas are responding by restricting formulary offerings to commercially manufactured products with established safety profiles.
Subscription-based wellness plans are displacing fee-for-service billing in companion animal general practice, with monthly debits bundling examinations, vaccines, and laboratory screening. Corporate consolidators and independent practices alike are migrating toward this model to smooth revenue volatility and lock client retention. The shift is most pronounced in United States metropolitan markets where pet insurance penetration exceeds fifteen percent and owners demonstrate willingness to prepay for predictable care costs.
Veterinary Services Market Segmentation
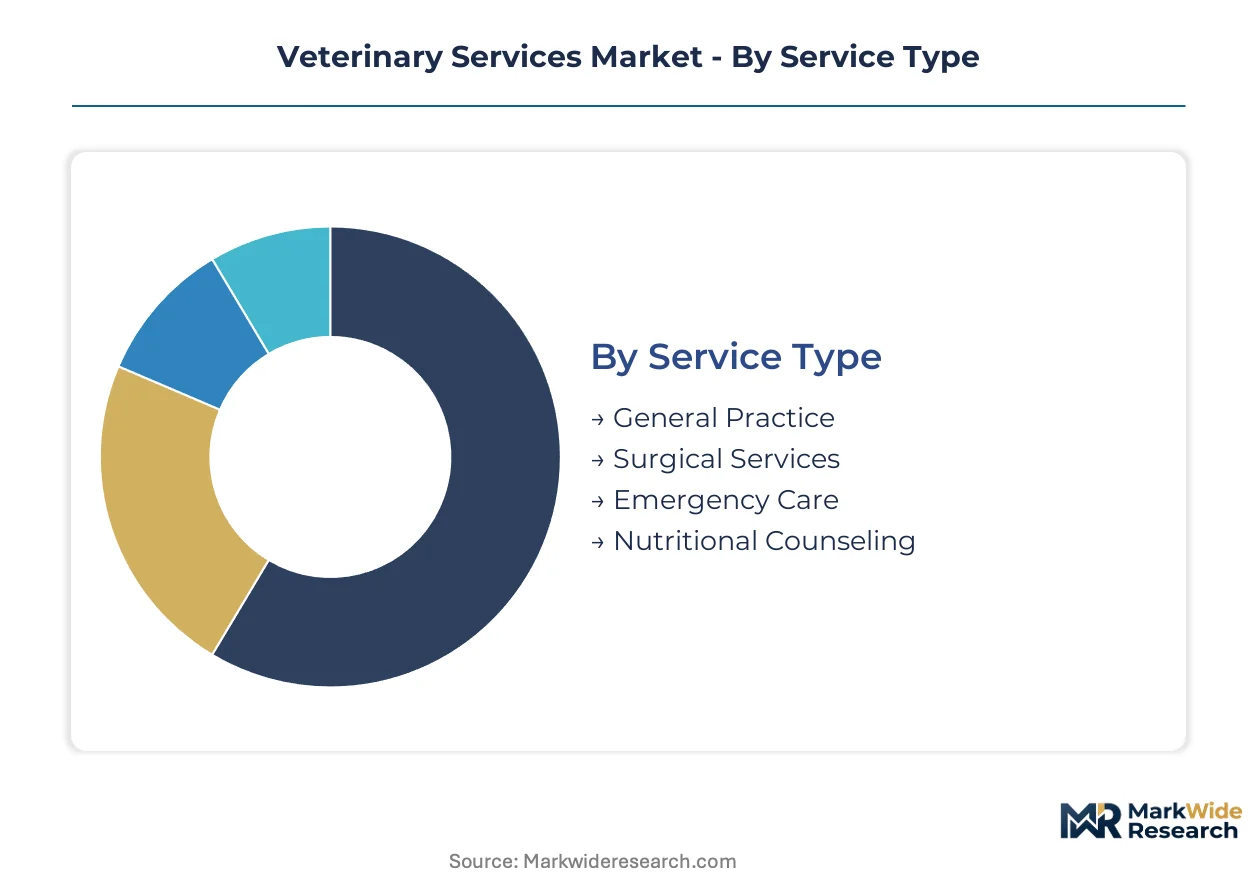
Veterinary services fragment across four distinct dimensions that determine pricing power, capital intensity, and regulatory exposure. Service type and delivery mode classifications now dominate strategic planning as consolidators optimize portfolio mix and independent practices defend referral relationships.
Service Type:
Cost tier structures the veterinary services landscape, with fee schedules scaling dramatically from preventive wellness to complex surgical intervention.
- General Practice:Routine examinations, vaccinations, and minor medical interventions form the volume foundation of veterinary service delivery. Demand concentrates in suburban United States markets where pet insurance penetration exceeds fifteen percent and wellness plan subscriptions smooth revenue predictability.
- Surgical Services:Orthopedic repairs, soft tissue procedures, and neurosurgical interventions require specialized equipment and boarded practitioner credentials. Metropolitan clusters in California and Texas absorb premium pricing for TPLO cruciate repairs and oncological resections as specialist credentialing bottlenecks limit supply expansion.
- Emergency Care:After-hours critical stabilization and trauma management commands the highest fee multiples in veterinary medicine.
- Nutritional Counseling:Therapeutic diet formulation and obesity management protocols support chronic disease management in aging companion animal populations.
General Practice holds installed capacity. Surgical Services is rotating up the share rankings.
Animal Type:
Customer type determines service intensity and payment modality across the veterinary market.
- Dogs:Canine patients generate the highest per-capita service expenditure through orthopedic surgery, oncology protocols, and cardiac interventions. Urban United States households drive demand for breed-specific genetic screening and preventive dental programs.
- Cats:Feline patients present diagnostic challenges due to stress-induced masking of clinical signs, elevating reliance on laboratory screening and imaging. Suburban practices report climbing visit frequency as indoor cat longevity extends and owners accept chronic disease management costs.
- Horses:Equine veterinary services concentrate in Kentucky, Florida, and California racing circuits with mobile radiography and reproductive services dominating.
- Exotic Animals:Avian, reptile, and small mammal care requires specialized anesthesia protocols and husbandry expertise.
Dogs command revenue concentration. Cats are expanding most quickly in visit volume.
Delivery Mode:
Application context shapes infrastructure investment and regulatory compliance requirements for veterinary service providers.
- In-clinic:Traditional brick-and-mortar facilities retain dominance for surgical procedures, diagnostic imaging, and controlled substance administration. United States metropolitan markets absorb escalating real estate costs as corporate consolidators pursue geographic density strategies.
- Telemedicine:Remote consultation platforms expand addressable reach beyond physical catchment areas, constrained by DEA prescribing rules and state veterinary board practice act variations. California and Texas lead state-level regulatory accommodation for digital-first service models.
- Mobile Services:Equipped veterinary vehicles capture home euthanasia and wellness examination demand from aging pet owner demographics.
- Home Visits:House call practices serve multi-pet households and mobility-limited clients with personalized care delivery.
In-clinic maintains procedure dominance. Telemedicine is climbing the fastest in platform investment.
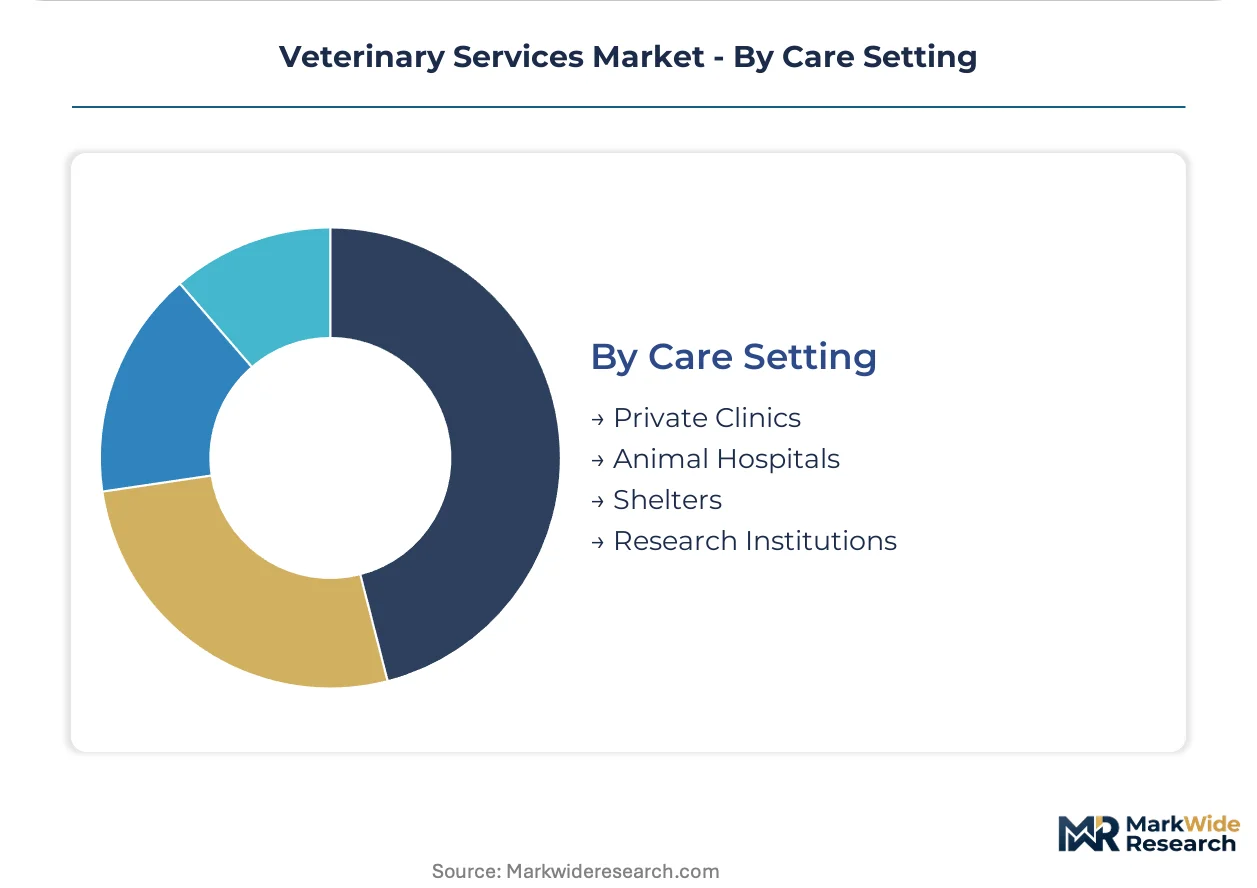
Care Setting:
Supply concentration varies across institutional categories with divergent capital requirements and client acquisition economics.
- Private Clinics:Independent owner-operator practices retain significant share in rural United States markets and specialty niches, though consolidation pressure intensifies.
- Animal Hospitals:Multi-doctor facilities with in-house laboratory and imaging capabilities capture complex medical and surgical cases. Corporate chains in Florida and New York deploy standardized protocols across metropolitan networks.
- Shelters:Municipal and nonprofit facilities provide subsidized sterilization and vaccination services with veterinary staffing supported by tax revenue and donation streams.
- Research Institutions:Academic veterinary medical centers combine clinical service with residency training and investigational trials.
Animal Hospitals hold capacity concentration. Private Clinics are gaining share fastest in specialty retreatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification demand for companion animal relocation and commercial breeding operations is reshaping veterinary service requirements across major economies. Trade documentation standards now dictate service specialization in key markets. Regulatory divergence between jurisdictions is fragmenting cross-border service protocols.
United States
Pet insurance penetration exceeding fifteen percent in metropolitan clusters is driving preventive service intensity. The FDA Center for Veterinary Medicine enforces pharmaceutical safety standards that shape clinic protocols. California and Texas lead state-level telehealth regulatory accommodation, with corporate consolidators deploying standardized operational frameworks across these catchment areas.
Germany
Equine veterinary demand concentrates in Baden-Württemberg and Lower Saxony racing circuits with mobile diagnostic services. The Federal Ministry of Food and Agriculture oversees animal welfare compliance standards that elevate documentation burdens. Munich and Hamburg anchor specialty referral networks where boarded practitioners command premium fee structures for orthopedic and oncological interventions.
United Kingdom
Corporate consolidation pressure is intensifying across England's suburban veterinary networks as subscription wellness plans displace fee-for-service billing. The Royal College of Veterinary Surgeons governs telemedicine scope-of-practice rules that constrain remote consultation expansion. Greater London and Manchester metropolitan areas absorb escalating real estate costs for multi-doctor hospital facilities.
Japan
Aging companion animal populations in Tokyo and Osaka metropolitan corridors are elevating chronic disease management service demand. The Ministry of Agriculture, Forestry and Fisheries regulates animal quarantine protocols for international health documentation. Kanto region specialty centers are integrating AI-assisted radiography platforms to reduce specialist referral dependency for thoracic and orthopedic imaging.
Australia
Home euthanasia and mobile wellness examination demand is climbing among aging pet owner demographics in Sydney and Melbourne. The Department of Agriculture, Fisheries and Forestry administers export certification requirements for commercial breeding operations. Queensland and Victoria are witnessing expanded accredited veterinarian networks serving international companion animal relocation corridors.
Veterinary Services Market Vendor Landscape
On the supply side, the industry is consolidating around corporate hospital networks and diagnostic technology platforms. Independent owner-operator practices retain significant share in rural catchments, though acquisition pressure intensifies. Three archetypes dominate: multi-brand hospital consolidators, diagnostic technology specialists, and regional veterinary group operators. M&A activity and geographic density strategies represent the primary competitive vectors as players vie for metropolitan market positioning.
Within the consolidator tier, Mars Inc. and IVC Evidensia exemplify multi-brand hospital network operators. IDEXX Laboratories anchors the diagnostic technology segment. CVS Group PLC represents the European veterinary group archetype. These entities occupy positions defined by geographic concentration strategies and standardized operational protocol deployment across metropolitan clusters.
| Leading Market Players |
|---|
| Mars Inc. |
| National Veterinary Associates |
| CVS Group PLC |
| IVC Evidensia |
| VetPartners |
| Ethos Veterinary Health |
| Greencross Vets |
| Pets at Home Group PLC |
| IDEXX Laboratories |
| Others |
Supply Flow & Price Mechanics
California's metropolitan veterinary clusters anchor premium fee structures through specialist credential scarcity and concentrated corporate ownership. The state's surgical specialty centers in Los Angeles and San Francisco absorb escalating real estate costs while commanding fee multiples for orthopedic and oncological interventions that suburban general practices cannot match.
Pricing Analysis
Next-generation AI-assisted diagnostic platforms command subscription premiums over legacy fee-for-service billing, while traditional wellness examination pricing faces compression from corporate wellness plan standardization. Three-tier pricing structure across premium specialty referral, standard general practice, and economy shelter-subsidized tiers stratifies by equipment intensity and practitioner certification level. Pricing pressure stems from telemedicine platform entry into routine consultation markets with lower overhead structures. Corporate consolidators demonstrate lowest price sensitivity due to scale purchasing power, while independent rural practices face acute margin compression from fixed cost absorption.
Supply Chain Analysis
Upstream pharmaceutical and diagnostic equipment sourcing concentrates manufacturing in the United States, Germany, and Switzerland for precision instrumentation, with China supplying consumable laboratory reagents and generic pharmaceutical formulations. Critical dependencies include DEA-scheduled controlled substances for anesthesia protocols, ISO-certified surgical implants, and FDA-validated in-clinic assay platforms. Single-source vulnerability runs through reference laboratory networks where IDEXX and Zoetis anchor national specimen processing capacity. Distribution runs through corporate procurement consortia serving multi-hospital networks, with independent practices accessing veterinary-exclusive distributors such as MWI Animal Health and Patterson Veterinary.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary service fragmentation creates white-space opportunities as telemedicine adoption and specialty credentialing bottlenecks simultaneously expand addressable niches and constrain incumbent capacity. Companion animal humanization generates demand micro-segments around geriatric chronic disease management and preventive genetic screening that unified corporate protocols cannot efficiently serve.
For Market Incumbents: Pre-empt telemedicine platform encroachment by embedding remote consultation workflows into existing client relationships before digital-first entrants capture routine case triage. Acquire accredited mobile veterinary units in aging suburban corridors to defend against home euthanasia and wellness examination specialists. Vertical integration into reference laboratory services locks diagnostic revenue and creates switching costs for referring general practitioners.
For New Entrants and Emerging Players: Build out USDA APHIS export certification capabilities in Queensland and Victoria corridors serving international companion animal relocation demand, where accredited veterinarian networks remain underdeveloped relative to breeding operation growth. Target mobile surgical sterilization units for municipal shelter contracts, leveraging lower overhead structures against fixed-location hospital bids. Deploy direct-to-consumer subscription wellness plans in pet insurance-penetrated metropolitan markets to bypass incumbent client acquisition barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic platform operators and specialty hospital consolidators over general practice roll-ups facing telemedicine disintermediation. Long-term viability hinges on regulatory accommodation for remote prescribing and AI-assisted diagnosis expansion. Acquisition target archetype: multi-site specialty surgical centers in California and Texas with boarded practitioner employment contracts. The signal to watch is state veterinary medical board telehealth legislation velocity as inflection indicator for digital-first platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Hybrid care workflows retain clients against digital-first entrants in California and Texas markets. |
| AI-Assisted Diagnostic Deployment | Convolutional neural networks reduce specialist referral dependency for thoracic and orthopedic imaging interpretation. |
| Mobile Service Unit Expansion | Equipped vehicles capture home euthanasia demand from aging pet owner demographics unwilling to transport animals. |
| Reference Laboratory Acquisition | In-house diagnostic capacity locks revenue and creates switching costs for referring general practitioners. |
| Subscription Wellness Plan Migration | Monthly debits smooth revenue volatility and improve client retention in pet insurance-penetrated metropolitan clusters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine adverse event databases, state veterinary medical board practice act compilations, and corporate SEC filings. Veterinary practice owners, specialty hospital medical directors, telemedicine platform operators, and pharmaceutical regulatory affairs specialists provided operational validation. Secondary sources included USDA APHIS interstate health certificate documentation standards, pet insurance penetration studies, and veterinary school enrollment statistics. Bottom-up service volume estimates triangulated against top-down expenditure projections from national companion animal ownership surveys.
Forecast inputs encompass service type segmentation across general practice, surgical services, emergency care, and nutritional counseling dimensions, intersected with delivery mode categories of in-clinic, telemedicine, mobile, and home visit. Animal type splits for canine, feline, equine, and exotic patient populations modeled separately. Care setting differentiation between private clinics, animal hospitals, shelters, and research institutions informed capacity utilization assumptions. CAGRs derived from regression analysis against macroeconomic indicators and demographic pet ownership trends without year-specific anchoring.
The forecast holds incumbent behavior within observed patterns; aggressive consolidation moves by Mars Inc. or IVC Evidensia would shift competitive dynamics and service pricing trajectories. Telemedicine regulatory acceleration or DEA controlled substance prescribing relaxation would revise platform adoption curves and specialty referral volume assumptions. Cross-checking against American Veterinary Medical Association membership and practice ownership surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Topical Drugs CDMO Market
Healthcare
Bone Metabolism Test Market
Healthcare
Compression Stockings Market
Healthcare
Cognitive and Memory Enhancer Drugs Market
Healthcare
Tissue Banking Market
Healthcare
Musculoskeletal System Disorders Market
Healthcare
Endometrial Cancer Treatment Market
Healthcare
US Wound Irrigation System Market
Healthcare
Interatrial Shunt Market
Healthcare
Mexico Hemp CBD Market
Healthcare
Oral Solid Dosage Contract Manufacturing Market
Healthcare
Global Dermatoscope Market
Healthcare
Vascular Guidewires Market
Healthcare
Prosthetic Disc Nucleus Market
Healthcare
Drug Free Depression Treatment Market
Healthcare
Pharmacy and Drug Store Franchises Market