
 Orthopedic Splints and Casts Market | 2026-2036
Orthopedic Splints and Casts Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Splints and Casts Market Insights
ISO 13485 certification is rotating as the primary gating mechanism for manufacturers seeking entry into the orthopedic immobilization sector. Stryker Corporation leverages its integrated hospital supply chain to sustain premium positioning across acute care settings. DJO Global anchors its competitive stance through specialized rehabilitation-focused distribution channels.
Orthopedic splints and casts are external immobilization devices fabricated from fiberglass, plaster, thermoplastic, or composite substrates, designed to stabilize bone fractures and soft tissue injuries through controlled load distribution and motion restriction. Fiberglass and thermoplastic segments command expanding share due to their radiolucency, water resistance, and reduced application weight compared to conventional plaster. Soft splints occupy a growing niche in home care and preventative applications where patient comfort and removability drive preference over rigid alternatives.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) establish divergent compliance burdens that fragment market access strategies between North American and European commercial teams. The EPA's oversight of volatile organic compound emissions during fiberglass resin curing further constrains domestic manufacturing economics. Stakeholders must monitor how evolving biocompatibility testing standards and sustainability mandates reshape material selection and supplier qualification timelines.
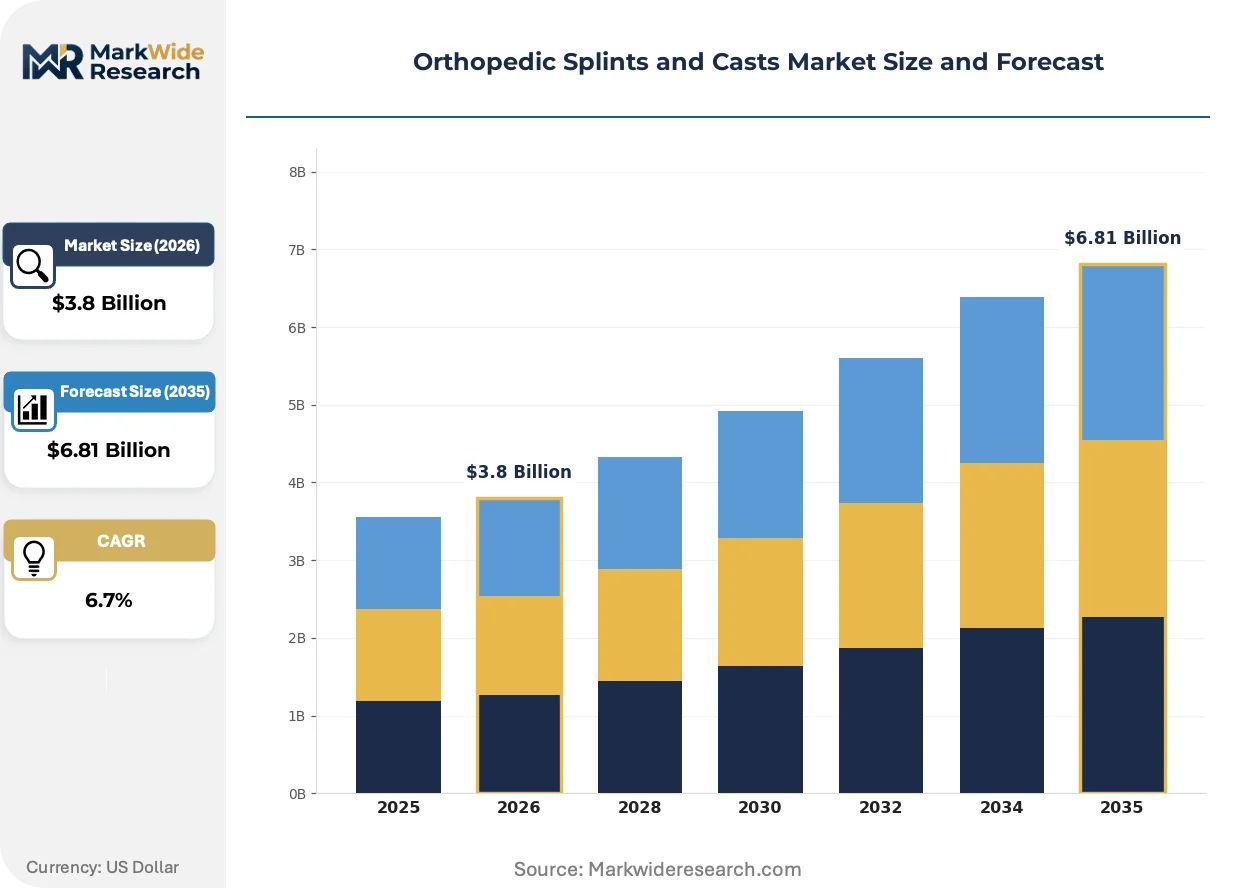
Market Dynamics
Hospital procurement departments are consolidating supplier relationships around ISO 13485-certified manufacturers capable of delivering radiolucent, waterproof immobilization systems that reduce cast room turnaround times and eliminate plaster-related supply chain complexity.
Growth Catalysts
- Fiberglass substrate penetration:Acute care facilities in the United States are standardizing on fiberglass casting tape for its 50% weight reduction versus plaster and compatibility with MRI protocols. The material's faster application time compresses orthopedic clinic throughput constraints.
- 510(k) clearance pathway:The FDA's streamlined premarket notification framework for Class II medical devices accelerates manufacturer time-to-revenue for novel splint designs. This regulatory efficiency attracts venture-backed entrants targeting sports medicine segments.
- Thermoplastic demand in home care:Removable, washable thermoplastic splints are capturing preference among geriatric patients managing chronic conditions. The segment benefits from Medicare reimbursement alignment with ambulatory surgical center discharge protocols.
Market Restraints
- Resin input cost volatility:Epoxy and polyester resin prices fluctuate with petrochemical feedstock markets, compressing gross margins for fiberglass cast manufacturers during crude oil price spikes.
- Plaster supply concentration:Gypsum mining and processing for orthopedic plaster concentrates in a limited number of North American quarries, creating geographic supply risk during regional environmental compliance actions.
- Radiolucency technical ceiling:Conventional plaster formulations remain opaque to X-ray penetration, forcing repeat imaging and radiation exposure that fiberglass alternatives eliminate.
Strategic Opportunities
- Pediatric custom-molded segment:Underpenetrated demand exists for 3D-printed thermoplastic splints sized to anatomical variation in children. The application requires minimal FDA regulatory burden under existing 510(k) predicates.
- EU MDR biocompatibility tailwind:The European Medical Device Regulation's enhanced material testing requirements favor manufacturers with established ISO 10993 documentation, creating competitive moats against low-cost Asian exporters.
- Direct-to-patient e-commerce:Specialized orthopedic supply platforms are emerging as viable channels for soft splint and brace sales, bypassing traditional durable medical equipment distributor markups.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 cytotoxicity and sensitization testing extends product development cycles by 8-14 months for novel polymer formulations.
- Cast technician skill scarcity:Proper fiberglass and thermoplastic application requires specialized training that orthopedic residency programs have deprioritized in favor of operative techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Splints and Casts Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Splints, Soft Splints, Casts, Immobilizers Material: Fiberglass, Plaster, Thermoplastic, Composite End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Home Care Application: Fractures, Sprains, Post-Surgery, Preventative Care |
| Companies Covered | 3M Company, BSN Medical GmbH, DeRoyal Industries, Inc., DJO Global, Stryker Corporation, Zimmer Biomet Holdings, Inc., Össur hf., Prime Medical, Inc., Orfit Industries N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Splints and Casts Market Trends and Innovations
Material science advances and regulatory harmonization efforts are compressing the innovation cycle for external immobilization devices, while procurement centralization in integrated delivery networks reshapes how manufacturers access clinical decision-makers.
Thermoplastic copolymer splinting systems are displacing traditional plaster in emergency department fast-track protocols. These materials permit remolding during the acute inflammatory phase without complete cast removal. Major academic medical centers in the United States are adopting them for distal radius and pediatric forearm fractures, reducing unscheduled return visits by enabling in-clinic adjustments.
The EU Medical Device Regulation's substance disclosure requirements are forcing reformulation of fiberglass resin systems. Manufacturers must now document phthalate and bisphenol content across supply tiers. European orthopedic device distributors are qualifying alternative suppliers from Switzerland and Germany who pre-certify MDR technical documentation, compressing market access timelines for compliant products.
Hospital supply chain consolidation is eliminating independent cast room purchasing autonomy. Integrated delivery networks in the United States are mandating single-source contracts for immobilization supplies across 15-30 facility footprints. This concentration forces regional manufacturers to secure group purchasing organization membership or cede volume to Stryker and DJO Global's established contracting relationships.
Orthopedic Splints and Casts Market Segmentation
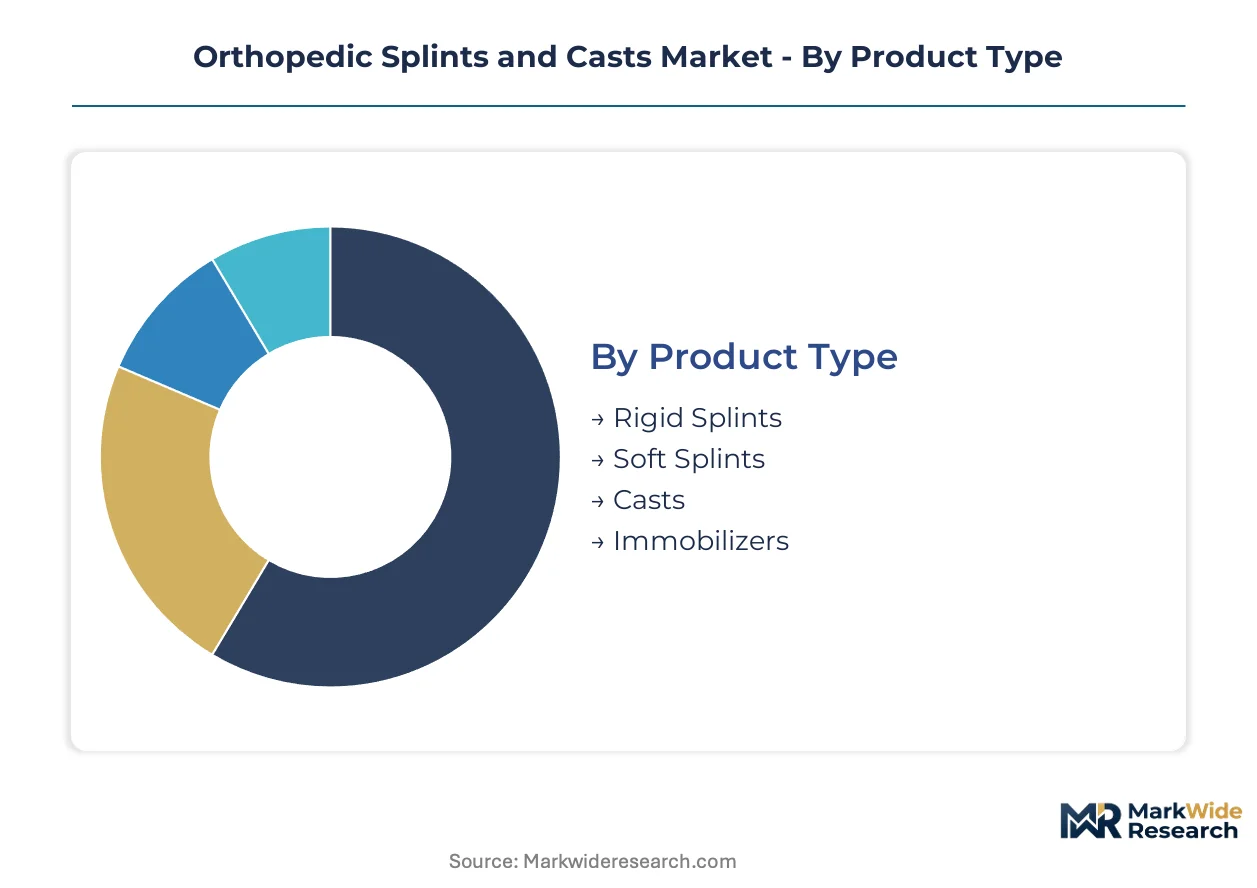
Orthopedic immobilization products fragment across material substrates, care settings, and injury severity levels. Procurement teams in acute care networks prioritize segments that compress cast room throughput while home care channels favor removability and patient self-management.
Product Type:
Fiberglass-based rigid splints dominate domestic hospital procurement in the United States, while thermoplastic variants drive export volume into European ambulatory care markets. Soft splint demand concentrates in direct-to-patient channels where Medicare Advantage plans subsidize home-based recovery.
- Rigid Splints:These devices incorporate fiberglass or aluminum substrates laminated to foam padding, delivering anatomical stabilization for acute fractures. Demand clusters in United States emergency departments where 50% weight reduction versus plaster accelerates patient discharge workflows.
- Soft Splints:Constructed from neoprene, foam, or elastic fabrics with adjustable strapping systems, these products permit removal for hygiene and rehabilitation exercises. German and Swiss rehabilitation centers are standardizing soft splints for chronic instability management where patient compliance determines outcomes.
- Casts:Circumferential immobilization systems fabricated from plaster or synthetic casting tape. Plaster formulations retain cost-sensitive volume in India and Brazil while synthetic alternatives capture share in Japanese orthopedic networks requiring MRI compatibility.
- Immobilizers:Prefabricated devices for shoulder, knee, and ankle stabilization requiring minimal customization. Australian sports medicine clinics deploy these for acute ligament injuries where immediate immobilization precedes definitive surgical planning.
Casts command the established base. The steepest expansion runs through soft splints.
Material:
Cost tier differentiation separates premium thermoplastic systems from economy plaster lines, with fiberglass occupying the volume midpoint where hospital procurement committees optimize total cost of ownership.
- Fiberglass:Woven glass fiber substrates impregnated with polyurethane resin, delivering radiolucency and water resistance. United States orthopedic clinics are eliminating plaster inventory entirely, converting cast rooms to fiberglass-only protocols that integrate with digital radiography workflows.
- Plaster:Gypsum-derived casting material requiring water activation and setting time. Indian government hospitals and rural Brazilian facilities maintain plaster procurement due to distributor availability and technician familiarity, though supply concentrates in limited North American quarries.
- Thermoplastic:Low-temperature moldable polymers that soften in hot water and rigidify at room temperature. French and German pediatric specialists prefer thermoplastic for growing patients requiring serial remolding, with Swiss manufacturers leading MDR-compliant formulation documentation.
- Composite:Hybrid substrates combining carbon fiber, fiberglass, or Kevlar with thermoset resins. Australian defense medical services and United States veterans affairs systems specify composites for high-activity patients where cast durability determines return-to-duty timelines.
Fiberglass anchors volume procurement. Thermoplastic climbs the fastest through pediatric and sports medicine channels.
End User:
Customer type segmentation reveals divergent purchasing authority: hospitals centralize through supply chain committees while home care channels fragment across durable medical equipment retailers and direct-to-patient platforms.
- Hospitals:Acute care facilities with cast rooms, emergency departments, and orthopedic surgery units. Integrated delivery networks in Texas, California, and Florida are consolidating immobilization contracts across 20-30 facility footprints, eliminating independent cast room purchasing autonomy.
- Orthopedic Clinics:Ambulatory specialty practices focused on fracture management and sports medicine. Independent clinics in Germany and Switzerland maintain direct supplier relationships for custom-molded thermoplastic systems that differentiate patient experience.
- Rehabilitation Centers:Post-acute facilities managing recovery from orthopedic surgery or neurological conditions. Medicare reimbursement alignment with discharge protocols drives soft splint volume in United States skilled nursing facilities.
- Home Care:Patient-directed purchasing for chronic condition management and post-operative recovery. Australian and United Kingdom consumers are accessing specialized orthopedic supply platforms that bypass traditional distributor markups for removable splint systems.
Hospitals command the established base. Home care gains share fastest through e-commerce channel development.
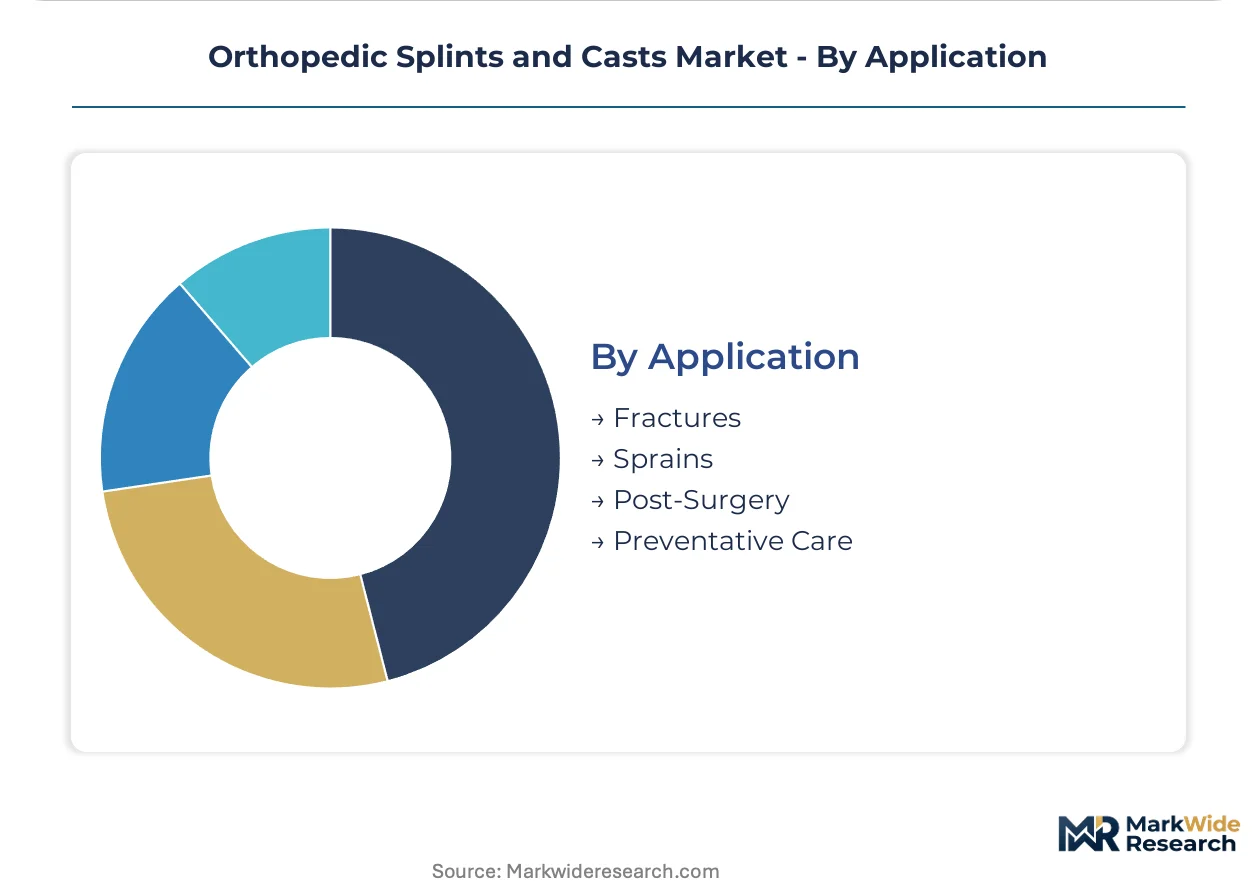
Application:
Maturity curves separate well-established fracture management from emerging preventative applications where clinical evidence and reimbursement alignment remain incomplete.
- Fractures:Acute bone disruption requiring anatomical reduction and stabilization. United States trauma centers are standardizing fiberglass casting tape for distal radius and ankle fractures, with application time compression driving protocol adoption.
- Sprains:Ligamentous injury without osseous involvement, typically managed with removable support. German sports medicine practices combine thermoplastic splinting with early mobilization protocols for ankle and wrist sprains, reducing long-term instability incidence.
- Post-Surgery:Immobilization following orthopedic operative intervention. Ambulatory surgical center discharge protocols in Florida and Arizona are mandating waterproof casting systems that permit showering without wound contamination risk.
- Preventative Care:Prophylactic immobilization for high-risk populations including diabetic neuropathy patients and competitive athletes. Clinical evidence gaps and reimbursement uncertainty constrain United States volume, though Australian private insurers are piloting coverage for offloading splints in diabetic foot management.
Fracture applications anchor the revenue base. Preventative care represents the fastest-growing trajectory as evidence accumulates for diabetic and sports prophylaxis indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 510(k) clearance pathway attracts venture-backed entrants targeting United States sports medicine segments, while EU MDR substance disclosure requirements force reformulation of fiberglass resin systems across European supply chains.
United States
Hospital procurement departments in Texas, California, and Florida are consolidating immobilization contracts across 20-30 facility footprints. The FDA's streamlined premarket notification framework accelerates manufacturer time-to-revenue for novel splint designs. Academic medical centers in Boston and Stanford are adopting thermoplastic copolymer systems for distal radius and pediatric forearm fractures.
Germany
Independent orthopedic clinics maintain direct supplier relationships for custom-molded thermoplastic systems that differentiate patient experience. The EU Medical Device Regulation's enhanced material testing requirements favor manufacturers with established ISO 10993 documentation. Industrial clusters in Bavaria and Baden-Württemberg host Swiss-qualified suppliers who pre-certify MDR technical documentation.
Switzerland
Pediatric specialists prefer thermoplastic for growing patients requiring serial remolding. Swissmedic oversees device registration alongside EU MDR alignment for market access. Basel and Zurich manufacturing corridors lead MDR-compliant formulation documentation for export into German and French ambulatory care markets.
Australia
Sports medicine clinics deploy prefabricated immobilizers for acute ligament injuries where immediate stabilization precedes definitive surgical planning. The Therapeutic Goods Administration (TGA) regulates device safety while private insurers pilot coverage for offloading splints in diabetic foot management. Sydney and Melbourne rehabilitation centers are standardizing soft splints for chronic instability management.
Japan
Orthopedic networks require MRI-compatible synthetic casting alternatives for aging demographics with complex fracture patterns. The Pharmaceuticals and Medical Devices Agency (PMDA) maintains stringent biocompatibility standards that extend certification timelines. Osaka and Nagoya medical device clusters concentrate import distribution for fiberglass and thermoplastic systems.
Orthopedic Splints and Casts Market Competitive Landscape
Listed leaders compete with private specialists across acute care supply chain integration. Stryker Corporation and Zimmer Biomet Holdings anchor the publicly traded tier with integrated hospital contracting networks, while DeRoyal Industries and Prime Medical occupy private specialist positions in regional distribution. Three archetypes define competitive positioning: diversified orthopedic conglomerates with GPO relationships, rehabilitation-focused device specialists, and regional fabricators with custom-molding capabilities. M&A activity concentrates on ISO 13485-certified manufacturers with established 510(k) predicate libraries, while strategic partnerships target e-commerce channel development for home care segments.
Among diversified orthopedic conglomerates, Stryker Corporation exemplifies the acute care supply chain archetype through its integrated hospital relationships. DJO Global occupies a position within the rehabilitation-focused specialist tier, anchoring competitive stance through dedicated distribution channels for post-acute settings. BSN Medical GmbH represents the European manufacturing archetype with MDR-compliant formulation capabilities. 3M Company sits within the materials science tier, leveraging substrate innovation across medical and industrial applications. Össur hf. exemplifies the sports medicine specialist position with focused positioning in ambulatory and athletic segments.
| Leading Market Players |
|---|
| 3M Company |
| BSN Medical GmbH |
| DeRoyal Industries, Inc. |
| DJO Global |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Össur hf. |
| Prime Medical, Inc. |
| Orfit Industries N.V. |
| Others |
Pricing and Supply Chain Analysis
Long-term group purchasing organization contracts lock in supply access and price visibility for ISO 13485-certified manufacturers serving United States integrated delivery networks. These multi-year agreements eliminate spot market exposure for fiberglass casting tape while binding procurement committees to single-source fulfillment across 20-30 facility footprints.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers in this market. FDA 510(k)-cleared products command 15-25% premiums over CE-marked equivalents in United States acute care channels, while economy plaster lines retain cost-sensitive volume in Indian government hospitals. Pricing pressure stems from resin input cost volatility tied to petrochemical feedstock markets, compressing gross margins for fiberglass manufacturers during crude oil spikes. Hospital procurement committees exhibit highest price sensitivity for commoditized plaster inventory, whereas orthopedic clinics demonstrate lowest sensitivity for custom-molded thermoplastic systems that differentiate patient throughput.
Supply Chain Analysis
China and South Korea anchor woven glass fiber substrate production for global fiberglass casting tape manufacturers. United States and German facilities draw from Asian fiber imports while adding polyurethane resin impregnation and final sterilization packaging. Single-source vulnerability concentrates in North American gypsum quarries supplying orthopedic plaster, creating geographic supply risk during regional environmental compliance actions. Distribution runs through group purchasing organization networks in United States acute care, direct supplier relationships in German ambulatory clinics, and emerging e-commerce platforms for Australian home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-era orthopedic procedure deferrals, with procedure volume normalization driving cyclical demand restoration for immobilization products.
For Market Incumbents: Secure group purchasing organization contract renewals ahead of 510(k) predicate library expansion by venture-backed entrants. Deepen backward integration into resin formulation capabilities to defend margin position against petrochemical feedstock volatility. Prioritize ISO 10993 biocompatibility documentation investment to maintain competitive moats under evolving EU MDR substance disclosure requirements. For New Entrants and Emerging Players: FDA 510(k) clearance fast-track offers the most penetrable regulatory pathway for novel splint designs targeting United States sports medicine segments. White-space exists in pediatric custom-molded thermoplastic applications where anatomical variation demands specialized sizing. Direct-to-patient e-commerce channels bypass traditional durable medical equipment distributor markups for soft splint sales in Australian and United Kingdom markets. For Investors and Strategic Acquirers: ISO 13485-certified regional fabricators with custom-molding capabilities represent the most attractive acquisition target archetype for portfolio consolidation. Long-term viability favors manufacturers with established MDR technical documentation and hospital system contracting relationships over commodity plaster suppliers facing supply concentration risk. Watch pediatric procedure volume trends as inflection indicator for thermoplastic segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| 510(k) Predicate Library Expansion | Accelerates regulatory clearance timelines for novel fiberglass and thermoplastic splint designs in United States acute care. |
| MDR Technical Documentation Pre-Certification | Swiss and German suppliers compress European market access timelines through pre-qualified substance disclosure compliance. |
| Group Purchasing Organization Membership | Stryker and DJO Global sustain volume concentration across 20-30 facility integrated delivery network footprints. |
| Direct-to-Patient E-Commerce Launch | Specialized orthopedic supply platforms bypass distributor markups for soft splint sales in Medicare Advantage channels. |
| Backward Integration into Resin Formulation | Captive supply of polyurethane resin systems defends gross margins against petrochemical feedstock price volatility. |
Research Methodology
The analysis maps fiberglass substrate, thermoplastic polymer, plaster-derived, and composite material sub-sectors, each validated through hospital procurement managers, orthopedic cast technicians, GPO contracts managers, and biomedical engineers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contracts, and CMS Medicare reimbursement schedules. Bottom-up volume triangulation across material substrates and care settings reconciled with top-down market sizing from trade flow analysis.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for glass fiber imports and group purchasing organization contract disclosure filings. The analytical framework segments by product type, material substrate, end user category, and application severity across the projection horizon. CAGRs derived from procedure volume elasticity models incorporating aging demographic trajectories and sports medicine expansion rates. Forecast inputs included orthopedic residency training capacity for cast technician skill pipeline and Medicare Advantage plan penetration for home care channel development.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) clearance efficiency and resin feedstock price normalization; material deviation in regulatory timelines or petrochemical markets would warrant model refresh. Specific risks include EU MDR substance disclosure expansion, cast technician training program deprioritization, and integrated delivery network contract consolidation acceleration. Recalibration cycles align with material shifts in procedure volume recovery trajectories and group purchasing organization contract renewal windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
3D Orthopedic Scanning System Market