
 Global IVF Devices and Consumables Market | 2026-2036
Global IVF Devices and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Global IVF Devices and Consumables Market Foresight
Market Context
Polymer-based culture media formulations are pivoting from traditional glass-dependent systems toward single-use consumable architectures that reduce contamination risk and streamline clinic workflows. Thermo Fisher Scientific leverages its life sciences distribution network to sustain broad geographic coverage of IVF reagents and instruments. Vitrolife AB anchors its competitive position through specialized media products optimized for time-lapse embryo monitoring protocols. CooperSurgical Inc. dominates the catheter segment with proprietary designs that integrate aspiration and transfer functions.
Technical Definition and Segment Structure
IVF devices and consumables comprise the instruments, media, and disposable tools engineered to execute extracorporeal fertilization, embryo culture, cryopreservation, and uterine transfer procedures under controlled laboratory conditions. These products operate within precise thermal, pH, and osmolarity parameters to maintain gamete and embryo viability outside the human body. Culture media commands the largest margin pool due to recurring purchase cycles and proprietary additive formulations that differentiate supplier offerings. Cryopreservation equipment exhibits the fastest structural expansion as elective egg freezing protocols gain traction among fertility clinics. Catheters remain the most mature product category, with competition centered on material flexibility and tip geometry rather than breakthrough innovation.
Regulatory Framework and Outlook
The FDA 510(k) clearance pathway governs device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on implantable and active reproductive devices. Japan's PMDA maintains distinct quality standards for culture media that foreign manufacturers must navigate through local partnership structures. China's NMPA has accelerated review timelines for domestically manufactured IVF consumables under innovation-track designations. Stakeholders must monitor evolving premarket submission requirements across these jurisdictions to anticipate compliance costs and market access timelines.
Market Dynamics
Single-use consumable architectures are compressing capital expenditure cycles for fertility clinics while fragmenting supplier power across media, catheters, and cryopreservation equipment categories.
Growth Catalysts
- China's NMPA innovation-track designations:Domestic manufacturers receive accelerated review timelines for IVF consumables, expanding clinic access to lower-cost alternatives.
- Time-lapse embryo monitoring protocols:Specialized culture media formulations optimized for continuous imaging systems drive recurring purchase cycles among high-throughput fertility centers.
- Elective egg freezing protocols:Cryopreservation equipment demand concentrates in urban fertility clusters across Japan and South Korea as delayed family planning normalizes.
Market Restraints
- Pharmaceutical-grade raw material volatility:Purified water and recombinant protein inputs face supply concentration from European chemical suppliers.
- EU MDR clinical evidence requirements:Stricter documentation burdens for implantable reproductive devices extend commercialization timelines for catheter manufacturers.
- Glass-dependent legacy infrastructure:Established clinics in Germany and France retain sunk investments in reusable culture vessel systems that resist full conversion.
Strategic Opportunities
- India's government-funded infertility programs:Public hospital networks in Maharashtra and Tamil Nadu represent underpenetrated volume channels for standardized consumable bundles.
- Remote monitoring integration:Cloud-connected incubator systems enable fertility clinics to offer decentralized embryo tracking services.
- ISO 20399 standard harmonization:Emerging global benchmarks for assisted reproductive technology materials create first-mover certification advantages for compliant suppliers.
Industry Challenges
- Embryologist training pipeline gaps:Specialized micromanipulation skills required for intracytoplasmic sperm injection face scarcity across Southeast Asian markets.
- Legacy laboratory information system integration:Time-lapse imaging platforms require costly middleware development to connect with established electronic medical record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IVF Devices and Consumables Market |
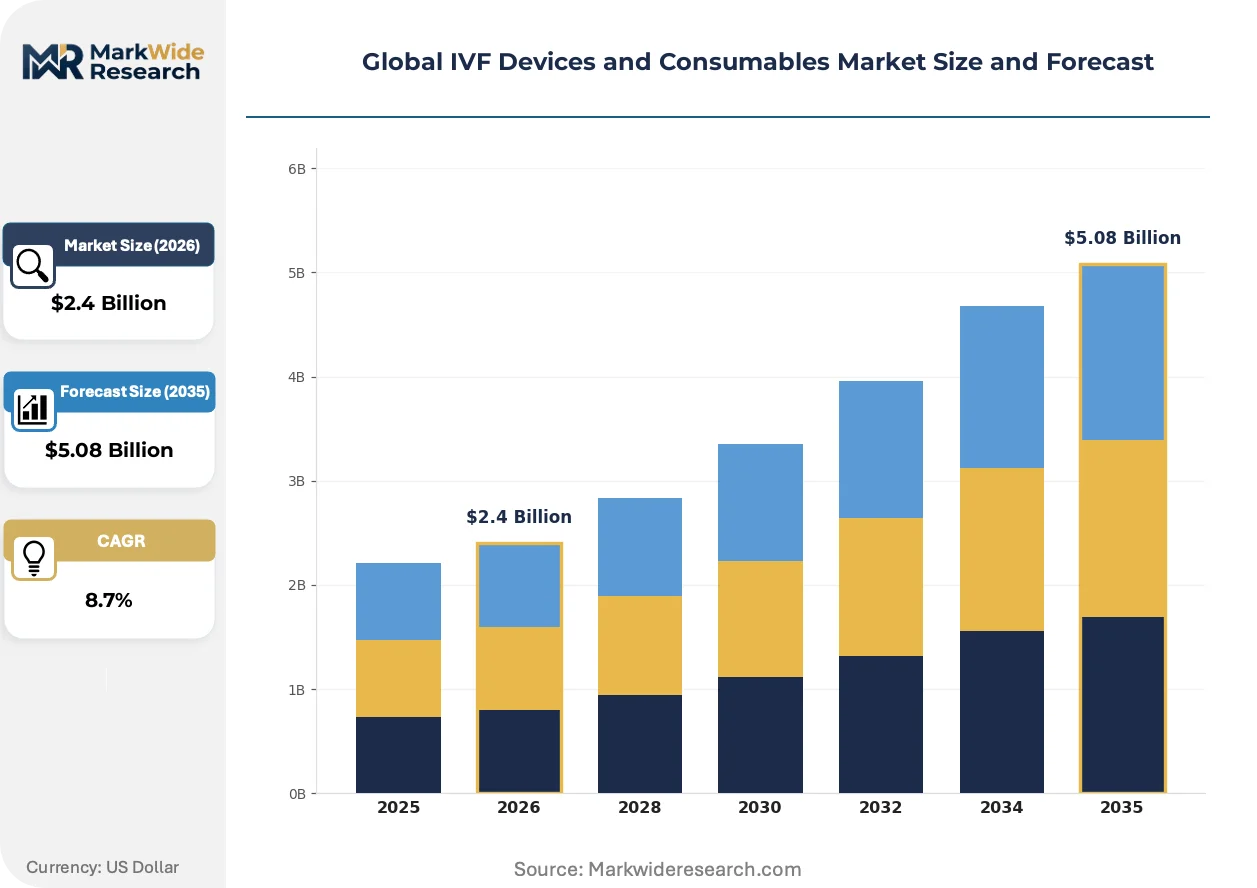
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Incubators, Cryopreservation Equipment, Culture Media, Catheters Application: In Vitro Fertilization, Intracytoplasmic Sperm Injection, Egg Freezing, Embryo Transfer, Gamete Intrafallopian Transfer End User: Fertility Clinics, Research Laboratories, Diagnostic Centers, Hospitals, Medical Institutes Deployment: Hospital-Based Clinics, Standalone Fertility Centers, Mobile Units, IVF Laboratories, Academic Facilities |
| Companies Covered | CooperSurgical Inc., Vitrolife AB, Thermo Fisher Scientific Inc., Hamilton Thorne Ltd., Esco Micro Pte. Ltd., Merck KGaA, Cook Medical Inc., Kitazato Corporation, FUJIFILM Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IVF Devices and Consumables Market Shifts & Advancements
Workflow automation and regulatory data integrity requirements are compressing the gap between laboratory equipment and enterprise software systems in fertility clinic operations.
Polymer-based culture media is absorbing the functional role of traditional borosilicate glass vessels in embryo culture workflows. High-throughput fertility networks in Spain and the Czech Republic are adopting single-use chambers at scale. This shift is absorbing capital that previously flowed into autoclave infrastructure and reusable vessel sterilization protocols.
EU Medical Device Regulation Annex XVI expansions are reclassifying certain embryo culture incubators as active implantable devices. Manufacturers must now submit clinical performance data beyond bench validation. The catheter segment faces the steepest compliance cost escalation as notified bodies apply heightened scrutiny to tip geometry claims.
Fertility clinic procurement departments are consolidating supplier relationships around full-protocol bundles rather than discrete product categories. Independent distributors in Italy and Poland are losing shelf space to manufacturer-direct service contracts. This consolidation concentrates most visibly among mid-sized clinic networks seeking simplified vendor management.
Global IVF Devices and Consumables Market Segmentation
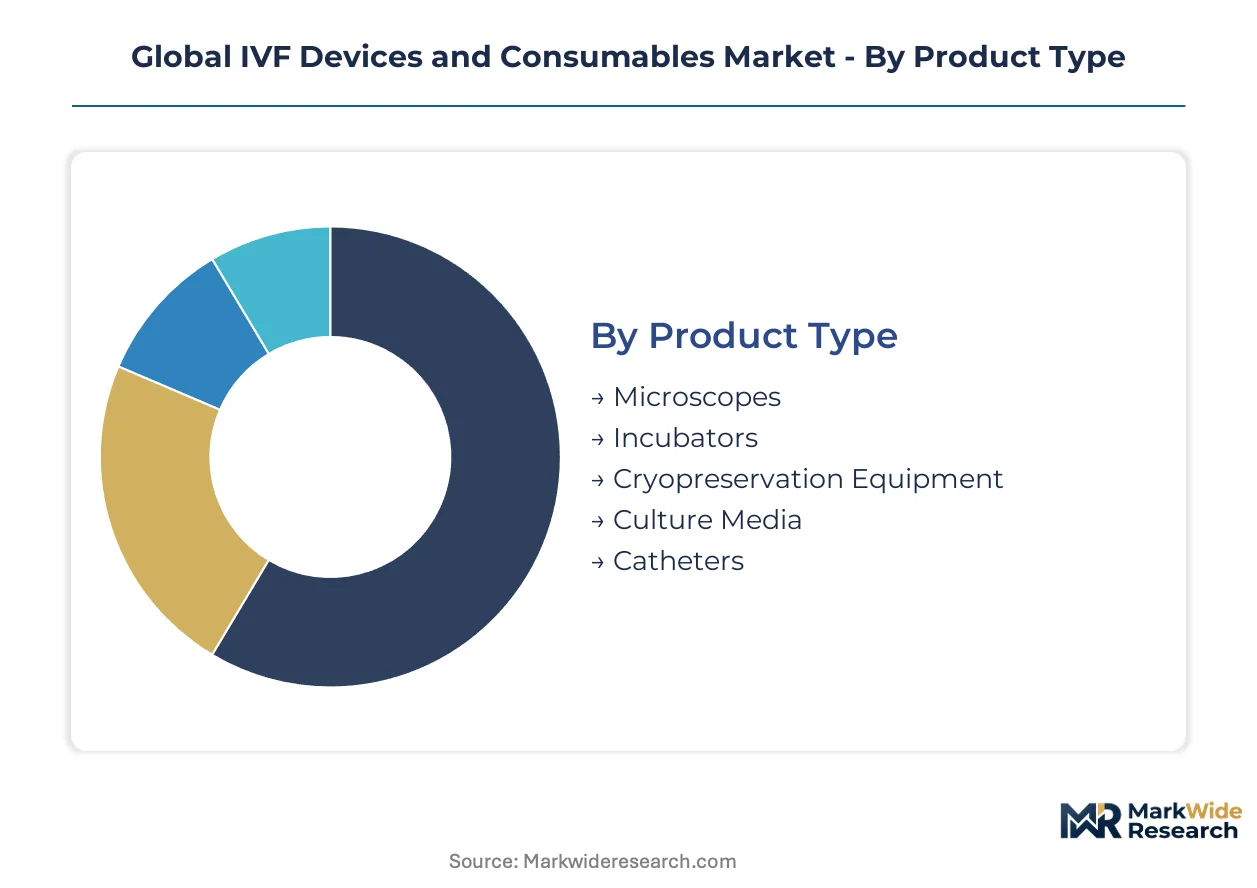
Segmentation in the IVF devices and consumables market reveals how procurement patterns fragment across clinical workflows and regulatory environments. Suppliers must align product architectures with distinct end-user infrastructure investments and patient volume thresholds.
Product Type:
Supply concentration varies sharply across product categories, with recurring consumables commanding different margin profiles than capital equipment.
- Culture Media:Proprietary additive formulations differentiate supplier offerings through optimized pH buffering and protein supplementation. Demand concentrates in high-throughput fertility centers across China and India as government-funded programs expand clinic networks.
- Cryopreservation Equipment:Vitrification systems and controlled-rate freezers maintain gamete viability through precise thermal cycling protocols. Elective egg freezing protocols in Japan and South Korea drive equipment upgrades in urban fertility clusters.
- Microscopes:Inverted optical systems with micromanipulation stages enable embryo assessment and intracytoplasmic sperm injection procedures.
- Incubators:Time-lapse imaging platforms integrate continuous embryo monitoring with cloud-connected data logging.
- Catheters:Transfer and aspiration devices compete on material flexibility and tip geometry optimization.
Today's leader: Culture Media. Tomorrow's challenger: Cryopreservation Equipment.
Application:
Clinical application segmentation tracks how procedural complexity shapes device specifications and consumable bundling strategies.
- In Vitro Fertilization:Standard extracorporeal fertilization protocols require synchronized culture media, incubators, and transfer catheters across multi-day embryo development cycles. Fertility clinics in Spain and the Czech Republic deploy high-volume standardized workflows.
- Intracytoplasmic Sperm Injection:Micromanipulation-intensive procedures demand specialized inverted microscopes with piezo-driven injection systems. Southeast Asian markets face embryologist training pipeline gaps that constrain procedure expansion.
- Egg Freezing:Oocyte vitrification protocols require rapid cooling systems and cryoprotectant media formulations.
- Embryo Transfer:Uterine catheterization procedures prioritize tip flexibility and echogenic visibility under ultrasound guidance.
- Gamete Intrafallopian Transfer:Laparoscopic delivery methods retain niche application in specific patient cohorts.
Volume concentrates in In Vitro Fertilization. Complexity premiums accrue to Intracytoplasmic Sperm Injection.
End User:
End-user segmentation exposes divergent procurement authority structures between independent clinics and institutional health systems.
- Fertility Clinics:Specialized reproductive medicine centers command the largest consumable volumes through recurring media and catheter purchases. Patient volumes surge across Asia-Pacific markets as regulatory harmonization accelerates product standardization.
- Research Laboratories:Academic and commercial R&D facilities drive demand for experimental media formulations and advanced imaging systems.
- Diagnostic Centers:Pre-treatment fertility assessment sites require andrology workstations and hormone assay integration.
- Hospitals:Integrated health systems leverage centralized procurement for standardized consumable bundles.
- Medical Institutes:Training and credentialing facilities maintain simulation equipment for embryologist skill development.
Procurement autonomy defines Fertility Clinics. Budget integration shapes Hospitals.
Deployment:
Deployment mode segmentation captures infrastructure investment patterns from fixed installations to distributed service models.
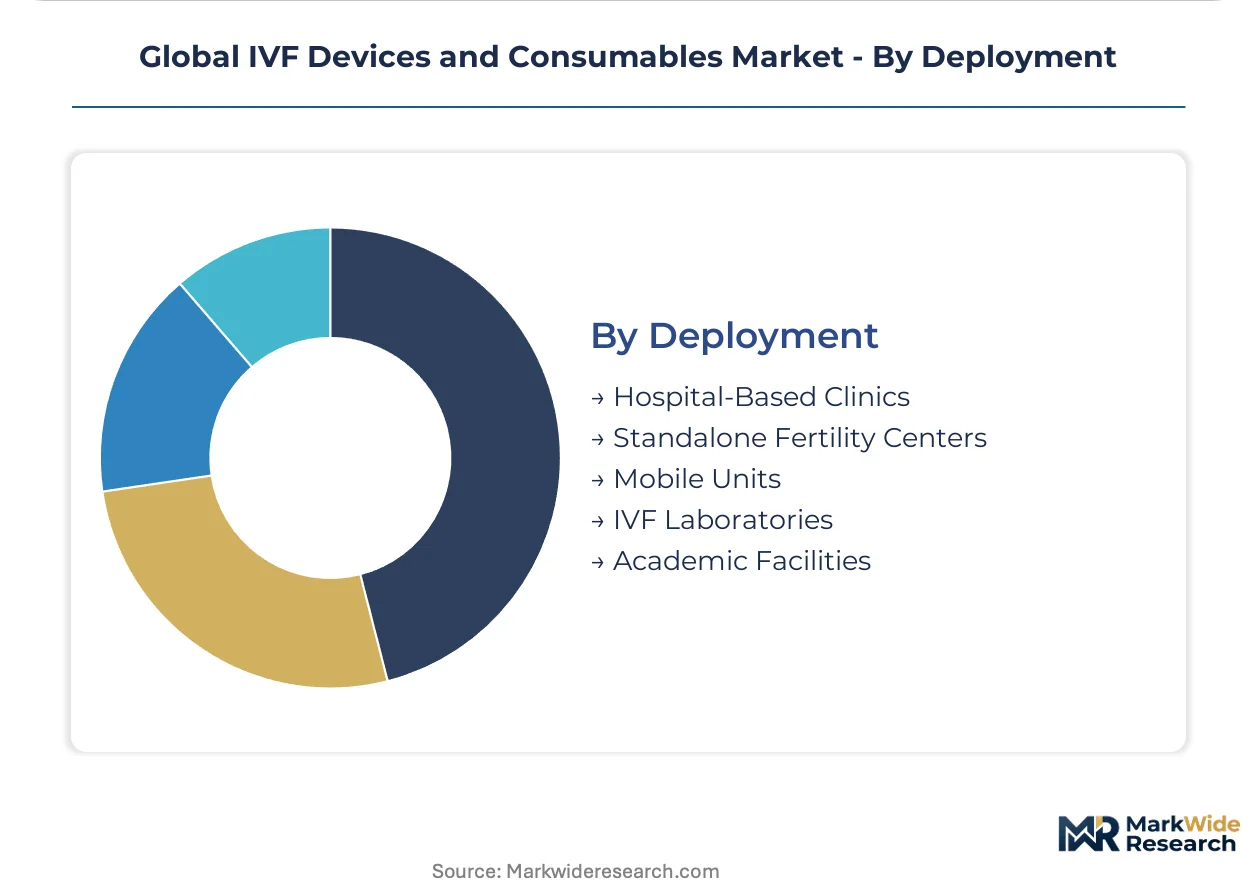
- Standalone Fertility Centers:Purpose-built facilities optimize laboratory layouts for cleanroom specifications and patient flow efficiency. Urban clusters in Maharashtra and Tamil Nadu represent underpenetrated volume channels for standardized consumable bundles.
- Hospital-Based Clinics:Embedded reproductive units leverage existing laboratory infrastructure and electronic medical record systems.
- IVF Laboratories:Dedicated embryo culture facilities serve multiple clinical sites through centralized processing.
- Mobile Units:Deployable screening and cryopreservation services extend access to underserved geographic regions.
- Academic Facilities:University-affiliated centers combine clinical service with research protocol development.
Fixed infrastructure dominates Standalone Fertility Centers. Distributed models challenge Mobile Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's fertility clinic corridor concentrates China's IVF consumable demand through government-funded infertility program expansions. Patient volumes surge across municipal hospital networks as NMPA innovation-track designations accelerate domestic product approvals. Urban clusters in Maharashtra and Tamil Nadu represent underpenetrated volume channels for standardized consumable bundles.
United States
Fertility clinic consolidation drives centralized procurement of single-use media and catheter bundles across multi-site networks. FDA 510(k) clearance pathways govern device commercialization timelines for implantable reproductive technologies. Greater Boston's academic medical centers anchor demand for time-lapse imaging platforms with integrated cloud data logging.
China
Domestic manufacturers receive accelerated NMPA review timelines for IVF consumables under innovation-track designations. Public hospital networks expand access to lower-cost alternatives as government-funded infertility programs scale. Shanghai's municipal fertility centers deploy high-throughput standardized workflows for culture media and cryopreservation equipment.
Japan
Elective egg freezing protocols concentrate equipment demand in Tokyo and Osaka urban fertility clusters. PMDA maintains distinct quality standards for culture media that foreign manufacturers navigate through local partnership structures. Kanto region clinics upgrade vitrification systems as delayed family planning normalizes among professional demographics.
India
Maharashtra and Tamil Nadu public hospital networks represent underpenetrated volume channels for standardized consumable bundles. Government-funded infertility programs expand clinic access across tier-2 and tier-3 cities. Bangalore's private fertility chains adopt polymer-based culture media to replace glass-dependent legacy infrastructure.
Germany
Established clinics in Bavaria and North Rhine-Westphalia retain sunk investments in reusable glass vessel systems that resist full conversion. EU MDR clinical evidence requirements extend commercialization timelines for catheter manufacturers seeking notified body approval. Berlin's research institutes drive demand for experimental media formulations and advanced imaging systems.
Global IVF Devices and Consumables Market Competitive Landscape
Global majors compete with regional champions across distribution reach and regulatory navigation capabilities. The supplier base fragments across media formulations, cryopreservation equipment, and catheter categories with distinct margin profiles. Three archetypes dominate: diversified life sciences conglomerates with broad reagent portfolios, specialized reproductive technology firms with proprietary media additives, and regional equipment fabricators with localized service networks. Competitive moves concentrate on strategic partnerships for regulatory market access and portfolio diversification into adjacent fertility diagnostics.
Within the specialized reproductive technology tier, Vitrolife AB and Kitazato Corporation exemplify focused players anchoring competitive positions through proprietary culture media formulations. Thermo Fisher Scientific Inc. occupies a position representing diversified life sciences conglomerates leveraging distribution scale across geographic markets. CooperSurgical Inc. sits within the integrated device-architecture archetype, with catheter designs that consolidate aspiration and transfer functions. These three company structures illustrate how supplier power fragments across recurring consumables, capital equipment, and integrated procedure tools.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| Vitrolife AB |
| Thermo Fisher Scientific Inc. |
| Hamilton Thorne Ltd. |
| Esco Micro Pte. Ltd. |
| Merck KGaA |
| Cook Medical Inc. |
| Kitazato Corporation |
| FUJIFILM Holdings Corporation |
| Others |
Supply & Pricing Matrix
Embryologist workforce concentration in Southeast Asian fertility hubs compresses labor-cost differentials into pricing-tier spreads between premium media formulations and standardized consumable bundles. Cost arbitrage between European chemical suppliers and Asian manufacturing clusters propagates through catheter and cryopreservation equipment procurement decisions.
Pricing Analysis
Input-cost pass-through from pharmaceutical-grade recombinant proteins and purified water concentrates pricing pressure at the premium media tier. Three-tier pricing structure across premium, standard, and economy levels separates time-lapse-optimized formulations from basic culture media and generic catheter alternatives. Price differentiation hinges on ISO 20399 certification status and volume-scale procurement contracts. Public hospital networks in India exhibit highest price sensitivity, while Japan's urban fertility clusters absorb premium positioning for elective egg freezing protocols.
Supply Chain Analysis
Single-source vulnerability sits with European chemical suppliers dominating recombinant protein and pharmaceutical-grade water inputs. Manufacturing concentration clusters in Germany, Japan, and China for culture media, cryopreservation equipment, and polymer-based consumables respectively. Raw material dependencies include borosilicate glass alternatives, cryoprotectant chemicals, and precision-molded catheter polymers. Tariff exposure on Chinese-manufactured consumables entering US and EU markets constitutes the dominant supply chain risk. Distribution runs through manufacturer-direct service contracts consolidating procurement relationships across mid-sized clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting toward premium specifications as time-lapse embryo monitoring protocols become standard in high-throughput fertility centers.
For Market Incumbents: To counter domestic manufacturer encroachment under China's NMPA innovation-track designations, anchor market position through backward integration into pharmaceutical-grade raw material production. Prioritize ISO 20399 certification investment to create compliance moats against lower-cost Asian entrants. For New Entrants and Emerging Players: Enter via India's government-funded infertility programs in Maharashtra and Tamil Nadu public hospital networks, where standardized consumable bundles face limited incumbent penetration. Target remote monitoring integration partnerships as the go-to-market angle for cloud-connected incubator systems. For Investors and Strategic Acquirers: Diversified life sciences conglomerates represent the most active acquirer in this space, seeking specialized reproductive technology firms with proprietary media additive portfolios. Five-to-ten year viability favors suppliers with regulatory navigation capabilities across FDA, EU MDR, and PMDA jurisdictions. Watch NMPA approval velocity for domestic Chinese manufacturers as the inflection signal for competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20399 Certification Pathway | First-mover compliance advantages create procurement preference in EU and Japanese fertility clinics. |
| Hospital System Partnership | Direct service contracts with multi-site networks displace independent distributors in Italy and Poland. |
| Backward Integration into Raw Materials | In-house production of recombinant proteins buffers margin compression from European supplier concentration. |
| Software Companion Development | Cloud-connected embryo tracking platforms enable decentralized service models for remote fertility monitoring. |
| Reimbursement Strategy | Government-funded infertility program alignment in China and India unlocks volume channels for standardized bundles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fertility clinic laboratory directors, embryologists, biomedical engineers, and GPO contracts managers alongside secondary validation. FDA 510(k) filings, EU MDR notified body records, NMPA innovation-track designations, and hospital procurement databases anchored the data foundation. Bottom-up clinic-level volume estimates and top-down manufacturer revenue triangulation cross-validated segment sizing.
Segment-weighting approaches distributed value across product type, application, end user, and deployment mode dimensions throughout the forecast period. CAGRs derived from procedure volume trajectories, consumable purchase cycle frequencies, and equipment replacement intervals across fertility clinic networks. Time-lapse imaging platform adoption curves and elective egg freezing protocol penetration supplied industry-specific forecast inputs.
Inputs from regulatory filings and hospital procurement systems were available through the study window; gaps in private clinic pricing transparency introduce uncertainty bands around premium-tier margin estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hearing Aid with Lithium-Ion Battery Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
Bariatric Beds Market
Medical Devices
Portable OT Light Market
Medical Devices
Canada Varicose Vein Treatment Devices Market