
 Cognitive and Memory Enhancer Drugs Market | 2026-2036
Cognitive and Memory Enhancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive and Memory Enhancer Drugs Market Intelligence
Neuropharmacology talent scarcity is bifurcating the competitive landscape between large-cap developers with captive research infrastructure and mid-tier firms dependent on contract research organizations. Eisai Co., Ltd leverages its deep amyloid-targeting expertise to sustain leadership in Alzheimer's therapeutics. Biogen Inc anchors its position through upstream control over monoclonal antibody manufacturing for cognitive indications. AbbVie Inc competes by extending its immunology discovery engine into neurodegenerative pathways.
Cognitive and memory enhancer drugs comprise synthetic and biologic agents that modulate neurotransmitter systems—primarily acetylcholine, glutamate, and dopamine—to improve synaptic plasticity, attention, or memory retention in patients with neurodegenerative or neuropsychiatric conditions. Cholinesterase inhibitors such as donepezil function by preventing acetylcholine breakdown in cortical and hippocampal circuits, while NMDA receptor antagonists like memantine regulate glutamatergic excitotoxicity in moderate-to-severe dementia. The therapy area dimension reveals Alzheimer's Disease commanding the largest revenue pool due to irreversible progression and chronic polypharmacy, whereas ADHD formulations in tablet and capsule formats are gaining traction through expanded adult-diagnosis protocols. Racetams and ampakines occupy narrower prescription volumes but attract outsized R&D investment from research institutions exploring off-label neuroprotection.
The FDA's accelerated approval framework and EMA's conditional marketing authorization pathways are tightening evidentiary standards for amyloid-clearing therapies while opening faster routes for breakthrough cognitive drugs. Japan's PMDA maintains distinct pharmacovigilance requirements for geriatric psychotropics that shape trial design for Asia-Pacific submissions. Stakeholders must monitor how CMS coverage determinations for novel Alzheimer's therapies will reshape prescribing economics across neurology clinics and geriatric care centers.
Market Dynamics
Accelerated approval pathways for amyloid-clearing therapies are compressing development timelines while elevating evidentiary burdens, forcing developers to front-load biomarker validation and adaptive trial infrastructure before regulatory submission.
Growth Catalysts
- Japan's PMDA geriatric psychotropic guidelines:Specialized pharmacovigilance frameworks for aging populations create predictable regulatory pathways for dementia therapeutics targeting the Asia-Pacific's fastest-aging demographic.
- Adult ADHD diagnosis expansion:Revised clinical protocols in primary care settings are extending stimulant and non-stimulant prescriptions beyond pediatric populations into working-age cohorts.
- Medicare reimbursement alignment:CMS coverage determinations for novel Alzheimer's therapies are standardizing prescribing economics across US neurology clinics and memory care centers.
Market Restraints
- Biomarker validation costs:PET imaging and CSF assay requirements for amyloid confirmation impose substantial diagnostic infrastructure investments before therapeutic initiation.
- Specialized manufacturing concentration:Monoclonal antibody production for cognitive indications clusters among a limited network of contract manufacturing organizations with mammalian cell culture capabilities.
- Generic erosion of cholinesterase inhibitors:Donepezil and rivastigmine patent expirations have collapsed price points for standard-of-care dementia maintenance therapy.
Strategic Opportunities
- Digital therapeutics integration:FDA breakthrough device designation pathways enable software-based cognitive training platforms to complement pharmacological interventions in mild cognitive impairment.
- India's CDSCO accelerated approval:Streamlined review timelines for drugs addressing unmet neurological needs open access to a geriatric population exceeding 100 million.
- Gene therapy convergence with small molecules:Combination regimens targeting APOE4 carriers represent an underexplored mechanistic frontier beyond amyloid and tau monotherapies.
Industry Challenges
- Neuropharmacology talent scarcity:Shortages of translational researchers with CNS drug development expertise constrain mid-tier firms to reliance on contract research organizations for pivotal trials.
- Adaptive trial infrastructure:Real-time biomarker monitoring and Bayesian statistical frameworks demand capital investment in data science capabilities foreign to legacy development organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive and Memory Enhancer Drugs Market |
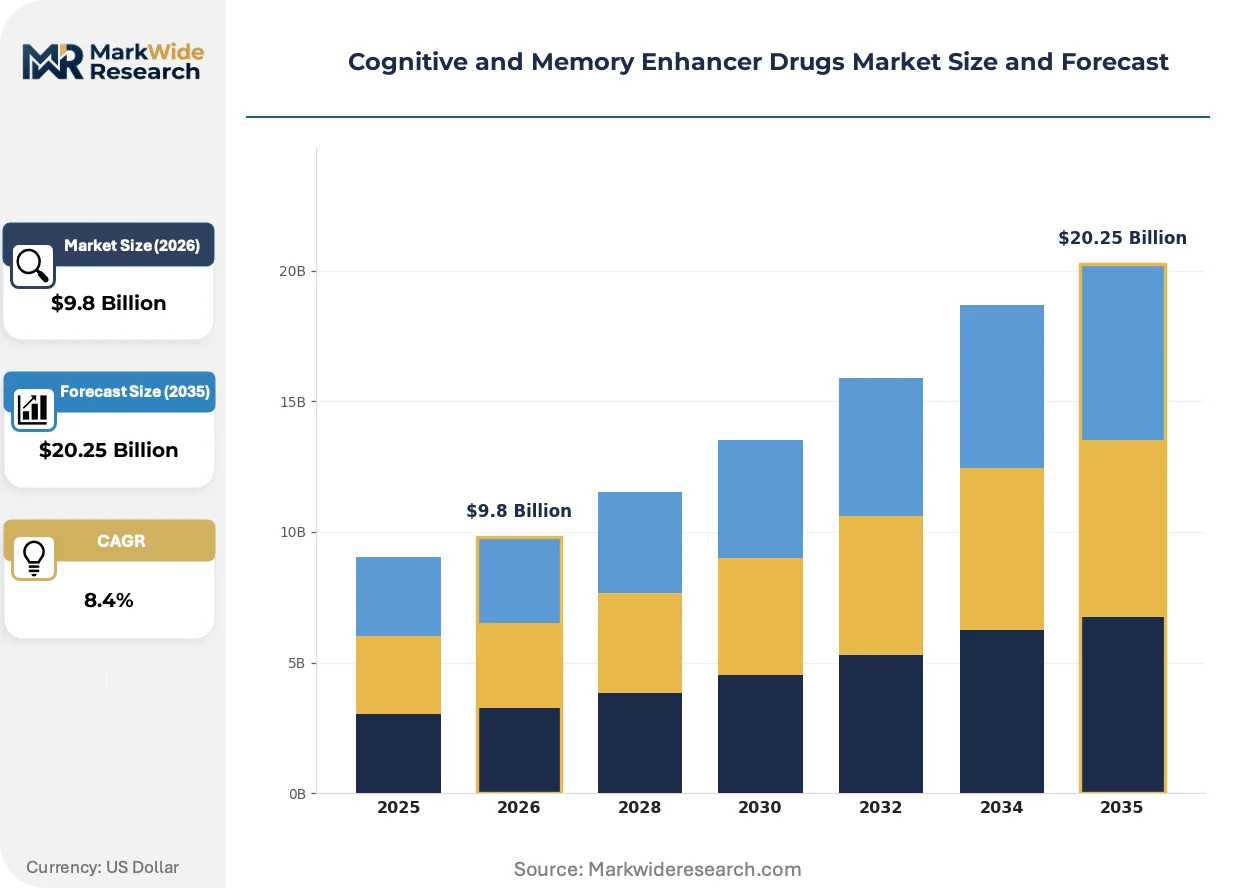
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholinesterase Inhibitors, NMDA Receptor Antagonists, Racetams, Ampakines, Nutraceuticals Therapy Area: Alzheimer’s Disease, Dementia, ADHD, Traumatic Brain Injury, Age-related Cognitive Decline End User: Neurology Clinics, Geriatric Care Centers, Psychiatric Facilities, Research Institutions, Pharmacies Formulation Type: Tablets, Capsules, Oral Solutions, Injectable, Powder |
| Companies Covered | Bayer AG, Eisai Co., Ltd, AbbVie Inc, GlaxoSmithKline plc, Eli Lilly and Company, Allergan Plc, Biogen Inc, Johnson & Johnson, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive and Memory Enhancer Drugs Market Strategic Shifts & Innovations
Mechanism diversification beyond cholinergic and glutamatergic modulation is reshaping pipeline composition, with anti-amyloid immunotherapies and tau-targeting small molecules commanding disproportionate R&D allocation despite heterogeneous clinical outcomes.
Blood-based biomarker assays for phosphorylated tau and neurofilament light chain are displacing lumbar puncture and PET imaging requirements in early-stage patient identification. Primary care networks in the United States and Western Europe are adopting these platforms to streamline specialist referral workflows. The shift is compressing diagnostic delays from months to weeks while expanding the addressable screening population.
The EMA's conditional marketing authorization framework is tightening evidentiary standards for surrogate endpoint acceptance in Alzheimer's disease. Developers must now demonstrate clinical benefit correlation rather than biomarker change alone. Mid-stage programs are responding by embedding cognitive endpoint batteries earlier in Phase II adaptive designs.
Integrated care contracts linking pharmaceutical reimbursement to functional outcome maintenance are replacing fee-for-service prescribing in Germany's statutory health insurance system. Memory care centers are consolidating purchasing decisions under hospital network procurement offices. This behavioral shift is most visible in Bavaria and North Rhine-Westphalia, where accountable care organizations now control formulary placement for cognitive enhancers.
Cognitive and Memory Enhancer Drugs Market Segmentation
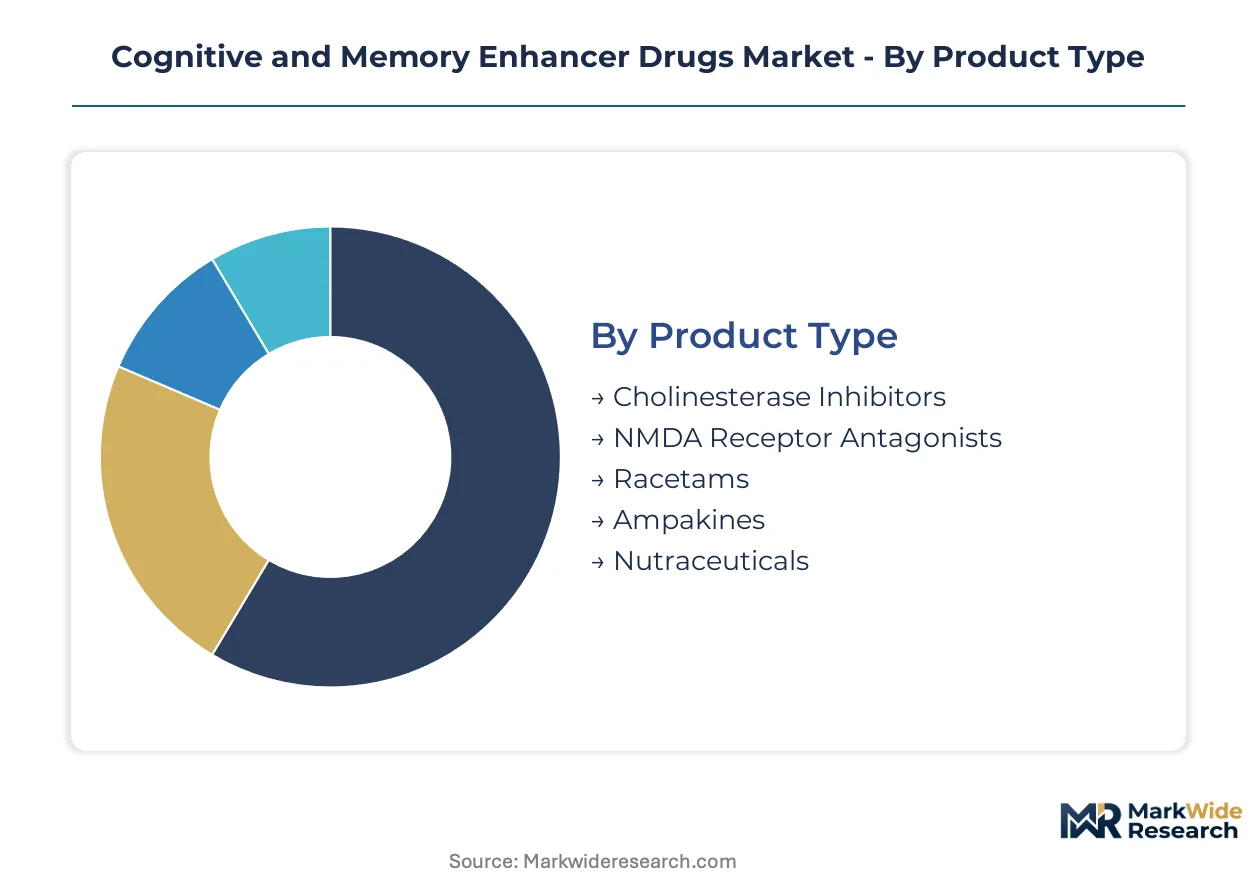
Segmentation in cognitive therapeutics reveals divergent substitution pressures across mechanism classes, with small-molecule standards facing erosion from biologic entrants while formulation innovation reshapes patient adherence economics. Understanding these fault lines guides portfolio allocation between defensive maintenance therapies and breakthrough modalities.
Product Type:
Cholinesterase inhibitors face intensifying generic substitution as patent cliffs erode branded pricing power, while monoclonal antibody developers exploit the protection gap with premium positioning.
- Cholinesterase Inhibitors:Synthetic small molecules—donepezil, rivastigmine, galantamine—block acetylcholinesterase to sustain cortical cholinergic signaling. Demand concentrates in Medicare-reimbursed long-term care facilities across Florida and Arizona, where polypharmacy protocols favor established efficacy profiles over novel mechanisms.
- NMDA Receptor Antagonists:Memantine and related compounds modulate glutamatergic excitotoxicity through uncompetitive NMDA channel blockade. Prescribing clusters in Germany's statutory health insurance networks, where integrated care contracts now tie reimbursement to functional outcome maintenance rather than biomarker response.
- Racetams:Piracetam-class nootropics enhance membrane fluidity and mitochondrial function; niche adoption persists in Eastern European markets with distinct pharmacovigilance frameworks for geriatric psychotropics.
- Ampakines:Positive allosteric modulators of AMPA receptors accelerate synaptic potentiation; development pipelines target fragile X syndrome and residual cognitive deficits post-TBI.
- Nutraceuticals:Omega-3 phospholipids, ginkgo biloba extracts, and citicoline formulations occupy over-the-counter channels with limited clinical trial substantiation.
Cholinesterase inhibitors retain volume leadership; ampakines hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention windows, with Alzheimer's commanding premium pricing against commoditized ADHD maintenance.
- Alzheimer's Disease:Progressive neurodegeneration with amyloid and tau pathology drives the largest revenue pool. Anti-amyloid immunotherapies from Eisai and Biogen anchor prescriber attention, though CMS coverage determinations restrict access to confirmed biomarker-positive patients.
- Dementia:Vascular and Lewy body variants require differentiated pharmacologic approaches; cholinesterase inhibitors dominate despite modest efficacy signals.
- ADHD:Stimulant and non-stimulant formulations expand into working-age cohorts through revised primary care diagnostic protocols in the United States and United Kingdom.
- Traumatic Brain Injury:Off-label racetam and ampakine use persists in rehabilitation settings with limited regulatory guidance.
- Age-related Cognitive Decline:Mild cognitive impairment represents the most contested boundary between pharmacologic and digital therapeutic intervention.
Alzheimer's Disease captures the premium tier; ADHD prescriptions are climbing the fastest.
End User:
Customer type fragmentation concentrates purchasing authority in consolidated health networks, with independent psychiatric facilities losing formulary control to centralized procurement offices.
- Neurology Clinics:Specialist-directed prescribing for Alzheimer's and movement disorder dementias; amyloid PET confirmation requirements filter patient eligibility.
- Geriatric Care Centers:Long-term care facilities in Japan and the United States administer cholinesterase inhibitors through bundled payment arrangements.
- Psychiatric Facilities:Inpatient and residential settings manage acute agitation comorbid with cognitive impairment.
- Research Institutions:Academic medical centers conduct adaptive trial designs for tau-targeting small molecules and gene therapy vectors.
- Pharmacies:Retail and specialty pharmacy channels handle prior authorization workflows for Medicare Part D coverage of novel Alzheimer's therapies.
Neurology clinics retain volume leadership; geriatric care centers are gaining share fastest.
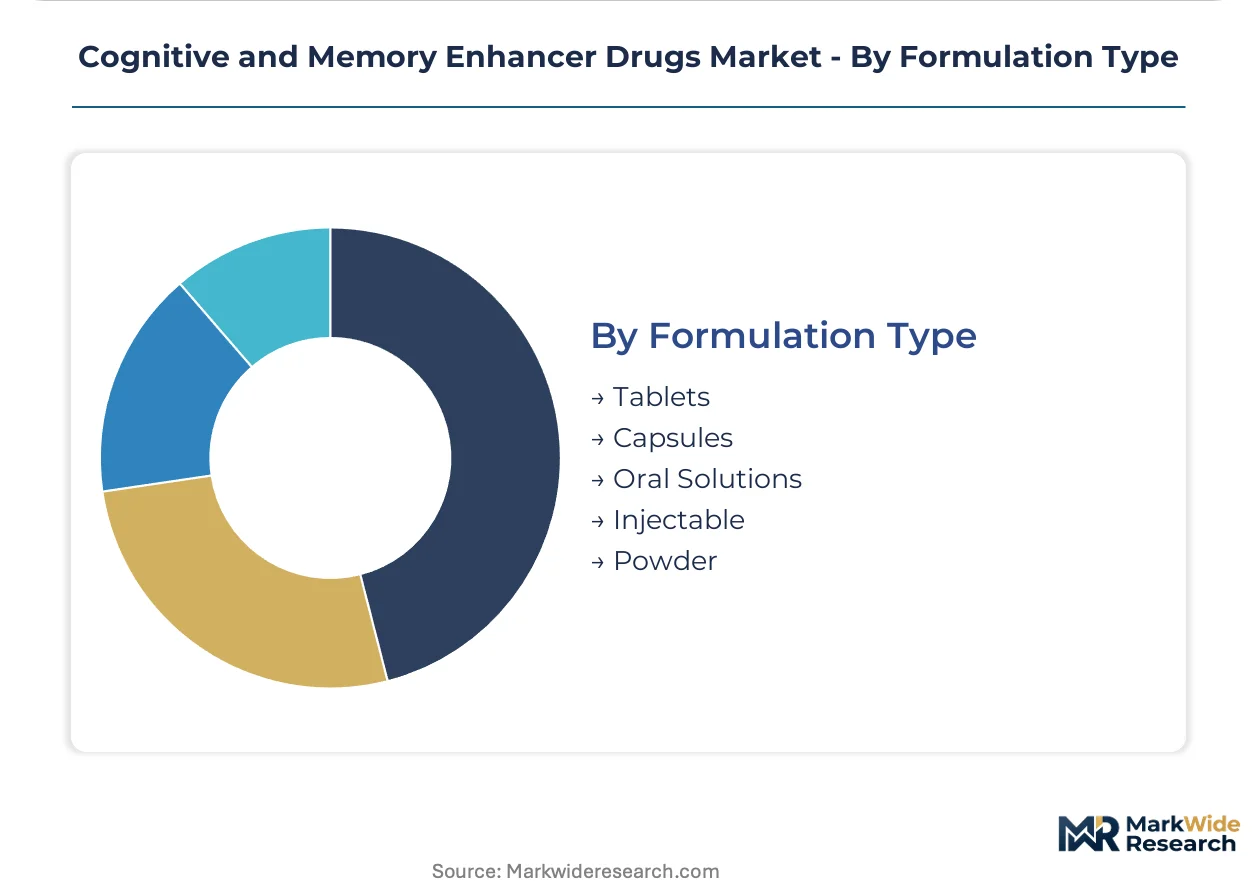
Formulation Type:
Supply concentration in parenteral manufacturing creates bottlenecks for biologic cognitive enhancers, while oral solid dose capacity remains commoditized across contract manufacturing networks.
- Tablets:Immediate and extended-release donepezil formulations dominate maintenance therapy; high-speed compression lines at Indian and Chinese contract manufacturers supply global demand.
- Capsules:Rivastigmine and galantamine capsules serve patients with dysphagia risk; demand clusters in Japan's geriatric care infrastructure.
- Oral Solutions:Liquid formulations address swallowing difficulties in advanced dementia; compounding pharmacies supplement manufactured supply.
- Injectable:Monoclonal antibody infusions for Alzheimer's require cold chain distribution through specialty pharmacy networks.
- Powder:Nutraceutical bulk ingredients and research-grade compounds supply compounding and institutional research use.
Tablets retain volume leadership; injectable formulations command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes cognitive enhancers through Medicare-reimbursed long-term care channels, while Japan and Germany integrate dementia therapeutics into statutory health insurance frameworks with distinct pharmacovigilance requirements.
United States
Medicare Part D reimbursement policies shape prescribing volumes for cholinesterase inhibitors across Florida and Arizona geriatric care networks. The FDA's accelerated approval pathways for amyloid-clearing therapies compress development timelines while elevating biomarker validation requirements. Boston's biopharma corridor anchors monoclonal antibody manufacturing for cognitive indications.
Japan
PMDA geriatric psychotropic guidelines create predictable regulatory pathways for dementia therapeutics targeting the fastest-aging demographic in Asia-Pacific. The agency maintains distinct pharmacovigilance requirements that shape trial design for regional submissions. Tokyo-Osaka pharmaceutical clusters concentrate amyloid-targeting expertise among integrated developers.
Germany
Integrated care contracts in Bavaria and North Rhine-Westphalia now tie pharmaceutical reimbursement to functional outcome maintenance rather than biomarker response. EMA conditional marketing authorization frameworks influence evidentiary standards for surrogate endpoint acceptance. Frankfurt's statutory health insurance networks consolidate formulary placement decisions under hospital procurement offices.
India
CDSCO accelerated approval pathways for drugs addressing unmet neurological needs open access to a geriatric population exceeding 100 million. Streamlined review timelines attract contract manufacturing organizations supplying global demand for oral solid dose formulations. Hyderabad and Ahmedabad house high-speed compression lines serving international markets.
Switzerland
Swissmedic regulatory frameworks support precision medicine approaches for neurodegenerative indications through adaptive trial design approvals. The country's pharmaceutical clusters leverage proximity to EMA headquarters for streamlined European market access. Basel's research institutions anchor tau-targeting small molecule development programs.
Cognitive and Memory Enhancer Drugs Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in cognitive therapeutics, with vertical integration into monoclonal antibody manufacturing and amyloid-targeting research infrastructure separating the tiers. Large-cap developers with captive research capabilities capture premium positioning in Alzheimer's immunotherapies, while mid-tier firms rely on contract research organizations for pivotal trials. Strategic archetypes include integrated biopharma conglomerates, amyloid-specialized developers, and immunology-to-neuroscience extenders. Dominant competitive moves encompass upstream control over biologic manufacturing capacity and extension of discovery engines from adjacent therapeutic areas.
Within the integrated biopharma tier, Eisai Co., Ltd and Biogen Inc occupy positions defined by deep amyloid-targeting expertise and monoclonal antibody manufacturing control respectively. AbbVie Inc represents the immunology-to-neuroscience extender archetype, leveraging existing discovery infrastructure to enter neurodegenerative pathways. These three companies exemplify how therapeutic focus and manufacturing capabilities determine competitive positioning in a market where biomarker validation requirements favor organizations with established clinical infrastructure.
| Leading Market Players |
|---|
| Bayer AG |
| Eisai Co., Ltd |
| AbbVie Inc |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Allergan Plc |
| Biogen Inc |
| Johnson & Johnson |
| AstraZeneca plc |
| Others |
Cost & Logistics Intelligence
Ninety-day cold-chain inventory buffers for monoclonal antibody infusions concentrate pricing power among contract manufacturers with validated mammalian cell culture suites, while generic donepezil tablets flow through commoditized oral solid dose networks with minimal margin capture.
Pricing Analysis
Long-term offtake agreements between Alzheimer's immunotherapy developers and specialty pharmacy networks anchor premium pricing for amyloid-clearing biologics, while spot-market purchasing dominates generic cholinesterase inhibitor procurement by long-term care facilities. Price differentiation rests on biomarker confirmation requirements and CMS coverage tier, with biomarker-positive patient segments showing lowest price sensitivity and maintenance therapy populations in Medicare Part D exhibiting highest elasticity. Cost compression in the small-molecule tier intensifies as Indian and Chinese contract manufacturers expand high-speed compression capacity.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled monoclonal antibody shipments through Rotterdam and Singapore ports constrain distribution economics for biologic cognitive enhancers, favoring regional fill-finish partnerships over centralized manufacturing. Active pharmaceutical ingredient production for donepezil and memantine concentrates in India and China, while monoclonal antibody drug substance manufacturing clusters in the United States, Switzerland, and Japan. Supply chain risk centers on single-source dependency for amyloid-targeting cell lines. Distribution runs through specialty pharmacy networks with cold chain verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
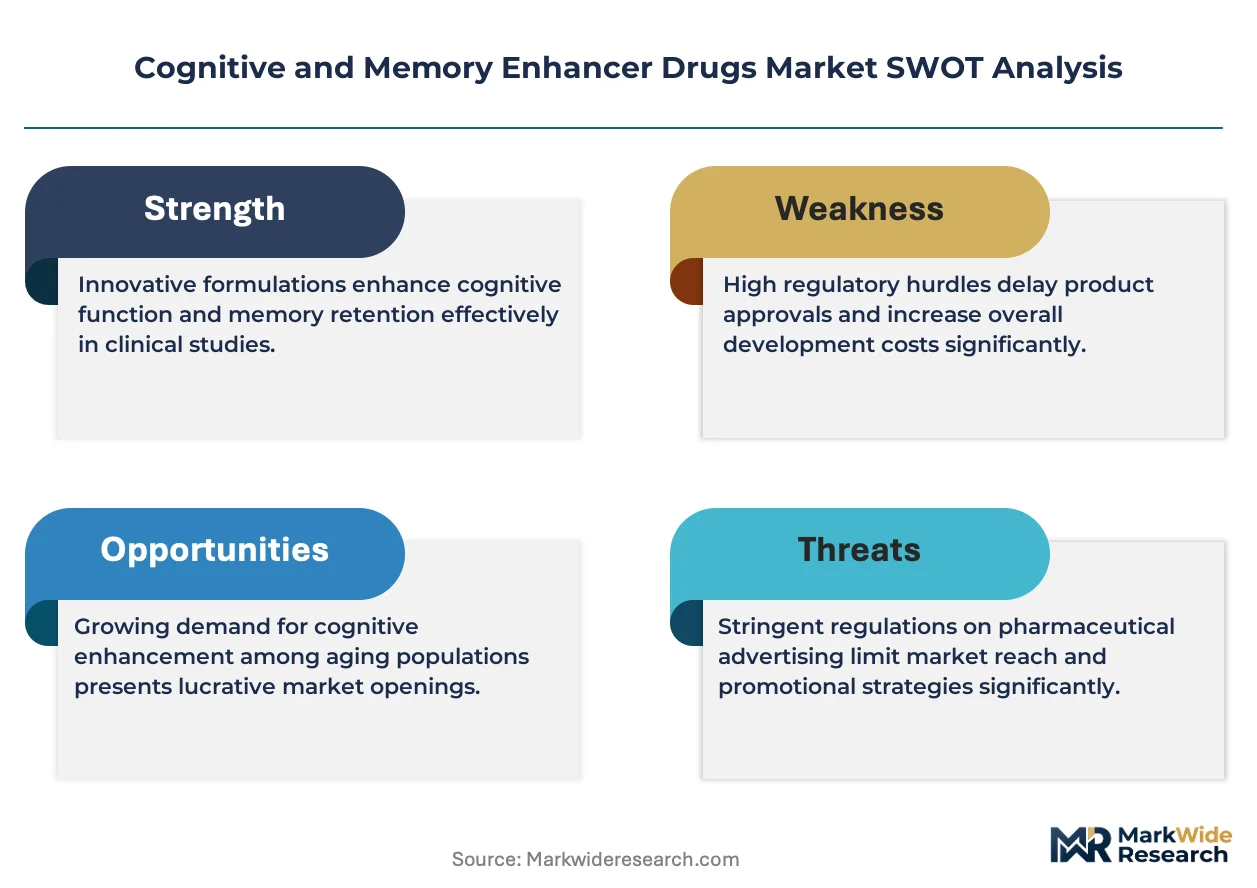
The scarcity of translational neuropharmacologists with CNS drug development expertise constrains pipeline velocity and forces reliance on contract research organizations, creating defensive moats for integrated developers with captive research infrastructure.
For Market Incumbents: Compound amyloid-targeting expertise through upstream control over biologic manufacturing capacity in Boston and Basel clusters. Secure adaptive trial infrastructure investments before regulatory submission windows compress further. Defend against mid-tier CRO-dependent competitors by embedding biomarker validation capabilities in-house. For New Entrants and Emerging Players: Digital therapeutics integration for mild cognitive impairment represents the most penetrable white-space segment, as FDA breakthrough device designation pathways enable software-based cognitive training platforms to complement pharmacological interventions. Target accountable care organizations in Germany's statutory health insurance networks through outcome-based contracting models. Pursue CDSCO accelerated approval in India for geriatric populations exceeding 100 million. For Investors and Strategic Acquirers: Long-term, this sits as a capability-accumulation play because biomarker validation requirements and adaptive trial infrastructure demands favor organizations with established clinical infrastructure over capital-light entrants. Acquisition targets should display vertical integration into monoclonal antibody manufacturing or tau-targeting small molecule pipelines. Watch CMS coverage determinations for novel Alzheimer's therapies as the critical inflection signal for prescribing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Infrastructure Investment | Real-time biomarker monitoring capabilities satisfy FDA accelerated approval evidentiary standards for amyloid-clearing therapies. |
| Biomarker Validation Partnership | Blood-based tau assay integration compresses diagnostic delays from months to weeks in primary care networks. |
| Specialty Pharmacy Network Expansion | Cold chain distribution partnerships secure prior authorization workflows for Medicare Part D coverage of novel immunotherapies. |
| Digital Therapeutic Co-development | FDA breakthrough device designation pathways enable software platforms to complement pharmacological interventions in mild cognitive impairment. |
| Regional Manufacturing Footprint | Indian and Chinese contract manufacturing capacity serves global demand for oral solid dose cholinesterase inhibitors. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis were triangulated to anchor market size estimates.
Variance decomposition across mechanism class, therapy area, formulation type, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against demographic aging trajectories and regulatory approval velocity. Forecast inputs incorporated PMDA geriatric psychotropic guideline evolution and CMS coverage determination timelines for novel Alzheimer's therapies.
Underlying assumptions cover biomarker adoption curves and reimbursement policy stability, with deviation risk concentrated in accelerated approval pathway evidentiary standard changes and generic substitution rates for cholinesterase inhibitors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Teriflunomide Market