
 Equine Veterinary Services Market | 2026-2036
Equine Veterinary Services Market Size, Share, and Industry Trends Forecast 2026-2036
Equine Veterinary Services Market Analysis
North American equine hospital networks is consolidating as independent practices face rising imaging equipment costs and specialist recruitment challenges. Zoetis Services LLC leverages its pharmaceutical portfolio to anchor preventive care contracts with large breeding farms in Kentucky and Florida. Merck Animal Health competes through vaccine development programs targeting equine influenza and West Nile virus. Boehringer Ingelheim International GmbH differentiates via its equine health diagnostics division, which supplies PCR testing platforms to referral hospitals.
Equine veterinary services encompass medical, surgical, and reproductive care delivered to horses by licensed veterinarians, typically requiring portable radiography units capable of 90-120 kVp output for field lameness examinations and reproductive ultrasound with 5-7 MHz transducers for follicular monitoring. These services support performance optimization in sport horses, genetic selection in breeding programs, and regulatory health certification for interstate and international movement. Diagnostic services now generate the strongest margin pools as imaging and laboratory testing displace empirical treatment, while telemedicine adoption accelerates among rural horse owners seeking specialist consultations without transport stress. Surgical services remain concentrated at referral institutions due to anesthesia recovery infrastructure requirements, with emergency care commanding premium pricing during foaling season peaks.
The FDA veterinary feed directive restricts over-the-counter antimicrobial use, compelling veterinary oversight for prescription medications and elevating preventive care service volumes. State veterinary practice acts, enforced by boards in Kentucky, California, and New York, govern ambulatory service licensing and telemedicine prescription authority, creating compliance complexity for multi-state operators. Stakeholders must monitor evolving USDA interstate movement health certificate digitization and state-level scope-of-practice debates that could reshape how mobile practitioners serve dispersed equine populations.
Market Dynamics
The FDA's veterinary feed directive has restructured antimicrobial prescribing authority, forcing veterinarians into gatekeeper roles while farms absorb elevated preventive care costs. This regulatory compression is concentrating service demand around diagnostic capabilities and telemedicine platforms that extend specialist reach without transport infrastructure.
Growth Catalysts
- Sport Horse Performance Optimization:FEI-sanctioned competition rules now mandate pre-event health certificates, expanding diagnostic service volumes at Kentucky and Wellington show circuits.
- PCR Platform Adoption:Real-time pathogen detection at point-of-care is replacing culture-based wait times, accelerating treatment decisions for infectious respiratory outbreaks.
- Thoroughbred Breeding Concentration:Central Kentucky's 450+ farms generate sustained reproductive service demand through synchronized breeding programs requiring daily follicular monitoring.
Market Restraints
- Imaging Equipment Cost Concentration:Portable digital radiography units exceeding 90 kVp output require capital outlays that strain independent practitioners in rural Montana and Wyoming.
- Specialist Geographic Clustering:Board-certified equine surgeons concentrate at six US academic hospitals, creating 400-mile service deserts for emergency colic surgery.
- Antimicrobial Substitution Constraints:Bacteriophage therapy and immunomodulators remain unproven for routine equine applications, limiting alternatives to restricted antibiotics.
Strategic Opportunities
- Telemedicine Regulatory Expansion:State veterinary boards in Texas and Florida are revising practice acts to permit prescription authority without prior physical examination.
- Reproductive Technology Convergence:OPU-ICSI protocols combined with genomic screening are creating premium service tiers for warmblood breeding operations seeking elite embryo transfer.
- Dubai Endurance Racing Growth:UAE federal equine health mandates are constructing veterinary infrastructure demand across Al Wathba and Seih Assalam training complexes.
Industry Challenges
- Anesthesia Recovery Infrastructure Gap:General practitioner practices lack padded recovery stalls and 24-hour monitoring capability required for insured surgical procedures.
- Telemedicine Licensing Fragmentation:Multi-state ambulatory operators face compliance complexity navigating divergent state board definitions of veterinarian-client-patient relationships.
- Specialist Recruitment Bottleneck:Residency positions in equine surgery and internal medicine fill at rates insufficient to replace retiring diplomates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equine Veterinary Services Market |
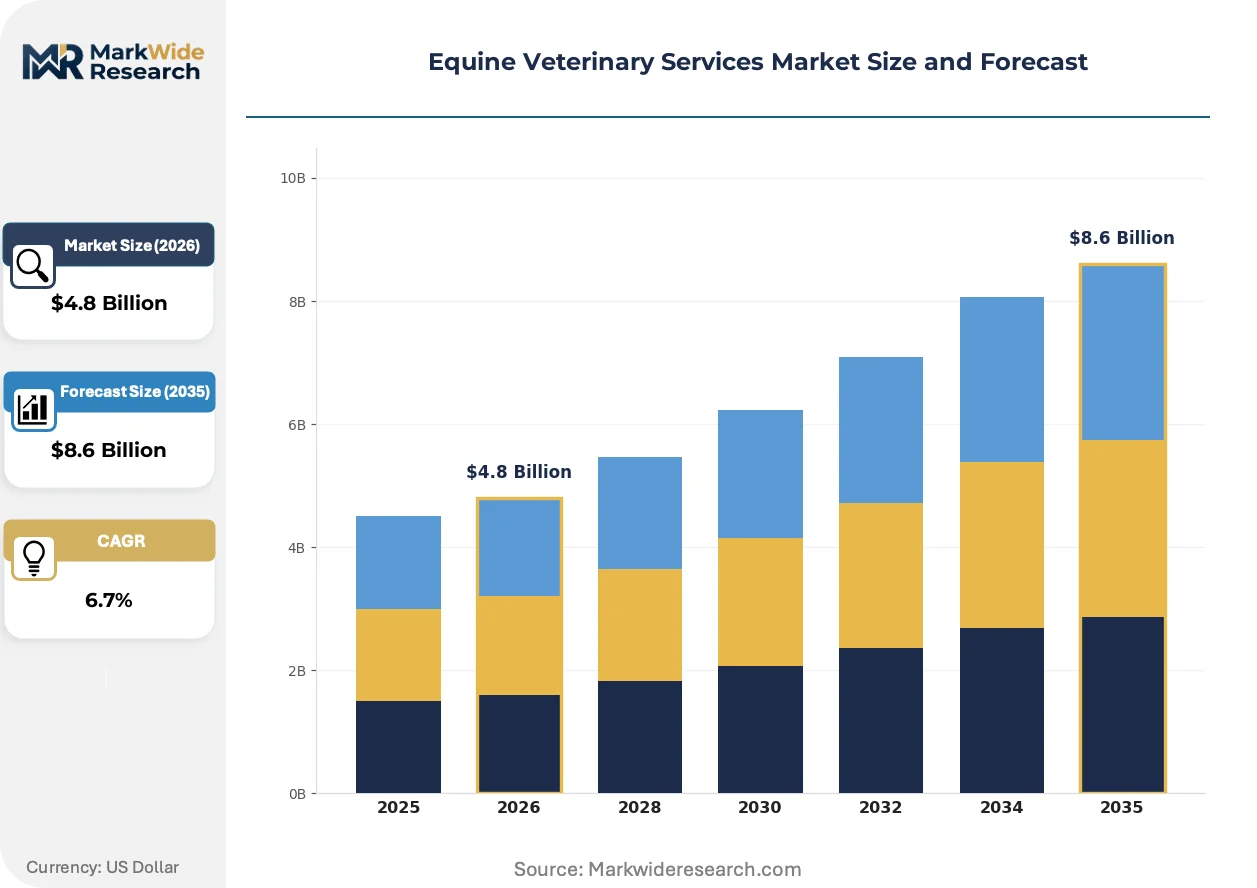
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Care, Surgical Services, Diagnostic Services, Emergency Care Technology: Telemedicine, Imaging Techniques, Anesthesia Equipment, Lab Testing Solutions End User: Horse Owners, Breeding Farms, Equine Clinics, Racing Organizations Animal Type: Sport Horses, Draft Horses, Miniature Horses, Ponies |
| Companies Covered | Zoetis Services LLC, Merck Animal Health, Boehringer Ingelheim International GmbH, IDEXX Laboratories, CVS Group plc, Elanco, Dechra, Hagyard Equine Medical Institute, Rood & Riddle Equine Hospital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equine Veterinary Services Market Emerging Trajectories
Diagnostic imaging and remote consultation platforms are compressing the traditional referral hierarchy, enabling field practitioners to retain cases previously lost to academic centers. This technological redistribution is reshaping service delivery economics across dispersed equine populations.
Portable wireless radiography systems with 100-meter transmission range are decentralizing lameness diagnosis from hospital-based specialists to ambulatory practitioners. Kentucky Derby trainers now demand same-day imaging at training barns, eliminating transport stress and time loss. This capability diffusion is compressing the geographic monopoly of university referral hospitals.
The FDA's veterinary feed directive tightened antimicrobial oversight, compelling veterinary prescription authority for previously over-the-counter medications. Kentucky breeding farms now maintain standing veterinary relationships for routine health maintenance rather than episodic emergency calls. This regulatory compression elevates preventive care service volumes while reducing empirical treatment.
Sport horse owners increasingly unbundle after-sales care from purchase transactions, selecting independent veterinarians over seller-recommended practitioners. Wellington show circuit participants source second-opinion lameness evaluations through digital teleradiology platforms. This buyer autonomy shift concentrates in high-value hunter-jumper segments where performance certification carries insurance implications.
Equine Veterinary Services Market Segmentation
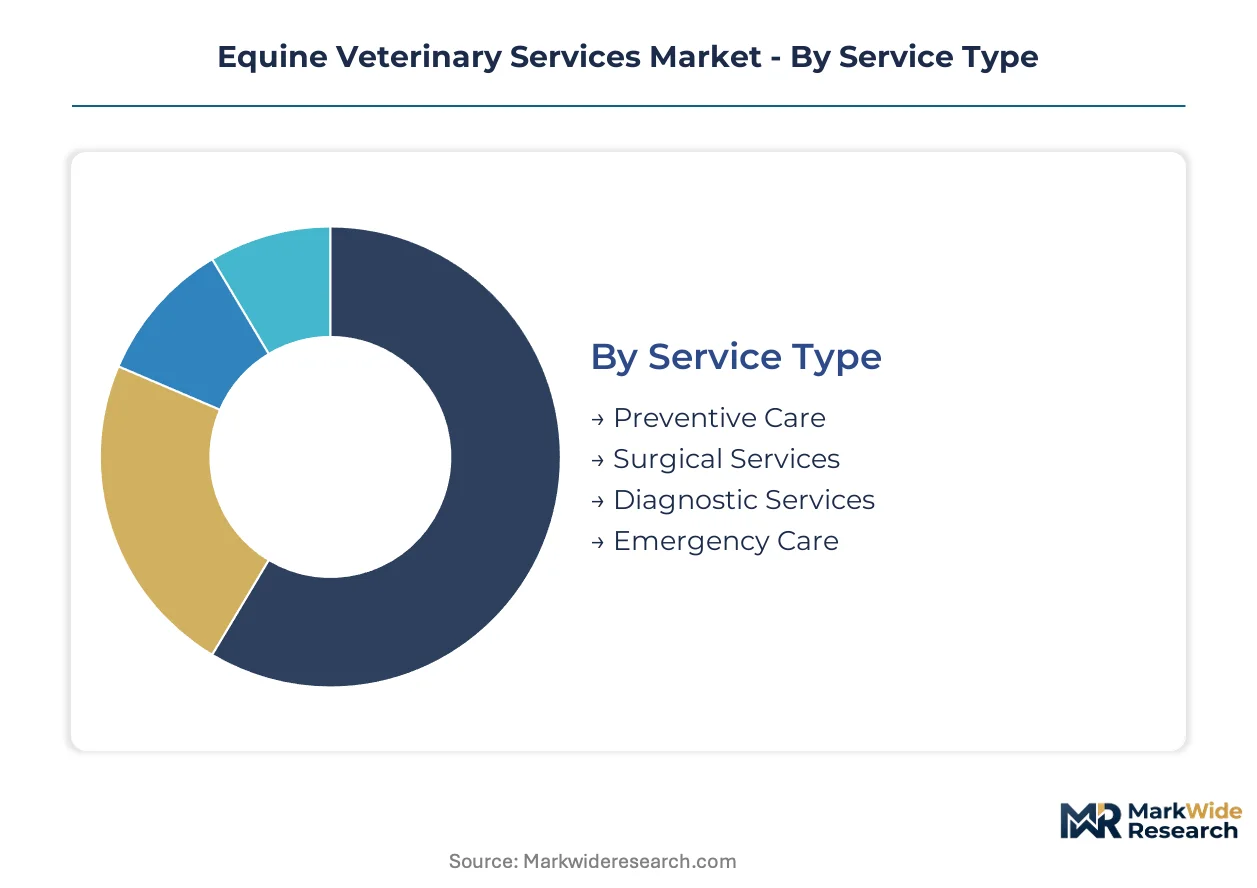
Service differentiation in equine veterinary care creates distinct margin profiles and capital requirements across delivery models. Segment boundaries blur as diagnostic capabilities migrate from referral hospitals to field practitioners, reshaping competitive positioning within each category.
Service Type:
Volume concentrates in routine preventive protocols, while premium pricing attaches to surgical interventions requiring specialized infrastructure.
- Diagnostic Services:Imaging and laboratory testing now displace empirical treatment as the primary revenue engine. Kentucky Derby trainers demand same-day portable radiography at training barns, compressing the traditional referral hierarchy. FEI-sanctioned competition rules mandate pre-event health certificates, expanding service volumes at Wellington and Kentucky show circuits.
- Preventive Care:FDA veterinary feed directive compliance elevated veterinary oversight from episodic emergency response to standing farm relationships. Central Kentucky's 450+ breeding farms generate sustained demand through synchronized breeding programs requiring daily follicular monitoring and routine health maintenance.
- Surgical Services:Anesthesia recovery infrastructure requirements concentrate procedures at six US academic hospitals, creating 400-mile service deserts for emergency colic intervention.
- Emergency Care:Foaling season peaks command premium pricing, with after-hours callouts generating disproportionate margin contribution for ambulatory practices.
Today's leader: Preventive Care. Tomorrow's challenger: Diagnostic Services.
Technology:
Capital intensity separates field-deployable platforms from hospital-anchored systems, with wireless connectivity enabling geographic redistribution of specialist expertise.
- Imaging Techniques:Portable digital radiography units with 90-120 kVp output and 100-meter wireless transmission range decentralize lameness diagnosis from university referral centers to ambulatory practitioners. Kentucky and Florida sport horse operations now retain cases previously lost to academic hospitals.
- Telemedicine:Real-time specialist consultation platforms extend board-certified expertise to rural populations without transport stress. State veterinary boards in Texas and Florida are revising practice acts to permit prescription authority without prior physical examination, accelerating platform adoption.
- Lab Testing Solutions:PCR platforms at point-of-care replace culture-based wait times, accelerating treatment decisions for infectious respiratory outbreaks at breeding farms.
- Anesthesia Equipment:Recovery stall infrastructure requirements limit general practitioner participation, maintaining surgical concentration at referral institutions.
Imaging Techniques commands current investment flows. Telemedicine holds the steepest expansion trajectory as regulatory barriers dissolve.
End User:
Customer sophistication and animal inventory scale determine service bundling preferences and price elasticity.
- Breeding Farms:Central Kentucky's concentrated Thoroughbred operations generate predictable, high-frequency reproductive service demand. Synchronized breeding programs require daily follicular monitoring through 5-7 MHz transducer ultrasound, creating captive revenue streams for established veterinary relationships.
- Racing Organizations:Dubai's Al Wathba and Seih Assalam training complexes drive infrastructure investment under UAE federal equine health mandates. Kentucky and Dubai operations are expanding veterinary budgets specifically for pre-race diagnostics.
- Equine Clinics:Referral institutions compete on specialist availability and imaging throughput, facing consolidation pressure from rising equipment costs.
- Horse Owners:Sport horse participants increasingly unbundle after-sales care from purchase transactions, selecting independent practitioners over seller-recommended veterinarians.
Breeding Farms anchor current revenue stability. Racing Organizations are gaining share fastest as international competition intensifies.
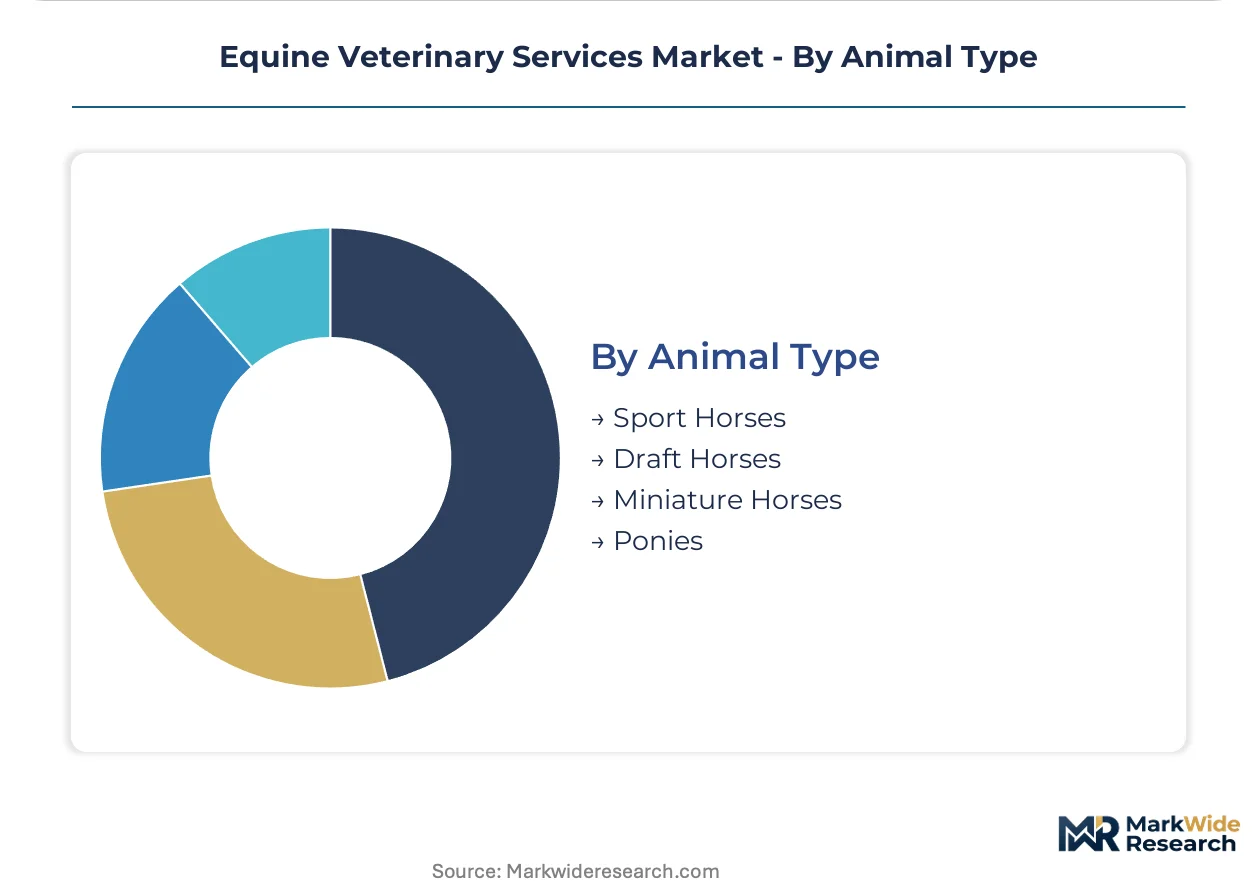
Animal Type:
Performance optimization requirements and insurance valuation create tiered service intensity across equine categories.
- Sport Horses:Hunter-jumper and dressage segments command premium lameness screening and performance certification. Wellington show circuit participants source second-opinion evaluations through digital teleradiology platforms, with insurance implications driving diagnostic thoroughness.
- Draft Horses:Agricultural and exhibition applications generate routine preventive demand with lower imaging intensity than performance breeds.
- Ponies:Youth competition segments create entry-level service relationships that migrate to full-size horse care as participants advance.
- Miniature Horses:Companion and exhibition niches generate episodic demand with limited surgical intervention requirements.
Sport Horses dominate premium service tiers. Ponies represent the deepest untapped lifetime value pool through participant progression pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping service delivery geography as practitioners migrate toward jurisdictions with streamlined telemedicine prescription authority and lower compliance burdens. The FDA's veterinary feed directive created compliance cost differentials that favor established veterinary relationships in states with flexible practice act interpretations.
United States
Kentucky's concentrated Thoroughbred breeding operations generate sustained demand for reproductive and lameness services across 450+ farms. The FDA veterinary feed directive elevated veterinary oversight requirements, compelling standing farm relationships rather than episodic emergency calls. Central Kentucky's equine medical corridor anchors specialist clustering around Lexington and Louisville referral hospitals.
United Arab Emirates
Federal equine health mandates under MOHAP jurisdiction are constructing veterinary infrastructure demand across Dubai's Al Wathba and Seih Assalam training complexes. Endurance racing growth drives pre-race diagnostic service expansion with premium pricing for international competition compliance. Abu Dhabi's equine regulatory framework attracts veterinary specialists through streamlined licensing reciprocity.
Germany
The EMA's veterinary medicinal product regulations shape antimicrobial prescribing protocols across Baden-Württemberg and Lower Saxony breeding regions. FEI-sanctioned competition density in Warendorf and Aachen generates sport horse lameness screening demand with insurance-linked diagnostic thoroughness. Bavarian warmblood breeding operations are adopting OPU-ICSI protocols for elite embryo transfer services.
United Kingdom
Newmarket's concentrated Thoroughbred industry sustains high-frequency veterinary relationships through the Jockey Club's regulatory health certification requirements. The RCVS practice standards framework governs telemedicine prescription authority, creating compliance complexity for cross-border practitioners serving Irish and French racing operations. Suffolk and Cambridgeshire host the densest specialist surgical capacity outside London referral centers.
Australia
The APVMA's veterinary chemical regulations govern antimicrobial access across New South Wales and Victoria racing jurisdictions. Spring Racing Carnival demand concentrates veterinary diagnostic services in Melbourne's Flemington corridor. Queensland's expanding Thoroughbred breeding sector in the Darling Downs is attracting ambulatory practitioners through seasonal reproductive service contracts.
Equine Veterinary Services Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue telemedicine platform specialization and point-of-care diagnostic decentralization. The market structure concentrates around pharmaceutical-anchored service contracts and independent referral hospital networks, with equipment cost barriers fragmenting ambulatory practitioner scale. Three archetypes dominate: multinational animal health conglomerates with pharmaceutical portfolios, independent academic-affiliated referral hospitals, and technology-enabled ambulatory platforms. Competitive moves center on diagnostic equipment leasing partnerships and multi-state telemedicine licensing consolidation.
Among pharmaceutical-anchored service providers, Zoetis Services LLC and Merck Animal Health exemplify the conglomerate archetype through preventive care contract structures with large breeding operations. Boehringer Ingelheim International GmbH occupies a diagnostics-focused position within this tier. IDEXX Laboratories represents the laboratory and imaging technology vector that enables field practitioner capability expansion. These entities anchor competitive positioning through differentiated access to either pharmaceutical formularies, diagnostic platforms, or specialist referral networks rather than direct service delivery scale.
| Leading Market Players |
|---|
| Zoetis Services LLC |
| Merck Animal Health |
| Boehringer Ingelheim International GmbH |
| IDEXX Laboratories |
| CVS Group plc |
| Elanco |
| Dechra |
| Hagyard Equine Medical Institute |
| Rood & Riddle Equine Hospital |
| Others |
Supply Flow & Price Mechanics
The FDA's veterinary feed directive gates qualified supply access and premium-tier pricing power by compelling veterinary prescription authority for previously over-the-counter antimicrobials. Kentucky breeding farms now absorb elevated preventive care costs through standing veterinary relationships, while ambulatory practitioners face capital barriers to imaging equipment that stratifies service tiers.
Pricing Analysis
Direct-to-farm contract pricing dominates service delivery, with three-tier pricing structure across premium, standard, and economy levels differentiated by specialist certification and equipment capability. Price differentiation hinges on board-certified surgeon availability and portable radiography unit specifications. Cost compression in standard-tier ambulatory services is intensifying because independent practitioners struggle with 90-120 kVp equipment financing. Racing organizations show least price sensitivity; rural hobby horse owners exhibit greatest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese manufacturers of high-frequency ultrasound transducers and digital radiography sensors. Imaging equipment supply concentrates in Germany, Japan, and the United States, with PCR platform production anchored in the United States and Switzerland. Raw material dependencies include rare earth elements for sensor arrays, specialized optical glass, and veterinary pharmaceutical active ingredients. Tariff exposure runs through imaging component imports. Distribution runs through manufacturer-direct sales to referral hospitals and equipment leasing networks serving ambulatory practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Kentucky's concentrated breeding demand and Texas's evolving telemedicine prescription authority, where regulatory cost differentials favor multi-state operators with flexible practice act compliance.
For Market Incumbents: Cement diagnostic equipment leasing partnerships with ambulatory practitioners to lock in recurring revenue streams against emerging telemedicine platforms. Anchor backward integration into PCR testing platforms to capture laboratory margin pools that independent practitioners currently outsource. Board-certified specialist recruitment bottlenecks threaten service capacity; expand residency pipeline investments at Lexington and Louisville academic hospitals.
For New Entrants and Emerging Players: Telemedicine platform licensing offers the lowest barrier route into sport horse segments where Wellington circuit participants already seek second-opinion lameness evaluations digitally. Target Montana and Wyoming service deserts where 400-mile gaps separate emergency colic surgery access. Pursue white-label diagnostic imaging partnerships with Kentucky Derby training barns seeking same-day portable radiography without transport stress.
For Investors and Strategic Acquirers: Roll-up economics work for independent ambulatory practices because equipment cost barriers prevent organic scale and owner-operators face succession gaps without exit alternatives. Acquire clusters in Central Kentucky and Florida's Ocala corridor where breeding farm density supports predictable cash flows. Watch Texas and Florida state veterinary board rulings on telemedicine prescription authority as the inflection signal for platform-enabled practice valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Licensing | Extends specialist reach to rural Montana and Wyoming populations without infrastructure investment. |
| Diagnostic Equipment Leasing Partnerships | Lowers capital barriers for independent practitioners competing with university referral hospitals. |
| Residency Pipeline Expansion | Addresses board-certified surgeon shortages threatening emergency colic surgery capacity. |
| PCR Platform Backward Integration | Captures laboratory margin pools from infectious respiratory outbreak testing at breeding farms. |
| Multi-State Practice Consolidation | Reduces compliance complexity from divergent state veterinary board telemedicine definitions. |
Methodological Framework
Coverage spans North America, Europe, Middle East, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with equine veterinary practitioners, breeding farm managers, referral hospital administrators, and pharmaceutical regulatory affairs specialists informed demand-side dynamics. Secondary sources include FDA veterinary feed directive filings, USDA interstate movement health certificate digitization records, state veterinary practice act databases, and FEI competition rule amendments. Bottom-up service volume estimates triangulated against top-down pharmaceutical and equipment sales data.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions modeled include service type, technology platform, end-user category, and animal type, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporate breeding farm synchronization program expansion rates and telemedicine platform penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for portable wireless radiography would alter the outlook if transmission range capabilities exceed 100-meter specifications or if battery life improvements accelerate field deployment. Forecasts reflect assumptions about FDA enforcement continuity, state board telemedicine liberalization, and specialist residency fill rates. Disease outbreak frequency, antimicrobial resistance patterns, and insurance reimbursement shifts for sport horse diagnostics constitute revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Mouth Spray Market
Healthcare
Respiratory Measurement Devices Market
Healthcare
France Oral Anti-Diabetic Drug Market
Healthcare
Adsorption Apheresis Devices Market
Healthcare
US Dental Chains Market
Healthcare
Spain Digital Radiology Market
Healthcare
US Hyperbaric Oxygen Therapy (HBOT) Market
Healthcare
Asia Pacific Surgical Equipment Market
Healthcare
Wearable Atrial Fibrillation Detection Devices Market
Healthcare
Inhaled Nitric Oxide Market
Healthcare
Orthodontic Retainers Market
Healthcare
Spinal Implants and Devices Market
Healthcare
Sperm Separation Systems Market
Healthcare
Haematocrit Centrifuge Market
Healthcare
North America Oxygen Concentrators Market
Healthcare
At-Home Testing Market