
 Panoramic and Cephalometric Radiography Systems Market | 2026-2036
Panoramic and Cephalometric Radiography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Panoramic and Cephalometric Radiography Systems Market Analysis
China is tilting toward domestic manufacturing of flat panel detectors and sensor arrays for panoramic units. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to sustain premium positioning across European dental chains. Planmeca Oy anchors Nordic market share through proprietary open-architecture software that interoperates with third-party practice management platforms.
Panoramic and cephalometric radiography systems are extraoral imaging platforms that rotate an X-ray source and detector around a patient's head to capture single-plane or dual-plane views of dentition, maxillofacial bones, and temporomandibular joints, typically operating at tube voltages between 60-90 kV with exposure times under 20 seconds. These systems serve orthodontists, oral surgeons, and implantologists requiring low-radiation-dose diagnostic imagery for treatment planning and post-operative assessment. Digital radiography dominates installed base value due to replacement cycles of aging analog fleets across mature markets, while cone beam technology commands the fastest expansion trajectory as clinicians demand volumetric data for guided implantology. Hybrid systems that merge panoramic, cephalometric, and limited-field CBCT functionality concentrate margin pools by reducing capital expenditure per chair for mid-size dental groups.
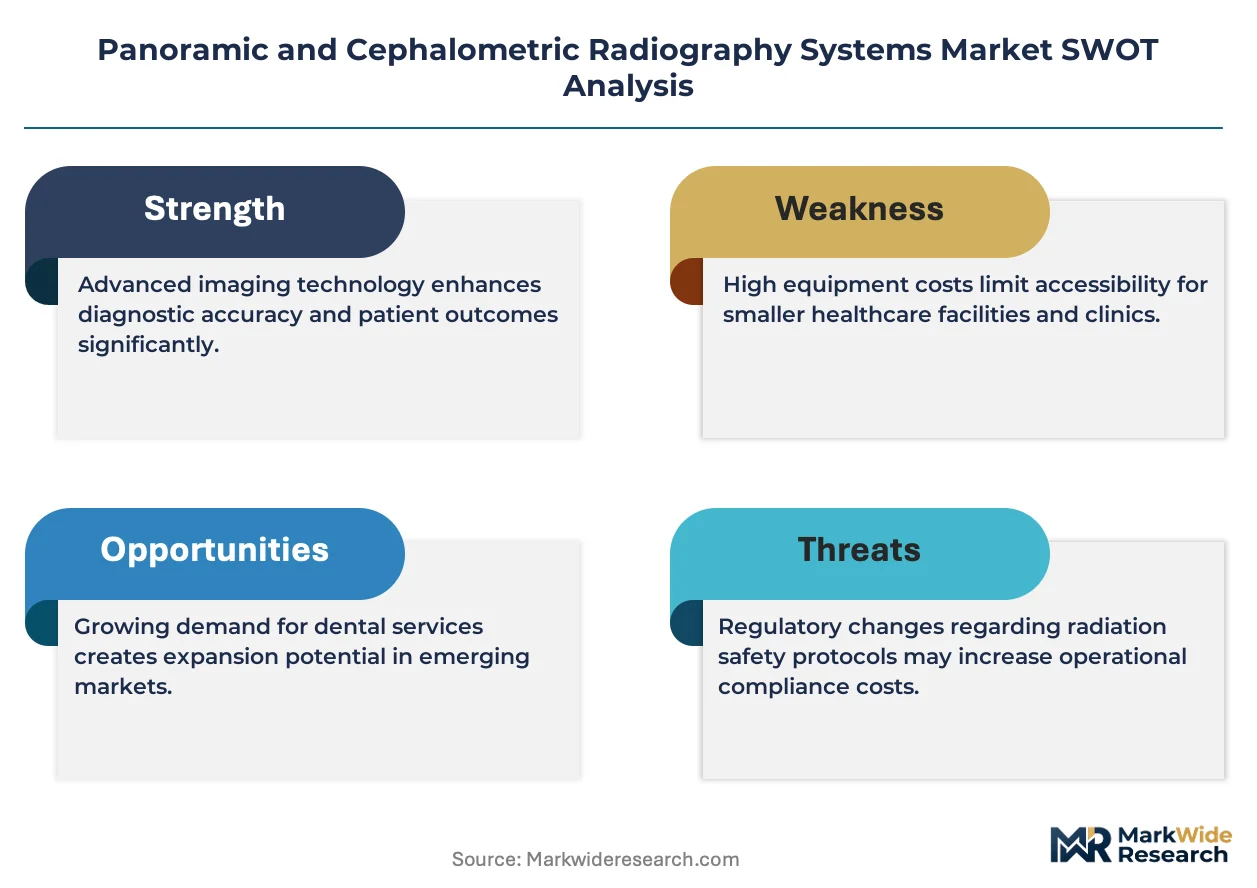
FDA 510(k) clearance pathways shape product launch sequencing for manufacturers targeting the United States, while EU MDR technical documentation requirements extend certification timelines and raise quality management system costs for CE-marked devices. Japan's PMDA enforces distinct electromagnetic compatibility and radiation safety protocols that necessitate localized hardware modifications for market entry. Stakeholders must monitor evolving ALARA-based dose reference levels from national radiological protection boards and assess whether software-as-a-service imaging analytics can offset hardware margin compression.
Market Dynamics
Cone beam computed tomography is virtualizing diagnostic workflows across orthodontic and implantology practices, compressing replacement cycles for legacy panoramic units while elevating software and service attach rates for hardware vendors.
Growth Catalysts
- EU MDR Compliance Mandates:Germany's dental clinic chains are expanding digital imaging suites to meet technical documentation requirements, accelerating analog-to-digital replacement demand.
- Flat Panel Detector Localization:China's domestic manufacturing push for sensor arrays is reducing import dependency and expanding accessible price tiers for panoramic systems.
- Guided Implantology:Oral surgeons now require volumetric data for surgical navigation, pulling hybrid CBCT-panoramic systems into mid-size group practices.
Market Restraints
- Xenon Shortage in Tube Manufacturing:Geopolitical concentration of noble gas refining in Eastern Europe creates input cost volatility for X-ray source producers.
- EU MDR Certification Timelines:Extended technical documentation review periods delay product launches by 12-18 months for CE-marked devices.
- Intraoral Scanner Substitution:High-resolution digital impressions for orthodontic planning reduce cephalometric radiograph frequency in select cases.
Strategic Opportunities
- Brazil's Private Orthodontic Sector:Cone beam technology penetration remains below 35% in independent practices outside São Paulo and Rio de Janeiro corridors.
- Software-as-a-Service Imaging Analytics:Cloud-based AI diagnostic tools create recurring revenue streams offsetting hardware margin compression.
- Japan's PMDA Localization:Electromagnetic compatibility and radiation safety protocol adaptations open entry pathways for compliant manufacturers.
Industry Challenges
- Medical Physics Talent Scarcity:Qualified radiation safety officers for ALARA compliance are concentrated in urban hospital systems, limiting rural clinic expansion.
- Legacy PACS Integration Complexity:Open-architecture software requirements force costly middleware development for third-party practice management connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panoramic and Cephalometric Radiography Systems Market |
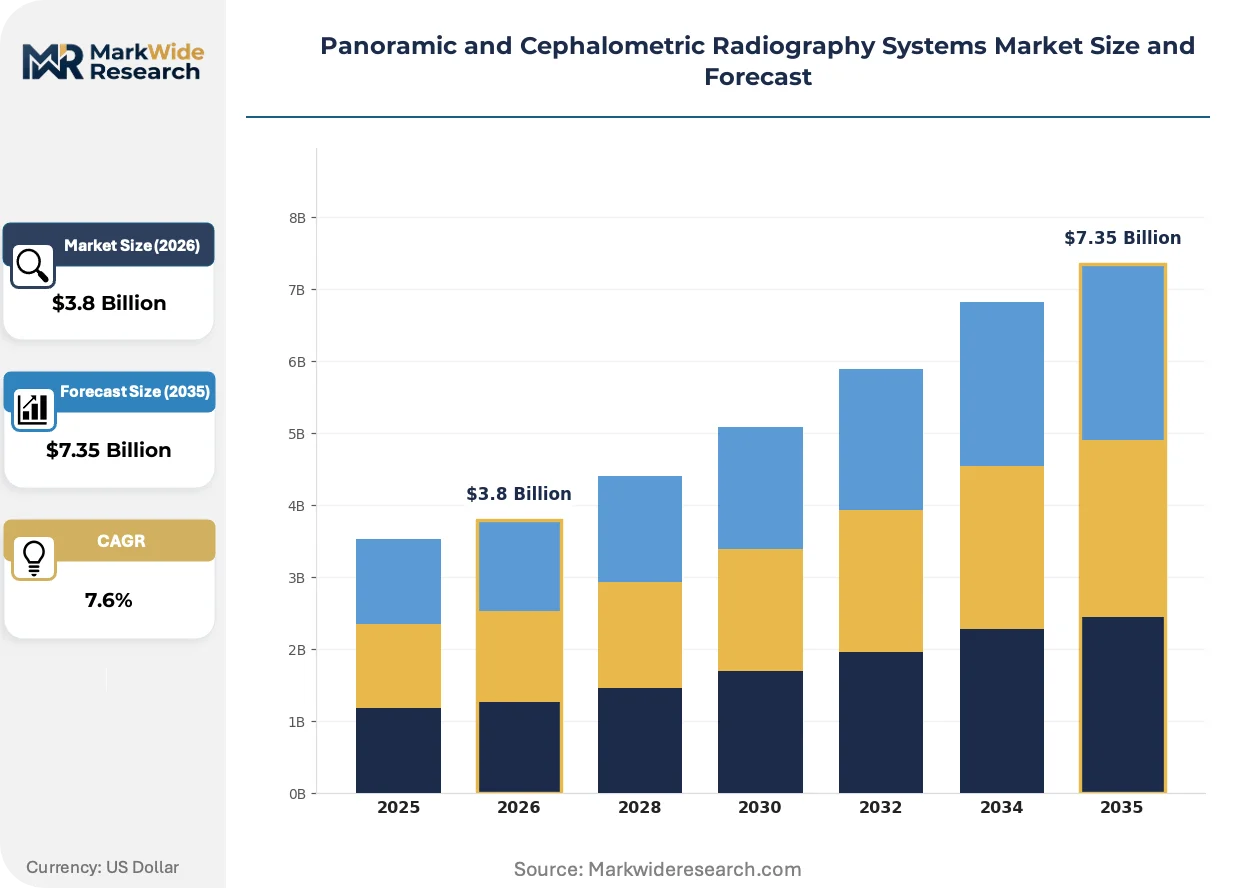
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Radiography, Analog Radiography, 3D Imaging, Hybrid Systems Application: Orthodontics, Oral Surgery, Implantology, Dental Diagnosis End User: Dental Clinics, Hospitals, Research Laboratories, Educational Institutions Technology: Computed Radiography, Direct Radiography, Cone Beam Technology, Flat Panel Detectors |
| Companies Covered | Dentsply Sirona, Envista Holdings Corporation, Planmeca Oy, Carestream Dental LLC, VATECH, ACTEON, Owandy Radiology Inc., Genoray Co., Ltd., Asahi Roentgen Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panoramic and Cephalometric Radiography Systems Market Emerging Trajectories
Artificial intelligence inference engines are embedding directly into panoramic system firmware, enabling real-time anatomical landmark detection and automated cephalometric tracing without external workstation dependency.
Photon-counting detector technology is virtualizing image acquisition protocols by distinguishing tissue density at the photon level rather than integrating total energy deposition. Implantologists in Nordic countries are adopting these sensors for 40% dose reduction in pre-operative assessments. The structural consequence is compressing demand for iterative exposure techniques and legacy scintillator-based flat panels.
FDA 510(k) clearance pathways are tightening predicate device equivalence standards for AI-enabled radiography software, extending submission preparation timelines. Manufacturers targeting the United States must now submit standalone algorithm validation datasets separate from hardware filings. Dental chains with multi-site standardization mandates are delaying procurement decisions until dual FDA-CE marking is secured.
Subscription-based equipment procurement is displacing capital purchase models among dental service organizations managing 50-plus chair networks. Leasing structures bundle hardware, software licenses, and preventive maintenance into per-exposure fees. This shift is most visible in Germany's corporatized dental sector, where balance sheet optimization outweighs long-term ownership preferences.
Panoramic and Cephalometric Radiography Systems Market Segmentation
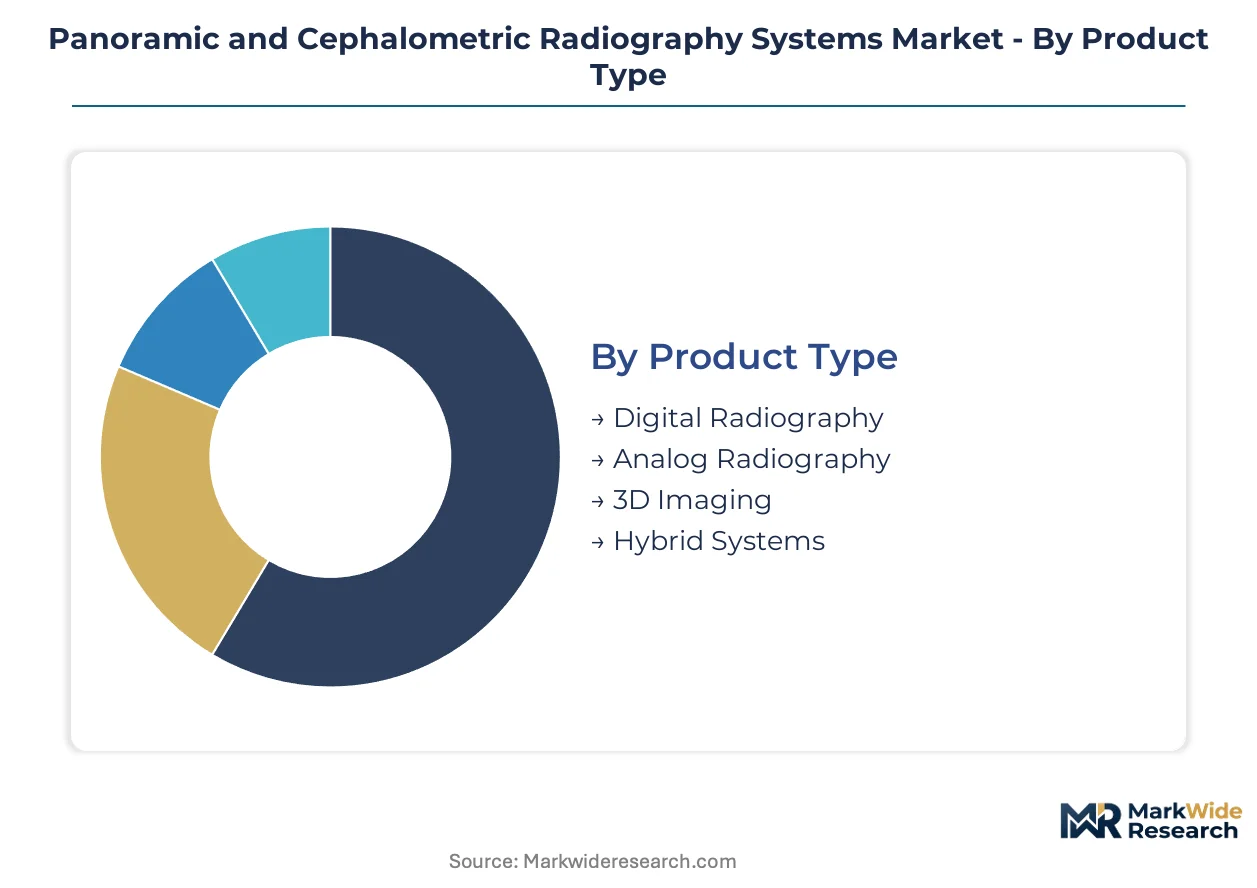
Segmentation in panoramic and cephalometric radiography systems reveals distinct replacement cadences across hardware generations and divergent software attach rates by clinical setting. Understanding these cycle-time differentials enables vendors to align R&D roadmaps with revenue concentration points.
Product Type:
Digital radiography systems turn over fastest at 5-7 year cycles, while analog installations persist 12-15 years in cost-constrained markets, creating asynchronous demand waves across installed base vintages.
- Digital Radiography:Flat panel detector systems with immediate image rendering and DICOM-native output dominate replacement demand in EU MDR-compliant clinic chains. German dental groups prioritize these units for ALARA dose documentation and seamless PACS integration.
- Hybrid Systems:Combined panoramic-cephalometric-CBCT platforms reduce capital expenditure per chair for mid-size dental groups while capturing premium pricing through software-enabled surgical navigation. Demand concentrates in US and Brazilian implantology practices seeking volumetric data without dedicated CBCT suites.
- 3D Imaging:Cone beam computed tomography units with limited field-of-view options serve orthodontic practices requiring craniofacial reconstruction.
- Analog Radiography:Film-based systems persist in rural clinics and emerging markets with limited digital infrastructure.
Digital radiography anchors the volume base while hybrid systems gain share at the steepest rate.
Application:
Cost tier stratification separates high-volume orthodontic screening from premium-priced surgical navigation, with implantology commanding the steepest software and service attach rates.
- Implantology:Guided surgery protocols require sub-millimeter accuracy in bone density mapping, pulling hybrid CBCT systems into private practices. Nordic countries lead adoption of photon-counting detectors for pre-operative assessments.
- Orthodontics:Cephalometric analysis for treatment planning drives recurring software license demand, though intraoral scanner substitution compresses radiograph frequency in select adolescent cases.
- Oral Surgery:Temporomandibular joint imaging and trauma assessment utilize panoramic baselines with CBCT escalation for complex cases.
- Dental Diagnosis:General screening applications prioritize throughput and dose minimization over specialized functionality.
Orthodontics anchors the volume base while implantology climbs the fastest on software-enabled procedure premiums.
End User:
Customer type determines procurement modality, with dental service organizations favoring subscription structures and academic centers requiring research-grade calibration protocols.
- Dental Clinics:Independent and corporatized practices represent the primary installed base, with German chains expanding digital suites under EU MDR mandates and Brazilian private orthodontics driving cone beam penetration outside São Paulo corridors.
- Hospitals:Maxillofacial departments integrate panoramic systems into broader imaging departments with centralized radiation safety officer oversight.
- Research Laboratories:Craniofacial morphology studies require calibrated systems with raw data export capabilities.
- Educational Institutions:Dental schools balance training needs against budget constraints, often extending replacement cycles.
Dental clinics anchor the volume base while hospitals expand most quickly on integrated department mandates.
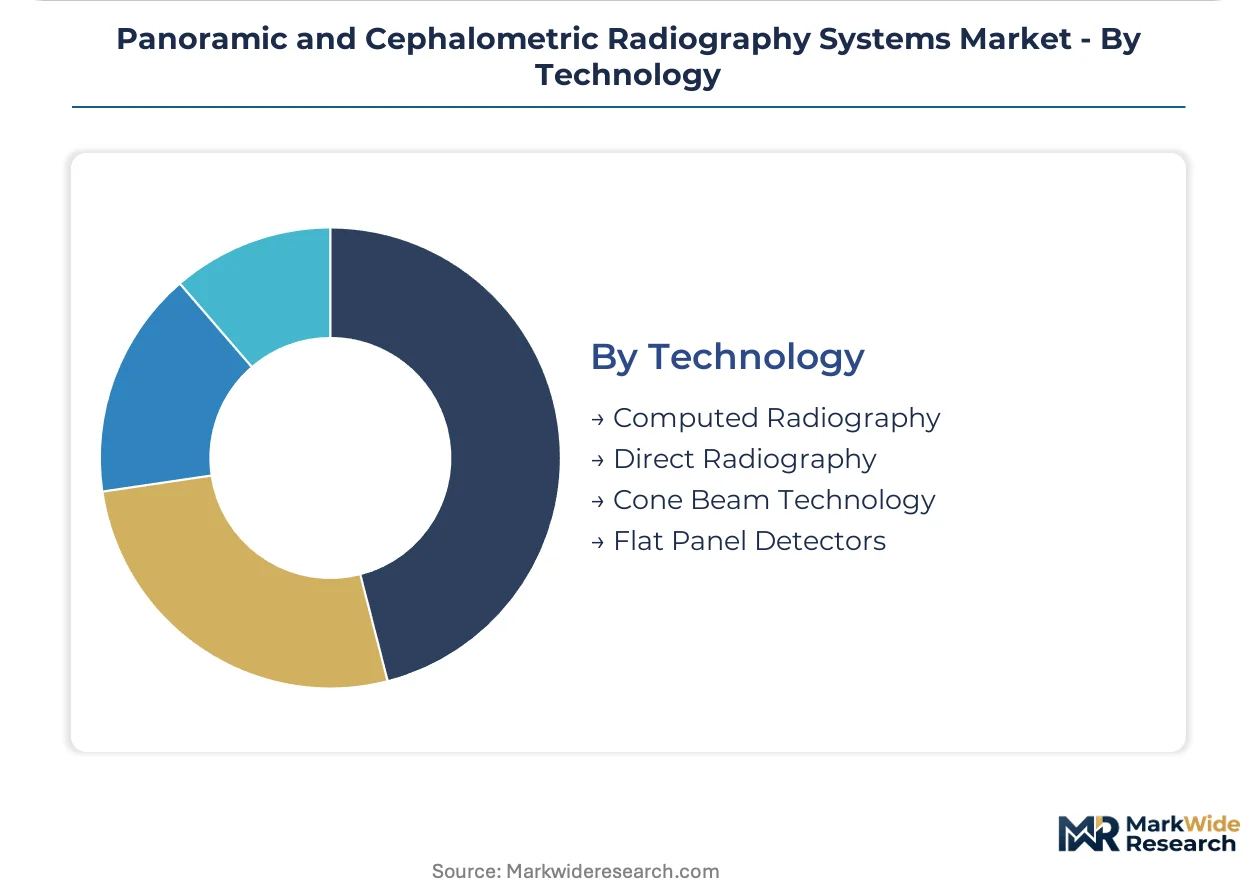
Technology:
Supply concentration in flat panel detector manufacturing shapes margin distribution, with direct radiography capturing value from scintillator-based alternatives.
- Flat Panel Detectors:Amorphous silicon and CMOS sensor arrays enable immediate image acquisition without cassette handling. China's domestic manufacturing push reduces import dependency and expands accessible price tiers.
- Cone Beam Technology:Volumetric reconstruction algorithms compress diagnostic workflows for implantologists and oral surgeons, elevating hardware-software bundle pricing.
- Direct Radiography:Solid-state detectors with direct charge conversion offer improved dose efficiency over indirect scintillator approaches.
- Computed Radiography:Photostimulable phosphor plate systems persist as transitional technology in partially digitized practices.
Flat panel detectors anchor the volume base while cone beam technology expands most quickly on clinical workflow virtualization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's distribution corridor for Nordic-manufactured imaging equipment into Central European dental chains.
United States
FDA 510(k) clearance pathways compress product launch sequencing for panoramic system manufacturers targeting orthodontic practices. The agency's tightening predicate device equivalence standards for AI-enabled software extend submission preparation timelines. Dallas-Fort Worth dental service organizations drive subscription-based equipment procurement across 50-plus chair networks.
Germany
EU MDR technical documentation requirements accelerate analog-to-digital replacement cycles in corporatized dental clinic chains. The country's national pharmaceutical regulator enforces extended certification timelines that raise quality management system costs for CE-marked devices. Bavarian dental groups prioritize flat panel detector systems for ALARA dose documentation and PACS integration.
China
Domestic manufacturing of flat panel detectors and sensor arrays reduces import dependency for panoramic unit production. The national medical products administration supports localization through GB standards alignment for electromagnetic compatibility. Yangtze River Delta fabrication clusters expand accessible price tiers for digital radiography systems.
Brazil
Private orthodontic practices outside São Paulo and Rio de Janeiro corridors drive cone beam technology penetration below 35% market saturation. ANVISA registration requirements shape product adaptation for Latin American voltage and humidity conditions. Minas Gerais implantology clinics pull hybrid CBCT-panoramic systems into mid-size group practices.
Japan
PMDA electromagnetic compatibility and radiation safety protocols necessitate localized hardware modifications for panoramic system market entry. METI industrial policy supports photon-counting detector adoption for 40% dose reduction in pre-operative assessments. Osaka-Kobe dental equipment distributors anchor premium-tier import channels for Nordic and German manufacturers.
Panoramic and Cephalometric Radiography Systems Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in detector arrays and tube manufacturing. The vendor base concentrates around dental conglomerates with imaging portfolios and regional specialists with open-architecture software differentiation. Three archetypes dominate: full-suite platform vendors, hybrid hardware-software bundlers, and component OEMs supplying detector technology. Consolidation pressure intensifies through strategic partnerships for AI diagnostic modules and vertical integration into flat panel detector supply.
Within the Nordic specialist tier, Planmeca Oy anchors open-architecture positioning through proprietary software interoperability. Dentsply Sirona occupies the integrated CAD/CAM ecosystem vector across European dental chains. VATECH exemplifies the Asia-Pacific platform archetype with regional manufacturing scale. These three represent distinct competitive vectors: software openness, vertical integration depth, and geographic production proximity.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista Holdings Corporation |
| Planmeca Oy |
| Carestream Dental LLC |
| VATECH |
| ACTEON |
| Owandy Radiology Inc. |
| Genoray Co., Ltd. |
| Asahi Roentgen Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
The Port of Hamburg anchors Germany's distribution corridor for Nordic-manufactured imaging equipment, with freight cost fluctuations compressing margins on premium-tier systems while enabling price differentiation between EU MDR-certified and legacy analog units across Central European dental chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates photon-counting detector systems from flat panel configurations and legacy scintillator-based alternatives. Certification grade under EU MDR and FDA 510(k) pathways drives substantial price spreads, with dual-marked devices commanding 15-20% premiums over single-jurisdiction equivalents. Cost compression in economy tiers intensifies as Chinese domestic manufacturing expands accessible price points. Dental service organizations exhibit lowest price sensitivity due to subscription-based procurement models, while independent rural clinics remain most cost-constrained.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for flat panel detector procurement, with supply-chain finance facilities increasingly prevalent among Nordic and German component vendors. Manufacturing concentrates in Finland, Germany, and South Korea for sensor arrays, while X-ray tube production draws from Japanese and German specialists. Xenon gas refining dependencies in Eastern Europe create single-source vulnerability for high-output tube assemblies. Distribution runs through regional dental equipment distributors with direct-to-clinic service contracts dominating aftermarket revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified radiation safety officers for ALARA compliance remain concentrated in urban hospital systems, creating a talent bottleneck that constrains rural clinic expansion and shapes competitive positioning for vendors with embedded physics expertise.
For Market Incumbents: Pre-empt intraoral scanner substitution by embedding AI-powered cephalometric tracing directly into panoramic system firmware, eliminating external workstation dependency. Capture margin pools through backward integration into flat panel detector supply chains, reducing exposure to Chinese import tariff volatility. Prioritize EU MDR technical documentation completion ahead of competitors to secure 12-18 month first-mover advantage in German clinic chain procurement cycles. For New Entrants and Emerging Players: Mid-size implantology practices in Brazil's Minas Gerais and Northeast corridors represent the most penetrable entry point, with cone beam penetration below 35% outside São Paulo and Rio de Janeiro. Software-as-a-service imaging analytics for orthodontic treatment planning offers recurring revenue traction without capital-intensive hardware manufacturing. Partner with established Nordic or German manufacturers for private-label distribution to bypass ANVISA registration complexity. For Investors and Strategic Acquirers: Component OEMs with captive flat panel detector technology and open-architecture software stacks present optimal acquisition profiles for platform consolidation plays. Long-term viability hinges on AI diagnostic module integration and subscription revenue attach rates exceeding hardware depreciation cycles. Monitor FDA 510(k) clearance velocity for AI-enabled software as inflection indicator for vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Adoption | Nordic implantology practices achieve 40% dose reduction in pre-operative bone density assessments. |
| EU MDR Certification Acceleration | German dental chains prioritize ALARA-compliant digital suites for technical documentation requirements. |
| Software-as-a-Service Imaging Analytics | Cloud-based AI diagnostic tools create recurring revenue streams offsetting hardware margin compression. |
| Subscription-Based Equipment Procurement | German dental service organizations optimize balance sheets through per-exposure fee structures. |
| Domestic Manufacturing Localization | China's Yangtze River Delta clusters reduce import dependency for sensor array production. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, dental clinic procurement managers, GPO contracts managers, and radiation safety officers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data. Bottom-up installed base modeling triangulated with top-down market sizing across product type, application, end user, and technology segmentation dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning digital-hybrid-analog product tiers, implantology-orthodontics-oral surgery applications, and clinic-hospital-research end user categories. CAGRs derived from replacement cycle analysis, technology diffusion curves, and regulatory compliance acceleration effects. Forecast inputs incorporated EU MDR certification timeline delays and photon-counting detector adoption trajectories.
Practitioners should monitor FDA predicate device equivalence standard tightening and xenon supply chain disruptions for early signals of competitive repositioning. Forecasts reflect assumptions of continued ALARA dose reduction mandates and stable reimbursement for guided implantology procedures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Cephalometric X-Ray System Market
Medical Imaging
Mobile Tomography Market