
 United States Infrared Sauna Market | 2026-2036
United States Infrared Sauna Market Size, Share, and Industry Trends Forecast 2026-2036
United States Infrared Sauna Market Insights
Multi-source component procurement is expanding across the United States infrared sauna supply base as manufacturers diversify beyond single-origin carbon fiber panel suppliers. Sunlighten leverages vertical integration in heater design to sustain premium positioning, while Clearlight Saunas competes through rigorous third-party EMF testing protocols. JNH Lifestyles anchors its market presence via direct-to-consumer channel control and aggressive online pricing.
An infrared sauna employs far-infrared, mid-infrared, and near-infrared wavelengths—typically generated by carbon fiber or ceramic heaters operating between 110°F and 140°F—to induce sweat at lower ambient temperatures than traditional steam saunas. Its primary commercial purpose centers on detoxification support, cardiovascular stress simulation, and muscle recovery applications in both residential and clinical settings. Indoor installations dominate volume due to space efficiency and climate control advantages, while carbon fiber heating technology leads on energy efficiency metrics and operational longevity. Portable units represent the fastest-growing structural segment, capturing apartment-dwelling wellness enthusiasts and travel-oriented health practitioners.
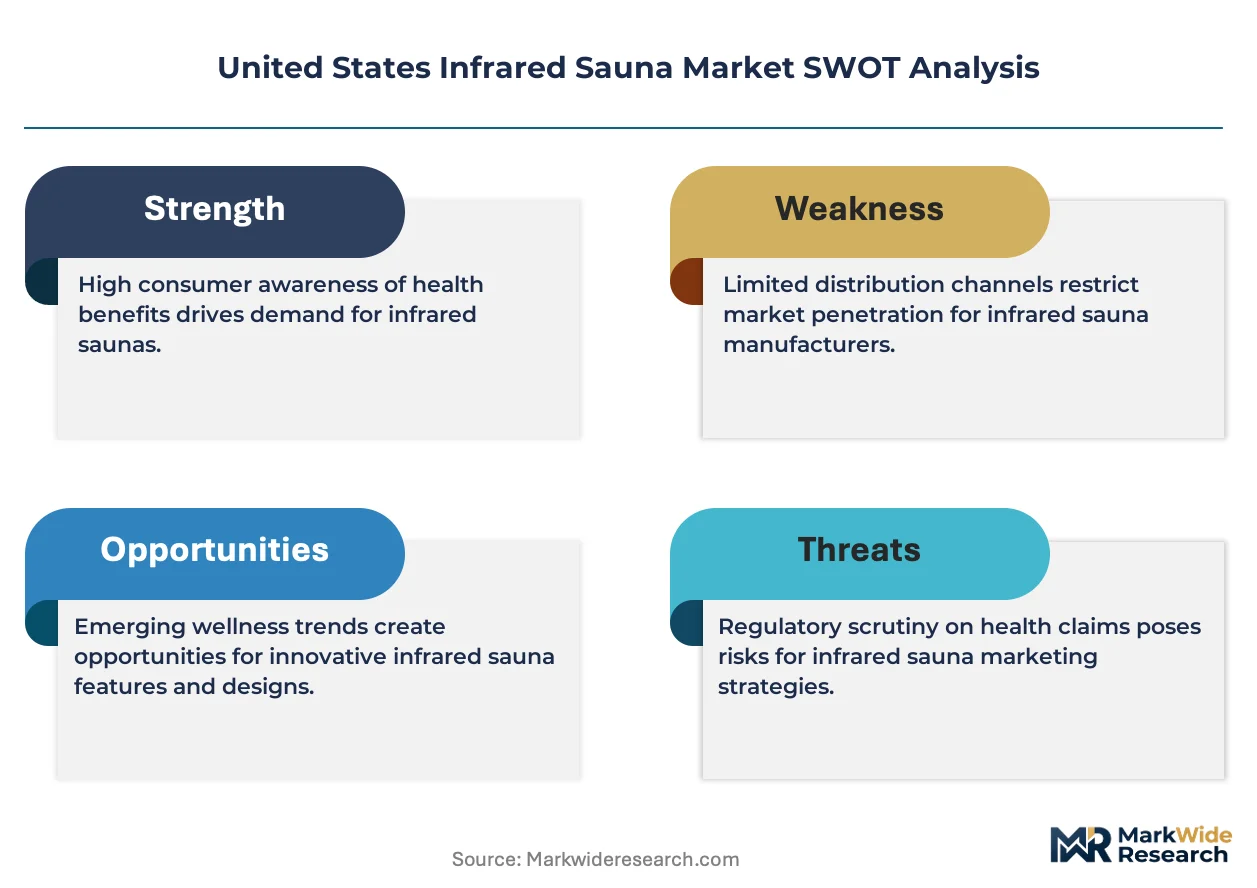
The Consumer Product Safety Commission (CPSC) oversees electrical safety compliance, while the Federal Trade Commission (FTC) monitors health-benefit advertising claims in this sector. California's Proposition 65 labeling requirements for formaldehyde and wood treatments add a state-level compliance layer that shapes material sourcing decisions. Stakeholders must monitor evolving EMF exposure guidelines and state-level building code adaptations for residential sauna installations.
Market Dynamics
Low electromagnetic field certification standards from the Consumer Product Safety Commission are forcing manufacturers to redesign heater architectures and revalidate third-party testing protocols, compressing product development cycles while elevating compliance costs across the supply base.
Growth Catalysts
- California Proposition 65 labeling mandates:Formaldehyde disclosure requirements for wood treatments are accelerating demand for certified low-emission cedar and hemlock sourcing, creating premium material differentiation.
- Wellness facility procurement:Commercial spas and recovery centers in Florida and California are specifying infrared units for post-treatment protocols, expanding institutional order volumes.
- Carbon fiber heater efficiency:Advanced panel designs operating at 110°F to 140°F deliver superior energy conversion rates versus ceramic alternatives, reducing operational costs for residential buyers.
Market Restraints
- Input cost volatility:Canadian cedar and Western red cedar lumber face pricing pressure from construction sector competition, squeezing margin structures for domestic manufacturers.
- Single-origin supplier concentration:Carbon fiber panel production clusters in East Asian manufacturing hubs expose buyers to shipping cost fluctuations and extended lead times.
- Substitution by traditional steam:Steam sauna retrofits in existing hospitality properties limit greenfield infrared adoption where plumbing infrastructure is already installed.
Strategic Opportunities
- Apartment-dwelling wellness segment:Portable infrared units address space constraints in dense urban housing across New York and Chicago, unlocking non-traditional residential demand.
- Clinical recovery applications:Physical therapy chains and sports medicine practices are integrating infrared protocols for muscle rehabilitation, expanding reimbursed service categories.
- FTC health-claim guidance alignment:Manufacturers investing in substantiated cardiovascular and detoxification messaging gain defensible positioning against enforcement actions.
Industry Challenges
- EMF testing talent scarcity:Qualified electromagnetic field measurement technicians are concentrated in California and Texas testing laboratories, creating hiring bottlenecks for quality assurance expansion.
- State building code fragmentation:Residential installation requirements vary across municipal jurisdictions, complicating national distribution and contractor training programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Infrared Sauna Market |
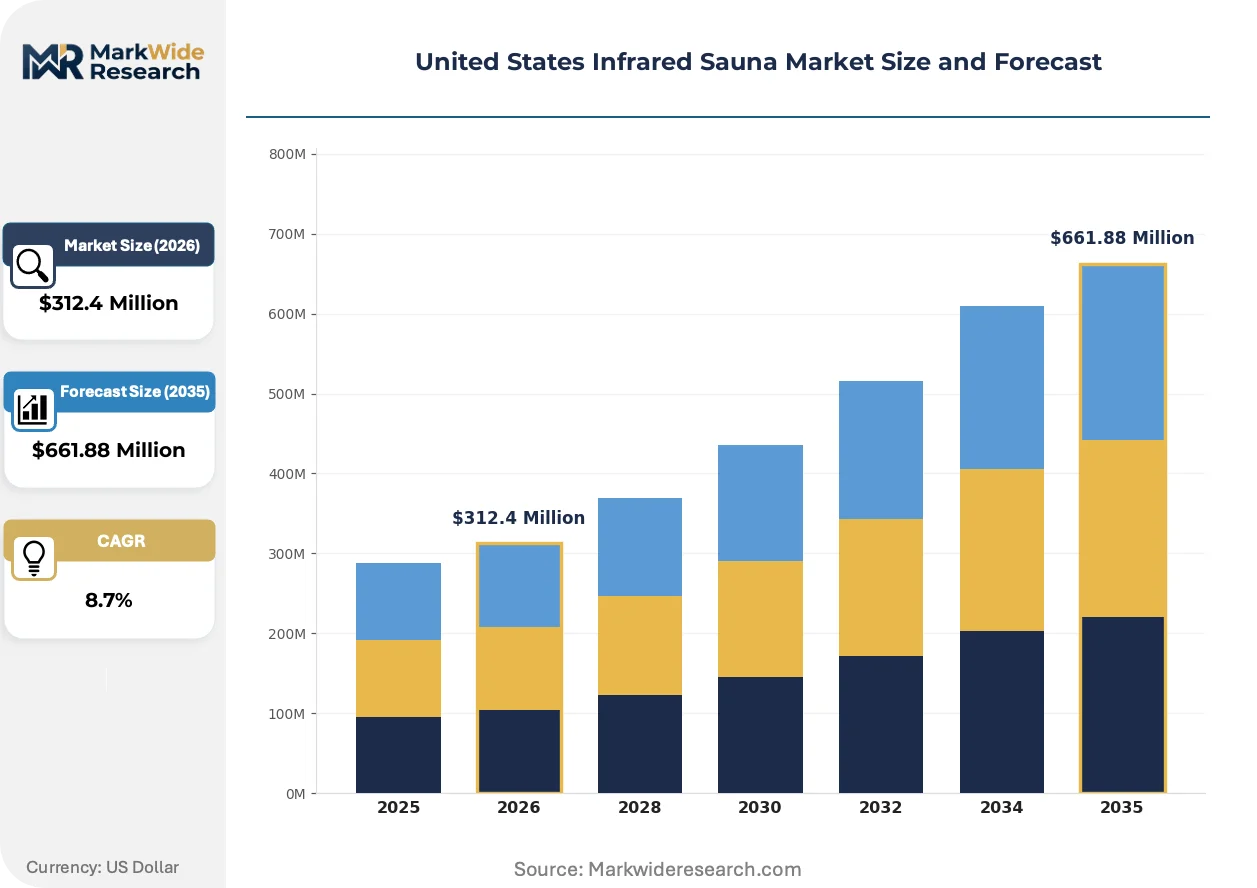
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
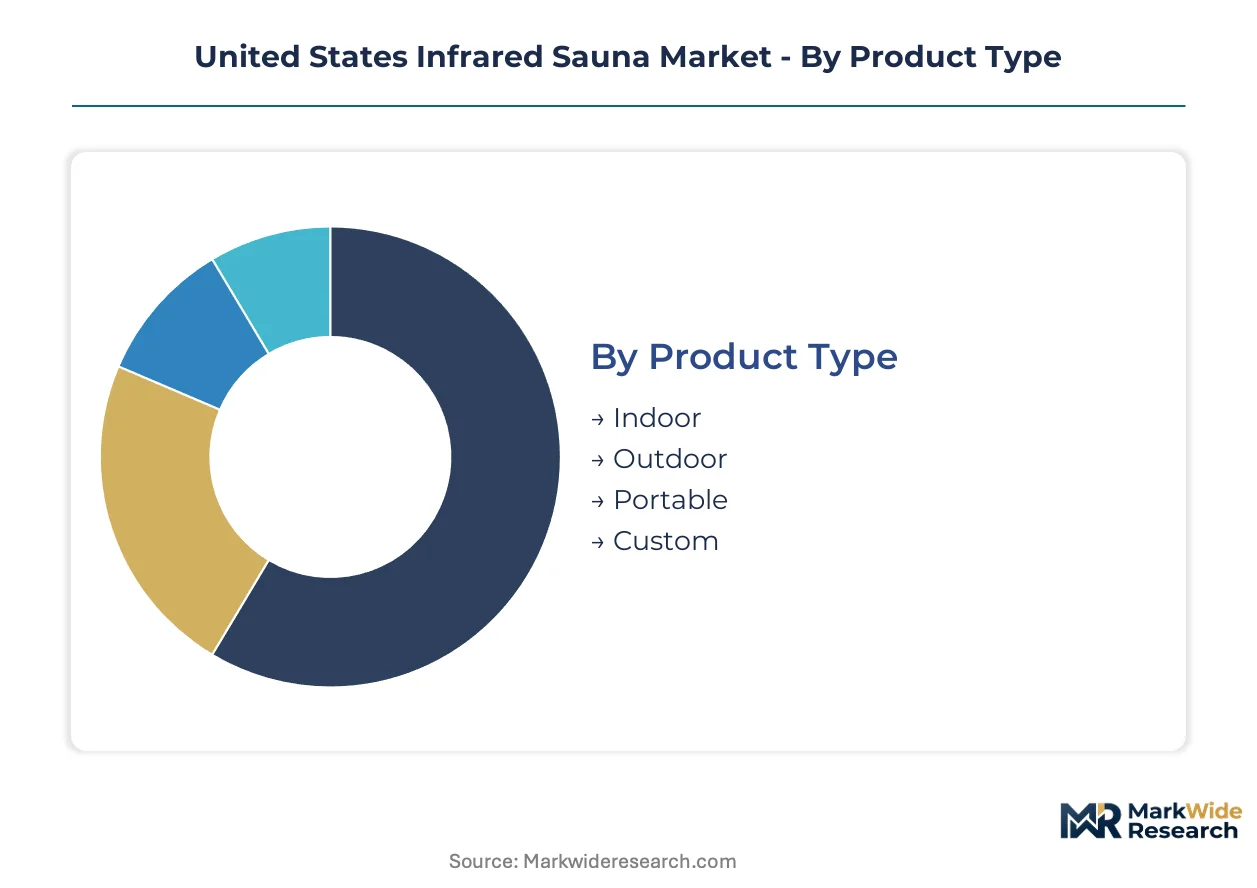
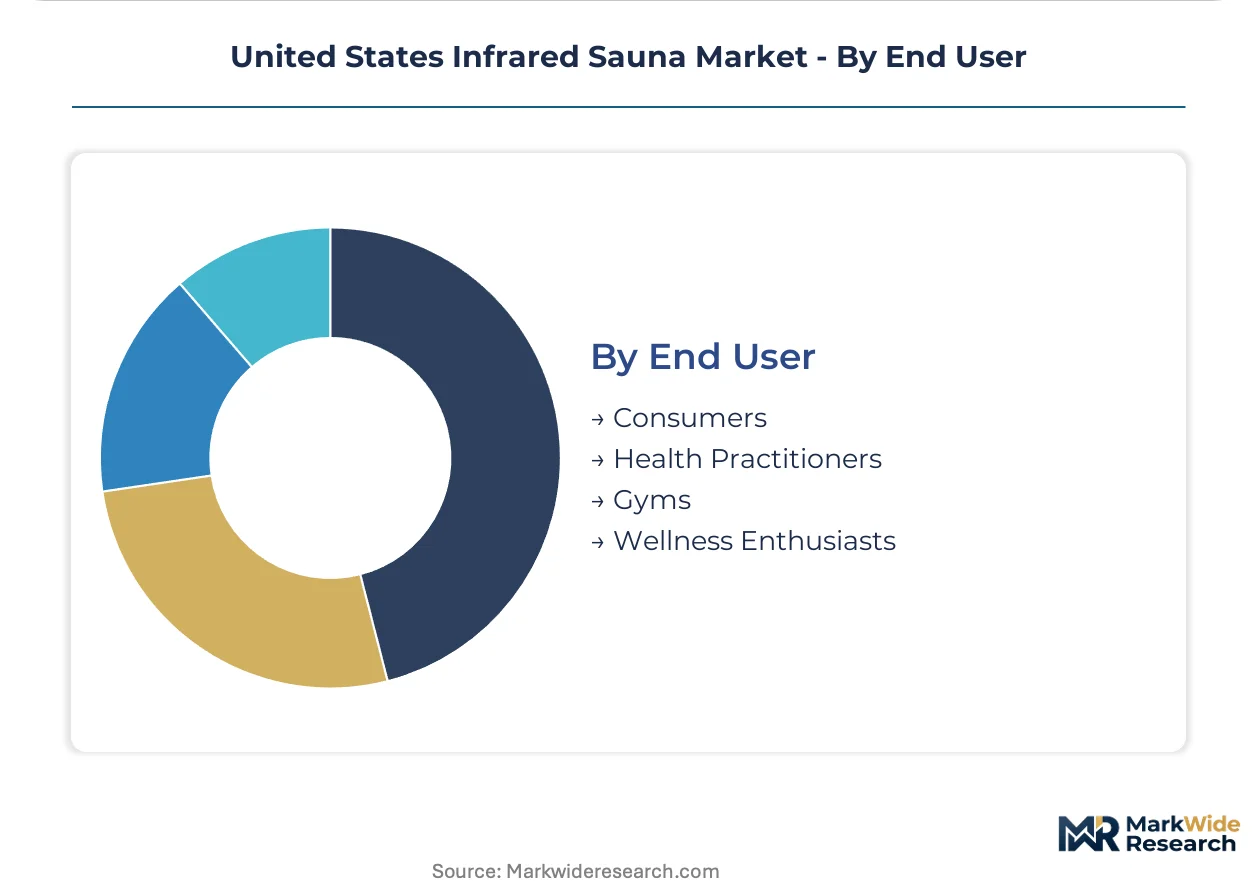
| Segmentation | Product Type: Indoor, Outdoor, Portable, Custom Heating Technology: Carbon Fiber, Ceramic, Radiant, Halogen Application: Home Use, Commercial Spa, Fitness Centers, Wellness Facilities End User: Consumers, Health Practitioners, Gyms, Wellness Enthusiasts |
| Companies Covered | Sunlighten, Clearlight Saunas, JNH Lifestyles, Dynamic Saunas, Radiant Health Saunas, TheraSauna, Health Mate Sauna, SaunaSpace, Heavenly Heat Saunas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Infrared Sauna Market Trends and Innovations
Heater technology convergence and regulatory scrutiny are compressing product lifecycles while elevating certification requirements as the primary purchasing filter for both residential and commercial buyers.
Full-spectrum infrared systems combining far-infrared, mid-infrared, and near-infrared wavelengths in single cabin architectures are rewriting competitive specifications for premium residential installations. Luxury hospitality buyers in California and Florida are specifying these multi-wavelength units for guest wellness amenities. The technology is compressing demand for single-wavelength legacy products while extending replacement cycles through modular upgrade pathways.
The Consumer Product Safety Commission's evolving electrical safety compliance frameworks are mandating enhanced ground-fault protection and thermal cutoff redundancy in residential sauna designs. Manufacturers are redesigning control systems and wiring harnesses to meet updated inspection protocols. California and Florida state inspectors are enforcing these standards most stringently, driving regional product configuration divergence.
Direct-to-consumer channel expansion is displacing traditional specialty retailer distribution for mid-market infrared sauna purchases. Online configurators and virtual installation guidance are reducing buyer reliance on in-person showroom experiences. This pattern concentrates in Texas and Arizona markets where suburban sprawl limits specialty retail density.
United States Infrared Sauna Market Segmentation
Infrared sauna procurement decisions split across technical specifications, installation constraints, and end-use intensity. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that reshape competitive positioning.
Product Type:
Carbon fiber and ceramic heater specifications dictate cabin architecture requirements across installation environments.
- Indoor:Climate-controlled environments optimize heater efficiency at 110°F to 140°F operating ranges. Demand concentrates in California and Florida residential basements and home gyms where year-round usability drives preference. Space efficiency and HVAC integration requirements elevate specification complexity for contractors.
- Portable:Collapsible cabin designs employing lightweight carbon fiber panels address apartment-dwelling constraints in New York and Chicago. Travel-oriented health practitioners and urban wellness enthusiasts are expanding this segment most quickly.
- Outdoor:Weather-resistant cedar and hemlock construction withstands seasonal exposure. Mountain and coastal properties in Colorado and Florida specify these units for pool-adjacent installation.
- Custom:Bespoke dimensions and multi-wavelength heater configurations serve luxury hospitality buyers. California wellness resorts commission these for guest amenity differentiation.
Indoor leads on scale; portable leads on momentum.
Heating Technology:
Energy conversion efficiency and EMF emission profiles differentiate procurement specifications across buyer tiers.
- Carbon Fiber:Large-surface-area panels distribute infrared wavelengths evenly at lower wattage density. California and Florida commercial spas specify these for operational cost control and extended heater longevity.
- Ceramic:Rod-style emitters concentrate heat output for rapid cabin warmup. Budget-conscious residential buyers in Texas and Arizona accept higher energy draw for lower upfront acquisition cost.
- Radiant:Reflector-backed tube designs optimize far-infrared penetration depth. Physical therapy chains integrate these for muscle recovery protocols.
- Halogen:Near-infrared-focused tubes support skin-targeted applications. Boutique facial and med-spa operators in Florida specify these for treatment-room installations.
Carbon fiber dominates volume; halogen climbs the fastest.
Application:
Usage intensity and reimbursement pathways reshape specification requirements across installation settings.
- Home Use:Residential buyers prioritize EMF certification and low-formaldehyde wood sourcing under California Proposition 65 awareness. Texas and Arizona suburban markets drive volume through direct-to-consumer channel preference.
- Commercial Spa:High-duty-cycle operation demands modular heater replacement capability. Florida luxury hospitality properties specify these for post-treatment recovery protocols.
- Fitness Centers:Post-workout recovery stations require rapid session turnover and durability. California boutique gym chains are integrating infrared as membership differentiation.
- Wellness Facilities:Clinical-grade detoxification and cardiovascular stress simulation applications demand precise wavelength control. Medical spa operators in Florida pursue these for service menu expansion.
Home use anchors revenue; wellness facilities gain share fastest.
End User:
Purchasing authority and technical sophistication segment specification complexity across buyer types.
- Consumers:Individual buyers rely on online configurators and EMF certification badges for decision support. Direct-to-consumer channels in Texas and Arizona concentrate this demand.
- Health Practitioners:Chiropractors and functional medicine clinicians specify clinical-grade units for in-practice patient protocols. California and Florida lead this professional adoption.
- Gyms:Facility managers prioritize durability warranties and rapid maintenance turnaround. Franchise operators in Florida specify standardized units across location portfolios.
- Wellness Enthusiasts:Biohacking-oriented buyers demand full-spectrum wavelength coverage and third-party testing documentation. California concentration drives premium specification tolerance.
Consumers dominate transaction count; wellness enthusiasts command highest per-unit spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's wellness corridor anchors United States infrared sauna demand through luxury hospitality investment and residential biohacking adoption. State-level regulatory frameworks and climate advantages concentrate procurement decisions in coastal metropolitan clusters.
California
Los Angeles and San Francisco metropolitan areas drive premium residential installations through health-conscious consumer density. Proposition 65 mandates formaldehyde disclosure for wood treatments, accelerating certified low-emission cedar sourcing. Santa Monica wellness resorts commission full-spectrum multi-wavelength units for guest amenity differentiation.
Florida
Miami and Orlando luxury hospitality properties specify infrared units for post-treatment recovery protocols. The state's building code adaptations for residential sauna installations vary across municipal jurisdictions. Tampa Bay commercial spas anchor institutional order volumes through high-duty-cycle operational requirements.
Texas
Houston and Dallas suburban markets concentrate direct-to-consumer channel preference through limited specialty retail density. The Consumer Product Safety Commission's electrical safety compliance frameworks shape regional product configuration. Austin boutique gym chains integrate infrared as membership differentiation.
New York
Manhattan and Brooklyn apartment-dwelling constraints expand portable unit adoption among urban wellness enthusiasts. State building inspectors enforce enhanced ground-fault protection standards stringently. Upstate New York wellness facilities pursue clinical-grade detoxification applications.
Colorado
Denver and Boulder mountain properties specify outdoor weather-resistant installations for pool-adjacent placement. The state's altitude considerations influence heater efficiency specifications for cardiovascular stress simulation applications. Aspen luxury hospitality buyers commission custom bespoke dimensions for guest amenity portfolios.
United States Infrared Sauna Market Competitive Landscape
Global majors compete with regional champions across certification standards and channel control dimensions. The United States infrared sauna market structures around three tiers: premium specialists commanding EMF-certified positioning, mid-market players optimizing direct-to-consumer reach, and value-oriented fabricators competing on acquisition cost. Strategic archetypes include vertical integrators controlling heater design, third-party testing validators, and online pricing aggressors. Dominant competitive moves encompass multi-source component procurement diversification and rigorous compliance protocol investments.
Within the premium specialist tier, Sunlighten anchors positioning through captive heater design capabilities, while Clearlight Saunas exemplifies third-party EMF testing validation. JNH Lifestyles occupies the mid-market direct-to-consumer vector through online channel control. These three United States-based entities represent distinct competitive archetypes: upstream integration, compliance differentiation, and pricing accessibility respectively.
| Leading Market Players |
|---|
| Sunlighten |
| Clearlight Saunas |
| JNH Lifestyles |
| Dynamic Saunas |
| Radiant Health Saunas |
| TheraSauna |
| Health Mate Sauna |
| SaunaSpace |
| Heavenly Heat Saunas |
| Others |
Pricing and Supply Chain Analysis
Western red cedar lumber price volatility cascades through United States infrared sauna manufacturing into three distinct pricing tiers, as California Proposition 65 compliance costs and East Asian carbon fiber panel shipping rates compound input cost differentials across premium EMF-certified, mid-market direct-to-consumer, and value-oriented ceramic heater product lines.
Pricing Analysis
Input-cost pass-through from Canadian cedar and carbon fiber panel sourcing stratifies pricing across premium, standard, and economy levels. EMF certification grade and low-formaldehyde wood sourcing differentiate the premium tier commanded by California wellness resorts, while Texas and Arizona suburban buyers exhibit highest price sensitivity toward ceramic alternatives. Pricing pressure stems from construction sector competition for cedar feedstock, compressing margins for domestic manufacturers unable to secure long-term lumber contracts.
Supply Chain Analysis
Reverse-logistics flows for heater panel refurbishment and cabin component remanufacturing remain underdeveloped, limiting circular economy capture. Manufacturing concentration in China, Taiwan, and Vietnam for carbon fiber heating elements creates single-source vulnerability for United States assemblers, while Canadian and domestic Western red cedar sourcing feeds from forestry operations with extended harvest cycles. Distribution runs through direct-to-consumer platforms, commercial spa procurement departments, and specialty wellness retailers in descending volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States infrared sauna procurement functions as a geographic-arbitrage play between California's stringent Proposition 65 compliance costs and Texas's lighter regulatory burden, enabling margin capture for manufacturers with flexible production footprints.
For Market Incumbents: Anticipate FTC enforcement actions on unsubstantiated cardiovascular health claims by pre-investing in clinical validation studies and third-party EMF testing documentation. Defensive consolidation through captive heater design capabilities and multi-source cedar sourcing contracts protects against East Asian shipping disruptions and lumber price spikes.
For New Entrants and Emerging Players: Direct-to-consumer channel partners offer lowest barrier to entry for portable infrared units targeting New York and Chicago apartment dwellers. White-space concentration in clinical recovery applications for physical therapy chains and reimbursed wellness protocols in Florida presents penetrable institutional demand with higher switching costs than residential segments.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-market players possessing established online configurators and virtual installation infrastructure. Five-to-ten year viability hinges on EMF testing talent acquisition and state building code harmonization progress. Monitor CPSC electrical safety compliance framework updates as inflection indicators for mandatory product redesign cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| EMF Certification Investment | Third-party testing protocols from CPSC-aligned laboratories deflect FTC enforcement risk. |
| Multi-Source Cedar Sourcing | Certified low-emission Canadian and Western red cedar suppliers buffer Proposition 65 exposure. |
| Direct-to-Consumer Platform Expansion | Online configurators displace showroom dependency in Texas and Arizona suburban sprawl. |
| Clinical Partnership Development | Physical therapy chain integrations in Florida expand reimbursed service categories. |
| Portable Product Line Launch | Collapsible cabin designs unlock New York and Chicago apartment-dwelling wellness demand. |
Research Methodology
Direct dialogue with sauna manufacturer engineering directors, commercial spa procurement managers, wellness facility operators, and CPSC compliance officers grounded qualitative insights, cross-referenced against customs import records for carbon fiber panels, California Air Resources Board formaldehyde emission databases, FTC advertising enforcement dockets, and trade association shipment surveys. Bottom-up unit economics and top-down category spend estimates triangulated market sizing.
Bottom-up modeling of installed base by product type, heating technology, and application combined with top-down wellness facility capital expenditure tracking across the projection horizon. Segmentation dimensions encompassed installation environment, heater architecture, end-use intensity, and buyer sophistication tier. CAGRs derived from weighted average of historical shipment momentum and penetration rate assumptions against demographic and hospitality investment drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CPSC EMF guideline evolution, cedar lumber futures volatility, and state building code fragmentation. Practitioners should monitor FTC health-claim enforcement patterns and clinical reimbursement policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Nursing Products Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Consumer Healthcare Market