
 Sarcoma Drugs Market | 2026-2036
Sarcoma Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Sarcoma Drugs Market Analysis
Oncology clinics is rotating demand away from inpatient hospital administration as oral and subcutaneous formulations reduce infusion dependency. Pfizer Inc. anchors its position through manufacturing scale across cytotoxic and biologic portfolios. Novartis AG differentiates via targeted therapy leadership in gastrointestinal stromal tumors. Eli Lilly and Company competes through R&D intensity in precision oncology pipelines.
Sarcoma drugs comprise pharmaceutical agents designed to treat malignant tumors arising from mesenchymal tissues, including alkylating agents, anthracyclines, tyrosine kinase inhibitors, and immune checkpoint modulators that interfere with DNA replication, angiogenesis, or tumor immune evasion. These therapies serve the primary commercial purpose of extending progression-free survival in patient populations with limited curative surgical options. Targeted therapy commands the largest current revenue pool given established kinase inhibitors, while immunotherapy represents the fastest-expanding segment as checkpoint combinations advance through late-stage trials. Oral administration routes are gaining share as patient preference and pharmacy benefit structures shift, though intravenous delivery retains dominance in neoadjuvant settings where bioavailability monitoring remains critical.
The FDA's orphan drug designation and breakthrough therapy pathways shape development economics by extending market exclusivity and enabling earlier revenue recognition. EMA's PRIME scheme and Japan's PMDA sakigake designation create parallel access routes that multinational sponsors must navigate simultaneously. Stakeholders must monitor how evolving biomarker-defined trial eligibility reshapes addressable patient populations and reimbursement thresholds across regulatory jurisdictions.
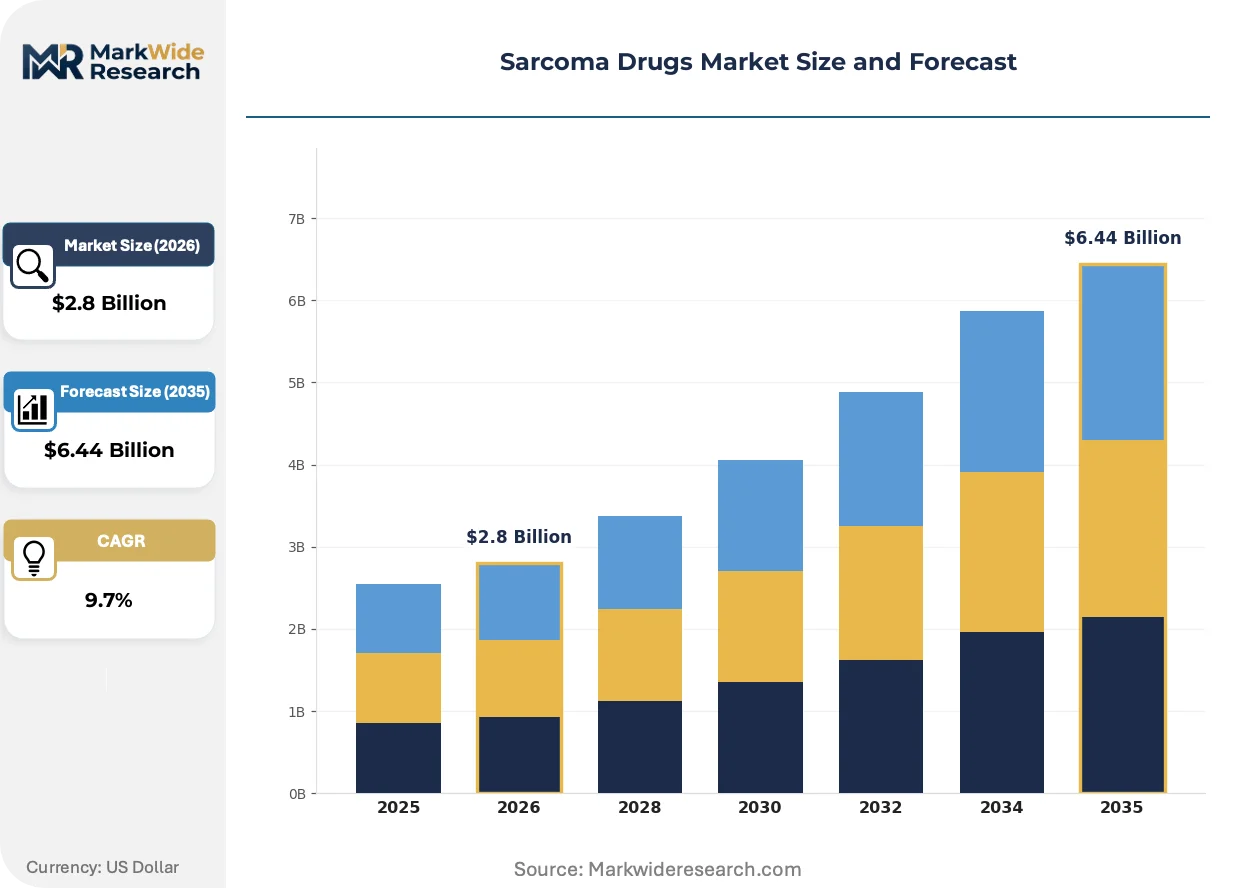
Market Dynamics
FDA's accelerated approval pathways for rare cancers are compressing development timelines and reshaping competitive entry patterns for novel sarcoma agents. Oncology clinics are capturing administered therapy volume as care migrates toward outpatient settings, altering site-of-service economics and distribution infrastructure requirements.
Growth Catalysts
- Orphan Drug Exclusivity:The FDA's orphan drug designation extends market exclusivity periods for rare cancer indications, improving sponsor ROI calculations for sarcoma pipeline investments.
- Subcutaneous Formulation Advances:Reduced infusion dependency is enabling oncology clinics to administer complex biologics without hospital infrastructure, expanding addressable treatment sites.
- Biomarker-Defined Eligibility:NTRK fusion testing and other molecular diagnostics are identifying responsive patient subsets, improving trial efficiency and regulatory success rates.
Market Restraints
- Anthracycline Manufacturing Concentration:Active pharmaceutical ingredient production for doxorubicin concentrates among a limited supplier base in India and China, creating supply vulnerability.
- Reimbursement Compression:Medicare's Hospital Outpatient Prospective Payment System is narrowing margin spreads for infused therapies administered in hospital-affiliated clinics.
- Small Addressable Populations:Ultra-rare sarcoma subtypes limit commercial scale, forcing sponsors to price at levels that attract payer scrutiny and access restrictions.
Strategic Opportunities
- Japan's Sakigake Designation:The PMDA's priority review scheme offers expedited timelines for innovative oncology agents, enabling earlier revenue recognition in the world's third-largest pharmaceutical market.
- Combination Checkpoint Protocols:Pairing anti-PD-1 agents with novel macrophage modulators represents underexplored mechanistic territory with potential in undifferentiated pleomorphic sarcoma.
- Specialty Pharmacy Networks:Oral kinase inhibitors are creating channel expansion opportunities through limited distribution networks that capture patient data and adherence monitoring revenue.
Industry Challenges
- Translational Biology Talent Scarcity:Sarcoma drug development requires specialized expertise in mesenchymal tumor biology that concentrates at a limited number of academic medical centers.
- Companion Diagnostic Synchronization:Parallel FDA review of therapeutics and diagnostics creates timeline misalignment risks that delay commercial launches.
- Real-World Evidence Collection:Post-approval confirmatory trials require robust data infrastructure that many oncology clinics lack, threatening accelerated approval conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sarcoma Drugs Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Targeted Therapy, Chemotherapy, Immunotherapy, Radiation Therapy Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Therapy Area: Soft Tissue Sarcoma, Bone Sarcoma, Pediatric Sarcoma, Others |
| Companies Covered | Amgen Inc., Bayer AG, Eisai Co., Ltd., Novartis AG, Pfizer Inc., Johnson & Johnson Services Inc., Eli Lilly and Company, GlaxoSmithKline plc, F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sarcoma Drugs Market Emerging Trajectories
Next-generation sequencing is fragmenting sarcoma taxonomy into molecularly defined subtypes, forcing sponsors to redesign trial architectures and commercial targeting approaches. Three developments are reshaping how therapies reach patients and how value is captured.
Antibody-drug conjugates targeting surface proteins expressed in synovial sarcoma and myxoid liposarcoma are displacing conventional cytotoxic regimens in neoadjuvant settings. Sarcoma centers of excellence in the United States are adopting these agents through early-access protocols before full approval. The shift is compressing the commercial window for established anthracycline-based combinations and demanding new biomarker infrastructure investments.
The European Medicines Agency's PRIME scheme is compressing scientific advice timelines and enabling parallel development with FDA breakthrough therapy pathways. Multinational sponsors now coordinate rolling submissions across both jurisdictions to synchronize approval dates. Gastrointestinal stromal tumor programs are most affected, with sponsors restructuring development teams to manage dual-track regulatory engagement.
Patient advocacy organizations are consolidating purchasing influence through foundation-funded access programs that negotiate directly with manufacturers. The Sarcoma Foundation of America and equivalent European bodies are channeling patients toward centers with clinical trial availability, reshaping referral patterns. This concentration is most visible in the United States, where travel reimbursement programs concentrate trial enrollment at coastal academic medical centers.
Sarcoma Drugs Market Segmentation
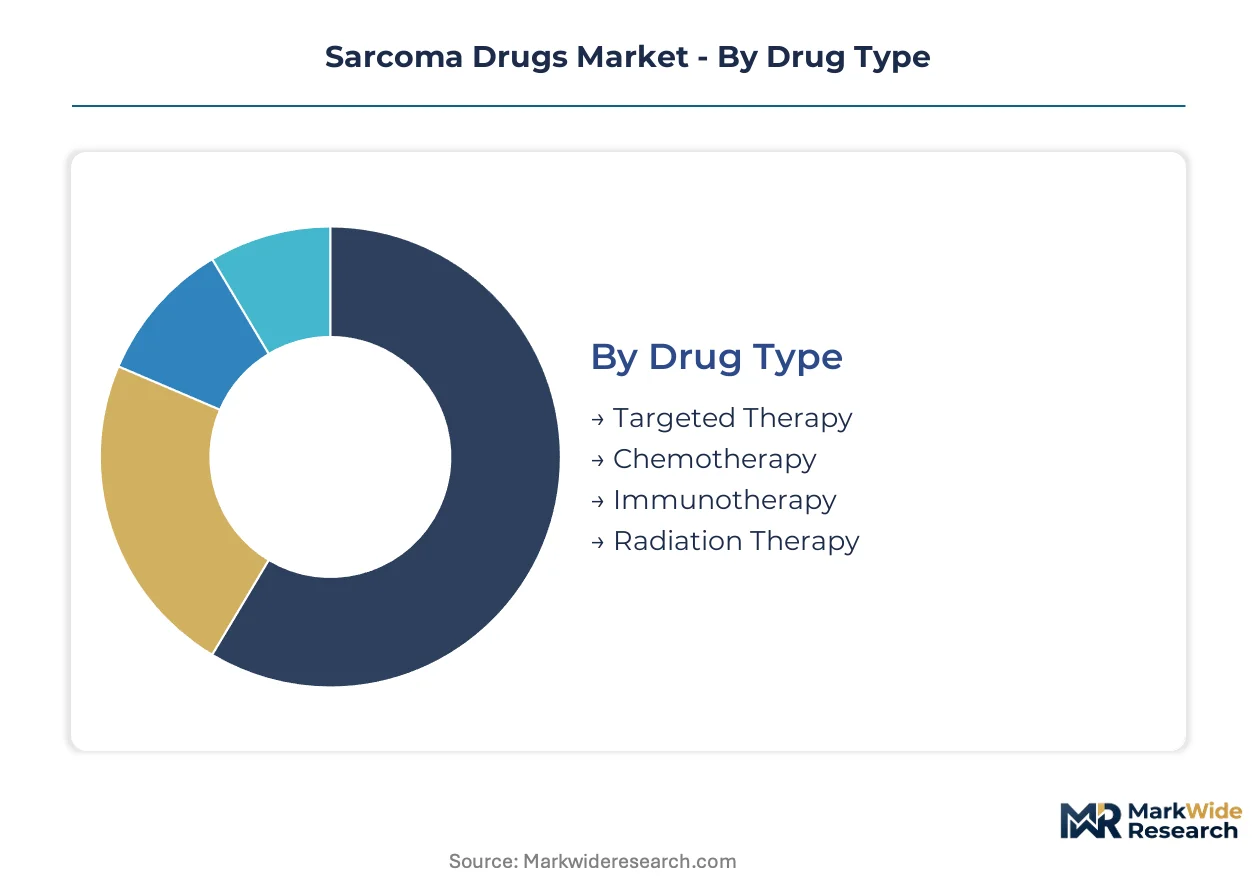
Sarcoma drug segmentation reveals how formulation science and site-of-service economics reshape competitive positioning. Channel strategy diverges sharply across administration routes, with oral agents flowing through specialty pharmacies while infused therapies concentrate at hospital-affiliated clinics.
Drug Type:
Targeted therapies and immunotherapies flow through limited distribution networks and oncology clinics, while cytotoxic agents remain tethered to hospital infusion centers with their captive pharmacy infrastructure.
- Targeted Therapy:Kinase inhibitors and NTRK fusion blockers deliver precision intervention against specific molecular drivers. Demand concentrates in gastrointestinal stromal tumor populations at sarcoma centers of excellence in the United States, where companion diagnostic testing infrastructure supports biomarker-driven prescribing.
- Immunotherapy:Checkpoint inhibitors and macrophage modulators redirect immune surveillance against mesenchymal malignancies. Expansion concentrates in undifferentiated pleomorphic sarcoma trials at academic medical centers, driven by FDA breakthrough therapy pathway acceleration for combination protocols.
- Chemotherapy:Anthracycline and alkylating agent regimens retain neoadjuvant utility despite toxicity profiles.
- Radiation Therapy:Adjunctive modalities integrate with systemic agents in limb-sparing protocols.
Targeted therapy dominates installed base. Immunotherapy is where expansion concentrates.
Administration Route:
Route selection determines reimbursement mechanics and site-of-service eligibility, with oral formulations capturing pharmacy benefit structures and parenteral routes remaining under medical benefit administration.
- Oral:Kinase inhibitors and hormonal agents enable outpatient self-administration with adherence monitoring through specialty pharmacy networks. Volume concentrates in Medicare Part D populations seeking to avoid infusion center travel burdens.
- Intravenous:Anthracyclines and checkpoint inhibitors require bioavailability monitoring and hypersensitivity protocols. Demand clusters at hospital outpatient departments where Medicare's Hospital Outpatient Prospective Payment System governs reimbursement.
- Subcutaneous:Reduced infusion duration is displacing intravenous equivalents in oncology clinic settings.
- Topical:Limited application in cutaneous soft tissue presentations.
Intravenous administration dominates installed base. Subcutaneous formulations are climbing the fastest.
End User:
Patient volume migration from inpatient to outpatient settings restructures procurement relationships, with oncology clinics gaining administered therapy share through formulary committee influence.
- Oncology Clinics:Community-based infusion centers and physician-owned practices capture shifting care delivery. Expansion concentrates in United States metropolitan corridors where sarcoma foundation travel reimbursement programs channel patients toward trial-accessible sites.
- Hospitals:Academic medical centers retain complex case referrals and neoadjuvant protocols. Volume anchors at coastal sarcoma centers of excellence with embedded phase I trial infrastructure.
- Research Institutions:Early-phase investigation sites drive pipeline visibility.
- Homecare:Oral agent dispensing extends treatment access geographically.
Hospitals dominate installed base. Oncology clinics are gaining share fastest.
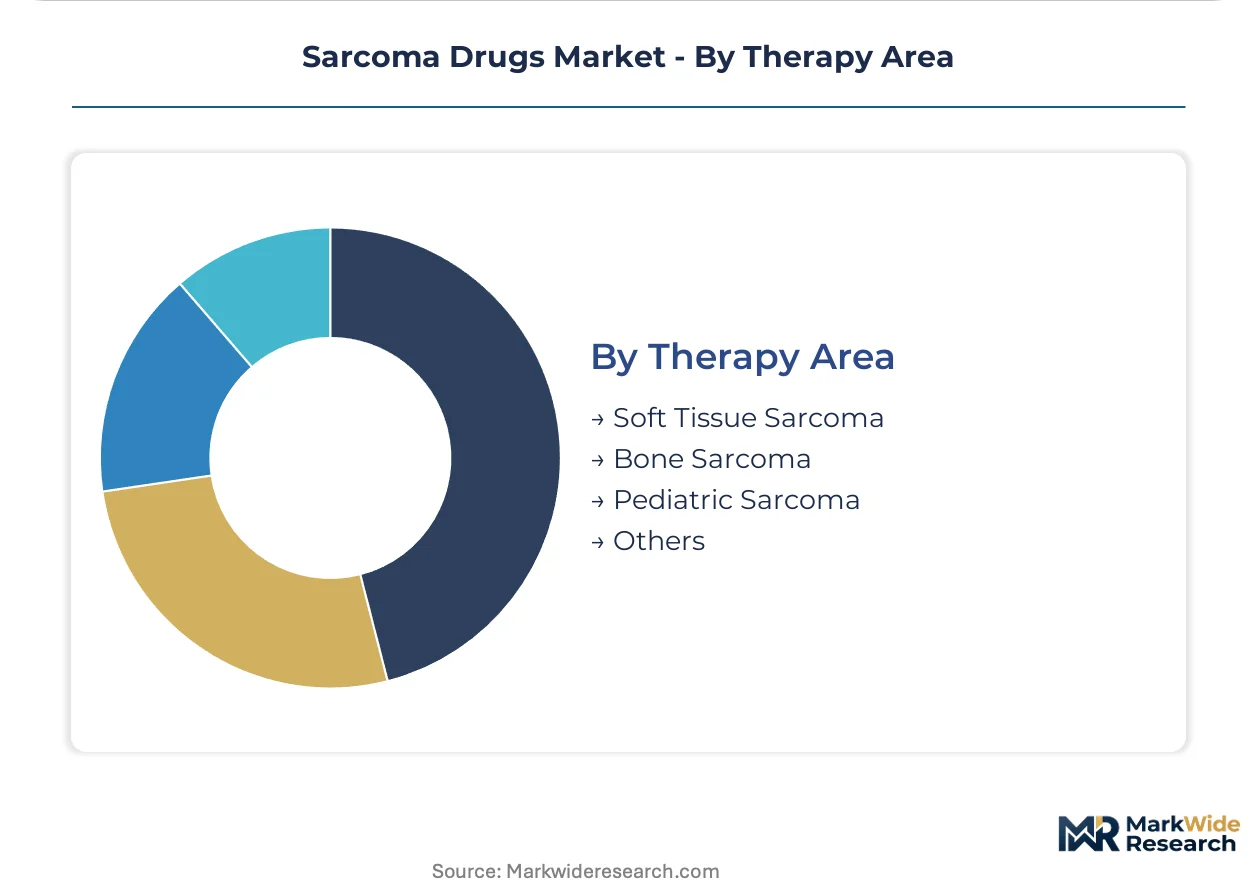
Therapy Area:
Disease-specific development programs fragment addressable populations, with molecular taxonomy advances enabling ultra-narrow indication strategies that reshape clinical trial recruitment geography.
- Soft Tissue Sarcoma:Liposarcoma, leiomyosarcoma, and synovial sarcoma subtypes drive kinase inhibitor development. Demand concentrates in United States coastal academic centers where next-generation sequencing platforms enable molecular stratification.
- Bone Sarcoma:Osteosarcoma and Ewing sarcoma retain dependence on cytotoxic backbones with limited targeted penetration. Volume anchors at pediatric oncology consortium institutions with established methotrexate and cisplatin protocols.
- Pediatric Sarcoma:Rhabdomyosarcoma and Ewing family tumors trigger orphan designation incentives.
- Others:Ultra-rare subtypes including desmoid tumors and PEComas.
Soft tissue sarcoma dominates installed base. Pediatric indications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Memorial Sloan Kettering Cancer Center corridor in Manhattan anchors North American sarcoma drug development through its integrated phase I trial infrastructure and companion diagnostic partnerships.
United States
FDA breakthrough therapy designations and orphan drug exclusivity compress development timelines for rare cancer indications. The Sarcoma Foundation of America channels patients toward coastal academic medical centers through travel reimbursement programs. MD Anderson Cancer Center in Houston and Dana-Farber Cancer Institute in Boston concentrate trial enrollment for gastrointestinal stromal tumor kinase inhibitors.
Germany
EMA PRIME scheme acceleration and centralized European reimbursement negotiations attract multinational sponsors to Berlin and Munich regulatory hubs. The German Cancer Research Center in Heidelberg coordinates pan-European biomarker-defined trial networks. Bavarian oncology clinics adopt subcutaneous biologic formulations ahead of southern European markets.
Japan
PMDA sakigake priority review creates parallel approval pathways for innovative oncology agents. Tokyo and Osaka sarcoma centers concentrate patient volume for undifferentiated pleomorphic sarcoma checkpoint combination trials. METI industrial policy supports domestic biologic manufacturing capacity expansion for export to Asian markets.
United Kingdom
NICE technology appraisals and Cancer Drugs Fund access schemes determine commercial viability for premium-priced targeted therapies. The Royal Marsden Hospital in London anchors European early-phase investigation for antibody-drug conjugates. Manchester and Birmingham oncology networks expand community-based infusion capacity for oral kinase inhibitor transitions.
Switzerland
Swissmedic expedited review pathways and bilateral FDA mutual recognition agreements enable synchronized transatlantic launches. Basel and Zurich pharmaceutical clusters host specialized mesenchymal tumor biology research units. Roche's Genentech partnership channels late-stage pipeline assets through Swiss regulatory filing coordination.
Sarcoma Drugs Market Vendor Landscape
Concentration sits with large-cap diversified pharmaceutical manufacturers holding cytotoxic and biologic portfolios across multiple oncology indications. Mid-tier specialists concentrate in gastrointestinal stromal tumor kinase inhibitors and rare sarcoma subtypes. Two strategic archetypes dominate: scale-driven manufacturers leveraging manufacturing infrastructure across dose forms, and precision oncology developers pursuing biomarker-defined narrow indications. Competitive moves center on companion diagnostic synchronization and subcutaneous formulation development to capture oncology clinic volume.
Among large-cap diversified manufacturers, Pfizer Inc., Novartis AG, and Eli Lilly and Company occupy anchor positions. Pfizer exemplifies the scale-driven archetype through manufacturing breadth. Novartis represents targeted therapy leadership in molecularly defined sarcoma subtypes. Eli Lilly sits within the precision oncology tier through R&D intensity in biomarker-driven development programs.
| Leading Market Players |
|---|
| Amgen Inc. |
| Bayer AG |
| Eisai Co., Ltd. |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson Services Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for anthracycline active pharmaceutical ingredients lock in supply access and price visibility for oncology drug manufacturers, insulating them from spot market volatility in Indian and Chinese production clusters while compressing margin flexibility for generic entrants.
Pricing Analysis
Volume-discount tiering structures separate originator kinase inhibitors from biosimilar entrants and commodity cytotoxics, with pricing stratifying across premium, standard, and economy tiers based on FDA breakthrough designation status and companion diagnostic bundling. Cost compression in the cytotoxic segment intensifies because of concentrated API supply and Medicare reimbursement compression, while sarcoma centers of excellence show lowest price sensitivity for novel immunotherapy combinations.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for doxorubicin and ifosfamide, with Switzerland and Germany hosting fill-finish operations for biologic agents. The network draws from fermentation-derived small molecules and mammalian cell culture substrates, facing single-source vulnerability in oncology API manufacturing. Distribution runs through specialty pharmacy networks for oral agents and direct-to-clinic channels for infused therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for rare cancers are compressing development timelines and enabling earlier revenue recognition, creating a high-growth disruption environment where biomarker-defined eligibility reshapes competitive entry patterns.
For Market Incumbents: Fortify manufacturing scale advantages through captive supply of anthracycline APIs and subcutaneous formulation investments that capture oncology clinic volume migration. Vertical integration into companion diagnostic partnerships defends against precision oncology entrants threatening kinase inhibitor franchises. For New Entrants and Emerging Players: Anchor in undifferentiated pleomorphic sarcoma checkpoint combinations where trial infrastructure gaps exist at community oncology clinics, and leverage Japan's PMDA sakigake designation for expedited timeline arbitrage against FDA-tracked competitors. For Investors and Strategic Acquirers: Biomarker-testing platform developers with FDA-synchronized diagnostic pipelines represent the most defensible acquisition archetype, with long-term viability hinging on companion diagnostic approval conversion rates as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Synchronization | Parallel FDA review of therapeutics and diagnostics compresses commercial launch timelines. |
| Subcutaneous Formulation Development | Reduced infusion dependency captures oncology clinic volume away from hospital outpatient departments. |
| Orphan Drug Designation Pursuit | FDA exclusivity extension improves ROI calculations for ultra-rare sarcoma subtype programs. |
| Specialty Pharmacy Network Expansion | Limited distribution channels enable adherence monitoring revenue and patient data capture. |
| Dual-Track Regulatory Engagement | Coordinated EMA PRIME and FDA breakthrough submissions synchronize transatlantic approval dates. |
Methodological Framework
Cross-validation between regulatory filing databases and hospital procurement records anchors the qualitative findings, combining primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement data. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation ensure segmentation integrity.
Sensitivity analysis across the projection horizon tests alternative scenarios for biomarker penetration rates and accelerated approval conversion outcomes, with segmentation dimensions spanning drug type, administration route, end-user setting, and therapy area. CAGRs derive from patent expiry curves, pipeline probability-adjusted net present values, and site-of-service economics modeling, incorporating orphan drug exclusivity periods and companion diagnostic adoption curves as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory pathway assumptions; material deviation in FDA confirmatory trial requirements or EMA scientific advice timelines would warrant model refresh. Recalibration cycles align with material shifts in biomarker-defined trial eligibility and reimbursement threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Retinal Drugs Market